China Surface Treatment Market Size & Growth Rate
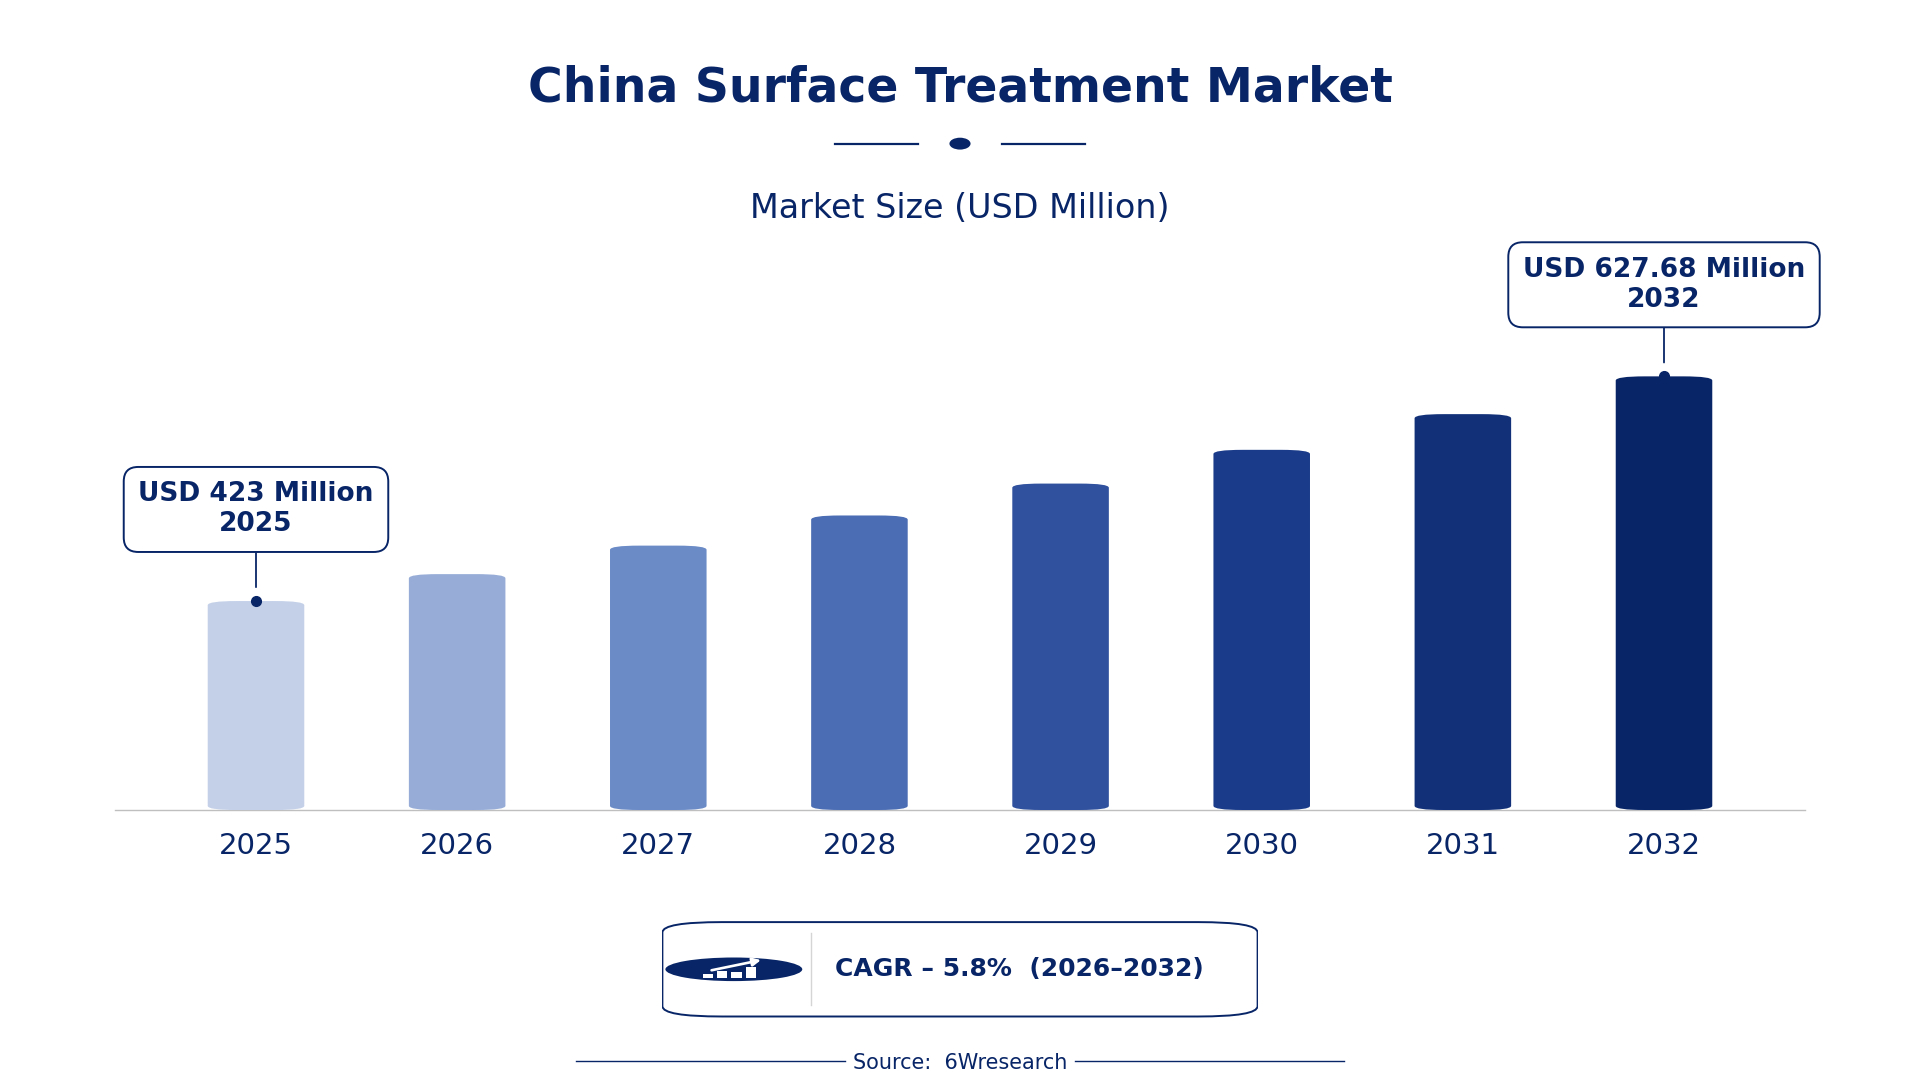
According to 6Wresearch internal database and industry insights, the China Surface Treatment Market was valued at USD 423.0 million in 2025 and is projected to reach USD 627.68 million by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China Surface Treatment Market Highlights
| Report Metric | Details |
| Report Name | China Surface Treatment Market |
| Market Size 2025 | USD 423.0 million |
| Market Size 2032 | USD 627.68 million |
| Absolute Growth 2025–2032 | USD 204.68 million |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 8.3% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Treatment Type, 2025 | Anodizing (42% share) |
| Leading Process Technology, 2025 | Electrochemical (45% share) |
| Leading Target Material, 2025 | Aluminum (42% share) |
| Leading End User, 2025 | Aerospace OEMs (35% share) |
| Fastest-Growing Treatment Type | Plating (8.0% CAGR) |
| Fastest-Growing Process Technology | Electroplating (7.6% CAGR) |
| Fastest-Growing Target Material | Steel (8.0% CAGR) |
| Fastest-Growing End User | Auto Component Manufacturers (7.8% CAGR) |
| Growing Sector | Auto Component Manufacturers |
| Key End Users | Aerospace OEMs, Auto Component Manufacturers, Industrial Equipment Makers, Electronics Manufacturers |
China Surface Treatment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
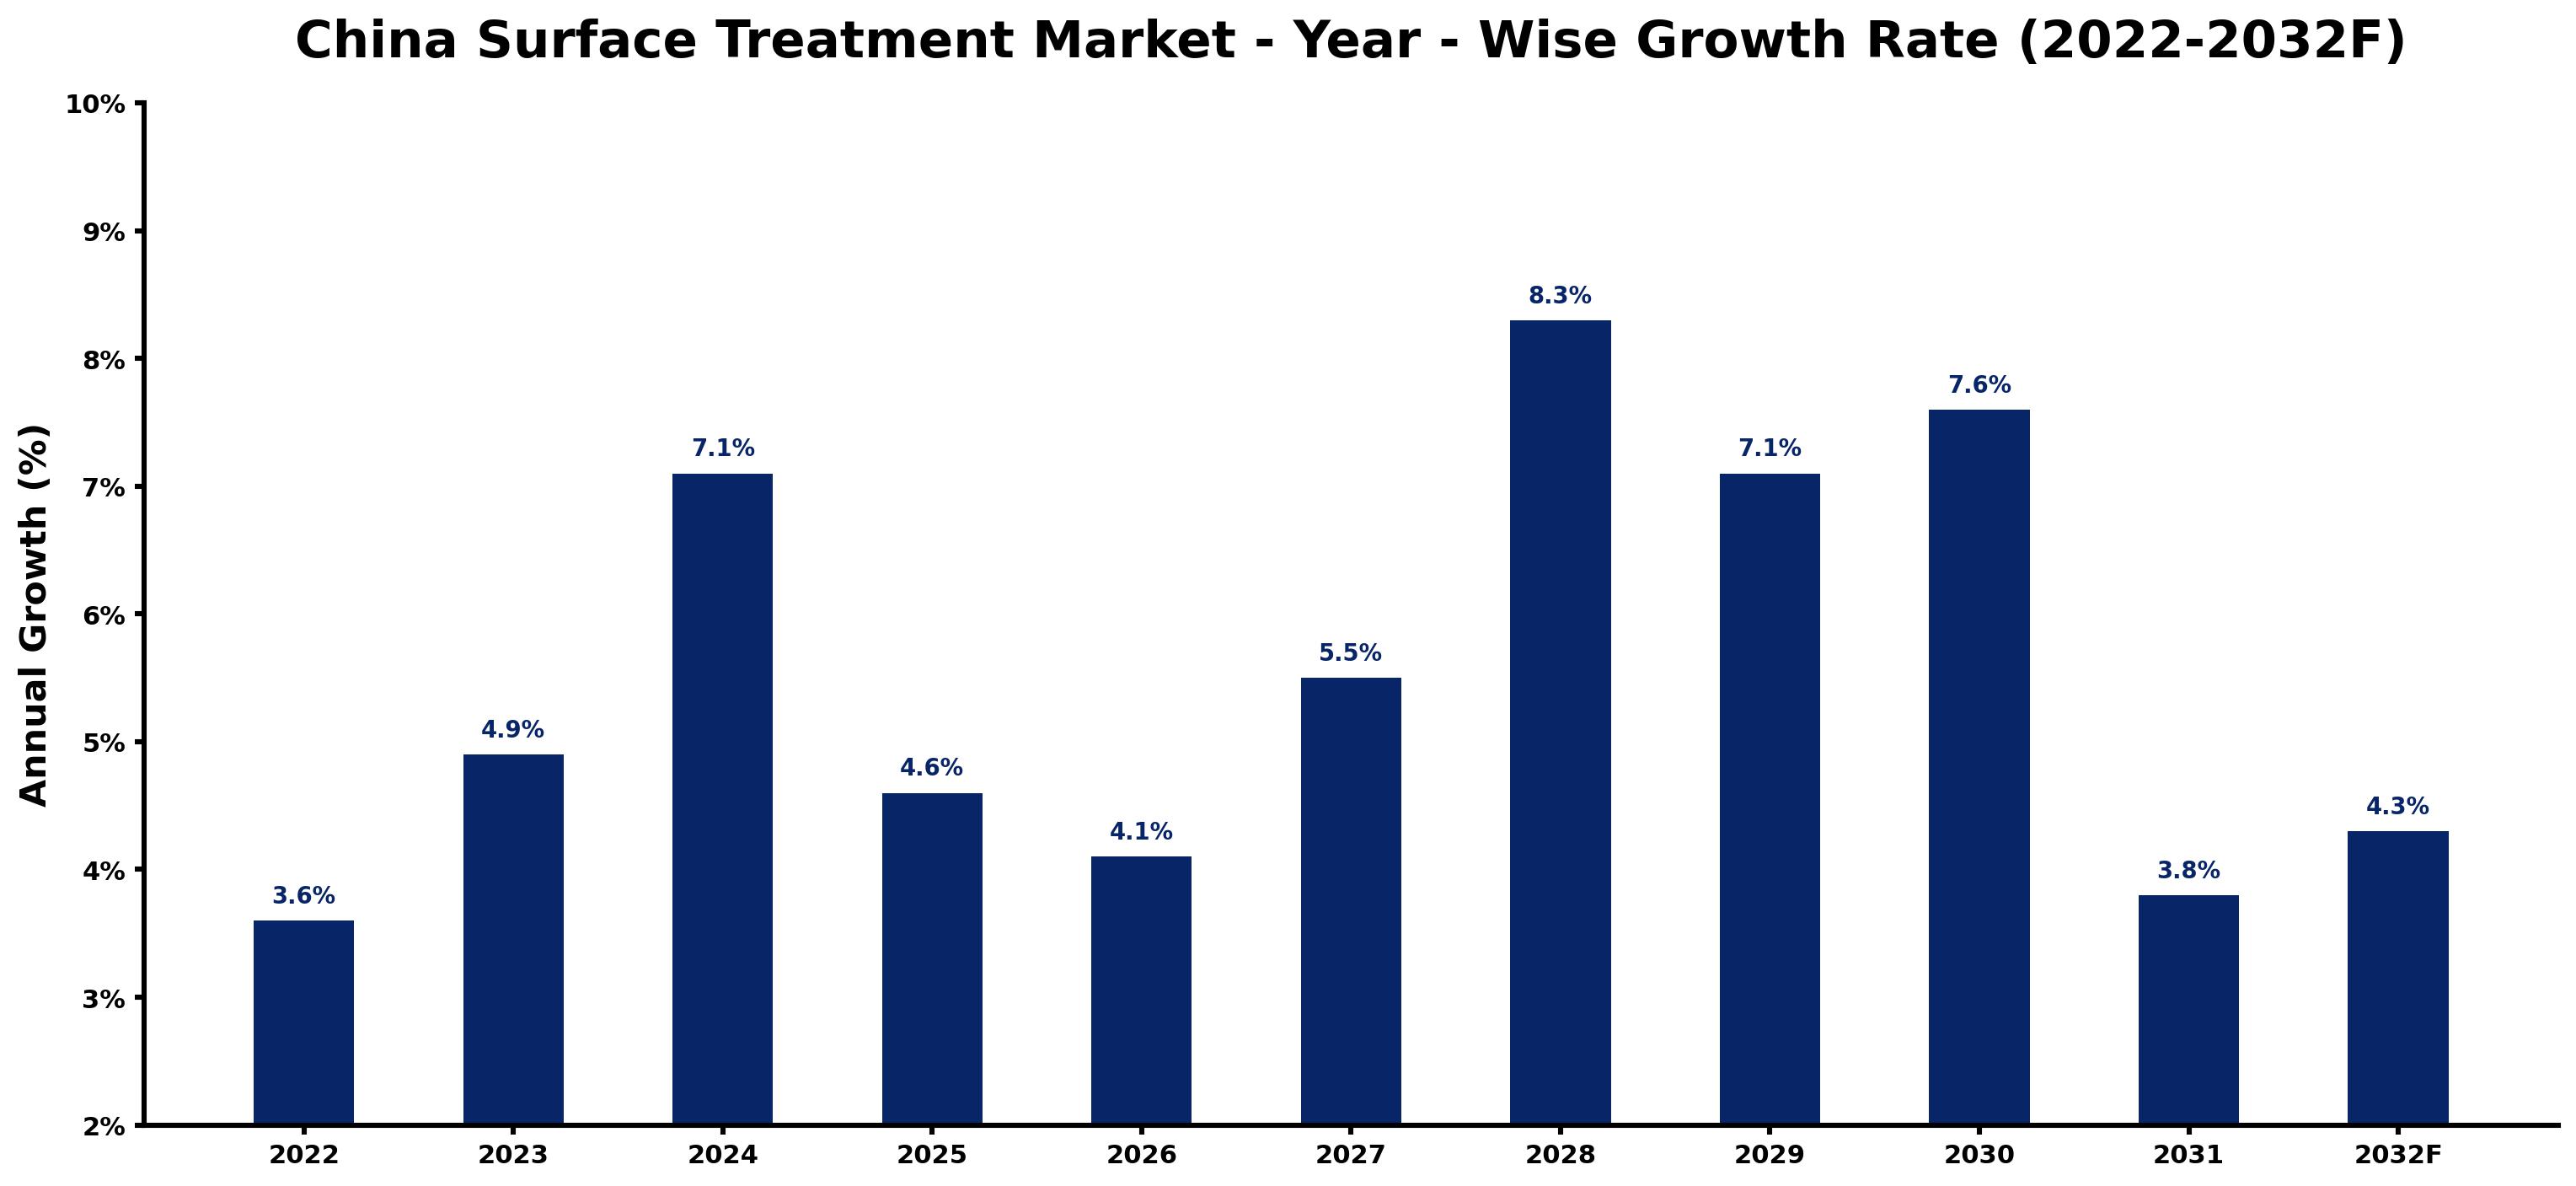
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.6 | The market showed steady activity, supported by domestic manufacturing and exports. |
| 2023 | 4.9 | Demand from the automotive sector increased, leading to faster growth than the previous year. |
| 2024 | 7.1 | The aerospace industry expanded, contributing to growth in surface treatment needs. |
| 2025 | 4.6 | Automotive production growth slowed, resulting in a slight decrease in growth rate. |
| 2026 | 4.1 | Demand remained steady, but growth is expected to slow due to adjustments in the automotive sector. |
| 2027 | 5.5 | The electronics industry will ramp up production, driving increased demand for surface treatment. |
| 2028 | 8.3 | A surge in automotive production will lead to peak growth in surface treatment demand. |
| 2029 | 7.1 | The market will experience a slowdown as growth rates normalise after the peak. |
| 2030 | 7.6 | Demand from aerospace OEMs is projected to increase, leading to a rise in growth rates once again. |
| 2031 | 3.8 | Growth will slow as the market stabilises following a period of rapid expansion. |
| 2032 | 4.3 | The market is expected to grow steadily, driven by ongoing demand from key industries. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Surface Treatment Market Synopsis
Surface Treatment in China involves various processes that modify material properties, particularly for metals. Techniques like anodizing, plating, and coating enhance durability and resistance to corrosion. The China Surface Treatment Market is growing due to strong demand from the automotive and electronics sectors, supported by over 1,000 aerospace manufacturers and a forecasted automotive production of 30 million vehicles annually by 2025. The electronics manufacturing industry is expected to reach a market size of $1 trillion by 2025, further driving demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased automotive production drives demand for surface treatment processes. | Driver | High | Plating |
| Growing aerospace sector requires treated components for safety and performance. | Driver | High | Anodizing |
| Investment in surface treatment technology upgrades presents new market opportunities. | Opportunity | High | Electrochemical |
| Expansion of the electronics sector creates demand for surface treatment services. | Opportunity | High | Coating |
| Environmental regulations impose restrictions on certain surface treatment processes. | Restraint | Medium | Chemical |
| Quality management standards like ISO 9001 can limit operational flexibility. | Restraint | Medium | Electroplating |
| The surface treatment market in China faces challenges related to skilled labour shortages. | Challenge | High | Aerospace OEMs |
| Rising costs of raw materials can impact pricing strategies for surface treatment providers. | Challenge | Medium | Auto Component Manufacturers |
Evaluation of Drivers in China Surface Treatment Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising automotive production increases the need for surface treatment processes. | Plating | The automotive sector in China is set to produce 30 million vehicles annually by 2025, driving demand for surface treatment. |
| Expansion of the aerospace sector boosts demand for treated components. | Anodizing | China has over 1,000 aerospace manufacturers in regions like Shanghai, increasing the need for surface treatment. |
| Investment in technology upgrades improves surface treatment capabilities. | Electrochemical | In 2022, the National Development and Reform Commission approved a $500 million investment for surface treatment technology upgrades. |
| Growth in the electronics sector necessitates high-quality surface treatment. | Coating | The electronics manufacturing industry in China is expected to reach a market size of $1 trillion by 2025, increasing demand for surface treatment. |
| Environmental regulations encourage sustainable surface treatment practices. | Chemical | The surface treatment market is projected to grow due to rising environmental regulations and demand for sustainable practices. |
Expansion of the Surface Treatment market in China is backed by rising automotive production, increased aerospace activity, and substantial investment in technology upgrades. The automotive sector is on track to produce 30 million vehicles annually by 2025, driving demand for surface treatment processes. Over 1,000 aerospace manufacturers are increasing the need for treated components. A $500 million investment in technology upgrades was approved in 2022, enhancing capabilities. The electronics manufacturing industry is forecasted to reach a market size of $1 trillion by 2025, further boosting demand.
Evaluation of Restraints in China Surface Treatment Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Environmental regulations impose strict compliance requirements on surface treatment processes. | Chemical | Compliance with regulations can increase operational costs and limit flexibility in operations. |
| ISO 9001 standards require rigorous quality management, impacting operational efficiency. | Electroplating | Adhering to ISO 9001 can slow down production processes and increase costs for facilities. |
| Skilled labour shortages hinder the growth of surface treatment capabilities. | Aerospace OEMs | The aerospace sector's demand for skilled workers in surface treatment is not being met, affecting production timelines. |
| Rising raw material costs can impact pricing strategies for surface treatment providers. | Auto Component Manufacturers | Increased costs of metals and chemicals can lead to higher prices for treated components, affecting buyer decisions. |
| Market fluctuations can lead to uncertainty in demand for surface treatment services. | Coating | Economic shifts may affect production levels in key sectors, impacting the consistency of demand. |
China Surface Treatment Market Challenges
In the China surface treatment market, a primary concern is the shortage of skilled workers, particularly in complex processes like anodizing and plating. This skills gap arises from rapid industry growth that has outstripped available training, leading to delays for manufacturers unable to meet production schedules. Rising raw material costs present another challenge, with aluminum prices climbing by 15% in the past year, straining budgets for automotive and electronics producers. Buyers also face prolonged lead times due to supply chain disruptions, resulting in potential project delays and lost revenue for manufacturers. Stricter environmental regulations require facilities to invest in compliance, diverting funds from necessary technology upgrades.
Trends in the China Surface Treatment Market
Below mentioned are some of the trends shaping the China Surface Treatment Market growth.
- Shift Towards Sustainable Practices in Surface Treatment: Since 2023, there has been a notable shift towards sustainable surface treatment methods. The 'Advanced Manufacturing Industry Development Plan' aims to boost eco-friendly technologies, with a $500 million investment supporting this transition.
- Rise of Automated Surface Treatment Processes: In 2025, automated surface treatment processes are becoming more prevalent, improving efficiency. The adoption of automation technologies is projected to increase productivity by 20% in facilities across Guangdong province.
- Increased Demand for Anodizing in Aerospace: The aerospace sector has seen a rise in anodizing applications since 2022, driven by safety standards. Approximately 35% of aerospace components now require anodized finishes to meet performance criteria.
- Growth in Plating Technologies for Electronics: Since 2026, plating technologies have gained traction in the electronics sector. The demand for plated components is expected to grow by 8% annually, driven by advancements in electronic devices.
Investment Opportunities in the China Surface Treatment Market
Several openings in the China Surface Treatment Market merit attention from investors.
- Investment in Eco-Friendly Surface Treatment Technologies: The market gap for sustainable surface treatment technologies is considerable, with a $500 million investment available. Companies focusing on eco-friendly practices can target aerospace manufacturers aiming to comply with environmental regulations.
- Expansion of Surface Treatment Facilities in Guangdong: Guangdong province serves as a hub for surface treatment, with a rising need for advanced facilities. Investing in new treatment plants can address the increasing demand from the automotive sector, projected to produce 30 million vehicles by 2025.
- Supply of Advanced Coating Solutions: Electronics manufacturers are in search of high-performance coating solutions to enhance product reliability. With the electronics market expected to reach $1 trillion by 2025, suppliers can establish partnerships with local manufacturers.
- Development of Electroplating Services for Automotive Parts: The automotive sector's shift towards advanced electroplating services presents a notable opportunity, with a growth rate of 7.6%. Suppliers can collaborate with auto component manufacturers to meet rising demand.
Government Initiatives in the China Surface Treatment Market
In 2023, the Ministry of Industry and Information Technology launched the 'Advanced Manufacturing Industry Development Plan', which aims to improve surface treatment technologies. This measure builds on previous initiatives by promoting innovation and investment in the sector. The plan will increase efficiency and sustainability across surface treatment facilities, ensuring compliance with environmental regulations. Additionally, the initiative is set to support the growth of over 1,000 aerospace manufacturers in regions like Shanghai and Beijing.
The National Development and Reform Commission oversees funding for surface treatment technology upgrades, approving significant investments. In 2022, they approved a $500 million investment aimed at modernising existing facilities and improving capabilities. This funding supports the transition to more advanced and eco-friendly surface treatment processes, benefiting producers and buyers alike.
Future Insight of the China Surface Treatment Market
The China surface treatment market is set for substantial changes by 2032, driven by the 'Advanced Manufacturing Industry Development Plan' which prioritises technological advancements. The automotive sector's expected production of 30 million vehicles annually will create heightened demand for surface treatment processes. The electronics manufacturing industry is on track to reach a market size of $1 trillion by 2025, significantly boosting the need for improved surface treatment capabilities. Investments in technology upgrades, including a recent $500 million commitment, will modernise operations and enhance efficiency across the sector.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Treatment Type – Anodizing Dominated, Plating Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, the largest treatment type category in 2025 was Anodizing, with a 42% share of total revenue. Anodizing holds the largest share in China's surface treatment market as it is essential for enhancing corrosion resistance in aluminum products, particularly for aerospace applications. The presence of over 1,000 aerospace manufacturers in regions like Shanghai and Beijing underscores its critical role in this sector. Plating is projected to grow fastest, at a CAGR of 8.0% during 2026–2032. Plating is experiencing rapid growth due to its importance in improving electrical conductivity for various components, especially in the booming electronics industry. With the electronics manufacturing market expected to reach $1 trillion by 2025, the demand for plating processes will continue to surge. Suppliers should focus on enhancing anodizing capabilities while also investing in plating technologies to cater to the increasing demands from the automotive and electronics sectors.
By Process Technology – Electrochemical Dominated, Electroplating Expected to Grow Fastest
In 2025, Electrochemical led the process technology split with a 45% share. Electrochemical processes dominate the market as they are vital for both anodizing and plating, widely employed in surface treatment applications. The adherence to ISO 9001 standards among many facilities reinforces the importance of electrochemical methods in ensuring quality and reliability. Electroplating is set to record the highest CAGR in this split, 7.6% over 2026–2032. Electroplating is the fastest growing process technology, widely utilised for coating metals with another metal, particularly in the automotive and electronics sectors. With the automotive industry projected to produce 30 million vehicles annually by 2025, the demand for electroplated components is set to rise significantly. Investing in advanced electroplating technologies will be essential for suppliers to capture the growing market share driven by the expansion of the automotive industry.
By Target Material – Aluminum Dominated, Steel Expected to Grow Fastest
With a 42% revenue share in 2025, Aluminum was the largest target material category. Aluminum is the leading target material in China's surface treatment market, extensively treated for aerospace and automotive applications. The production of approximately 50 million tons of aluminum annually highlights its significance and the ongoing demand for surface treatment processes like anodizing. Over 2026–2032, Steel is expected to post the fastest growth, at a CAGR of 8.0%. Steel is the fastest growing target material as it is increasingly treated for strength and corrosion resistance in construction applications. The push for sustainable practices and environmental regulations is driving the demand for treated steel in various sectors. Suppliers should consider diversifying their offerings to include steel treatments to capitalise on the growing market opportunities in construction and infrastructure.
By End User – Aerospace OEMs Dominated, Auto Component Manufacturers Expected to Grow Fastest
Aerospace OEMs held a 35% share of the China Surface Treatment Market by end user in 2025. Aerospace OEMs command the largest share in the end user segment, relying heavily on treated components for safety and performance in aircraft. The stringent safety regulations in the aerospace sector necessitate high-quality surface treatment solutions, solidifying the dominance of aerospace OEMs. The quickest growth will come from Auto Component Manufacturers, forecast to expand at a CAGR of 7.8% between 2026 and 2032. Auto Component Manufacturers are the fastest growing end user group, driven by the increasing need for treated parts that ensure durability and performance in vehicles. With the automotive sector's projected production increase, this segment is well-positioned for continued growth. Suppliers must tailor their strategies to meet the specific requirements of auto component manufacturers, ensuring the provision of durable and high-quality surface treatment solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Surface Treatment Market Outlook
- Market Size of China Surface Treatment Market, 2025
- Forecast of China Surface Treatment Market, 2032
- Historical Data and Forecast of China Surface Treatment Revenues & Volume for the Period 2022 - 2032F
- China Surface Treatment Market Trend Evolution
- China Surface Treatment Market Drivers and Challenges
- China Surface Treatment Price Trends
- China Surface Treatment Porter's Five Forces
- China Surface Treatment Industry Life Cycle
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Treatment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Anodizing for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Plating for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Etching for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Process Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Electrochemical for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Electroplating for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Powder/Liquid for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Chemical for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Target Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Steel, Copper for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Plastics/Metal for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Glass/Semiconductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Aerospace OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Auto Component Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Industrial Equipment Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Treatment Market Revenues & Volume By Electronics Manufacturers for the Period 2022 - 2032F
- China Surface Treatment Import Export Trade Statistics
- Market Opportunity Assessment By Treatment Type
- Market Opportunity Assessment By Process Technology
- Market Opportunity Assessment By Target Material
- Market Opportunity Assessment By End User
- China Surface Treatment Top Companies Market Share
- China Surface Treatment Competitive Benchmarking By Technical and Operational Parameters
- China Surface Treatment Company Profiles
- China Surface Treatment Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Treatment Type
- Anodizing
- Plating
- Coating
- Etching
By Process Technology
- Electrochemical
- Electroplating
- Powder/Liquid
- Chemical
By Target Material
- Aluminum
- Steel
- Copper
- Plastics/Metal
- Glass/Semiconductors
By End User
- Aerospace OEMs
- Auto Component Manufacturers
- Industrial Equipment Makers
- Electronics Manufacturers































