China Surgical Wound Closure Market Size & Growth Rate
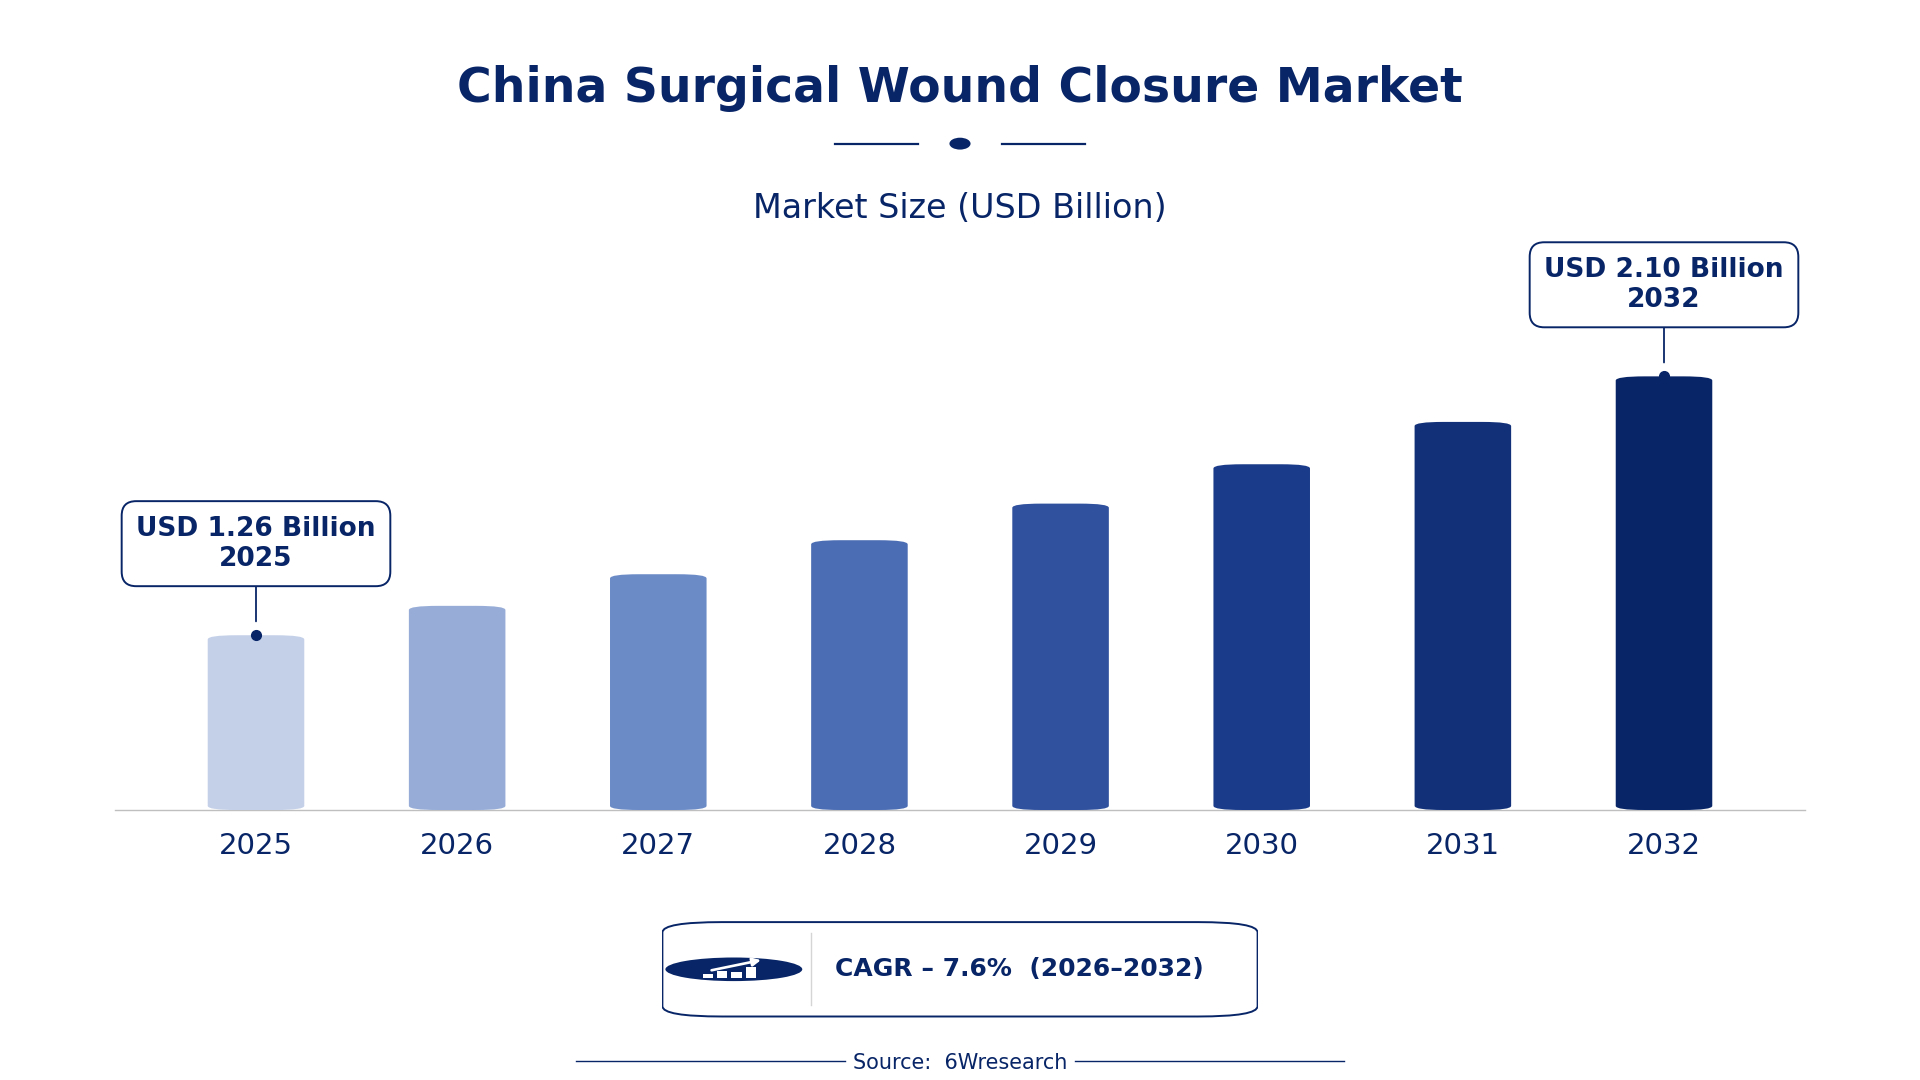
According to 6Wresearch internal database and industry insights, the China Surgical Wound Closure Market was valued at USD 1.26 billion in 2025 and is projected to reach USD 2.10 billion by 2032, growing at a CAGR of approximately 7.6% during 2026–2032.
China Surgical Wound Closure Market Highlights
| Report Metric | Details |
| Report Name | China Surgical Wound Closure Market |
| Market Size 2025 | USD 1.26 billion |
| Market Size 2032 | USD 2.10 billion |
| Absolute Growth 2025–2032 | USD 0.84 billion |
| CAGR 2026–2032 | 7.6% |
| Peak Annual Growth | 9.6% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Closure Type, 2025 | Sutures (48% share) |
| Leading Method, 2025 | Needle & Thread (44% share) |
| Leading Application Type, 2025 | Skin & Deep Tissue (51% share) |
| Leading End User, 2025 | General Surgery Centers (46% share) |
| Fastest-Growing Closure Type | Staples (8.7% CAGR) |
| Fastest-Growing Method | Mechanical Closure (10.1% CAGR) |
| Fastest-Growing Application Type | Skin/Scalp Closure (9.4% CAGR) |
| Fastest-Growing End User | ER and Trauma Units (9.8% CAGR) |
| Growing Sector | General Surgery |
| Key End Users | General Surgery Centers, ER and Trauma Units, Plastic Surgery Clinics, Outpatient Clinics |
China Surgical Wound Closure Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
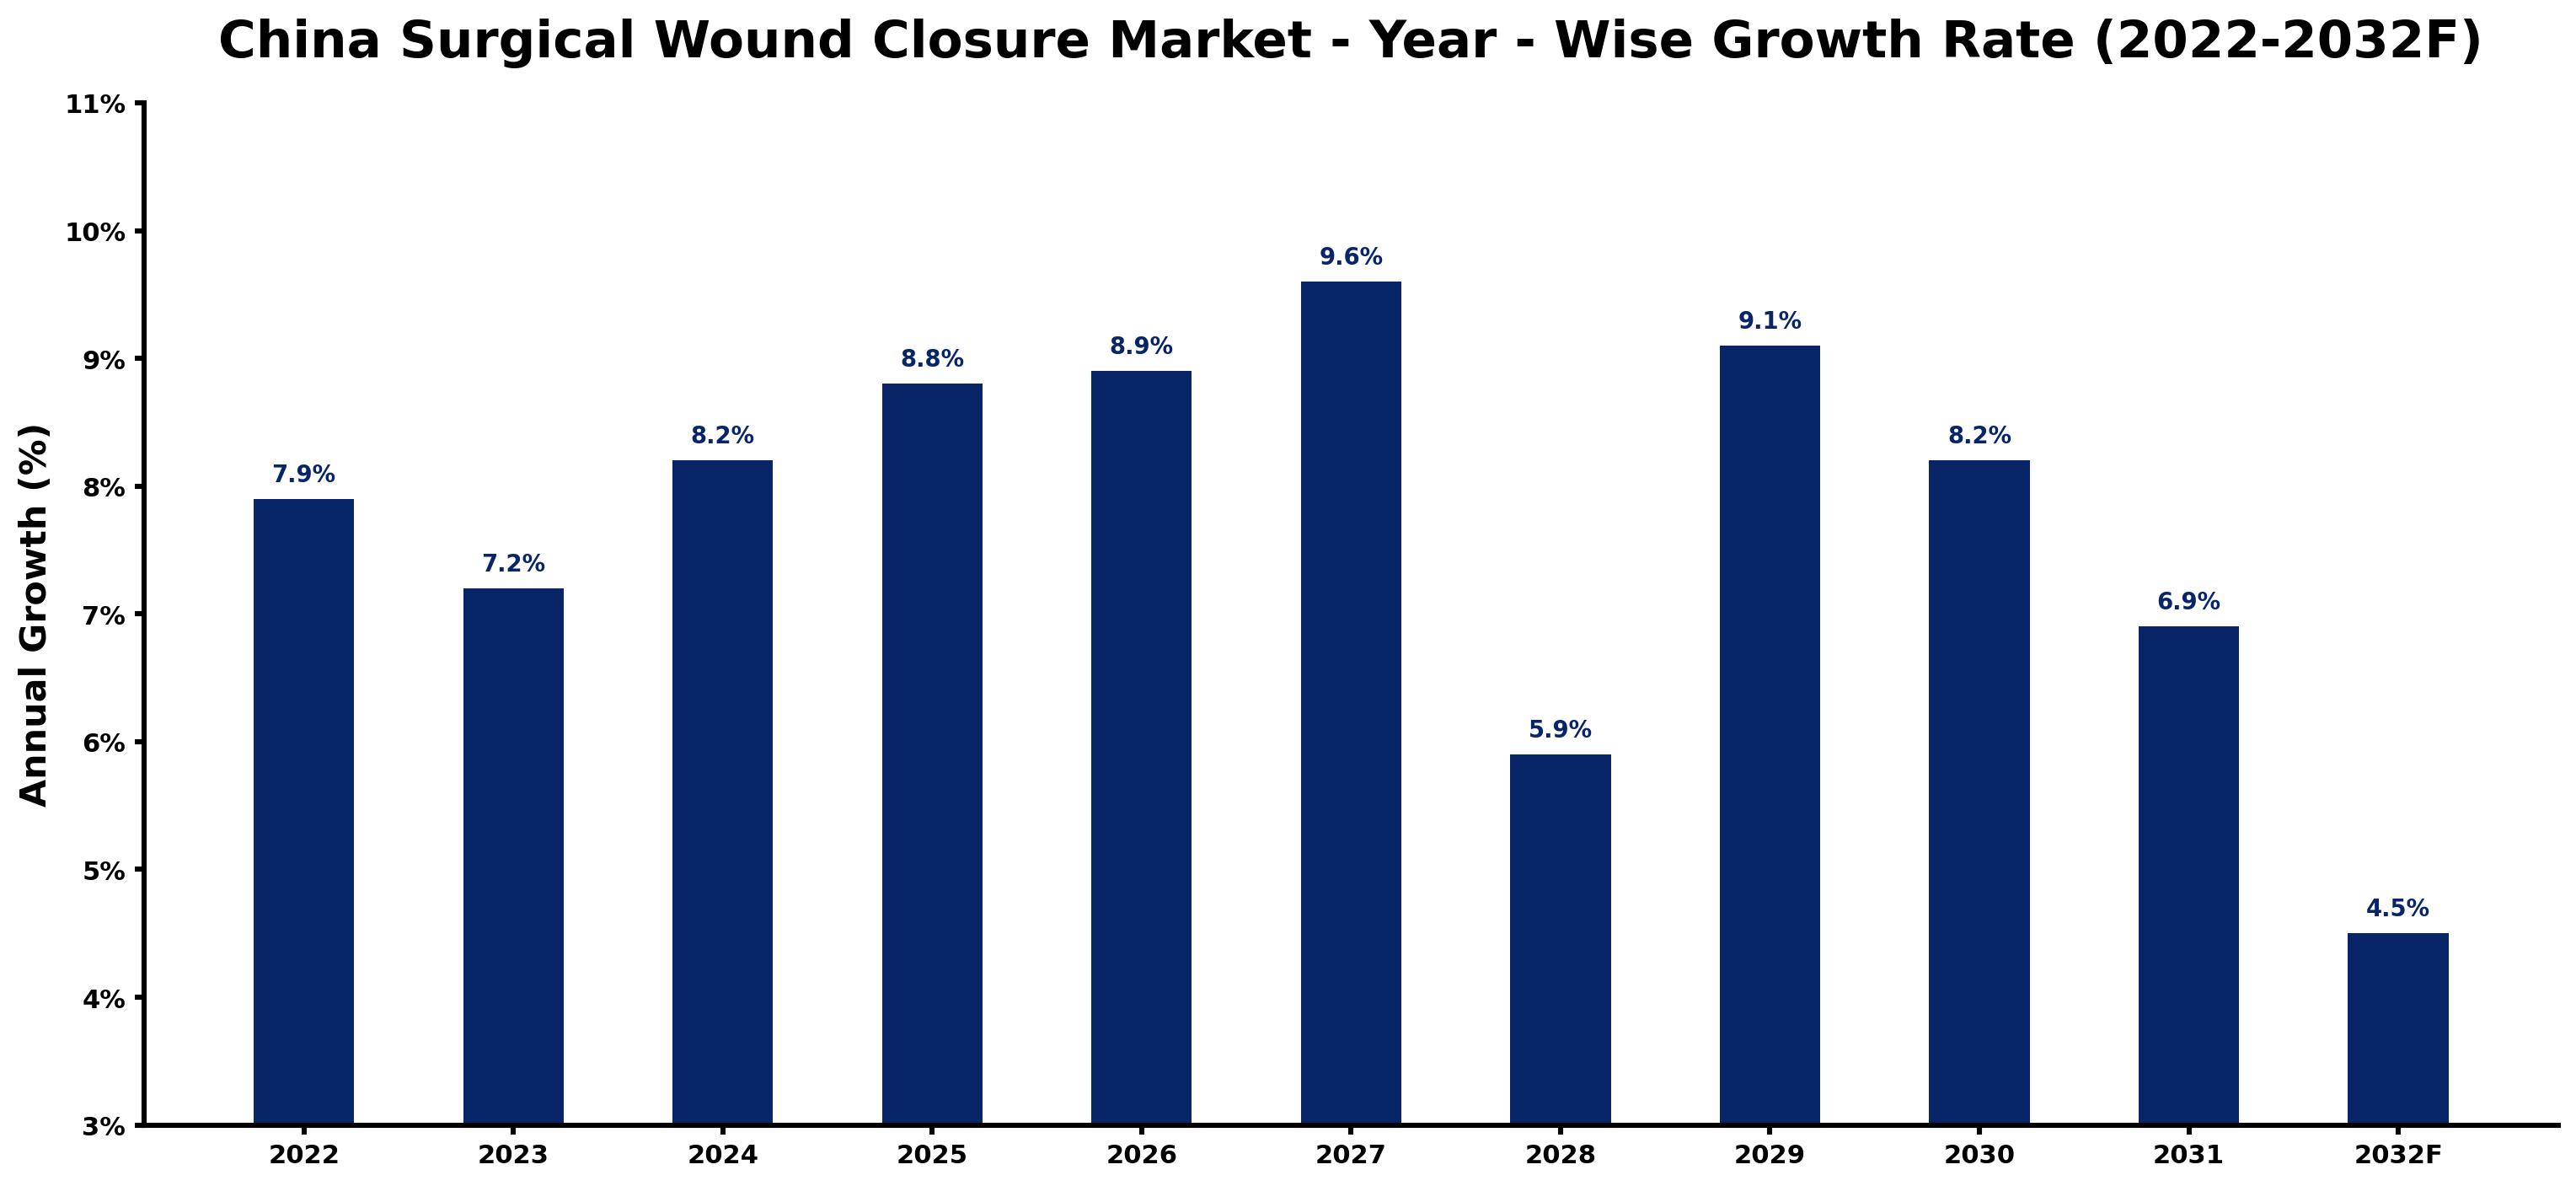
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.9 | The market experienced steady demand from hospitals and clinics across the country. |
| 2023 | 7.2 | Growth slowed slightly due to the 'Surgical Quality Improvement Program' focusing on healthcare reforms. |
| 2024 | 8.2 | Increased surgical procedures contributed to a faster growth rate this year. |
| 2025 | 8.8 | The market saw a surge in demand driven by rising surgical volumes and more ER units. |
| 2026 | 8.9 | Continued investment in healthcare infrastructure is expected to support growth in surgical closures. |
| 2027 | 9.6 | A peak in growth occurred as hospitals expanded their surgical capabilities and services. |
| 2028 | 5.9 | Growth is expected to slow as the market adjusts to increased supply and demand. |
| 2029 | 9.1 | Demand will rise again as emergency and trauma units expand services and capabilities. |
| 2030 | 8.2 | Growth is projected to slow due to market saturation in certain regions and facilities. |
| 2031 | 6.9 | The market will continue to grow but at a slower pace as competition increases. |
| 2032 | 4.5 | Growth is expected to slow further as the market stabilises and matures. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Surgical Wound Closure Market Synopsis
Surgical Wound Closure in China includes medical devices designed to close surgical incisions or wounds. These products, crafted from absorbable or non-absorbable polymers, support healing in surgical and trauma care. The China Surgical Wound Closure Market is growing due to a large population and an uptick in surgical procedures. More than 1,000 general surgery centres and 2,500 ER and trauma units contribute to this demand. Furthermore, the government's commitment to enhancing access to surgical care is prompting additional investment in this sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising surgical procedures due to population growth | Driver | High | Sutures |
| Investment in healthcare infrastructure and technology | Driver | High | Staples |
| Growing demand for surgical wound closure products in rural areas | Opportunity | High | General Surgery Centers |
| Increasing prevalence of cosmetic surgeries driving tissue adhesive use | Opportunity | Medium | Plastic Surgery Clinics |
| Regulatory challenges in product approval processes | Restraint | High | Tissue Adhesives |
| Limited awareness of advanced closure methods among practitioners | Restraint | Medium | Needle & Thread |
| Supply chain disruptions affecting product availability | Challenge | High | Mechanical Closure |
| Competition from alternative wound closure methods | Challenge | Medium | Adhesive Strips |
Evaluation of Drivers in China Surgical Wound Closure Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing surgical procedures leading to higher demand for closures | Sutures | In 2022, the average hospital performed thousands of surgeries, increasing the need for sutures. |
| Investment in healthcare infrastructure enhances surgical capabilities | Staples | China's healthcare expenditure reached 7.1% of GDP in 2022, boosting demand for staples. |
| Rising demand for cosmetic surgeries drives tissue adhesive use | Tissue Adhesives | Plastic surgery clinics in China conduct over 10 million procedures annually, increasing adhesive demand. |
| Growth in emergency and trauma units expands closure product usage | Mechanical Closure | Approximately 2,500 ER and trauma units operate across China, requiring efficient closure solutions. |
| Government initiatives to improve surgical care access | General Surgery Centers | The 'Healthcare Reform Plan 2021-2025' aims to enhance surgical services in rural areas. |
Growth across the Surgical Wound Closure market in China is anchored in rising surgical procedures, investment in healthcare infrastructure, and increasing demand for cosmetic surgeries. The average hospital performs thousands of surgeries annually, driving the need for sutures. China's healthcare expenditure reached 7.1% of GDP in 2022, which boosts demand for surgical products. Over 10 million cosmetic procedures are conducted each year, increasing the use of tissue adhesives. The 'Healthcare Reform Plan 2021-2025' aims to improve surgical care access, expanding the market for general surgery centers.
Evaluation of Restraints in China Surgical Wound Closure Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory challenges in product approval processes | Tissue Adhesives | The National Medical Products Administration's regulations can delay new product introductions by several months. |
| Limited awareness of advanced closure methods among practitioners | Needle & Thread | Many practitioners still rely on traditional methods, limiting market growth and innovation. |
| High costs associated with advanced surgical products | Staples | Budget constraints in some healthcare facilities restrict the adoption of newer technologies, limiting options. |
| Supply chain disruptions affecting product availability | Mechanical Closure | Global supply chain issues have impacted the timely availability of closure products, affecting hospitals. |
| Competition from alternative wound closure methods | Adhesive Strips | Increasing popularity of non-invasive closure options limits demand for adhesive strips in hospitals. |
China Surgical Wound Closure Market Challenges
In the China surgical wound closure market, buyers face technological limitations as many hospitals continue to depend on traditional sutures and staples, which can extend recovery times for patients. Suppliers encounter regulatory challenges from the National Medical Products Administration, resulting in product approval delays that may last up to six months. Hospitals are grappling with rising costs, with healthcare expenditure at 7.1% of GDP in 2022, forcing them to allocate more funds for essential surgical products. Competition intensifies as over 1,000 general surgery centres and 30,000 outpatient clinics increase their demand for effective closure solutions, compelling suppliers to innovate swiftly to stay relevant in the market.
Trends in the China Surgical Wound Closure Market
Four trends stand out in the China Surgical Wound Closure Market.
- Shift towards Advanced Closure Techniques: China is experiencing a shift towards advanced closure techniques in surgical procedures. The 'Surgical Quality Improvement Program' launched in 2021 aims to improve outcomes across hospitals, targeting enhancements in surgical practices.
- Increase in Cosmetic Surgery Demand: The demand for cosmetic surgeries is rising significantly in urban areas. With over 10 million procedures performed annually, this trend drives the use of tissue adhesives in cosmetic surgery.
- Expansion of ER and Trauma Services: Emergency and trauma units are expanding their services to meet rising demand. With approximately 2,500 units operating, there is a growing need for efficient wound closure products.
- Focus on Rural Surgical Care: The government is prioritising surgical care access in rural areas. The 'Healthcare Reform Plan 2021-2025' aims to improve surgical services, impacting the demand for wound closure products.
Investment Opportunities in the China Surgical Wound Closure Market
The following opportunities in the China Surgical Wound Closure Market pair current demand with a clear way in.
- Partnerships for Local Manufacturing: Now is an opportune time for collaborations to boost local manufacturing capabilities. The 'National Medical Device Innovation Strategy' encourages local production, creating investment opportunities for suppliers.
- Investment in Rural Healthcare Facilities: With a target of improving surgical care access by 2025, there is a significant opportunity to invest in rural healthcare facilities. General Surgery Centres in these areas are expanding services.
- Growing Market for Tissue Adhesives: The demand for tissue adhesives is expected to rise, particularly in urban cosmetic surgery clinics. Investing in this segment can meet the needs of the growing market.
- Expansion of Outpatient Clinics: With over 30,000 outpatient clinics in China, there is a need for efficient wound closure products. Suppliers can enter this market through local partnerships.
Government Initiatives in the China Surgical Wound Closure Market
Healthcare providers, particularly general surgery centres, benefit from the 'Surgical Quality Improvement Program' launched in 2021. This initiative provides funding for training and resources to improve surgical practices. The National Medical Products Administration oversees the 'Medical Device Registration Pathway', which streamlines approvals for new surgical closure technologies. This pathway facilitates quicker access to innovative products, helping healthcare providers meet the growing need for effective wound closure solutions.
The 'National Medical Device Innovation Strategy' approved in 2022 promotes local manufacturing of surgical products. This strategy encourages investment in domestic production, allowing healthcare facilities to access advanced surgical wound closure solutions. The Ministry of Health's 'Healthcare Reform Plan 2021-2025' aims to increase the availability of surgical services in rural areas, impacting demand for wound closure products across the country.
Future Insight of the China Surgical Wound Closure Market
The China surgical wound closure market will experience greater access to advanced products by 2032, driven by the government's health improvement strategy focused on surgical care in rural areas. Increased investment in healthcare infrastructure will facilitate the adoption of innovative closure technologies, benefiting hospitals and suppliers. The growing demand for cosmetic procedures will heighten the need for advanced closure methods, particularly in urban centres. By 2025, the emphasis on improving surgical standards will likely lead to higher quality and more diverse product offerings in the market.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Closure Type – Sutures Dominated, Staples Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, with a 48% revenue share in 2025, Sutures was the largest closure type category. Sutures hold the largest market share as they are the primary method for closing wounds and incisions in China's healthcare facilities. Their extensive application in over 1,000 general surgery centers highlights their essential role in surgical procedures. Staples are projected to grow fastest, at a CAGR of 8.7% during 2026–2032. Staples are gaining popularity due to their efficiency in providing quick closure during surgeries, which is crucial as the number of procedures increases annually. This trend is further amplified by the rising demand for streamlined surgical processes. Suppliers should prioritise product development in sutures and staples to effectively capture the growing market share.
By Method – Needle & Thread Dominated, Mechanical Closure Expected to Grow Fastest
The largest method category in 2025 was Needle & Thread, with a 44% share of total revenue. Needle & Thread is the leading method for wound closure, as it remains the traditional choice widely adopted in surgical practices across China. Its established presence in thousands of surgeries performed each year reinforces its dominant market position. Over 2026–2032, Mechanical Closure is expected to post the fastest growth, at a CAGR of 10.1%. Mechanical Closure is experiencing rapid growth due to its efficiency in various surgical settings, meeting the increasing demand for quicker surgical procedures. This trend is supported by heightened investments in healthcare aimed at improving surgical care. Buyers may benefit by exploring advanced mechanical closure solutions to enhance overall surgical efficiency.
By Application Type – Skin & Deep Tissue Dominated, Skin/Scalp Closure Expected to Grow Fastest
Skin & Deep Tissue took a 51% share of application type in 2025, more than any other category. Skin & Deep Tissue is the leading application area for wound closure, reflecting the substantial need for effective healing in surgical procedures across China. The large population requiring surgical interventions ensures this segment captures a significant market share. Skin/Scalp Closure is set to record the highest CAGR in this split, 9.4% over 2026–2032. Skin/Scalp Closure is witnessing the fastest growth as it addresses specific surgical needs, particularly in trauma and emergency care. The expansion of ER and trauma units drives the increasing demand for targeted solutions in this area. Suppliers should focus on developing specialised products for skin and scalp closure to align with the evolving market demands.
By End User – General Surgery Centers Dominated, ER and Trauma Units Expected to Grow Fastest
General Surgery Centers held a 46% share of the China Surgical Wound Closure Market by end user in 2025. General Surgery Centers dominate the market as the primary end user for surgical closures, given their critical role in performing numerous surgeries. The high volume of procedures conducted in these facilities drives the demand for wound closure products. The quickest growth will come from ER and Trauma Units, forecast to expand at a CAGR of 9.8% between 2026 and 2032. ER and Trauma Units are experiencing the fastest growth due to their critical need for emergency wound closure solutions, particularly as the number of trauma cases rises. This segment's growth is supported by the increasing number of ER units operating across China. Suppliers should prioritise partnerships with ER and trauma units to align with their urgent needs for wound closure products.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Surgical Wound Closure Market Outlook
- Market Size of China Surgical Wound Closure Market, 2025
- Forecast of China Surgical Wound Closure Market, 2032
- Historical Data and Forecast of China Surgical Wound Closure Revenues & Volume for the Period 2022 - 2032F
- China Surgical Wound Closure Market Trend Evolution
- China Surgical Wound Closure Market Drivers and Challenges
- China Surgical Wound Closure Price Trends
- China Surgical Wound Closure Porter's Five Forces
- China Surgical Wound Closure Industry Life Cycle
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Closure Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Sutures for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Staples for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Adhesive Strips for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Tissue Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Needle & Thread for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Mechanical Closure for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By External Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Liquid Glue for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Application Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Skin & Deep Tissue for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Skin/Scalp Closure for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Minor Cuts/Incisions for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Cosmetic and Pediatric Use for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By General Surgery Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By ER and Trauma Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Outpatient Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of China Surgical Wound Closure Market Revenues & Volume By Plastic Surgery Clinics for the Period 2022 - 2032F
- China Surgical Wound Closure Import Export Trade Statistics
- Market Opportunity Assessment By Closure Type
- Market Opportunity Assessment By Method
- Market Opportunity Assessment By Application Type
- Market Opportunity Assessment By End User
- China Surgical Wound Closure Top Companies Market Share
- China Surgical Wound Closure Competitive Benchmarking By Technical and Operational Parameters
- China Surgical Wound Closure Company Profiles
- China Surgical Wound Closure Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Closure Type
- Sutures
- Staples
- Adhesive Strips
- Tissue Adhesives
By Method
- Needle & Thread
- Mechanical Closure
- External Bonding
- Liquid Glue
By Application Type
- Skin & Deep Tissue
- Skin/Scalp Closure
- Minor Cuts/Incisions
- Cosmetic and Pediatric Use
By End User
- General Surgery Centers
- ER and Trauma Units
- Outpatient Clinics
- Plastic Surgery Clinics































