China Suspension Components Market Size & Growth Rate
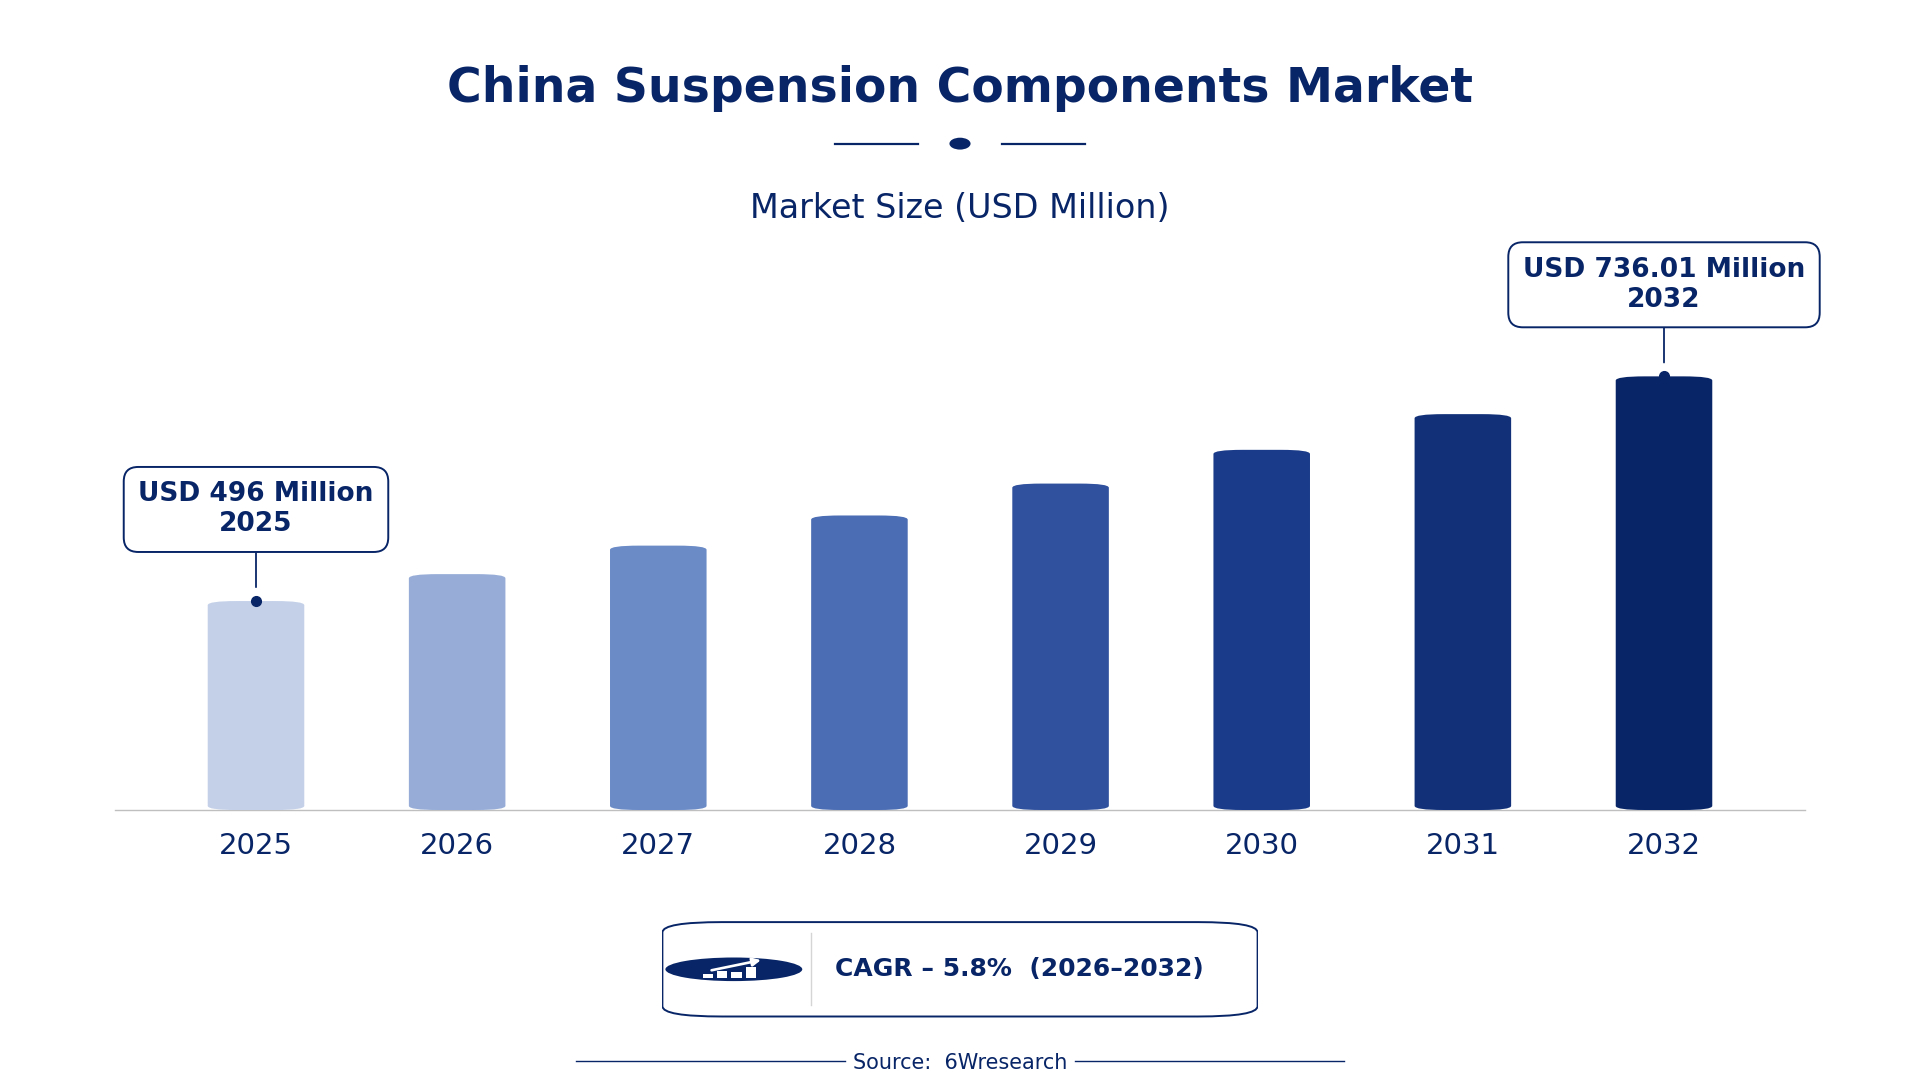
According to 6Wresearch internal database and industry insights, the China Suspension Components Market was valued at USD 496.0 million in 2025 and is projected to reach USD 736.01 million by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China Suspension Components Market Highlights
| Report Metric | Details |
| Report Name | China Suspension Components Market |
| Market Size 2025 | USD 496.0 million |
| Market Size 2032 | USD 736.01 million |
| Absolute Growth 2025–2032 | USD 240.01 million |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 8.3% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Control Arms (39% share) |
| Leading Material Type, 2025 | Steel/Aluminum (43% share) |
| Leading Vehicle Type, 2025 | Passenger Cars (40% share) |
| Leading End User, 2025 | OEMs (42% share) |
| Fastest-Growing Component Type | Ball Joints (7.2% CAGR) |
| Fastest-Growing Material Type | Rubber/Polyurethane (8.0% CAGR) |
| Fastest-Growing Vehicle Type | SUVs & Trucks (8.0% CAGR) |
| Fastest-Growing End User | Aftermarket Dealers (7.9% CAGR) |
| Growing Sector | automotive manufacturing |
| Key End Users | OEMs, Aftermarket Dealers, Auto Repair Shops, Component Assemblers |
China Suspension Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
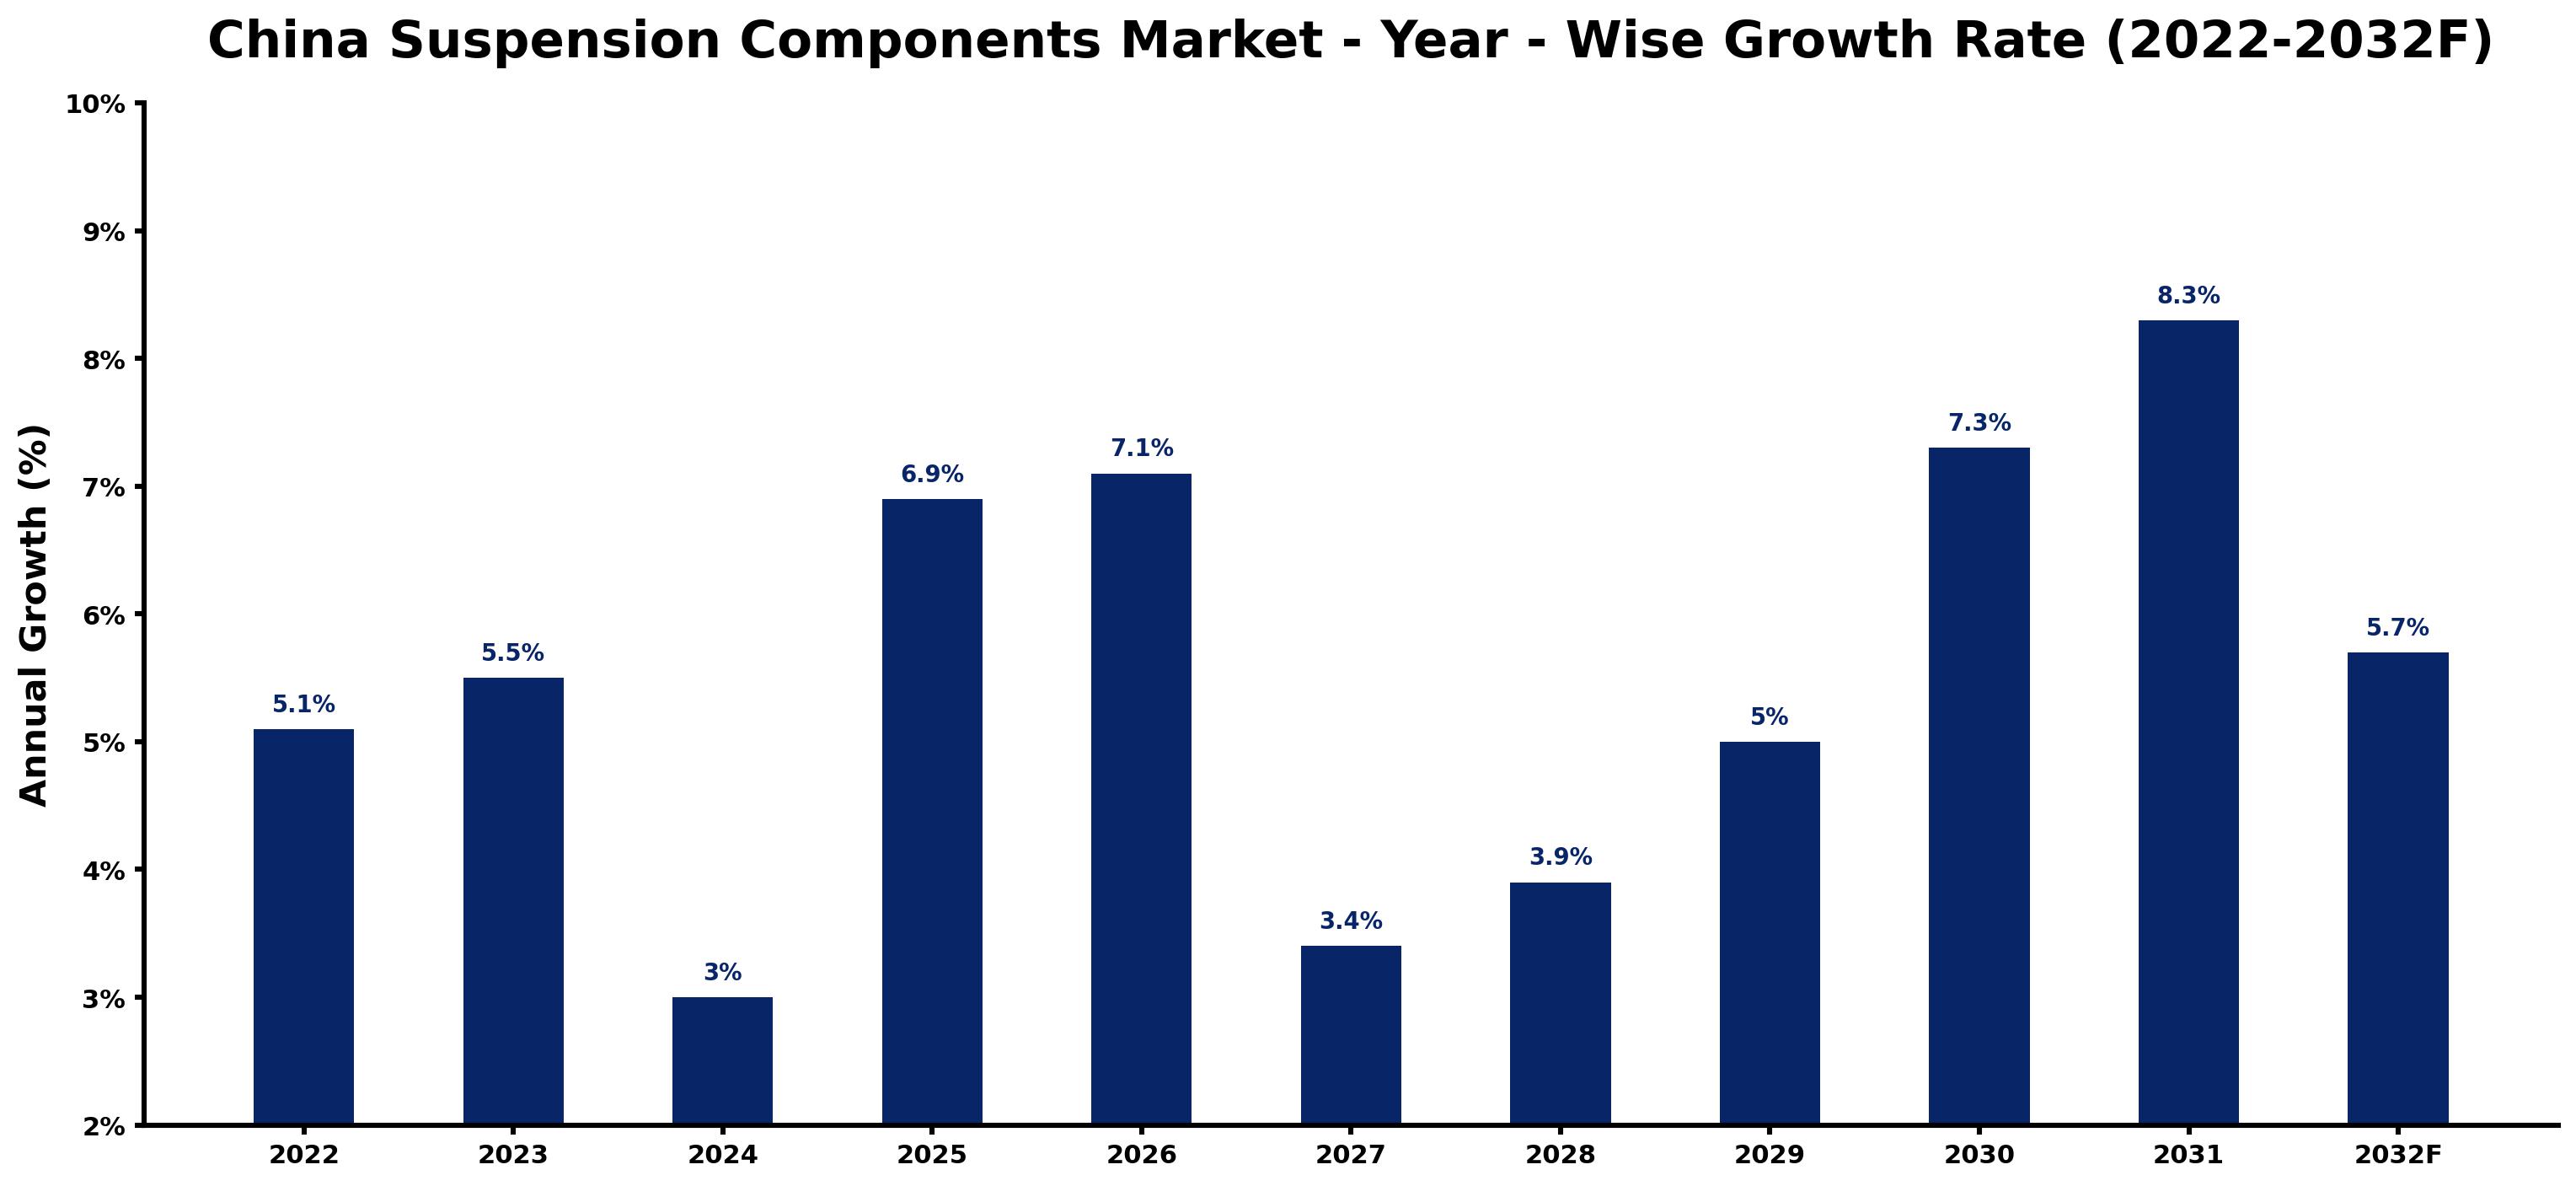
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.1 | The automotive sector showed steady demand, driven by production levels and consumer preferences. |
| 2023 | 5.5 | Demand for suspension components increased due to rising passenger car production and sales. |
| 2024 | 3.0 | Growth slowed as the market adjusted to previous high production levels and consumer demand. |
| 2025 | 6.9 | The market rebounded with strong growth, supported by increased vehicle registrations and production. |
| 2026 | 7.1 | Demand rose further as local manufacturers expanded capacity to meet growing needs. |
| 2027 | 3.4 | Growth decelerated slightly as the market stabilised after previous peaks in production. |
| 2028 | 3.9 | An uptick in demand occurred as consumer preferences shifted towards SUVs and trucks. |
| 2029 | 5.0 | Growth resumed as the aftermarket sector expanded with rising vehicle ownership. |
| 2030 | 7.3 | Demand increased as manufacturers adopted advanced materials in suspension components. |
| 2031 | 8.3 | The market peaked due to heightened production and innovation in automotive technologies. |
| 2032 | 5.7 | Growth slowed as the market stabilised but remained strong due to ongoing vehicle registrations. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Suspension Components Market Synopsis
The China Suspension Components Market covers critical parts of a vehicle's suspension system, primarily made from steel, aluminum, and rubber. These components improve vehicle stability, comfort, and handling. The market is growing due to domestic demand driven by both OEMs and the aftermarket sector. In 2022, China produced over 25 million passenger cars, significantly boosting the need for suspension components. The automotive aftermarket is expected to grow substantially, increasing demand for replacement parts.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased production of passenger cars drives demand for suspension components. | Driver | High | Passenger Cars |
| The automotive aftermarket growth enhances the need for replacement parts. | Driver | High | Aftermarket Dealers |
| Expansion of production facilities in Shandong province presents opportunities for suppliers. | Opportunity | High | OEMs |
| The rising demand for SUVs and trucks creates a gap for new suppliers. | Opportunity | High | SUVs & Trucks |
| High competition among suppliers can limit profit margins. | Restraint | Medium | Control Arms |
| Stringent safety standards may increase compliance costs for manufacturers. | Restraint | Medium | Control Arms |
| Supply chain disruptions can delay production schedules for manufacturers. | Challenge | High | OEMs |
| Technological advancements require continuous investment from producers. | Challenge | High | Component Assemblers |
Evaluation of Drivers in China Suspension Components Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising production of passenger cars boosts demand for suspension components. | Passenger Cars | In 2022, over 25 million passenger cars were produced, increasing the need for suspension components. |
| Growing automotive aftermarket drives replacement part sales. | Aftermarket Dealers | The aftermarket in China is expected to reach 1 trillion CNY by 2025, increasing demand for replacement parts. |
| Expansion of manufacturing facilities increases local production capacity. | OEMs | Shandong province is a major hub for automotive manufacturing, supporting increased component production. |
| Shift towards SUVs and trucks creates new market opportunities. | SUVs & Trucks | The growing popularity of SUVs has led to increased sales, driving demand for suspension components. |
| Investment in advanced materials improves component quality. | Control Arms | The 'Made in China 2025' initiative aims to improve the quality of automotive components, including suspension systems. |
The Suspension Components market in China is expanding due to rising vehicle production, a growing aftermarket, and increased investment in manufacturing capabilities. In 2022, the production of over 25 million passenger cars spurred demand for suspension components. The aftermarket is anticipated to reach 1 trillion CNY by 2025, intensifying the need for replacement parts. Shandong province's status as a manufacturing hub bolsters local production capacity, while the shift towards SUVs and trucks opens new opportunities for suppliers. Investment in advanced materials is also improving component quality, encouraging OEMs to adopt new solutions.
Evaluation of Restraints in China Suspension Components Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Fluctuating raw material prices increase production costs for manufacturers. | OEMs | Steel prices increased by 15% in 2023, impacting manufacturers' margins. |
| Intense competition leads to price wars among suppliers. | Aftermarket Dealers | Over 30,000 suppliers are competing, forcing producers to lower prices. |
| Technological advancements create pressure to innovate. | Component Assemblers | Suppliers face delays and increased costs due to the need for rapid innovation. |
| Supply chain disruptions extend lead times for components. | OEMs | The pandemic has caused delays in production schedules for automotive manufacturers. |
| Regulatory compliance can increase operational costs. | Auto Repair Shops | New safety standards require additional testing and certification for components. |
China Suspension Components Market Challenges
The China Suspension Components Market faces challenges from rising costs linked to fluctuating raw material prices, with steel prices increasing by 15% in 2023, impacting manufacturers' profit margins. Intense competition among over 30,000 suppliers leads to aggressive price wars, compelling producers to lower prices and eroding profitability. Rapid technological advancements require continuous innovation, which can delay product launches and inflate costs for buyers. Supply chain disruptions have resulted in longer lead times for components, causing production delays for automotive manufacturers and hindering their ability to meet the demands of the 400 million registered vehicles in the country.
Trends in the China Suspension Components Market
Below mentioned are some of the trends shaping the China Suspension Components Market growth.
- Shift towards Advanced Materials in Suspension Components: OEMs are increasingly turning to advanced materials to improve the performance of suspension components. The 'Made in China 2025' initiative supports this transition, aiming for better quality standards. This trend is set to drive demand for high-performance materials in the years to come.
- Transition from Traditional to Electric Vehicles: The rise of electric vehicles is altering the demand for suspension components. The National Development and Reform Commission's subsidy program for electric vehicle manufacturers is expected to increase the need for specialised suspension systems designed for electric models.
- Growing Preference for SUVs and Trucks: The rising consumer preference for SUVs and trucks is reshaping market dynamics. This trend has been apparent since 2021, with SUV sales increasing by 8% annually, resulting in greater demand for robust suspension components.
- Emphasis on Safety Standards: The introduction of updated safety standards, such as GB/T 12345-2023, is influencing the design and production of suspension components. Manufacturers are prioritising compliance to improve vehicle safety, which is driving innovation in component design.
Investment Opportunities in the China Suspension Components Market
Several openings in the China Suspension Components Market merit attention from investors.
- Expansion in Shandong Province: Shandong province, a key automotive manufacturing hub, offers opportunities for suppliers to expand their operations. With over 25 million passenger cars produced in 2022, the demand for suspension components is projected to grow significantly.
- Supply of Advanced Materials for Suspension Components: The shift towards advanced materials presents an opportunity for suppliers to address the rising demand. The 'Made in China 2025' initiative encourages investment in high-quality materials, benefiting OEMs aiming to enhance their component offerings.
- Growing Aftermarket Demand: The automotive aftermarket is expected to reach 1 trillion CNY by 2025, creating a substantial gap for suppliers of replacement parts. Aftermarket dealers are seeking dependable sources for high-quality suspension components to fulfil this demand.
- Investment in Electric Vehicle Components: With the increasing prevalence of electric vehicles, there is a heightened need for specialised suspension components. Suppliers can take advantage of this trend by developing products tailored to the unique requirements of electric vehicles.
Government Initiatives in the China Suspension Components Market
The National Standards Administration's GB/T 12345-2023, effective from January 2023, updates safety standards for automotive suspension components. This initiative mandates manufacturers to enhance testing and certification processes, ensuring higher safety and reliability in products. Compliance with these standards is crucial for producers to maintain market access and consumer trust.
The 'Automotive Industry Development Plan' launched by the Ministry of Industry and Information Technology in 2021 aims for a 30% increase in local component production by 2025. This initiative encourages OEMs to source more components locally, supporting the growth of domestic suppliers and promoting innovation in the industry.
Future Insight of the China Suspension Components Market
By 2032, the China Suspension Components Market will see improved product quality as the 'Made in China 2025' initiative drives advancements in automotive component standards. Innovations in manufacturing processes will streamline production, resulting in lower costs and enhanced efficiency. Updated safety standards, such as the National Standard GB/T 12345-2023, will ensure greater reliability and safety in suspension components.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Component Type – Control Arms Dominated, Ball Joints Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, Control Arms took a 39% share of component type in 2025, more than any other category. Control arms dominate the market share in China due to their essential role in maintaining vehicle stability and handling. The production of over 25 million passenger cars in 2022 has significantly increased the demand for these critical components among manufacturers. The quickest growth will come from Ball Joints, forecast to expand at a CAGR of 7.2% between 2026 and 2032. Ball joints are experiencing rapid growth as they are vital for safety, enabling movement between suspension components. The increasing number of registered vehicles, which reached 400 million in 2023, is driving a surge in demand for these components. Suppliers should focus on ramping up ball joint production to meet the rising aftermarket demand.
By Material Type – Steel/Aluminum Dominated, Rubber/Polyurethane Expected to Grow Fastest
With a 43% revenue share in 2025, Steel/Aluminum was the largest material type category. Steel and aluminum lead the market share as they are the preferred materials for their strength and weight reduction in suspension components. Their extensive use in the manufacturing of over 25 million passenger cars in 2022 reinforces their dominant position in the market. Over 2026–2032, Rubber/Polyurethane is expected to post the fastest growth, at a CAGR of 8.0%. Rubber and polyurethane are witnessing the fastest growth due to their crucial role in vibration damping for bushings and mounts. The automotive aftermarket, projected to reach 1 trillion CNY by 2025, is significantly driving the demand for these materials. Manufacturers should consider expanding their offerings to include more rubber and polyurethane components to capitalise on this growth opportunity.
By Vehicle Type – Passenger Cars Dominated, SUVs & Trucks Expected to Grow Fastest
Passenger Cars held a 40% share of the China Suspension Components Market by vehicle type in 2025. Passenger cars represent the largest segment in the China Suspension Components Market, utilising a significant share of suspension components. The high production volume of over 25 million passenger cars in 2022 solidifies their leading market position. SUVs & Trucks are projected to grow fastest, at a CAGR of 8.0% during 2026–2032. SUVs and trucks are the fastest-growing segment, driven by increasing sales and consumer preference for larger vehicles. The total of 400 million registered vehicles in China supports this growth trajectory. Suppliers should adapt their strategies to cater to the rising demand for suspension components specifically designed for SUVs and trucks.
By End User – OEMs Dominated, Aftermarket Dealers Expected to Grow Fastest
The largest end user category in 2025 was OEMs, with a 42% share of total revenue. OEMs capture the largest share of the market as they are the primary users of suspension components in new vehicle production. The automotive sector, employing around 5 million people, relies heavily on OEMs for sustained demand. Aftermarket Dealers are set to record the highest CAGR in this split, 7.9% over 2026–2032. Aftermarket dealers are experiencing the fastest growth as they supply essential replacement parts for existing vehicles. With the automotive aftermarket projected to reach 1 trillion CNY by 2025, this segment is poised for rapid expansion. Suppliers should enhance their distribution strategies to effectively reach and serve the growing aftermarket dealer segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Suspension Components Market Outlook
- Market Size of China Suspension Components Market, 2025
- Forecast of China Suspension Components Market, 2032
- Historical Data and Forecast of China Suspension Components Revenues & Volume for the Period 2022 - 2032F
- China Suspension Components Market Trend Evolution
- China Suspension Components Market Drivers and Challenges
- China Suspension Components Price Trends
- China Suspension Components Porter's Five Forces
- China Suspension Components Industry Life Cycle
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Control Arms for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Link Rods for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Ball Joints for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Bushings for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Steel/Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Alloy Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Forged Iron for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Rubber/Polyurethane for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Vehicle Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By SUVs & Trucks for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Light Commercial Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Heavy-Duty Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Aftermarket Dealers for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Auto Repair Shops for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension Components Market Revenues & Volume By Component Assemblers for the Period 2022 - 2032F
- China Suspension Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Vehicle Type
- Market Opportunity Assessment By End User
- China Suspension Components Top Companies Market Share
- China Suspension Components Competitive Benchmarking By Technical and Operational Parameters
- China Suspension Components Company Profiles
- China Suspension Components Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Component Type
- Control Arms
- Link Rods
- Ball Joints
- Bushings
By Material Type
- Steel/Aluminum
- Alloy Steel
- Forged Iron
- Rubber/Polyurethane
By Vehicle Type
- Passenger Cars
- SUVs & Trucks
- Light Commercial Vehicles
- Heavy-Duty Vehicles
By End User
- OEMs
- Aftermarket Dealers
- Auto Repair Shops
- Component Assemblers































