China Suspension & Handling Parts Market Size & Growth Rate
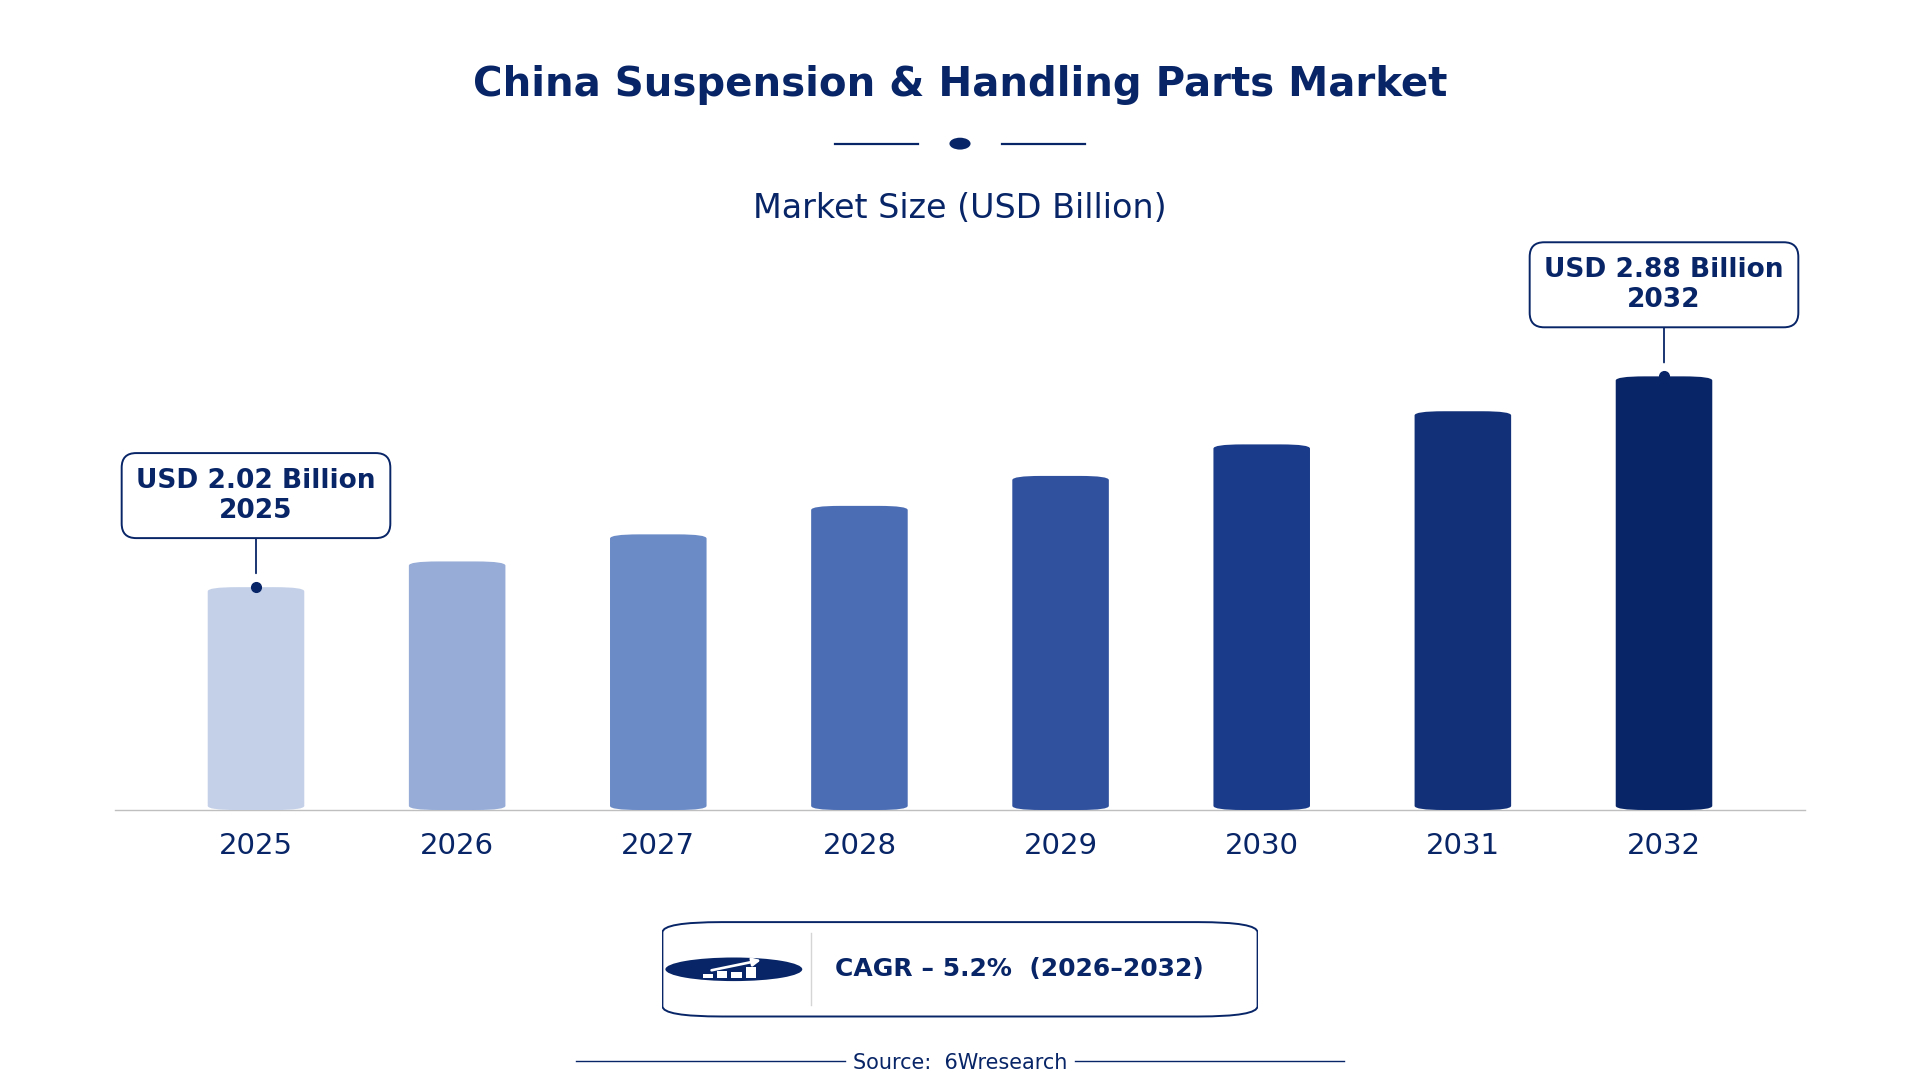
According to 6Wresearch internal database and industry insights, the China Suspension & Handling Parts Market was valued at USD 2.02 billion in 2025 and is projected to reach USD 2.88 billion by 2032, growing at a CAGR of approximately 5.2% during 2026–2032.
China Suspension & Handling Parts Market Highlights
| Report Metric | Details |
| Report Name | China Suspension & Handling Parts Market |
| Market Size 2025 | USD 2.02 billion |
| Market Size 2032 | USD 2.88 billion |
| Absolute Growth 2025–2032 | USD 0.86 billion |
| CAGR 2026–2032 | 5.2% |
| Peak Annual Growth | 7.4% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Part Type, 2025 | Shock Absorbers (44% share) |
| Leading Vehicle Segment, 2025 | Passenger/Commercial (45% share) |
| Leading Material Type, 2025 | Steel (37% share) |
| Leading End User, 2025 | OEMs (50% share) |
| Fastest-Growing Part Type | Control Arms (7.8% CAGR) |
| Fastest-Growing Vehicle Segment | Light/Heavy Vehicles (7.5% CAGR) |
| Fastest-Growing Material Type | Forged Aluminum (7.0% CAGR) |
| Fastest-Growing End User | Aftermarket Suppliers (6.4% CAGR) |
| Growing Sector | automotive aftermarket |
| Key End Users | OEMs, Aftermarket Suppliers, Auto Service Providers, Vehicle Manufacturers |
China Suspension & Handling Parts Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
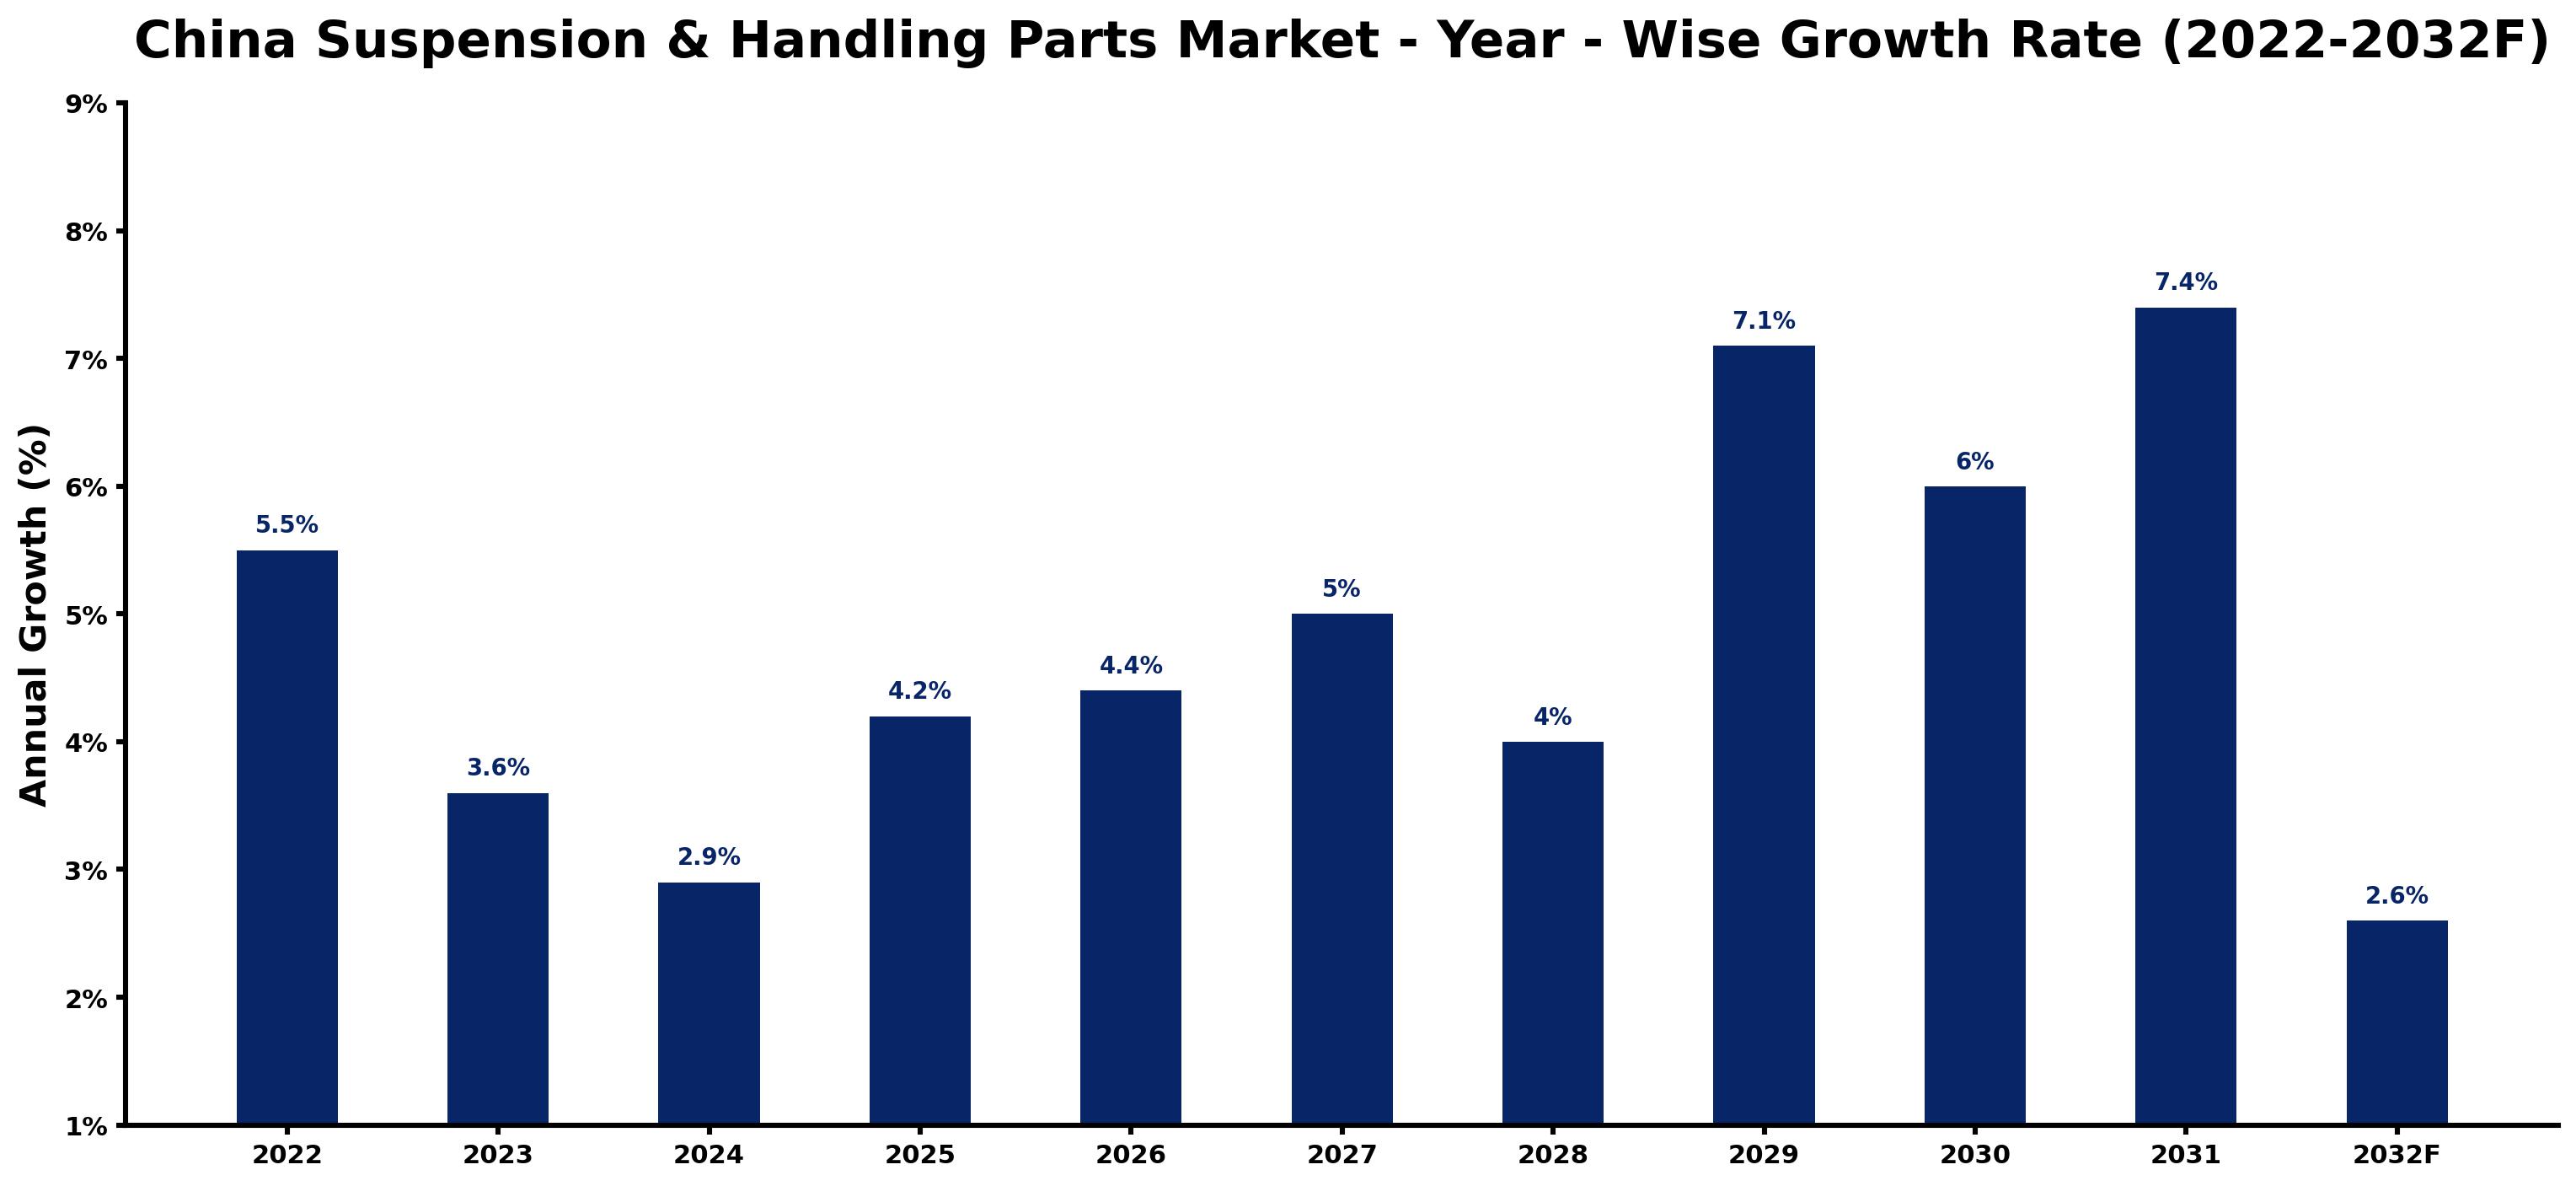
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.5 | The automotive industry was active, with substantial vehicle production driving demand for parts. |
| 2023 | 3.6 | Demand growth slowed due to the 'Automotive Aftermarket Development Initiative' focusing on service quality improvements. |
| 2024 | 2.9 | Continued demand for vehicles led to a further slowdown as supply chain issues persisted. |
| 2025 | 4.2 | A recovery in vehicle sales boosted demand for suspension parts as manufacturers ramped up production. |
| 2026 | 4.4 | The introduction of new vehicle models will spur demand for suspension components under the 'Automotive Standards Revision Program'. |
| 2027 | 5.0 | Rising vehicle ownership and urbanisation will increase the need for suspension parts in various vehicles. |
| 2028 | 4.0 | Demand growth will slow as the market stabilises after previous surges in production. |
| 2029 | 7.1 | A renewed focus on electric vehicles will stimulate demand for advanced suspension technologies due to the 'New Energy Vehicle Industry Development Plan'. |
| 2030 | 6.0 | Demand growth will slow as the market adjusts to new industry standards and consumer trends. |
| 2031 | 7.4 | The peak growth will be driven by increased production capacity and new automotive technologies. |
| 2032 | 2.6 | A slowdown in growth is anticipated as the market matures and competition intensifies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Suspension & Handling Parts Market Synopsis
Suspension & Handling Parts in China encompasses components used in vehicle suspension systems to enhance ride quality and handling. These parts, made from materials like steel and rubber, are essential for improving vehicle stability and safety. The China Suspension & Handling Parts Market is experiencing growth due to rising vehicle production and a burgeoning automotive aftermarket. With over 25 million vehicles produced in 2022, demand is expected to continue from both OEMs and aftermarket suppliers. The government's initiatives to support green technologies further drive this market's expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased vehicle production and sales | Driver | High | Shock Absorbers |
| Expansion of the automotive aftermarket | Driver | High | Aftermarket Suppliers |
| Growing demand for electric vehicles | Opportunity | High | Control Arms |
| Investment in advanced manufacturing technologies | Opportunity | High | Steel |
| Supply chain disruptions affecting production | Restraint | High | Bushings & Bearings |
| Fluctuations in raw material prices | Restraint | High | Stabilizer Bars |
| Regulatory compliance costs for manufacturers | Challenge | Medium | OEMs |
| Technological advancements requiring constant updates | Challenge | Medium | Vehicle Manufacturers |
Evaluation of Drivers in China Suspension & Handling Parts Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising vehicle production | Shock Absorbers | China produced over 25 million vehicles in 2022, increasing demand for suspension parts. |
| Growth in the automotive aftermarket | Aftermarket Suppliers | The automotive aftermarket in China is projected to reach $200 billion by 2025, driving replacement part sales. |
| Shift towards electric vehicles | Control Arms | The government's aim to increase electric vehicle production by 20% annually impacts suspension part designs. |
| Investment in advanced manufacturing | Steel | Jiangsu Province supports production capabilities with advanced automotive manufacturing facilities, enhancing output by 15%. |
| Focus on safety standards | Bushings & Bearings | ISO 9001 certification is essential for manufacturers, ensuring quality and safety in production. |
Market growth in China for Suspension & Handling Parts rests on rising vehicle production, expanding aftermarket demand, and the shift towards electric vehicles. The automotive industry produced over 25 million vehicles in 2022, increasing the need for suspension components. By 2025, the automotive aftermarket will reach $200 billion, driving demand for replacement parts. The goal to boost electric vehicle production by 20% annually will reshape suspension part requirements. Investment in advanced manufacturing facilities will improve production efficiency and capacity, enhancing overall market dynamics.
Evaluation of Restraints in China Suspension & Handling Parts Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions | Bushings & Bearings | Ongoing global supply chain issues have delayed the availability of critical components, impacting production timelines. |
| Raw material price fluctuations | Stabilizer Bars | Fluctuations in steel and rubber prices have increased production costs, affecting profit margins for manufacturers. |
| Regulatory compliance costs | OEMs | Manufacturers face costs to comply with evolving safety and quality standards, impacting overall profitability by approximately 10%. |
| Technological advancements | Vehicle Manufacturers | Rapid technological changes require constant updates to production processes, leading to increased operational costs of about 15%. |
| Market competition | Control Arms | Intense competition among manufacturers pressures prices, limiting profitability and investment in innovation, resulting in a 5% margin reduction. |
China Suspension & Handling Parts Market Challenges
The China Suspension & Handling Parts Market encounters rising production costs that challenge domestic manufacturers, driven by fluctuating raw material prices which can escalate component costs by up to 15%. Buyers in the automotive sector face delays in obtaining essential parts due to outdated manufacturing technology, extending lead times by as much as 30%. Local producers find it difficult to compete with international suppliers who employ advanced production techniques, requiring investments that many cannot afford. Compliance with standards set by the Ministry of Industry and Information Technology can prolong the approval process for new products, delaying market entry for suppliers by several months.
Trends in the China Suspension & Handling Parts Market
Several trends are reshaping the China Suspension & Handling Parts Market; the most important are set out below.
- Shift Towards Electric Vehicle Components: The 'New Energy Vehicle Industry Development Plan' encourages the production of electric vehicles, influencing suspension part designs. By 2025, electric vehicle production is set to increase by 20%, creating new design requirements for suspension components.
- Increased Focus on Aftermarket Services: Aftermarket Suppliers are improving service quality due to the 'Automotive Aftermarket Development Initiative'. This initiative aims to improve parts availability and service standards, with the market projected to reach $200 billion by 2025.
- Adoption of Advanced Materials: The 'National Automotive Industry Innovation Strategy' promotes the use of advanced materials in vehicle parts. This strategy, launched in 2022, aims to improve performance and durability, impacting material choices for suspension components.
- Growth of Manufacturing Hubs: Shandong Province is emerging as a major hub for automotive parts manufacturing. With over 5 million people employed in the automotive industry as of 2023, it is driving local production capabilities.
Investment Opportunities in the China Suspension & Handling Parts Market
Below are the investment opportunities with the strongest case in the China Suspension & Handling Parts Market.
- Supply of Advanced Suspension Components: There is a rising demand for advanced suspension parts as the automotive industry evolves. With the automotive aftermarket projected to reach $200 billion by 2025, suppliers can target aftermarket providers for partnerships.
- Investment in Electric Vehicle Parts: The transition to electric vehicles offers opportunities for manufacturers to supply specialised suspension components. OEMs focused on electric vehicle production in Jiangsu Province are seeking local partnerships for sourcing.
- Expansion into Aftermarket Services: The automotive aftermarket is growing rapidly, creating opportunities for service providers. With the market expected to reach $200 billion by 2025, companies can invest in improving service quality.
- Development of Lightweight Materials: The demand for lightweight materials in suspension parts is on the rise. Suppliers can target manufacturers focusing on advanced materials, particularly in Shandong Province, to meet this demand.
Government Initiatives in the China Suspension & Handling Parts Market
The 'Automotive Industry Development Plan' by the Ministry of Industry and Information Technology aims to boost the competitiveness of domestic manufacturers by 2025. This plan encourages investment in advanced manufacturing technologies and supports the development of new suspension parts. It also promotes collaboration between manufacturers and research institutions to drive innovation in the sector. By focusing on quality and safety standards, this plan seeks to improve the overall performance of suspension components in the market. The initiative is expected to enhance production efficiency by 15%.
The 'Automotive Standards Revision Program' initiated by the Standardization Administration of China updates safety standards for suspension parts, effective from 2021. This program ensures that manufacturers comply with the latest safety regulations, improving product reliability. The National Development and Reform Commission supports green automotive technologies, funding projects that focus on sustainable manufacturing practices. This initiative aims to reduce the environmental impact of suspension parts production, targeting a 20% reduction in emissions by 2025.
Future Insight of the China Suspension & Handling Parts Market
The China Suspension & Handling Parts Market will experience notable changes by 2032, driven by advancements in manufacturing technology and a government push for electric vehicle production. Smart manufacturing facilities will enhance efficiency and reduce costs for producers, while the rise of green automotive technologies will stimulate innovation. Improved standards from the Ministry of Industry and Information Technology will further shape product development and market trends.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Part Type – Shock Absorbers Dominated, Control Arms Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, Shock Absorbers accounted for a 44% market share by part type in 2025. Shock absorbers command the largest share in the China Suspension & Handling Parts Market due to their critical role in ensuring vehicle stability and comfort. With over 25 million vehicles produced in 2022, the demand for these components remains robust among local manufacturers. Over 2026–2032, Control Arms are expected to post the fastest growth, at a CAGR of 7.8%. Control arms are witnessing rapid growth as they are vital for wheel alignment and handling, increasingly prioritised in modern vehicle designs. The shift towards advanced suspension systems in new vehicles contributes significantly to this segment's expansion. Suppliers should prioritise enhancing control arm offerings to meet the rising demand in the market.
By Vehicle Segment – Passenger/Commercial Dominated, Light/Heavy Vehicles Expected to Grow Fastest
In 2025, Passenger/Commercial led the vehicle segment split with a 45% share. The passenger/commercial vehicle segment leads the market share as it encompasses a wide variety of vehicle types, serving both personal and business needs. This diverse demand guarantees a steady requirement for suspension parts across numerous applications. Light/Heavy Vehicles are set to record the highest CAGR in this split, 7.5% over 2026–2032. Light and heavy vehicles are the fastest-growing segments, driven by the increasing production rates of both categories in China. The government's push to enhance electric vehicle output significantly influences the demand for suspension components in these segments. Suppliers must adapt their strategies to meet the evolving needs of light and heavy vehicle manufacturers.
By Material Type – Steel Dominated, Forged Aluminum Expected to Grow Fastest
Steel took a 37% share of material type in 2025, more than any other category. Steel holds the largest market share as the primary material for suspension parts, valued for its durability and strength. This material is crucial for sustaining the performance of suspension systems in the high-volume automotive sector. Forged Aluminum is projected to grow fastest, at a CAGR of 7.0% during 2026–2032. Forged aluminum is the fastest-growing material type, primarily due to its application in lightweight suspension components that enhance fuel efficiency. As manufacturers focus on producing lighter vehicles, the demand for forged aluminum is projected to increase substantially. Suppliers should invest in developing forged aluminum products to align with the industry's trend towards lightweight materials.
By End User – OEMs Dominated, Aftermarket Suppliers Expected to Grow Fastest
The largest end user category in 2025 was OEMs, with a 50% share of total revenue. OEMs represent the largest share of the market as they are the primary buyers for new vehicles, ensuring a consistent demand for suspension parts. Their reliance on high-quality components for vehicle assembly reinforces their dominant position. The quickest growth will come from Aftermarket Suppliers, forecast to expand at a CAGR of 6.4% between 2026 and 2032. Aftermarket suppliers are the fastest-growing segment, driven by the increasing need for replacement parts and upgrades as vehicle ownership rises. The projected growth of the automotive aftermarket to $200 billion by 2025 highlights this trend. Suppliers should consider expanding their partnerships with aftermarket suppliers to capture this growing market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Suspension & Handling Parts Market Outlook
- Market Size of China Suspension & Handling Parts Market, 2025
- Forecast of China Suspension & Handling Parts Market, 2032
- Historical Data and Forecast of China Suspension & Handling Parts Revenues & Volume for the Period 2022 - 2032F
- China Suspension & Handling Parts Market Trend Evolution
- China Suspension & Handling Parts Market Drivers and Challenges
- China Suspension & Handling Parts Price Trends
- China Suspension & Handling Parts Porter's Five Forces
- China Suspension & Handling Parts Industry Life Cycle
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Part Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Shock Absorbers for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Control Arms for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Bushings & Bearings for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Stabilizer Bars for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Vehicle Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Passenger/Commercial for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Light/Heavy Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Suspension Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Steering Handling for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Forged Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Rubber/Metal for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Steel Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Aftermarket Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Auto Service Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension & Handling Parts Market Revenues & Volume By Vehicle Manufacturers for the Period 2022 - 2032F
- China Suspension & Handling Parts Import Export Trade Statistics
- Market Opportunity Assessment By Part Type
- Market Opportunity Assessment By Vehicle Segment
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By End User
- China Suspension & Handling Parts Top Companies Market Share
- China Suspension & Handling Parts Competitive Benchmarking By Technical and Operational Parameters
- China Suspension & Handling Parts Company Profiles
- China Suspension & Handling Parts Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Part Type
- Shock Absorbers
- Control Arms
- Bushings & Bearings
- Stabilizer Bars
By Vehicle Segment
- Passenger/Commercial
- Light/Heavy Vehicles
- Suspension Systems
- Steering Handling
By Material Type
- Steel
- Forged Aluminum
- Rubber/Metal
- Steel Alloy
By End User
- OEMs
- Aftermarket Suppliers
- Auto Service Providers
- Vehicle Manufacturers































