China Telecom Infrastructure Hardware Market Size & Growth Rate
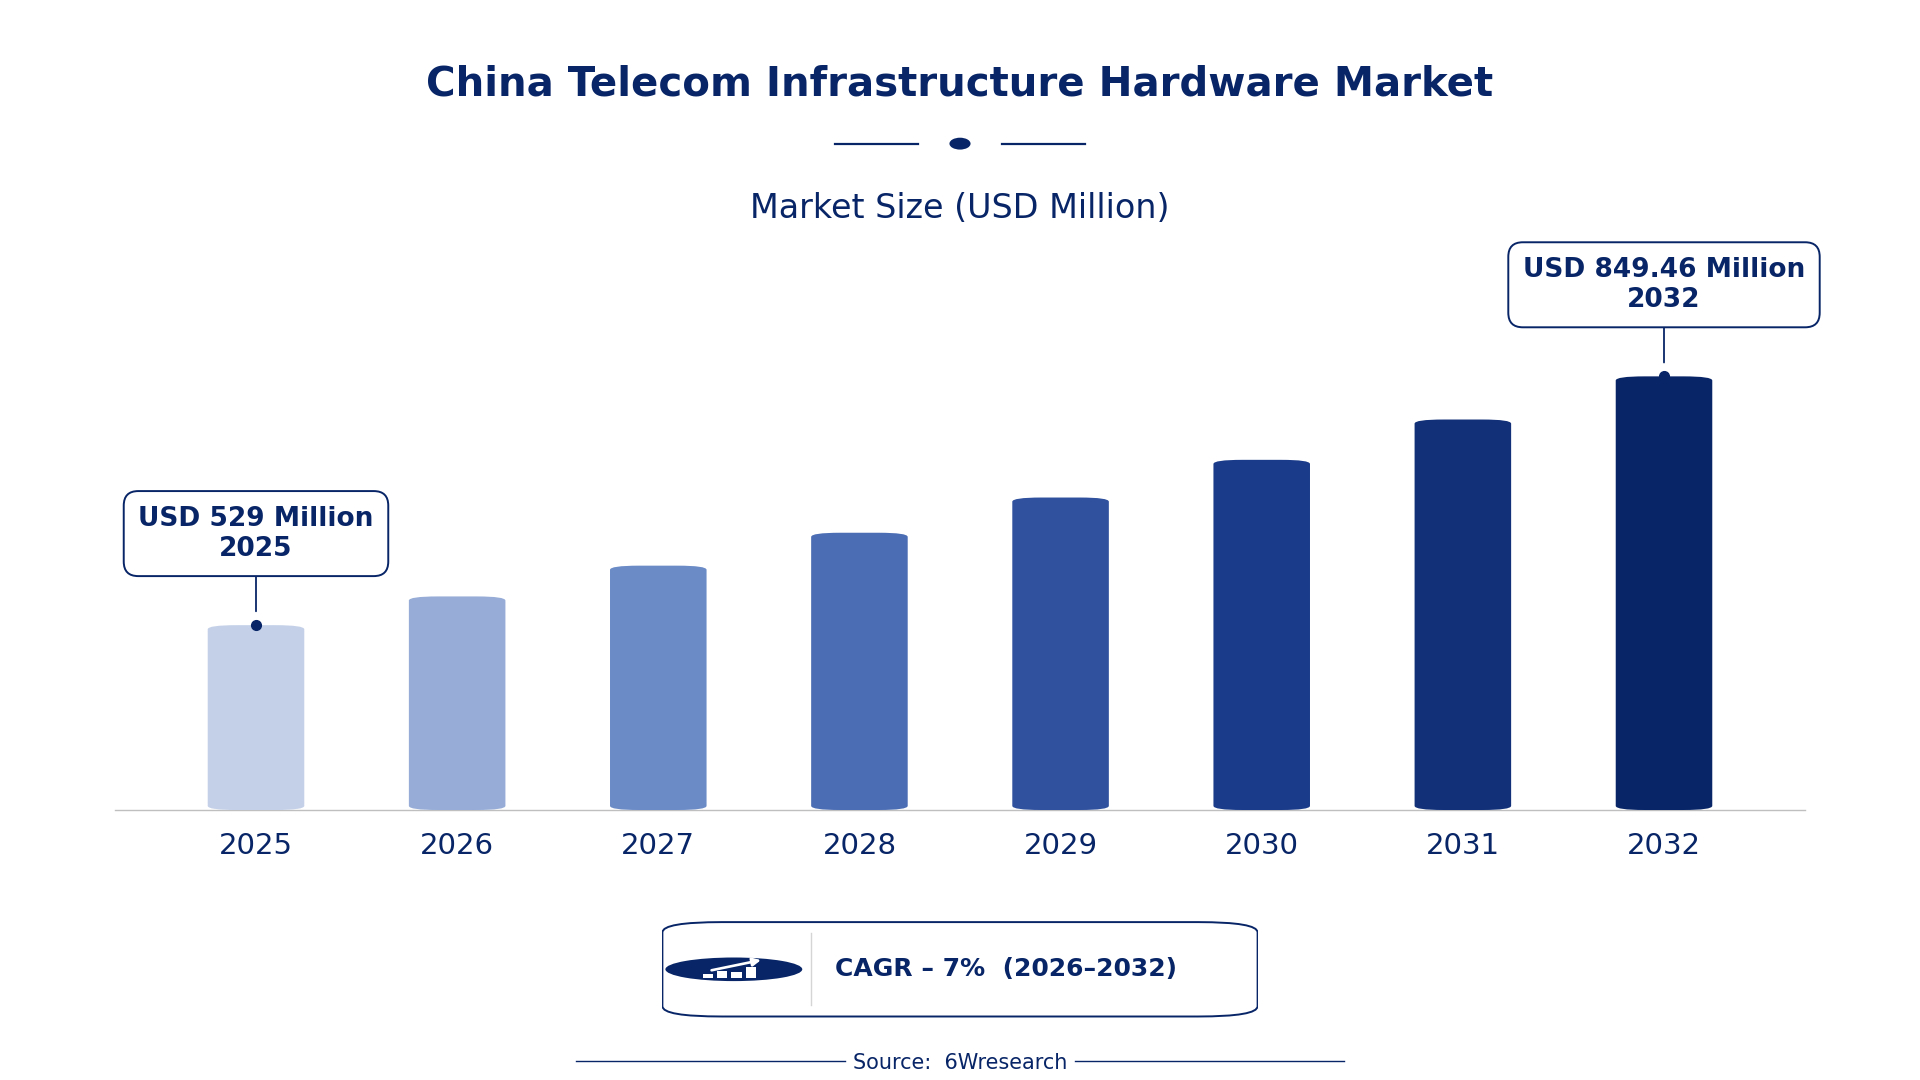
According to 6Wresearch internal database and industry insights, the China Telecom Infrastructure Hardware Market was valued at USD 529.0 million in 2025 and is projected to reach USD 849.46 million by 2032, growing at a CAGR of approximately 7% during 2026–2032.
China Telecom Infrastructure Hardware Market Highlights
| Report Metric | Details |
| Report Name | China Telecom Infrastructure Hardware Market |
| Market Size 2025 | USD 529.0 million |
| Market Size 2032 | USD 849.46 million |
| Absolute Growth 2025–2032 | USD 320.46 million |
| CAGR 2026–2032 | 7% |
| Peak Annual Growth | 9.5% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Infrastructure Hardware, 2025 | Radio Access Network (39% share) |
| Leading Product Type, 2025 | RRUs & BBUs (44% share) |
| Leading Component Type, 2025 | 5G NR/LTE (45% share) |
| Leading Distribution Channel, 2025 | Direct Supply (49% share) |
| Leading End User Industry, 2025 | Telecom Operators (45% share) |
| Fastest-Growing Infrastructure Hardware | Power and Cooling Systems (9.0% CAGR) |
| Fastest-Growing Component Type | GPON/XGS-PON (9.2% CAGR) |
| Fastest-Growing Distribution Channel | Network Integrators (8.8% CAGR) |
| Fastest-Growing End User Industry | Broadband Providers (8.4% CAGR) |
| Growing Sector | Broadband Providers |
| Key End Users | Telecom Operators, Broadband Providers, Telecom Carriers, Data Center Companies |
China Telecom Infrastructure Hardware Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
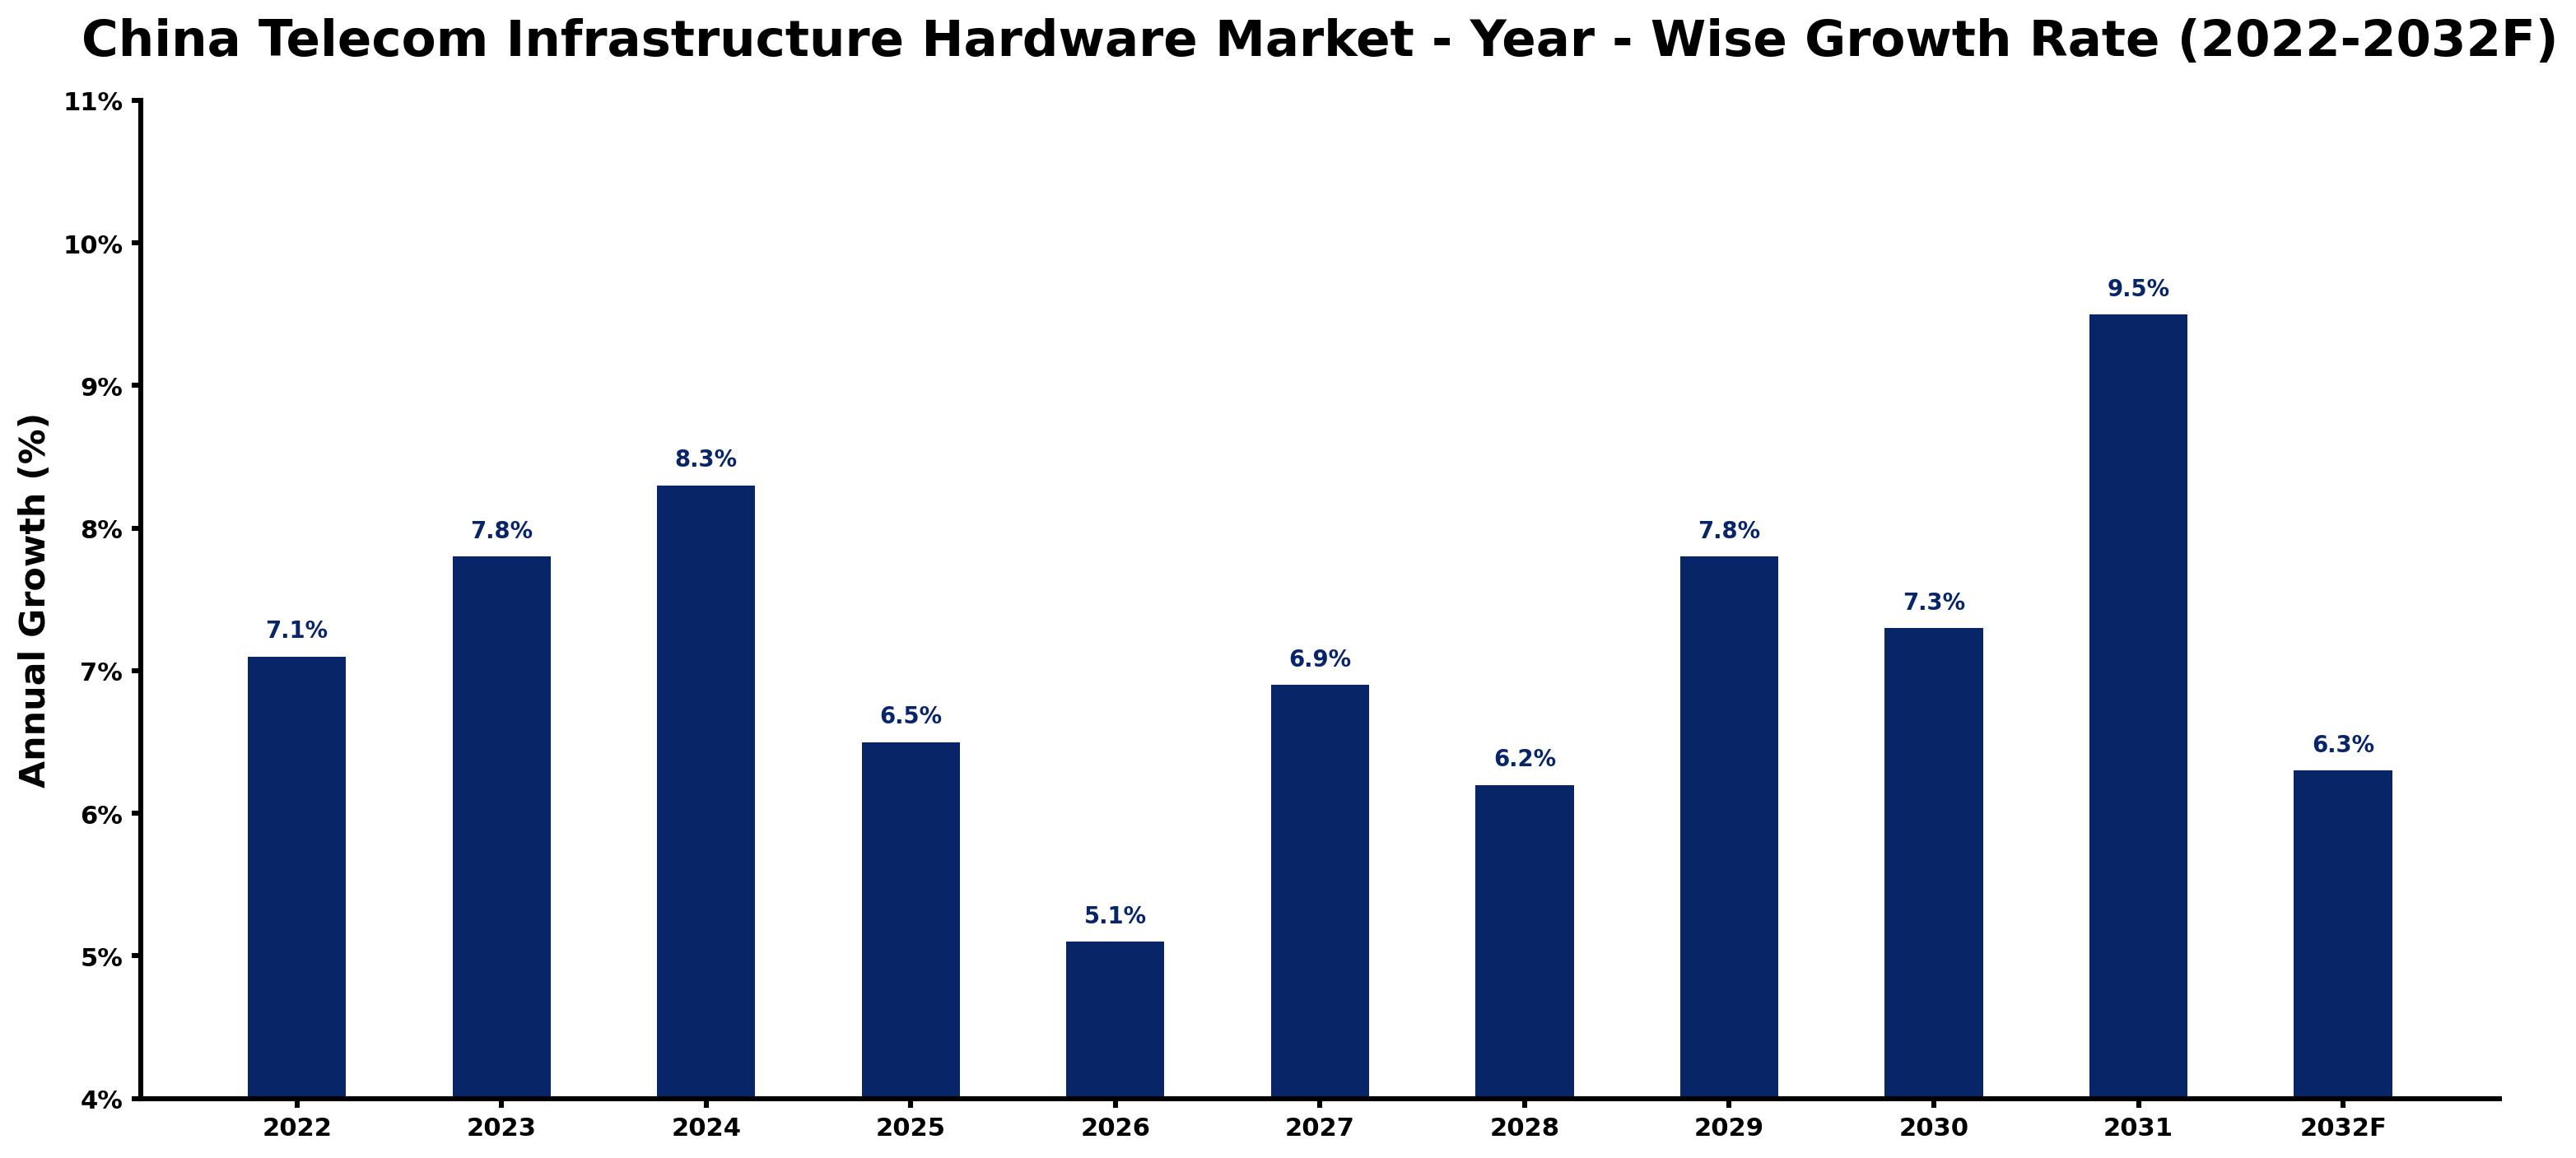
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.1 | The market showed steady growth, supported by strong domestic demand for telecom services. |
| 2023 | 7.8 | Investment in 5G infrastructure expanded, increasing the need for telecom hardware. |
| 2024 | 8.3 | The installation of new 5G base stations accelerated, driving higher demand for equipment. |
| 2025 | 6.5 | Growth slowed as market adjustments occurred following rapid expansion in previous years. |
| 2026 | 5.1 | Demand continued to rise, although at a slower pace due to market saturation effects. |
| 2027 | 6.9 | Investment in green energy solutions for infrastructure boosted hardware purchases. |
| 2028 | 6.2 | The market experienced a slight slowdown as competition intensified among suppliers. |
| 2029 | 7.8 | Increased urbanisation led to higher demand for broadband services and infrastructure. |
| 2030 | 7.3 | Growth moderated as the market stabilised after previous peaks in demand. |
| 2031 | 9.5 | A surge in 5G network deployment drove exceptional growth in hardware sales. |
| 2032 | 6.3 | Growth slowed as the market matured, but demand for upgrades remained strong. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Telecom Infrastructure Hardware Market Synopsis
Telecom Infrastructure Hardware in China includes key technologies for telecommunications networks, such as base stations and fibre optics. The market is set to reach 1.5 trillion CNY by 2025, driven by a mobile subscriber base exceeding 1.4 billion. Investments in network expansion and the '14th Five-Year Plan' for digital infrastructure development further stimulate growth. With 5G coverage projected to reach 90% of urban areas by 2025, the demand for reliable and efficient telecom hardware continues to increase.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for 5G infrastructure due to urbanisation | Driver | High | Radio Access Network |
| Investment in green energy solutions for telecom infrastructure | Driver | High | Power and Cooling Systems |
| Expansion of broadband services requiring enhanced infrastructure | Opportunity | High | Fiber Optic Infrastructure |
| Need for energy-efficient solutions in data centers | Opportunity | Medium | Batteries/AC Units |
| Compliance with cybersecurity regulations increasing operational costs | Restraint | High | Telecom Operators |
| Market saturation limiting new investments in infrastructure | Restraint | Medium | Telecom Operators |
| High competition among suppliers affecting pricing strategies | Challenge | High | Radio Access Network |
| Supply chain disruptions impacting timely hardware availability | Challenge | Medium | Telecom Operators |
Evaluation of Drivers in China Telecom Infrastructure Hardware Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased mobile subscriber base | Radio Access Network | With over 1.4 billion mobile subscribers, telecom operators are investing in infrastructure to support growing connectivity needs. |
| Government initiatives promoting digital infrastructure | Fiber Optic Infrastructure | The 'Broadband China' initiative aims to improve internet access nationwide, driving demand for fiber optic solutions. |
| Rising demand for 5G services | 5G NR/LTE | The projected 90% coverage of urban areas by 2025 necessitates significant investment in 5G hardware. |
| Focus on energy efficiency in telecom operations | Batteries/AC Units | Telecom operators are adopting green energy solutions, increasing the need for efficient power management systems. |
| Expansion of data centers requiring reliable connectivity | Transmission Systems | Data centers are expected to consume 1.5 billion kWh by 2025, driving demand for dependable transmission systems. |
Market growth in China for Telecom Infrastructure Hardware rests on the increasing mobile subscriber base, with over 1.4 billion users driving infrastructure investments. The anticipated 90% coverage of urban areas by 2025 necessitates substantial investment in 5G hardware, further propelling growth. Telecom operators are focusing on energy efficiency, increasing the demand for advanced power management systems. The expansion of data centers, projected to consume 1.5 billion kWh by 2025, also drives the need for reliable transmission systems. Investments in green energy solutions for infrastructure are expected to boost hardware purchases significantly, particularly in urban regions where demand is rising rapidly.
Evaluation of Restraints in China Telecom Infrastructure Hardware Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition among manufacturers | Radio Access Network | Numerous manufacturers vie for market share, leading to price wars that can erode profit margins by up to 20% for producers. |
| Supply chain disruptions | Fiber Optic Infrastructure | Delays in raw material procurement can hinder production schedules, forcing buyers to wait longer for essential infrastructure components. |
| Rapid technological advancements | 5G NR/LTE | Suppliers must continually invest in new equipment to stay relevant, which can delay product availability for buyers by several months. |
| Quality concerns due to cost-cutting | Batteries/AC Units | Manufacturers may cut corners to maintain profitability, resulting in buyers receiving lower-quality products. |
| Regulatory compliance costs | Transmission Systems | Compliance with standards like the Cybersecurity Law increases operational costs for telecom equipment manufacturers. |
China Telecom Infrastructure Hardware Market Challenges
Buyers and suppliers in the China Telecom Infrastructure Hardware market encounter fierce competition, with numerous manufacturers competing for market share, leading to price reductions that can shrink profit margins by up to 20%. This competitive environment pressures suppliers to reduce costs, resulting in buyers receiving lower-quality products that may not meet necessary industry standards. Rapid technological advancements require substantial investments in new equipment, causing delays that can extend lead times for buyers by several months. Additionally, supply chain disruptions in raw material sourcing can delay production schedules, forcing buyers to face longer wait times for critical infrastructure components.
Trends in the China Telecom Infrastructure Hardware Market
Several trends are reshaping the China Telecom Infrastructure Hardware Market; the most important are set out below.
- Shift towards Sustainable Telecom Practices: China is increasingly prioritising sustainable practices in telecom infrastructure, as demonstrated by the 'Green Telecom Development Initiative' launched in 2022. This initiative encourages telecom operators to adopt energy-efficient solutions, aligning with the national goal of reducing carbon emissions.
- Expansion of 5G Infrastructure: The deployment of 5G networks is accelerating, with over 700,000 new 5G base stations installed in 2022. This rapid expansion is crucial for improving connectivity and supporting the rising demand for high-speed data services.
- Integration of Digital Technologies: The '5G+ Industrial Internet' strategy aims to integrate 5G with industrial applications by 2025, promoting innovation across various sectors. This integration is expected to drive demand for advanced telecom infrastructure solutions.
- Increased Focus on Data Security: The updated 'Telecommunications Network Security Protection Regulations' in 2022 strengthen cybersecurity measures for telecom infrastructure. This emphasis on data security is important for building consumer trust and ensuring compliance with national standards.
Investment Opportunities in the China Telecom Infrastructure Hardware Market
Below are the investment opportunities with the strongest case in the China Telecom Infrastructure Hardware Market.
- Supply of Advanced Power Management Systems: The demand for efficient power management systems is rising, driven by telecom operators adopting green energy solutions. With the market projected to expand significantly, partnerships with local distributors can facilitate entry.
- Provision of 5G Infrastructure Solutions: The surge in 5G network deployment creates opportunities for suppliers of advanced telecom hardware. Collaborating with telecom operators can enhance market presence and drive sales.
- Development of Fiber Optic Solutions: As the 'Broadband China' initiative aims to improve internet access nationwide, there is a pressing need for fibre optic solutions. Suppliers can capitalise on this opportunity by establishing joint ventures with local firms.
- Investment in Sustainable Telecom Equipment: The emphasis on green energy solutions presents an opportunity for suppliers of sustainable telecom equipment. Engaging with telecom operators committed to sustainability can lead to fruitful partnerships.
Government Initiatives in the China Telecom Infrastructure Hardware Market
In 2021, the Ministry of Industry and Information Technology launched the '14th Five-Year Plan for the Development of the Telecommunications Industry' to improve infrastructure and digital services. This plan aims to enhance the overall quality of telecom services and expand network coverage, ensuring that telecom operators meet the growing demand for connectivity. The initiative is expected to drive substantial investments in telecom infrastructure, focusing on modernising existing networks and deploying new technologies.
Telecom operators benefit from the National Development and Reform Commission's 'Digital Economy Development Plan' (2022), which aims to invest 3 trillion CNY in digital infrastructure by 2025. This plan supports various projects aimed at enhancing network capabilities and expanding broadband access. The Ministry of Ecology and Environment's 'Green Telecom Development Initiative' also promotes sustainable practices in telecom infrastructure, encouraging operators to adopt energy-efficient solutions and reduce their environmental impact.
Future Insight of the China Telecom Infrastructure Hardware Market
The China Telecom Infrastructure Hardware market will undergo notable changes by 2032, driven by the 'Broadband China' initiative aimed at improving nationwide internet access. The '14th Five-Year Plan' will prioritise digital infrastructure development, creating new opportunities for suppliers. By 2025, the country will install over 700,000 new 5G base stations, expanding network capacity for buyers. Additionally, the focus on energy-efficient data centres will reshape production practices, aligning with the growing demand for sustainable solutions in the telecom sector.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Infrastructure Hardware – Radio Access Network Dominated, Power and Cooling Systems Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, Radio Access Network took a 39% share of infrastructure hardware in 2025, more than any other category. The Radio Access Network segment holds the largest share due to its critical role in mobile connectivity, essential for over 1.4 billion mobile subscribers in China. This extensive user base underscores the necessity for robust infrastructure to maintain seamless communication services. The quickest growth will come from Power and Cooling Systems, forecast to expand at a CAGR of 9.0% between 2026 and 2032. Power and Cooling Systems are experiencing rapid growth, driven by telecom operators' increasing emphasis on energy efficiency and reliability. The installation of over 700,000 new 5G base stations in 2022 has heightened the demand for effective cooling solutions to ensure operational efficiency. Suppliers must focus on developing efficient power and cooling systems to meet the rising demands of telecom operators.
By Product Type – RRUs & BBUs Dominated and Is Expected to Record the Fastest Growth
With a 44% revenue share in 2025, RRUs & BBUs was the largest product type category. RRUs & BBUs dominate the market share as they are core components for radio access, directly facilitating the extensive network needed for mobile subscribers. Their pivotal role in enabling 5G connectivity significantly strengthens their market position. Its lead should widen, with a projected CAGR of 8.3% during 2026–2032, the highest in this split. RRUs & BBUs are also the fastest-growing segment, propelled by the swift deployment of 5G networks across urban areas. The ongoing expansion of mobile services ensures sustained demand for these essential components. Manufacturers should invest in advanced technologies for RRUs & BBUs to maintain their competitive edge in the evolving telecom market.
By Component Type – 5G NR/LTE Dominated, GPON/XGS-PON Expected to Grow Fastest
In 2025, 5G NR/LTE led the component type split with a 45% share. 5G NR/LTE leads the market share as it is fundamental for the development of next-generation networks, crucial for accommodating the growing number of mobile users. The segment's strength is reinforced by the drive for extensive 5G coverage in urban regions. GPON/XGS-PON is set to record the highest CAGR in this split, 9.2% over 2026–2032. GPON/XGS-PON is the fastest-growing component type, fueled by the increasing demand for high-speed broadband delivery. The 'Broadband China' initiative aims to enhance internet access, positioning this segment for substantial growth. Suppliers should focus on advancing GPON/XGS-PON solutions to capitalise on the rising demand for high-speed internet services.
By Distribution Channel – Direct Supply Dominated, Network Integrators Expected to Grow Fastest
Direct Supply held a 49% share of the China Telecom Infrastructure Hardware Market by distribution channel in 2025. Direct Supply captures the largest share as it serves as the main procurement channel, allowing telecom operators to acquire essential infrastructure directly. This method streamlines the acquisition process for critical components necessary for network expansion. Network Integrators are projected to grow fastest, at a CAGR of 8.8% during 2026–2032. Network Integrators represent the fastest-growing distribution channel, vital for system integration in complex telecom infrastructure projects. Their importance is amplified by the increasing complexity of telecom networks that require expert integration services. Suppliers should strengthen partnerships with network integrators to expand their market reach and facilitate smoother project implementations.
By End User Industry – Telecom Operators Dominated, Broadband Providers Expected to Grow Fastest
Telecom Operators accounted for a 45% market share by end user industry in 2025. Telecom Operators are the principal users of telecom infrastructure, holding the largest market share as they necessitate extensive hardware to support their vast subscriber base. Their continuous investments in network expansion reinforce their dominant position in the market. The quickest growth will come from Broadband Providers, forecast to expand at a CAGR of 8.4% between 2026 and 2032. Broadband Providers are the fastest-growing end-user segment, driven by the escalating demand for high-speed internet services across both urban and rural areas. Government initiatives aimed at improving internet access nationwide further fuel this rapid growth. Suppliers should customise their offerings to address the specific needs of broadband providers to capture a larger share of this expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Telecom Infrastructure Hardware Market Outlook
- Market Size of China Telecom Infrastructure Hardware Market, 2025
- Forecast of China Telecom Infrastructure Hardware Market, 2032
- Historical Data and Forecast of China Telecom Infrastructure Hardware Revenues & Volume for the Period 2022 - 2032F
- China Telecom Infrastructure Hardware Market Trend Evolution
- China Telecom Infrastructure Hardware Market Drivers and Challenges
- China Telecom Infrastructure Hardware Price Trends
- China Telecom Infrastructure Hardware Porter's Five Forces
- China Telecom Infrastructure Hardware Industry Life Cycle
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Infrastructure Hardware for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Radio Access Network for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Fiber Optic Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Transmission Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Power and Cooling Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By RRUs & BBUs for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By OLTs/ONTs for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Microwave Radios for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Batteries/AC Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By 5G NR/LTE for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By GPON/XGS-PON for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Backhaul/Longhaul for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Site Power Mgmt for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Direct Supply for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Network Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Infrastructure Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Industrial Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Telecom Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Broadband Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Telecom Carriers for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Hardware Market Revenues & Volume By Data Center Companies for the Period 2022 - 2032F
- China Telecom Infrastructure Hardware Import Export Trade Statistics
- Market Opportunity Assessment By Infrastructure Hardware
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Telecom Infrastructure Hardware Top Companies Market Share
- China Telecom Infrastructure Hardware Competitive Benchmarking By Technical and Operational Parameters
- China Telecom Infrastructure Hardware Company Profiles
- China Telecom Infrastructure Hardware Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Infrastructure Hardware
- Radio Access Network
- Fiber Optic Infrastructure
- Transmission Systems
- Power and Cooling Systems
By Product Type
- RRUs & BBUs
- OLTs/ONTs
- Microwave Radios
- Batteries/AC Units
By Component Type
- 5G NR/LTE
- GPON/XGS-PON
- Backhaul/Longhaul
- Site Power Mgmt
By Distribution Channel
- Direct Supply
- Network Integrators
- Infrastructure Vendors
- Industrial Distributors
By End User Industry
- Telecom Operators
- Broadband Providers
- Telecom Carriers
- Data Center Companies































