China Textile Components for Vehicles Market Size & Growth Rate
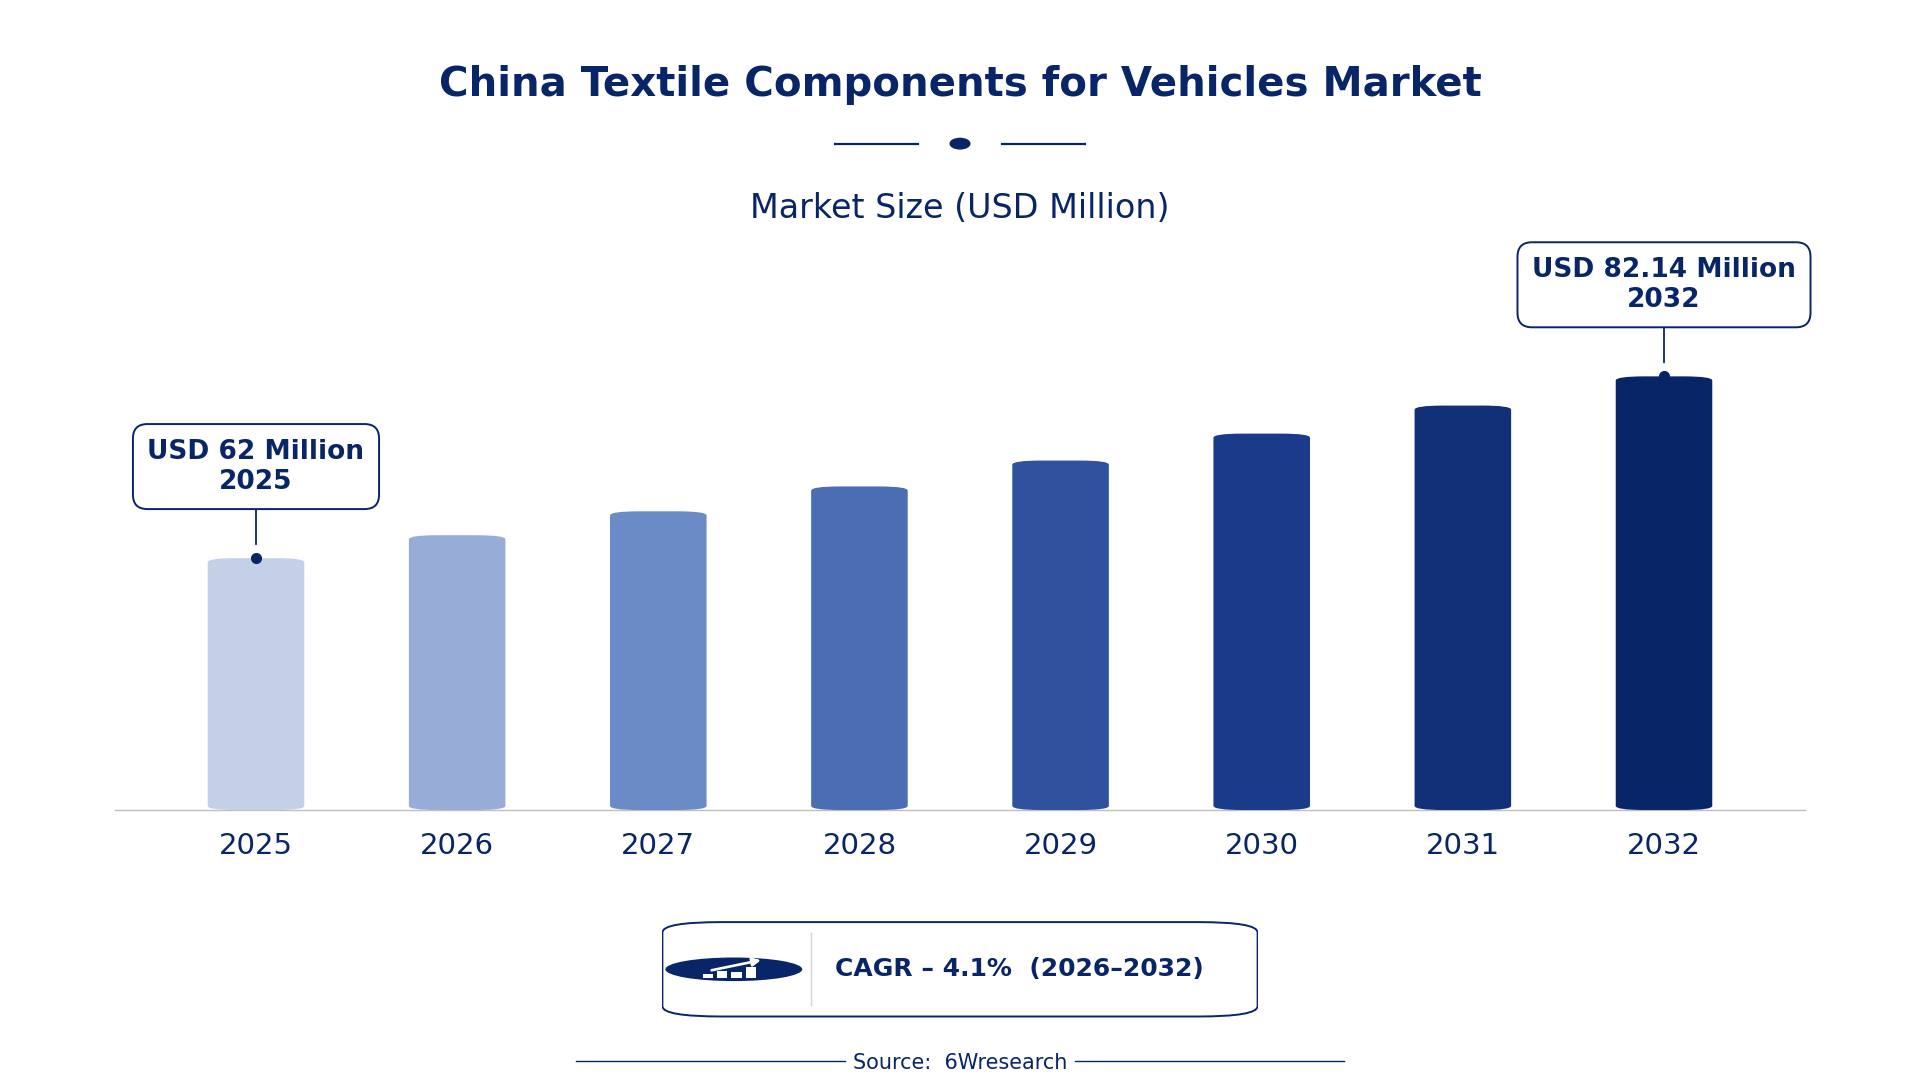
According to 6Wresearch internal database and industry insights, the China Textile Components for Vehicles Market was valued at USD 62.0 million in 2025 and is projected to reach USD 82.14 million by 2032, growing at a CAGR of approximately 4.1% during 2026–2032.
China Textile Components for Vehicles Market Highlights
| Report Metric | Details |
| Report Name | China Textile Components for Vehicles Market |
| Market Size 2025 | USD 62.0 million |
| Market Size 2032 | USD 82.14 million |
| Absolute Growth 2025–2032 | USD 20.14 million |
| CAGR 2026–2032 | 4.1% |
| Peak Annual Growth | 5.8% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Vehicle Textile Components, 2025 | Automotive Carpets (40% share) |
| Leading Product Type, 2025 | Floor Coverings (54% share) |
| Leading Material Type, 2025 | Polypropylene/PA (35% share) |
| Leading Distribution Channel, 2025 | OEM Tier 1 Supply (39% share) |
| Leading End User Industry, 2025 | Passenger Vehicles (39% share) |
| Fastest-Growing Vehicle Textile Components | Seat Upholstery Fabrics (6.3% CAGR) |
| Fastest-Growing Product Type | Engineered Textiles (5.3% CAGR) |
| Fastest-Growing Material Type | PET/PU-Coated Cloth (6.7% CAGR) |
| Fastest-Growing Distribution Channel | Automotive Interior OEMs (5.4% CAGR) |
| Fastest-Growing End User Industry | Commercial Vehicles (5.4% CAGR) |
| Growing Sector | Commercial Vehicles |
| Key End Users | Passenger Vehicles, Commercial Vehicles, Bus & Railway OEMs, Vehicle Manufacturers |
China Textile Components for Vehicles Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
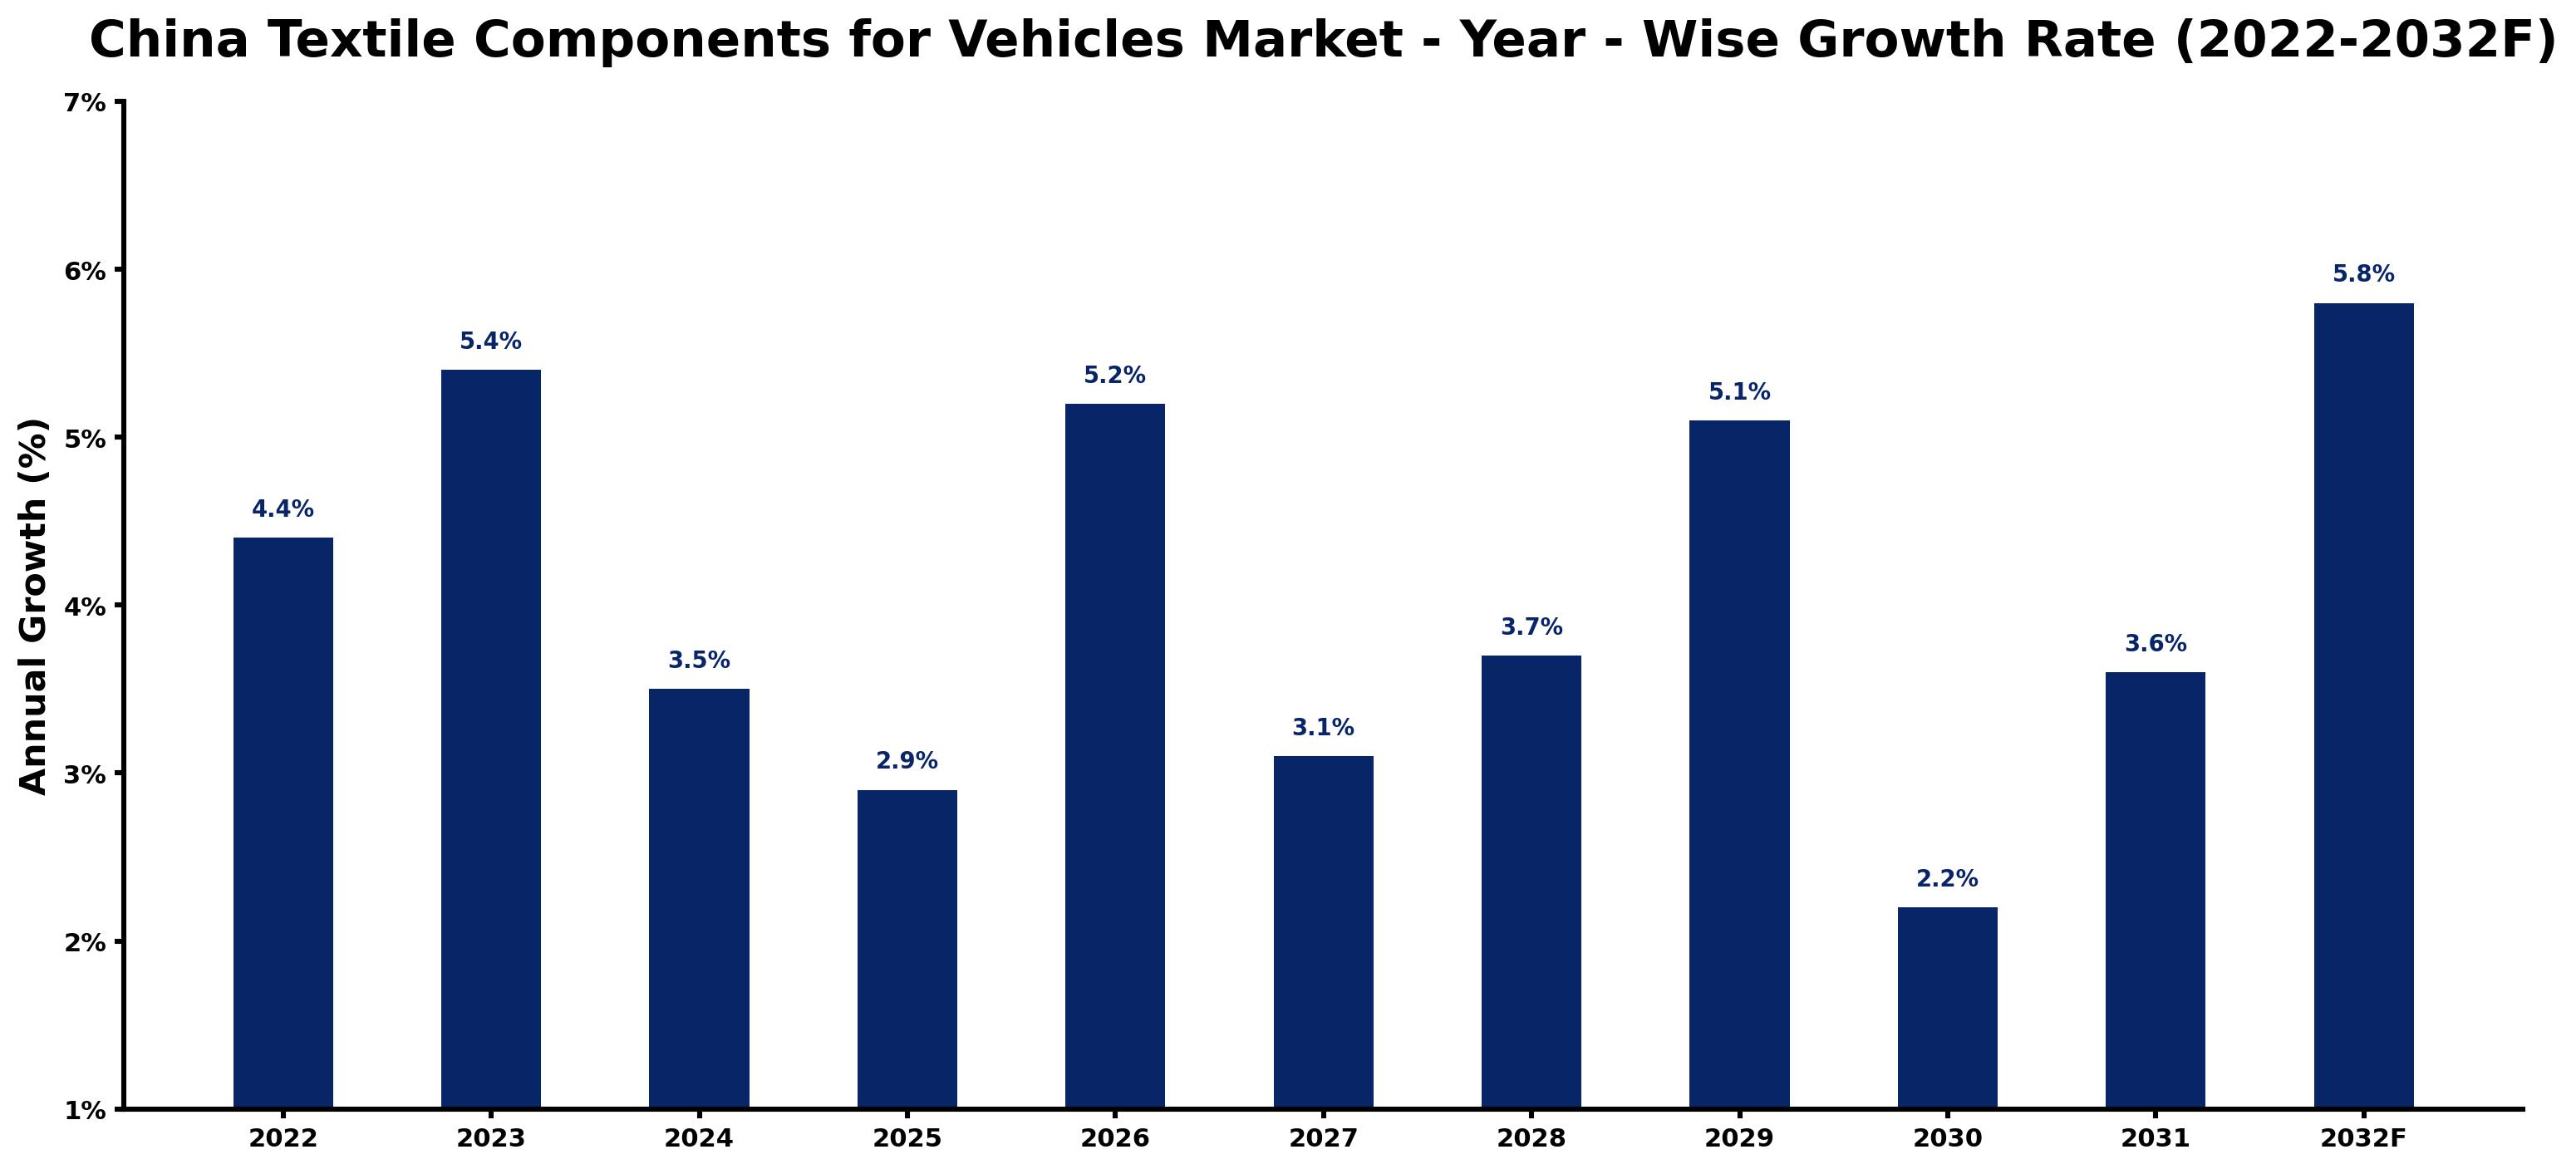
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.4 | The market experienced solid demand from domestic manufacturers in the automotive sector. |
| 2023 | 5.4 | Growth accelerated due to increased production of passenger vehicles, reaching over 25 million units. |
| 2024 | 3.5 | The market faced a slowdown as demand stabilised after a strong previous year. |
| 2025 | 2.9 | Demand decelerated as manufacturers focused on cost management in production processes. |
| 2026 | 5.2 | A resurgence in demand is expected to be driven by new automotive projects and investments in innovation. |
| 2027 | 3.1 | The market will see slower growth as manufacturers adjust to changing consumer preferences. |
| 2028 | 3.7 | Demand is projected to pick up again as new textile applications emerge in the automotive sector. |
| 2029 | 5.1 | Growth is expected to accelerate with rising investments in advanced textile manufacturing technologies. |
| 2030 | 2.2 | The market will slow again as manufacturers face challenges in sourcing materials. |
| 2031 | 3.6 | A rebound is projected as demand for passenger vehicles increases significantly. |
| 2032 | 5.8 | The market is expected to peak with strong growth driven by the introduction of new automotive standards. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Textile Components for Vehicles Market Synopsis
Textile Components for Vehicles in China encompass materials used to improve vehicle interiors, including synthetic fibers and composites. These components provide comfort, safety, and aesthetic appeal in vehicles. Ongoing investments in innovation and the 'Automotive Industry Development Plan' are key factors fuelling this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising production of passenger vehicles increases demand for textile components. | Driver | High | Passenger Vehicles |
| Growing investments in advanced textile manufacturing technologies create new opportunities. | Driver | High | Automotive Carpets |
| Increased demand for safety textiles due to stricter regulations presents a significant opportunity. | Opportunity | High | Safety Textiles |
| The expansion of commercial vehicle production opens new markets for textile suppliers. | Opportunity | Medium | Commercial Vehicles |
| Supply chain disruptions can impact the availability of raw materials for textiles. | Restraint | High | Engineered Textiles |
| Compliance with national standards may increase production costs for manufacturers. | Restraint | Medium | Airbag Fabrics |
| The China Textile Components for Vehicles market faces challenges from fluctuating raw material prices. | Challenge | High | Cabin Textiles |
| Competition from alternative materials can limit market share for traditional textile components. | Challenge | Medium | Floor Coverings |
Evaluation of Drivers in China Textile Components for Vehicles Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of over 25 million passenger vehicles in 2022 drives demand for automotive textiles. | Passenger Vehicles | This high volume creates a substantial need for various textile components in vehicle interiors. |
| Investments in innovation are projected to reach 150 billion RMB by 2025, boosting textile manufacturing capabilities. | Automotive Carpets | These investments will lead to the development of advanced materials and processes, driving demand. |
| The 'Made in China 2025' initiative promotes high-quality textile production, increasing competitiveness. | Safety Textiles | This initiative encourages manufacturers to adopt better practices, improving product quality and safety. |
| The growing trend towards sustainable manufacturing practices is influencing textile production. | Engineered Textiles | Sustainability initiatives are prompting manufacturers to invest in eco-friendly materials and processes. |
| The national standard GB/T 18983-2003 regulates automotive textile materials, ensuring quality compliance. | Airbag Fabrics | Compliance with this standard drives demand for certified materials, improving safety in vehicles. |
Expansion of the Textile Components for Vehicles market in China is backed by strong demand from domestic manufacturers, with over 25 million passenger vehicles produced in 2022. Investments in innovation are projected to reach 150 billion RMB by 2025, which will enhance manufacturing capabilities. The trend towards sustainable manufacturing is influencing textile production, prompting investments in eco-friendly materials. Compliance with national standards ensures quality, driving demand for certified airbag fabrics.
Evaluation of Restraints in China Textile Components for Vehicles Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder material availability, affecting production timelines. | Automotive Carpets | Fluctuating raw material prices can inflate production costs for producers by up to 20%. |
| Rising prices of textile components strain budgets for buyers. | Seat Upholstery Fabrics | Increased costs can lead to a 15% rise in textile component expenses for buyers. |
| Competition escalates as manufacturers struggle to meet international standards. | Airbag Fabrics | This challenge could result in a potential 10% loss in market share for domestic producers. |
| Compliance with updated safety regulations imposes additional costs on smaller suppliers. | Safety Textiles | These costs impact the operational viability of smaller manufacturers in the market. |
| Limited access to advanced technologies affects production efficiency. | Engineered Textiles | This limitation can hinder the ability to innovate and meet market demands. |
China Textile Components for Vehicles Market Challenges
The China Textile Components for Vehicles Market faces a few practical problems, beginning with supply chain disruptions that limit the availability of key materials. These disruptions arise from volatile raw material prices, which can increase production costs for producers by 20%, causing delays in delivery times. Buyers experience rising costs, with textile components seeing price hikes of around 15%, which strains their budgets. Competition intensifies as domestic manufacturers struggle to comply with international standards, risking a potential 10% loss in market share. Regulatory compliance with updated safety standards adds financial burdens on smaller suppliers, threatening their operational viability.
Trends in the China Textile Components for Vehicles Market
Several trends are reshaping the China Textile Components for Vehicles Market; the most important are set out below.
- Shift Towards Sustainable Materials: Shandong province is increasingly adopting sustainable practices in textile production, focusing on eco-friendly materials. This shift is expected to improve the quality and appeal of automotive textiles, attracting environmentally conscious buyers.
- Emergence of Advanced Textile Technologies: The automotive sector is embracing advanced textile technologies, particularly in Jiangsu province. Investments in high-performance materials are anticipated to rise, enhancing vehicle comfort and safety features.
- Growing Demand for Non-Woven Composites: The use of non-woven composites for sound insulation in vehicles is gaining traction. This trend is driven by the need for improved interior acoustics, appealing to consumers seeking enhanced driving experiences.
- Expansion of Automotive Textile Applications: Since 2022, the automotive industry has broadened its use of textile applications beyond traditional uses. This diversification is expected to create new opportunities for suppliers across various segments.
Investment Opportunities in the China Textile Components for Vehicles Market
The following opportunities in the China Textile Components for Vehicles Market pair current demand with a clear way in.
- Investment in Eco-Friendly Materials: Automotive Interior OEMs are increasingly seeking sustainable textile solutions. With a projected market size of 10 billion USD by 2025, suppliers can enter this space by partnering with local manufacturers.
- Demand for Advanced Safety Textiles: The automotive sector is expected to invest heavily in safety textiles, with compliance to ISO standards driving demand. Suppliers can capitalise by obtaining necessary certifications and collaborating with safety equipment suppliers.
- Growth in Commercial Vehicle Segment: Commercial Vehicles are projected to see a CAGR of 5.4% from 2026 to 2032. Suppliers should focus on this segment by developing tailored textile solutions for utility vehicles.
- Expansion of Automotive Manufacturing Hubs: Jiangsu province is rapidly expanding its automotive sector, creating a need for diverse textile components. Suppliers can establish partnerships with local manufacturers to meet this growing demand.
Government Initiatives in the China Textile Components for Vehicles Market
The 'Automotive Industry Development Plan' launched in 2021 outlines strategic initiatives to enhance the automotive sector, including the promotion of advanced textile manufacturing. This plan mandates compliance with national standards, such as GB/T 18983-2003, which governs automotive textile materials. Producers must ensure their products meet these regulations to access the growing market, particularly as passenger vehicles account for 70% of textile components. The 'Green Manufacturing' initiative further supports sustainable production practices, encouraging investment in eco-friendly materials. By 2025, the automotive sector is expected to invest 150 billion RMB in innovation, driving advancements in textile technology.
The China National Textile and Apparel Council oversees the implementation of industry standards and practices, ensuring compliance with regulations. This agency approves certifications for textile components, which are critical for market entry. Additionally, the Ministry of Industry and Information Technology funds projects aimed at enhancing production capabilities and innovation in textile manufacturing. These initiatives are designed to support domestic manufacturers in meeting both local and international market demands, ultimately benefiting the automotive sector's growth.
Future Insight of the China Textile Components for Vehicles Market
Several forward-looking factors should support the China Textile Components for Vehicles Market over the coming years. The automotive sector is set to invest 150 billion RMB in innovation by 2025, driving advancements in textile technology. The 'Made in China 2025' initiative will enhance production capabilities, allowing suppliers to better meet the growing demand. The increasing adoption of non-woven composites for sound insulation will improve vehicle comfort, appealing to buyers. The recent updates to national standards for automotive interior materials will raise quality benchmarks, benefiting both manufacturers and consumers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Vehicle Textile Components – Automotive Carpets Dominated, Seat Upholstery Fabrics Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, with a 40% revenue share in 2025, Automotive Carpets was the largest vehicle textile components category. Automotive carpets hold the largest market share in China due to their essential role in providing comfort and enhancing vehicle aesthetics. The production of over 25 million passenger vehicles in 2022 underscores the significant demand for durable flooring solutions in the automotive sector. Seat Upholstery Fabrics are set to record the highest CAGR in this split, 6.3% over 2026–2032. Seat upholstery fabrics are experiencing rapid growth as manufacturers focus more on passenger comfort and innovative interior designs. With passenger vehicles accounting for 70% of the textile components market, this trend is expected to continue driving demand. Suppliers should invest in advanced technologies for seat upholstery to capture the growing market share.
By Product Type – Floor Coverings Dominated, Engineered Textiles Expected to Grow Fastest
The largest product type category in 2025 was Floor Coverings, with a 54% share of total revenue. Floor coverings lead in market share as they are crucial for protecting vehicle interiors while also enhancing aesthetic appeal. Their importance in the overall vehicle experience ensures consistent demand from automotive manufacturers. Engineered Textiles are projected to grow fastest, at a CAGR of 5.3% during 2026–2032. Engineered textiles are witnessing the fastest growth owing to their specialised applications in the automotive industry. The ongoing investments in advanced textile manufacturing, particularly under initiatives like 'Made in China 2025', are propelling this segment forward. Buyers should consider integrating engineered textiles to improve functionality and performance in vehicle interiors.
By Material Type – Polypropylene/PA Dominated, PET/PU-Coated Cloth Expected to Grow Fastest
In 2025, Polypropylene/PA led the material type split with a 35% share. Polypropylene/PA dominates the market share due to its durability and widespread use in automotive carpets. This material is highly regarded by manufacturers seeking quality and reliability in vehicle interiors. Over 2026–2032, PET/PU-Coated Cloth is expected to post the fastest growth, at a CAGR of 6.7%. PET/PU-coated cloth is rapidly gaining traction as it offers essential water resistance, a vital feature for automotive applications. The increasing focus on vehicle longevity and performance is driving this material's demand. Suppliers need to develop high-performance materials like PET/PU-coated cloth to meet evolving market needs.
By Distribution Channel – OEM Tier 1 Supply Dominated, Automotive Interior OEMs Expected to Grow Fastest
OEM Tier 1 Supply accounted for a 39% market share by distribution channel in 2025. OEM Tier 1 supply channels command the largest market share as they serve as the primary suppliers for automotive manufacturers. This established supply chain ensures that manufacturers receive high-quality textile components efficiently. The quickest growth will come from Automotive Interior OEMs, forecast to expand at a CAGR of 5.4% between 2026 and 2032. Automotive interior OEMs are experiencing the fastest growth due to their critical role in vehicle design and production. As the automotive sector expands, the demand for textile components from these OEMs is projected to rise significantly. Suppliers should strengthen their partnerships with automotive interior OEMs to enhance market presence.
By End User Industry – Passenger Vehicles Dominated, Commercial Vehicles Expected to Grow Fastest
Passenger Vehicles held a 39% share of the China Textile Components for Vehicles Market by end user industry in 2025. Passenger vehicles account for the largest segment of textile components, driven by consumer preferences for comfort and aesthetics. A significant portion of the automotive market is dedicated to passenger vehicles, making this segment vital for suppliers. Commercial Vehicles are set to record the highest CAGR in this split, 5.4% over 2026–2032. Commercial vehicles are witnessing the fastest growth as the demand for utility vehicles rises. The increasing need for versatile transportation solutions is a key factor driving the expansion of this segment. Suppliers should explore opportunities in the commercial vehicle sector to capture emerging market share.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Textile Components for Vehicles Market Outlook
- Market Size of China Textile Components for Vehicles Market, 2025
- Forecast of China Textile Components for Vehicles Market, 2032
- Historical Data and Forecast of China Textile Components for Vehicles Revenues & Volume for the Period 2022 - 2032F
- China Textile Components for Vehicles Market Trend Evolution
- China Textile Components for Vehicles Market Drivers and Challenges
- China Textile Components for Vehicles Price Trends
- China Textile Components for Vehicles Porter's Five Forces
- China Textile Components for Vehicles Industry Life Cycle
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Vehicle Textile Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Automotive Carpets for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Seat Upholstery Fabrics for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Headliners & Liners for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Airbag Fabrics for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Floor Coverings for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Engineered Textiles for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Cabin Textiles for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Safety Textiles for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Polypropylene/PA for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By PET/PU-Coated Cloth for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Non Woven Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By High-Tensile Nylon for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By OEM Tier 1 Supply for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Automotive Interior OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Safety Equipment Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Passenger Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Commercial Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Bus & Railway OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Textile Components for Vehicles Market Revenues & Volume By Vehicle Manufacturers for the Period 2022 - 2032F
- China Textile Components for Vehicles Import Export Trade Statistics
- Market Opportunity Assessment By Vehicle Textile Components
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Textile Components for Vehicles Top Companies Market Share
- China Textile Components for Vehicles Competitive Benchmarking By Technical and Operational Parameters
- China Textile Components for Vehicles Company Profiles
- China Textile Components for Vehicles Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Vehicle Textile Components
- Automotive Carpets
- Seat Upholstery Fabrics
- Headliners & Liners
- Airbag Fabrics
By Product Type
- Floor Coverings
- Engineered Textiles
- Cabin Textiles
- Safety Textiles
By Material Type
- Polypropylene/PA
- PET/PU-Coated Cloth
- Non‑Woven Composites
- High-Tensile Nylon
By Distribution Channel
- OEM Tier 1 Supply
- Automotive Interior OEMs
- Direct Sales
- Safety Equipment Suppliers
By End User Industry
- Passenger Vehicles
- Commercial Vehicles
- Bus & Railway OEMs
- Vehicle Manufacturers































