China Thermoplastics for Aerospace Market Size & Growth Rate
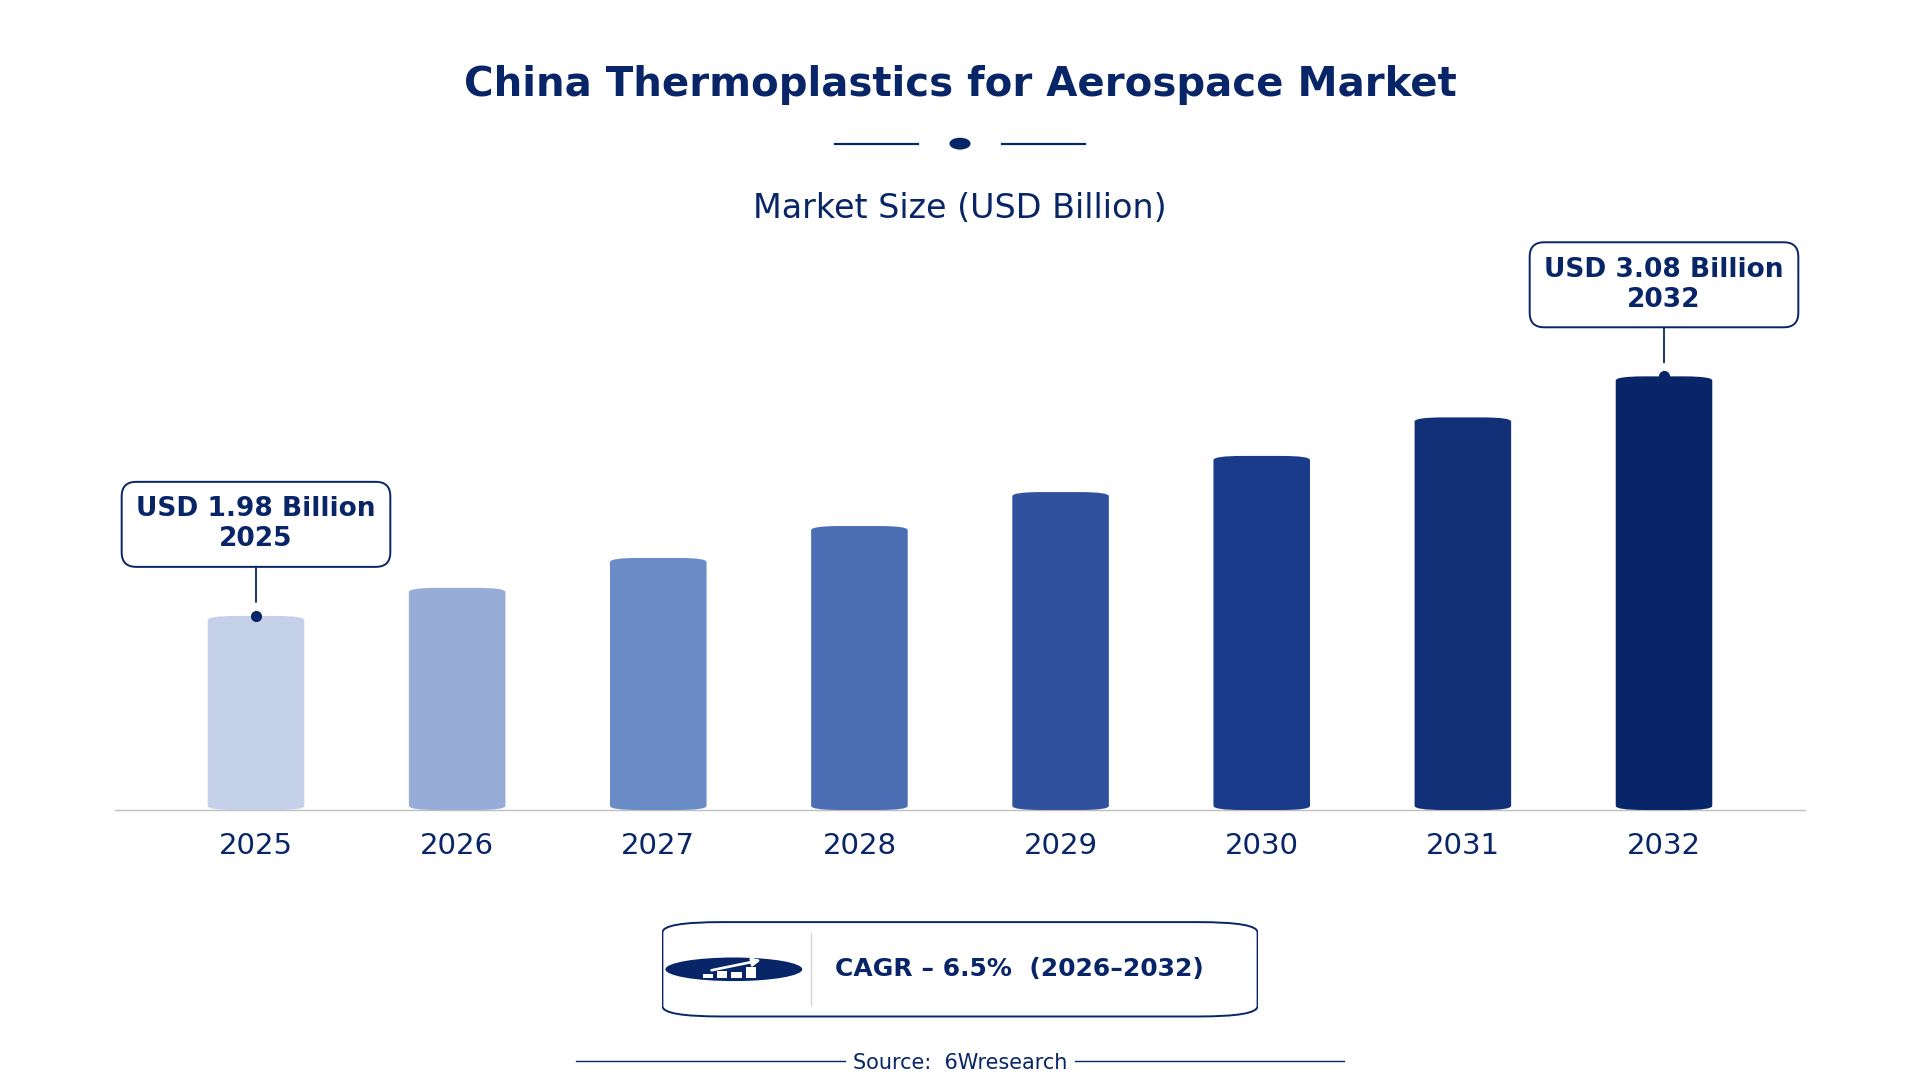
According to 6Wresearch internal database and industry insights, the China Thermoplastics for Aerospace Market was valued at USD 1.98 billion in 2025 and is projected to reach USD 3.08 billion by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
China Thermoplastics for Aerospace Market Highlights
| Report Metric | Details |
| Report Name | China Thermoplastics for Aerospace Market |
| Market Size 2025 | USD 1.98 billion |
| Market Size 2032 | USD 3.08 billion |
| Absolute Growth 2025–2032 | USD 1.10 billion |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 9.0% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Thermoplastics for Aerospace, 2025 | PEI (Ultem®) (48% share) |
| Leading Product Type, 2025 | High Temp Parts (51% share) |
| Leading Polymer Grade, 2025 | Flame-Retardant Grade (34% share) |
| Leading Distribution Channel, 2025 | Aerospace Distributors (48% share) |
| Leading End User Industry, 2025 | Aircraft Interiors (48% share) |
| Fastest-Growing Thermoplastics for Aerospace | PPSU (9.0% CAGR) |
| Fastest-Growing Product Type | Plumbing/Seals (8.2% CAGR) |
| Fastest-Growing Polymer Grade | Autoclave-Capable (8.3% CAGR) |
| Fastest-Growing Distribution Channel | Direct Suppliers (8.3% CAGR) |
| Fastest-Growing End User Industry | Commercial Aircraft (8.7% CAGR) |
| Growing Sector | Commercial Aircraft |
| Key End Users | Aircraft Manufacturers, UAV Manufacturers, Aerospace Distributors, Engineering Firms |
China Thermoplastics for Aerospace Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
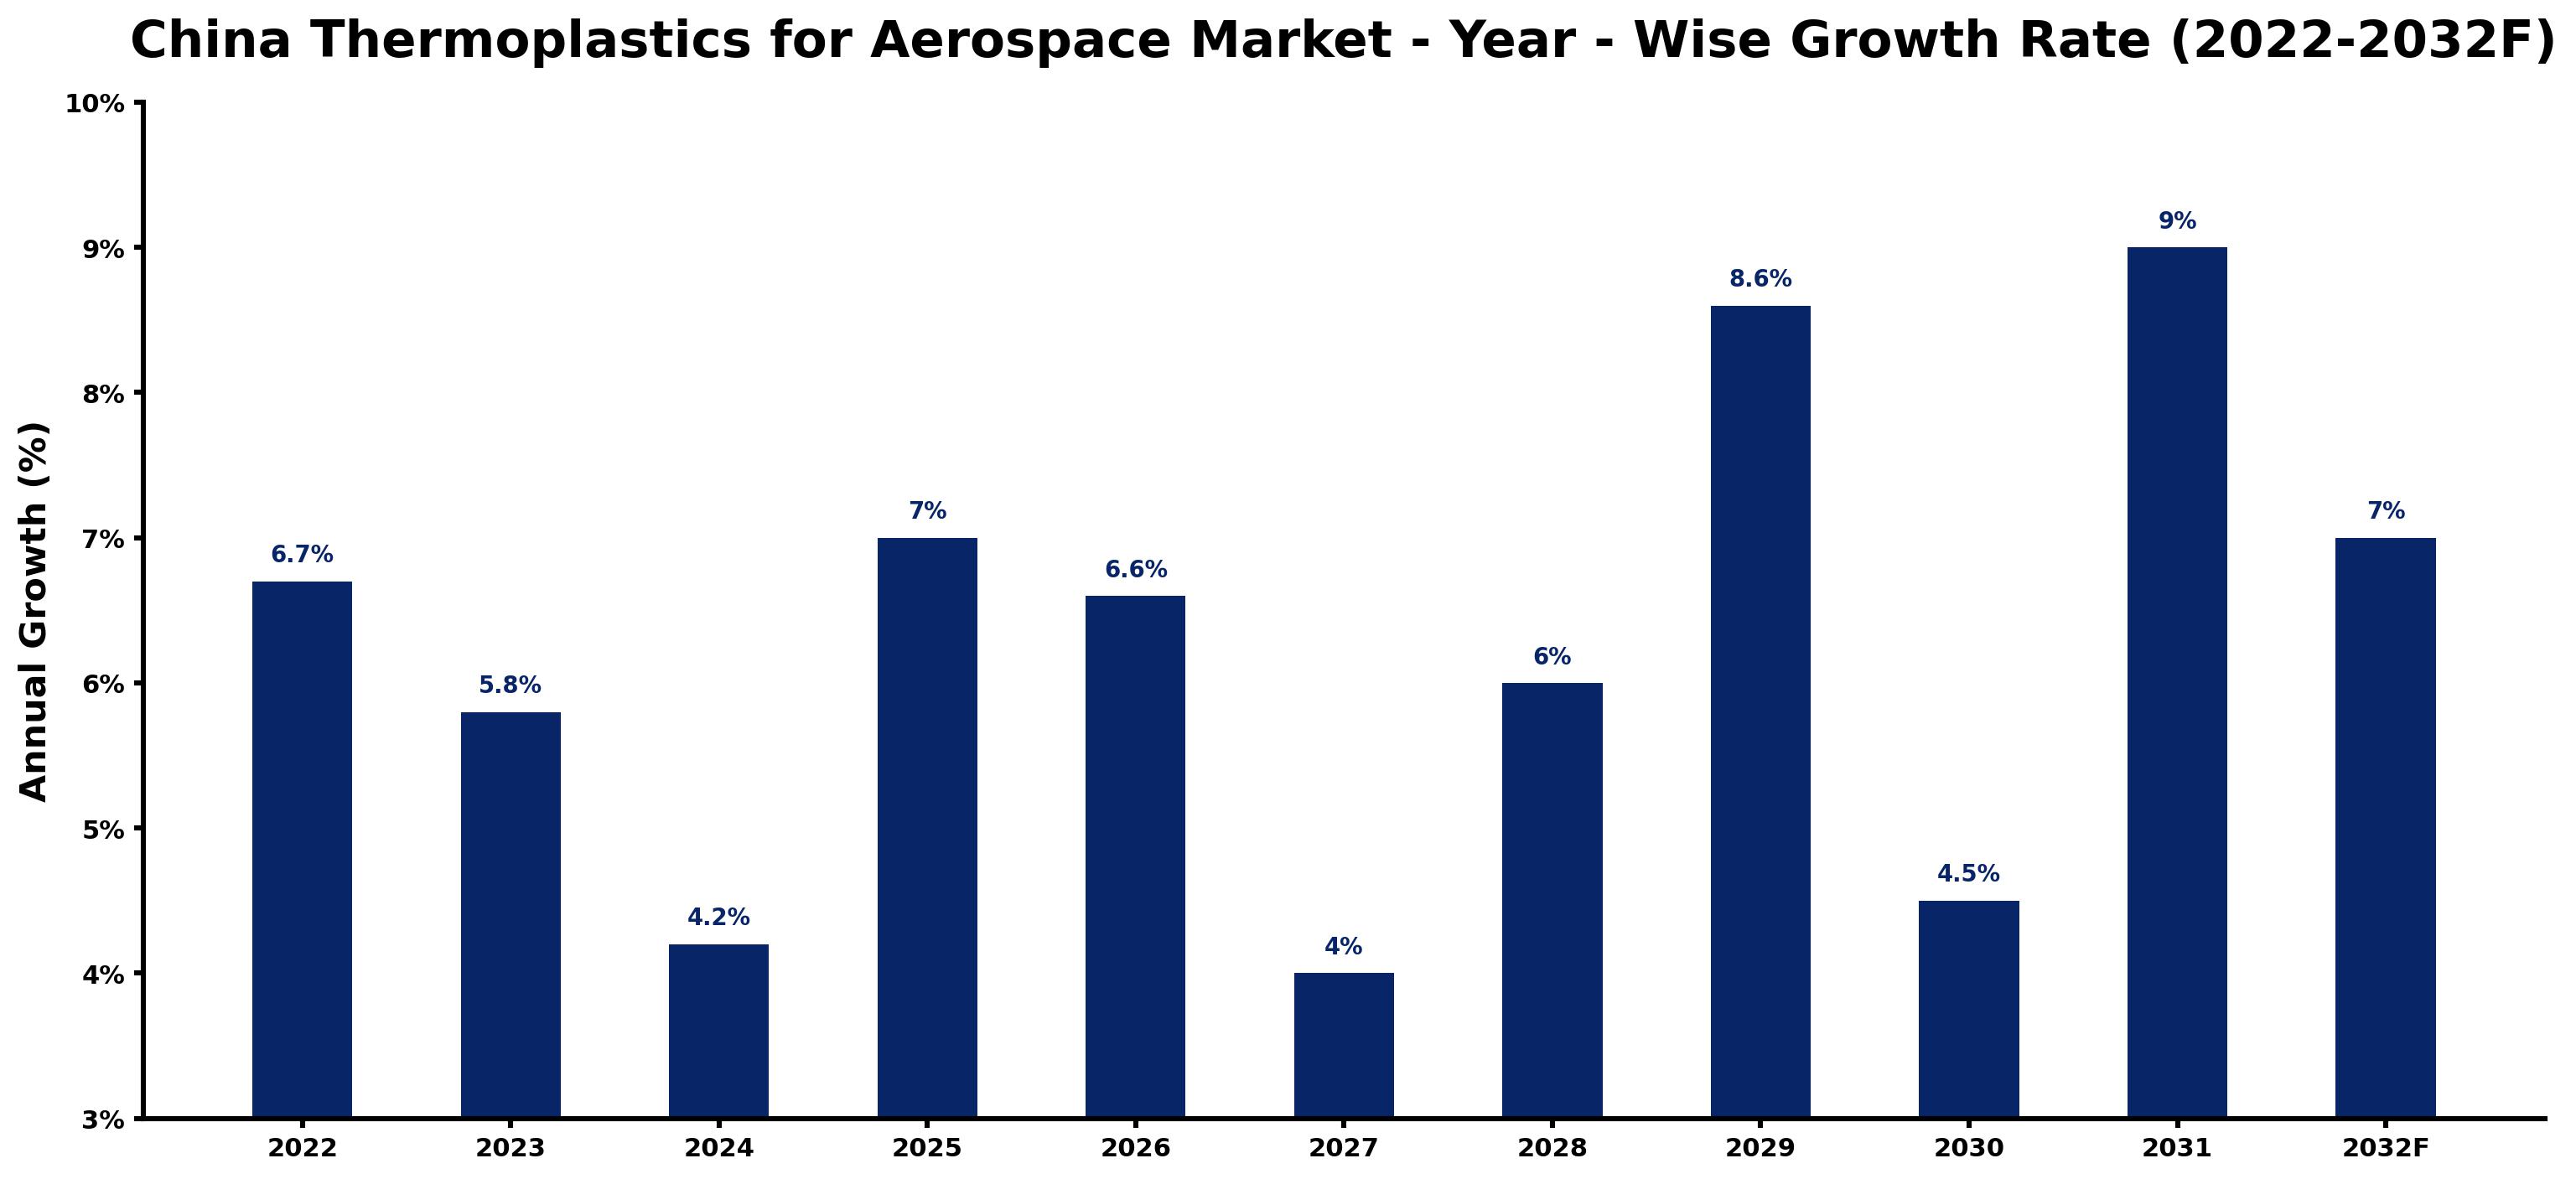
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.7 | The market experienced steady demand due to ongoing production of commercial aircraft. |
| 2023 | 5.8 | Growth slowed as manufacturers adjusted to supply chain challenges in the aerospace sector. |
| 2024 | 4.2 | Demand continued to slow as the market stabilised after previous peaks in production. |
| 2025 | 7.0 | The market rebounded with increased production of high-temperature parts for aircraft. |
| 2026 | 6.6 | Growth slowed as manufacturers focused on quality improvements and material certifications. |
| 2027 | 4.0 | Demand continued to decelerate as the focus shifted towards efficiency in production processes. |
| 2028 | 6.0 | Growth accelerated with rising interest in advanced materials for commercial aircraft. |
| 2029 | 8.6 | The market expanded rapidly as demand surged for advanced thermoplastic solutions. |
| 2030 | 4.5 | Growth slowed as manufacturers faced challenges in meeting new safety regulations. |
| 2031 | 9.0 | The market peaked with heightened demand for thermoplastics in jet engine components. |
| 2032 | 7.0 | Growth decelerated as the market stabilised after reaching new production capacities. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Thermoplastics for Aerospace Market Synopsis
Thermoplastics for Aerospace in China encompasses high-performance polymers utilised in aircraft manufacturing, recognised for their lightweight and heat-resistant attributes. These materials play a crucial role in structural components, interiors, and engine parts. The China Thermoplastics for Aerospace Market is growing due to increasing demand from domestic manufacturers and international collaborations. The aerospace industry is projected to reach a value of $1 trillion by 2030, with the UAV market expected to grow by 15% annually. This expansion is further supported by initiatives like 'Made in China 2025' aimed at improving advanced manufacturing capabilities.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for lightweight materials in commercial aircraft manufacturing | Driver | High | High Temp Parts |
| Increased investment in UAV technology and manufacturing | Driver | High | Commercial Aircraft |
| Expansion of aerospace manufacturing hubs in regions like Tianjin | Opportunity | High | Structural Parts |
| Rising demand for flame-retardant grades due to safety regulations | Opportunity | Medium | Flame-Retardant Grade |
| High costs associated with advanced thermoplastic materials | Restraint | High | PEEK |
| Limited availability of certified suppliers for aerospace-grade materials | Restraint | Medium | PPSU |
| Challenges in meeting new safety standards for thermoplastics | Challenge | High | Jet Engine Components |
| Competition from alternative materials in aerospace applications | Challenge | Medium | AM Filaments |
Evaluation of Drivers in China Thermoplastics for Aerospace Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of commercial aircraft leads to higher demand for thermoplastics. | High Temp Parts | In 2022, China produced over 300 commercial aircraft, boosting material needs. |
| Growing UAV market drives demand for advanced thermoplastic materials. | Commercial Aircraft | The UAV market is expected to grow by 15% annually, increasing material requirements. |
| Investment in aerospace manufacturing hubs strengthens local production capabilities. | Structural Parts | China has established several hubs in Tianjin and Shanghai to support aerospace growth. |
| Rising safety regulations necessitate the use of flame-retardant materials in interiors. | Flame-Retardant Grade | The demand for flame-retardant grades is increasing due to safety regulations. |
| Advancements in additive manufacturing technologies boost the use of AM filaments. | AM Filaments | Aerospace 3D printing is supported by government programs aimed at innovation. |
Growth across the Thermoplastics for Aerospace market in China is anchored in rising end-use demand from the commercial aircraft sector, coupled with increased investment in UAV technologies. In 2022, over 300 commercial aircraft were produced, leading to higher material requirements. The UAV market is anticipated to expand by 15% annually, driving further demand for advanced thermoplastics. Investment in aerospace manufacturing hubs in Tianjin and Shanghai strengthens local production capabilities.
Evaluation of Restraints in China Thermoplastics for Aerospace Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced thermoplastic materials limit adoption. | PEEK | The high price of PEEK restricts its use in cost-sensitive applications. |
| Limited availability of certified suppliers for aerospace-grade materials affects supply. | PPSU | A shortage of certified suppliers can delay production timelines for manufacturers. |
| Challenges in meeting new safety standards for thermoplastics complicate compliance. | Jet Engine Components | New regulations require extensive testing and certification processes, increasing costs. |
| Competition from alternative materials in aerospace applications pressures pricing. | AM Filaments | Alternative materials may offer lower costs, impacting thermoplastic demand. |
| Slow adoption of new technologies in traditional manufacturing processes hinders growth. | High Temp Parts | Manufacturers may be reluctant to invest in new technologies, limiting innovation. |
China Thermoplastics for Aerospace Market Challenges
Buyers in the China thermoplastics for aerospace market face rising costs from imported advanced materials, with over 20,000 tons imported in 2022, inflating production expenses by up to 20%. Suppliers struggle with regulatory compliance as the National Standard GB/T 33530-2017 enforces strict requirements that can delay product launches by six months, hindering their ability to meet market needs. Rapid technological advancements in aerospace 3D printing require substantial investment, deterring smaller manufacturers and limiting competition. Additionally, increasing demand for flame-retardant thermoplastics due to safety regulations forces suppliers to adjust product lines quickly, often resulting in higher costs for buyers.
Trends in the China Thermoplastics for Aerospace Market
Several trends are reshaping the China Thermoplastics for Aerospace Market; the most important are set out below.
- Partnerships with Local Manufacturers: Investing in partnerships with local manufacturers in China is essential for market entry. The aerospace industry is projected to reach $1 trillion by 2030, creating opportunities for collaboration.
- Investment in UAV Technologies: The UAV market is set to expand by 15% annually, presenting a timely opportunity for suppliers of thermoplastics. Targeting UAV manufacturers in regions like Tianjin can facilitate market entry.
- Expansion into Composite Materials: With a target of 30% of new aircraft made from composite materials by 2030, there is a gap for suppliers to fill. Engaging with aerospace manufacturers can lead to fruitful partnerships.
- Certification for Advanced Materials: Investing in certification for advanced thermoplastic grades is essential. The rising need for flame-retardant materials due to safety regulations offers a timely opportunity.
Investment Opportunities in the China Thermoplastics for Aerospace Market
Investors looking at the China Thermoplastics for Aerospace Market should consider the following areas.
- Partnerships with Local Manufacturers: Investing in partnerships with local manufacturers in China is essential for market entry. The aerospace industry is projected to reach $1 trillion by 2030, creating opportunities for collaboration.
- Investment in UAV Technologies: The UAV market is set to grow by 15% annually, presenting a timely opportunity for suppliers of thermoplastics. Targeting UAV manufacturers in regions like Tianjin can facilitate market entry.
- Expansion into Composite Materials: With a target of 30% of new aircraft made from composite materials by 2030, there is a gap for suppliers to fill. Engaging with aerospace manufacturers can lead to fruitful partnerships.
- Certification for Advanced Materials: Investing in certification for advanced thermoplastic grades is essential. The rising need for flame-retardant materials due to safety regulations offers a timely opportunity.
Government Initiatives in the China Thermoplastics for Aerospace Market
The aerospace industry in China is shaped by several key policies aimed at boosting the production of thermoplastics. The 'Aerospace Materials Development Plan' launched by the Ministry of Industry and Information Technology in 2021 focuses on enhancing domestic production capabilities for aerospace materials. In 2022, the National Development and Reform Commission approved the 'Aerospace Innovation Strategy', which aims to increase R&D investment in advanced materials by 20% by 2025. Additionally, the 'Aerospace Safety Standards' introduced by the China National Aeronautics and Space Administration in 2023 regulate the use of thermoplastics in aircraft manufacturing, ensuring compliance with safety requirements. These measures collectively improve the manufacturing environment for thermoplastics in aerospace applications.
Buyers in the aerospace sector benefit from various government schemes that support the use of advanced materials. The National Development and Reform Commission's funding programs for aerospace innovations encourage research and development in thermoplastics, facilitating the introduction of new materials. The Shanghai Aerospace Industry Association promotes the adoption of advanced materials among local manufacturers, enhancing their competitiveness. Furthermore, the Beijing Institute of Aeronautical Materials conducts research on thermoplastics, providing valuable insights and certifications that help buyers ensure compliance with industry standards. These initiatives collectively strengthen the supply chain and improve the availability of high-quality thermoplastics for aerospace applications.
Future Insight of the China Thermoplastics for Aerospace Market
By 2032, buyers and suppliers in the China thermoplastics for aerospace market can expect notable changes driven by the 'Made in China 2025' initiative, which aims to improve advanced manufacturing capabilities. The installed base of over 3,000 commercial aircraft will create substantial demand for lightweight thermoplastics in structural components. The goal of 30% composite materials in new aircraft by 2030 will encourage advancements in thermoplastic formulations. Government funding programs from the National Development and Reform Commission will support research initiatives, leading to improvements in production efficiency.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Thermoplastics for Aerospace – PEI (Ultem®) Dominated, PPSU Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, PEI (Ultem®) held a 48% share of the China Thermoplastics for Aerospace Market by thermoplastics for aerospace in 2025. PEI (Ultem®) holds a substantial share in the China thermoplastics for aerospace market, primarily due to its critical application in high-temperature environments, particularly in jet engine components. The extensive installed base of over 3,000 commercial aircraft necessitates materials that meet stringent performance standards. The quickest growth will come from PPSU, forecast to expand at a CAGR of 9.0% between 2026 and 2032. PPSU is rapidly gaining traction, driven by its exceptional chemical resistance, which is vital for plumbing and seals in aircraft. With the aerospace sector projected to expand significantly, the demand for durable materials in fluid systems is expected to rise sharply. Suppliers should enhance their offerings of high-performance thermoplastics to meet the increasing demands of the aerospace industry.
By Product Type – High Temp Parts Dominated, Plumbing/Seals Expected to Grow Fastest
With a 51% revenue share in 2025, High Temp Parts was the largest product type category. High Temp Parts command a significant share in the market as they are essential for components exposed to extreme temperatures in aircraft. The production of over 300 commercial aircraft in 2022 reinforces the necessity for these specialised materials in the aerospace sector. Over 2026–2032, Plumbing/Seals are expected to post the fastest growth, at a CAGR of 8.2%. The Plumbing/Seals segment is witnessing rapid growth due to the rising need for reliable fluid systems in aircraft. As the demand for commercial aircraft escalates, so too does the requirement for effective plumbing solutions, propelling this segment's expansion. Manufacturers should prioritise the development of high-performance plumbing and sealing solutions to align with the evolving needs of the aerospace industry.
By Polymer Grade – Flame-Retardant Grade Dominated, Autoclave-Capable Expected to Grow Fastest
Flame-Retardant Grade accounted for a 34% market share by polymer grade in 2025. Flame-Retardant Grade captures a significant share in the China thermoplastics for aerospace market, as it is crucial for ensuring safety in aircraft interiors. The stringent safety regulations in the aerospace sector necessitate materials that can withstand fire hazards, making this grade highly sought after. Autoclave-Capable is projected to grow fastest, at a CAGR of 8.3% during 2026–2032. The Autoclave-Capable segment is experiencing rapid growth due to its essential role in parts manufactured in autoclaves, which are critical for high-performance applications. As the aerospace industry continues to innovate, the demand for autoclave-capable materials is expected to increase. Suppliers should focus on developing flame-retardant and autoclave-capable thermoplastics to meet regulatory requirements and market demands.
By Distribution Channel – Aerospace Distributors Dominated, Direct Suppliers Expected to Grow Fastest
Aerospace Distributors took a 48% share of distribution channel in 2025, more than any other category. Aerospace Distributors hold a prominent share in the market as they facilitate the supply of thermoplastics to various manufacturers in the aerospace sector. Their established networks and relationships with manufacturers ensure a steady flow of materials necessary for production. Direct Suppliers are set to record the highest CAGR in this split, 8.3% over 2026–2032. Direct Suppliers are rapidly gaining ground as they provide materials directly to manufacturers, streamlining the supply chain. This direct relationship allows for quicker response times and tailored solutions, which are increasingly valued in the aerospace industry. Distributors must adapt to the growing preference for direct supply channels to remain competitive in the aerospace materials market.
By End User Industry – Aircraft Interiors Dominated, Commercial Aircraft Expected to Grow Fastest
In 2025, Aircraft Interiors led the end user industry split with a 48% share. Aircraft Interiors represent the largest share in the China thermoplastics for aerospace market, as they are vital for ensuring passenger comfort and safety. The growing emphasis on enhancing the passenger experience in commercial aircraft drives demand for high-quality materials in this segment. The quickest growth will come from Commercial Aircraft, forecast to expand at a CAGR of 8.7% between 2026 and 2032. The Commercial Aircraft segment is experiencing the fastest growth due to the surge in aircraft production and the increasing demand for air travel in China. As the aerospace market expands, the need for thermoplastics in commercial aircraft applications will continue to grow. Manufacturers should concentrate on developing advanced thermoplastics specifically for aircraft interiors to capitalise on the growing demand in the commercial aircraft sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Thermoplastics for Aerospace Market Outlook
- Market Size of China Thermoplastics for Aerospace Market, 2025
- Forecast of China Thermoplastics for Aerospace Market, 2032
- Historical Data and Forecast of China Thermoplastics for Aerospace Revenues & Volume for the Period 2022 - 2032F
- China Thermoplastics for Aerospace Market Trend Evolution
- China Thermoplastics for Aerospace Market Drivers and Challenges
- China Thermoplastics for Aerospace Price Trends
- China Thermoplastics for Aerospace Porter's Five Forces
- China Thermoplastics for Aerospace Industry Life Cycle
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Thermoplastics for Aerospace for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By PEI (Ultem ) for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By PPSU for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By PEEK for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By PEKK for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By High Temp Parts for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Plumbing/Seals for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Structural Parts for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By AM Filaments for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Polymer Grade for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Flame-Retardant Grade for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Autoclave-Capable for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Composite Grades for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By 3D Printed Parts for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Aerospace Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Direct Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Specialty Resellers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Aerospace 3D Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Aircraft Interiors for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Commercial Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By Jet Engine Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoplastics for Aerospace Market Revenues & Volume By UAV/Additive Manufacturing for the Period 2022 - 2032F
- China Thermoplastics for Aerospace Import Export Trade Statistics
- Market Opportunity Assessment By Thermoplastics for Aerospace
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Polymer Grade
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Thermoplastics for Aerospace Top Companies Market Share
- China Thermoplastics for Aerospace Competitive Benchmarking By Technical and Operational Parameters
- China Thermoplastics for Aerospace Company Profiles
- China Thermoplastics for Aerospace Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Thermoplastics for Aerospace
- PEI (Ultem®)
- PPSU
- PEEK
- PEKK
By Product Type
- High Temp Parts
- Plumbing/Seals
- Structural Parts
- AM Filaments
By Polymer Grade
- Flame-Retardant Grade
- Autoclave-Capable
- Composite Grades
- 3D Printed Parts
By Distribution Channel
- Aerospace Distributors
- Direct Suppliers
- Specialty Resellers
- Aerospace 3D Suppliers
By End User Industry
- Aircraft Interiors
- Commercial Aircraft
- Jet Engine Components
- UAV/Additive Manufacturing































