China Thick Film Pastes Market Size & Growth Rate
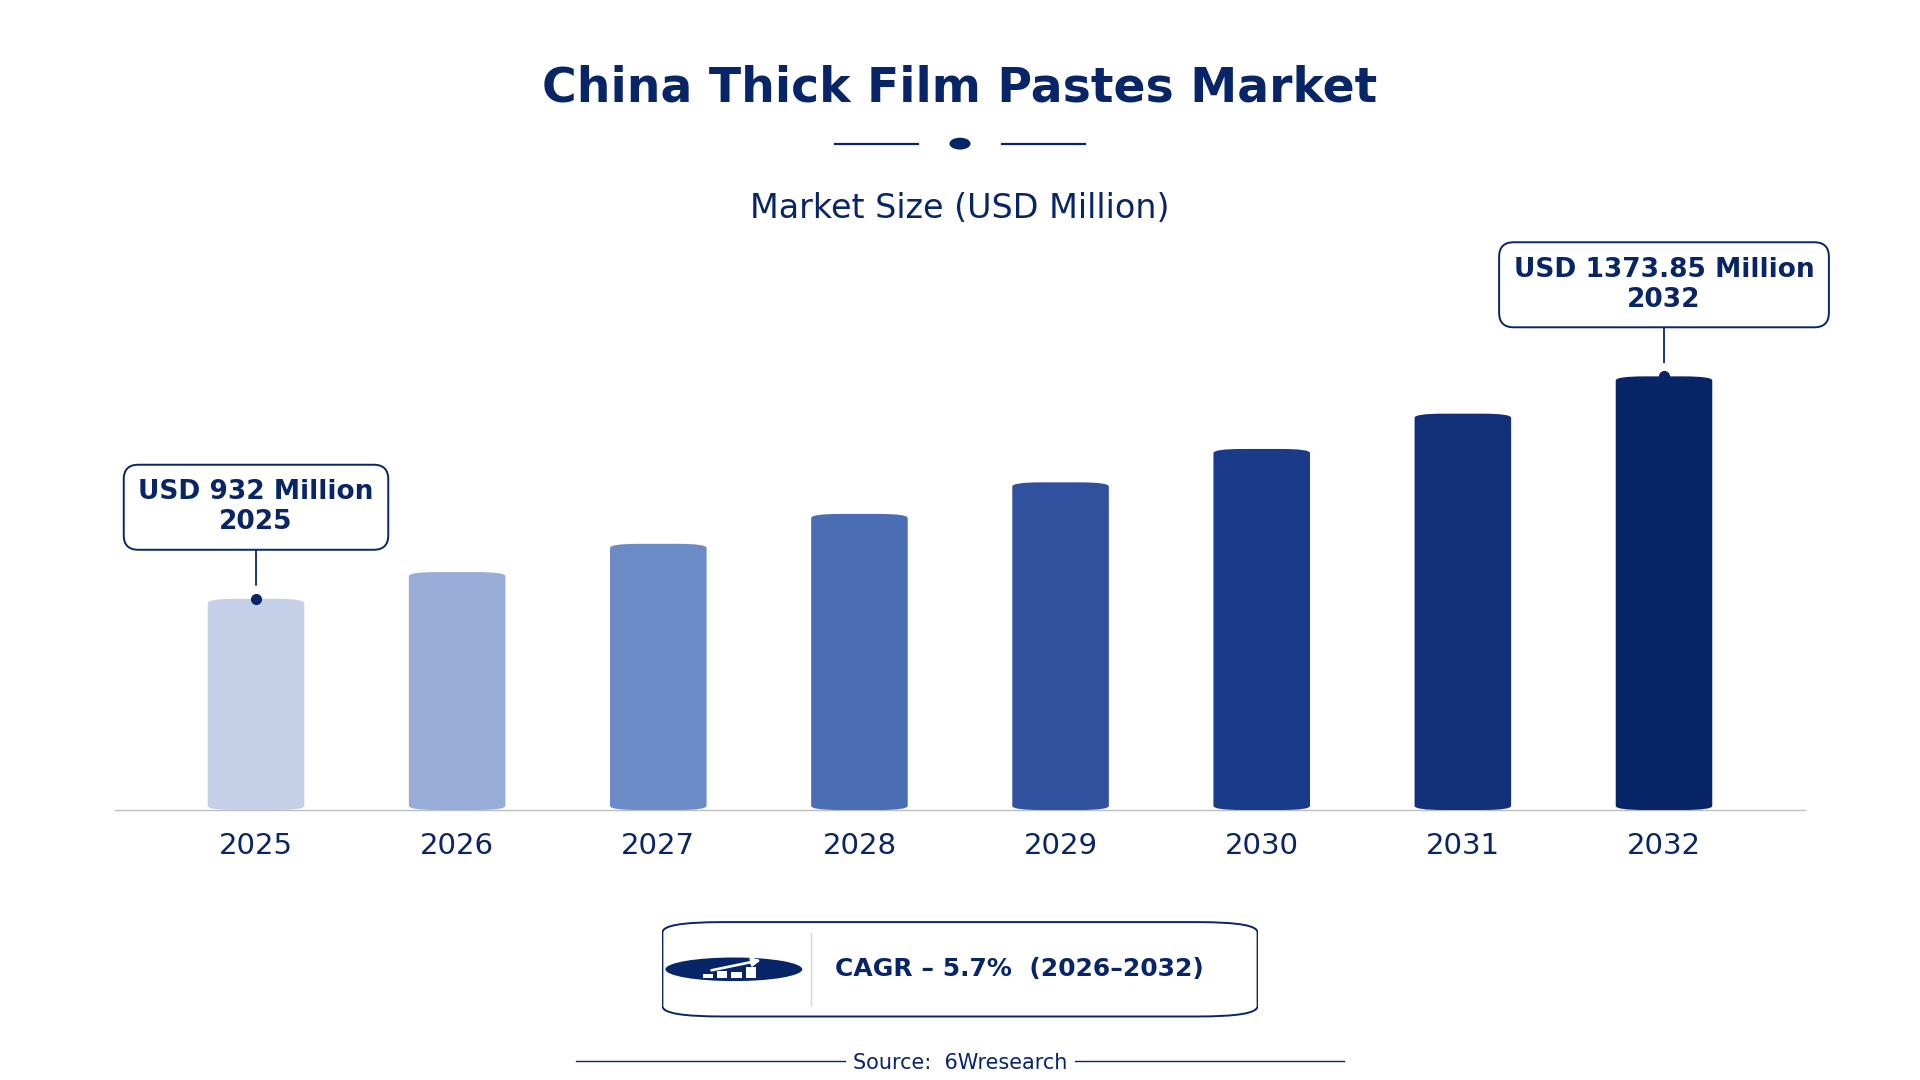
According to 6Wresearch internal database and industry insights, the China Thick Film Pastes Market was valued at USD 932.0 million in 2025 and is projected to reach USD 1,373.85 million by 2032, growing at a CAGR of approximately 5.7% during 2026–2032.
China Thick Film Pastes Market Highlights
| Report Metric | Details |
| Report Name | China Thick Film Pastes Market |
| Market Size 2025 | USD 932.0 million |
| Market Size 2032 | USD 1,373.85 million |
| Absolute Growth 2025–2032 | USD 441.85 million |
| CAGR 2026–2032 | 5.7% |
| Peak Annual Growth | 8.3% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Paste Type, 2025 | Silver Paste (49% share) |
| Leading Application Area, 2025 | Circuit Printing (40% share) |
| Leading Conductivity Type, 2025 | Conductive (53% share) |
| Leading End User, 2025 | Electronics OEMs (49% share) |
| Fastest-Growing Paste Type | Dielectric Paste (8.3% CAGR) |
| Fastest-Growing Application Area | Insulation Layers (7.6% CAGR) |
| Fastest-Growing Conductivity Type | Non-Conductive (6.9% CAGR) |
| Fastest-Growing End User | Solar Cell Manufacturers (7.3% CAGR) |
| Growing Sector | Electronics |
| Key End Users | Electronics OEMs, Automotive Electronics, Solar Cell Manufacturers, Military Electronics Firms |
China Thick Film Pastes Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
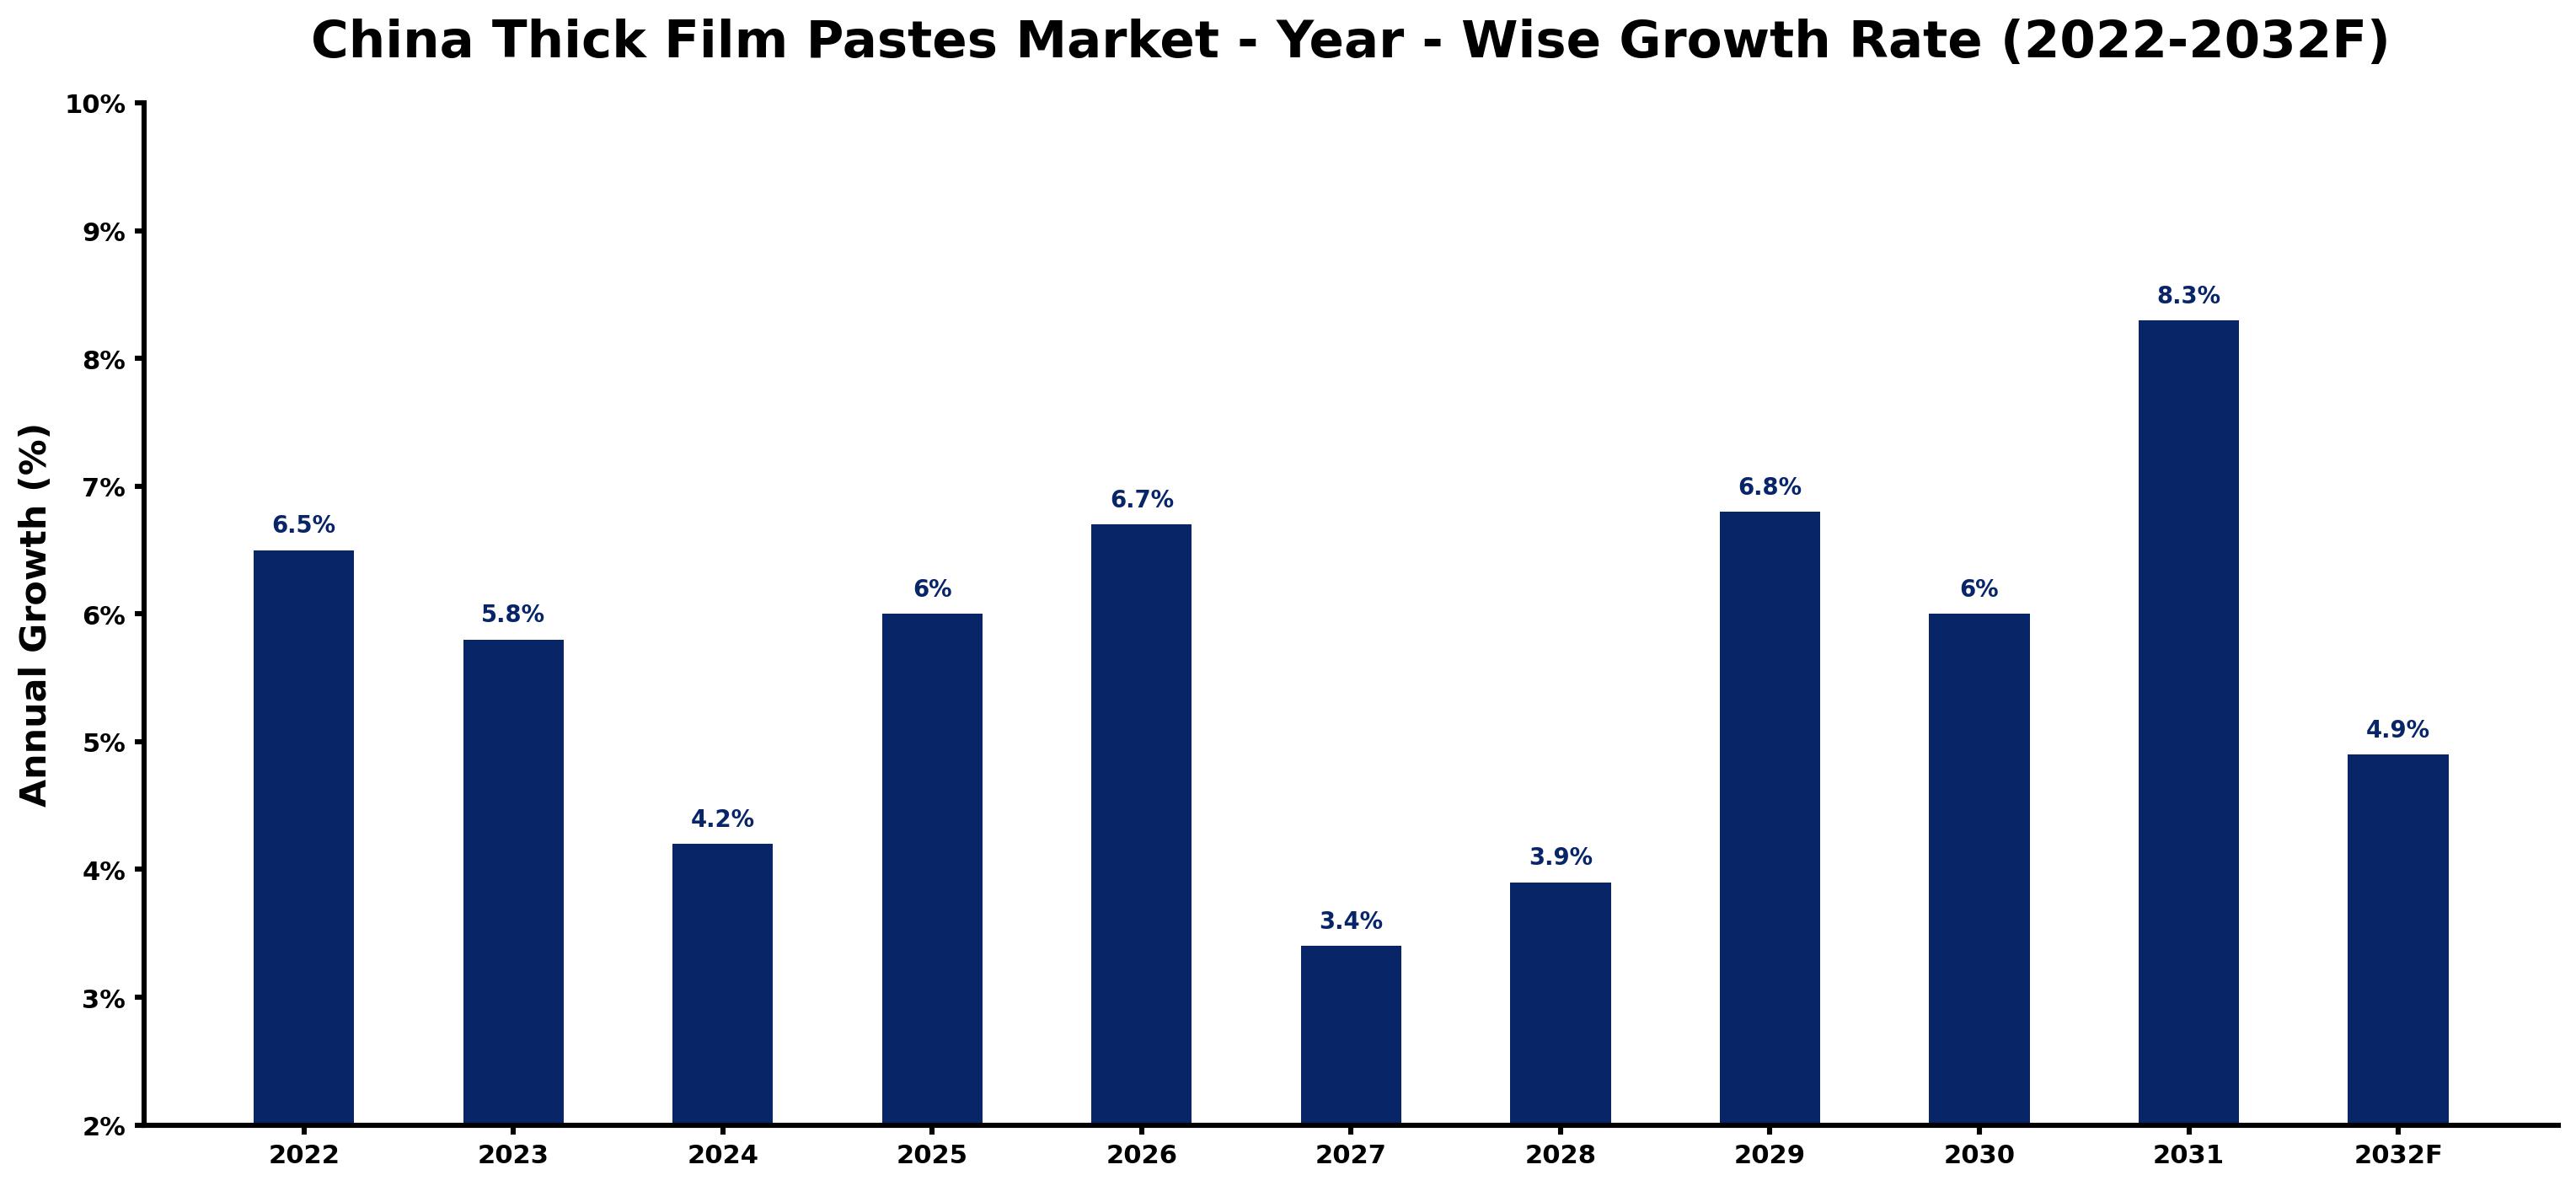
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.5 | The market showed strong demand from electronics manufacturers and significant production capabilities. |
| 2023 | 5.8 | Growth slowed due to the impact of the 'Made in China 2025' initiative on market dynamics. |
| 2024 | 4.2 | The market continued to slow as manufacturers faced rising costs in raw materials and production. |
| 2025 | 6.0 | Demand increased as electronics OEMs expanded production to meet growing market needs. |
| 2026 | 6.7 | Growth is expected to accelerate with the introduction of new technologies in circuit printing. |
| 2027 | 3.4 | The market is projected to slow as demand stabilises amid fluctuating material costs. |
| 2028 | 3.9 | Demand is expected to pick up as insulation layers gain traction in electronic devices. |
| 2029 | 6.8 | Growth is projected to resume as the automotive electronics sector expands rapidly. |
| 2030 | 6.0 | The market will experience a slowdown as manufacturers adjust to new regulatory standards. |
| 2031 | 8.3 | Demand is expected to surge with the introduction of advanced materials in electronics manufacturing. |
| 2032 | 4.9 | Growth will slow as the market stabilises after reaching a peak in previous years. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Thick Film Pastes Market Synopsis
Thick Film Pastes in China are conductive materials primarily used in electronics for printing circuits and components. These pastes are made by mixing metal powders, glass frit, and organic binders, serving critical applications in circuit printing and insulation layers. The China Thick Film Pastes Market is growing due to strong domestic demand from electronics OEMs and ongoing investments in technology. The electronics manufacturing sector employs around 6 million people, driving substantial growth. The 'Made in China 2025' initiative further supports advancements in manufacturing capabilities, contributing to increased demand for thick film pastes.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong domestic demand from electronics manufacturers | Driver | High | Circuit Printing |
| Growing investments in advanced materials | Driver | High | Conductive |
| Increasing demand for insulation layers in electronic devices | Opportunity | High | Insulation Layers |
| Expansion of the automotive electronics market | Opportunity | Medium | Automotive Electronics |
| Rising costs of raw materials affecting production | Restraint | High | Dielectric Paste |
| Increased competition leading to price pressures | Restraint | Medium | Silver Paste |
| Delays in regulatory approvals for new materials | Challenge | High | Hybrid Circuits |
| Supply chain disruptions impacting material availability | Challenge | Medium | High-Frequency Devices |
Evaluation of Drivers in China Thick Film Pastes Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Strong domestic demand from electronics manufacturers | Circuit Printing | This demand drives increased purchases of thick film pastes for circuit applications, with over 20,000 tons produced in 2022. |
| Growing investments in advanced materials | Conductive | Investments in new technologies are improving production capabilities, increasing consumption of conductive pastes in electronics. |
| Expansion of the automotive electronics sector | Automotive Electronics | The automotive electronics market is expected to reach $100 billion by 2025, boosting demand for thick film pastes. |
| Rising adoption of insulation layers in electronic devices | Insulation Layers | The annual demand for dielectric pastes is estimated at 5,000 tons, reflecting the growing need for insulation. |
| Support from government initiatives like 'Made in China 2025' | Hybrid Circuits | This initiative promotes local production capabilities, increasing demand for hybrid circuit applications. |
Market growth for Thick Film Pastes in China is underpinned by strong domestic demand from electronics manufacturers, driving substantial production. In 2022, over 20,000 tons of thick film pastes were produced, reflecting the electronics sector's activity. The automotive electronics market is expanding rapidly, spurring demand for conductive materials. The annual demand for dielectric pastes is estimated at 5,000 tons, indicating the need for insulation layers.
Evaluation of Restraints in China Thick Film Pastes Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Rising costs of raw materials affecting production | Dielectric Paste | Increased costs of metal powders and binders are impacting profit margins for manufacturers. |
| Increased competition causing price pressures | Silver Paste | Price competition among manufacturers is squeezing margins, affecting profitability. |
| Delays in regulatory approvals for new materials | Hybrid Circuits | Regulatory hurdles slow down the introduction of new materials into the market. |
| Supply chain disruptions impacting material availability | High-Frequency Devices | Global supply chain issues are causing delays in the procurement of essential materials. |
| Limited awareness of advanced applications among manufacturers | Insulation Layers | Manufacturers may not fully utilise insulation layers due to a lack of understanding of their benefits. |
China Thick Film Pastes Market Challenges
The China Thick Film Pastes Market faces significant competition from both domestic and international manufacturers, leading to price wars that erode profit margins for producers and threaten their sustainability. Technological advancements in thick film paste formulations are not keeping pace with the rapid changes in the electronics sector, resulting in delays for suppliers who struggle to meet evolving industry standards. Regulatory requirements enforced by the National Development and Reform Commission impose additional compliance costs on manufacturers, extending the time needed for product approvals and delaying market entry. A shortage of skilled workers in advanced manufacturing techniques hampers innovation, restricting producers' ability to enhance product offerings and meet the increasing demand from the electronics industry.
Trends in the China Thick Film Pastes Market
Several trends are reshaping the China Thick Film Pastes Market; the most important are set out below.
- Shift towards Advanced Materials in Electronics: The 'Made in China 2025' initiative is pushing manufacturers to adopt advanced materials, improving the quality of thick film pastes. This shift is expected to increase production efficiency, with the electronics sector projected to grow to $1 trillion by 2025.
- Transition from Traditional to Smart Electronics: Since 2023, the demand for smart electronic devices has surged, leading to increased use of thick film pastes in circuit printing. The installed base of electronic devices in China has surpassed 1.4 billion units, driving this trend.
- Emergence of Insulation Layers in Circuit Design: Beginning in 2024, insulation layers have gained prominence in circuit design, essential for preventing electrical interference. The annual demand for dielectric pastes is estimated at 5,000 tons, indicating this growing trend.
- Growing Focus on Sustainable Manufacturing: The 'Green Manufacturing Program' initiated in 2020 encourages sustainable practices in the electronics sector. This shift is prompting manufacturers to invest in eco-friendly thick film paste technologies.
Investment Opportunities in the China Thick Film Pastes Market
Investors looking at the China Thick Film Pastes Market should consider the following areas.
- $100 Billion Automotive Electronics Market: With the automotive electronics market projected to reach $100 billion by 2025, there is an opportunity for suppliers of thick film pastes. Collaborating with automotive OEMs can facilitate entry into this growing sector.
- Increasing Demand for Insulation Layers: The annual demand for dielectric pastes is estimated at 5,000 tons, presenting a lucrative opportunity for manufacturers. Focusing on partnerships with electronics OEMs can enhance market penetration.
- Expansion of Solar Cell Manufacturing: China's solar cell production capacity reached 200 GW in 2022, driving demand for thick film pastes. Suppliers can engage with solar cell manufacturers to meet the growing material needs.
- Support from Government Initiatives: The '14th Five-Year Plan for the Electronics Industry' aims to enhance domestic production capabilities, creating opportunities for investment in thick film paste technologies. Collaborating with local partners can facilitate market entry.
Government Initiatives in the China Thick Film Pastes Market
In 2021, the Ministry of Industry and Information Technology launched the '14th Five-Year Plan for the Electronics Industry', which aims to boost domestic production capabilities. This plan focuses on technological advancements and supports local manufacturers in adopting new materials. The initiative is set to significantly increase the production capacity of thick film pastes in the coming years. Additionally, it establishes clear targets for innovation and quality improvements in the electronics sector.
In 2023, the State Council approved the 'National Strategy for Semiconductor Development', with a budget of $500 million allocated to strengthen local semiconductor manufacturing. This strategy, overseen by the Ministry of Industry and Information Technology, aims to bolster the supply chain for electronics manufacturing. It includes funding for research and development in thick film paste technologies, which will improve production capabilities and support manufacturers in meeting growing market demands.
Future Insight of the China Thick Film Pastes Market
The China Thick Film Pastes Market is expected to evolve significantly by 2032, driven by key developments. The 'Made in China 2025' initiative will push manufacturers toward adopting advanced production techniques, improving operational efficiency. Government support for research and development in thick film technologies will foster innovation, resulting in superior products. By 2025, the solar cell production capacity is projected to reach 200 GW, boosting the demand for high-quality thick film pastes. As the electronics market grows to $1 trillion by 2025, suppliers must ensure adequate product availability to satisfy the surging consumer demand.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Paste Type – Silver Paste Dominated, Dielectric Paste Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, with a 49% revenue share in 2025, Silver Paste was the largest paste type category. Silver paste holds the largest share in the China Thick Film Pastes Market due to its extensive use in circuit printing applications, which are critical for the electronics sector. With over 20,000 tons produced in 2022, it is the go-to choice for manufacturers prioritising reliability in their products. Over 2026–2032, Dielectric Paste is expected to post the fastest growth, at a CAGR of 8.3%. Dielectric paste is experiencing the fastest growth, attributed to its essential role in insulation layers that prevent electrical interference in electronic components. The annual demand for dielectric pastes, estimated at 5,000 tons, indicates a significant opportunity for expansion in this area. Suppliers should focus on developing dielectric paste solutions to meet the rising demand from electronics manufacturers.
By Application Area – Circuit Printing Dominated, Insulation Layers Expected to Grow Fastest
In 2025, Circuit Printing led the application area split with a 40% share. Circuit printing commands the largest share in the China Thick Film Pastes Market as it is the primary application for thick film pastes, essential for producing electronic devices. This application is integral to the thriving electronics manufacturing sector, which employs around 6 million people. Insulation Layers are projected to grow fastest, at a CAGR of 7.6% during 2026–2032. Insulation layers are the fastest-growing application area, driven by the increasing necessity to prevent electrical interference in electronic components. As the electronics market is projected to grow to $1 trillion by 2025, the demand for insulation layers will continue to rise significantly. This trend indicates that suppliers must enhance their insulation layer solutions to align with the growing requirements of the electronics manufacturing industry.
By Conductivity Type – Conductive Dominated, Non-Conductive Expected to Grow Fastest
The largest conductivity type category in 2025 was Conductive, with a 53% share of total revenue. Conductive thick film pastes dominate the market share as they are the primary type used in electronic applications, crucial for ensuring effective circuit functionality. Their widespread use across various electronic devices highlights their importance in the overall performance of the electronics sector. The quickest growth will come from Non-Conductive, forecast to expand at a CAGR of 6.9% between 2026 and 2032. Non-conductive thick film pastes are witnessing rapid growth, primarily due to their specific applications where conductivity is not required. As manufacturers seek specialised solutions, the demand for non-conductive options is expected to rise, creating new market opportunities. This trend signals to suppliers the need to diversify their product offerings to include non-conductive pastes for niche applications in electronics.
By End User – Electronics OEMs Dominated, Solar Cell Manufacturers Expected to Grow Fastest
Electronics OEMs accounted for a 49% market share by end user in 2025. Electronics OEMs represent the largest share in the China Thick Film Pastes Market as they are the primary users of thick film pastes for manufacturing electronic devices. Their significant presence in the market is reinforced by the ongoing investments in the electronics sector, driving consistent demand for these materials. Solar Cell Manufacturers are set to record the highest CAGR in this split, 7.3% over 2026–2032. Solar cell manufacturers are the fastest-growing end user segment, utilising thick film pastes in the production of photovoltaic cells. The rapid expansion of solar energy initiatives in China is significantly boosting the demand for these materials in this sector. This growth suggests that suppliers should focus on establishing partnerships with solar cell manufacturers to capitalise on the increasing demand for thick film pastes in renewable energy applications.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Thick Film Pastes Market Outlook
- Market Size of China Thick Film Pastes Market, 2025
- Forecast of China Thick Film Pastes Market, 2032
- Historical Data and Forecast of China Thick Film Pastes Revenues & Volume for the Period 2022 - 2032F
- China Thick Film Pastes Market Trend Evolution
- China Thick Film Pastes Market Drivers and Challenges
- China Thick Film Pastes Price Trends
- China Thick Film Pastes Porter's Five Forces
- China Thick Film Pastes Industry Life Cycle
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Paste Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Silver Paste for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Dielectric Paste for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Resistor Paste for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Gold Paste for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Circuit Printing for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Insulation Layers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Hybrid Circuits for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By High-Frequency Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Conductivity Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Conductive for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Non-Conductive for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Variable Resistivity for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By High-Conductivity for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Electronics OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Solar Cell Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Automotive Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Thick Film Pastes Market Revenues & Volume By Military Electronics Firms for the Period 2022 - 2032F
- China Thick Film Pastes Import Export Trade Statistics
- Market Opportunity Assessment By Paste Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Conductivity Type
- Market Opportunity Assessment By End User
- China Thick Film Pastes Top Companies Market Share
- China Thick Film Pastes Competitive Benchmarking By Technical and Operational Parameters
- China Thick Film Pastes Company Profiles
- China Thick Film Pastes Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Paste Type
- Silver Paste
- Dielectric Paste
- Resistor Paste
- Gold Paste
By Application Area
- Circuit Printing
- Insulation Layers
- Hybrid Circuits
- High-Frequency Devices
By Conductivity Type
- Conductive
- Non-Conductive
- Variable Resistivity
- High-Conductivity
By End User
- Electronics OEMs
- Solar Cell Manufacturers
- Automotive Electronics
- Military Electronics Firms































