China Transmission Gear Components Market Size & Growth Rate
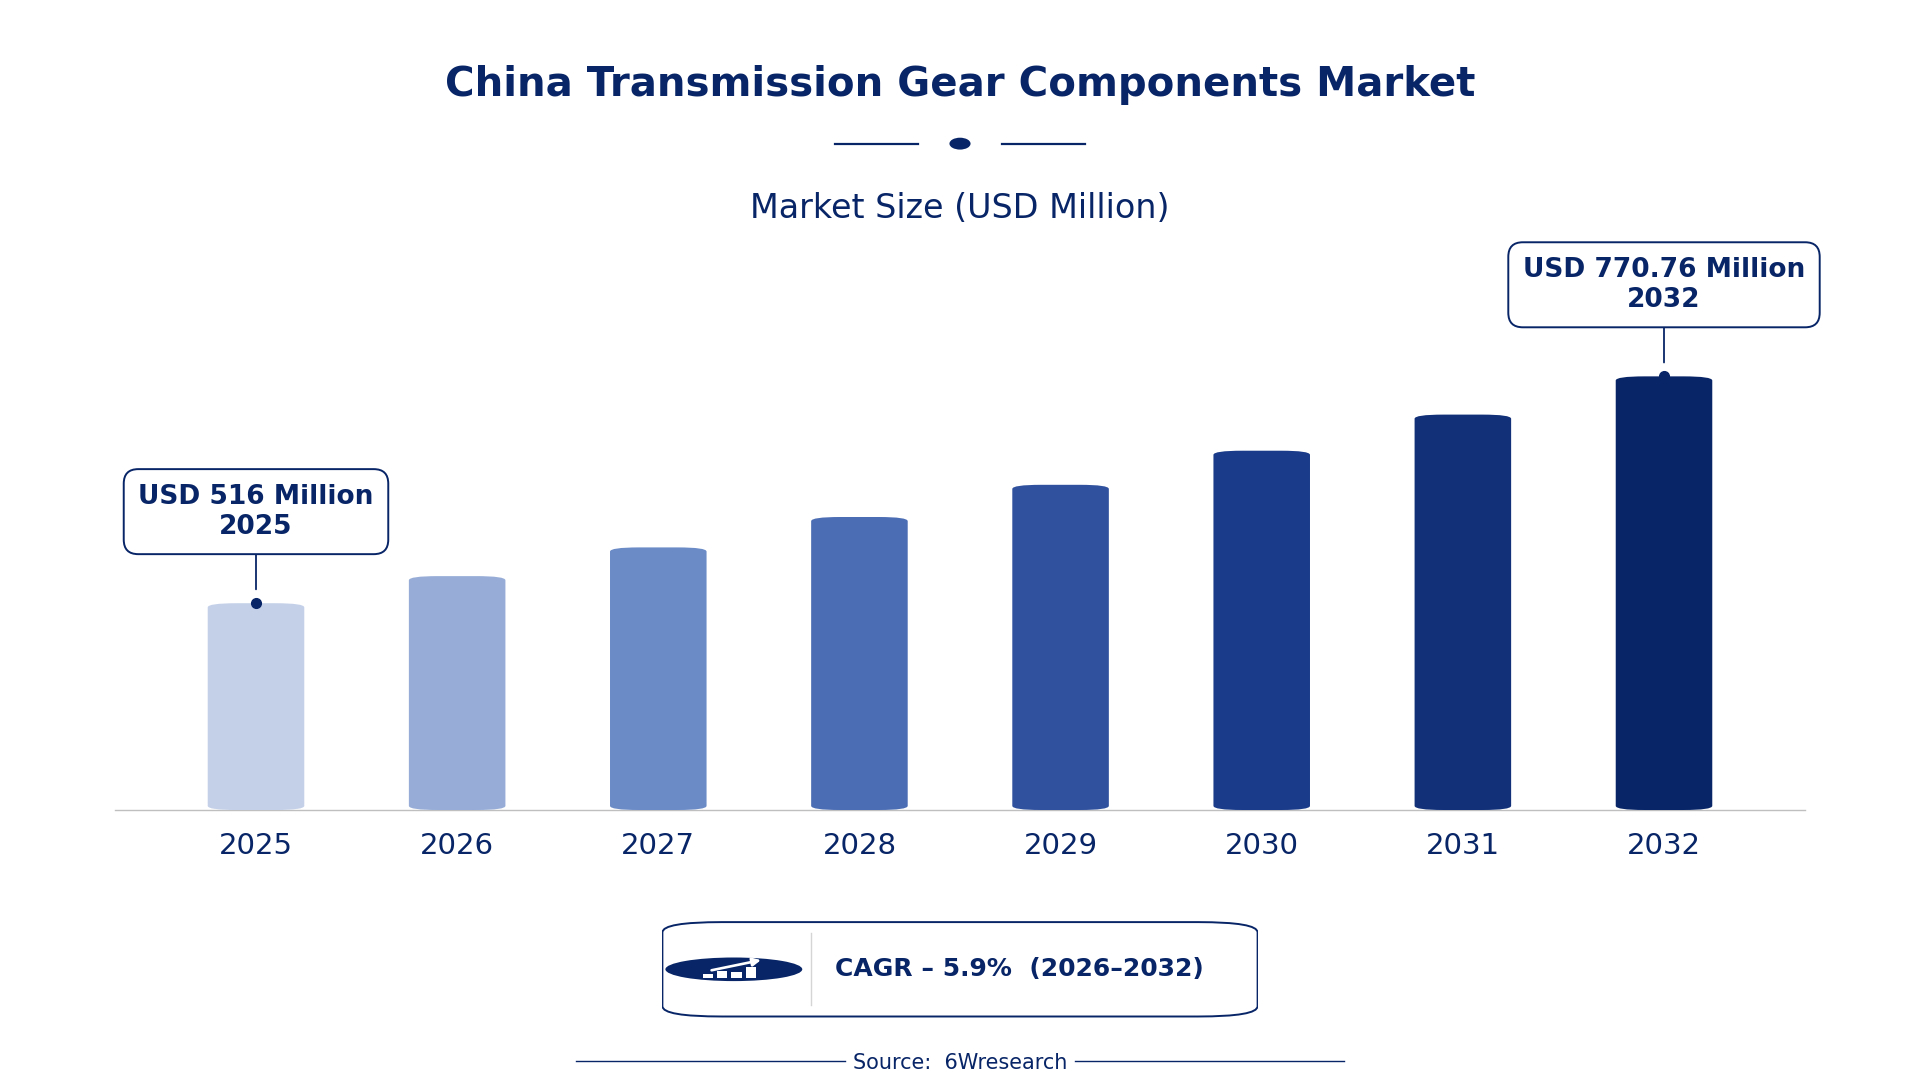
According to 6Wresearch internal database and industry insights, the China Transmission Gear Components Market was valued at USD 516.0 million in 2025 and is projected to reach USD 770.76 million by 2032, growing at a CAGR of approximately 5.9% during 2026–2032.
China Transmission Gear Components Market Highlights
| Report Metric | Details |
| Report Name | China Transmission Gear Components Market |
| Market Size 2025 | USD 516.0 million |
| Market Size 2032 | USD 770.76 million |
| Absolute Growth 2025–2032 | USD 254.76 million |
| CAGR 2026–2032 | 5.9% |
| Peak Annual Growth | 8.4% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Gear Type, 2025 | Spur Gears (52% share) |
| Leading Material Composition, 2025 | Case-Hardened Steel (39% share) |
| Leading Application Sector, 2025 | Light-Duty Vehicles (35% share) |
| Leading End User, 2025 | Automotive OEMs (42% share) |
| Fastest-Growing Gear Type | Helical Gears (7.8% CAGR) |
| Fastest-Growing Material Composition | Alloy Steel (7.8% CAGR) |
| Fastest-Growing Application Sector | Passenger Cars (7.4% CAGR) |
| Fastest-Growing End User | Gear Makers (8.4% CAGR) |
| Growing Sector | Automotive |
| Key End Users | Automotive OEMs, Gear Makers, Gearbox Suppliers, Utility Vehicle Makers |
China Transmission Gear Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
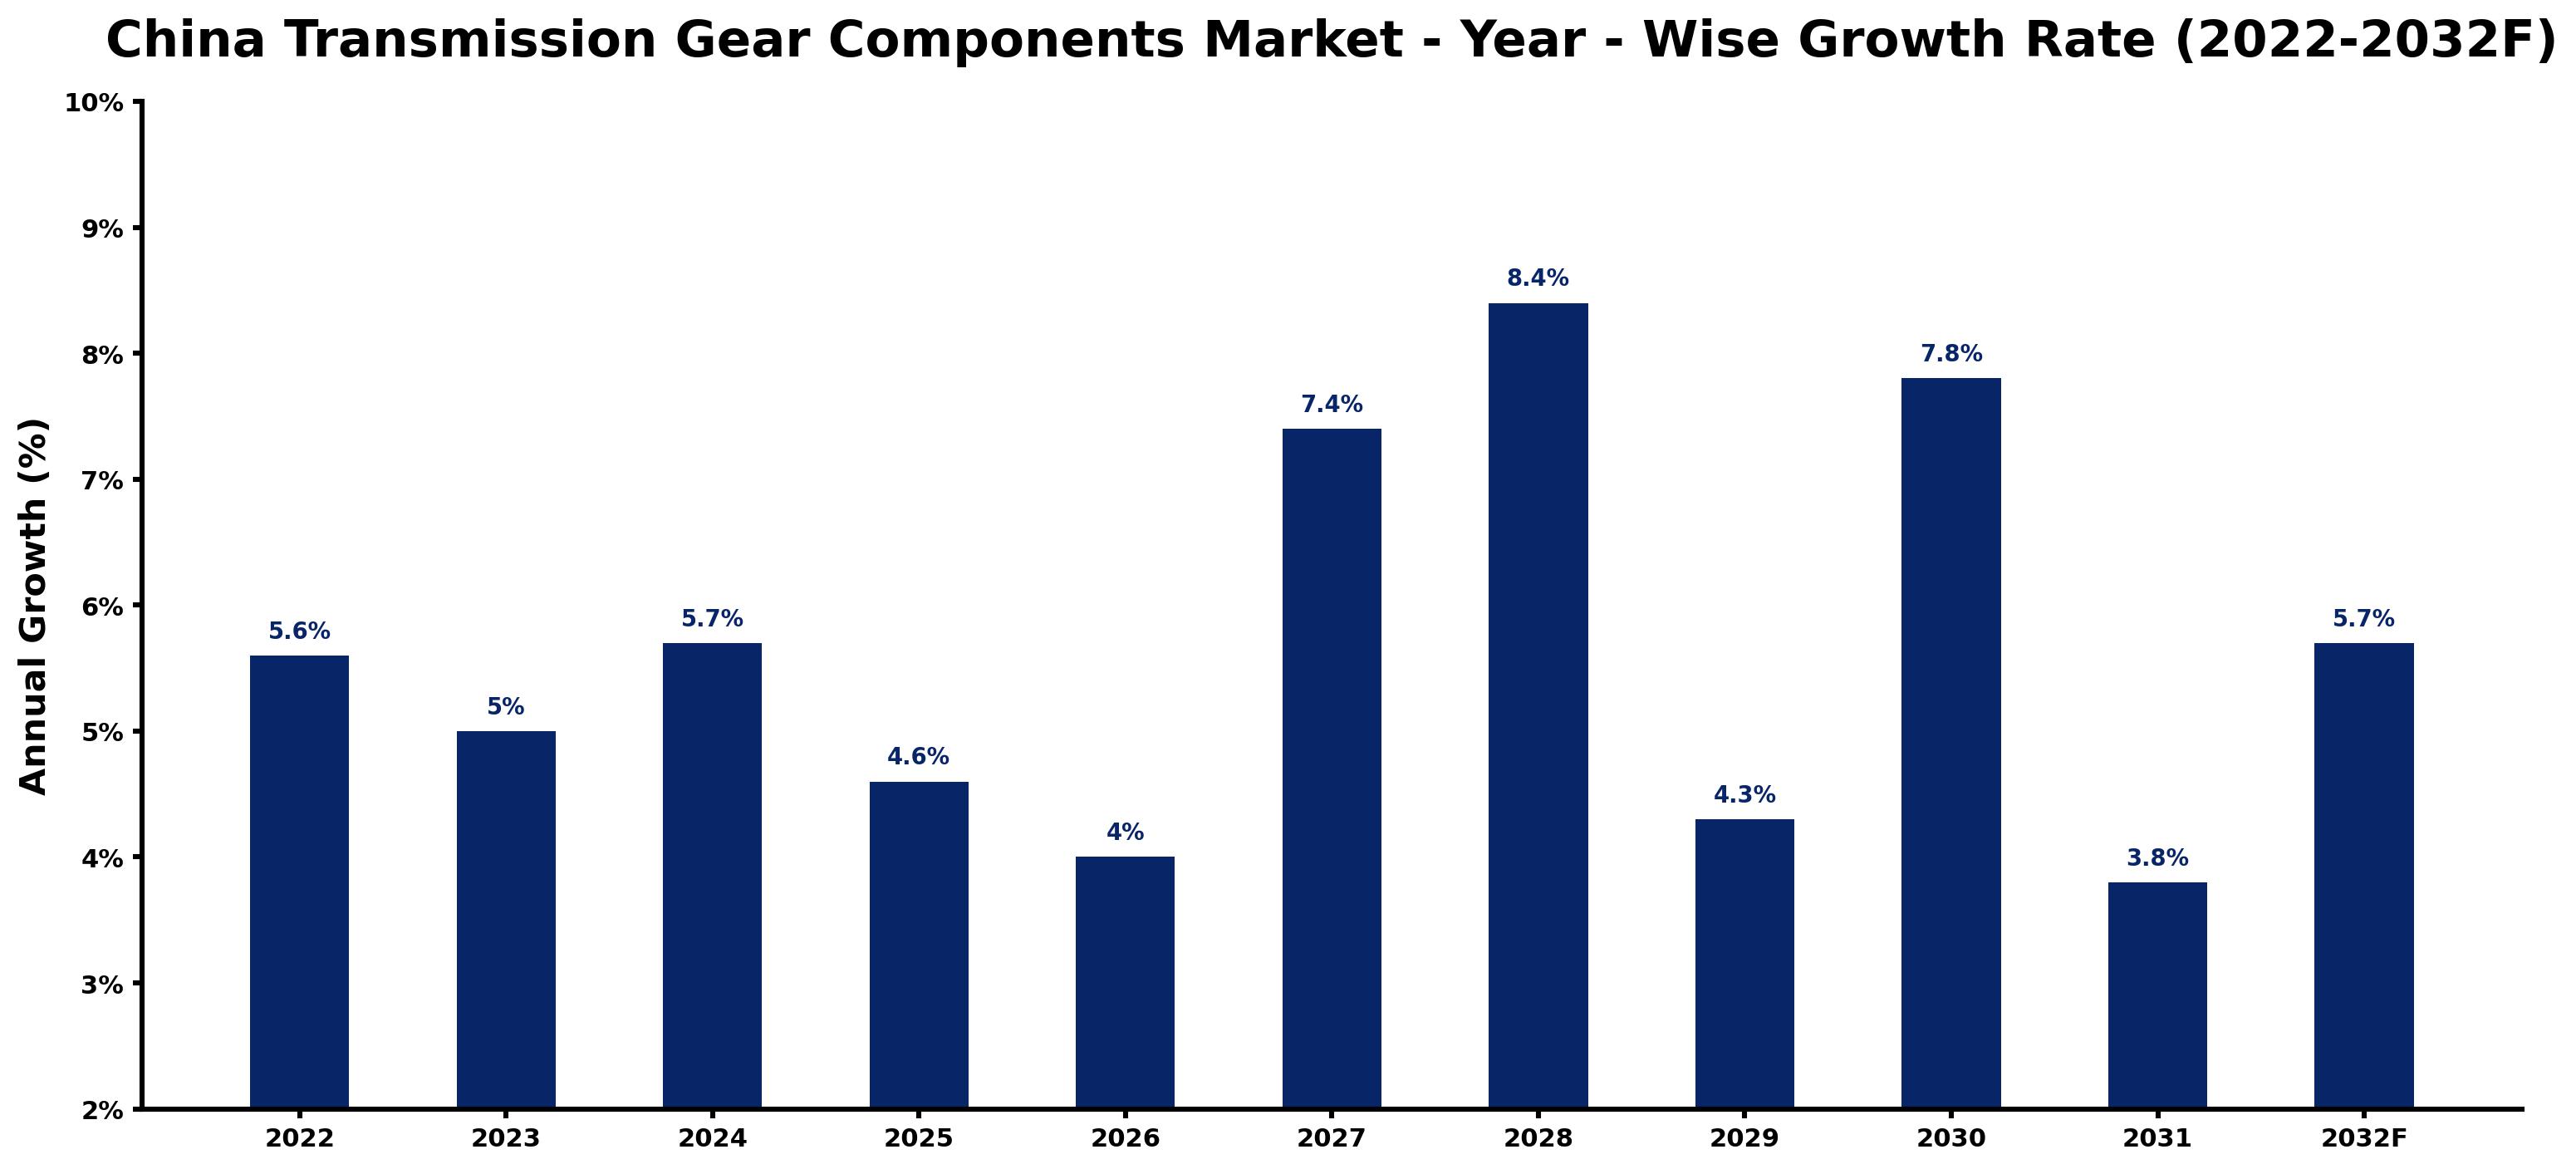
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.6 | The market experienced steady growth due to ongoing vehicle production and sales. |
| 2023 | 5.0 | Growth slowed as manufacturers adjusted to supply chain challenges and market conditions. |
| 2024 | 5.7 | Demand increased with a rise in passenger car production and consumer interest. |
| 2025 | 4.6 | Growth slowed again as market saturation began to affect new orders. |
| 2026 | 4.0 | A further slowdown occurred as manufacturers faced rising material costs and competition. |
| 2027 | 7.4 | Demand surged as automotive manufacturers ramped up production in response to market recovery. |
| 2028 | 8.4 | The market peaked as electric vehicle production gained momentum and investment increased. |
| 2029 | 4.3 | Growth slowed as market dynamics shifted towards electric vehicles and new technologies. |
| 2030 | 7.8 | Demand rebounded with a focus on innovation and new energy vehicles. |
| 2031 | 3.8 | Growth slowed again as market adjustments took place amid evolving consumer preferences. |
| 2032 | 5.7 | Demand increased as manufacturers adapted to new standards and technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Transmission Gear Components Market Synopsis
Transmission Gear Components in China encompass mechanical parts essential for power transmission and speed control in vehicles. These components are produced through forging, machining, and heat treatment processes. The China Transmission Gear Components Market is expanding due to rising vehicle production and sales, particularly in the automotive sector. The automotive industry contributes approximately 10% to China's GDP, supported by over 1,000 automotive component manufacturers. With the government's focus on electric vehicle development, demand for innovative gear solutions is expected to grow significantly.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising vehicle production and sales drive demand for transmission gear components. | Driver | High | Light-Duty Vehicles |
| Increasing focus on electric vehicle production fosters demand for advanced gear components. | Driver | High | Passenger Cars |
| The automotive aftermarket in China is valued at over $200 billion, presenting significant investment opportunities. | Opportunity | High | Automotive OEMs |
| Shandong province, a hub for automotive manufacturing, is experiencing rapid growth in gear component demand. | Opportunity | High | Gear Makers |
| Rising material costs may limit profit margins for manufacturers of transmission gear components. | Restraint | High | Case-Hardened Steel |
| Competition from international manufacturers may constrain the growth of local producers. | Restraint | Medium | Alloy Steel |
| Supply chain disruptions can delay production schedules and affect delivery timelines. | Challenge | High | Gearbox Suppliers |
| Technological advancements require continuous investment, which can strain smaller manufacturers. | Challenge | Medium | Utility Vehicle Makers |
Evaluation of Drivers in China Transmission Gear Components Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising vehicle production increases the demand for transmission gear components. | Light-Duty Vehicles | China produced 25 million passenger cars in 2022, leading to higher demand for gears. |
| The shift towards electric vehicles necessitates advanced gear technologies. | Spur Gears | The New Energy Vehicle Industry Development Plan, launched in 2023, promotes electric vehicle production. |
| The automotive aftermarket's growth fuels demand for replacement gear components. | Spur Gears | The automotive aftermarket in China is valued at over $200 billion, creating opportunities for suppliers. |
| Investment in automotive manufacturing facilities expands production capacity. | Spur Gears | Shandong province is a hub for automotive manufacturing, attracting significant investments in production. |
| Technological advancements in gear design improve performance and efficiency. | Gearbox Suppliers | ISO 9001 is a common quality standard among gear manufacturers in China, ensuring product reliability. |
The Transmission Gear Components market in China is expanding as rising vehicle production, increased focus on electric vehicles, and growth in the automotive aftermarket drive demand. In 2022, China produced 25 million passenger cars, creating a strong need for transmission components. The New Energy Vehicle Industry Development Plan promotes electric vehicle production, further boosting demand for advanced gear solutions. The automotive aftermarket, valued at over $200 billion, also contributes to the market's growth. Investments in Shandong province, a manufacturing hub, are enhancing production capacity and efficiency to meet the rising needs of domestic manufacturers.
Evaluation of Restraints in China Transmission Gear Components Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Rising material costs may limit profit margins for manufacturers of transmission gear components. | Case-Hardened Steel | Material costs have increased by 20%, affecting overall production expenses. |
| Competition from international manufacturers may constrain the growth of local producers. | Alloy Steel | Local manufacturers face challenges in competing with established international brands that dominate the market. |
| Supply chain disruptions can delay production schedules and affect delivery timelines. | Gearbox Suppliers | Recent global supply chain issues have impacted timely delivery of essential components for manufacturers. |
| Technological advancements require continuous investment, which can strain smaller manufacturers. | Utility Vehicle Makers | Smaller manufacturers may struggle to keep up with rapid technological changes and investment requirements. |
| Market saturation can limit growth opportunities for existing manufacturers. | Light-Duty Vehicles | An oversupply of certain vehicle types has led to reduced demand for new components, impacting production. |
China Transmission Gear Components Market Challenges
China's transmission gear components market faces several challenges, beginning with outdated manufacturing technology. Many producers depend on traditional processes, which can increase production costs by up to 15%, affecting pricing strategies for buyers. Buyers also encounter issues with fluctuating raw material prices, as steel costs surged by 20% last year, prompting budget adjustments and potential project delays. Regulatory compliance complicates operations, as manufacturers must adhere to standards set by the Ministry of Industry and Information Technology, which can lead to delays in product launches. Skills shortages in advanced manufacturing techniques further limit production capabilities, leaving suppliers struggling to meet the automotive sector's growing demand.
Trends in the China Transmission Gear Components Market
The trends below show where the China Transmission Gear Components Market is heading.
- Shift Towards Electric Vehicle Components: In 2023, the government introduced the "New Energy Vehicle Industry Development Plan" to promote electric vehicles, which is anticipated to significantly boost demand for specialised gear components.
- Growth in Automotive Aftermarket: The automotive aftermarket in China is valued at over $200 billion, highlighting a growing need for replacement parts and components. This trend offers opportunities for manufacturers to broaden their product offerings in urban areas.
- Increased Focus on Quality Standards: ISO 9001 certification is gaining importance among gear manufacturers to enhance product quality and reliability. This trend demonstrates the industry's commitment to meeting international standards, with over 70% of manufacturers adopting it.
- Technological Advancements in Gear Design: Recent innovations in gear design are enhancing performance and efficiency across various applications. Manufacturers are investing heavily in research and development to maintain competitiveness in the evolving market.
Investment Opportunities in the China Transmission Gear Components Market
Several openings in the China Transmission Gear Components Market merit attention from investors.
- Growing Demand for Electric Vehicle Components: With the government's focus on electric vehicles, the market is projected to see a substantial increase in demand for specialized gear components. This presents an opportunity for suppliers to innovate and meet new standards.
- Expansion of Automotive Manufacturing in Shandong: Shandong province is experiencing rapid growth in automotive manufacturing, with investments exceeding $1 billion. This creates opportunities for suppliers of transmission gear components to establish local partnerships.
- Investment in Advanced Manufacturing Technologies: Investment in advanced manufacturing technologies can improve production efficiency and product quality. This is particularly relevant for automotive OEMs looking to enhance their supply chains and reduce costs.
- Rising Aftermarket Demand for Replacement Parts: The automotive aftermarket's value of over $200 billion presents significant opportunities for manufacturers to supply replacement transmission gear components, especially in urban areas where vehicle ownership is increasing.
Government Initiatives in the China Transmission Gear Components Market
In 2023, the "New Energy Vehicle Industry Development Plan" was launched to promote electric vehicle production and innovation in the automotive sector. This initiative builds on the "Automotive Industry Development Policy" from 2020, which supports innovation and competitiveness in the sector, ensuring that manufacturers adapt to new technologies and standards. The new plan aims to increase the production of electric vehicles by 30% by 2025, boosting the demand for transmission gear components.
The Ministry of Industry and Information Technology oversees the implementation of automotive standards and policies. This agency ensures compliance with regulations and provides funding for projects aimed at improving the capabilities of the automotive sector, with a budget of $500 million allocated for 2023. This funding enables manufacturers to upgrade their facilities and improve production processes, directly benefiting the transmission gear components market.
Future Insight of the China Transmission Gear Components Market
The transmission gear components market in China is expected to evolve by 2032, driven by several key factors. The government's "New Energy Vehicle Industry Development Plan" will increase demand for advanced components, while the automotive aftermarket is projected to surpass $300 billion by 2025, creating new opportunities for suppliers. Improved manufacturing technology will enhance production efficiency, allowing producers to better meet the rising needs of domestic manufacturers. The push for stricter quality standards will also elevate product quality, ultimately benefiting buyers in the long run.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Gear Type – Spur Gears Dominated, Helical Gears Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, the largest gear type category in 2025 was Spur Gears, with a 52% share of total revenue. Spur gears hold the largest market share because they are widely used in various gear systems, ensuring effective power transmission. Their common application in light-duty vehicles, a major segment of the automotive market, solidifies their leading position in the China Transmission Gear Components Market. The quickest growth will come from Helical Gears, forecast to expand at a CAGR of 7.8% between 2026 and 2032. Helical gears are growing quickly as they are preferred for their smooth and quiet operation in vehicles. The increase in passenger car production, which often features helical gears, significantly contributes to this segment's rapid growth. Suppliers should focus on helical gear production to meet the rising demand from the automotive sector.
By Material Composition – Case-Hardened Steel Dominated, Alloy Steel Expected to Grow Fastest
Case-Hardened Steel held a 39% share of the China Transmission Gear Components Market by material composition in 2025. Case-hardened steel dominates the market share due to its durability and strength, essential for high-stress applications in automotive gear components. Its reliability in critical automotive systems makes it the top choice for manufacturers, reinforcing its leading status. Over 2026–2032, Alloy Steel is expected to post the fastest growth, at a CAGR of 7.8%. Alloy steel is experiencing the fastest growth because of its enhanced mechanical properties, making it increasingly sought after for gear components. The shift towards more efficient and robust materials in vehicle manufacturing is a key factor in this rapid expansion. Manufacturers should enhance their alloy steel production capabilities to capitalise on the growing demand for advanced gear materials.
By Application Sector – Light-Duty Vehicles Dominated, Passenger Cars Expected to Grow Fastest
Light-Duty Vehicles took a 35% share of application sector in 2025, more than any other category. Light-duty vehicles hold the largest market share as they create substantial demand for transmission components, particularly from passenger and utility vehicles. The production of 25 million passenger cars in 2022 highlights the significance of this segment in the China Transmission Gear Components Market. Passenger Cars are set to record the highest CAGR in this split, 7.4% over 2026–2032. Passenger cars are the fastest-growing application sector, influenced by the rising consumer preference for personal vehicles. The ongoing growth of the automotive market in China is anticipated to further accelerate this sector's expansion. Suppliers must adjust their strategies to meet the increasing demand for transmission components specifically in the passenger car segment.
By End User – Automotive OEMs Dominated, Gear Makers Expected to Grow Fastest
With a 42% revenue share in 2025, Automotive OEMs was the largest end user category. Automotive OEMs command the largest market share as they are the primary users of transmission gear components in vehicle manufacturing. Their extensive production capabilities and established supply chains solidify their leading position in the market. Gear Makers are projected to grow fastest, at a CAGR of 8.4% during 2026–2032. Gear makers are experiencing the fastest growth due to their role in supplying gears for various applications, including the rapidly expanding electric vehicle market. The push for innovation in automotive design is driving demand for specialised gear components. Suppliers should strengthen partnerships with gear makers to tap into the growing opportunities within the automotive sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Transmission Gear Components Market Outlook
- Market Size of China Transmission Gear Components Market, 2025
- Forecast of China Transmission Gear Components Market, 2032
- Historical Data and Forecast of China Transmission Gear Components Revenues & Volume for the Period 2022 - 2032F
- China Transmission Gear Components Market Trend Evolution
- China Transmission Gear Components Market Drivers and Challenges
- China Transmission Gear Components Price Trends
- China Transmission Gear Components Porter's Five Forces
- China Transmission Gear Components Industry Life Cycle
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Gear Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Spur Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Helical Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Planetary Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Bevel Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Material Composition for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Case-Hardened Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Alloy Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Powder Metallurgy for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Forged Iron for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Application Sector for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Light-Duty Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Heavy-Duty Trucks for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Off-Road Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Automotive OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Gear Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Gearbox Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Gear Components Market Revenues & Volume By Utility Vehicle Makers for the Period 2022 - 2032F
- China Transmission Gear Components Import Export Trade Statistics
- Market Opportunity Assessment By Gear Type
- Market Opportunity Assessment By Material Composition
- Market Opportunity Assessment By Application Sector
- Market Opportunity Assessment By End User
- China Transmission Gear Components Top Companies Market Share
- China Transmission Gear Components Competitive Benchmarking By Technical and Operational Parameters
- China Transmission Gear Components Company Profiles
- China Transmission Gear Components Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Gear Type
- Spur Gears
- Helical Gears
- Planetary Gears
- Bevel Gears
By Material Composition
- Case-Hardened Steel
- Alloy Steel
- Powder Metallurgy
- Forged Iron
By Application Sector
- Light-Duty Vehicles
- Passenger Cars
- Heavy-Duty Trucks
- Off-Road Vehicles
By End User
- Automotive OEMs
- Gear Makers
- Gearbox Suppliers
- Utility Vehicle Makers































