China Tungsten Compounds Market Size & Growth Rate
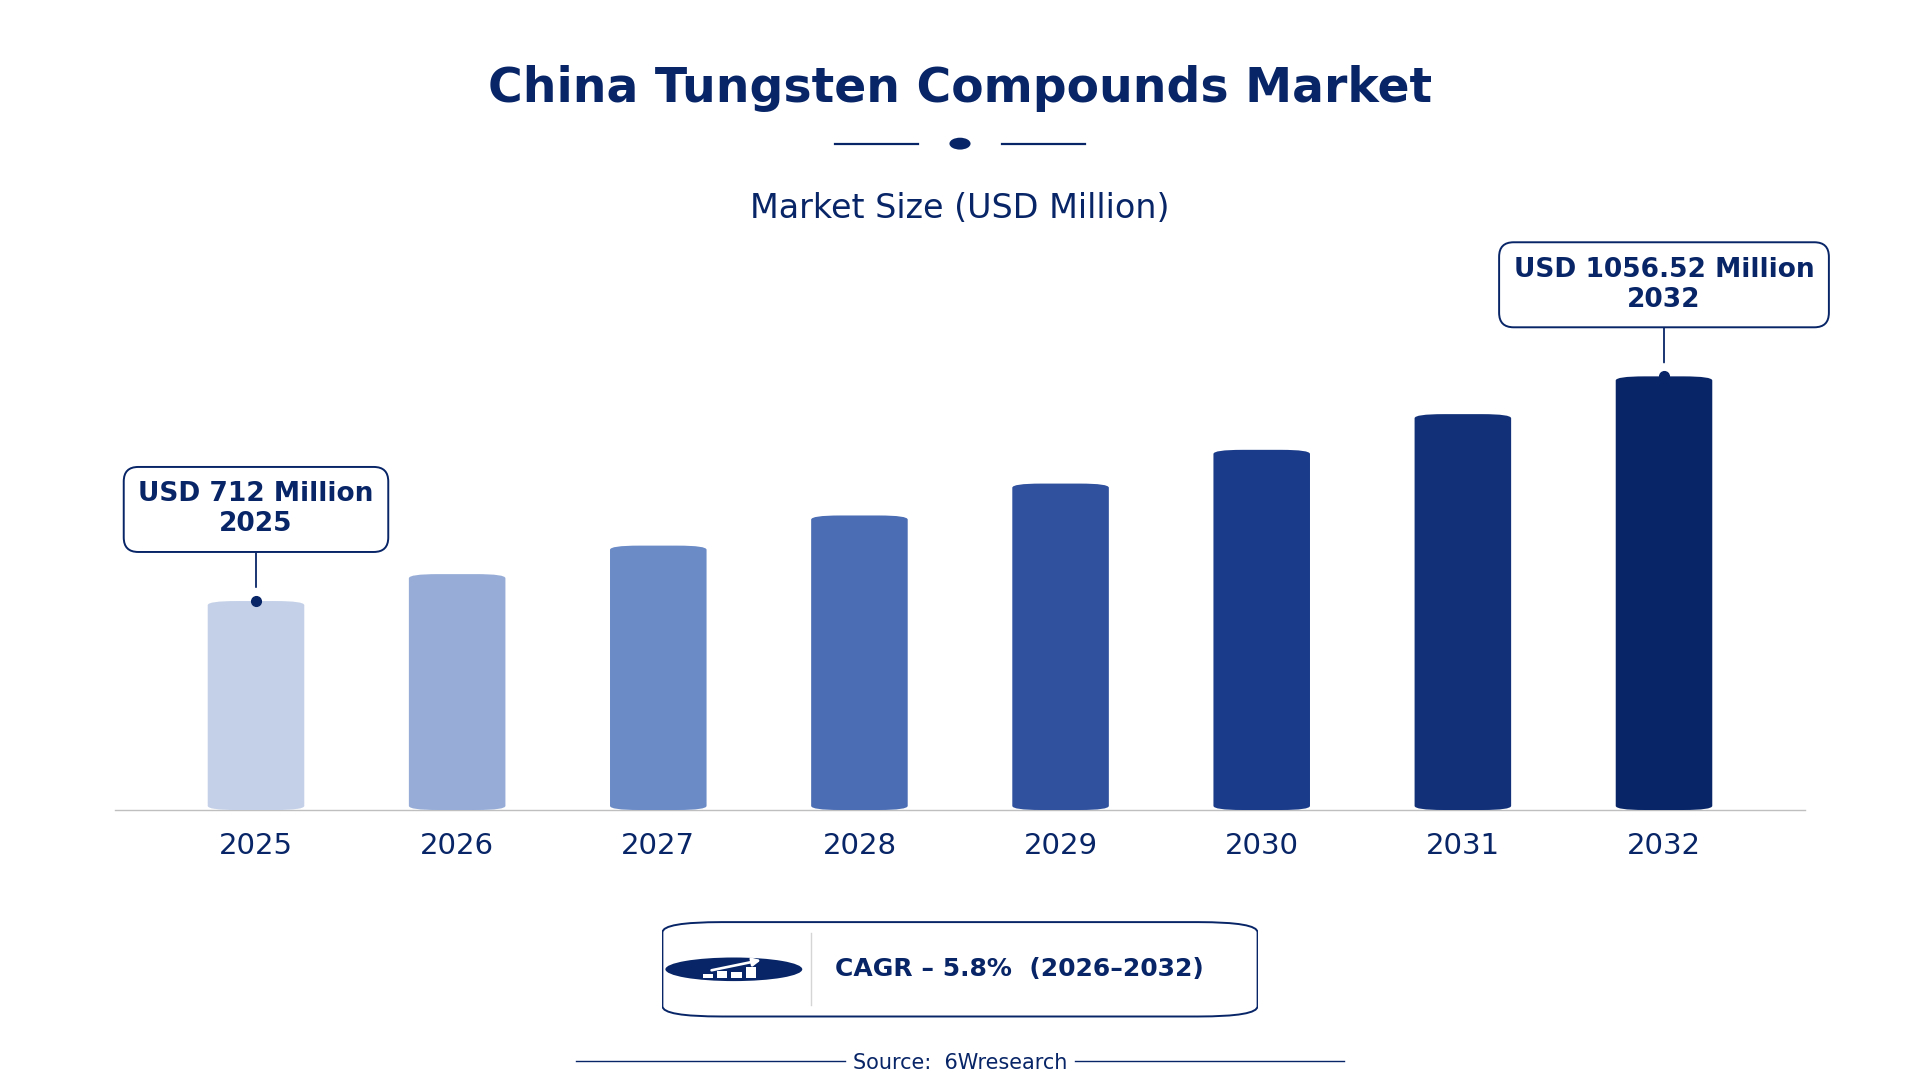
According to 6Wresearch internal database and industry insights, the China Tungsten Compounds Market was valued at USD 712.0 million in 2025 and is projected to reach USD 1,056.52 million by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China Tungsten Compounds Market Highlights
| Report Metric | Details |
| Report Name | China Tungsten Compounds Market |
| Market Size 2025 | USD 712.0 million |
| Market Size 2032 | USD 1,056.52 million |
| Absolute Growth 2025–2032 | USD 344.52 million |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 7.6% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Compound Type, 2025 | Tungsten Oxide (44% share) |
| Leading Chemical Application, 2025 | Pigments/Catalysts (51% share) |
| Leading Industry Segment, 2025 | Chemical Processing (42% share) |
| Leading End User, 2025 | Catalyst Manufacturers (38% share) |
| Fastest-Growing Compound Type | Tungsten Disulfide (7.3% CAGR) |
| Fastest-Growing Chemical Application | Lubricants (7.9% CAGR) |
| Fastest-Growing Industry Segment | Metal Refining (7.8% CAGR) |
| Fastest-Growing End User | Lubricant Suppliers (7.2% CAGR) |
| Growing Sector | Lubricants |
| Key End Users | Pigments/Catalysts, Lubricants, Anti-Corrosion, Intermediate Compound |
China Tungsten Compounds Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
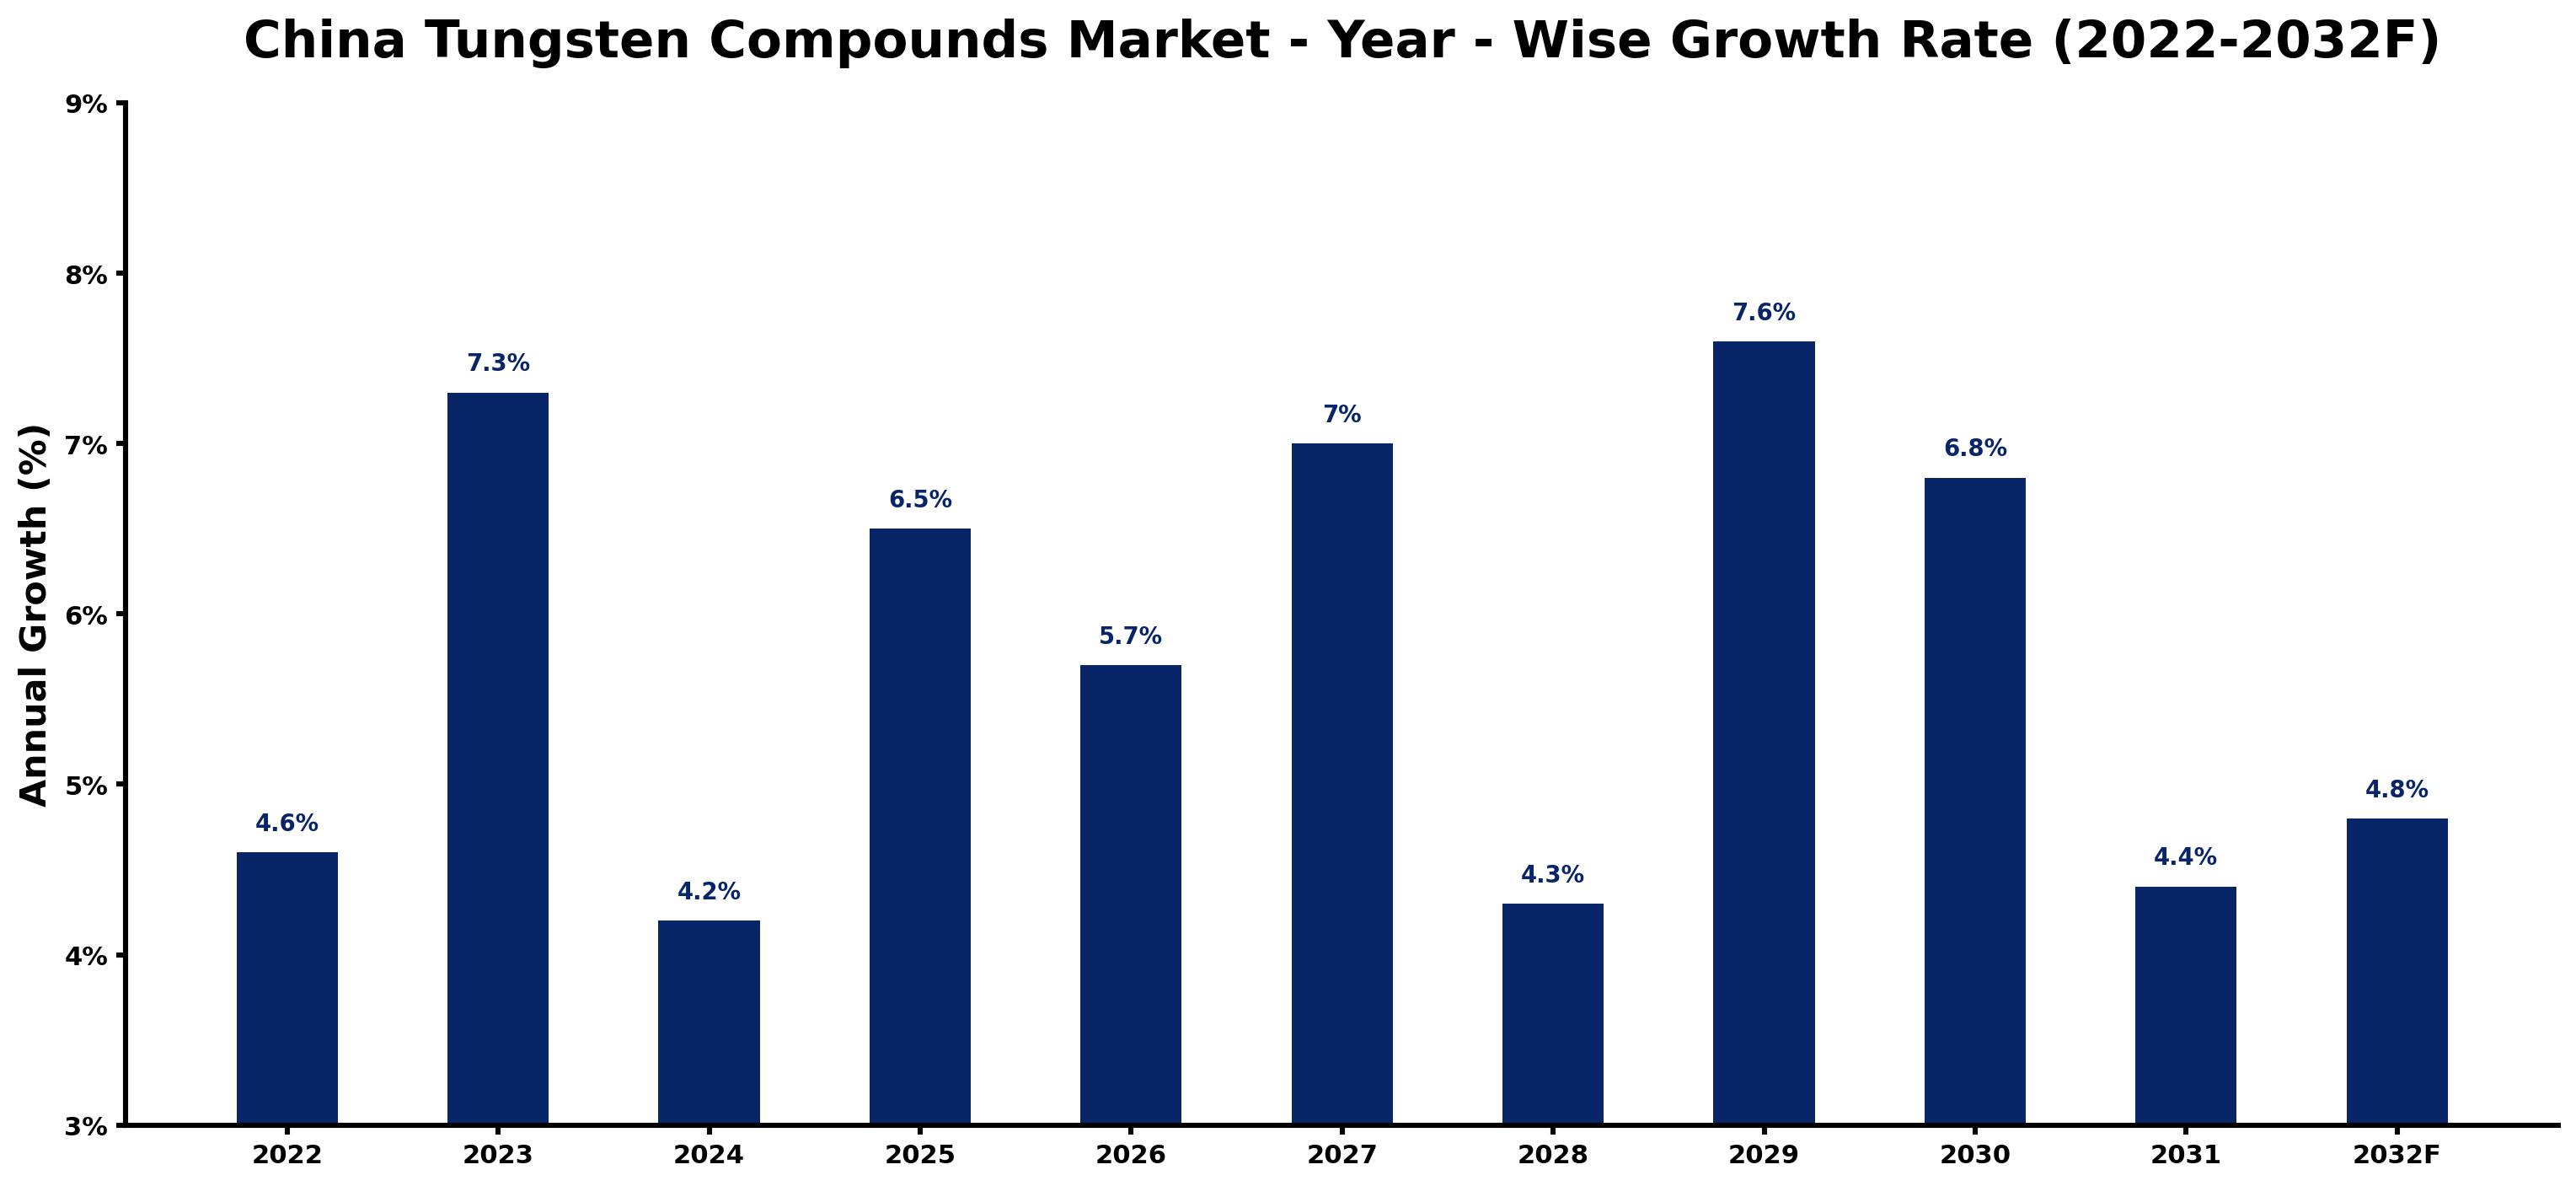
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.6 | The market experienced steady growth due to ongoing industrial demand for tungsten compounds from the chemical processing sector. |
| 2023 | 7.3 | Growth accelerated as production in Yunnan province increased, boosting supply for various applications. |
| 2024 | 4.2 | A slowdown occurred as demand stabilised following the previous year's rapid expansion in the lubricant market. |
| 2025 | 6.5 | Demand rose again, driven by recovery in the chemical processing sector and increased investments in production. |
| 2026 | 5.7 | Growth slowed as regulatory changes began impacting mining operations and production timelines. |
| 2027 | 7.0 | The market rebounded with increased demand from lubricant suppliers and aerospace components in Guangdong province. |
| 2028 | 4.3 | A slowdown was noted as the market adjusted to new environmental regulations affecting production. |
| 2029 | 7.6 | Growth peaked as investments in tungsten recycling and processing facilities surged, enhancing supply capabilities. |
| 2030 | 6.8 | A slowdown followed as the market stabilised after reaching peak demand levels in the aerospace sector. |
| 2031 | 4.4 | Growth continued to slow as market saturation began to take effect in key sectors like chemical processing. |
| 2032 | 4.8 | Demand is expected to rise again as new applications for tungsten compounds emerge in various industries. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Tungsten Compounds Market Synopsis
The China Tungsten Compounds Market includes a range of chemical substances derived from tungsten, mainly utilised in industrial applications such as catalysts and lubricants. These compounds result from chemical reactions involving tungsten ore, with strong demand from sectors like chemical manufacturing and metal refining. Growth in the market stems from increasing investments in tungsten processing facilities, particularly in Sichuan province, where the installed base in chemical processing exceeds 50,000 tons annually. By 2025, sodium tungstate demand in chemical applications is expected to reach 10,000 tons, reflecting robust industrial activity.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand from chemical processing industries | Driver | High | Chemical Processing |
| Growing applications in aerospace components | Driver | High | Aerospace Components |
| Investment in tungsten processing facilities in Sichuan | Opportunity | High | Tungsten Disulfide |
| Emerging demand for sustainable tungsten recycling | Opportunity | High | Tungsten Oxide |
| Stricter regulations on tungsten mining practices | Restraint | High | Tungsten Oxide |
| Environmental concerns affecting production capacity | Restraint | Medium | Tungsten Oxide |
| Challenges in meeting new environmental standards | Challenge | High | Chemical Processing |
| High costs associated with sustainable mining practices | Challenge | Medium | Tungsten Oxide |
Evaluation of Drivers in China Tungsten Compounds Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of tungsten oxide for pigments | Tungsten Oxide | China produced approximately 80% of the world's tungsten in 2022, driving demand for pigments and catalysts in various applications. |
| Rising use of tungsten disulfide in aerospace applications | Tungsten Disulfide | The aerospace sector in Guangdong province is expanding, increasing the need for high-performance lubricants in aircraft manufacturing. |
| Growing investment in chemical processing facilities | Chemical Processing | The installed base of tungsten compounds in chemical processing exceeds 50,000 tons annually, indicating strong demand from manufacturers. |
| Demand for ammonium paratungstate in tool manufacturing | Ammonium Paratungstate | Ammonium paratungstate is crucial for producing tungsten carbide tools, which are in high demand across various industries. |
| Expansion of the lubricant market due to industrial growth | Lubricants | The lubricant market is expanding as industries seek efficient solutions to reduce friction in machinery, driving demand for tungsten disulfide. |
Market growth for Tungsten Compounds in China is underpinned by rising applications in chemical processing, aerospace components, and lubricants. The domestic production of tungsten supports demand for tungsten oxide used in pigments and catalysts. Investment in chemical processing facilities reached 500 million yuan in Sichuan province in 2022, further supporting growth. The aerospace sector in Guangdong province is expanding, increasing the need for high-performance lubricants such as tungsten disulfide. The demand for ammonium paratungstate is rising due to its critical role in producing tungsten carbide tools, reflecting strong industrial activity across sectors.
Evaluation of Restraints in China Tungsten Compounds Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Stricter regulations on tungsten mining practices | Tungsten Oxide | The Ministry of Ecology and Environment is enforcing stricter regulations, impacting production timelines and increasing operational costs. |
| Environmental concerns affecting production capacity | Tungsten Oxide | Increased scrutiny on mining practices has led to delays in production and higher compliance costs for suppliers. |
| Challenges in meeting new environmental standards | Chemical Processing | New regulations require investment in cleaner technologies, impacting operational budgets for manufacturers in the sector. |
| High costs associated with sustainable mining practices | Tungsten Oxide | Implementing sustainable practices can increase operational costs, affecting pricing strategies for suppliers in the market. |
| Market saturation in key sectors | Tungsten Oxide | As demand stabilises, competition increases, leading to price pressures in the tungsten compounds market. |
China Tungsten Compounds Market Challenges
Buyers in the China tungsten compounds market face rising competition, as domestic production accounted for approximately 80% of global output in 2022, which pressures pricing for end-users. Suppliers encounter supply chain disruptions due to stricter regulations from the Ministry of Ecology and Environment, which aim to reduce environmental impact and can delay shipments by up to three weeks. Compliance with National Standard GB/T 16466-2008 complicates operations for producers, as meeting quality requirements incurs additional costs, reducing profit margins. Buyers also struggle with fluctuating demand for sodium tungstate, projected to reach 10,000 tons by 2025, complicating inventory management and forecasting.
Trends in the China Tungsten Compounds Market
Four trends stand out in the China Tungsten Compounds Market.
- Shift towards Sustainable Tungsten Recycling: In 2023, the Ministry of Industry and Information Technology initiated a programme to enhance tungsten recycling efficiency, aiming to reduce waste and promote sustainable practices with an investment of 200 million yuan.
- Emergence of New Applications for Tungsten Compounds: The demand for sodium tungstate in chemical applications is anticipated to reach 10,000 tons by 2025, indicating a growing interest in its use across various industrial processes.
- Expansion of Aerospace Applications for Tungsten Disulfide: Tungsten disulfide is increasingly utilised in aerospace components produced in Guangdong province, reflecting a trend towards high-performance materials in the sector.
- Growth in Lubricant Applications: The lubricant market is projected to grow, with a CAGR of 7.9% for lubricants in the tungsten compounds sector, driven by industrial demand for efficient solutions.
Investment Opportunities in the China Tungsten Compounds Market
The following opportunities in the China Tungsten Compounds Market pair current demand with a clear way in.
- Investment in Sichuan Processing Facilities: Investment in tungsten processing facilities in Sichuan province reached 500 million yuan in 2022, presenting opportunities for suppliers to enter the market through partnerships or joint ventures.
- Emerging Demand for Sustainable Practices: The shift towards sustainable tungsten recycling creates opportunities for companies to develop solutions, particularly for chemical suppliers aiming to meet new environmental standards.
- Expansion of Aerospace Component Manufacturing: The aerospace sector in Guangdong province is expanding, creating demand for high-performance tungsten disulfide lubricants, providing opportunities for suppliers to cater to this growing market.
- Growth in Chemical Processing Applications: The anticipated demand for sodium tungstate in chemical applications, reaching 10,000 tons by 2025, offers opportunities for suppliers to invest in production capacity.
Government Initiatives in the China Tungsten Compounds Market
The 'Tungsten Industry Development Plan' launched by the National Development and Reform Commission in 2021 aims to promote sustainable mining practices and increase recycling rates. This plan is designed to modernise the industry and ensure long-term viability, benefiting producers by creating a more stable regulatory environment. Additionally, the State Administration for Market Regulation updated the 'Product Quality Law' in 2020 to enforce stricter standards on tungsten products, ensuring higher quality and safety for buyers.
The 'Green Manufacturing Program' initiated by the Ministry of Industry and Information Technology in 2022 aims to reduce emissions in tungsten processing industries. This programme supports manufacturers in adopting cleaner technologies and practices, ultimately benefiting buyers by ensuring environmentally friendly products. Furthermore, the Ministry of Science and Technology approved the 'Tungsten Resource Innovation Project' in 2023, with a budget of 200 million yuan, to support research in tungsten applications, facilitating innovation and improving product offerings for buyers.
Future Insight of the China Tungsten Compounds Market
The China tungsten compounds market is set to evolve significantly by 2032, driven by advancements in recycling technologies and stricter environmental regulations. The Ministry of Industry and Information Technology's new programme to improve tungsten recycling efficiency will likely increase material availability for producers. Investment in tungsten processing facilities in regions like Yunnan will further expand production capabilities. Growing applications in chemical manufacturing will prompt suppliers to innovate and diversify their product offerings, addressing the specific requirements of buyers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Compound Type – Tungsten Oxide Dominated, Tungsten Disulfide Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, with a 44% revenue share in 2025, Tungsten Oxide was the largest compound type category. Tungsten oxide holds the largest share due to its extensive use in producing pigments and catalysts, particularly in Jiangsu province, a hub for chemical manufacturing. The established market presence is further highlighted by the annual consumption of over 50,000 tons of tungsten compounds in the chemical processing sector. The quickest growth will come from Tungsten Disulfide, forecast to expand at a CAGR of 7.3% between 2026 and 2032. Tungsten disulfide is experiencing rapid growth as a lubricant, especially within aerospace applications in Guangdong province, where demand is increasing due to advancements in technology. This segment's growth trajectory will likely continue as investments in processing facilities expand. Suppliers should focus on enhancing production capabilities for tungsten disulfide to meet the rising demand in aerospace applications.
By Chemical Application – Pigments/Catalysts Dominated, Lubricants Expected to Grow Fastest
The largest chemical application category in 2025 was Pigments/Catalysts, with a 51% share of total revenue. Pigments and catalysts lead the market share as these compounds are essential in coatings and chemical reactions, driven by strong demand across various industries. The importance of maintaining quality standards, particularly under National Standard GB/T 16466-2008, reinforces this segment's dominance. Lubricants are set to record the highest CAGR in this split, 7.9% over 2026–2032. Lubricants are the fastest-growing application, propelled by their critical role in machinery to reduce friction, particularly in automotive and industrial sectors. The increasing emphasis on efficiency and performance in machinery is fuelling this growth. Buyers in the lubricant sector should seek reliable suppliers to ensure consistent quality and availability of tungsten disulfide.
By Industry Segment – Chemical Processing Dominated, Metal Refining Expected to Grow Fastest
Chemical Processing held a 42% share of the China Tungsten Compounds Market by industry segment in 2025. Chemical processing captures the largest market share as tungsten compounds are essential for producing a wide range of chemicals, reflecting strong domestic demand. The annual installed base of over 50,000 tons demonstrates the sector's heavy reliance on these compounds for its operations. Over 2026–2032, Metal Refining is expected to post the fastest growth, at a CAGR of 7.8%. Metal refining is the fastest-growing segment, primarily due to the critical role tungsten compounds play in refining tungsten ores, with notable output from Yunnan province. The increasing emphasis on sustainable practices in mining is also propelling this growth. Investors should seek opportunities in the metal refining segment to capitalise on the rising demand for tungsten compounds.
By End User – Catalyst Manufacturers Dominated, Lubricant Suppliers Expected to Grow Fastest
In 2025, Catalyst Manufacturers led the end user split with a 38% share. Catalyst manufacturers represent the largest share as they rely heavily on tungsten compounds for producing various catalysts that are vital in chemical processes. The strong demand in this sector is driven by the need for high-quality catalysts across multiple applications. Lubricant Suppliers are projected to grow fastest, at a CAGR of 7.2% during 2026–2032. Lubricant suppliers are the fastest-growing end user segment, driven by the increasing demand for high-performance lubricants in machinery applications. This growth is supported by technological advancements and enhanced production capacities in the sector. Suppliers should strengthen partnerships with lubricant suppliers to capitalise on the expanding market for tungsten disulfide.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Tungsten Compounds Market Outlook
- Market Size of China Tungsten Compounds Market, 2025
- Forecast of China Tungsten Compounds Market, 2032
- Historical Data and Forecast of China Tungsten Compounds Revenues & Volume for the Period 2022 - 2032F
- China Tungsten Compounds Market Trend Evolution
- China Tungsten Compounds Market Drivers and Challenges
- China Tungsten Compounds Price Trends
- China Tungsten Compounds Porter's Five Forces
- China Tungsten Compounds Industry Life Cycle
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Compound Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Tungsten Oxide for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Tungsten Disulfide for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Sodium Tungstate for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Ammonium Paratungstate for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Chemical Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Pigments/Catalysts for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Lubricants for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Anti-Corrosion for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Intermediate Compound for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Industry Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Chemical Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Aerospace Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Metal Plating for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Metal Refining for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Catalyst Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Lubricant Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Coating Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Tungsten Compounds Market Revenues & Volume By Chemical Suppliers for the Period 2022 - 2032F
- China Tungsten Compounds Import Export Trade Statistics
- Market Opportunity Assessment By Compound Type
- Market Opportunity Assessment By Chemical Application
- Market Opportunity Assessment By Industry Segment
- Market Opportunity Assessment By End User
- China Tungsten Compounds Top Companies Market Share
- China Tungsten Compounds Competitive Benchmarking By Technical and Operational Parameters
- China Tungsten Compounds Company Profiles
- China Tungsten Compounds Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Compound Type
- Tungsten Oxide
- Tungsten Disulfide
- Sodium Tungstate
- Ammonium Paratungstate
By Chemical Application
- Pigments/Catalysts
- Lubricants
- Anti-Corrosion
- Intermediate Compound
By Industry Segment
- Chemical Processing
- Aerospace Components
- Metal Plating
- Metal Refining
By End User
- Catalyst Manufacturers
- Lubricant Suppliers
- Coating Companies
- Chemical Suppliers































