China UNS AOG Response Market Size & Growth Rate
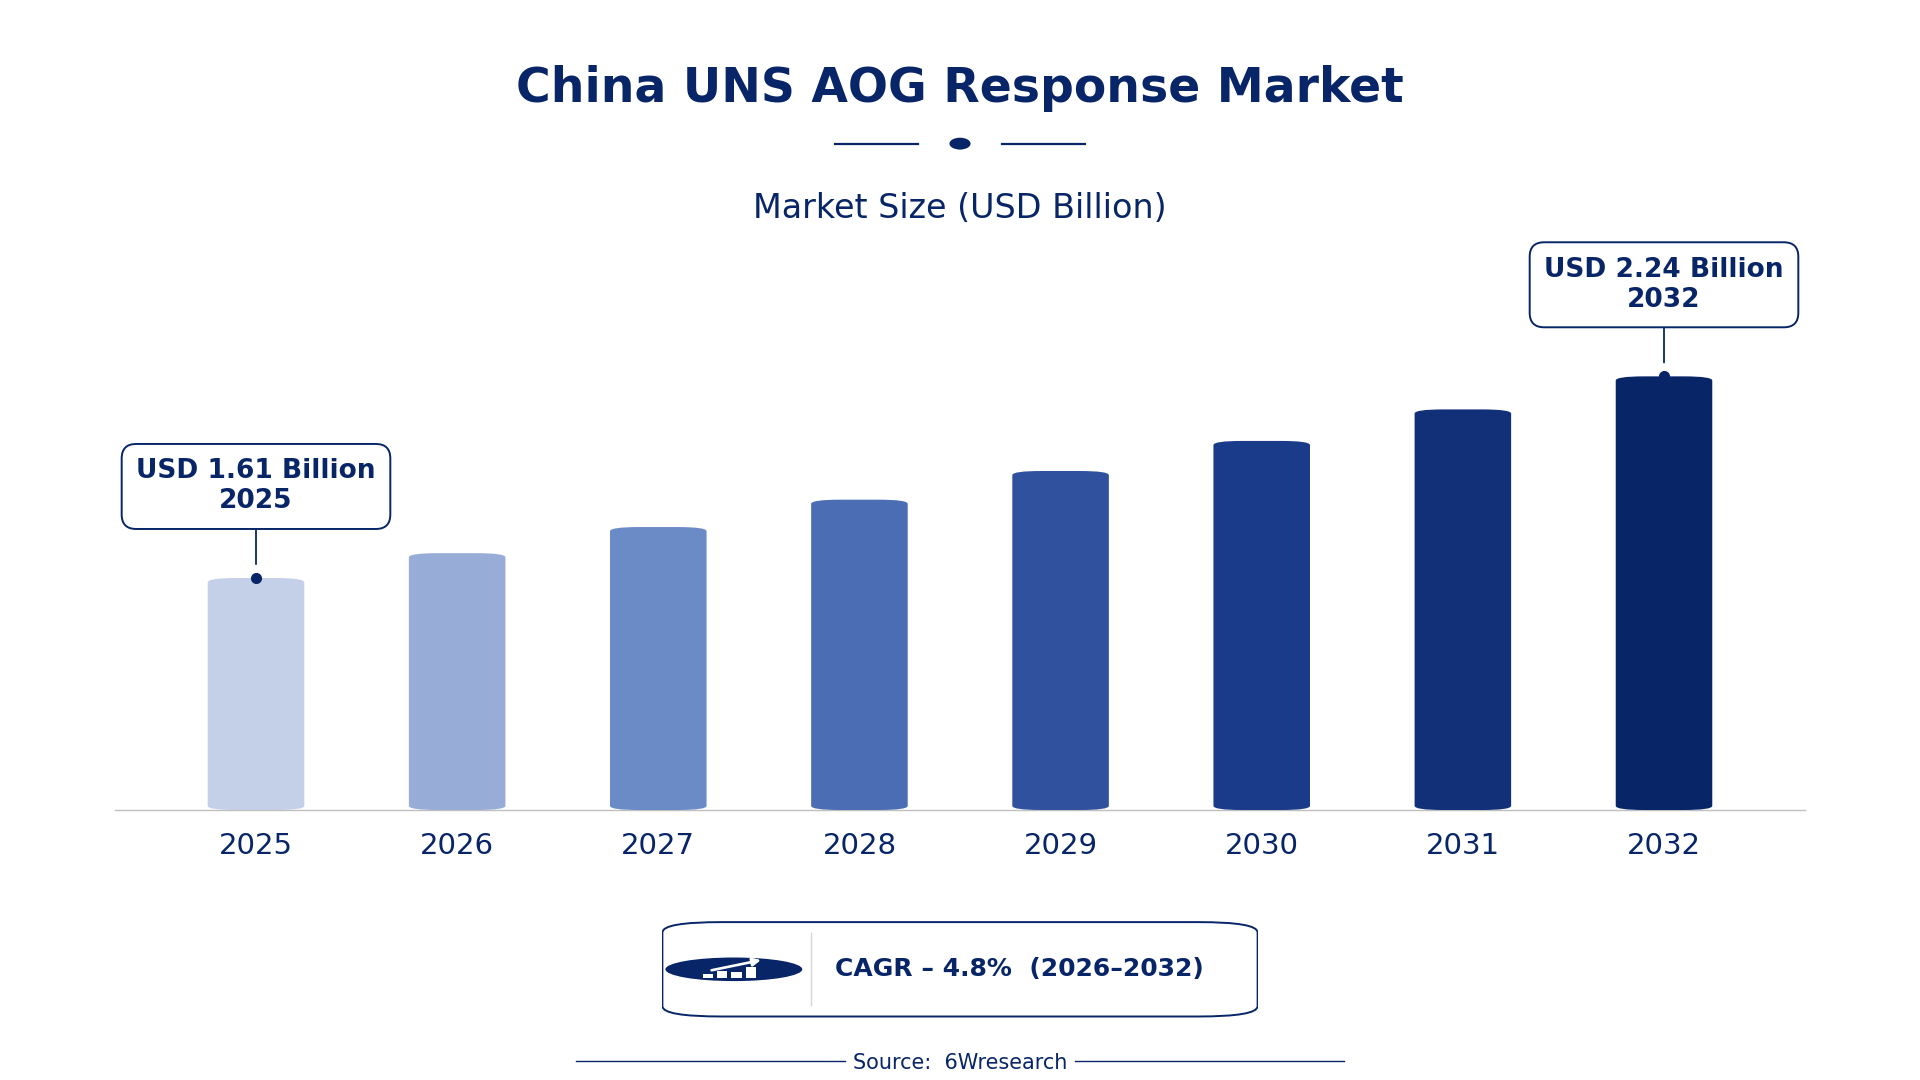
According to 6Wresearch internal database and industry insights, the China UNS AOG Response Market was valued at USD 1.61 billion in 2025 and is projected to reach USD 2.24 billion by 2032, growing at a CAGR of approximately 4.8% during 2026–2032.
China UNS AOG Response Market Highlights
| Report Metric | Details |
| Report Name | China UNS AOG Response Market |
| Market Size 2025 | USD 1.61 billion |
| Market Size 2032 | USD 2.24 billion |
| Absolute Growth 2025–2032 | USD 0.63 billion |
| CAGR 2026–2032 | 4.8% |
| Peak Annual Growth | 7.1% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Service Type, 2025 | Emergency Spares (51% share) |
| Leading Aircraft Component, 2025 | Engine (39% share) |
| Leading Response Time SLA, 2025 | <4 Hours (43% share) |
| Leading End User, 2025 | Airlines (47% share) |
| Fastest-Growing Service Type | Logistics Handling (6.3% CAGR) |
| Fastest-Growing Aircraft Component | Avionics (6.6% CAGR) |
| Fastest-Growing End User | MRO Providers (6.4% CAGR) |
| Growing Sector | MRO Providers |
| Key End Users | Airlines, MRO Providers, Aircraft Operators, OEMs |
China UNS AOG Response Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
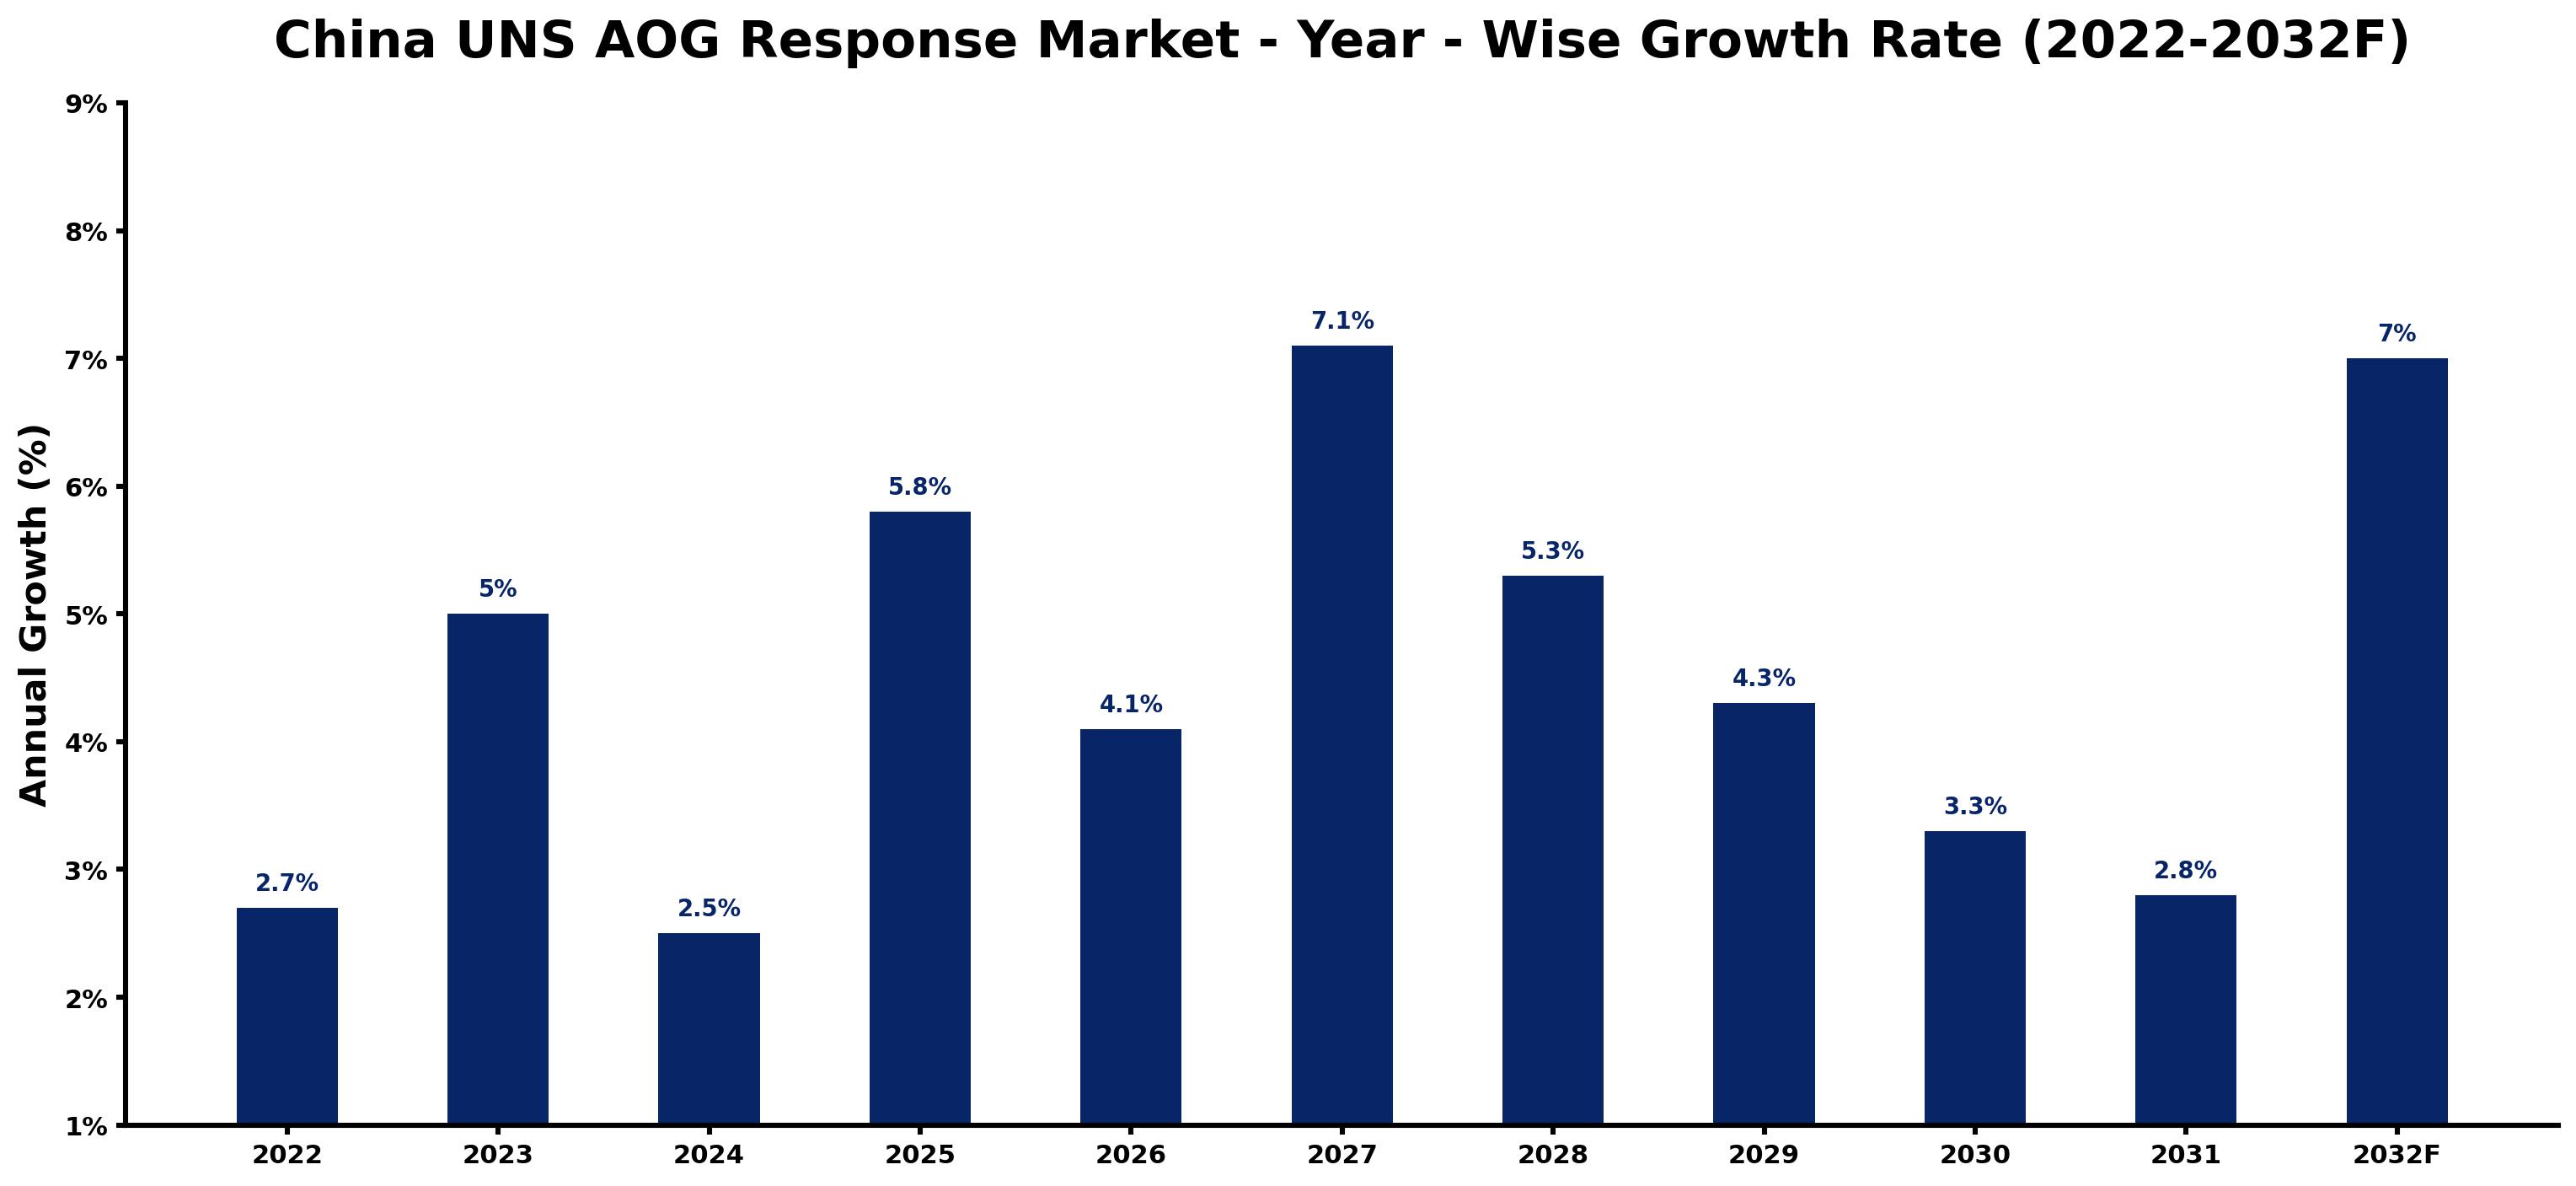
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.7 | The market experienced steady activity due to a growing aviation sector. |
| 2023 | 5.0 | Demand increased as airlines expanded operations and improved service capabilities through the 'National Civil Aviation Development Plan'. |
| 2024 | 2.5 | Growth slowed as airlines focused on cost management amid rising operational expenses. |
| 2025 | 5.8 | A surge in passenger numbers boosted demand for AOG services, with over 1 billion passengers projected by 2025. |
| 2026 | 4.1 | Growth is expected to decelerate as airlines adapt to increased service capacity demands following the updated 'Aviation Safety Law'. |
| 2027 | 7.1 | A peak in demand is projected as airlines seek rapid response capabilities to meet operational efficiency goals. |
| 2028 | 5.3 | Growth is expected to moderate as airlines refine their AOG service strategies in response to evolving safety standards. |
| 2029 | 4.3 | Demand is projected to continue rising, albeit at a slower pace, due to ongoing fleet expansion and increased MRO capabilities. |
| 2030 | 3.3 | Growth is expected to slow further as airlines face challenges in maintaining service levels amid rising operational costs. |
| 2031 | 2.8 | The market is projected to experience a slight slowdown as operational efficiencies are prioritised in response to competitive pressures. |
| 2032 | 7.0 | A resurgence in demand is anticipated as the 'National Civil Aviation Development Plan' continues to support the aviation sector's expansion. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China UNS AOG Response Market Synopsis
UNS AOG Response services in China tackle aircraft on ground (AOG) situations, ensuring swift responses to minimise downtime. This encompasses logistics management, component leasing, and repair services tailored for airlines and maintenance, repair, and overhaul (MRO) providers. The China UNS AOG Response Market is growing due to a thriving aviation sector, with over 300 commercial airlines operating domestically and a forecast of 1 billion passengers by 2025. The heightened focus on operational efficiency and safety standards propels demand for these services, backed by considerable government investments in aviation infrastructure.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing passenger traffic drives demand for AOG services. | Driver | High | Emergency Spares |
| Fleet expansion necessitates timely AOG responses. | Driver | High | Logistics Handling |
| Growing MRO providers seek to enhance service offerings. | Opportunity | High | MRO Providers |
| Investment in airport infrastructure creates demand for AOG services. | Opportunity | High | Airlines |
| High operational costs can limit service availability. | Restraint | Medium | Component Leasing |
| Regulatory compliance requirements can delay service provision. | Restraint | Medium | Repair & Maintenance |
| The market faces challenges in meeting rapid response times. | Challenge | High | Emergency Spares |
| Limited availability of skilled technicians impacts service quality. | Challenge | Medium | MRO Providers |
Evaluation of Drivers in China UNS AOG Response Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Surge in passenger numbers boosts demand for AOG services. | Emergency Spares | With over 1 billion passengers expected by 2025, airlines need immediate AOG solutions to maintain operations. |
| Fleet growth drives the need for efficient logistics handling. | Logistics Handling | The installed base of approximately 3,800 aircraft necessitates timely AOG responses to minimise downtime. |
| Increasing focus on safety standards drives demand for AOG services. | Repair & Maintenance | The Civil Aviation Administration of China mandates high operational safety standards, compelling airlines to invest in AOG services. |
| Expansion of MRO providers increases service capabilities. | MRO Providers | The number of MRO providers in China has increased by 20% since 2020, enhancing service availability. |
| Government investment in aviation infrastructure supports market growth. | Airlines | The Chinese government invested $1.5 billion in airport infrastructure in 2023, facilitating better AOG service delivery. |
Market growth for UNS AOG Response in China is underpinned by rising passenger traffic, fleet expansion, and increasing safety standards. The aviation sector is expected to accommodate 1 billion passengers by 2025, prompting airlines to prioritise immediate AOG solutions. With approximately 3,800 aircraft in operation, efficient logistics handling is essential to minimise downtime. Stringent safety standards enforced by the Civil Aviation Administration of China drive demand for repair and maintenance services. The growth of MRO providers, which have increased by 20% since 2020, further supports service capabilities in the market.
Evaluation of Restraints in China UNS AOG Response Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High operational costs limit the availability of AOG services. | Component Leasing | Increased operational expenses can deter airlines from utilising AOG services, leading to a 10% reduction in demand. |
| Regulatory compliance can delay AOG service provision. | Repair & Maintenance | Strict safety regulations require thorough inspections before service approval, extending service times by 15%. |
| Limited availability of parts can impact service delivery. | Emergency Spares | Supply chain disruptions can lead to delays in obtaining critical components, increasing downtime for airlines. |
| Market saturation may restrict new service entrants. | Emergency Spares | An increasing number of providers can lead to intensified competition, reducing profit margins by 5%. |
| Operational inefficiencies can hinder timely AOG responses. | Emergency Spares | Delays in logistics can impact the ability to meet SLA commitments, causing potential downtime of up to 20%. |
China UNS AOG Response Market Challenges
The China UNS AOG Response market faces high logistics costs, which can delay service delivery by up to 20% for airlines. Intense competition among over 300 commercial airlines drives prices down, reducing profit margins for maintenance, repair, and overhaul providers. A shortage of skilled technicians hampers the workforce's ability to respond quickly, resulting in average response times that can exceed 6 hours during critical AOG situations. Domestic airlines are under pressure from a 15% increase in AOG service demand in 2023, straining resources and risking further service delays.
Trends in the China UNS AOG Response Market
Buyers and suppliers in the China UNS AOG Response Market are adjusting to the following trends.
- Shift towards Improved Logistics Handling: The 'National Civil Aviation Development Plan' initiated in 2021 prioritises improved logistics handling for AOG services. This shift aims to streamline operations and reduce response times, with a projected 15% increase in AOG service demand by 2023.
- Implementation of Updated Safety Standards: Since 2021, the updated 'Aviation Safety Law' has introduced new standards for AOG services. This change ensures compliance with safety protocols while enhancing service delivery across the aviation sector.
- Focus on Component Leasing Growth: The demand for component leasing has surged as airlines aim to minimise upfront costs. This trend is clear as MRO providers increasingly offer leasing options, with a projected growth rate of 6.3% through 2032.
- Expansion of MRO Provider Network: The number of MRO providers has increased significantly since 2020, reflecting a shift towards decentralised service models. With over 40 maintenance bases established, this expansion improves service availability across major aviation hubs.
Investment Opportunities in the China UNS AOG Response Market
The following opportunities in the China UNS AOG Response Market pair current demand with a clear way in.
- Investment in AOG Services: With the aviation sector expanding rapidly, there is an opportunity to invest in AOG services. Airlines are actively seeking partnerships to enhance their service capabilities and meet rising demand for rapid response solutions.
- Entry into the MRO Market: The growing number of MRO providers presents an opportunity for joint ventures. With a 20% increase in providers since 2020, collaborating with local firms can facilitate market entry and service expansion.
- Need for Rapid Response Capabilities: The average response time for AOG services is under 6 hours, indicating a need for improved logistics handling. Airlines are searching for solutions that can meet or exceed this standard, creating demand for capable service providers.
- Airlines Seeking Efficient Solutions: Airlines are emphasising operational efficiency, creating a demand for AOG services that minimise downtime. Investing in logistics management solutions can help address this growing need.
Government Initiatives in the China UNS AOG Response Market
The 'National Civil Aviation Development Plan' launched by the CAAC in 2021 aims to improve aviation infrastructure and service quality by 2025. This plan mandates enhancements in AOG response capabilities, ensuring that airlines maintain operational efficiency. Additionally, the 'Aviation Safety Law' introduced in 2022 establishes operational safety standards for AOG services, requiring compliance from all service providers. These measures collectively strengthen the reliability of AOG services in the aviation sector.
In 2023, the CAAC reported a 15% increase in AOG service demand, prompting the agency to implement the 'Civil Aviation Safety Program'. This program aims to reduce AOG incidents by 30% by 2025, enhancing safety protocols across the industry. The 'Aviation Industry Development Fund', established in 2021, supports technological advancements in AOG services, with a budget of $500 million allocated to improve service quality and efficiency. These initiatives are essential for ensuring that AOG services meet the growing demands of the aviation market.
Future Insight of the China UNS AOG Response Market
The China UNS AOG Response market will undergo transformative changes by 2032, driven by the 'National Civil Aviation Development Plan' which aims to enhance air transport services. The investment of $1.5 billion in airport infrastructure will expand maintenance bases and improve service capabilities. MRO services are projected to grow by 10% annually through 2025, increasing the market's capacity to manage AOG situations effectively. The 'Civil Aviation Safety Program' aims to cut AOG incidents by 30% by 2025, promoting better operational efficiency.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Service Type – Emergency Spares Dominated, Logistics Handling Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Emergency Spares held a 51% share of the China UNS AOG Response Market by service type in 2025. Emergency spares lead the China UNS AOG Response Market because they are critical for ensuring immediate aircraft operation. With over 300 commercial airlines depending on these spares, their availability is vital for maintaining flight schedules and operational efficiency. Logistics Handling is projected to grow fastest, at a CAGR of 6.3% during 2026–2032. Logistics handling is experiencing rapid growth as it ensures timely delivery of parts and services, crucial given the 15% increase in AOG service demand reported by the CAAC in 2023. This efficiency is essential for airlines and MRO providers to maintain their operational capabilities. Suppliers must focus on enhancing logistics capabilities to meet the rising demand for rapid AOG response services.
By Aircraft Component – Engine Dominated, Avionics Expected to Grow Fastest
The largest aircraft component category in 2025 was Engine, with a 39% share of total revenue. The engine segment commands the largest share in the market, being essential for aircraft operation and ensuring safety during flights. With the average age of aircraft in China around 8 years, the need for engine maintenance remains consistently high, driving demand. The quickest growth will come from Avionics, forecast to expand at a CAGR of 6.6% between 2026 and 2032. Avionics is the fastest-growing segment, spurred by the increasing importance of navigation and communication systems in modern aircraft. As the aviation sector aims to accommodate 1 billion passengers by 2025, the demand for advanced avionics will continue to rise. Investments in avionics technology are crucial for suppliers to capture the growing market share in aircraft components.
By Response Time SLA – <4 Hours Dominated and Is Expected to Record the Fastest Growth
<4 Hours took a 43% share of response time sla in 2025, more than any other category. The <4 hours response time SLA holds the largest share as it is critical for minimizing downtime, a key factor for airlines striving for operational efficiency. With the average response time for AOG services in China being under 6 hours, this standard is increasingly becoming the expectation. <4 Hours are also forecast to expand faster than any other category, at a CAGR of 6.5% over 2026–2032. The <4 hours SLA is also the fastest-growing segment, as airlines and MRO providers recognise the necessity of rapid response to maintain service continuity. This alignment with operational demands will likely widen the lead of this SLA in the market. Suppliers must prioritise achieving and maintaining a <4 hours SLA to remain competitive in the AOG response market.
By End User – Airlines Dominated, MRO Providers Expected to Grow Fastest
In 2025, Airlines led the end user split with a 47% share. Airlines hold the largest share of the market as they are the primary users of AOG response services, directly impacting their operational efficiency and safety. The ongoing growth of the aviation sector in China, highlighted by significant passenger increases, strengthens their dominant position. Over 2026–2032, MRO Providers are expected to post the fastest growth, at a CAGR of 6.4%. MRO providers are the fastest-growing segment, driven by a projected 10% annual growth rate in MRO services through 2025. Their role as essential service providers for aircraft maintenance will expand alongside the increasing fleet size and demand for AOG services. Suppliers should build strong partnerships with MRO providers to effectively tap into the expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China UNS AOG Response Market Outlook
- Market Size of China UNS AOG Response Market, 2025
- Forecast of China UNS AOG Response Market, 2032
- Historical Data and Forecast of China UNS AOG Response Revenues & Volume for the Period 2022 - 2032F
- China UNS AOG Response Market Trend Evolution
- China UNS AOG Response Market Drivers and Challenges
- China UNS AOG Response Price Trends
- China UNS AOG Response Porter's Five Forces
- China UNS AOG Response Industry Life Cycle
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Emergency Spares for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Component Leasing for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Logistics Handling for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Repair & Maintenance for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Aircraft Component for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Engine, Avionics for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Landing Gear, Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Cargo & Paperwork for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Any Aircraft Part for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Response Time SLA for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By <4 Hours for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By <24 Hours for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Expedited for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Scheduled AOG for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Airlines for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By MRO Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China UNS AOG Response Market Revenues & Volume By Aircraft Operators for the Period 2022 - 2032F
- China UNS AOG Response Import Export Trade Statistics
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Aircraft Component
- Market Opportunity Assessment By Response Time SLA
- Market Opportunity Assessment By End User
- China UNS AOG Response Top Companies Market Share
- China UNS AOG Response Competitive Benchmarking By Technical and Operational Parameters
- China UNS AOG Response Company Profiles
- China UNS AOG Response Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Service Type
- Emergency Spares
- Component Leasing
- Logistics Handling
- Repair & Maintenance
By Aircraft Component
- Engine
- Avionics
- Landing Gear
- Sensors
- Cargo & Paperwork
- Any Aircraft Part
By Response Time SLA
- <4 Hours
- <24 Hours
- Expedited
- Scheduled AOG
By End User
- Airlines
- MRO Providers
- OEMs
- Aircraft Operators































