China Utility-Grade Wire Market Size & Growth Rate
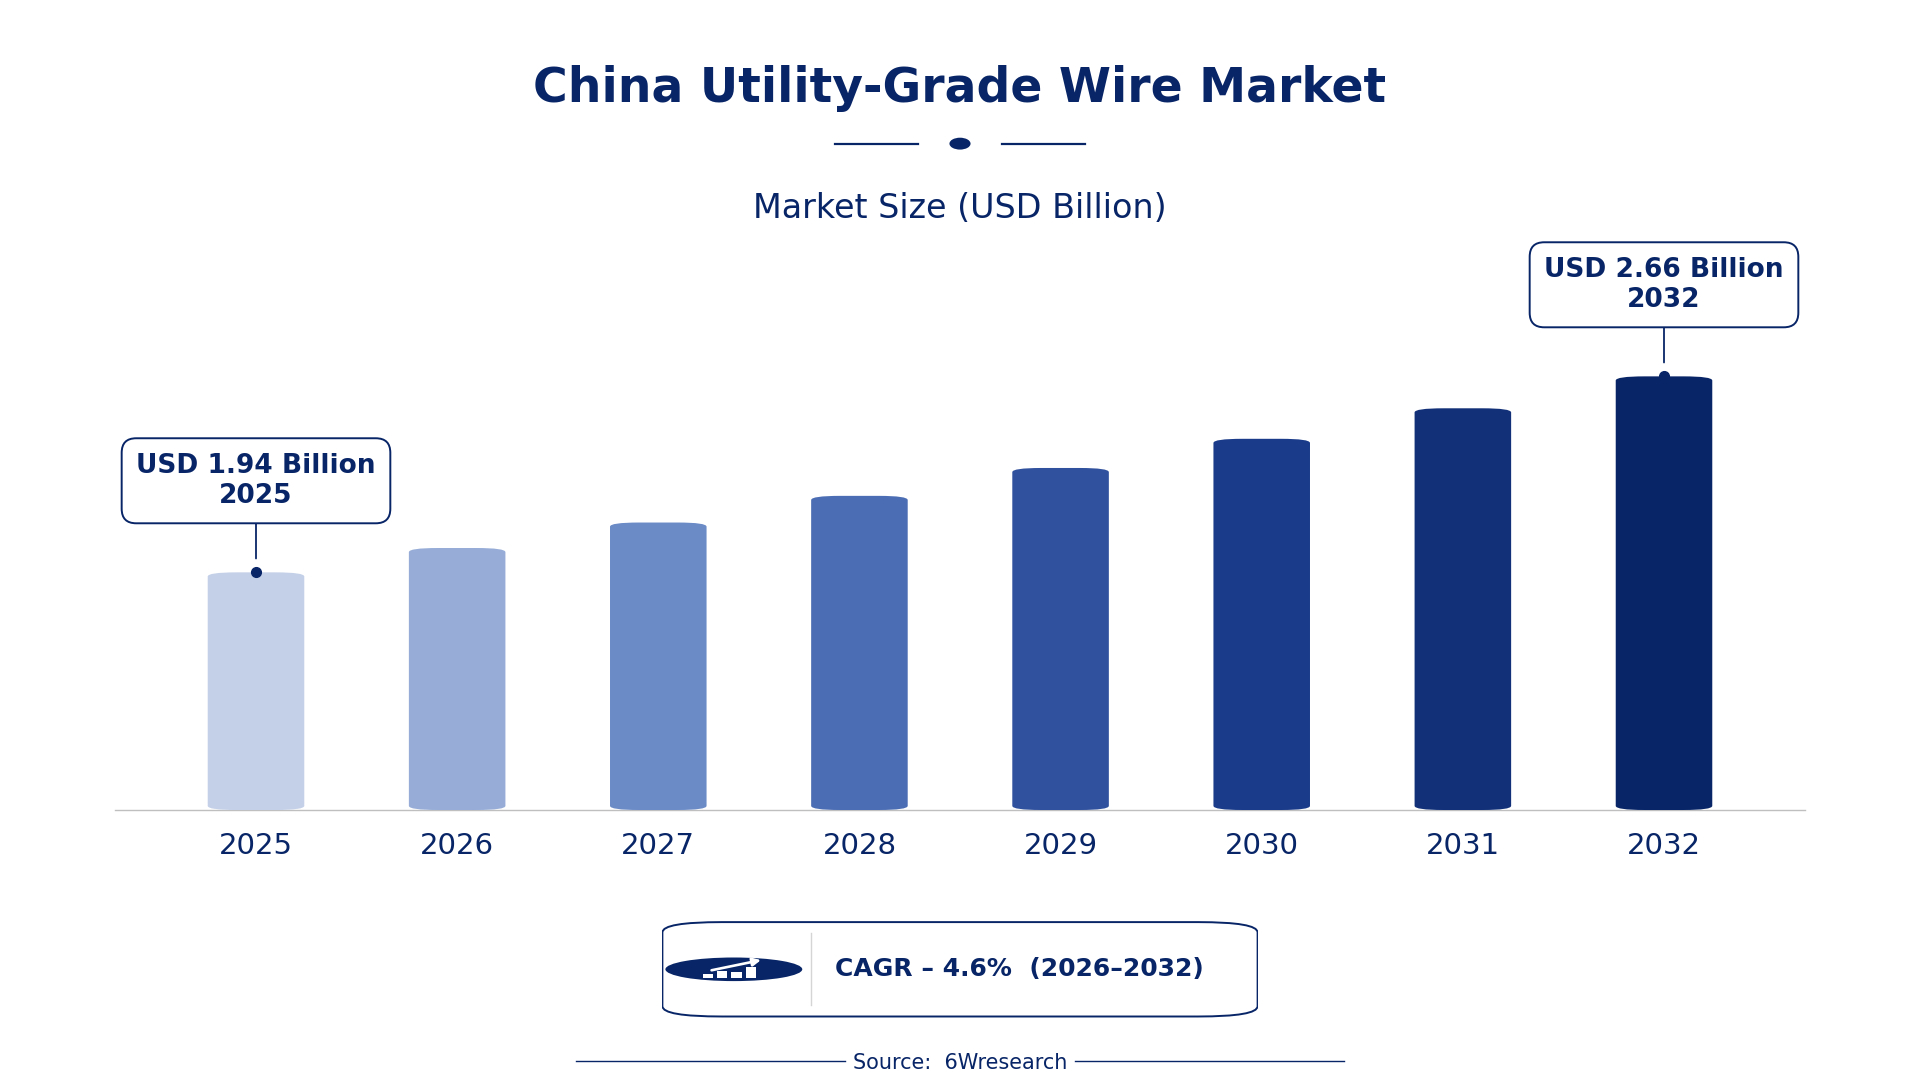
According to 6Wresearch internal database and industry insights, the China Utility-Grade Wire Market was valued at USD 1.94 billion in 2025 and is projected to reach USD 2.66 billion by 2032, growing at a CAGR of approximately 4.6% during 2026–2032.
China Utility-Grade Wire Market Highlights
| Report Metric | Details |
| Report Name | China Utility-Grade Wire Market |
| Market Size 2025 | USD 1.94 billion |
| Market Size 2032 | USD 2.66 billion |
| Absolute Growth 2025–2032 | USD 0.72 billion |
| CAGR 2026–2032 | 4.6% |
| Peak Annual Growth | 7.1% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Wire Type, 2025 | Overhead Conductors (37% share) |
| Leading Conductor Material, 2025 | ACSR/Aluminum (45% share) |
| Leading Insulation Type, 2025 | Bare (44% share) |
| Leading End User, 2025 | Transmission Grids (47% share) |
| Fastest-Growing Wire Type | Underground Cables (5.8% CAGR) |
| Fastest-Growing Conductor Material | Copper (6.1% CAGR) |
| Fastest-Growing Insulation Type | XLPE (6.0% CAGR) |
| Fastest-Growing End User | Distribution Utilities (6.1% CAGR) |
| Growing Sector | Urban Infrastructure |
| Key End Users | Transmission Utilities, Distribution Utilities, Substation Installers, Industrial Utilities |
China Utility-Grade Wire Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
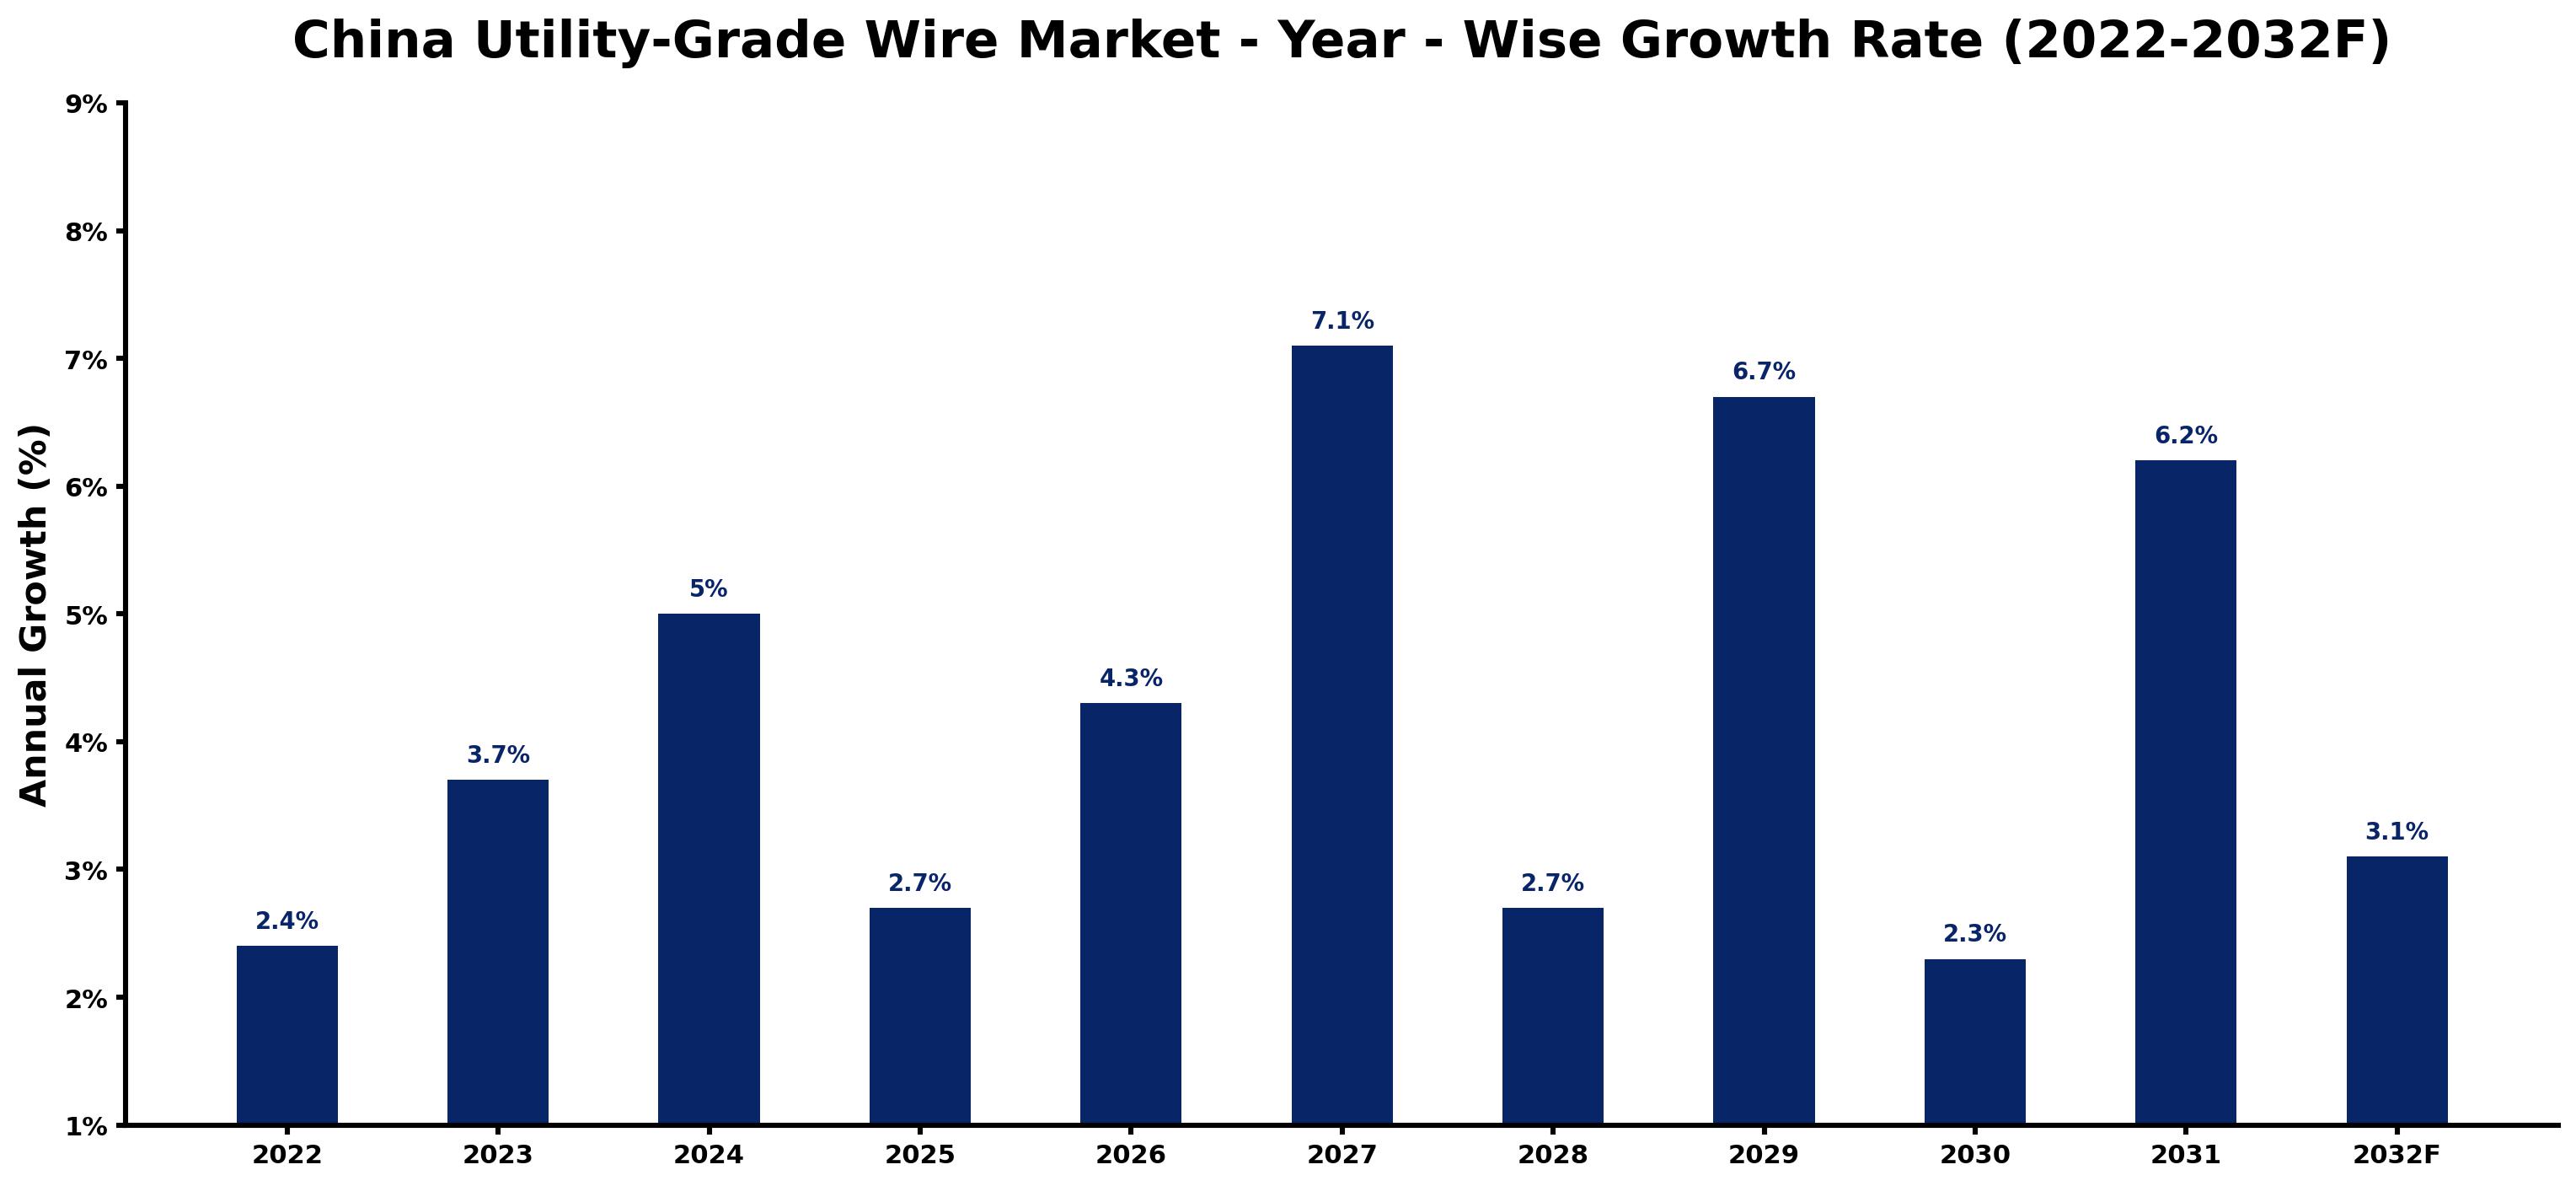
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.4 | The market experienced steady growth due to ongoing infrastructure projects. |
| 2023 | 3.7 | Demand increased as urbanisation initiatives expanded across major cities. |
| 2024 | 5.0 | Infrastructure investments peaked, driving demand for utility-grade wire. |
| 2025 | 2.7 | Growth slowed as some projects reached completion, impacting demand. |
| 2026 | 4.3 | The market rebounded with renewed investment in energy infrastructure. |
| 2027 | 7.1 | Peak growth was driven by the National Energy Administration's grid enhancement plan. |
| 2028 | 2.7 | A slight slowdown occurred as urban population growth stabilised. |
| 2029 | 6.7 | Demand accelerated again due to rising energy needs in urban areas. |
| 2030 | 2.3 | Growth slowed as urban infrastructure projects began to saturate the market. |
| 2031 | 6.2 | Increased investments in distribution utilities drove higher demand. |
| 2032 | 3.1 | The market is expected to stabilise with consistent demand from urban infrastructure projects. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Utility-Grade Wire Market Synopsis
Utility-Grade Wire in China encompasses wire utilised for electrical power transmission and distribution, crafted from materials such as aluminium and copper. Its applications include overhead conductors, underground cables, and substation wiring. The China Utility-Grade Wire Market is growing due to strong demand from domestic infrastructure projects and urbanisation initiatives. With the urban population projected to reach 1 billion by 2030, the need for utility-grade wire will further escalate. A $200 billion investment in energy infrastructure is expected to fuel additional growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising urbanisation initiatives are increasing demand for utility-grade wire. | Driver | High | Underground Cables |
| The National Energy Administration's grid enhancement plan is boosting infrastructure investments. | Driver | High | Overhead Conductors |
| The projected urban population growth presents opportunities for new infrastructure projects. | Opportunity | High | Substation Wiring |
| Investment in energy infrastructure is increasing demand for utility-grade wire. | Opportunity | High | Feeder Wires |
| Market saturation is beginning to slow growth as projects reach completion. | Restraint | Medium | ACSR/Aluminum |
| Rising production costs may impact pricing strategies for manufacturers. | Restraint | Medium | Copper |
| Supply chain disruptions can delay project timelines for buyers. | Challenge | High | Underground Cables |
| Approval processes for new projects can extend timelines and increase costs. | Challenge | Medium | Substation Wiring |
Evaluation of Drivers in China Utility-Grade Wire Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased urbanisation is driving demand for underground cables. | Underground Cables | With 40% of urban cables using XLPE insulation, demand for utility-grade wire is rising. |
| Investment in energy infrastructure is boosting overhead conductor usage. | Overhead Conductors | The $200 billion investment approved in 2023 is set to improve grid infrastructure. |
| Growing demand from transmission grids is increasing utility-grade wire purchases. | Transmission Grids | Transmission grids account for 47% of the end-user market share, driving higher wire demand. |
| The rise of urban population is pushing for more substation wiring. | Substation Wiring | China's urban population is projected to reach 1 billion by 2030, necessitating more wiring. |
| Demand for feeder wires is increasing due to infrastructure expansion. | Feeder Wires | As urbanisation grows, feeder wires are essential for distributing power to consumers. |
Growth across the Utility-Grade Wire market in China is anchored in rising urbanisation, substantial infrastructure investments, and increasing energy demands. In 2023, the National Development and Reform Commission approved a $200 billion investment for energy infrastructure, which will improve grid capabilities. Urban population projections indicate a rise to 1 billion by 2030, which will boost demand for underground cables, particularly those with XLPE insulation. The expansion of urban infrastructure is also increasing the demand for feeder wires, further elevating the need for utility-grade wire.
Evaluation of Restraints in China Utility-Grade Wire Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Market saturation is impacting growth rates as projects complete. | ACSR/Aluminum | As major projects finish, the demand for ACSR/Aluminum wire is stabilising. |
| Increasing production costs may lead to higher prices for buyers. | Copper | Rising costs in raw materials could affect pricing strategies for utility-grade wire. |
| Supply chain disruptions can delay project timelines. | Underground Cables | Delays in material supply can hinder the timely completion of urban projects. |
| Approval processes for new projects can extend timelines. | Substation Wiring | Lengthy regulatory approvals can slow down the implementation of new wiring solutions. |
| Competition among manufacturers may limit pricing flexibility. | Feeder Wires | Intense competition can restrict manufacturers' ability to adjust prices effectively. |
China Utility-Grade Wire Market Challenges
China's utility-grade wire market encounters delays due to strict ISO 9001 certification requirements, which can take up to six months for producers to secure, hindering their ability to fulfil orders for infrastructure projects. This regulatory burden raises production costs, forcing manufacturers to increase prices, which directly affects construction firms reliant on timely deliveries. Rapid urbanisation, with the urban population projected to reach 1 billion by 2030, strains existing production technology, leading to longer lead times for electrical contractors. Competition from alternative materials like PVC/EPDM insulated wires pressures producers to adapt, but skills shortages in advanced manufacturing technologies impede their ability to innovate, delaying product availability for buyers.
Trends in the China Utility-Grade Wire Market
Four trends stand out in the China Utility-Grade Wire Market.
- Shift from Copper to ACSR/Aluminum: China is experiencing a shift from copper to ACSR/Aluminum wire due to its lightweight and conductivity advantages. In 2022, ACSR/Aluminum accounted for 60% of the market, reflecting this trend.
- Transition to XLPE Insulation: Since 2020, there has been a transition towards XLPE insulation for underground cables, which offers better thermal properties. Currently, XLPE is used in 40% of urban underground cables, indicating a market shift.
- Emergence of Smart Grid Technologies: The rise of smart grid technologies is influencing utility-grade wire demand, particularly in urban areas. By 2025, the National Energy Administration's plan aims to improve grid infrastructure, driving further adoption of advanced wiring solutions.
- Increased Focus on Sustainable Materials: The utility sector is increasingly prioritising sustainable materials in wire production. The push for eco-friendly solutions is clear, with manufacturers exploring alternatives to traditional materials.
Investment Opportunities in the China Utility-Grade Wire Market
Several openings in the China Utility-Grade Wire Market merit attention from investors.
- Rising Urban Population: With China's urban population projected to reach 1 billion by 2030, there is a strong opportunity for investment in utility-grade wire for urban infrastructure projects. This presents a chance for suppliers to align with distribution utilities.
- Investment in Energy Infrastructure: The $200 billion investment approved in 2023 creates a timely opportunity for manufacturers to supply utility-grade wire. Collaborating with local distribution utilities can facilitate market entry.
- Growing Demand for Underground Cables: The average annual growth rate for underground cables is expected to be 5% until 2026, indicating a strong market opportunity for suppliers. Focusing on urban areas can enhance market penetration.
- Expansion of Substation Installations: As substation installations increase, there is a growing need for specific wiring solutions. Manufacturers can enter this market by forming partnerships with substation installers.
Government Initiatives in the China Utility-Grade Wire Market
The National Energy Administration's 2023 plan aims to improve grid infrastructure by 2025, building on previous regulations that mandated ISO 9001 certification for manufacturers. This new measure requires producers to meet stringent quality standards, ensuring reliability in utility-grade wire production. The framework established by the National Development and Reform Commission supports ongoing investments in energy infrastructure, facilitating growth in the sector. These measures aim to improve the quality and efficiency of utility-grade wire production, benefiting both producers and consumers.
The National Development and Reform Commission approved a $200 billion investment for energy infrastructure in 2023. This funding will support various projects aimed at modernising the energy grid and enhancing overall capacity. The agency is responsible for overseeing the implementation of these projects, ensuring compliance with national standards. Additionally, the National Energy Administration monitors the progress of grid enhancement initiatives, providing necessary approvals and guidance for manufacturers and buyers.
Future Insight of the China Utility-Grade Wire Market
The utility-grade wire market in China is expected to evolve significantly by 2032, driven by the National Energy Administration's grid infrastructure improvement plan, scheduled for completion by 2025. This initiative will facilitate a $200 billion investment in energy infrastructure, enhancing production capabilities for manufacturers. As urbanisation accelerates, demand for utility-grade wire will rise, particularly for advanced underground cables, which are projected to grow at an annual rate of 5% until 2026. The adoption of new manufacturing technologies will enable suppliers to better meet the specific requirements of construction firms.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Wire Type – Overhead Conductors Dominated, Underground Cables Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Overhead Conductors took a 37% share of wire type in 2025, more than any other category. Overhead conductors hold the largest market share as they are essential for transmitting electricity over long distances, ensuring efficient power delivery across regions. The National Energy Administration's initiative to enhance grid infrastructure further highlights their critical role in meeting China's energy demands. The quickest growth will come from Underground Cables, forecast to expand at a CAGR of 5.8% between 2026 and 2032. Underground cables are set to experience rapid growth, with an average annual growth rate of 5% until 2026, driven by urban expansion and the need to reduce visual impact. This trend indicates a strong preference for underground solutions in densely populated urban areas, ensuring reliable power distribution. Suppliers should focus on developing underground cable solutions to meet the increasing demand driven by urban infrastructure projects.
By Conductor Material – ACSR/Aluminum Dominated, Copper Expected to Grow Fastest
The largest conductor material category in 2025 was ACSR/Aluminum, with a 45% share of total revenue. ACSR/aluminum dominates the market due to its lightweight properties and excellent conductivity, making it the preferred choice for utility-grade wire applications. Its extensive use in major energy projects, including the recent $200 billion investment in infrastructure, solidifies its leading position. Over 2026–2032, Copper is expected to post the fastest growth, at a CAGR of 6.1%. Copper is the fastest-growing segment, primarily due to its superior electrical conductivity, which is crucial for high-performance applications. As the demand for efficient power solutions rises, copper's market share is anticipated to expand significantly. Buyers should consider integrating copper into their procurement strategies to improve performance and reliability in utility-grade wire applications.
By Insulation Type – Bare Dominated, XLPE Expected to Grow Fastest
In 2025, Bare led the insulation type split with a 44% share. Bare wire leads the insulation type segment due to its widespread use in overhead lines where insulation is not required, facilitating direct electricity transmission. This is particularly relevant in rural areas where overhead lines are prevalent. XLPE is projected to grow fastest, at a CAGR of 6.0% during 2026–2032. XLPE insulation is the fastest-growing type, offering excellent thermal and electrical properties, making it ideal for modern underground applications. As urbanisation accelerates, the demand for XLPE insulated cables is expected to surge. Manufacturers should prioritise the production of XLPE insulated wires to capitalise on the growing demand from urban infrastructure projects.
By End User – Transmission Grids Dominated, Distribution Utilities Expected to Grow Fastest
Transmission Grids held a 47% share of the China Utility-Grade Wire Market by end user in 2025. Transmission grids represent the largest share of the market as they are critical for national electricity distribution networks, ensuring reliable power supply across vast regions. The ongoing investments in grid infrastructure underscore the importance of this segment. Distribution Utilities are set to record the highest CAGR in this split, 6.1% over 2026–2032. Distribution utilities are the fastest-growing end user segment, primarily because they are the main consumers of utility-grade wire for local distribution needs. As urban populations increase, the demand for efficient local distribution systems will continue to rise. Suppliers must align their strategies with the needs of distribution utilities to capture the growing market share in local power distribution.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Utility-Grade Wire Market Outlook
- Market Size of China Utility-Grade Wire Market, 2025
- Forecast of China Utility-Grade Wire Market, 2032
- Historical Data and Forecast of China Utility-Grade Wire Revenues & Volume for the Period 2022 - 2032F
- China Utility-Grade Wire Market Trend Evolution
- China Utility-Grade Wire Market Drivers and Challenges
- China Utility-Grade Wire Price Trends
- China Utility-Grade Wire Porter's Five Forces
- China Utility-Grade Wire Industry Life Cycle
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Wire Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Overhead Conductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Underground Cables for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Substation Wiring for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Feeder Wires for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Conductor Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By ACSR/Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Copper for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Copper/Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Copper for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Insulation Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Bare for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By XLPE for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By PVC/EPDM for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Nylon-Coated for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Transmission Grids for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Distribution Utilities for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Substation Installers for the Period 2022 - 2032F
- Historical Data and Forecast of China Utility-Grade Wire Market Revenues & Volume By Industrial Utilities for the Period 2022 - 2032F
- China Utility-Grade Wire Import Export Trade Statistics
- Market Opportunity Assessment By Wire Type
- Market Opportunity Assessment By Conductor Material
- Market Opportunity Assessment By Insulation Type
- Market Opportunity Assessment By End User
- China Utility-Grade Wire Top Companies Market Share
- China Utility-Grade Wire Competitive Benchmarking By Technical and Operational Parameters
- China Utility-Grade Wire Company Profiles
- China Utility-Grade Wire Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Wire Type
- Overhead Conductors
- Underground Cables
- Substation Wiring
- Feeder Wires
By Conductor Material
- ACSR/Aluminum
- Copper
- Copper/Aluminum
By Insulation Type
- Bare
- XLPE
- PVC/EPDM
- Nylon-Coated
By End User
- Transmission Grids
- Distribution Utilities
- Substation Installers
- Industrial Utilities































