China Vehicle Body Shell and Chassis Assemblies Market Size & Growth Rate
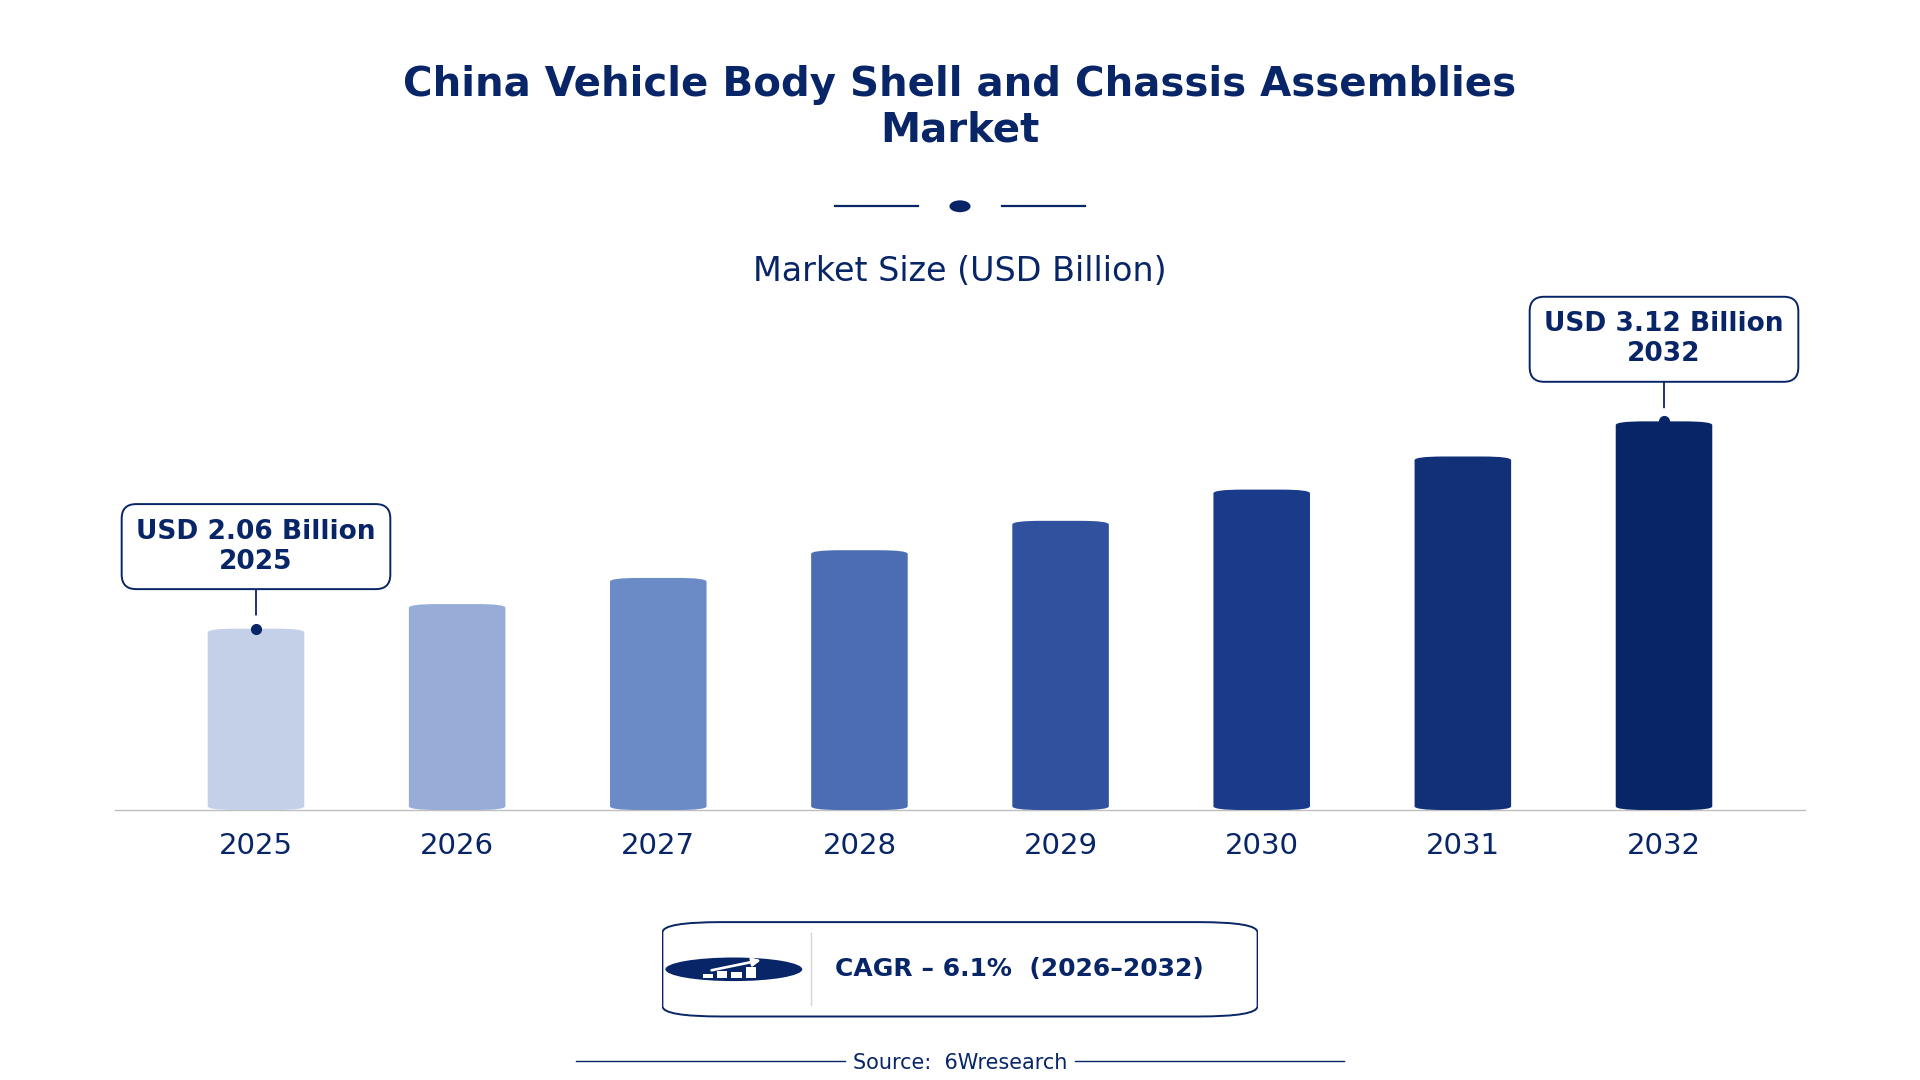
According to 6Wresearch internal database and industry insights, the China Vehicle Body Shell and Chassis Assemblies Market was valued at USD 2.06 billion in 2025 and is projected to reach USD 3.12 billion by 2032, growing at a CAGR of approximately 6.1% during 2026–2032.
China Vehicle Body Shell and Chassis Assemblies Market Highlights
| Report Metric | Details |
| Report Name | China Vehicle Body Shell and Chassis Assemblies Market |
| Market Size 2025 | USD 2.06 billion |
| Market Size 2032 | USD 3.12 billion |
| Absolute Growth 2025–2032 | USD 1.06 billion |
| CAGR 2026–2032 | 6.1% |
| Peak Annual Growth | 8.2% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Assembly Type, 2025 | Monocoque Body Shells (38% share) |
| Leading Frame Type, 2025 | Unibody (45% share) |
| Leading Integration Type, 2025 | Factory Integrated (46% share) |
| Leading End User, 2025 | Passenger Car Makers (40% share) |
| Fastest-Growing Assembly Type | Space Frame Structures (8.1% CAGR) |
| Fastest-Growing Frame Type | Lightweight (8.1% CAGR) |
| Fastest-Growing Integration Type | Modular (8.5% CAGR) |
| Fastest-Growing End User | Electric Vehicle Startups (8.5% CAGR) |
| Growing Sector | Electric Vehicle Startups |
| Key End Users | Passenger Car Makers, Commercial Vehicle OEMs, Electric Vehicle Startups, Racing Vehicle Manufacturers |
China Vehicle Body Shell and Chassis Assemblies Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
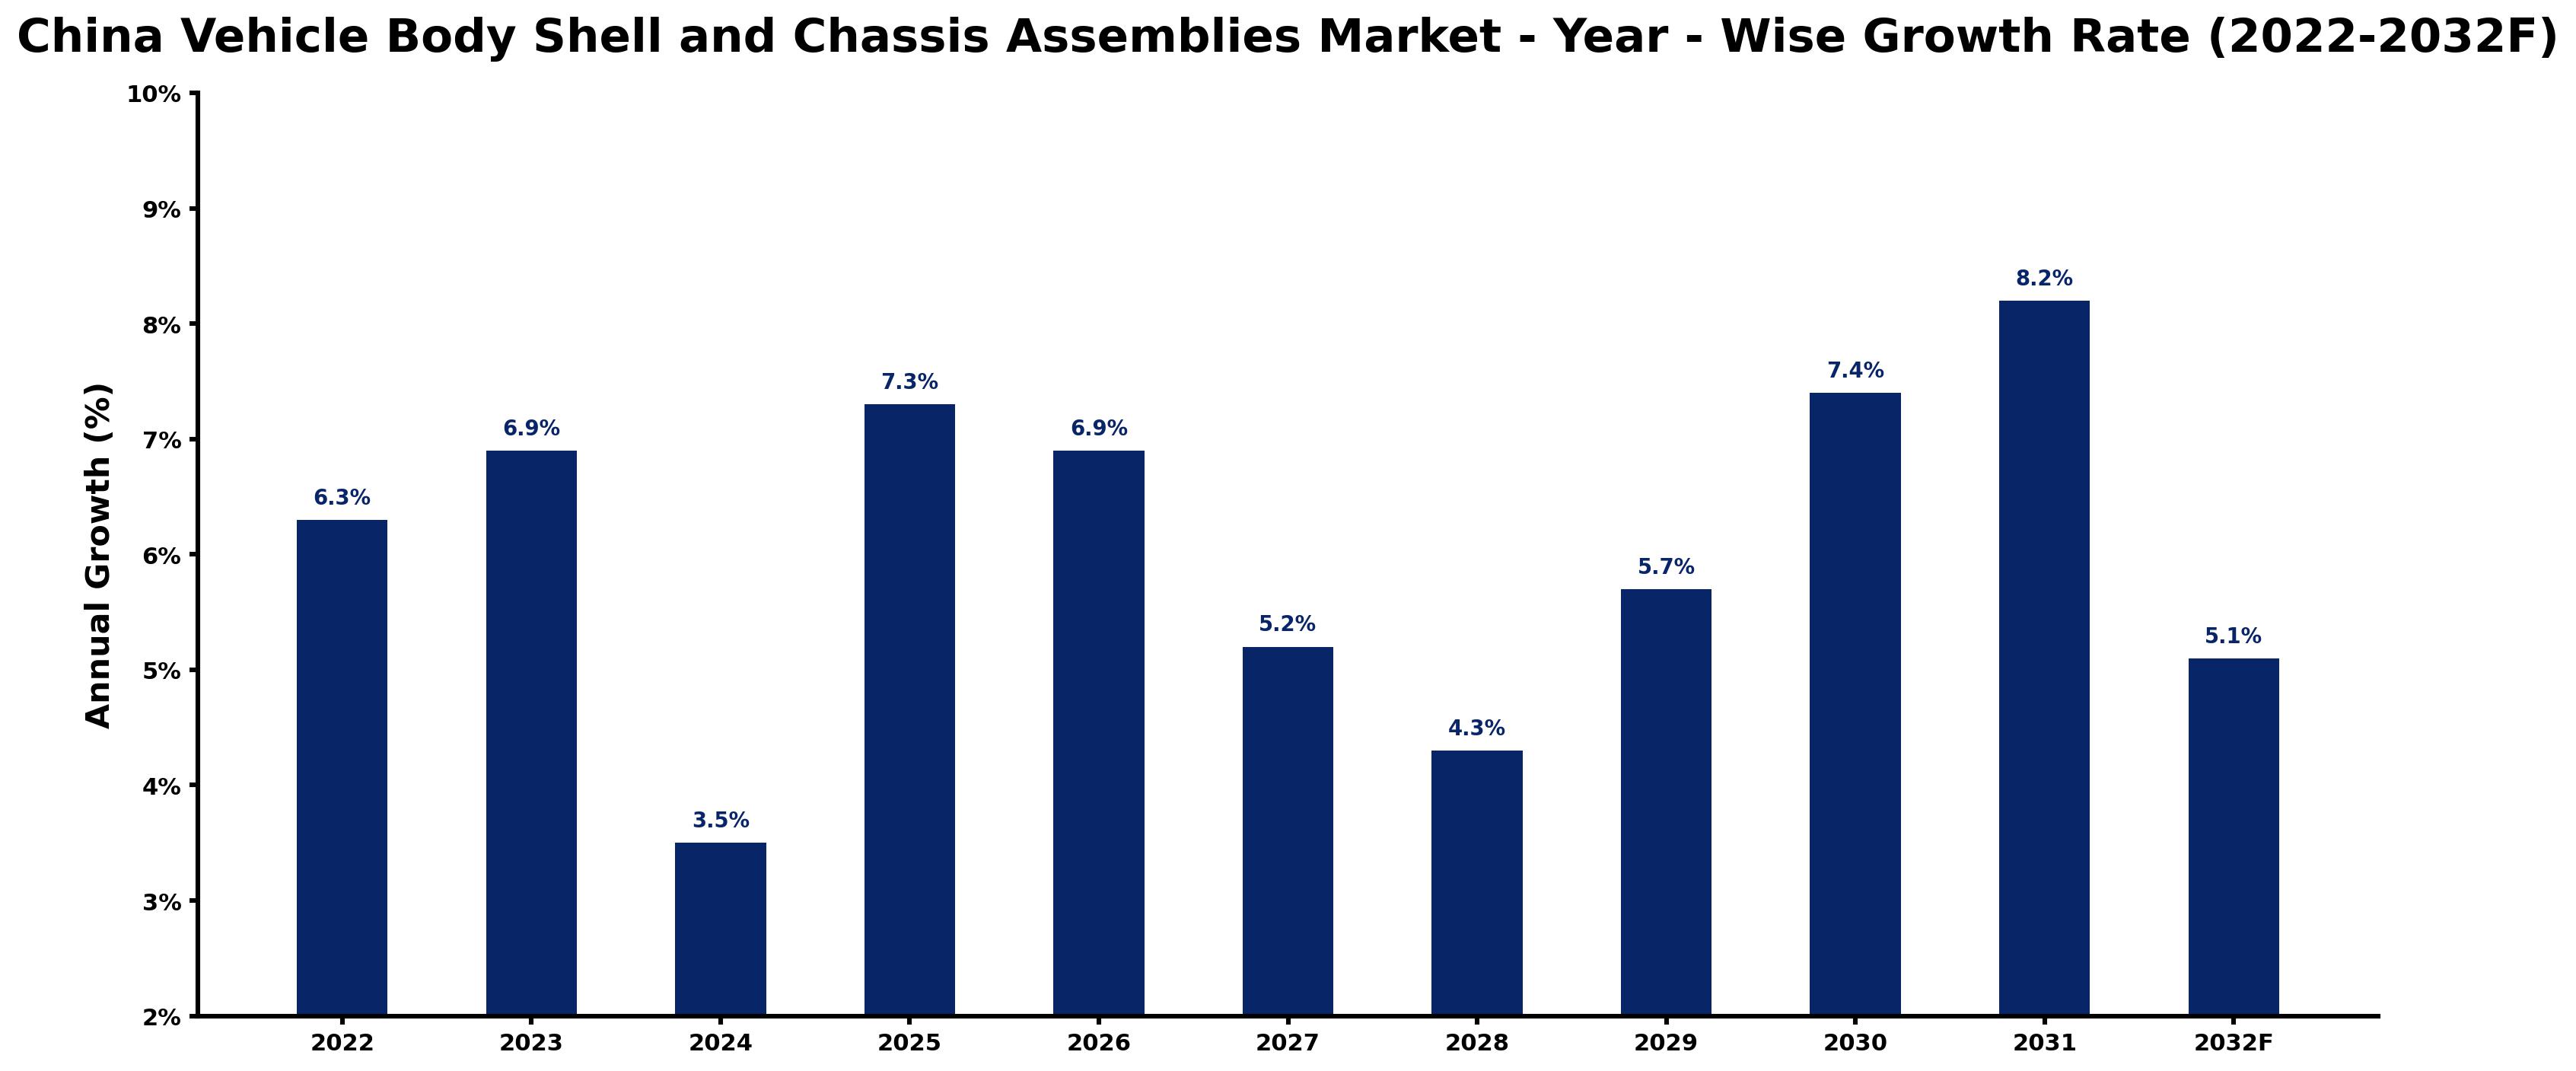
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.3 | The market experienced solid growth due to strong automotive production figures. |
| 2023 | 6.9 | Demand increased as electric vehicle startups expanded their operations. |
| 2024 | 3.5 | Growth slowed as manufacturers adjusted to changing market conditions. |
| 2025 | 7.3 | The market rebounded with heightened production capabilities and demand from passenger car makers. |
| 2026 | 6.9 | A slight slowdown occurred as manufacturers faced supply chain challenges in Guangdong. |
| 2027 | 5.2 | Continued adjustments in production led to further growth moderation amid rising costs. |
| 2028 | 4.3 | The market experienced another slowdown as competition intensified in the automotive sector. |
| 2029 | 5.7 | Demand improved as manufacturers focused on innovative vehicle designs and lightweight materials. |
| 2030 | 7.4 | Growth accelerated as consumer interest in electric vehicles surged, aligning with national goals. |
| 2031 | 8.2 | The market peaked, driven by advancements in manufacturing technologies and electric vehicle standards. |
| 2032 | 5.1 | A slowdown occurred as the market stabilises after rapid growth, influenced by regulatory compliance. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Vehicle Body Shell and Chassis Assemblies Market Synopsis
Vehicle Body Shell and Chassis Assemblies in China are critical components for vehicle integrity and safety, primarily made from metals or composites. These assemblies support various systems within vehicles and are essential for overall performance. The China Vehicle Body Shell and Chassis Assemblies Market is expanding due to strong automotive production, with 27 million units produced in 2022. Demand is driven by domestic manufacturers and over 300 electric vehicle startups focusing on innovation and sustainability.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising production of electric vehicles boosts demand for lightweight assemblies. | Driver | High | Lightweight |
| Increased focus on safety standards drives the need for high rigidity components. | Driver | High | High Rigidity |
| Growing electric vehicle startups present opportunities for innovative chassis solutions. | Opportunity | High | Electric Vehicle Startups |
| Expansion of production facilities in Jiangsu province creates new market openings. | Opportunity | High | Factory Integrated |
| High competition among manufacturers may limit profit margins. | Restraint | Medium | Monocoque Body Shells |
| Supply chain disruptions can delay production timelines for assemblies. | Restraint | High | Ladder Frame Assemblies |
| Technological integration challenges can hinder operational efficiency. | Challenge | High | Robotic Welding |
| Regulatory compliance costs can burden smaller manufacturers. | Challenge | Medium | Custom Build |
Evaluation of Drivers in China Vehicle Body Shell and Chassis Assemblies Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in electric vehicle production facilities. | Electric Vehicle Startups | This investment leads to higher demand for vehicle body assemblies, with over 300 startups in the market. |
| Growing consumer preference for lightweight vehicles drives assembly demand. | Lightweight | As fuel efficiency becomes a priority, manufacturers are adopting lighter materials to meet consumer expectations. |
| Rising safety standards necessitate high rigidity components. | High Rigidity | Compliance with national standards drives manufacturers to invest in safer vehicle designs, enhancing market demand. |
| The expansion of the automotive supply chain in Guangdong supports production. | Factory Integrated | This region's strong supply chain facilitates the production of vehicle body assemblies, improving efficiency. |
| Technological advancements in robotic welding improve production efficiency. | Robotic Welding | These advancements allow for faster production rates and reduced operational costs, increasing competitiveness. |
Growth in the Vehicle Body Shell and Chassis Assemblies market in China comes from increased investment in electric vehicle production facilities and a growing consumer preference for lightweight vehicles. In 2022, China's automotive production reached 27 million units, driving demand for assemblies. The focus on safety standards necessitates high rigidity components, compelling manufacturers to innovate. Investments in advanced manufacturing technologies are also rising, allowing for improved production efficiency. As a result, manufacturers are increasingly adopting these technologies to meet the rising demand for innovative vehicle designs.
Evaluation of Restraints in China Vehicle Body Shell and Chassis Assemblies Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition among manufacturers can compress profit margins. | Monocoque Body Shells | With numerous players in the market, price wars may affect profitability. |
| Supply chain disruptions can lead to production delays. | Ladder Frame Assemblies | Global supply chain issues have impacted the availability of raw materials, affecting production timelines. |
| Technological integration challenges may hinder operational efficiency. | Robotic Welding | Manufacturers face difficulties in adopting new technologies into existing processes, slowing production. |
| Regulatory compliance costs can burden smaller manufacturers. | Custom Build | Smaller firms may struggle to meet stringent safety and environmental regulations, impacting their competitiveness. |
| Market fluctuations can affect investment in new technologies. | High Rigidity | Economic uncertainties may lead to cautious spending on advanced manufacturing, hindering innovation. |
China Vehicle Body Shell and Chassis Assemblies Market Challenges
The China Vehicle Body Shell and Chassis Assemblies Market faces several pressing issues, starting with supply chain disruptions. These arise from concentrated manufacturing in regions like Jiangsu and Guangdong, causing production delays of up to three months for manufacturers. Regulatory hurdles follow, as adherence to the national standard GB/T 15089-2001 can extend the time-to-market for suppliers by several weeks. Technological advancements, particularly in robotic welding, necessitate substantial investments that can be burdensome for smaller producers. Finally, escalating raw material costs are squeezing margins, compelling buyers to seek more competitive pricing from suppliers.
Trends in the China Vehicle Body Shell and Chassis Assemblies Market
Several trends are reshaping the China Vehicle Body Shell and Chassis Assemblies Market; the most important are set out below.
- Shift towards Lightweight Materials in Vehicle Production: China's automotive industry is increasingly adopting lightweight materials to improve fuel efficiency. The national standard GB/T 15089-2001 supports this trend, with the market for lightweight assemblies projected to grow as manufacturers respond to consumer demand.
- Transition to Electric Vehicle Manufacturing: Since 2020, the focus on electric vehicle production has intensified, with a target of 20% of new vehicle sales being electric by 2025. This shift is driving demand for innovative chassis solutions across the industry, aligning with sustainability goals.
- Emergence of Smart Manufacturing Practices: The automotive industry is undergoing a digital transformation, with smart manufacturing initiatives gaining traction. In 2023, the government allocated 10 billion RMB for EV infrastructure, promoting advanced production technologies that streamline operations.
- Prioritisation of Safety Standards in Vehicle Design: The establishment of the Automotive Industry Standardization Technical Committee in 2021 has led to stricter safety regulations. This prioritisation is influencing manufacturers to invest in high rigidity components, ensuring compliance with evolving standards.
Investment Opportunities in the China Vehicle Body Shell and Chassis Assemblies Market
Several openings in the China Vehicle Body Shell and Chassis Assemblies Market merit attention from investors.
- Partnerships with Electric Vehicle Startups: Now is the ideal time to form joint ventures with electric vehicle startups, which are rapidly expanding. With over 300 startups in China, there is a growing demand for advanced chassis solutions that meet new standards.
- Investment in Advanced Manufacturing Technologies: The current focus on innovation presents opportunities for investment in advanced manufacturing technologies. The 'Made in China 2025' initiative encourages firms to adopt modern production methods that improve efficiency and competitiveness.
- Expansion of Production Facilities in Jiangsu Province: Jiangsu province is a major hub for vehicle manufacturing, making it a prime location for new production facilities. Collaborating with local manufacturers can improve market entry and enhance supply chain logistics.
- Supply of Lightweight Assemblies to Passenger Car Makers: With the increasing demand for fuel-efficient vehicles, supplying lightweight assemblies to passenger car makers is a lucrative opportunity. This segment is the largest consumer of vehicle body assemblies, driving significant market growth.
Government Initiatives in the China Vehicle Body Shell and Chassis Assemblies Market
The '14th Five-Year Plan for the Automotive Industry' launched in 2021 aims to promote innovation and sustainability in vehicle manufacturing. This plan encourages manufacturers to invest in new technologies and processes, improving the quality of vehicle body assemblies. The focus on electric vehicles aligns with national goals for reducing emissions and enhancing competitiveness in the automotive sector. By creating a supportive environment, the government is driving growth in the Vehicle Body Shell and Chassis Assemblies market.
The Ministry of Industry and Information Technology oversees the implementation of the 'New Energy Vehicle Industry Development Plan' introduced in 2020. This plan targets 20% of total vehicle sales to be electric by 2025, providing funding and support for manufacturers transitioning to electric vehicle production. Additionally, the National Development and Reform Commission has approved subsidy programs for electric vehicle manufacturers, promoting domestic production and innovation. These initiatives create a conducive environment for the growth of the Vehicle Body Shell and Chassis Assemblies market.
Future Insight of the China Vehicle Body Shell and Chassis Assemblies Market
By 2032, the China Vehicle Body Shell and Chassis Assemblies Market will undergo transformative changes driven by key factors. A government investment of 10 billion RMB in electric vehicle infrastructure will enhance production capabilities across the industry. The shift towards lightweight materials will improve vehicle performance and safety, appealing to manufacturers and consumers alike. The ongoing digital transformation will optimise manufacturing processes, allowing suppliers to respond swiftly to market demands. Moreover, the rise of over 300 electric vehicle startups will foster innovation and competition, reshaping the market landscape.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Assembly Type – Monocoque Body Shells Dominated, Space Frame Structures Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, in 2025, Monocoque Body Shells led the assembly type split with a 38% share. Monocoque Body Shells hold the largest share due to their critical role in ensuring the structural integrity and safety of the majority of passenger vehicles produced in China. The high production volume in regions like Jiangsu province reinforces their dominance in the market. Over 2026–2032, Space Frame Structures are expected to post the fastest growth, at a CAGR of 8.1%. Space Frame Structures are experiencing rapid growth as they cater to the niche market of high-performance vehicles, which are increasingly popular among consumers. The emergence of electric vehicle startups focusing on performance-oriented designs is a key driver of this trend. Suppliers should focus on strengthening their Monocoque Body Shell offerings while also exploring the expanding opportunities within the Space Frame Structures market.
By Frame Type – Unibody Dominated, Lightweight Expected to Grow Fastest
Unibody took a 45% share of frame type in 2025, more than any other category. Unibody designs hold the largest market share as they are extensively used in passenger vehicles, ensuring both structural integrity and safety. The installed base of over 300 million passenger vehicles in China reinforces the dominance of this frame type. Lightweight is projected to grow fastest, at a CAGR of 8.1% during 2026–2032. Lightweight frames are experiencing rapid growth driven by the increasing demand for fuel efficiency, particularly as manufacturers strive to meet government targets for electric vehicle sales. This trend highlights the automotive industry's shift towards sustainability and innovation. Manufacturers must adapt to the rising preference for Lightweight frames to stay competitive and align with fuel efficiency trends.
By Integration Type – Factory Integrated Dominated, Modular Expected to Grow Fastest
With a 46% revenue share in 2025, Factory Integrated was the largest integration type category. Factory Integrated systems lead the market share as they are common in mass production, ensuring efficiency and consistency in vehicle assembly. This method is particularly prevalent in the automotive hubs of Guangdong and Jiangsu provinces. Modular is set to record the highest CAGR in this split, 8.5% over 2026–2032. Modular integration is rapidly growing as it facilitates flexible manufacturing processes, enabling manufacturers to adapt quickly to market changes. The trend towards modular systems aligns with the industry's digital transformation initiatives. Suppliers should invest in modular technologies to meet the evolving demands of manufacturers seeking flexibility and efficiency.
By End User – Passenger Car Makers Dominated, Electric Vehicle Startups Expected to Grow Fastest
The largest end user category in 2025 was Passenger Car Makers, with a 40% share of total revenue. Passenger Car Makers dominate the market as they are the largest consumers of vehicle body assemblies, producing over 27 million units annually. Their significant presence in the automotive sector translates into a substantial market share for this segment. The quickest growth will come from Electric Vehicle Startups, forecast to expand at a CAGR of 8.5% between 2026 and 2032. Electric Vehicle Startups represent the fastest-growing segment, highlighting a shift towards innovation and sustainability in the automotive landscape. The government's backing for electric vehicle initiatives is propelling this segment's growth, offering new avenues for suppliers. Suppliers should seek to establish partnerships with Electric Vehicle Startups to leverage the rapid growth and innovative potential of this emerging segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Vehicle Body Shell and Chassis Assemblies Market Outlook
- Market Size of China Vehicle Body Shell and Chassis Assemblies Market, 2025
- Forecast of China Vehicle Body Shell and Chassis Assemblies Market, 2032
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Revenues & Volume for the Period 2022 - 2032F
- China Vehicle Body Shell and Chassis Assemblies Market Trend Evolution
- China Vehicle Body Shell and Chassis Assemblies Market Drivers and Challenges
- China Vehicle Body Shell and Chassis Assemblies Price Trends
- China Vehicle Body Shell and Chassis Assemblies Porter's Five Forces
- China Vehicle Body Shell and Chassis Assemblies Industry Life Cycle
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Assembly Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Monocoque Body Shells for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Ladder Frame Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Tubular Chassis for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Space Frame Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Frame Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Unibody for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Separate Chassis for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Lightweight for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By High Rigidity for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Integration Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Factory Integrated for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Modular for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Custom Build for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Robotic Welding for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Passenger Car Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Commercial Vehicle OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Racing Vehicle Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Shell and Chassis Assemblies Market Revenues & Volume By Electric Vehicle Startups for the Period 2022 - 2032F
- China Vehicle Body Shell and Chassis Assemblies Import Export Trade Statistics
- Market Opportunity Assessment By Assembly Type
- Market Opportunity Assessment By Frame Type
- Market Opportunity Assessment By Integration Type
- Market Opportunity Assessment By End User
- China Vehicle Body Shell and Chassis Assemblies Top Companies Market Share
- China Vehicle Body Shell and Chassis Assemblies Competitive Benchmarking By Technical and Operational Parameters
- China Vehicle Body Shell and Chassis Assemblies Company Profiles
- China Vehicle Body Shell and Chassis Assemblies Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Assembly Type
- Monocoque Body Shells
- Ladder Frame Assemblies
- Tubular Chassis
- Space Frame Structures
By Frame Type
- Unibody
- Separate Chassis
- Lightweight
- High Rigidity
By Integration Type
- Factory Integrated
- Modular
- Custom Build
- Robotic Welding
By End User
- Passenger Car Makers
- Commercial Vehicle OEMs
- Racing Vehicle Manufacturers
- Electric Vehicle Startups































