Global Nephrology and Urology Devices Market (2026-2032) | Pricing Analysis, Size, Trends, Segmentation, Restraints, Consumer Insights, Strategic Insights, Supply, Analysis, Segments, Demand, Competition, Strategy, Opportunities, Investment Trends, Forecast, Companies, Industry, Share, Competitive, Value, Outlook, Revenue, Drivers, Challenges, Growth
Market Forecast by Regions and Countries (North America, Europe, LATAM, Middle East, Asia and Africa), By Product (Instruments, Consumables and Accessories), By Applications (Kidney Diseases, Urological Cancer and BPH, Others), By End User (Hospitals, Dialysis Centers, Others) And Competitive Landscape
| Product Code: ETC13148812 | Publication Date: Apr 2025 | Updated Date: Sep 2026 | Product Type: Market Research Report | |
| Publisher: 6Wresearch | Author: Sachin Kumar Rai | No. of Pages: 190 | No. of Figures: 80 | No. of Tables: 40 |
Global Nephrology and Urology Devices Market Highlights
| Market Size (2025) | USD 14 Billion |
| Forecast Size (2032) | USD 19 Billion |
| CAGR | 5.90% |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Largest Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Largest Segment | Instruments |
| Fastest Growing Segment | Consumables |
| Leading Companies | Fresenius Medical Care, Baxter International, Boston Scientific, C.R. Bard, Medtronic |
Global Nephrology and Urology Devices Market Size & Growth Rate (2026-2032)
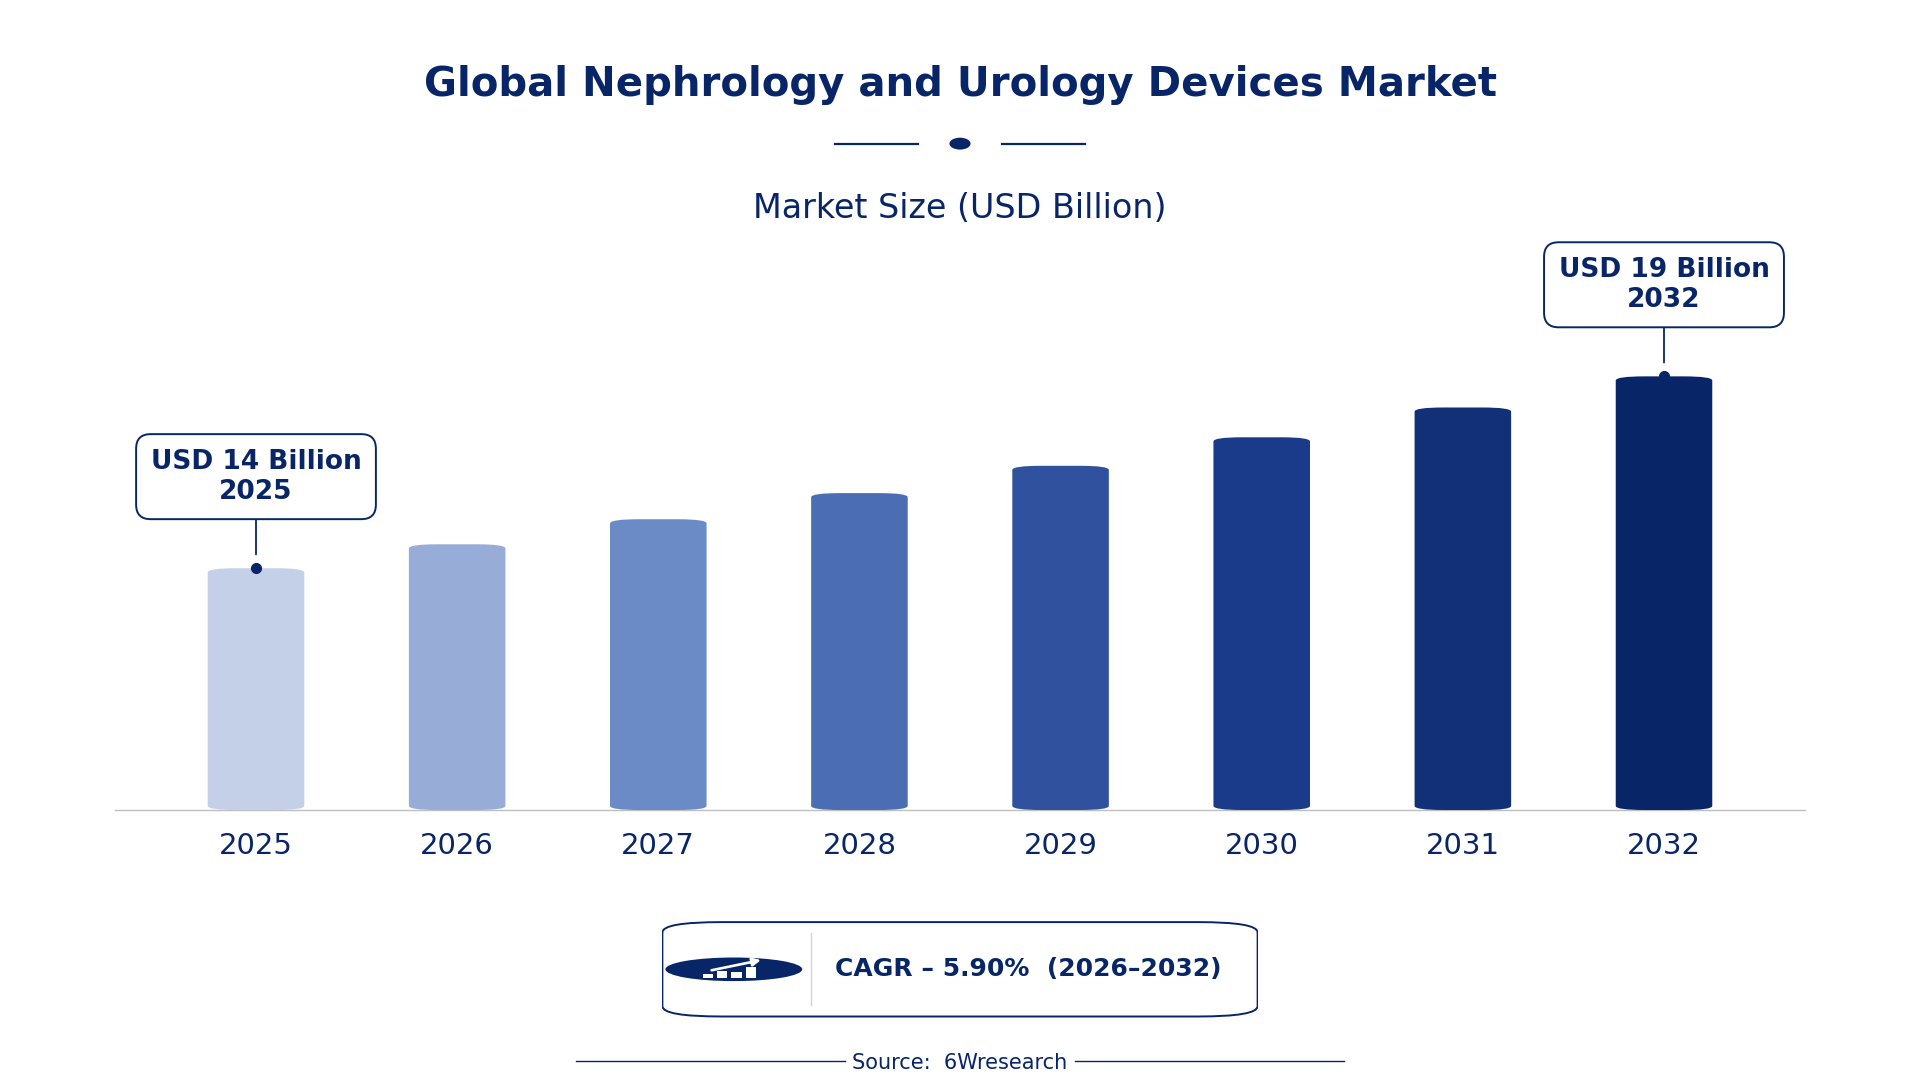
The Global Nephrology and Urology Devices Market was estimated at USD 14 Billion in 2025 and is projected to reach USD 19 Billion by 2032, growing at a CAGR of 5.90% from 2026 to 2032.
Global Nephrology and Urology Devices Market Synopsis
Currently, the Global Nephrology and Urology Devices Market is encountering significant dynamics, fueled primarily by a marked increase in chronic kidney diseases and urological disorders. This upturn is not merely driven by rising patient numbers, but also reflects an expanded healthcare ecosystem focusing on innovative diagnostic and therapeutic devices.
Furthermore, emerging markets are showing a heightened commitment to improving healthcare infrastructure, creating a fertile ground for growth in nephrology and urology sectors. Enhanced awareness about kidney health, coupled with burgeoning interest in minimally invasive procedures, differentiates this market from related sectors, offering specialized focus and opportunity for dedicated manufacturers.
Global Nephrology and Urology Devices Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Global Nephrology and Urology Devices Market from 2022 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
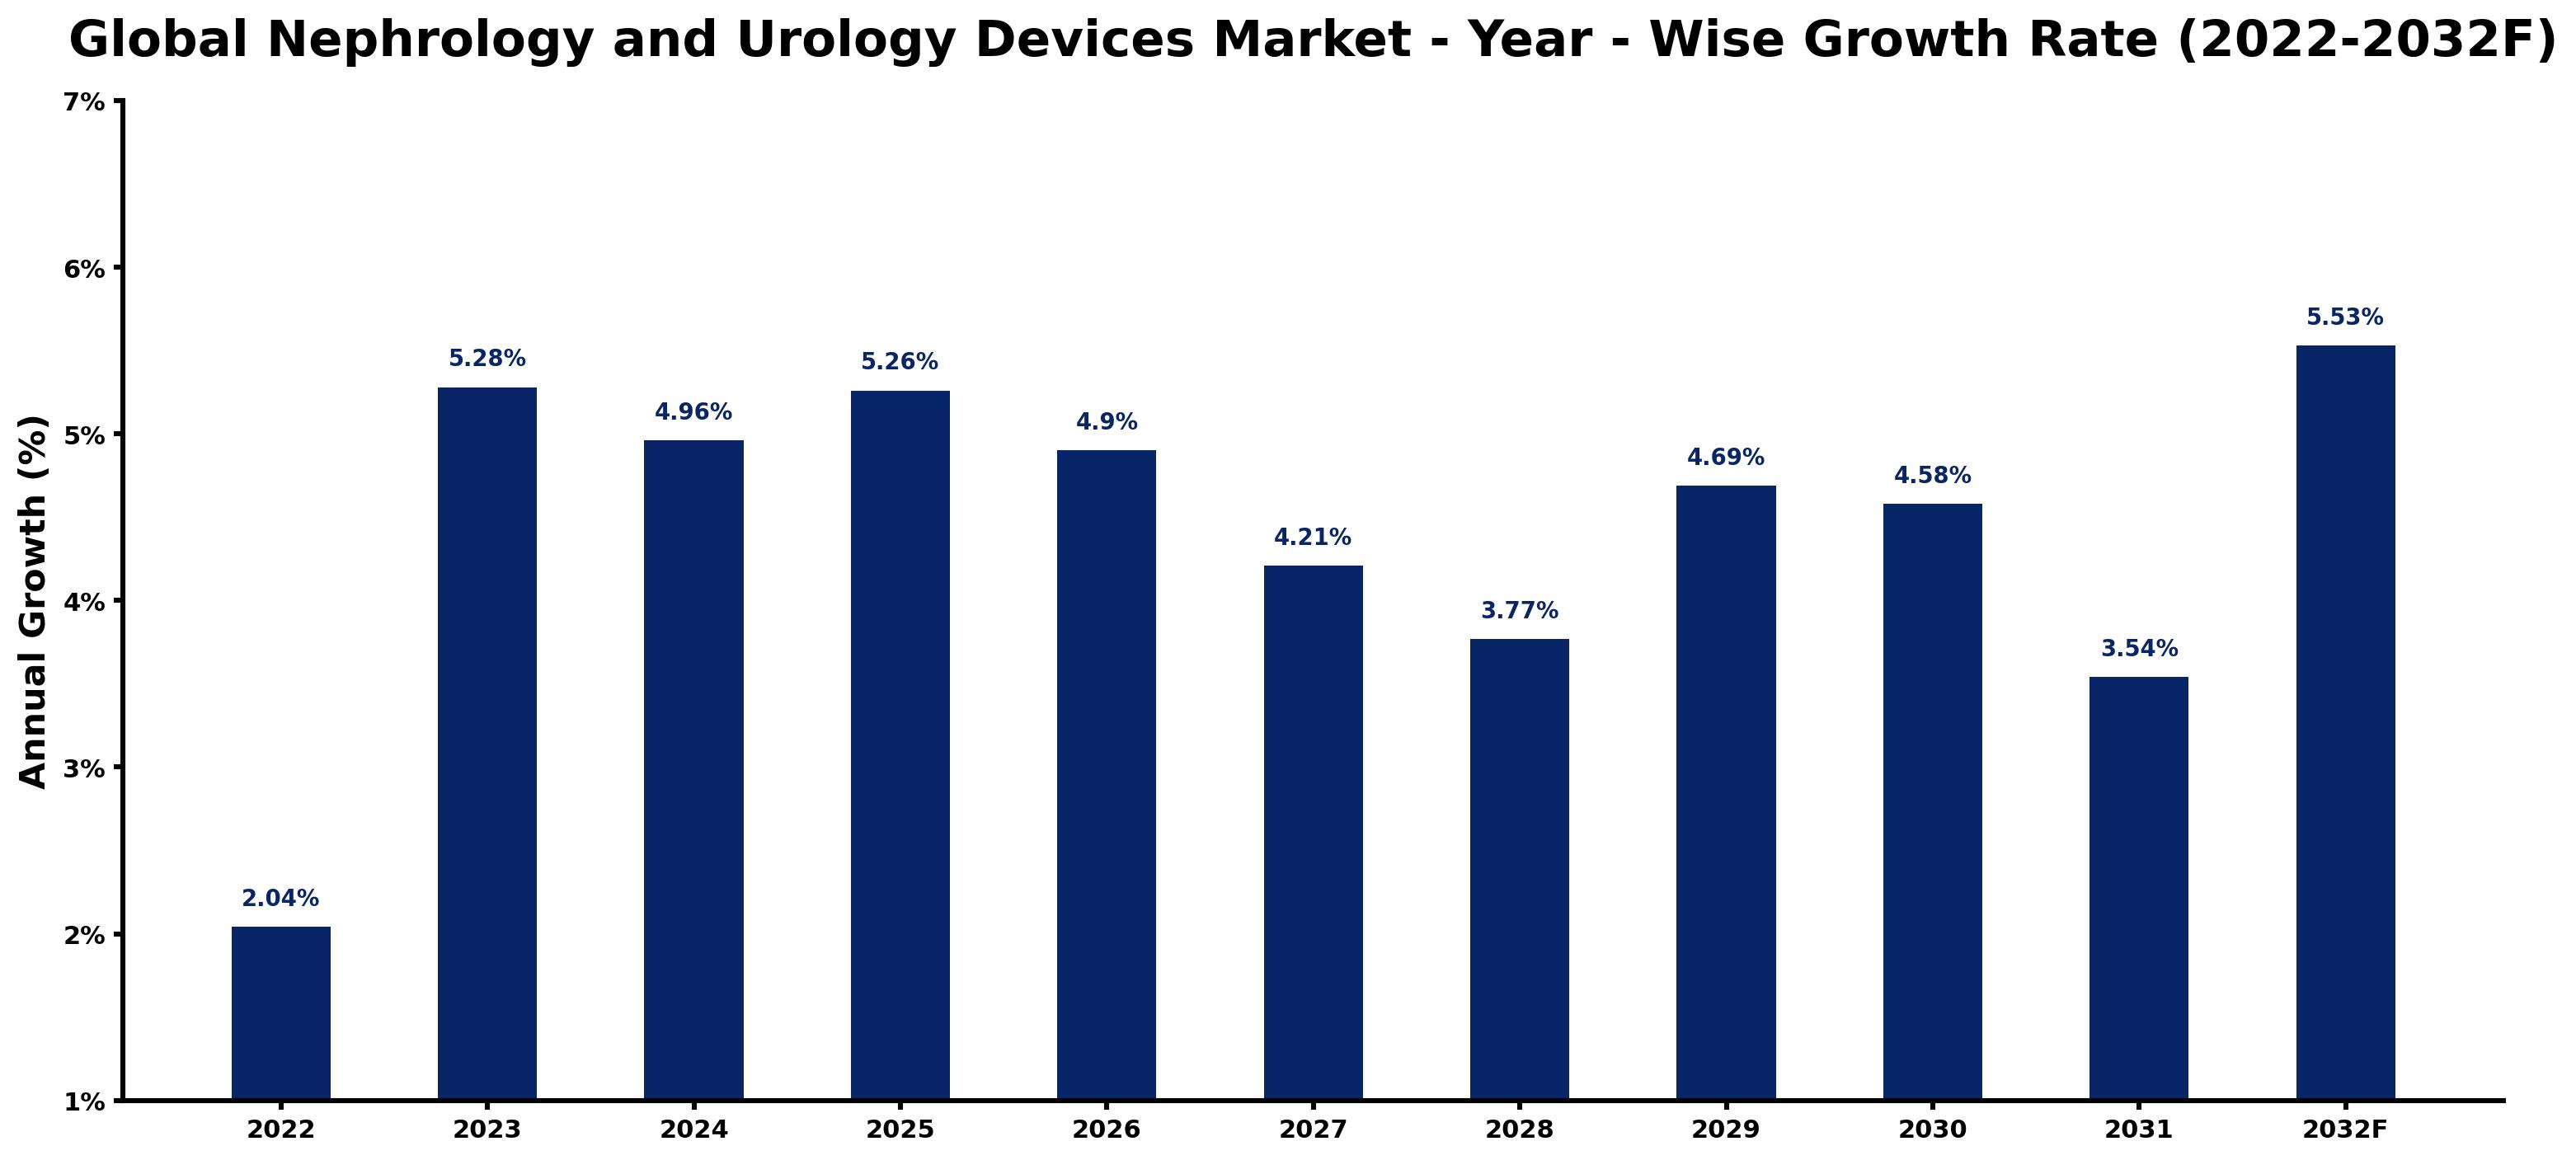
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate (%) | Major Drivers |
| 2022 | 2.04 | Increasing patient awareness leads to higher adoption of nephrology and urology devices. |
| 2023 | 5.28 | Healthcare providers optimize supply chain logistics for nephrology and urology device distribution. |
| 2024 | 4.96 | While competition among nephrology device manufacturers intensifies, innovation plays a crucial role. |
| 2025 | 5.26 | A shift toward strategic partnerships accelerates investment in nephrology and urology device development. |
| 2026 | 4.9 | Wearable monitoring devices are gaining traction among patients managing chronic kidney disease. |
| 2027 | 4.21 | Healthcare systems expand telehealth platforms to enhance access to urology services. |
| 2028 | 3.77 | Enhancing staff training initiatives improves effectiveness in nephrology and urology device utilization. |
| 2029 | 4.69 | In the United States, updated reimbursement policies enhance adoption of advanced urology technologies. |
| 2030 | 4.58 | Manufacturers prioritize sustainability in nephrology devices to meet emerging regulatory standards. |
| 2031 | 3.54 | Growing sophistication in diagnostic imaging technologies enhances nephrology and urology applications. |
| 2032 | 5.53 | Rising costs of raw materials necessitate innovative approaches in nephrology device production. |
Note - Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary research methodology, combining internal industry data, secondary research, and primary validation, updated periodically to reflect current market conditions. As markets evolve rapidly, figures for certain industries may vary slightly and are intended as informed estimates rather than absolute figures. For the most current market sizing, we recommend validating figures with a 6Wresearch analyst.
Global Nephrology and Urology Devices Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- The prevalence of kidney diseases is expected to escalate, contributing to a projected market share of approximately 43% by 2025 for instruments.
- In Asia-Pacific, healthcare expenditures are on track to increase by 8% annually, bolstering investment in nephrology and urology devices.
- Robotic-assisted surgical systems for urology have gained traction, with adoption rates increasing by 15% per year in leading hospitals since 2023.
- Baxter International's novel dialysis device, launched in 2024, is expected to capture an additional 3% market share in the consumables segment by 2026.
Evaluation of Restraints in Global Nephrology and Urology Devices Market
Despite its potential, the Global Nephrology and Urology Devices Market faces formidable challenges. Regulatory hurdles are prominent, with the FDA imposing stringent requirements that can delay product approvals by up to 18 months, impacting both revenue timelines and innovation capabilities. For example, the recent rejection of several renal stent approvals has raised concerns among manufacturers about regulatory transparency and consistency, which can deter investment in new technologies.
Global Nephrology and Urology Devices Market Trends
Several distinctive trends are reshaping the Global Nephrology and Urology Devices Market. One significant trend is the integration of advanced digital diagnostics within nephrology devices. Companies like Medtronic are pioneering products equipped with IoT capabilities, facilitating real-time monitoring and enhancing patient outcomes. For instance, their Smart Dialysis System, expected to launch in late 2026, will allow healthcare providers to adjust treatment protocols remotely.
Moreover, robotic-assisted surgeries have started to redefine procedural standards in urology. In 2023, Boston Scientific reported a 20% year-over-year increase in robotic system adoption in major surgical centers, thereby streamlining operational efficiencies. Lastly, a greater emphasis on patient-centric design is emerging, with devices increasingly tailored to improve user experience and accessibility, indicating a crucial shift in customer behavior.
Global Nephrology and Urology Devices Market Opportunities
The landscape for emerging revenue opportunities within the Global Nephrology and Urology Devices Market is rich. One notable domain is the integration of artificial intelligence in diagnostic tools. Companies such as C.R. Bard are investing heavily in AI-driven analytics that aim to enhance early detection of nephrological issues, with market estimates indicating an influx of $500 million in investment by 2027.
Additionally, the rise of telemedicine is expanding access to specialists in nephrology, particularly in under-served regions. For example, tele-nephrology initiatives in India have demonstrated a 30% increase in patient engagement since 2023, thereby presenting a viable avenue for service providers looking to leverage remote technologies. Private equity in medical device startups focusing on minimally invasive urological products is also anticipated to surge, enhancing competitive dynamics and fostering a strong growth environment.
Global Nephrology and Urology Devices Market by Product
The Global Nephrology and Urology Devices Market is predominantly led by instruments, which hold a market share of approximately 43% in 2025. This segment benefits from high demand for advanced diagnostic and treatment options, as healthcare providers prioritize performance and reliability. Notably, consumables are expected to emerge as the fastest-growing segment, projected to experience a CAGR of 6.5% from 2026 to 2032, driven by rising demand for disposable catheters and dialysis supplies, particularly in developing regions where healthcare access is improving.
Global Nephrology and Urology Devices Market by Applications
Within the applications of the Global Nephrology and Urology Devices Market, kidney diseases command the largest share, approximately 50% in 2025. This dominance is attributed to the escalating prevalence of conditions such as chronic kidney disease, which significantly affects global health outcomes. Furthermore, the segment focusing on urological cancer and BPH is anticipated to grow at a CAGR of 6.8% from 2026 to 2032, fueled by an increasing incidence of cancers and the high demand for related treatment innovations.
Global Nephrology and Urology Devices Market by End User
In the end-user landscape, hospitals are poised to lead, commanding around 65% market share in 2025. This significant portion reflects the preference for sophisticated medical equipment and technologies integral to patient care. Conversely, dialysis centers represent the fastest-growing segment, with an impressive CAGR of 7.2% from 2026 to 2032, attributable to rising patient volumes requiring specialized nephrology services, making them critical hubs for treatment innovation and device utilization.
Global Nephrology and Urology Devices Market by Region
North America currently dominates the Global Nephrology and Urology Devices Market, holding a substantial share of approximately 47% in 2025. This is largely driven by high healthcare expenditure, advanced technology adoption, and a well-established healthcare infrastructure. Conversely, the Asia-Pacific region is projected to be the fastest-growing, with a CAGR of 7.5% from 2026 to 2032, supported by rising healthcare investments and a burgeoning patient population that mandates advanced medical solutions.
Government Initiatives in the Global Nephrology and Urology Devices Market
The regulatory landscape for the Global Nephrology and Urology Devices Market is becoming increasingly proactive, with various government initiatives aimed at enhancing healthcare accessibility and device innovation. These policies are designed not only to promote advancements but also to ensure that manufacturers meet safety and efficacy standards, thereby fostering greater public trust in medical technologies.
- U.S. Department of Health and Human Services: "Medicare Coverage for New Dialysis Devices," released July 2023. This initiative improves reimbursement policies, facilitating broader access to dialysis technologies for patients.
- European Commission: "Regulation (EU) 2017/745 on Medical Devices," effective May 2024. This regulation emphasizes stricter compliance guidelines for device manufacturers, aimed at enhancing patient safety.
- National Health Service (NHS), UK: "Investment in Nephrology Services 2025-2030," announced March 2022, with a funding allocation of £500 million to boost dialysis and urology facilities.
- Ministry of Health, India: "National Dialysis Program," scheduled for implementation in 2026, aimed at deploying dialysis units across rural areas to promote equitable healthcare access.
Future Insights of the Global Nephrology and Urology Devices Market
The landscape of the Global Nephrology and Urology Devices Market is shifting toward enhanced personalization and digital integration. Companies are likely to focus on developing AI-driven solutions for early disease detection, as evidenced by C.R. Bard’s recent investments in AI technologies aimed at improving diagnostic accuracy. Furthermore, the increasing adoption of telemedicine signifies a structural change in patient-provider interactions, potentially redefining service delivery models. Projections indicate a strengthened focus on minimally invasive procedures, further aligning with patient preferences and improving recovery times.
Global Nephrology and Urology Devices Market Latest Developments
Several significant developments are shaping the Global Nephrology and Urology Devices Market. Each of these advancements plays a critical role in enhancing operational capabilities and competitive positions.
- Baxter International recently launched a next-generation dialysis product, expected to improve patient outcomes and operational efficiencies, marking a substantial technical advancement in late 2023.
- In 2024, Medtronic announced ongoing trials for its Smart Dialysis System, integrating IoT for real-time monitoring, which is anticipated to redefine treatment protocols and enhance patient monitoring.
- Boston Scientific is set to unveil an innovative robotic surgical system in early 2025, aimed at improving precision in urological surgeries and catering to the rising demand for robotic-assisted procedures.
- Recently, Fresenius Medical Care expanded its manufacturing capacity for renal device production in Asia-Pacific, reflecting its strategy to penetrate emerging markets and meet increasing regional healthcare needs.
Global Nephrology and Urology Devices Market Key Players and Industry Positioning
The Global Nephrology and Urology Devices Market is characterized by a mix of consolidated and fragmented components, featuring major players alongside emerging startups. While established companies dominate with robust product portfolios and technology leadership, smaller firms are innovating, particularly in specialized niches.
| Leading Company | Core Strength | Strategic Focus |
|---|---|---|
| Fresenius Medical Care | Expertise in renal therapies with a vast global reach | Expansion in emerging markets to address increasing healthcare demands |
| Baxter International | Strong presence in dialysis with continuous product innovation | Development of advanced dialysis solutions to enhance patient care |
| Boston Scientific | Leadership in minimally invasive surgical technologies | Investment in robotic surgical systems to improve precision |
| C.R. Bard | Advanced catheter technologies and specialty products | Innovative use of AI for enhanced diagnostics and treatment |
| Medtronic | Pioneering in smart healthcare technologies | Integration of IoT and data analytics in medical devices |
With the growing emphasis on advanced technology and patient-centric solutions, these companies are strategically positioned to leverage emerging trends while also addressing the evolving needs of healthcare professionals and patients alike.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global Nephrology and Urology Devices Market Outlook
- Market Size of Global Nephrology and Urology Devices Market, 2025
- Forecast of Global Nephrology and Urology Devices Market, 2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Revenues & Volume for the Period 2022-2032
- Global Nephrology and Urology Devices Market Trend Evolution
- Global Nephrology and Urology Devices Market Drivers and Challenges
- Global Nephrology and Urology Devices Price Trends
- Global Nephrology and Urology Devices Porter's Five Forces
- Global Nephrology and Urology Devices Industry Life Cycle
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Product for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Instruments for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Consumables and Accessories for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Applications for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Kidney Diseases for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Urological Cancer and BPH for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Hospitals for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Dialysis Centers for the Period 2022-2032
- Historical Data and Forecast of Global Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Product for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Instruments for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Consumables and Accessories for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Applications for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Kidney Diseases for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Urological Cancer and BPH for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Hospitals for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Dialysis Centers for the Period 2022-2032
- Historical Data and Forecast of North America Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United States of America Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Canada Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of North America Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Product for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Instruments for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Consumables and Accessories for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Applications for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Kidney Diseases for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Urological Cancer and BPH for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Hospitals for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Dialysis Centers for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Brazil Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Mexico Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Argentina Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of LATAM Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Product for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Instruments for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Consumables and Accessories for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Applications for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Kidney Diseases for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Urological Cancer and BPH for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Hospitals for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Dialysis Centers for the Period 2022-2032
- Historical Data and Forecast of Asia Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of China Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of India Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Japan Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Asia Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Product for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Instruments for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Consumables and Accessories for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Applications for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Kidney Diseases for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Urological Cancer and BPH for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Hospitals for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Dialysis Centers for the Period 2022-2032
- Historical Data and Forecast of Africa Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of South Africa Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Nigeria Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Egypt Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Africa Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Product for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Instruments for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Consumables and Accessories for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Applications for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Kidney Diseases for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Urological Cancer and BPH for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Hospitals for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Dialysis Centers for the Period 2022-2032
- Historical Data and Forecast of Europe Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United Kingdom Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of France Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Germany Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Europe Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Product for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Instruments for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Consumables and Accessories for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Applications for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Kidney Diseases for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Urological Cancer and BPH for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Hospitals for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Dialysis Centers for the Period 2022-2032
- Historical Data and Forecast of Middle East Nephrology and Urology Devices Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Saudi Arabia Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of UAE Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Turkey Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Middle East Nephrology and Urology Devices Market Revenues & Volume for the Period 2022-2032
- Global Nephrology and Urology Devices Market - Key Performance Indicators
- Global Nephrology and Urology Devices Market - Import Export Trade Statistics
- Global Nephrology and Urology Devices Market - Opportunity Assessment By Countries
- Global Nephrology and Urology Devices Market - Opportunity Assessment By Product
- Global Nephrology and Urology Devices Market - Opportunity Assessment By Applications
- Global Nephrology and Urology Devices Market - Opportunity Assessment By End User
- Global Nephrology and Urology Devices Market - Top Companies Market Share
- Global Nephrology and Urology Devices Market - Top Companies Profiles
- Global Nephrology and Urology Devices Market - Comparison of Players in Technical and Operating Parameters
- Global Nephrology and Urology Devices Market - Strategic Recommendations
Markets Covered
The Global Nephrology and Urology Devices Market report provides a detailed analysis of the following market segments:
By Regions and Countries:
- North America
- Europe
- LATAM
- Middle East
- Asia
- Africa
By Product:
- Instruments
- Consumables
- Accessories
By Applications:
- Kidney Diseases
- Urological Cancer
- BPH
- Others
By End User:
- Hospitals
- Dialysis Centers
- Others
Global Nephrology and Urology Devices Market - Frequently Asked Questions
The Global Nephrology and Urology Devices Market is projected to reach USD 19 Billion by 2032.
The estimated CAGR for the Global Nephrology and Urology Devices Market is 5.90% from 2026 to 2032.
The growth is primarily driven by the rising prevalence of chronic kidney diseases, technological advancements in minimally invasive procedures, and increased healthcare spending in emerging markets.
Key restraints include stringent regulatory requirements which can delay product approval processes and limit innovation capabilities.
Instruments lead the market share, while consumables represent the fastest-growing segment, reflecting the increased demand for disposable medical supplies.
The future outlook shows potential growth in AI integration, personalized treatments, and telehealth advancements, paving the way for innovative patient care solutions.
6Wresearch actively monitors the Global Nephrology and Urology Devices Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Global Nephrology and Urology Devices Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
Global Nephrology and Urology Devices Market |
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Global Nephrology and Urology Devices Market Overview |
3.1 Global Regional Macro Economic Indicators |
3.2 Global Nephrology and Urology Devices Market Revenues & Volume, 2022 & 2032F |
3.3 Global Nephrology and Urology Devices Market - Industry Life Cycle |
3.4 Global Nephrology and Urology Devices Market - Porter's Five Forces |
3.5 Global Nephrology and Urology Devices Market Revenues & Volume Share, By Regions, 2022 & 2032F |
3.6 Global Nephrology and Urology Devices Market Revenues & Volume Share, By Product, 2022 & 2032F |
3.7 Global Nephrology and Urology Devices Market Revenues & Volume Share, By Applications, 2022 & 2032F |
3.8 Global Nephrology and Urology Devices Market Revenues & Volume Share, By End User, 2022 & 2032F |
4 Global Nephrology and Urology Devices Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.3 Market Restraints |
5 Global Nephrology and Urology Devices Market Trends |
6 Global Nephrology and Urology Devices Market, 2022-2032 |
6.1 Global Nephrology and Urology Devices Market, Revenues & Volume, By Product, 2022-2032 |
6.1.1 Overview & Analysis |
6.1.2 Global Nephrology and Urology Devices Market, Revenues & Volume, By Instruments, 2022-2032 |
6.1.3 Global Nephrology and Urology Devices Market, Revenues & Volume, By Consumables and Accessories, 2022-2032 |
6.2 Global Nephrology and Urology Devices Market, Revenues & Volume, By Applications, 2022-2032 |
6.2.1 Overview & Analysis |
6.2.2 Global Nephrology and Urology Devices Market, Revenues & Volume, By Kidney Diseases, 2022-2032 |
6.2.3 Global Nephrology and Urology Devices Market, Revenues & Volume, By Urological Cancer and BPH, 2022-2032 |
6.2.4 Global Nephrology and Urology Devices Market, Revenues & Volume, By Others, 2022-2032 |
6.3 Global Nephrology and Urology Devices Market, Revenues & Volume, By End User, 2022-2032 |
6.3.1 Overview & Analysis |
6.3.2 Global Nephrology and Urology Devices Market, Revenues & Volume, By Hospitals, 2022-2032 |
6.3.3 Global Nephrology and Urology Devices Market, Revenues & Volume, By Dialysis Centers, 2022-2032 |
6.3.4 Global Nephrology and Urology Devices Market, Revenues & Volume, By Others, 2022-2032 |
7 North America Nephrology and Urology Devices Market, Overview & Analysis |
7.1 North America Nephrology and Urology Devices Market Revenues & Volume, 2022-2032 |
7.2 North America Nephrology and Urology Devices Market, Revenues & Volume, By Countries, 2022-2032 |
7.2.1 United States (US) Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
7.2.2 Canada Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
7.2.3 Rest of North America Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
7.3 North America Nephrology and Urology Devices Market, Revenues & Volume, By Product, 2022-2032 |
7.4 North America Nephrology and Urology Devices Market, Revenues & Volume, By Applications, 2022-2032 |
7.5 North America Nephrology and Urology Devices Market, Revenues & Volume, By End User, 2022-2032 |
8 Latin America (LATAM) Nephrology and Urology Devices Market, Overview & Analysis |
8.1 Latin America (LATAM) Nephrology and Urology Devices Market Revenues & Volume, 2022-2032 |
8.2 Latin America (LATAM) Nephrology and Urology Devices Market, Revenues & Volume, By Countries, 2022-2032 |
8.2.1 Brazil Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
8.2.2 Mexico Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
8.2.3 Argentina Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
8.2.4 Rest of LATAM Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
8.3 Latin America (LATAM) Nephrology and Urology Devices Market, Revenues & Volume, By Product, 2022-2032 |
8.4 Latin America (LATAM) Nephrology and Urology Devices Market, Revenues & Volume, By Applications, 2022-2032 |
8.5 Latin America (LATAM) Nephrology and Urology Devices Market, Revenues & Volume, By End User, 2022-2032 |
9 Asia Nephrology and Urology Devices Market, Overview & Analysis |
9.1 Asia Nephrology and Urology Devices Market Revenues & Volume, 2022-2032 |
9.2 Asia Nephrology and Urology Devices Market, Revenues & Volume, By Countries, 2022-2032 |
9.2.1 India Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
9.2.2 China Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
9.2.3 Japan Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
9.2.4 Rest of Asia Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
9.3 Asia Nephrology and Urology Devices Market, Revenues & Volume, By Product, 2022-2032 |
9.4 Asia Nephrology and Urology Devices Market, Revenues & Volume, By Applications, 2022-2032 |
9.5 Asia Nephrology and Urology Devices Market, Revenues & Volume, By End User, 2022-2032 |
10 Africa Nephrology and Urology Devices Market, Overview & Analysis |
10.1 Africa Nephrology and Urology Devices Market Revenues & Volume, 2022-2032 |
10.2 Africa Nephrology and Urology Devices Market, Revenues & Volume, By Countries, 2022-2032 |
10.2.1 South Africa Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
10.2.2 Egypt Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
10.2.3 Nigeria Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
10.2.4 Rest of Africa Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
10.3 Africa Nephrology and Urology Devices Market, Revenues & Volume, By Product, 2022-2032 |
10.4 Africa Nephrology and Urology Devices Market, Revenues & Volume, By Applications, 2022-2032 |
10.5 Africa Nephrology and Urology Devices Market, Revenues & Volume, By End User, 2022-2032 |
11 Europe Nephrology and Urology Devices Market, Overview & Analysis |
11.1 Europe Nephrology and Urology Devices Market Revenues & Volume, 2022-2032 |
11.2 Europe Nephrology and Urology Devices Market, Revenues & Volume, By Countries, 2022-2032 |
11.2.1 United Kingdom Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
11.2.2 Germany Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
11.2.3 France Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
11.2.4 Rest of Europe Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
11.3 Europe Nephrology and Urology Devices Market, Revenues & Volume, By Product, 2022-2032 |
11.4 Europe Nephrology and Urology Devices Market, Revenues & Volume, By Applications, 2022-2032 |
11.5 Europe Nephrology and Urology Devices Market, Revenues & Volume, By End User, 2022-2032 |
12 Middle East Nephrology and Urology Devices Market, Overview & Analysis |
12.1 Middle East Nephrology and Urology Devices Market Revenues & Volume, 2022-2032 |
12.2 Middle East Nephrology and Urology Devices Market, Revenues & Volume, By Countries, 2022-2032 |
12.2.1 Saudi Arabia Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
12.2.2 UAE Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
12.2.3 Turkey Nephrology and Urology Devices Market, Revenues & Volume, 2022-2032 |
12.3 Middle East Nephrology and Urology Devices Market, Revenues & Volume, By Product, 2022-2032 |
12.4 Middle East Nephrology and Urology Devices Market, Revenues & Volume, By Applications, 2022-2032 |
12.5 Middle East Nephrology and Urology Devices Market, Revenues & Volume, By End User, 2022-2032 |
13 Global Nephrology and Urology Devices Market Key Performance Indicators |
14 Global Nephrology and Urology Devices Market - Export/Import By Countries Assessment |
15 Global Nephrology and Urology Devices Market - Opportunity Assessment |
15.1 Global Nephrology and Urology Devices Market Opportunity Assessment, By Countries, 2022 & 2032F |
15.2 Global Nephrology and Urology Devices Market Opportunity Assessment, By Product, 2022 & 2032F |
15.3 Global Nephrology and Urology Devices Market Opportunity Assessment, By Applications, 2022 & 2032F |
15.4 Global Nephrology and Urology Devices Market Opportunity Assessment, By End User, 2022 & 2032F |
16 Global Nephrology and Urology Devices Market - Competitive Landscape |
16.1 Global Nephrology and Urology Devices Market Revenue Share, By Companies, 2025 |
16.2 Global Nephrology and Urology Devices Market Competitive Benchmarking, By Operating and Technical Parameters |
17 Top 10 Company Profiles |
18 Recommendations |
19 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 4,560
- Department License$ 5,055
- Site License$ 5,595
- Global License$ 6,000
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Global Whey Protein Market (2025-2031)
- Bahrain Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Azerbaijan Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Australia Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Argentina Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Algeria Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Zimbabwe Vehicle-Grade Aluminum Materials Market (2026-2032)
- Zambia Vehicle-Grade Aluminum Materials Market (2026-2032)
- Yemen Vehicle-Grade Aluminum Materials Market (2026-2032)
- Vanuatu Vehicle-Grade Aluminum Materials Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.