Global Pneumatic Tools for Construction Market (2026-2032) | Growth, Share, Restraints, Consumer Insights, Companies, Segments, Revenue, Size, Pricing Analysis, Investment Trends, Opportunities, Outlook, Demand, Analysis, Industry, Value, Strategic Insights, Forecast, Drivers, Trends, Competition, Supply, Competitive, Strategy, Challenges, Segmentation
Market Forecast by Regions and Countries (North America, Europe, LATAM, Middle East, Asia and Africa), By Type (Nail Guns, Drills, Grinders, Sanders, Others), By Power Source (Compressed Air, Electric, Battery, Gasoline, Others), By End User (Construction, Manufacturing, Mining, Automotive, Others), By Application (Framing & Roofing, Drilling & Fastening, Cutting & Shaping, Surface Finishing, Others) And Competitive Landscape
| Product Code: ETC13346187 | Publication Date: Apr 2025 | Updated Date: Sep 2026 | Product Type: Market Research Report | |
| Publisher: 6Wresearch | Author: Shubham Deep | No. of Pages: 190 | No. of Figures: 80 | No. of Tables: 40 |
Global Pneumatic Tools for Construction Market Highlights
| Market Size (2025) | USD 5.1 Billion |
| Forecast Size (2032) | USD 7.5 Billion |
| CAGR | 5.81% |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Largest Region | North America |
| Fastest Growing Region | Asia |
| Largest Segment | Nail Guns |
| Fastest Growing Segment | Drills |
| Leading Companies | DeWalt, Bosch, Makita, Ingersoll Rand, Hitachi |
Global Pneumatic Tools for Construction Market Size & Growth Rate (2026-2032)
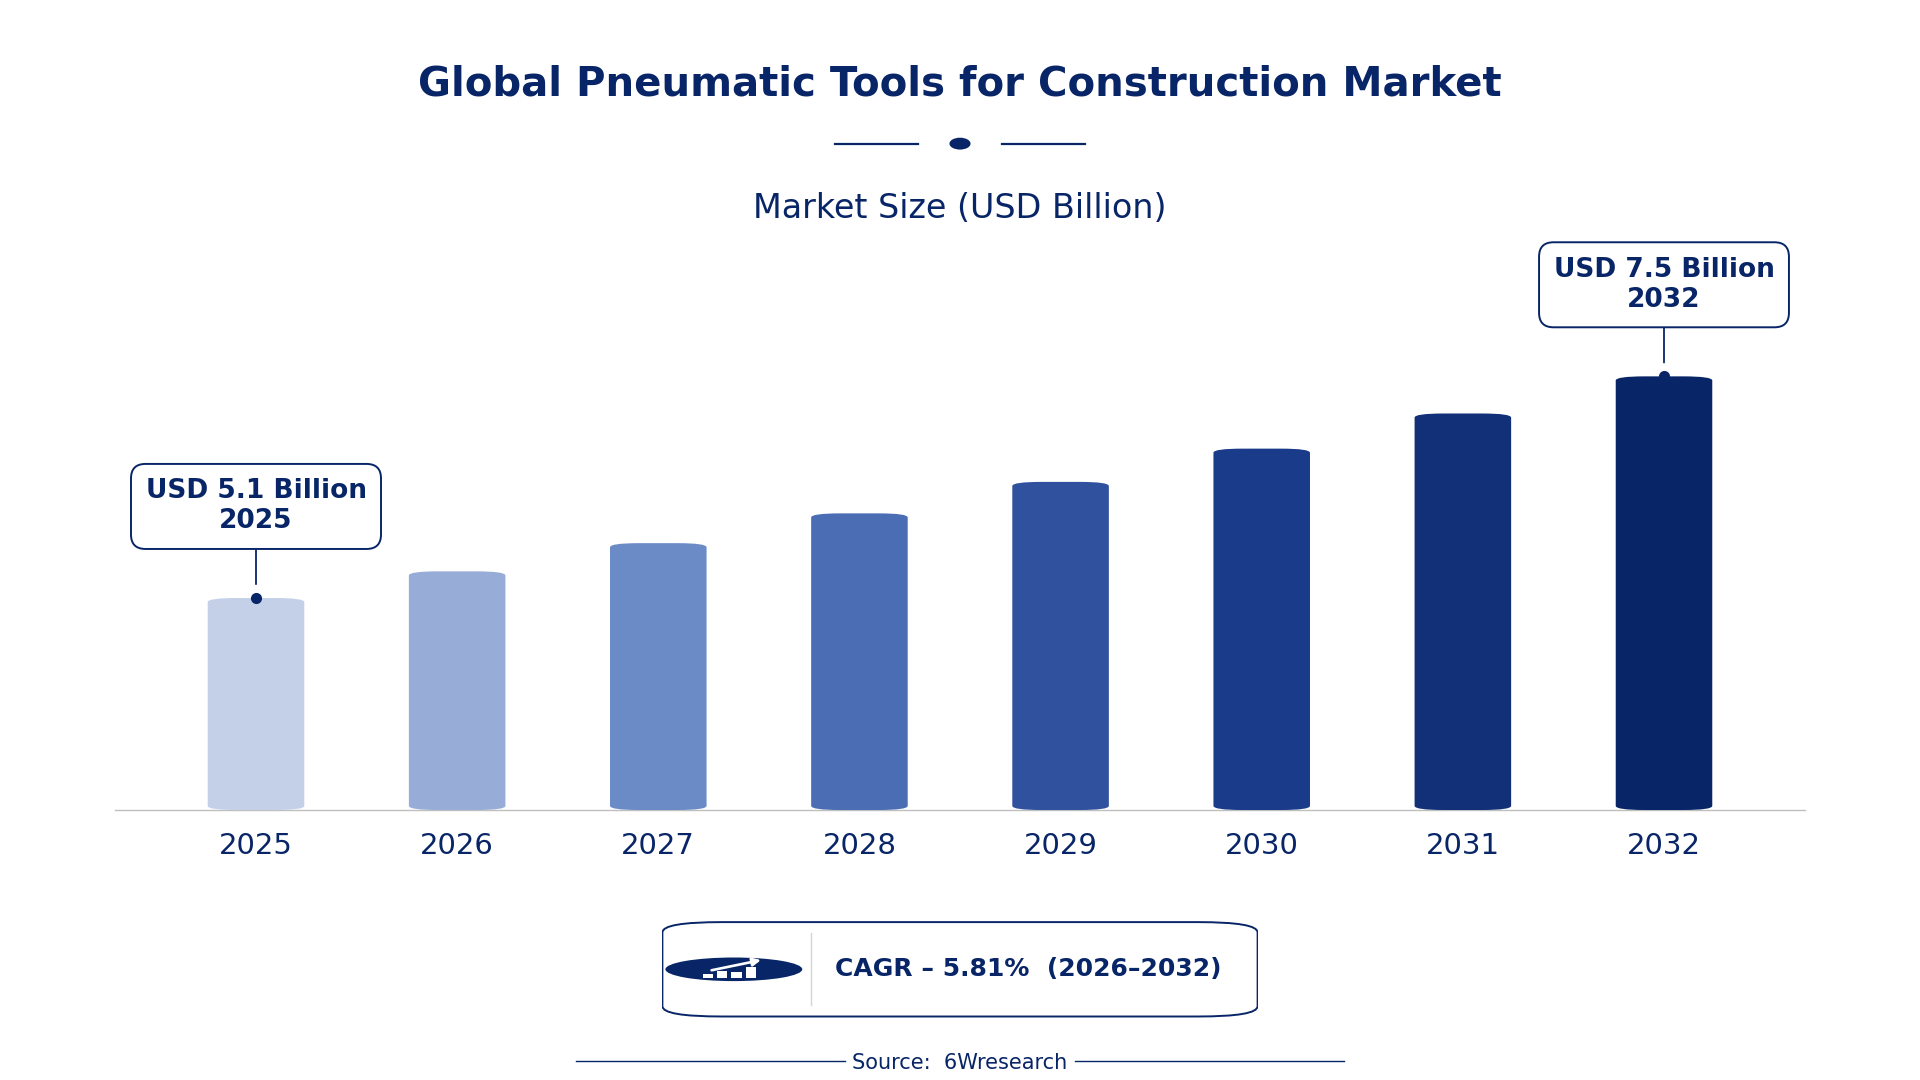
The Global Pneumatic Tools for Construction Market was estimated at USD 5.1 Billion in 2025 and is projected to reach USD 7.5 Billion by 2032, growing at a CAGR of 5.81% from 2026 to 2032.
Global Pneumatic Tools for Construction Market Synopsis
The Global Pneumatic Tools for Construction Market is currently undergoing transformative changes shaped by the dual forces of construction sector growth and technological advances. Key industries such as residential and commercial construction are pushing demand, particularly as urbanization trends accelerate. The increasing use of pneumatic tools signifies a shift towards achieving greater efficiency and performance, further solidifying their role in construction processes.
Emerging economies are enhancing their construction capabilities, significantly impacting the pneumatic tools sector. As these markets evolve, demand for specialized and high-performance tools is on the rise, enabling companies to innovate. The industry's focus on safety features and enhanced user ergonomics is redefining product offerings, setting the stage for a shift in competitive dynamics within the Global Pneumatic Tools for Construction Market.
Global Pneumatic Tools for Construction Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Global Pneumatic Tools for Construction Market from 2022 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
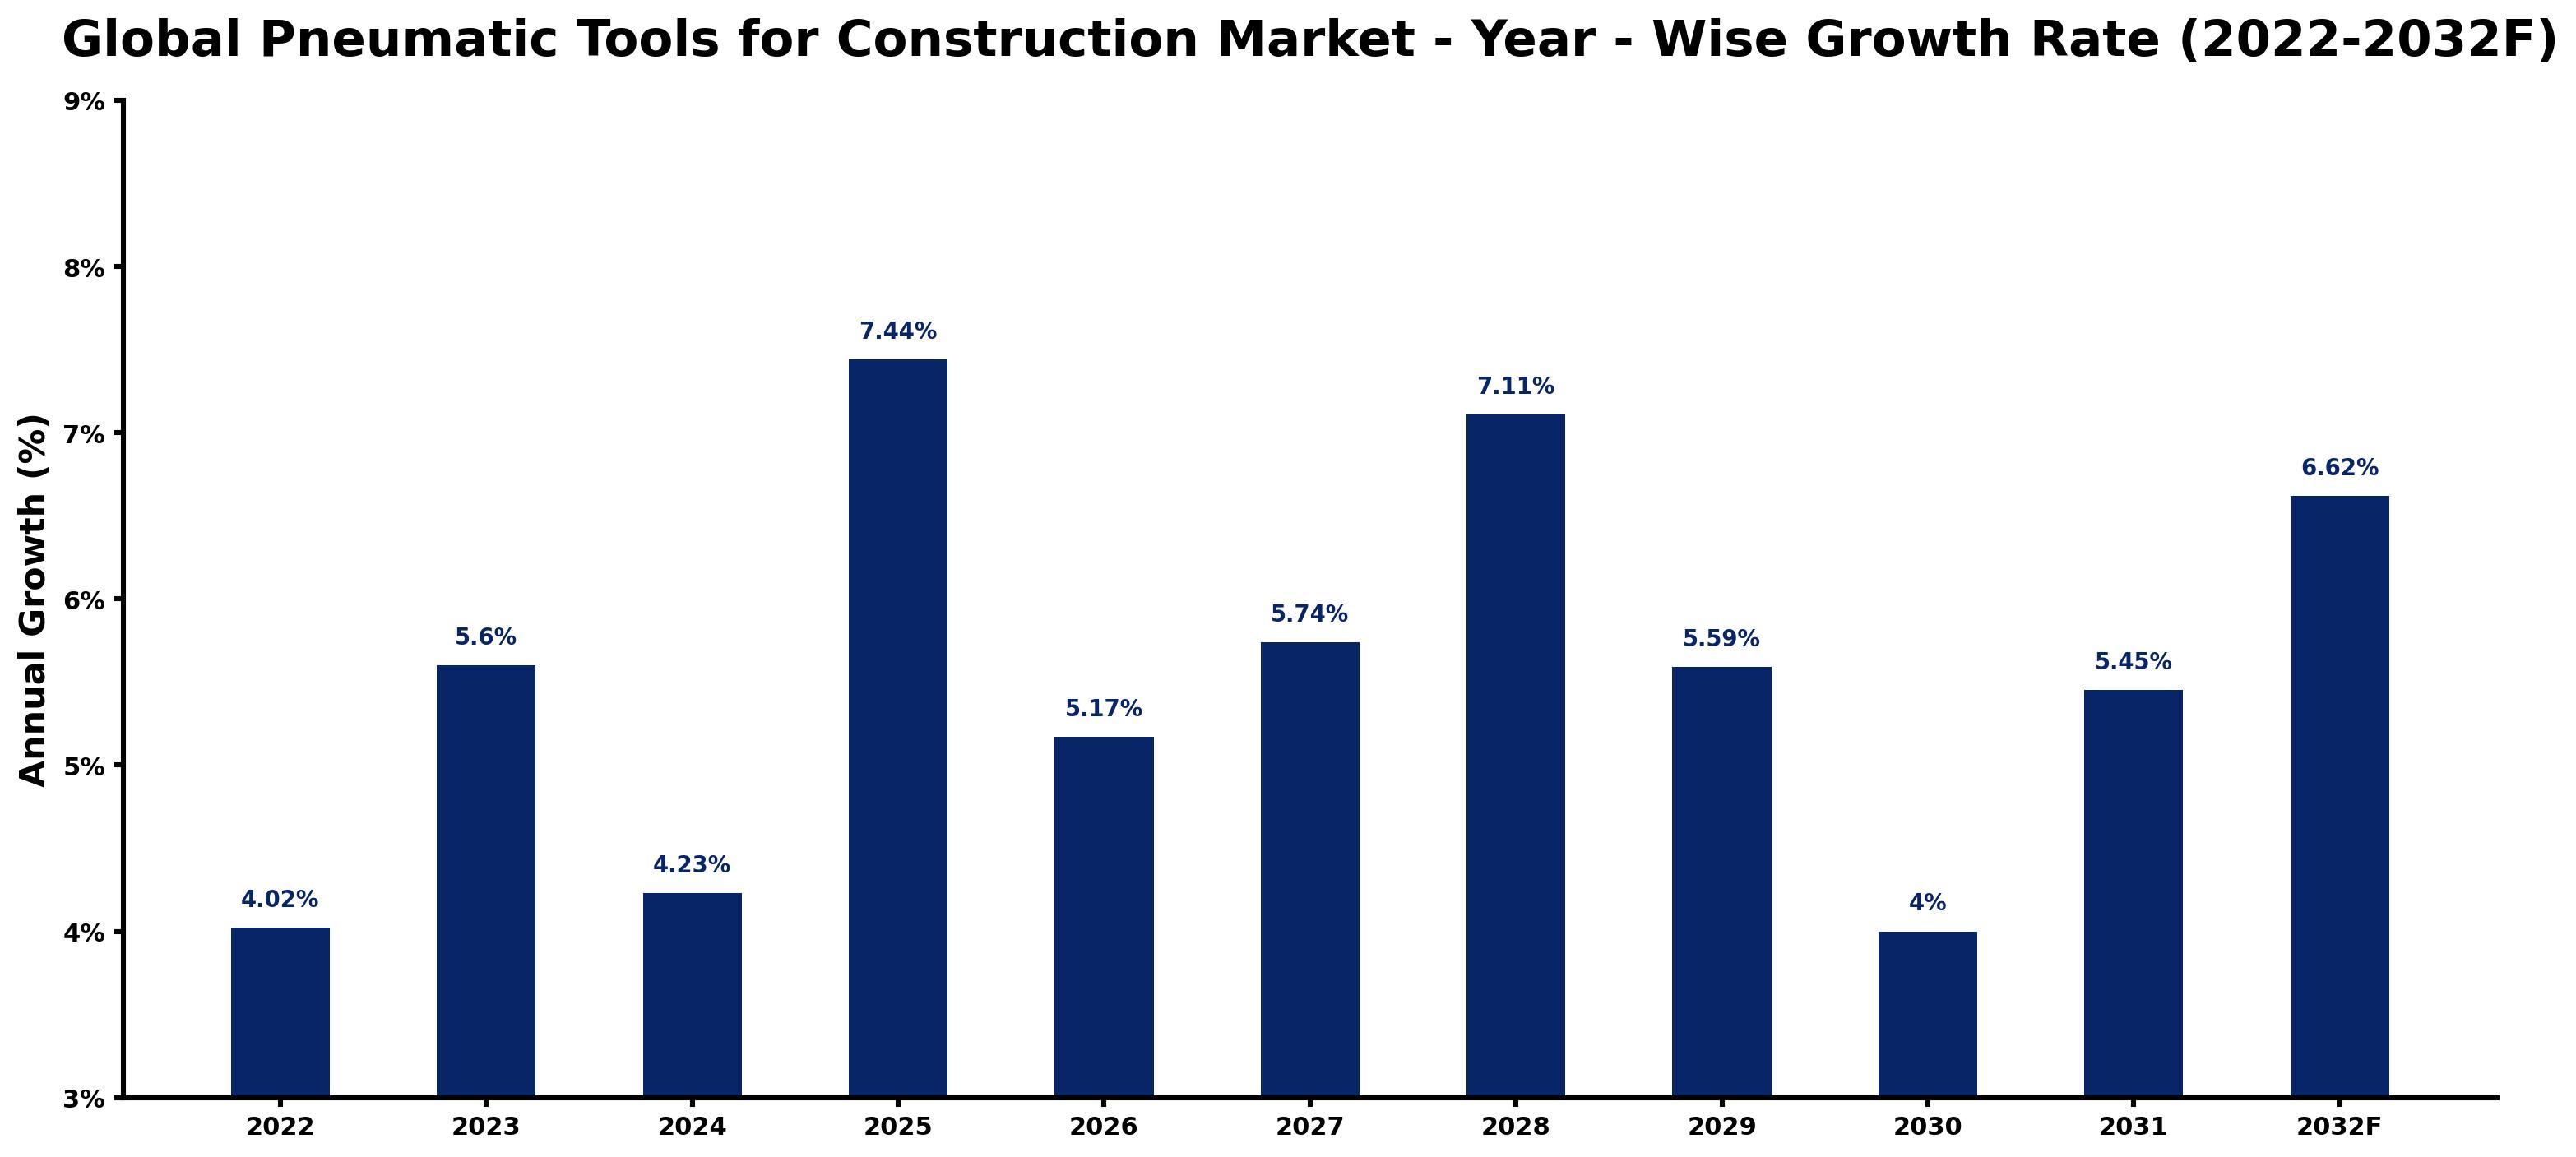
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate (%) | Major Drivers |
| 2022 | 4.02 | As regional markets expand, pneumatic tools gain traction in construction projects. |
| 2023 | 5.6 | Manufacturers innovate to compete, enhancing the appeal of pneumatic tools in construction. |
| 2024 | 4.23 | Adjusting supply chain logistics facilitates consistent access to pneumatic tools for contractors. |
| 2025 | 7.44 | Construction firms increasingly prioritize sustainability, driving demand for eco-friendly pneumatic tools. |
| 2026 | 5.17 | A shift toward smart pneumatic tools enhances efficiency across heavy machinery fleets. |
| 2027 | 5.74 | A growing focus on productivity leads end-users to adopt advanced pneumatic tools rapidly. |
| 2028 | 7.11 | Implementing training programs improves workforce skills, increasing the efficiency of pneumatic tools. |
| 2029 | 5.59 | In North American construction sectors, demand for pneumatic tools reflects a shift toward automation. |
| 2030 | 4 | Rising raw material costs create pressure, potentially affecting pneumatic tool pricing strategies. |
| 2031 | 5.45 | Pneumatic drill technologies attract significant investment, indicating confidence in the construction industry's future. |
| 2032 | 6.62 | Construction companies adapt to new regulations, further integrating pneumatic tools into operational workflows. |
Note - Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary research methodology, combining internal industry data, secondary research, and primary validation, updated periodically to reflect current market conditions. As markets evolve rapidly, figures for certain industries may vary slightly and are intended as informed estimates rather than absolute figures. For the most current market sizing, we recommend validating figures with a 6Wresearch analyst.
Global Pneumatic Tools for Construction Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- The market is expected to see adoption increases in Asia, with a projected CAGR exceeding 7.5% from 2026 to 2032, driven by rapid construction projects.
- Ingersoll Rand launched its latest line of lightweight pneumatic grinders in 2023, showcasing advancements in user-friendly designs.
- Nail guns, leading in market share, accounted for approximately 40% of the overall revenue in 2025, owing to their widespread use in framing.
- The integration of IoT technology in pneumatic tools is on the rise, enabling real-time performance monitoring, a trend that gained traction in 2022.
Evaluation of Restraints in Global Pneumatic Tools for Construction Market
Despite the growth trajectory, the Global Pneumatic Tools for Construction Market faces challenges that hinder its potential. High initial costs are a significant barrier, with entry-level pneumatic tools typically starting at USD 300 and going upwards, limiting access for smaller contractors. Regulatory hurdles also pose constraints, particularly safety and emissions standards that manufacturers must meet, driving up costs. For example, the 2020 OSHA regulations increased compliance costs for tool manufacturers by an estimated 15%, impacting pricing strategies. These factors necessitate strategic investment and innovation to navigate competitive pressures effectively.
Global Pneumatic Tools for Construction Market Trends
A notable trend in the Global Pneumatic Tools for Construction Market is the increasing integration of automation and smart technologies. Companies are developing automated pneumatic tools equipped with sensors for enhanced precision and performance. For instance, Makita's recent launch of powered nailers features advanced depth adjustment technology, which streamlines operations on construction sites. The emphasis on ergonomic design is also transforming product lines to enhance user comfort and reduce injury risks, particularly as worksite injuries remain a concern.
An additional trend is the rise in demand for energy-efficient tools, driven by sustainability initiatives within the construction industry. Pneumatic tools, often perceived as more energy-efficient than electric alternatives, are appealing to contractors looking to reduce both operational costs and environmental impact. This shift towards sustainability is supported by manufacturers investing in research and development focused on eco-friendly designs.
Global Pneumatic Tools for Construction Market Opportunities
Specific revenue opportunities in the Global Pneumatic Tools for Construction Market lie in emerging applications within renewable energy sectors. With increasing investment in wind and solar infrastructure, pneumatic tools are becoming essential for installation and maintenance tasks. As an example, the new trend toward solar panel installations has created a demand for specialized impact wrenches designed for mounting systems, projected to generate USD 450 million by 2028. Further collaborations with construction firms to develop custom, task-specific pneumatic tools could also drive revenue growth as companies seek tailored solutions for unique projects.
Global Pneumatic Tools for Construction Market by Type
Among the various tools, Nail Guns lead the segment with a commanding market share of approximately 40% in 2025, primarily due to their critical application in framing and finishing tasks. Conversely, Drills are the fastest-growing segment, expected to witness a CAGR of 7.2% from 2026 to 2032 as contractors increasingly adopt them for versatility in various applications, including electrical and plumbing tasks. This growth is driven by a significant push towards multipurpose tools capable of addressing diverse project needs.
Global Pneumatic Tools for Construction Market by Power Source
Compressed Air is the dominant power source within the market, accounting for around 55% share in 2025, favored for its reliability and performance across various applications. In contrast, the Battery segment is projected to grow rapidly, with a CAGR of 9.3% from 2026 to 2032, driven by advancements in battery technology and increasing interest in cordless tools, particularly in regions where mobility on worksites is essential. This growth reflects changing user preferences and designs focused on enhancing operational convenience.
Global Pneumatic Tools for Construction Market by End User
The Construction sector is the largest end-user, capturing approximately 65% market share in 2025 as construction projects increasingly rely on pneumatic tools for efficiency and speed. Meanwhile, the Automotive sector is noted as the fastest-growing end-user, forecasted to achieve a CAGR of 8.4% from 2026 to 2032, driven by the need for precision assembly and repairs. This growth signifies a shift in pneumatic tool applications beyond traditional construction, catering to automotive manufacturing processes.
Global Pneumatic Tools for Construction Market by Application
Framing & Roofing leads the application segment, comprising approximately 45% of the market share in 2025, primarily due to its widespread use in residential and commercial construction. However, Cutting & Shaping is expected to be the fastest-growing application, with a projected CAGR of 7.9% from 2026 to 2032 as new materials demand more precise cutting tools. This shift showcases evolving needs within the construction sector as various materials, including composites and metal frameworks, gain traction.
Global Pneumatic Tools for Construction Market by Region
North America remains the largest region, holding a notable share of around 48% in 2025, driven by a mature construction sector and robust industrial infrastructure. In contrast, Asia is the fastest-growing region, anticipated to experience a CAGR of 7.8% from 2026 to 2032. Factors fueling this growth include rapid urbanization, increasing investments in infrastructure, and a rising number of construction projects in emerging economies. The convergence of these elements positions Asia as a pivotal market in the Global Pneumatic Tools for Construction landscape.
Government Initiatives in the Global Pneumatic Tools for Construction Market
The regulatory landscape for the Global Pneumatic Tools for Construction Market is characterized by numerous government initiatives focused on improving industry standards, enhancing safety measures, and fostering innovation. These initiatives aim to address the challenges faced by manufacturers and end-users, ensuring sustainable growth in this sector.
- U.S. Department of Labor, Occupational Safety and Health Administration (OSHA) – Safety Standards for Pneumatic Tools, 2020: This regulation mandates the implementation of safety measures, benefiting manufacturers by ensuring compliance and encouraging the adoption of safer tools.
- European Commission – Eco-design Directive, 2023: This ongoing initiative promotes energy-efficient tools, pressuring manufacturers to comply and innovate, ultimately impacting market design and sustainability.
- Government of Canada – Innovation, Science and Economic Development Canada, Advanced Manufacturing Supercluster Initiative, 2021: This funding initiative supports R&D for pneumatic tools, encouraging innovation and enhancing competitiveness in the global market.
- Australian Government, Department of Industry, Science, Energy and Resources – Renewable Energy Tools Incentive Scheme (planned for 2024): This upcoming initiative aims to provide funding for manufacturers developing pneumatic tools tailored for renewable energy applications, indicating a strategic shift toward sustainability.
Future Insights of the Global Pneumatic Tools for Construction Market
The Global Pneumatic Tools for Construction Market is anticipated to undergo structural shifts as automation and digital connectivity become paramount. The integration of IoT technology, already gaining traction, is likely to define future developments in tool monitoring and performance management. For instance, recent initiatives by companies like Ingersoll Rand in creating smarter, user-friendly pneumatic tools demonstrate a strong inclination toward enhancing operational efficiencies, which will influence competitive dynamics through 2032.
Global Pneumatic Tools for Construction Market Latest Developments
Recent advancements in the Global Pneumatic Tools for Construction Market showcase innovative efforts from leading players. Key developments are highlighted below:
- In July 2023, DeWalt introduced a new range of high-performance pneumatic nailers optimized for lightweight applications, which expands their product offering and strengthens market presence.
- Recently in March 2023, Bosch unveiled its updated line of pneumatic drills featuring enhanced torque capabilities, catering to the evolving needs of contractors.
- Hitachi is investing in new manufacturing facilities in Southeast Asia, slated for completion in early 2024, aimed at boosting production capacity and regional distribution.
- Ingersoll Rand's recent advancement in sustainable pneumatic technology, announced in September 2023, focuses on reducing energy consumption across its product lines, enhancing the appeal of eco-friendly solutions.
Global Pneumatic Tools for Construction Market Key Players and Industry Positioning
The competitive structure of the Global Pneumatic Tools for Construction Market is somewhat fragmented, with substantial players vying for market share through innovation and regional strategies. Companies leverage unique strengths, such as specialized product development and strategic partnerships, to distinguish their offerings in a diverse marketplace.
| Leading Company | Core Strength | Strategic Focus |
|---|---|---|
| DeWalt | Market leader in power tools known for durability and performance. | Expanding product lines with advanced technology features. |
| Bosch | Strong R&D capability and innovative designs in pneumatic tools. | Focus on enhancing efficiency through smart technologies. |
| Makita | Diverse product range and robust distribution network. | Targeting global markets with ergonomic and modular tool designs. |
| Ingersoll Rand | Expertise in air compressor technology integrated with tools. | Investing in sustainable and energy-efficient product developments. |
| Hitachi | Reputation for precision tools and efficiency in manufacturing. | Expanding presence in emerging regions through localized production. |
As the market evolves, companies that can effectively marry technological advancements with user-centric design are well-positioned to lead and capture emerging opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global Pneumatic Tools for Construction Market Outlook
- Market Size of Global Pneumatic Tools for Construction Market, 2025
- Forecast of Global Pneumatic Tools for Construction Market, 2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Revenues & Volume for the Period 2022-2032
- Global Pneumatic Tools for Construction Market Trend Evolution
- Global Pneumatic Tools for Construction Market Drivers and Challenges
- Global Pneumatic Tools for Construction Price Trends
- Global Pneumatic Tools for Construction Porter's Five Forces
- Global Pneumatic Tools for Construction Industry Life Cycle
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Nail Guns for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Drills for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Grinders for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Sanders for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Power Source for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Compressed Air for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Battery for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Gasoline for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Manufacturing for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Mining for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Framing & Roofing for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Drilling & Fastening for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Cutting & Shaping for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Surface Finishing for the Period 2022-2032
- Historical Data and Forecast of Global Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Nail Guns for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Drills for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Grinders for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Sanders for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Power Source for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Compressed Air for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Battery for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Gasoline for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Manufacturing for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Mining for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Framing & Roofing for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Drilling & Fastening for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Cutting & Shaping for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Surface Finishing for the Period 2022-2032
- Historical Data and Forecast of North America Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United States of America Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Canada Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of North America Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Nail Guns for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Drills for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Grinders for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Sanders for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Power Source for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Compressed Air for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Battery for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Gasoline for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Manufacturing for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Mining for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Framing & Roofing for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Drilling & Fastening for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Cutting & Shaping for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Surface Finishing for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Brazil Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Mexico Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Argentina Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of LATAM Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Nail Guns for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Drills for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Grinders for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Sanders for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Power Source for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Compressed Air for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Battery for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Gasoline for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Manufacturing for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Mining for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Framing & Roofing for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Drilling & Fastening for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Cutting & Shaping for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Surface Finishing for the Period 2022-2032
- Historical Data and Forecast of Asia Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of China Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of India Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Japan Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Asia Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Nail Guns for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Drills for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Grinders for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Sanders for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Power Source for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Compressed Air for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Battery for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Gasoline for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Manufacturing for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Mining for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Framing & Roofing for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Drilling & Fastening for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Cutting & Shaping for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Surface Finishing for the Period 2022-2032
- Historical Data and Forecast of Africa Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of South Africa Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Nigeria Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Egypt Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Africa Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Nail Guns for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Drills for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Grinders for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Sanders for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Power Source for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Compressed Air for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Battery for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Gasoline for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Manufacturing for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Mining for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Framing & Roofing for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Drilling & Fastening for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Cutting & Shaping for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Surface Finishing for the Period 2022-2032
- Historical Data and Forecast of Europe Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United Kingdom Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of France Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Germany Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Europe Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Nail Guns for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Drills for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Grinders for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Sanders for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Power Source for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Compressed Air for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Battery for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Gasoline for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Manufacturing for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Mining for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Framing & Roofing for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Drilling & Fastening for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Cutting & Shaping for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Surface Finishing for the Period 2022-2032
- Historical Data and Forecast of Middle East Pneumatic Tools for Construction Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Saudi Arabia Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of UAE Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Turkey Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Middle East Pneumatic Tools for Construction Market Revenues & Volume for the Period 2022-2032
- Global Pneumatic Tools for Construction Market - Key Performance Indicators
- Global Pneumatic Tools for Construction Market - Import Export Trade Statistics
- Global Pneumatic Tools for Construction Market - Opportunity Assessment By Countries
- Global Pneumatic Tools for Construction Market - Opportunity Assessment By Type
- Global Pneumatic Tools for Construction Market - Opportunity Assessment By Power Source
- Global Pneumatic Tools for Construction Market - Opportunity Assessment By End User
- Global Pneumatic Tools for Construction Market - Opportunity Assessment By Application
- Global Pneumatic Tools for Construction Market - Top Companies Market Share
- Global Pneumatic Tools for Construction Market - Top Companies Profiles
- Global Pneumatic Tools for Construction Market - Comparison of Players in Technical and Operating Parameters
- Global Pneumatic Tools for Construction Market - Strategic Recommendations
Markets Covered
The Global Pneumatic Tools for Construction Market report provides a detailed analysis of the following market segments:
By Regions and Countries:
- North America
- Europe
- LATAM
- Middle East
- Asia
- Africa
By Type:
- Nail Guns
- Drills
- Grinders
- Sanders
- Others
By Power Source:
- Compressed Air
- Electric
- Battery
- Gasoline
- Others
By End User:
- Construction
- Manufacturing
- Mining
- Automotive
- Others
By Application:
- Framing & Roofing
- Drilling & Fastening
- Cutting & Shaping
- Surface Finishing
- Others
Global Pneumatic Tools for Construction Market - Frequently Asked Questions
The Global Pneumatic Tools for Construction Market was estimated at USD 5.1 Billion in 2025 and is projected to reach USD 7.5 Billion by 2032, growing at a CAGR of 5.81% from 2026 to 2032.
Key drivers include increased investment in construction projects, technological advancements in tool efficiency, and rising urbanization, particularly in Asia.
Nail guns lead the segment, holding approximately 40% market share in 2025, while drills are the fastest-growing segment due to their versatility across multiple applications.
High initial costs and stringent regulatory compliance requirements pose significant barriers, limiting entry for smaller contractors and impacting pricing strategies of manufacturers.
The future indicates a shift towards automation and smart technologies, with companies investing in IoT-enabled tools that enhance performance monitoring, reflecting evolving contractor needs.
6Wresearch actively monitors the Global Pneumatic Tools for Construction Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Global Pneumatic Tools for Construction Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
Global Pneumatic Tools for Construction Market |
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Global Pneumatic Tools for Construction Market Overview |
3.1 Global Regional Macro Economic Indicators |
3.2 Global Pneumatic Tools for Construction Market Revenues & Volume, 2022 & 2032F |
3.3 Global Pneumatic Tools for Construction Market - Industry Life Cycle |
3.4 Global Pneumatic Tools for Construction Market - Porter's Five Forces |
3.5 Global Pneumatic Tools for Construction Market Revenues & Volume Share, By Regions, 2022 & 2032F |
3.6 Global Pneumatic Tools for Construction Market Revenues & Volume Share, By Type, 2022 & 2032F |
3.7 Global Pneumatic Tools for Construction Market Revenues & Volume Share, By Power Source, 2022 & 2032F |
3.8 Global Pneumatic Tools for Construction Market Revenues & Volume Share, By End User, 2022 & 2032F |
3.9 Global Pneumatic Tools for Construction Market Revenues & Volume Share, By Application, 2022 & 2032F |
4 Global Pneumatic Tools for Construction Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.3 Market Restraints |
5 Global Pneumatic Tools for Construction Market Trends |
6 Global Pneumatic Tools for Construction Market, 2022-2032 |
6.1 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Type, 2022-2032 |
6.1.1 Overview & Analysis |
6.1.2 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Nail Guns, 2022-2032 |
6.1.3 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Drills, 2022-2032 |
6.1.4 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Grinders, 2022-2032 |
6.1.5 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Sanders, 2022-2032 |
6.1.6 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Others, 2022-2032 |
6.2 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Power Source, 2022-2032 |
6.2.1 Overview & Analysis |
6.2.2 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Compressed Air, 2022-2032 |
6.2.3 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Electric, 2022-2032 |
6.2.4 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Battery, 2022-2032 |
6.2.5 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Gasoline, 2022-2032 |
6.2.6 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Others, 2022-2032 |
6.3 Global Pneumatic Tools for Construction Market, Revenues & Volume, By End User, 2022-2032 |
6.3.1 Overview & Analysis |
6.3.2 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Construction, 2022-2032 |
6.3.3 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Manufacturing, 2022-2032 |
6.3.4 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Mining, 2022-2032 |
6.3.5 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Automotive, 2022-2032 |
6.3.6 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Others, 2022-2032 |
6.4 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Application, 2022-2032 |
6.4.1 Overview & Analysis |
6.4.2 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Framing & Roofing, 2022-2032 |
6.4.3 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Drilling & Fastening, 2022-2032 |
6.4.4 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Cutting & Shaping, 2022-2032 |
6.4.5 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Surface Finishing, 2022-2032 |
6.4.6 Global Pneumatic Tools for Construction Market, Revenues & Volume, By Others, 2022-2032 |
7 North America Pneumatic Tools for Construction Market, Overview & Analysis |
7.1 North America Pneumatic Tools for Construction Market Revenues & Volume, 2022-2032 |
7.2 North America Pneumatic Tools for Construction Market, Revenues & Volume, By Countries, 2022-2032 |
7.2.1 United States (US) Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
7.2.2 Canada Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
7.2.3 Rest of North America Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
7.3 North America Pneumatic Tools for Construction Market, Revenues & Volume, By Type, 2022-2032 |
7.4 North America Pneumatic Tools for Construction Market, Revenues & Volume, By Power Source, 2022-2032 |
7.5 North America Pneumatic Tools for Construction Market, Revenues & Volume, By End User, 2022-2032 |
7.6 North America Pneumatic Tools for Construction Market, Revenues & Volume, By Application, 2022-2032 |
8 Latin America (LATAM) Pneumatic Tools for Construction Market, Overview & Analysis |
8.1 Latin America (LATAM) Pneumatic Tools for Construction Market Revenues & Volume, 2022-2032 |
8.2 Latin America (LATAM) Pneumatic Tools for Construction Market, Revenues & Volume, By Countries, 2022-2032 |
8.2.1 Brazil Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
8.2.2 Mexico Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
8.2.3 Argentina Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
8.2.4 Rest of LATAM Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
8.3 Latin America (LATAM) Pneumatic Tools for Construction Market, Revenues & Volume, By Type, 2022-2032 |
8.4 Latin America (LATAM) Pneumatic Tools for Construction Market, Revenues & Volume, By Power Source, 2022-2032 |
8.5 Latin America (LATAM) Pneumatic Tools for Construction Market, Revenues & Volume, By End User, 2022-2032 |
8.6 Latin America (LATAM) Pneumatic Tools for Construction Market, Revenues & Volume, By Application, 2022-2032 |
9 Asia Pneumatic Tools for Construction Market, Overview & Analysis |
9.1 Asia Pneumatic Tools for Construction Market Revenues & Volume, 2022-2032 |
9.2 Asia Pneumatic Tools for Construction Market, Revenues & Volume, By Countries, 2022-2032 |
9.2.1 India Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
9.2.2 China Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
9.2.3 Japan Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
9.2.4 Rest of Asia Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
9.3 Asia Pneumatic Tools for Construction Market, Revenues & Volume, By Type, 2022-2032 |
9.4 Asia Pneumatic Tools for Construction Market, Revenues & Volume, By Power Source, 2022-2032 |
9.5 Asia Pneumatic Tools for Construction Market, Revenues & Volume, By End User, 2022-2032 |
9.6 Asia Pneumatic Tools for Construction Market, Revenues & Volume, By Application, 2022-2032 |
10 Africa Pneumatic Tools for Construction Market, Overview & Analysis |
10.1 Africa Pneumatic Tools for Construction Market Revenues & Volume, 2022-2032 |
10.2 Africa Pneumatic Tools for Construction Market, Revenues & Volume, By Countries, 2022-2032 |
10.2.1 South Africa Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
10.2.2 Egypt Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
10.2.3 Nigeria Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
10.2.4 Rest of Africa Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
10.3 Africa Pneumatic Tools for Construction Market, Revenues & Volume, By Type, 2022-2032 |
10.4 Africa Pneumatic Tools for Construction Market, Revenues & Volume, By Power Source, 2022-2032 |
10.5 Africa Pneumatic Tools for Construction Market, Revenues & Volume, By End User, 2022-2032 |
10.6 Africa Pneumatic Tools for Construction Market, Revenues & Volume, By Application, 2022-2032 |
11 Europe Pneumatic Tools for Construction Market, Overview & Analysis |
11.1 Europe Pneumatic Tools for Construction Market Revenues & Volume, 2022-2032 |
11.2 Europe Pneumatic Tools for Construction Market, Revenues & Volume, By Countries, 2022-2032 |
11.2.1 United Kingdom Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
11.2.2 Germany Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
11.2.3 France Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
11.2.4 Rest of Europe Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
11.3 Europe Pneumatic Tools for Construction Market, Revenues & Volume, By Type, 2022-2032 |
11.4 Europe Pneumatic Tools for Construction Market, Revenues & Volume, By Power Source, 2022-2032 |
11.5 Europe Pneumatic Tools for Construction Market, Revenues & Volume, By End User, 2022-2032 |
11.6 Europe Pneumatic Tools for Construction Market, Revenues & Volume, By Application, 2022-2032 |
12 Middle East Pneumatic Tools for Construction Market, Overview & Analysis |
12.1 Middle East Pneumatic Tools for Construction Market Revenues & Volume, 2022-2032 |
12.2 Middle East Pneumatic Tools for Construction Market, Revenues & Volume, By Countries, 2022-2032 |
12.2.1 Saudi Arabia Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
12.2.2 UAE Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
12.2.3 Turkey Pneumatic Tools for Construction Market, Revenues & Volume, 2022-2032 |
12.3 Middle East Pneumatic Tools for Construction Market, Revenues & Volume, By Type, 2022-2032 |
12.4 Middle East Pneumatic Tools for Construction Market, Revenues & Volume, By Power Source, 2022-2032 |
12.5 Middle East Pneumatic Tools for Construction Market, Revenues & Volume, By End User, 2022-2032 |
12.6 Middle East Pneumatic Tools for Construction Market, Revenues & Volume, By Application, 2022-2032 |
13 Global Pneumatic Tools for Construction Market Key Performance Indicators |
14 Global Pneumatic Tools for Construction Market - Export/Import By Countries Assessment |
15 Global Pneumatic Tools for Construction Market - Opportunity Assessment |
15.1 Global Pneumatic Tools for Construction Market Opportunity Assessment, By Countries, 2022 & 2032F |
15.2 Global Pneumatic Tools for Construction Market Opportunity Assessment, By Type, 2022 & 2032F |
15.3 Global Pneumatic Tools for Construction Market Opportunity Assessment, By Power Source, 2022 & 2032F |
15.4 Global Pneumatic Tools for Construction Market Opportunity Assessment, By End User, 2022 & 2032F |
15.5 Global Pneumatic Tools for Construction Market Opportunity Assessment, By Application, 2022 & 2032F |
16 Global Pneumatic Tools for Construction Market - Competitive Landscape |
16.1 Global Pneumatic Tools for Construction Market Revenue Share, By Companies, 2025 |
16.2 Global Pneumatic Tools for Construction Market Competitive Benchmarking, By Operating and Technical Parameters |
17 Top 10 Company Profiles |
18 Recommendations |
19 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 4,560
- Department License$ 5,055
- Site License$ 5,595
- Global License$ 6,000
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Peru Holistic Health Market (2026-2032)
- Pakistan Holistic Health Market (2026-2032)
- Oman Holistic Health Market (2026-2032)
- Nigeria Holistic Health Market (2026-2032)
- Nepal Holistic Health Market (2026-2032)
- Myanmar Holistic Health Market (2026-2032)
- Morocco Holistic Health Market (2026-2032)
- Mexico Holistic Health Market (2026-2032)
- Malaysia Holistic Health Market (2026-2032)
- Lebanon Holistic Health Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.


