India Aircraft Operational Software Market Size & Growth Rate
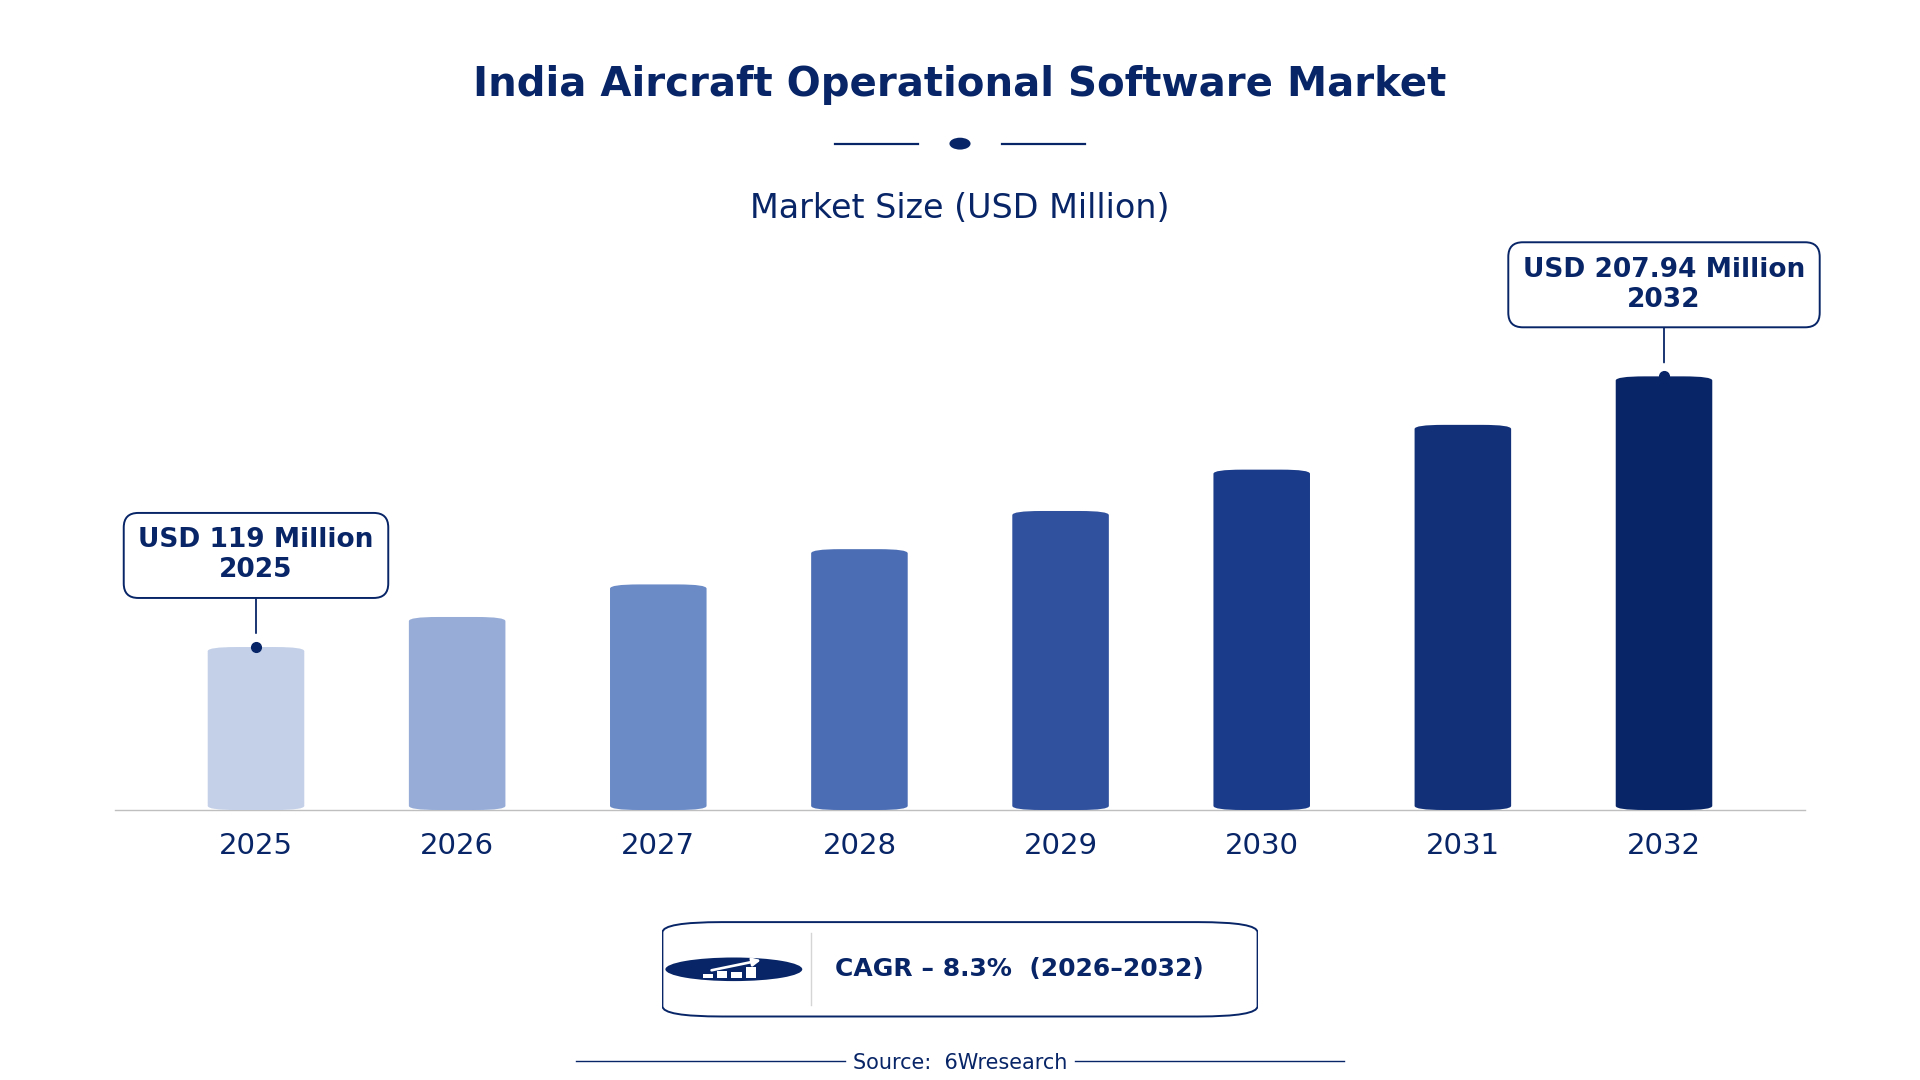
According to 6Wresearch internal database and industry insights, the India Aircraft Operational Software Market was valued at USD 119.0 million in 2025 and is projected to reach USD 207.94 million by 2032, growing at a CAGR of approximately 8.3% during 2026–2032.
India Aircraft Operational Software Market Highlights
| Report Metric | Details |
| Report Name | India Aircraft Operational Software Market |
| Market Size 2025 | USD 119.0 million |
| Market Size 2032 | USD 207.94 million |
| Absolute Growth 2025–2032 | USD 88.94 million |
| CAGR 2026–2032 | 8.3% |
| Peak Annual Growth | 10.3% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Software Type, 2025 | Flight Scheduling (36% share) |
| Leading Deployment Mode, 2025 | Cloud-Based (50% share) |
| Leading Distribution Channel, 2025 | Direct Sales (34% share) |
| Leading End User, 2025 | Airline Operators (43% share) |
| Fastest-Growing Software Type | Crew Management (11.0% CAGR) |
| Fastest-Growing Distribution Channel | OEM Distributors (9.7% CAGR) |
| Fastest-Growing End User | Cargo Airlines (9.8% CAGR) |
| Growing Sector | Aviation |
| Key End Users | Airline Operators, Charter Companies, Cargo Airlines, Ground Handlers |
India Aircraft Operational Software Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
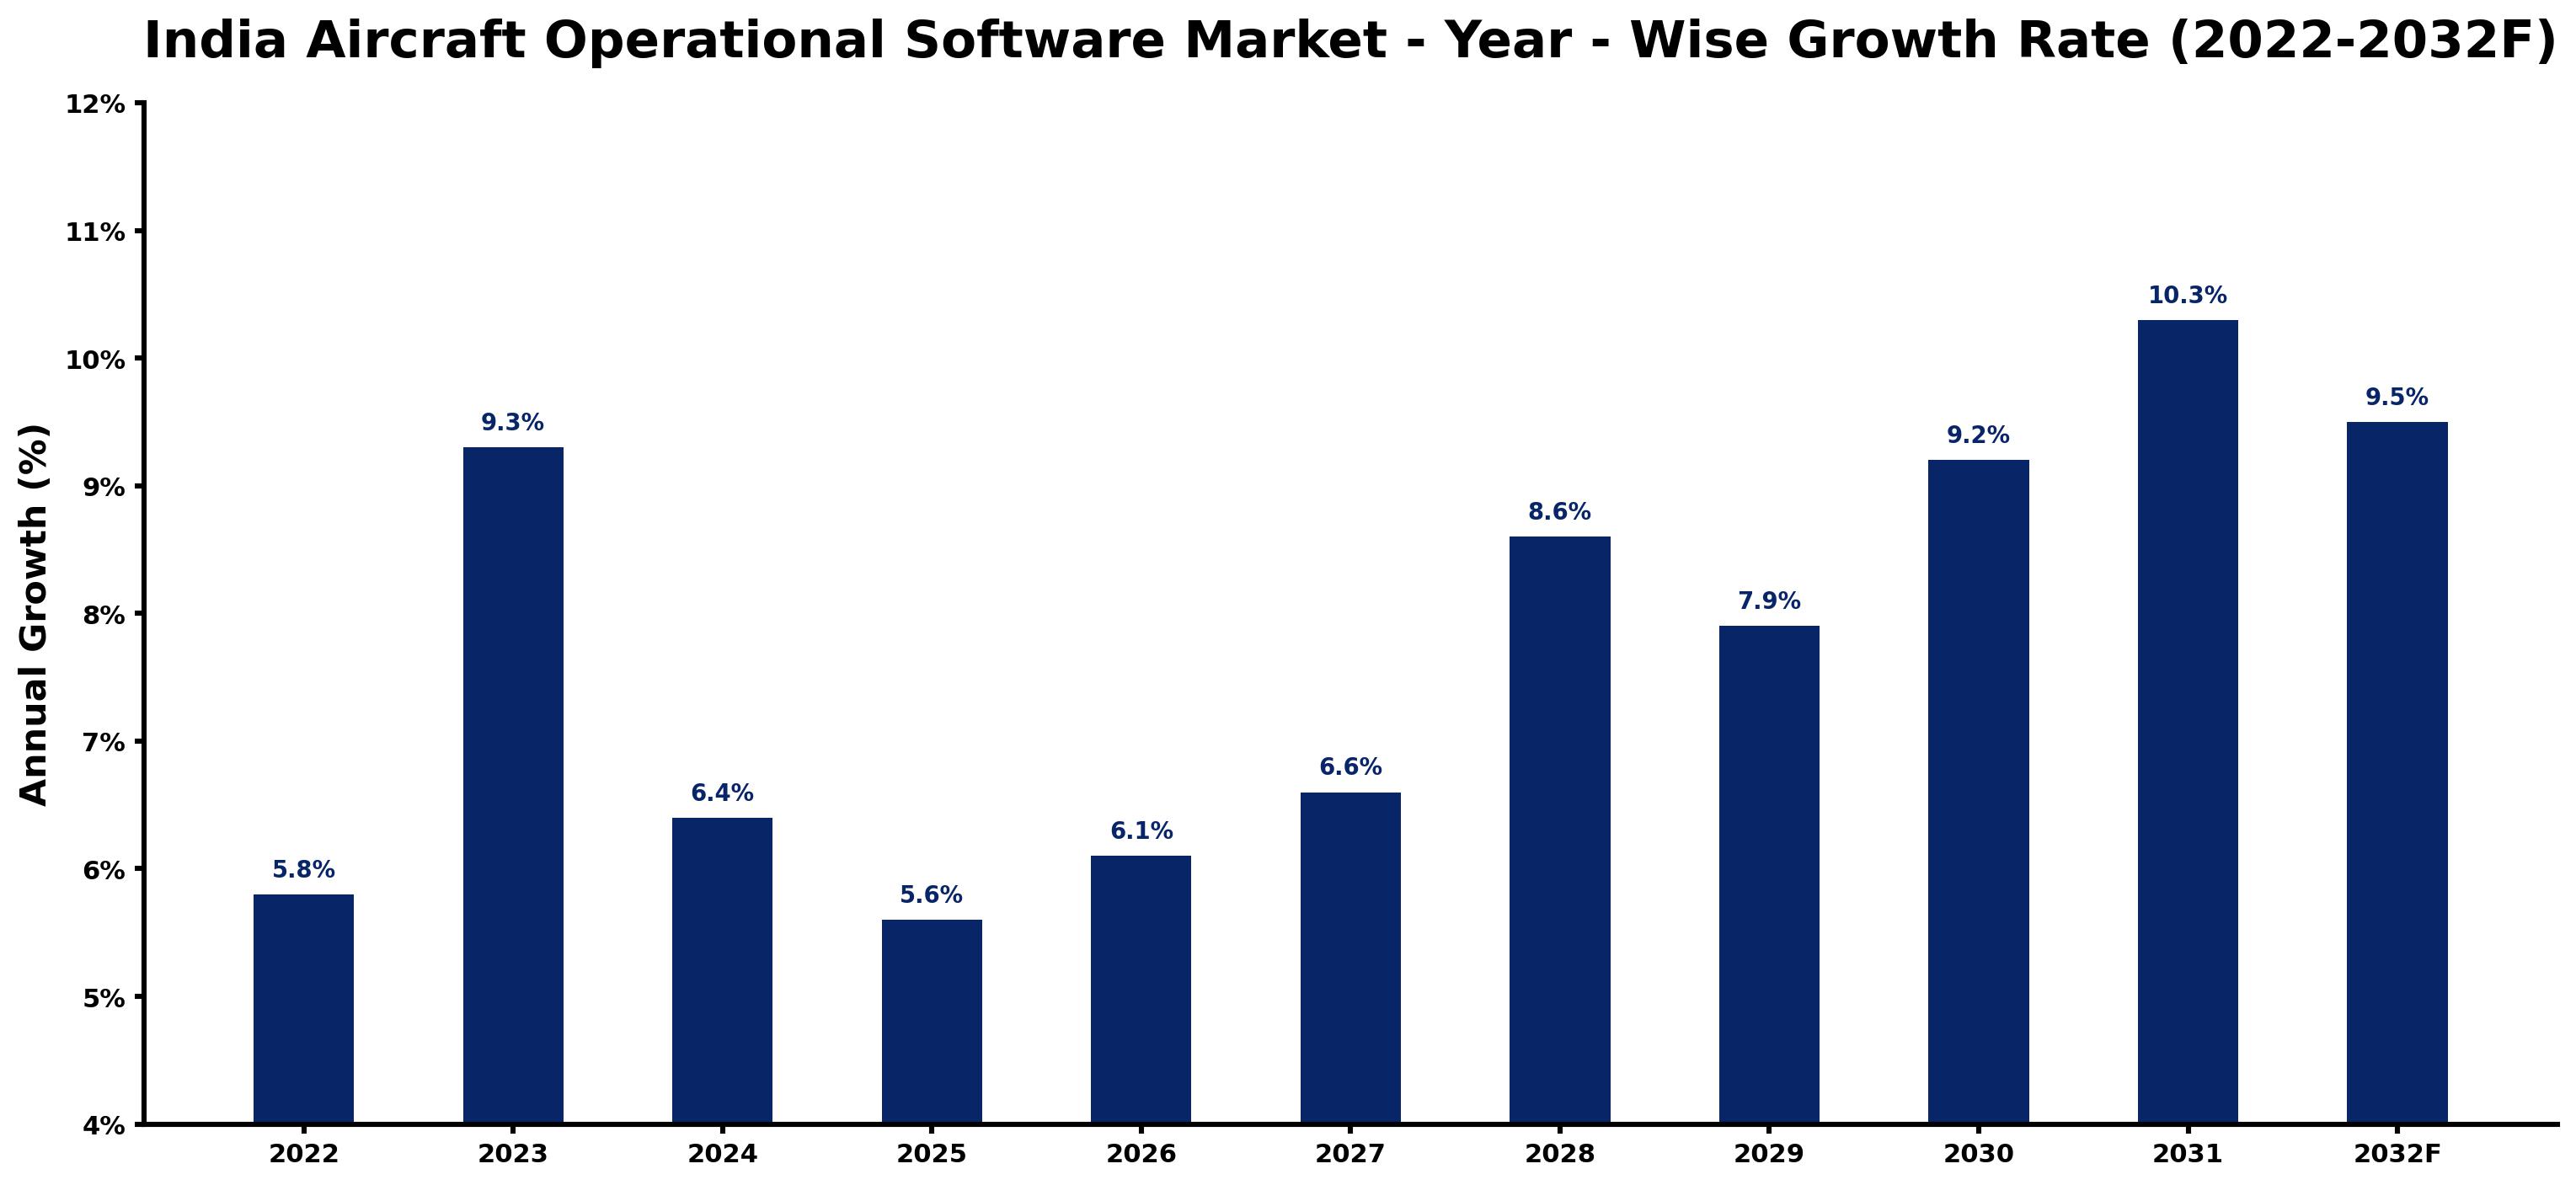
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.8 | The market experienced steady growth due to increasing demand for operational efficiency. |
| 2023 | 9.3 | Growth accelerated as airlines expanded operations and sought advanced software solutions. |
| 2024 | 6.4 | A slowdown occurred as market growth moderated following a peak in 2023. |
| 2025 | 5.6 | Continued demand for operational software maintained growth, albeit at a slower pace. |
| 2026 | 6.1 | Growth resumed as airlines increasingly adopted cloud-based solutions for flexibility. |
| 2027 | 6.6 | Demand strengthened with rising investments in aviation technology and infrastructure. |
| 2028 | 8.6 | The market saw significant growth driven by enhanced operational requirements and safety regulations. |
| 2029 | 7.9 | A slight slowdown was observed as the market adjusted to previous rapid growth rates. |
| 2030 | 9.2 | Growth accelerated again as airlines prepared for increased passenger traffic and operational demands. |
| 2031 | 10.3 | The market peaked with heightened investments in software solutions for operational efficiency. |
| 2032 | 9.5 | Growth slowed slightly as the market stabilised after reaching a peak. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Aircraft Operational Software Market Synopsis
The Aircraft Operational Software Market in India encompasses software solutions designed to optimise flight operations, manage crew schedules, and ensure safety compliance. This technology is crucial for improving operational efficiency and lowering costs in the aviation sector. The market is expanding due to increased demand from domestic airlines and charter services, as well as international operators. Investments in infrastructure and government initiatives, including the National Civil Aviation Policy, are propelling this growth. The sector is expected to rank as the third largest globally by 2030, highlighting its promising future.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for operational efficiency among airlines | Driver | High | Flight Scheduling |
| Increased investments in aviation technology and infrastructure | Driver | High | Crew Management |
| Expansion of regional airports under the UDAN scheme | Opportunity | High | Airline Operators |
| Rising adoption of cloud-based solutions for flexibility | Opportunity | Medium | Cloud-Based |
| Regulatory compliance requirements for aviation safety | Restraint | High | Load & Trim Software |
| Limited adoption of advanced software by smaller operators | Restraint | Medium | Real-time Monitoring |
| High costs associated with software implementation | Challenge | Medium | Crew Management |
| Integration challenges with existing aviation systems | Challenge | High | Flight Scheduling |
Evaluation of Drivers in India Aircraft Operational Software Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising operational efficiency demands | Flight Scheduling | This demand leads airlines to invest in advanced scheduling software, with a projected 36% market share in 2025. |
| Increased safety compliance requirements | Crew Management | Regulations drive airlines to adopt effective crew management systems, projected to grow at 11.0% CAGR from 2026 to 2032. |
| Government initiatives to improve regional connectivity | Cloud-Based | Cloud solutions are expected to capture 50% of the market by 2025, providing flexibility for airlines. |
| Expansion of commercial airports in India | Real-time Monitoring | With over 100 airports operational, the need for real-time monitoring software is increasing, driving demand. |
| Growing investments in aviation technology | Load & Trim Software | Investment in technology is expected to enhance operational safety and efficiency, driving software adoption. |
Airlines are projected to invest in flight scheduling software, which is expected to capture a significant market share. The UDAN scheme is set to boost demand among airline operators by enhancing regional airport infrastructure. Cloud-based solutions are projected to account for a substantial market share, providing airlines with necessary flexibility. The increasing number of operational airports, exceeding 100, necessitates advanced monitoring solutions to support operational performance.
Evaluation of Restraints in India Aircraft Operational Software Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High implementation costs for advanced software solutions | Crew Management | These costs can deter smaller operators from adopting necessary software, limiting their operational efficiency and growth potential. |
| Regulatory compliance complexities | Load & Trim Software | The need to meet stringent safety regulations can slow down software adoption among operators, impacting their operational capabilities. |
| Limited awareness of available software solutions | Real-time Monitoring | Many smaller airlines lack knowledge of the benefits of real-time monitoring, hindering market growth and operational improvements. |
| Integration difficulties with legacy systems | Cloud-Based | Inconsistent internet connectivity in some regions can limit the effectiveness of cloud-based solutions, affecting user adoption. |
| Market competition leading to price pressure | Flight Scheduling | Intense competition among software providers can drive prices down, affecting profitability for developers. |
India Aircraft Operational Software Market Challenges
The India Aircraft Operational Software market still has to solve a few problems, starting with intense competition among developers. This competitive landscape stems from a saturated market, resulting in price wars that erode profit margins for producers. Buyers face inflated costs due to a limited selection of software solutions, which can lead to higher operational expenses. Supply chain issues also persist, as integrating new operational software with existing aviation systems can cause delays in deployment for airlines. Regulatory compliance with standards set by the DGCA and BCAS complicates the development process, increasing costs and timelines for producers, which can hinder timely solution delivery.
Trends in the India Aircraft Operational Software Market
Below mentioned are some of the trends shaping the India Aircraft Operational Software Market growth.
- Shift towards Cloud-Based Solutions: Airline operators are increasingly adopting cloud-based software for operational flexibility. By 2025, cloud-based solutions are projected to hold a 50% market share, allowing airlines to scale operations efficiently.
- Growing Focus on Safety Compliance: The implementation of ISO 9001:2015 standards is becoming more prevalent in aviation operations. This standard ensures that airlines meet safety regulations effectively, improving overall operational safety.
- Increase in Regional Airport Development: The Indian government aims to increase the number of airports to 200 by 2025. This expansion will drive demand for operational software among airline operators and charter companies, creating new market opportunities.
- Emergence of Real-time Monitoring Solutions: Real-time monitoring software is gaining traction as airlines seek to improve operational performance. This segment is projected to grow as operational demands increase, driven by safety and efficiency needs.
Investment Opportunities in the India Aircraft Operational Software Market
Some of the investment opportunities in the India Aircraft Operational Software Market are mentioned below.
- Investment in Regional Airports: With the Indian government's target to increase airports to 200 by 2025, there is a strong opportunity for software providers to cater to new operators entering the market, improving operational capabilities.
- Partnerships with Local Airlines: Establishing joint ventures with local airlines can facilitate entry into the Indian market, especially as demand for operational software grows due to evolving safety regulations and operational needs.
- Focus on Training and Support Services: As the market expands, providing training and support for software implementation will be important. This is particularly relevant for smaller operators looking to improve their operational efficiency.
- Development of Customised Software Solutions: With increasing operational demands, there is a growing need for tailored software solutions. This presents an opportunity for developers to innovate and meet specific airline requirements.
Government Initiatives in the India Aircraft Operational Software Market
The National Civil Aviation Policy, launched in 2022, aims to improve the regulatory framework and promote investment in the aviation sector. This policy encourages airlines to adopt advanced operational software to comply with safety standards. Additionally, the Bureau of Civil Aviation Security updated its security protocols in 2021, which necessitates the use of sophisticated software solutions to ensure compliance. These measures are essential in shaping the operational environment for airlines in India.
In 2023, the Indian government allocated ₹1,500 crores for the development of regional airports under the UDAN scheme, which is overseen by the Ministry of Civil Aviation. This funding supports the establishment of new airports, enhancing connectivity and increasing the demand for operational software among airlines. The Airports Authority of India is also involved in managing these developments, ensuring that safety and efficiency standards are met.
Future Insight of the India Aircraft Operational Software Market
By 2032, buyers and suppliers in the India Aircraft Operational Software market can anticipate considerable advancements driven by government initiatives and technological progress. The 'Ude Desh ka Aam Naagrik' scheme will improve regional connectivity, creating a heightened need for efficient software solutions. The updated National Civil Aviation Policy will further stimulate growth, encouraging the development of custom software tailored to specific operational needs. With the Indian aviation sector projected to become the third largest globally by 2030, demand for operational software is set to increase, providing suppliers with ample opportunities to expand their offerings.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Software Type – Flight Scheduling Dominated, Crew Management Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, in 2025, Flight Scheduling led the software type split with a 36% share. Flight Scheduling captures the largest market share as it is essential for airlines to efficiently organise and manage their flight operations. With over 100 commercial airports operational in India, effective scheduling is vital for optimising resources and ensuring timely departures. The quickest growth will come from Crew Management, forecast to expand at a CAGR of 11.0% between 2026 and 2032. Crew Management is experiencing rapid growth due to the increasing emphasis on compliance with regulatory standards in the aviation sector. As the Indian aviation market is projected to be the third largest globally by 2030, the demand for robust crew scheduling solutions will continue to expand. Suppliers should enhance their Crew Management solutions to address the rising regulatory requirements in the aviation industry.
By Deployment Mode – Cloud-Based Dominated and Is Expected to Record the Fastest Growth
The largest deployment mode category in 2025 was Cloud-Based, with a 50% share of total revenue. Cloud-Based solutions lead the market share as they provide airlines with the flexibility and scalability necessary to optimise operations. Although not all airlines have adopted this technology, the trend towards cloud solutions is gaining momentum, particularly with the government's push for digital initiatives. Cloud-Based is also forecast to expand faster than any other category, at a CAGR of 10.3% over 2026–2032. The growth of Cloud-Based deployment is propelled by the increasing demand for operational flexibility and cost efficiency among airlines. As more operators shift towards cloud solutions, this segment's lead is expected to widen significantly. Suppliers must focus on developing cloud-based offerings to align with airlines' preferences for adaptable operational solutions.
By Distribution Channel – Direct Sales Dominated, OEM Distributors Expected to Grow Fastest
Direct Sales took a 34% share of distribution channel in 2025, more than any other category. Direct Sales dominates the distribution channel due to its prevalence in software procurement among airlines. This approach allows for customised solutions and direct client engagement, which are essential in the aviation sector. OEM Distributors are set to record the highest CAGR in this split, 9.7% over 2026–2032. OEM Distributors are experiencing growth as they begin to play a more prominent role in software sales, particularly for integrated solutions. As airlines seek comprehensive packages, the significance of this channel is likely to increase. Suppliers should strengthen partnerships with OEM distributors to broaden their market reach.
By End User – Airline Operators Dominated, Cargo Airlines Expected to Grow Fastest
Airline Operators accounted for a 43% market share by end user in 2025. Airline Operators account for the largest market share as they are the primary users of Aircraft Operational Software. With the aviation sector contributing about 1.5% to India's GDP, the demand from these operators is substantial and continues to grow. Over 2026–2032, Cargo Airlines are expected to post the fastest growth, at a CAGR of 9.8%. Cargo Airlines are the fastest-growing segment due to their critical role in logistics and scheduling within the aviation industry. As e-commerce and freight demands rise, the need for specialised software solutions will accelerate growth in this area. Suppliers should tailor their solutions to meet the specific needs of Cargo Airlines to capitalise on this expanding segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Aircraft Operational Software Market Outlook
- Market Size of India Aircraft Operational Software Market, 2025
- Forecast of India Aircraft Operational Software Market, 2032
- Historical Data and Forecast of India Aircraft Operational Software Revenues & Volume for the Period 2022 - 2032F
- India Aircraft Operational Software Market Trend Evolution
- India Aircraft Operational Software Market Drivers and Challenges
- India Aircraft Operational Software Price Trends
- India Aircraft Operational Software Porter's Five Forces
- India Aircraft Operational Software Industry Life Cycle
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Software Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Flight Scheduling for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Crew Management for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Load & Trim Software for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Real-time Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Deployment Mode for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Cloud-Based for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By SaaS for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By On-Premise for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By OEM Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Airline Operators for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Charter Companies for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Cargo Airlines for the Period 2022 - 2032F
- Historical Data and Forecast of India Aircraft Operational Software Market Revenues & Volume By Ground Handlers for the Period 2022 - 2032F
- India Aircraft Operational Software Import Export Trade Statistics
- Market Opportunity Assessment By Software Type
- Market Opportunity Assessment By Deployment Mode
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- India Aircraft Operational Software Top Companies Market Share
- India Aircraft Operational Software Competitive Benchmarking By Technical and Operational Parameters
- India Aircraft Operational Software Company Profiles
- India Aircraft Operational Software Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Software Type
- Flight Scheduling
- Crew Management
- Load & Trim Software
- Real-time Monitoring
By Deployment Mode
- Cloud-Based
- SaaS
- On-Premise
- Hybrid
By Distribution Channel
- Online Platforms
- Direct Sales
- Industrial Suppliers
- OEM Distributors
By End User
- Airline Operators
- Charter Companies
- Cargo Airlines
- Ground Handlers































