India In-Car Software Platform Market Size & Growth Rate
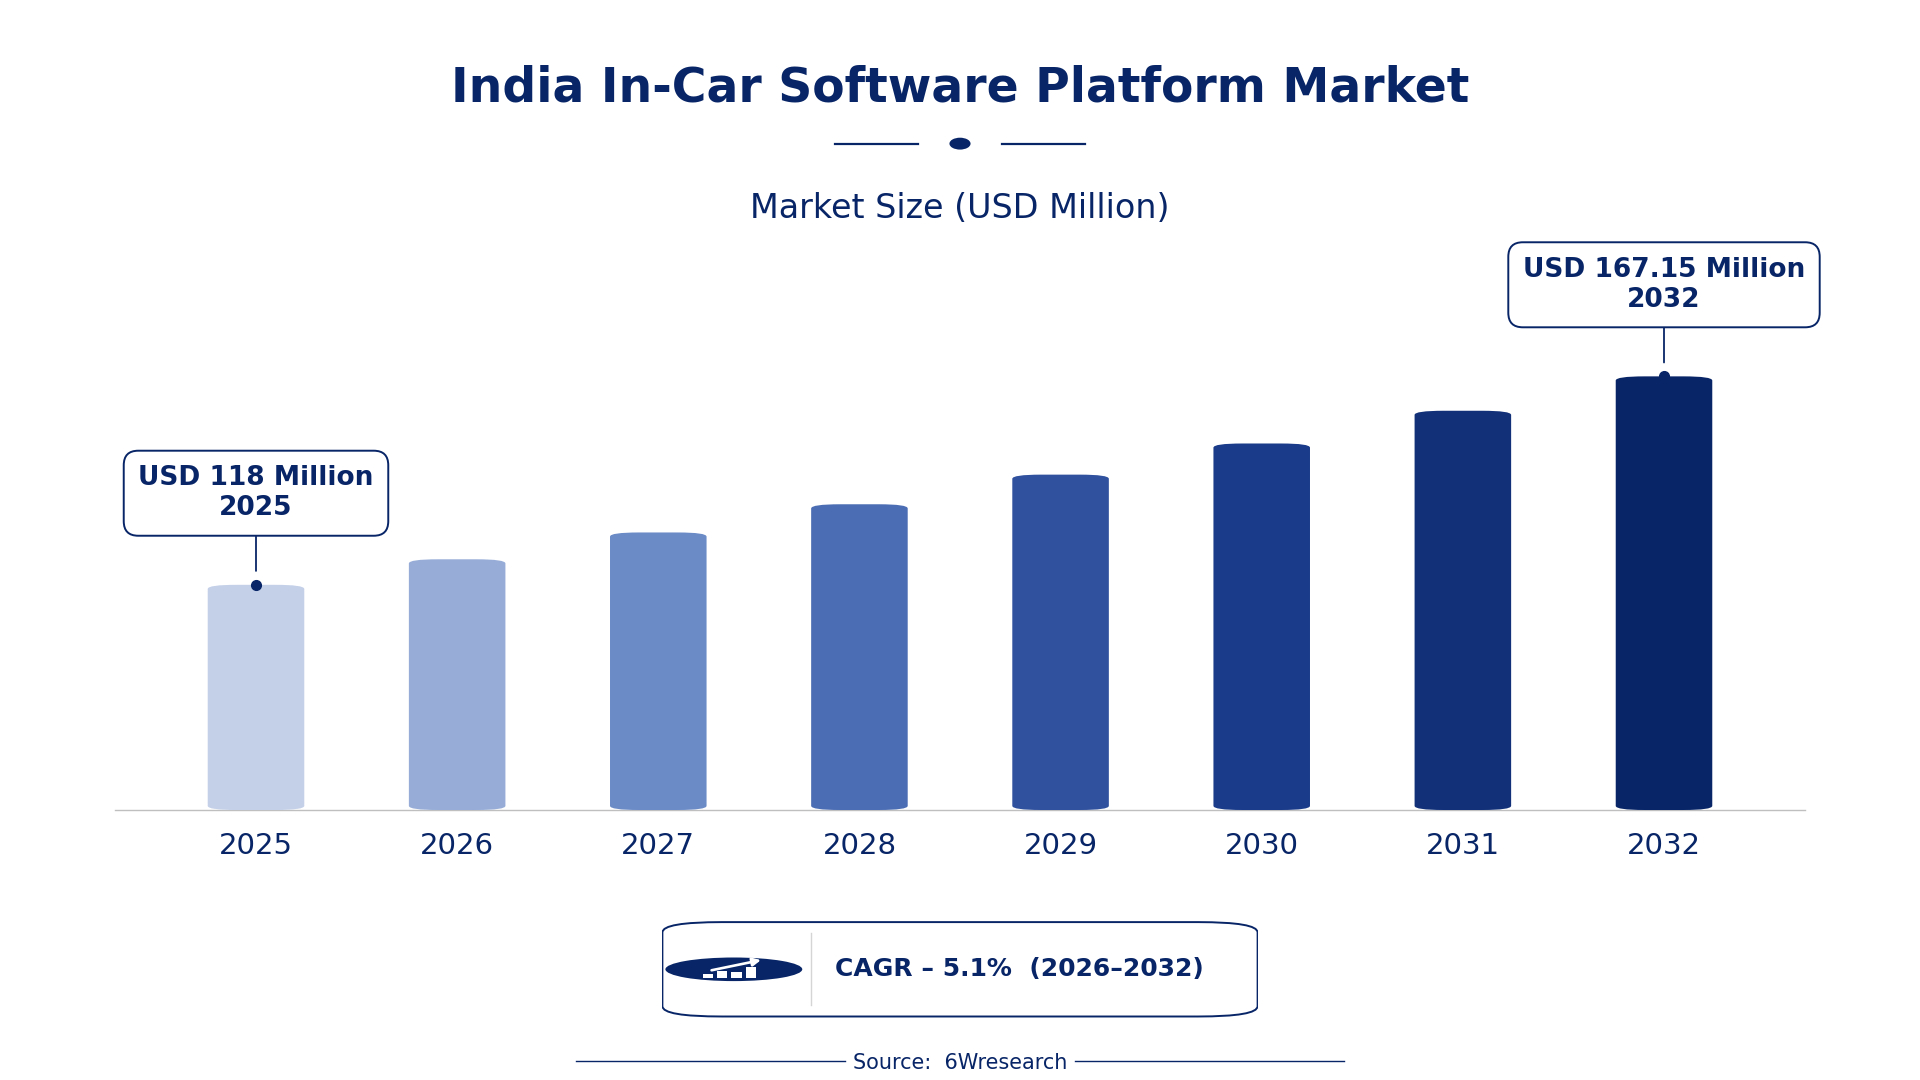
According to 6Wresearch internal database and industry insights, the India In-Car Software Platform Market was valued at USD 118.0 million in 2025 and is projected to reach USD 167.15 million by 2032, growing at a CAGR of approximately 5.1% during 2026–2032.
India In-Car Software Platform Market Highlights
| Report Metric | Details |
| Report Name | India In-Car Software Platform Market |
| Market Size 2025 | USD 118.0 million |
| Market Size 2032 | USD 167.15 million |
| Absolute Growth 2025–2032 | USD 49.15 million |
| CAGR 2026–2032 | 5.1% |
| Peak Annual Growth | 7.6% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Platform Type, 2025 | Android Automotive OS (39% share) |
| Leading OS Base, 2025 | Open Source (45% share) |
| Leading Functionality, 2025 | Infotainment (46% share) |
| Leading End User, 2025 | OEM Software Teams (39% share) |
| Fastest-Growing Platform Type | Automotive Middleware (7.0% CAGR) |
| Fastest-Growing OS Base | Safety-Critical OS (6.4% CAGR) |
| Fastest-Growing Functionality | ADAS (6.8% CAGR) |
| Fastest-Growing End User | Connectivity Developers (7.0% CAGR) |
| Growing Sector | Connectivity Developers |
| Key End Users | OEM Software Teams, Automotive Software Vendors, Tier-1 ECU Suppliers, Connectivity Developers |
India In-Car Software Platform Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
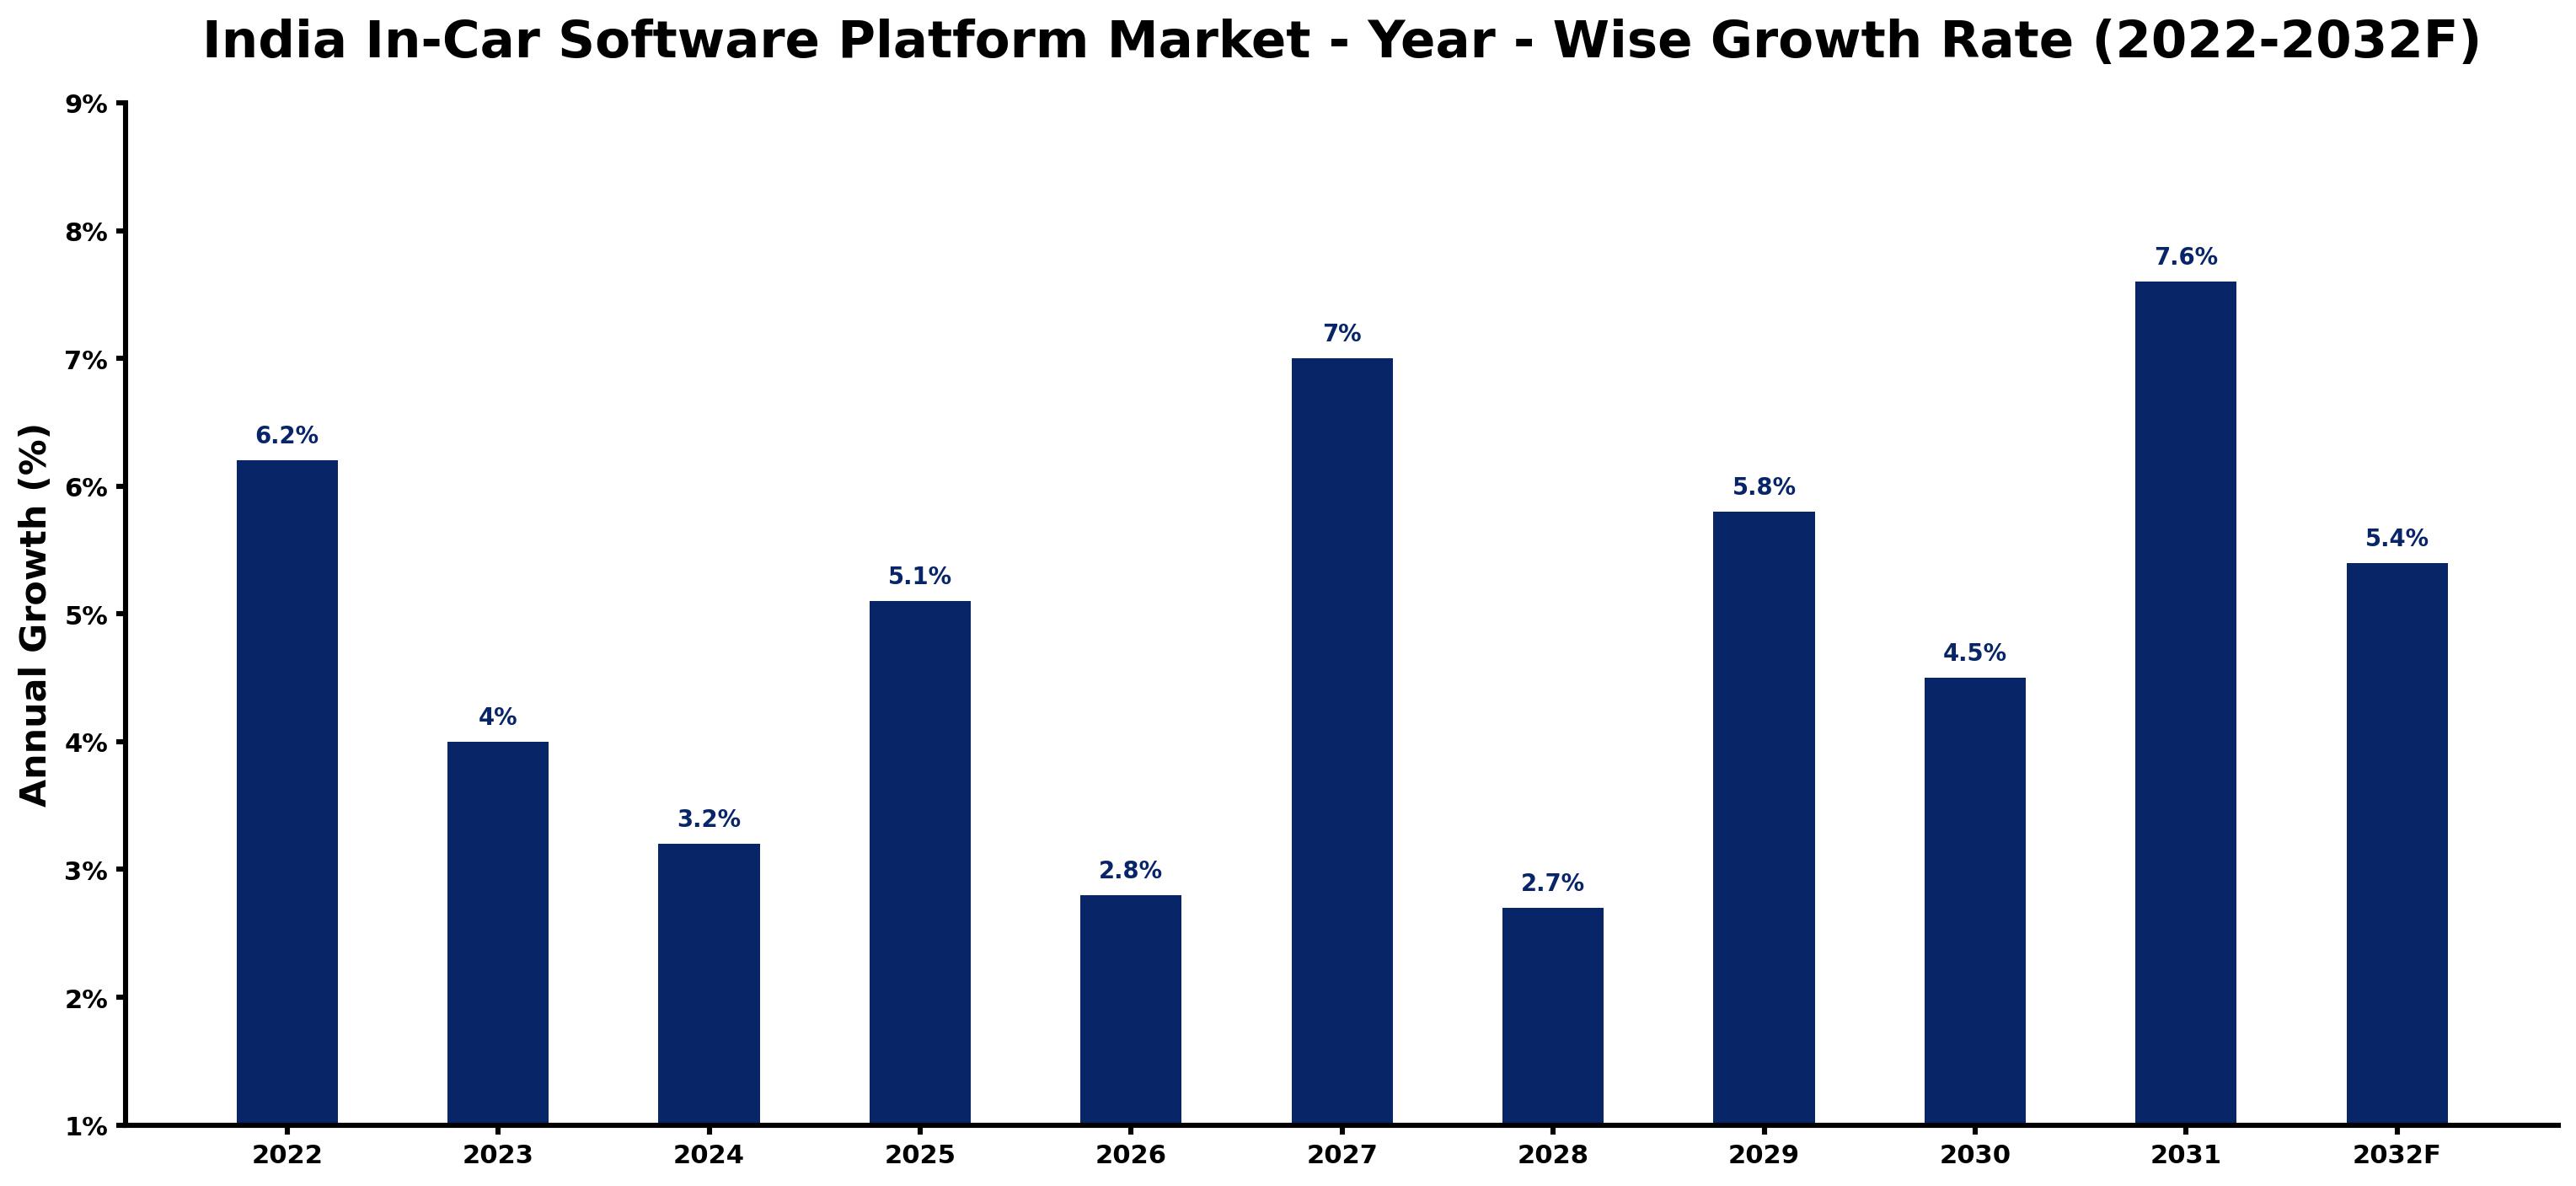
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.2 | The market experienced strong demand, driven by increased vehicle registrations and software integration. |
| 2023 | 4.0 | Growth slowed due to supply chain disruptions affecting software development and deployment. |
| 2024 | 3.2 | Continued supply chain issues constrained growth, impacting software availability for new models. |
| 2025 | 5.1 | Demand increased as automotive production ramped up, supported by the Automotive Mission Plan 2026. |
| 2026 | 2.8 | Growth is expected to slow again as the market adjusts to new technological standards and consumer preferences. |
| 2027 | 7.0 | A surge in demand is projected as OEMs focus on improving vehicle connectivity and infotainment features. |
| 2028 | 2.7 | Market growth is expected to decelerate as competition intensifies among software developers and suppliers. |
| 2029 | 5.8 | Demand will rise as more vehicles adopt advanced driver-assistance systems and infotainment solutions. |
| 2030 | 4.5 | Growth is expected to slow as the Production-Linked Incentive Scheme begins to stabilise the market. |
| 2031 | 7.6 | Peak growth is projected as the market capitalises on the rising demand for integrated software solutions. |
| 2032 | 5.4 | Growth will decelerate but remain strong, reflecting ongoing investments in automotive software innovation. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India In-Car Software Platform Market Synopsis
The In-Car Software Platform in India encompasses integrated systems designed to improve vehicle functionality and user experience through software applications. These platforms enhance driver safety, entertainment, and connectivity, utilising various operating systems. The India In-Car Software Platform Market is expanding due to rising vehicle registrations, with over 1.4 million registered vehicles annually, and the Automotive Mission Plan 2026 aiming for a 50% production increase. Demand for infotainment systems, present in 70% of new vehicles, drives this growth. OEMs are increasingly integrating advanced software solutions to meet consumer expectations.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising vehicle registrations drive demand for integrated software solutions. | Driver | High | Infotainment |
| The Automotive Mission Plan 2026 supports increased production capabilities. | Driver | High | OEM Software Teams |
| Growing demand for advanced driver-assistance systems presents new opportunities. | Opportunity | High | ADAS |
| Investment in electric vehicle technologies is expanding the software market. | Opportunity | High | Automotive Middleware |
| Supply chain disruptions hinder software availability and deployment. | Restraint | High | Embedded Linux |
| Intense competition among software developers pressures pricing and margins. | Restraint | Medium | Android Automotive OS |
| Technological advancements require constant updates and integration efforts. | Challenge | High | Connectivity Developers |
| Regulatory compliance for software safety standards increases operational costs. | Challenge | Medium | Safety-Critical OS |
Evaluation of Drivers in India In-Car Software Platform Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle registrations boost demand for software solutions. | Infotainment | With over 1.4 million vehicles registered annually, OEMs are integrating advanced software. |
| The Automotive Mission Plan 2026 enhances production capabilities. | OEM Software Teams | This initiative aims for a 50% increase in production, driving software integration. |
| Growing consumer preference for infotainment systems increases software needs. | Infotainment | Infotainment systems are now present in 70% of new vehicles sold in India. |
| Rising demand for ADAS features drives software development. | ADAS | As safety features become essential, software solutions for ADAS are increasingly sought after. |
| Investment in electric vehicle technologies expands the software market. | Automotive Middleware | The FAME India Scheme promotes electric vehicles, increasing software demand for these technologies. |
Growth in the In-Car Software Platform market in India comes from increased vehicle registrations, which boost demand for integrated software solutions. With over 1.4 million vehicles registered annually, OEMs are integrating advanced software, particularly in infotainment systems. Rising consumer preference for advanced driver-assistance systems is pushing software development, as safety features become essential in modern vehicles. The Automotive Mission Plan 2026 aims to significantly increase production capabilities, further driving software integration.
Evaluation of Restraints in India In-Car Software Platform Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder software availability and deployment. | Embedded Linux | These disruptions impact the timely delivery of software solutions to OEMs. |
| Intense competition among software developers pressures pricing and margins. | Android Automotive OS | This competition can lead to reduced profit margins for software vendors. |
| Technological advancements require constant updates and integration efforts. | Connectivity Developers | Keeping up with rapid changes increases operational costs for developers. |
| Regulatory compliance for software safety standards increases operational costs. | Safety-Critical OS | Meeting these standards requires substantial investment in testing and certification. |
| Limited awareness among consumers about advanced software functionalities. | Infotainment | This limits the potential market for innovative software solutions. |
India In-Car Software Platform Market Challenges
The India In-Car Software Platform market faces several pressing challenges, starting with a skills shortage in the automotive software sector. This gap in trained professionals delays project timelines for producers, resulting in slower innovation and missed market opportunities. Buyers experience increased costs due to strict regulatory compliance, as the Bureau of Indian Standards enforces safety protocols that can raise development expenses by 30%. Unpredictable regulations from the Ministry of Heavy Industries create uncertainty for suppliers, potentially leading to supply chain disruptions that affect product availability. Additionally, reliance on imported technologies can cause delays, impacting the timely delivery of advanced features to buyers.
Trends in the India In-Car Software Platform Market
Several trends are reshaping the India In-Car Software Platform Market; the most important are set out below.
- Increase in Infotainment System Adoption: Infotainment systems are now used in 70% of new vehicles sold in India, reflecting a shift towards improved user experience. This trend is driven by consumer demand for connectivity and entertainment features.
- Shift Towards Electric Vehicle Integration: The FAME India Scheme is promoting electric vehicles, resulting in a rise in demand for software that supports these technologies. With a target of 6 million electric vehicles, the need for advanced software solutions is growing.
- Growing Focus on Advanced Driver-Assistance Systems: As safety becomes a priority, there is an increasing demand for software solutions that support ADAS features. This trend is evident in the rising investments by OEMs in safety-critical systems.
- Rise of Automotive Middleware Solutions: Automotive Middleware is becoming essential for facilitating communication between software components. With a projected CAGR of 7.0%, this segment is gaining traction as vehicles become more connected.
Investment Opportunities in the India In-Car Software Platform Market
Below are the investment opportunities with the strongest case in the India In-Car Software Platform Market.
- Partnerships with Local Developers: Now is an ideal time to invest in partnerships with local automotive software developers, as the market is expanding rapidly. Collaborating with OEMs in Maharashtra can facilitate entry into the growing sector.
- Investment in Safety-Critical Software: With the rising need for safety features, investing in safety-critical software solutions is vital. OEM Software Teams in Tamil Nadu are actively seeking advanced software to improve vehicle safety.
- Focus on Infotainment Systems: The demand for infotainment systems is rising, presenting a lucrative opportunity for software vendors. Engaging with automotive hubs like Pune can help tap into this growing market.
- Development of Electric Vehicle Software: As electric vehicles gain traction, there is a pressing need for software solutions tailored to these technologies. Collaborating with the FAME India Scheme can provide access to funding and support.
Government Initiatives in the India In-Car Software Platform Market
The National Electric Mobility Mission Plan 2020, initiated by the Ministry of Heavy Industries, aims to promote electric vehicles and associated technologies with a target of 6 million electric vehicles. This initiative supports the development of software solutions tailored for electric vehicles, ensuring manufacturers can meet consumer demand. The Automotive Mission Plan 2026, launched by the Ministry of Heavy Industries in 2021, aims to boost manufacturing capabilities and attract investments in the automotive sector. This initiative encourages local manufacturers to adopt advanced technologies and integrate software solutions into their vehicles, targeting a 50% increase in production.
The Production-Linked Incentive Scheme for the automobile sector, introduced in 2021 by the Ministry of Heavy Industries, aims to boost domestic manufacturing and attract investments worth $3 billion. This scheme supports local manufacturers in enhancing production capabilities and integrating advanced software solutions. The National Automotive Testing and R&D Infrastructure Project, with a budget of $200 million, aims to establish testing facilities to improve automotive safety and innovation. Managed by the Ministry of Heavy Industries, this project facilitates the approval of new automotive technologies and standards, ensuring compliance with national regulations.
Future Insight of the India In-Car Software Platform Market
The India In-Car Software Platform market will undergo significant changes by 2032, driven by key developments. The Automotive Mission Plan 2026 aims to increase production, enhancing local capabilities and reducing dependency on imports. The National Automotive Testing and R&D Infrastructure Project will stimulate innovation and elevate safety standards across the sector. With over 500 automotive software vendors actively competing, advancements in user experience and connectivity will become more pronounced. The FAME India Scheme will accelerate the adoption of electric vehicles, facilitating the integration of advanced software solutions into the automotive landscape.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Platform Type – Android Automotive OS Dominated, Automotive Middleware Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, with a 39% revenue share in 2025, Android Automotive OS was the largest platform type category. Android Automotive OS holds the largest share due to its widespread adoption among vehicle manufacturers, allowing for seamless app integration. This system's flexibility makes it a top choice for enhancing user experience in Indian vehicles. Over 2026–2032, Automotive Middleware is expected to post the fastest growth, at a CAGR of 7.0%. Automotive Middleware is experiencing rapid growth as it is essential for enabling communication between various software components, crucial for the increasing complexity of in-car systems. This segment is set to expand significantly as vehicles become more interconnected and reliant on software solutions. Suppliers should prioritise the development of middleware solutions to meet the rising demand for integrated vehicle systems.
By OS Base – Open Source Dominated, Safety-Critical OS Expected to Grow Fastest
Open Source held a 45% share of the India In-Car Software Platform Market by os base in 2025. Open Source software commands the largest share as it is extensively used during the development of automotive applications, providing flexibility and cost-effectiveness. Its adaptability makes it a preferred choice for many automotive software developers in India. Safety-Critical OS is projected to grow fastest, at a CAGR of 6.4% during 2026–2032. Safety-Critical OS is growing quickly due to the increasing demand for high reliability in automotive systems, especially concerning safety features. This segment's growth reflects the industry's commitment to improving vehicle safety standards. Buyers should focus on safety-critical solutions to ensure compliance with evolving automotive safety regulations.
By Functionality – Infotainment Dominated, ADAS Expected to Grow Fastest
Infotainment accounted for a 46% market share by functionality in 2025. Infotainment systems dominate market share as they are the primary feature sought by consumers for entertainment and information in vehicles. With these systems featured in 70% of new vehicles sold, their popularity among Indian drivers is clear. ADAS is set to record the highest CAGR in this split, 6.8% over 2026–2032. ADAS is witnessing the fastest growth due to rising demand for advanced driver-assistance features that enhance safety and convenience. As consumers increasingly seek these technologies, the market for ADAS is poised for rapid expansion. Suppliers must invest in ADAS technologies to align with growing consumer expectations for enhanced vehicle safety.
By End User – OEM Software Teams Dominated, Connectivity Developers Expected to Grow Fastest
The largest end user category in 2025 was OEM Software Teams, with a 39% share of total revenue. OEM Software Teams lead the market share as they are directly responsible for developing and integrating software solutions tailored to vehicle requirements. Their crucial role in the automotive ecosystem ensures they remain at the forefront of software innovation in India. The quickest growth will come from Connectivity Developers, forecast to expand at a CAGR of 7.0% between 2026 and 2032. Connectivity Developers are growing rapidly as the demand for enhanced vehicle connectivity increases, driven by consumer expectations for seamless integration with mobile devices. This growth indicates a shift towards more connected vehicle experiences. Suppliers should align their offerings with the needs of connectivity developers to capture this expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India In-Car Software Platform Market Outlook
- Market Size of India In-Car Software Platform Market, 2025
- Forecast of India In-Car Software Platform Market, 2032
- Historical Data and Forecast of India In-Car Software Platform Revenues & Volume for the Period 2022 - 2032F
- India In-Car Software Platform Market Trend Evolution
- India In-Car Software Platform Market Drivers and Challenges
- India In-Car Software Platform Price Trends
- India In-Car Software Platform Porter's Five Forces
- India In-Car Software Platform Industry Life Cycle
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Android Automotive OS for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Embedded Linux for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By QNX for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Automotive Middleware for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By OS Base for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Open Source for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Custom Builds for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Safety-Critical OS for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By API Bridge for Apps for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Infotainment, Navigation for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Real-Time Systems for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By ADAS, Cluster Control for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Data Sharing & Sync for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By OEM Software Teams for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Automotive Software Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Tier-1 ECU Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Car Software Platform Market Revenues & Volume By Connectivity Developers for the Period 2022 - 2032F
- India In-Car Software Platform Import Export Trade Statistics
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By OS Base
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By End User
- India In-Car Software Platform Top Companies Market Share
- India In-Car Software Platform Competitive Benchmarking By Technical and Operational Parameters
- India In-Car Software Platform Company Profiles
- India In-Car Software Platform Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Platform Type
- Android Automotive OS
- Embedded Linux
- QNX
- Automotive Middleware
By OS Base
- Open Source
- Custom Builds
- Safety-Critical OS
- API Bridge for Apps
By Functionality
- Infotainment
- Navigation
- Real-Time Systems
- ADAS
- Cluster Control
- Data Sharing & Sync
By End User
- OEM Software Teams
- Automotive Software Vendors
- Tier-1 ECU Suppliers
- Connectivity Developers































