India Ready‑to‑Drink (Non-Alcoholic) Market Size & Growth Rate
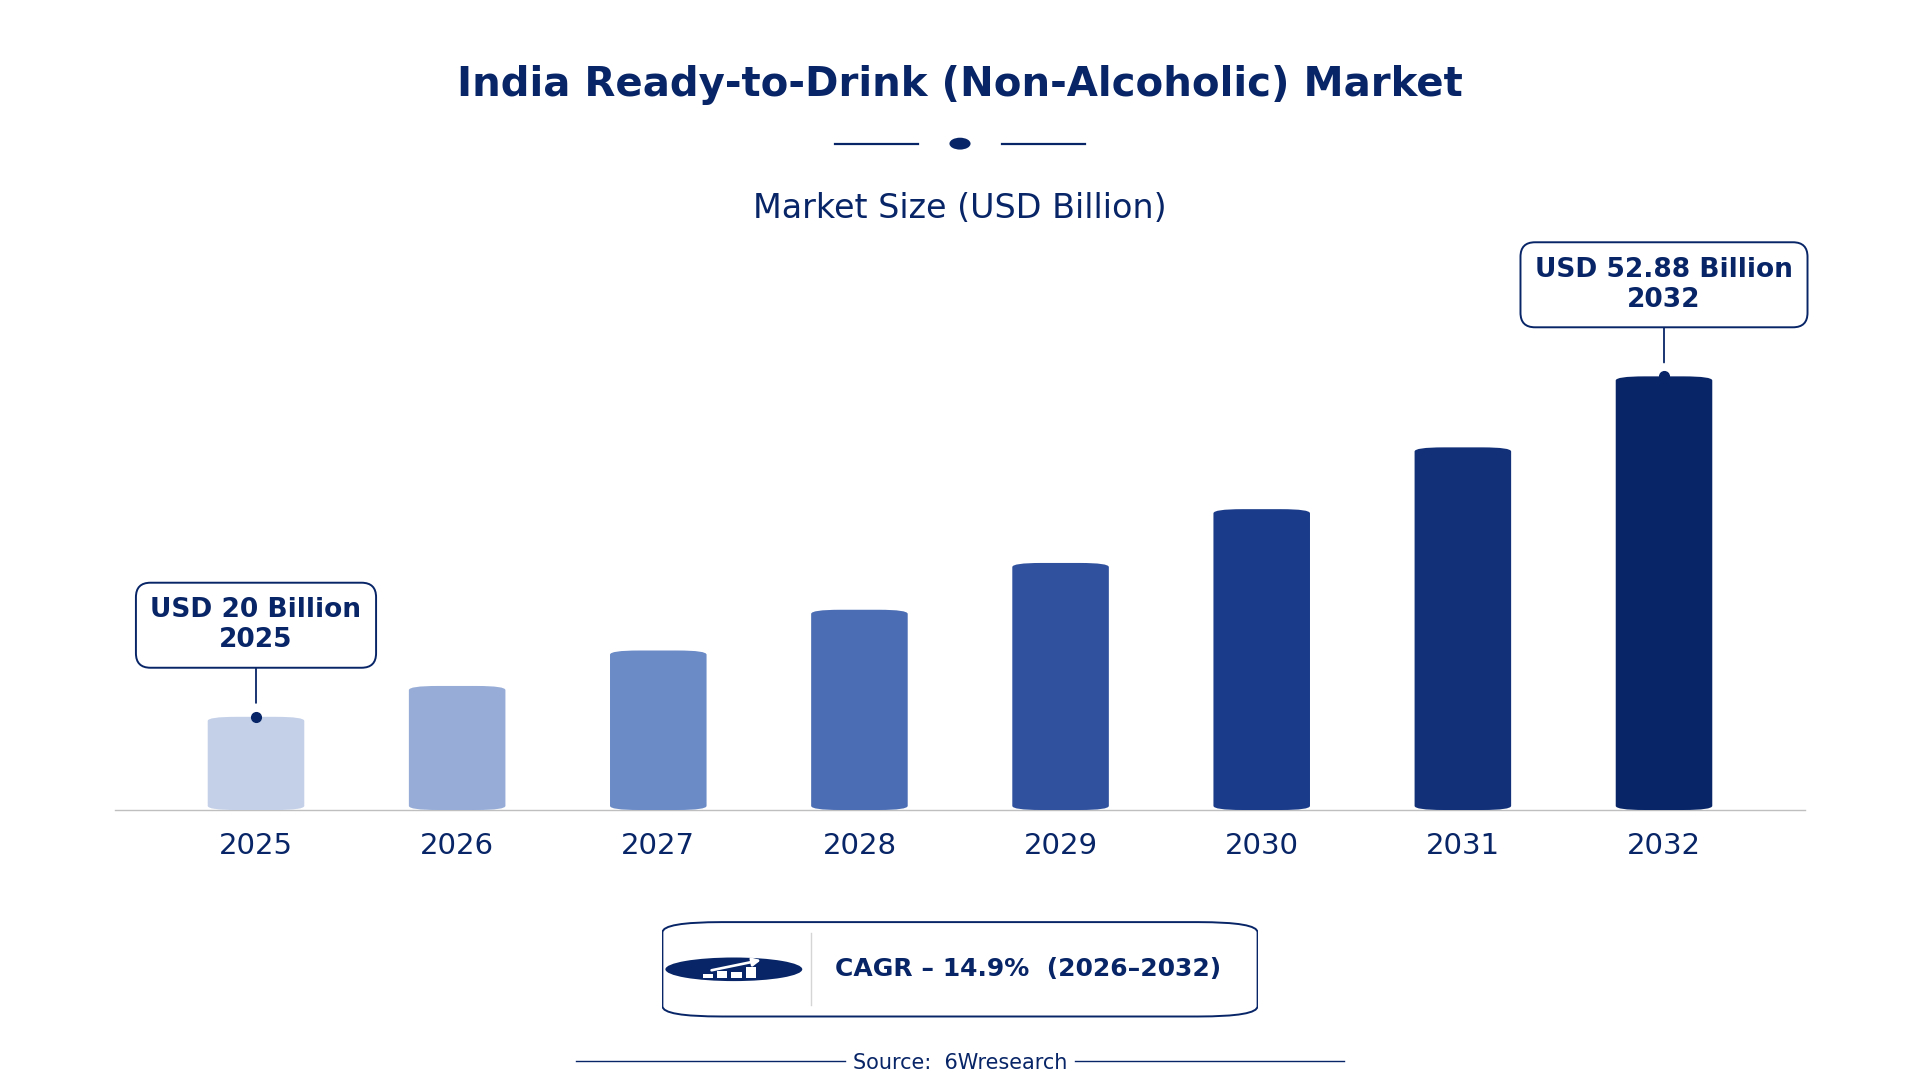
According to 6Wresearch internal database and industry insights, the India Ready‑to‑Drink (Non-Alcoholic) Market was valued at USD 20.00 billion in 2025 and is projected to reach USD 52.88 billion by 2032, growing at a CAGR of approximately 14.9% during 2026–2032.
India Ready‑to‑Drink (Non-Alcoholic) Market Highlights
| Report Metric | Details |
| Report Name | India Ready‑to‑Drink (Non-Alcoholic) Market |
| Market Size 2025 | USD 20.00 billion |
| Market Size 2032 | USD 52.88 billion |
| Absolute Growth 2025–2032 | USD 32.88 billion |
| CAGR 2026–2032 | 14.9% |
| Peak Annual Growth | 17.1% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Beverage Category, 2025 | Flavored Water (47% share) |
| Leading Flavor Profile, 2025 | Citrus/Herbal (39% share) |
| Leading Packaging Type, 2025 | Bottles (500 mL) (47% share) |
| Leading End User, 2025 | Fitness Enthusiasts (36% share) |
| Fastest-Growing Beverage Category | Functional Drinks (17.5% CAGR) |
| Fastest-Growing Flavor Profile | Electrolytes/Vitamins (16.5% CAGR) |
| Fastest-Growing Packaging Type | Pouches/Bottles (17.6% CAGR) |
| Fastest-Growing End User | Health-Conscious Consumers (15.9% CAGR) |
| Growing Sector | Functional Drinks |
| Key End Users | Fitness Enthusiasts, Health-Conscious Consumers, Urban Professionals, Family Households |
India Ready‑to‑Drink (Non-Alcoholic) Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
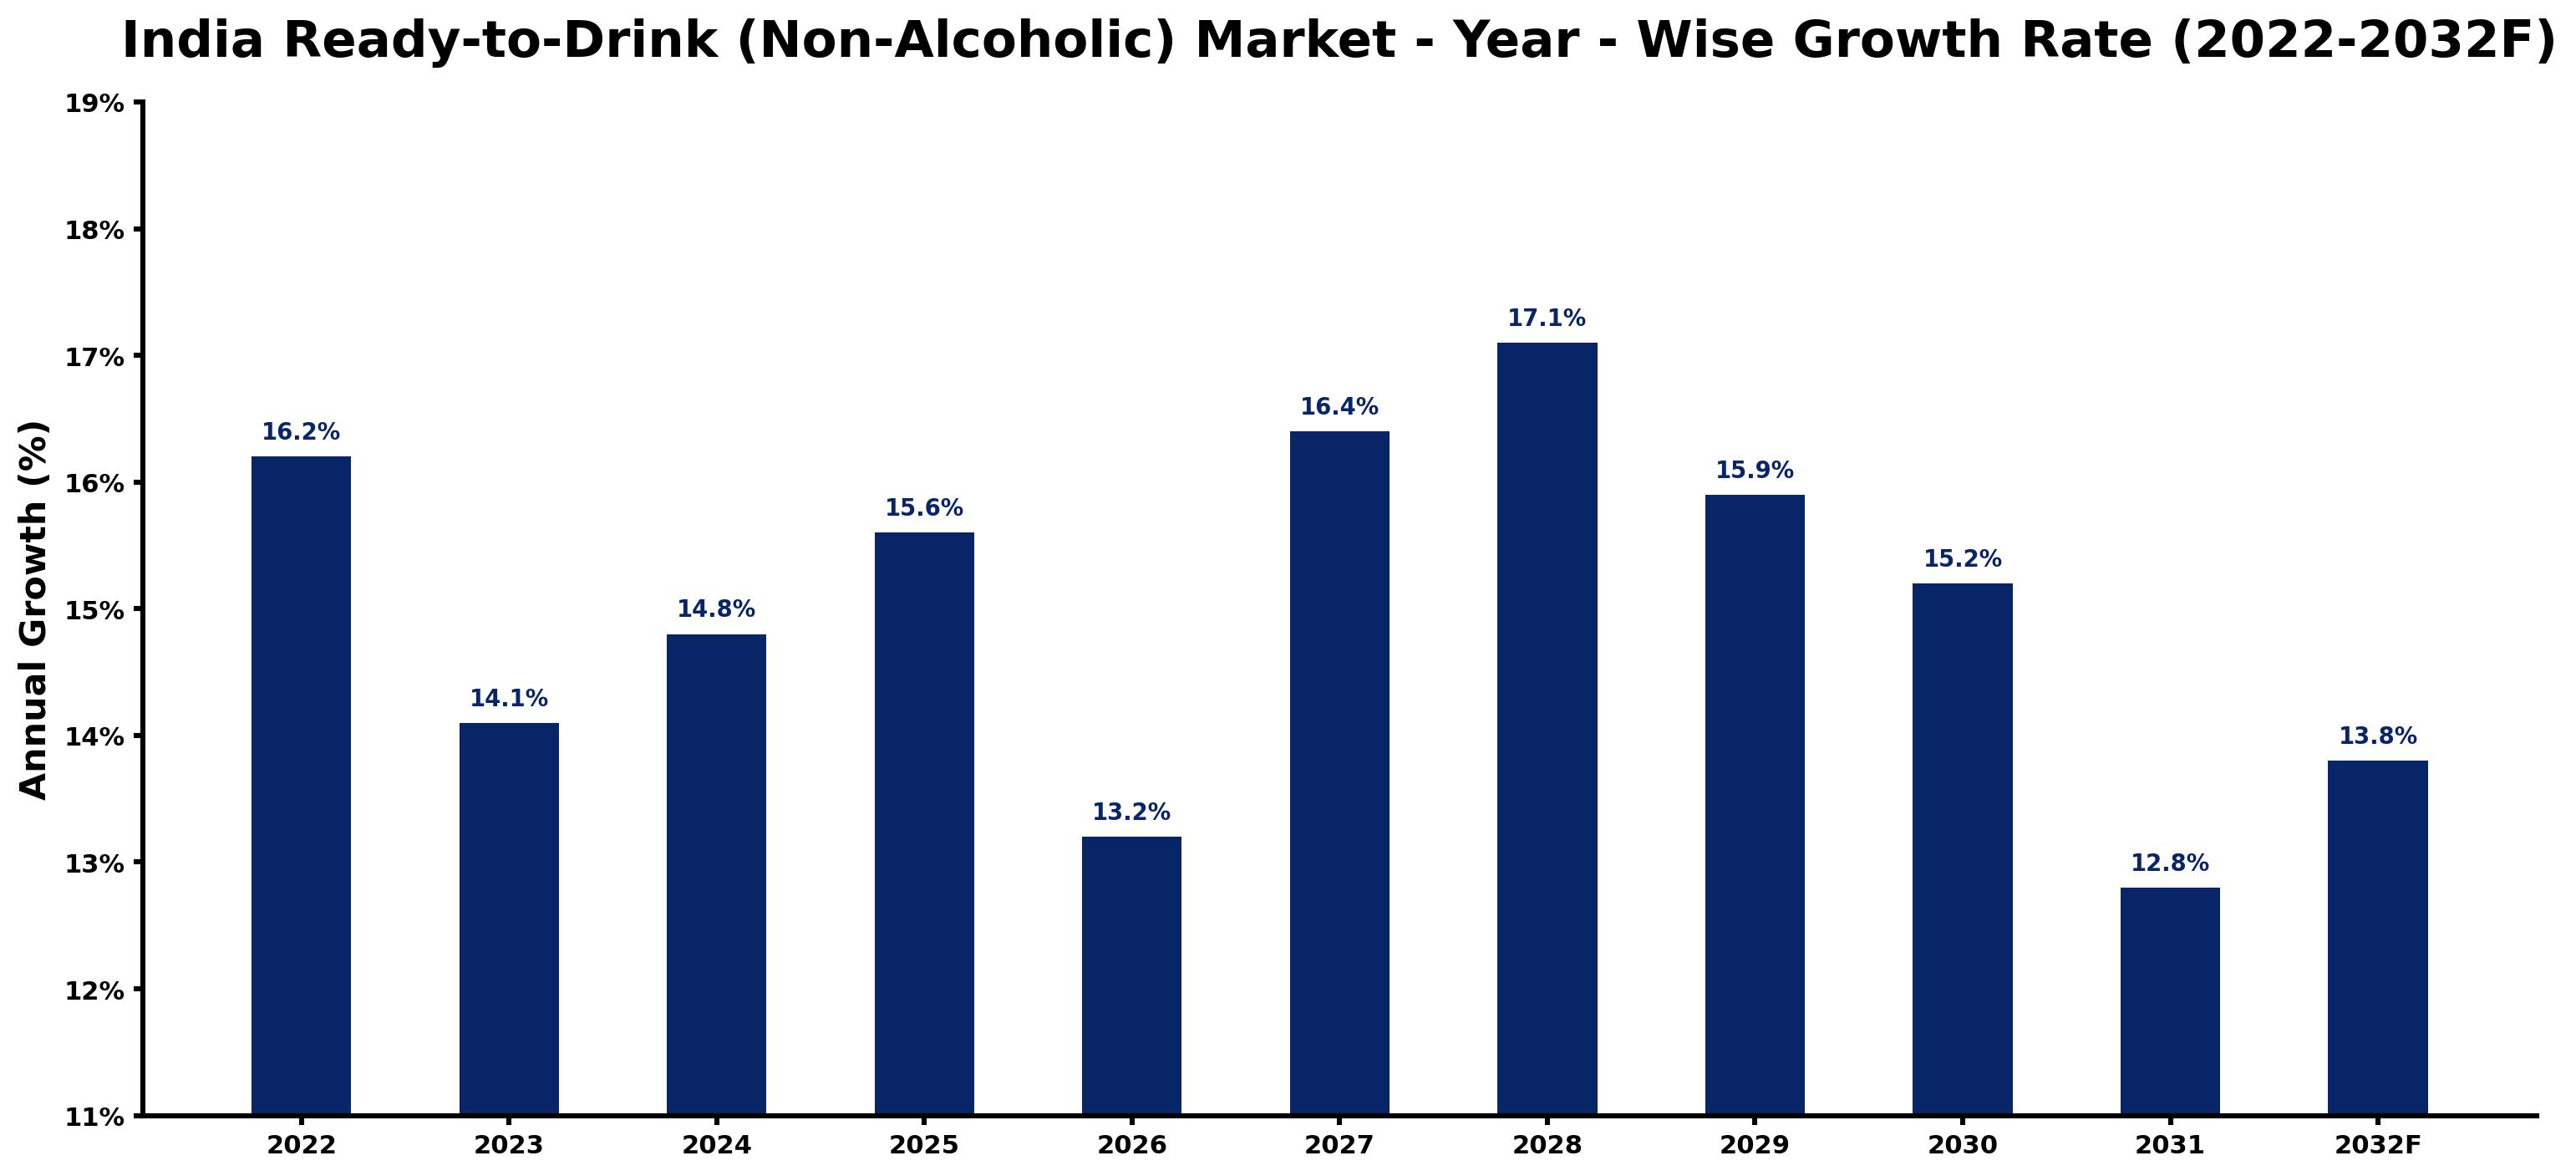
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 16.2 | The market experienced strong demand from urban areas and health-conscious consumers. |
| 2023 | 14.1 | Growth slowed due to increased local competition from the 'Atmanirbhar Bharat' initiative in the beverage sector. |
| 2024 | 14.8 | A rise in health awareness led to faster growth in functional drinks and flavored water offerings. |
| 2025 | 15.6 | Demand surged as urban households sought convenient hydration options and nutritious beverages. |
| 2026 | 13.2 | A slowdown is expected as the market adjusts to the previous year's rapid growth rates. |
| 2027 | 16.4 | Increased interest from fitness enthusiasts is projected to drive demand for functional beverages. |
| 2028 | 17.1 | The market is expected to peak as new product launches capture consumer attention and interest. |
| 2029 | 15.9 | Growth is projected to slow as market saturation begins to affect purchasing patterns and preferences. |
| 2030 | 15.2 | A continued slowdown is expected as health trends stabilise consumer preferences for beverages. |
| 2031 | 12.8 | Demand is projected to normalise as buyers adjust to market conditions and product offerings. |
| 2032 | 13.8 | Growth is expected to accelerate again as innovative packaging solutions attract more consumers. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Ready‑to‑Drink (Non-Alcoholic) Market Synopsis
The Ready-to-Drink (Non-Alcoholic) Market in India includes pre-packaged beverages designed for immediate consumption. These products, made with water, flavouring agents, and sweeteners, cater to hydration and convenience needs. The market thrives, driven by health-conscious consumers and family households, with urban areas contributing over 60% of total beverage consumption. Functional drinks and flavoured water are key growth segments, with flavoured water projected to grow by 15% annually in urban markets. The ongoing push for hydration from the National Institute of Nutrition further fuels this demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Urbanisation and health trends drive demand for convenient hydration solutions. | Driver | High | Flavored Water |
| Growing fitness culture increases interest in functional beverages with health benefits. | Driver | High | Functional Drinks |
| Urban professionals are seeking premium beverage options for convenience and taste. | Opportunity | High | Cold Brew Teas & Coffees |
| The market for sustainable packaging solutions is expanding, attracting eco-conscious buyers. | Opportunity | Medium | Juice Blends |
| Price sensitivity among family households limits premium product purchases. | Restraint | High | Juice Blends |
| Regulatory compliance costs can burden local producers, impacting pricing strategies. | Restraint | Medium | Functional Drinks |
| Supply chain disruptions can delay product availability for retailers and consumers. | Challenge | High | Cold Brew Teas & Coffees |
| Competition from international brands can pressure local manufacturers on pricing. | Challenge | Medium | Flavored Water |
Evaluation of Drivers in India Ready‑to‑Drink (Non-Alcoholic) Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Urban areas contribute to over 60% of beverage consumption. | Flavored Water | This high demand drives local producers to increase their output and variety to meet consumer preferences. |
| Health-conscious consumers represent 35% of the market. | Functional Drinks | This demographic seeks beverages that offer health benefits, increasing purchases and driving market growth. |
| The average Indian consumes about 20 liters of non-alcoholic beverages annually. | Juice Blends | This consumption level indicates a steady demand for diverse beverage options, encouraging producers to innovate. |
| Cold brew coffee has gained a 12% market share among urban professionals. | Cold Brew Teas & Coffees | This popularity encourages producers to innovate and expand their offerings to attract this demographic. |
| The National Institute of Nutrition promotes hydration through non-alcoholic beverages. | Flavored Water | This initiative raises awareness, resulting in increased consumption and demand for these products. |
Growth in the Ready‑to‑Drink (Non-Alcoholic) market in India comes from rising urbanisation, health trends, and increased consumption of diverse beverages. Urban areas account for over 60% of demand, prompting producers to expand their offerings to meet consumer preferences. The average Indian consumes about 20 liters of non-alcoholic beverages annually, indicating consistent demand for various products. Health-conscious consumers, who represent 35% of the market, are increasingly seeking functional drinks that offer health benefits. Additionally, the National Institute of Nutrition's promotion of hydration encourages greater consumption of flavored water, further boosting market growth.
Evaluation of Restraints in India Ready‑to‑Drink (Non-Alcoholic) Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Price sensitivity among family households limits premium product purchases. | Juice Blends | This sensitivity affects purchasing decisions, resulting in lower sales of higher-priced items and limiting market growth. |
| Regulatory compliance costs can burden local producers, impacting pricing strategies. | Functional Drinks | These costs can lead to higher retail prices, deterring price-sensitive consumers from purchasing these products. |
| Supply chain disruptions can delay product availability for retailers and consumers. | Cold Brew Teas & Coffees | Delays can result in lost sales opportunities and reduced market presence for local producers. |
| Limited consumer awareness of health benefits can slow the adoption of functional drinks. | Functional Drinks | Without awareness, potential buyers may not seek out these products, hindering market growth. |
| Competition from international brands can pressure local manufacturers on pricing. | Flavored Water | This competition can create price wars, affecting profit margins for local producers and limiting their market share. |
India Ready‑to‑Drink (Non-Alcoholic) Market Challenges
Urban buyers in the India Ready-to-Drink (Non-Alcoholic) market face supply challenges due to inconsistent availability of key ingredients, which can delay product launches and hinder market growth. Suppliers encounter rising costs from ingredient price inflation, with flavored water averaging around 30 INR for a 500 mL bottle, squeezing profit margins for producers. Health-conscious buyers struggle with limited product options, as only 35% of offerings meet their nutritional needs, leading to missed sales opportunities for retailers. Regulatory hurdles from ISO 22000 compliance can extend approval timelines for new beverages, delaying market entry for suppliers and impacting their competitiveness.
Trends in the India Ready‑to‑Drink (Non-Alcoholic) Market
Several trends are reshaping the India Ready‑to‑Drink (Non-Alcoholic) Market; the most important are set out below.
- Shift towards Health-Conscious Beverages: India is experiencing a shift towards health-conscious beverage choices, with functional drinks gaining traction. In 2023, these beverages reported a 10% increase in sales, appealing to health-focused consumers seeking nutritious options.
- Rise of Sustainable Packaging: The trend towards sustainable packaging is gaining momentum in India, with a growing focus on eco-friendly solutions. The market for sustainable packaging solutions is projected to expand, attracting environmentally conscious buyers looking for responsible products.
- Increased Popularity of Cold Brew: Cold brew coffee is becoming increasingly popular among urban professionals, capturing a 12% market share. This trend reflects a shift towards premium beverage options that cater to discerning consumers seeking quality.
- Growth of Flavoured Water: Flavoured water is rapidly gaining popularity as a hydration solution in urban areas. With a projected annual growth rate of 15%, it caters to health-conscious consumers seeking convenient and refreshing options.
Investment Opportunities in the India Ready‑to‑Drink (Non-Alcoholic) Market
Below are the investment opportunities with the strongest case in the India Ready‑to‑Drink (Non-Alcoholic) Market.
- Expansion of Functional Drink Offerings: The demand for functional drinks is increasing, with a 10% sales rise in 2023. Local manufacturers can invest in developing new products targeting health-conscious consumers, particularly in urban areas looking for nutritious options.
- Investment in Sustainable Packaging Solutions: With a growing focus on sustainability, there is an opportunity to invest in eco-friendly packaging. Local beverage manufacturers can collaborate with sustainable packaging firms to meet consumer demand for environmentally friendly products.
- Targeting Urban Professionals: Urban professionals represent a key demographic for premium beverages, with cold brew coffee capturing a 12% market share. Companies can focus on marketing and distribution strategies tailored to this group to enhance sales.
- Development of Juice Blends with Added Nutrients: The trend towards health-conscious consumption opens opportunities for juice blends fortified with vitamins. Family households are a key demographic, and products that offer added health benefits can attract buyers looking for nutritious options.
Government Initiatives in the India Ready‑to‑Drink (Non-Alcoholic) Market
The Food Safety and Standards Authority of India (FSSAI) enforces beverage quality and safety regulations, ensuring compliance with ISO 22000 standards. The 'Atmanirbhar Bharat' initiative, launched in 2023, supports local beverage manufacturers by boosting domestic production and reducing reliance on imports. This initiative enhances the operational framework for producers, enabling them to meet safety and quality standards while promoting local manufacturing. Additionally, the Ministry of Food Processing Industries has implemented various measures to support local producers in maintaining compliance with safety regulations and improving their market competitiveness.
The Ministry of Food Processing Industries oversees funding for local beverage production, approving projects that align with national goals. This agency supports initiatives that enhance the capabilities of local manufacturers, providing financial assistance and resources to improve production processes. The All India Soft Drink Manufacturers' Association also plays a role in advocating for industry standards and practices, ensuring that producers adhere to regulatory requirements while fostering growth in the sector. In 2023, the ministry approved several projects aimed at enhancing local production capabilities, benefiting both producers and consumers.
Future Insight of the India Ready‑to‑Drink (Non-Alcoholic) Market
The India Ready-to-Drink (Non-Alcoholic) market is set for evolution by 2032, driven by urban consumers' growing preference for healthier beverage choices. The 'Atmanirbhar Bharat' initiative will enhance local production capabilities, improving supply chain efficiency. Increased demand for functional drinks will reflect a broader health trend, attracting more investment in this segment. Sustainable packaging solutions will gain importance as environmental awareness rises among consumers, while ongoing hydration campaigns by the National Institute of Nutrition will further boost market demand, creating new opportunities for producers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Beverage Category – Flavored Water Dominated, Functional Drinks Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Flavored Water accounted for a 47% market share by beverage category in 2025. Flavored water holds the largest market share as it caters to the hydration needs of urban consumers who prioritise convenience. With over 60% of demand stemming from these areas, it effectively addresses the preferences of health-conscious buyers. Functional Drinks are projected to grow fastest, at a CAGR of 17.5% during 2026–2032. Functional drinks are experiencing rapid growth due to their popularity among fitness enthusiasts who value health benefits in their beverages. This segment is set to expand further, driven by increasing consumer awareness of nutrition and hydration. Suppliers should focus on developing functional drink options to capitalise on this growing market segment.
By Flavor Profile – Citrus/Herbal Dominated, Electrolytes/Vitamins Expected to Grow Fastest
In 2025, Citrus/Herbal led the flavor profile split with a 39% share. Citrus and herbal flavours dominate the market share as they are commonly found in various flavored products, appealing to a wide range of consumers. Their refreshing taste is particularly attractive to individuals seeking enjoyable hydration alternatives. Over 2026–2032, Electrolytes/Vitamins are expected to post the fastest growth, at a CAGR of 16.5%. Electrolyte and vitamin-infused beverages are rapidly gaining traction, especially among fitness enthusiasts who prioritise hydration and nutritional benefits. This segment's growth is propelled by a heightened focus on health and wellness among consumers. Marketers should actively promote electrolyte and vitamin beverages to effectively engage the health-oriented consumer base.
By Packaging Type – Bottles (500 mL) Dominated, Pouches/Bottles Expected to Grow Fastest
The largest packaging type category in 2025 was Bottles (500 mL), with a 47% share of total revenue. Bottles of 500 mL are the most popular packaging size, appealing to consumers for their convenience and portability. This format is widely accepted in the market, making it a preferred choice for ready-to-drink beverages. The quickest growth will come from Pouches/Bottles, forecast to expand at a CAGR of 17.6% between 2026 and 2032. Pouches and bottles are becoming increasingly popular due to their convenience and ease of use, particularly among on-the-go consumers. This shift indicates a growing demand for flexible packaging solutions that cater to modern lifestyles. Manufacturers should invest in diverse packaging options to meet the changing preferences of consumers.
By End User – Fitness Enthusiasts Dominated, Health-Conscious Consumers Expected to Grow Fastest
Fitness Enthusiasts took a 36% share of end user in 2025, more than any other category. Fitness enthusiasts represent the primary target market, significantly shaping the demand for beverages that support their active lifestyles. This group seeks products that enhance performance and recovery, contributing to their notable market share. Health-Conscious Consumers are set to record the highest CAGR in this split, 15.9% over 2026–2032. Health-conscious consumers are the fastest-growing demographic, increasingly seeking beverages that align with their wellness goals. Their heightened focus on nutrition is driving demand for products tailored to their needs. Brands should refine their marketing strategies to better connect with health-conscious consumers and address their specific preferences.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Outlook
- Market Size of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market, 2025
- Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market, 2032
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Revenues & Volume for the Period 2022 - 2032F
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Trend Evolution
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Drivers and Challenges
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Price Trends
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Porter's Five Forces
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Industry Life Cycle
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Beverage Category for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Flavored Water for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Functional Drinks for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Cold Brew Teas & Coffees for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Juice Blends for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Flavor Profile for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Citrus/Herbal for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Electrolytes/Vitamins for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Black/Green/Herbal for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Fruit/Veggie Mixes for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Packaging Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Bottles (500 mL) for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Pouches/Bottles for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Cans/Bottles for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Tetra Pack for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Fitness Enthusiasts for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Health-Conscious Consumers for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Urban Professionals for the Period 2022 - 2032F
- Historical Data and Forecast of India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Market Revenues & Volume By Family Households for the Period 2022 - 2032F
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Import Export Trade Statistics
- Market Opportunity Assessment By Beverage Category
- Market Opportunity Assessment By Flavor Profile
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By End User
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Top Companies Market Share
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Competitive Benchmarking By Technical and Operational Parameters
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Company Profiles
- India Ready to Drink (Non-Alcoholic) ) ) ) ) ) Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Beverage Category
- Flavored Water
- Functional Drinks
- Cold Brew Teas & Coffees
- Juice Blends
By Flavor Profile
- Citrus/Herbal
- Electrolytes/Vitamins
- Black/Green/Herbal
- Fruit/Veggie Mixes
By Packaging Type
- Bottles (500 mL)
- Pouches/Bottles
- Cans/Bottles
- Tetra Pack
By End User
- Fitness Enthusiasts
- Health-Conscious Consumers
- Urban Professionals
- Family Households































