India Semiconductor Supply Chain Market Size & Growth Rate
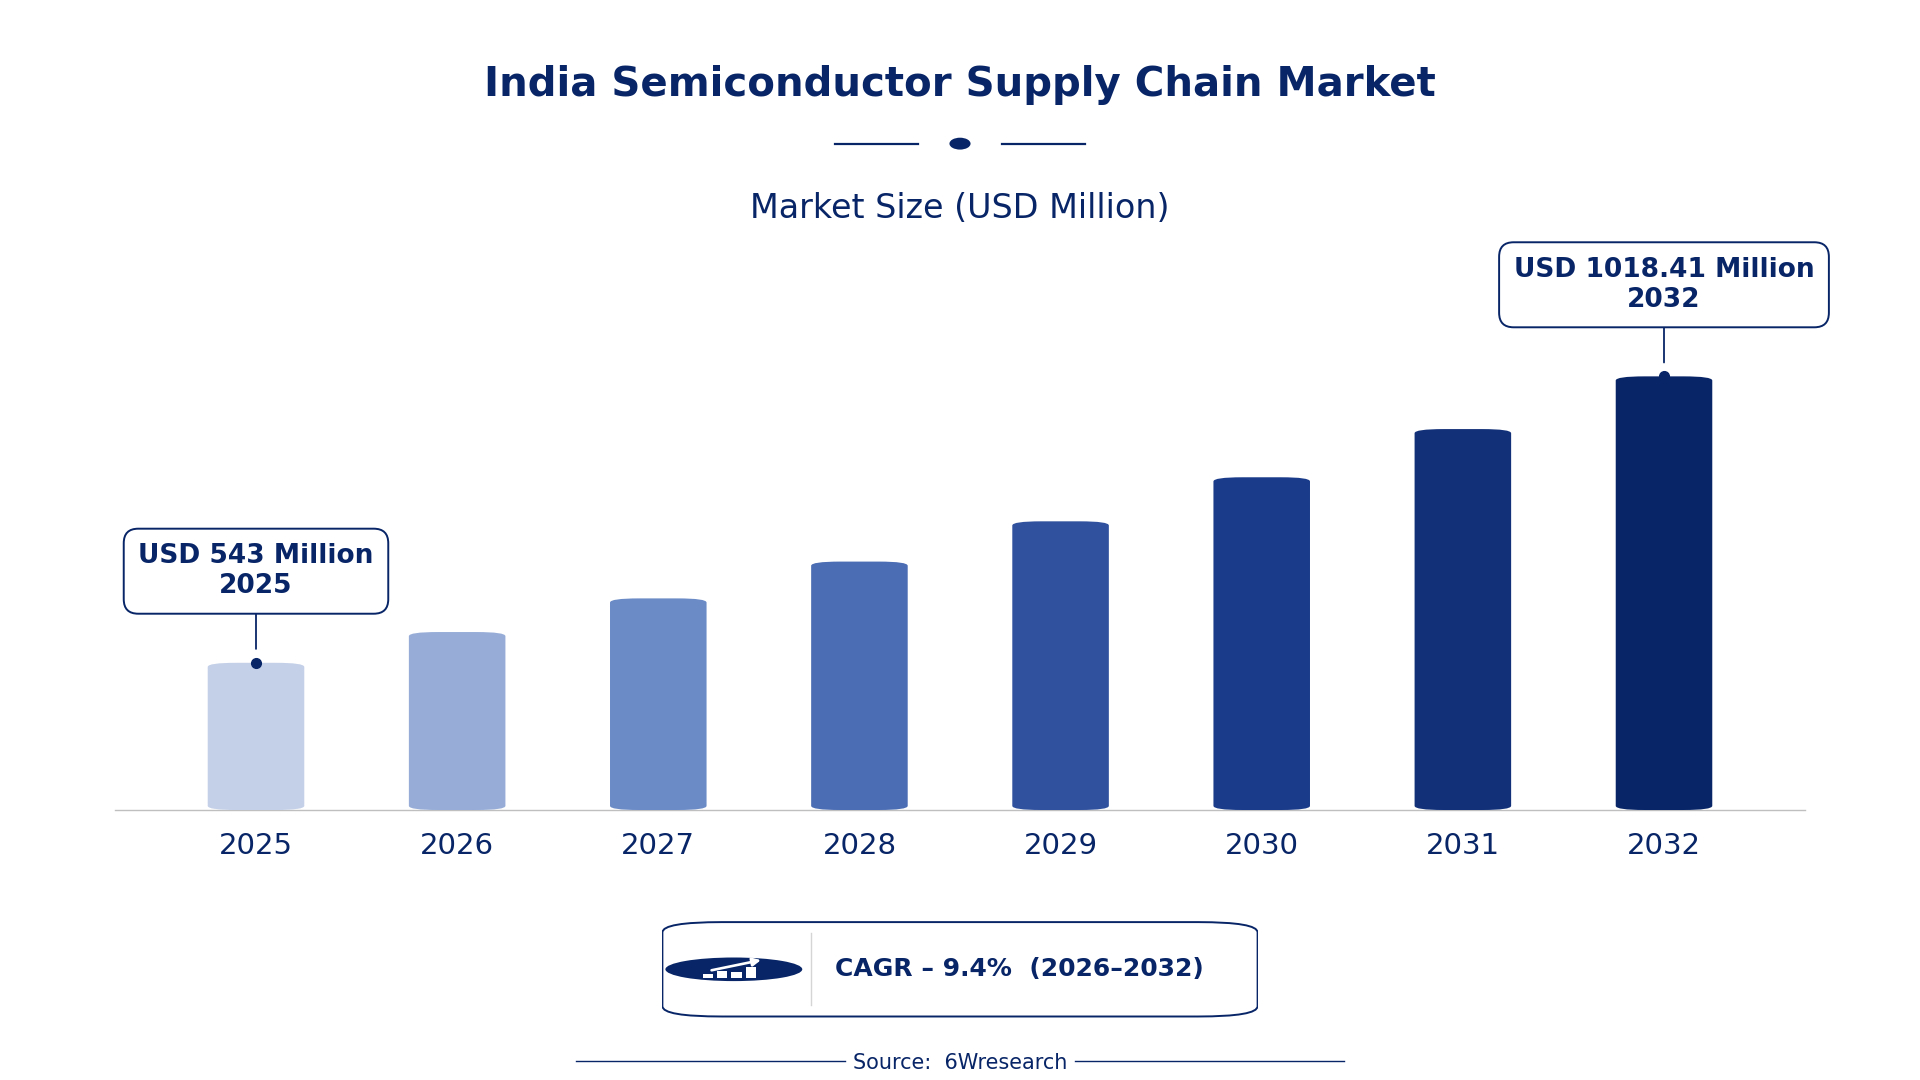
According to 6Wresearch internal database and industry insights, the India Semiconductor Supply Chain Market was valued at USD 543.0 million in 2025 and is projected to reach USD 1,018.41 million by 2032, growing at a CAGR of approximately 9.4% during 2026–2032.
India Semiconductor Supply Chain Market Highlights
| Report Metric | Details |
| Report Name | India Semiconductor Supply Chain Market |
| Market Size 2025 | USD 543.0 million |
| Market Size 2032 | USD 1,018.41 million |
| Absolute Growth 2025–2032 | USD 475.41 million |
| CAGR 2026–2032 | 9.4% |
| Peak Annual Growth | 12.4% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Segment Type, 2025 | Foundries (43% share) |
| Leading Activity Type, 2025 | Wafer Fabrication (35% share) |
| Leading End User, 2025 | Integrated Device Makers (40% share) |
| Fastest-Growing Segment Type | OSAT (11.7% CAGR) |
| Fastest-Growing Activity Type | Assembly & Test (12.0% CAGR) |
| Fastest-Growing End User | Automotive/Electronics OEMs (11.2% CAGR) |
| Growing Sector | Automotive/Electronics OEMs |
| Key End Users | Integrated Device Makers, Fabless Companies, Automotive/Electronics OEMs, Semiconductor Fabs |
India Semiconductor Supply Chain Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
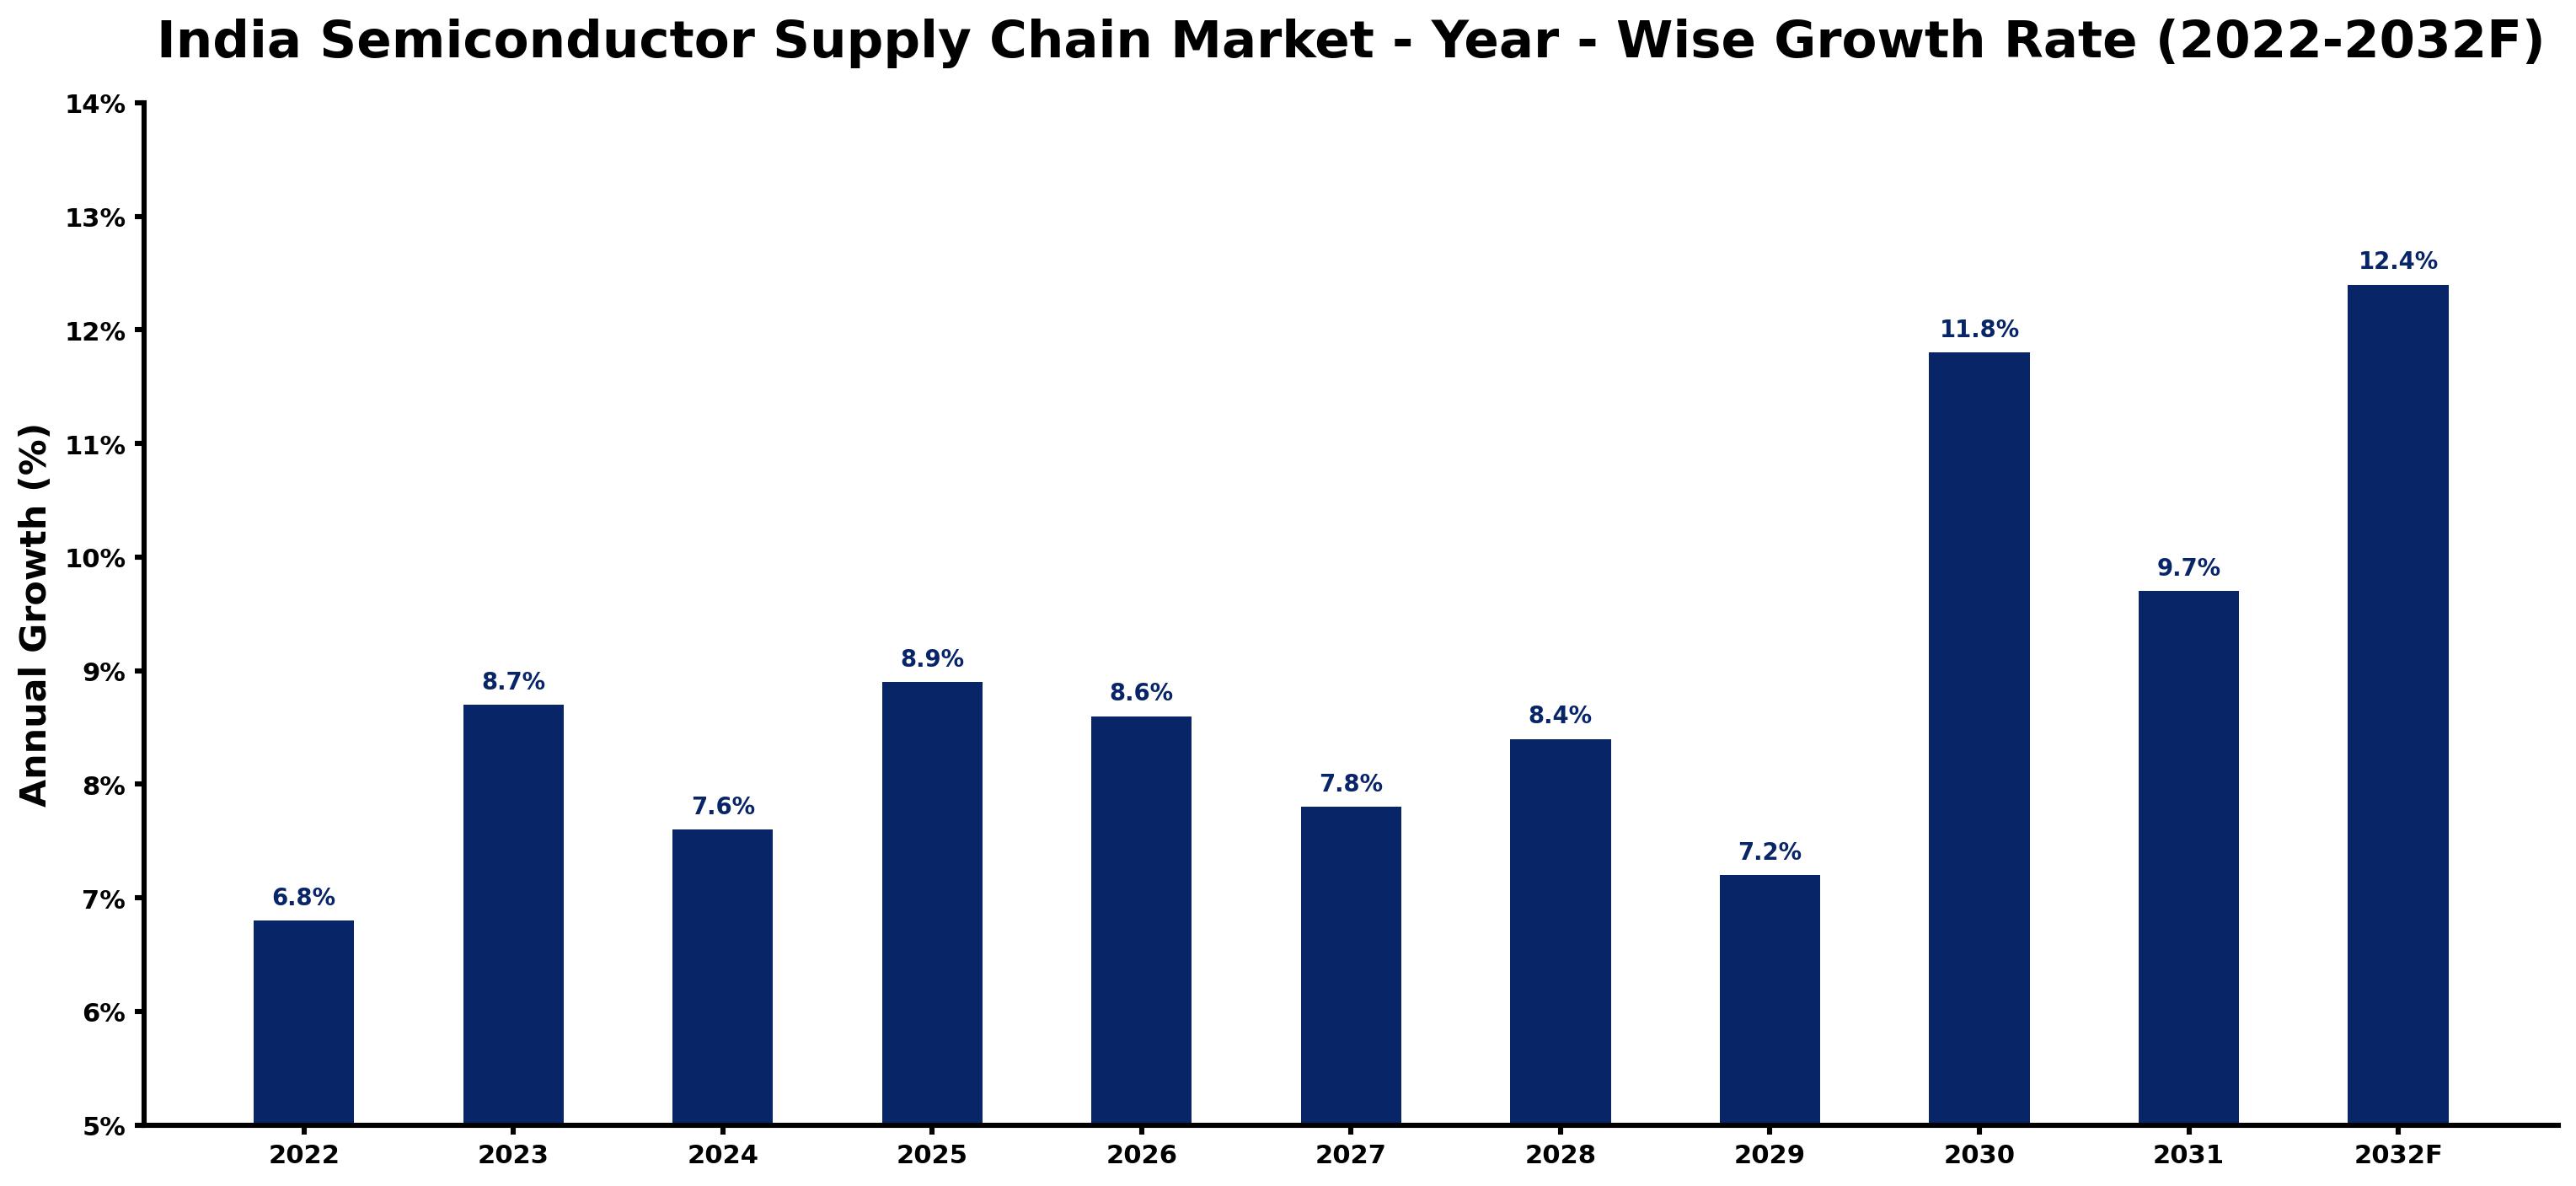
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.8 | The semiconductor supply chain experienced steady demand from local electronics manufacturers. |
| 2023 | 8.7 | Demand surged due to increased automotive production requiring more semiconductor components. |
| 2024 | 7.6 | Growth moderated as supply chain adjustments took place amid rising global demand. |
| 2025 | 8.9 | The market saw renewed momentum with the launch of new semiconductor fabs in Maharashtra. |
| 2026 | 8.6 | Demand growth is expected to slow slightly as manufacturers adjust to new production capacities. |
| 2027 | 7.8 | The market will continue to grow, supported by rising electronic consumption in urban areas. |
| 2028 | 8.4 | Growth is projected to pick up again as automotive OEMs expand their semiconductor requirements. |
| 2029 | 7.2 | The market is expected to experience a slowdown as global supply chain issues persist. |
| 2030 | 11.8 | Demand will accelerate with the government's push for local semiconductor production initiatives. |
| 2031 | 9.7 | Growth is projected to decelerate slightly as the 'Production Linked Incentive Scheme' stabilises investments in the sector. |
| 2032 | 12.4 | The semiconductor supply chain is expected to peak as domestic manufacturing capabilities mature. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Semiconductor Supply Chain Market Synopsis
The Semiconductor Supply Chain in India includes the design, manufacturing, and assembly of semiconductor devices. This encompasses wafer fabrication and assembly testing, primarily catering to the electronics, automotive, and telecommunications sectors. Demand is fuelled by local consumption and export potential. Government initiatives, particularly the Semiconductor Mission, are driving growth in this sector and establishing a solid foundation for semiconductor production.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand for semiconductors in the automotive sector drives growth, as manufacturers seek local supply to meet rising production needs. | Driver | High | Automotive/Electronics OEMs |
| Government initiatives such as the Semiconductor Mission promote local manufacturing, incentivising investments in semiconductor fabs. | Driver | High | Integrated Device Makers |
| The gap in local semiconductor production presents opportunities for investment in manufacturing facilities, particularly in tech hubs like Bengaluru. | Opportunity | High | Semiconductor Fabs |
| The growing demand for assembly and test services creates opportunities for OSAT providers to expand their operations in India. | Opportunity | High | OSAT |
| A skills shortage in the semiconductor industry hampers production capabilities, leading to delays and increased operational costs for suppliers. | Restraint | High | Foundries |
| Intense competition from established global players limits profit margins for local semiconductor manufacturers, affecting their sustainability. | Restraint | High | Design Houses |
| Outdated manufacturing technology results in inefficiencies, causing longer lead times that hinder buyers' ability to meet demand. | Challenge | High | Wafer Fabrication |
| Regulatory hurdles in establishing new semiconductor facilities can delay project timelines, impacting the overall supply chain. | Challenge | Medium | Assembly & Test |
Evaluation of Drivers in India Semiconductor Supply Chain Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased automotive production drives semiconductor demand. | Automotive/Electronics OEMs | India's automotive sector is expected to require 30% more semiconductors by 2025. |
| Government initiatives boost local manufacturing capabilities. | Semiconductor Fabs | The 'Semiconductor Mission' allocated $10 billion to promote domestic manufacturing. |
| Growing electronics consumption fuels demand for semiconductors. | Integrated Device Makers | India's population drives high demand for electronics. |
| Expansion of semiconductor design houses increases production capacity. | Design Houses | Over 20 semiconductor design houses are concentrated in key tech hubs. |
| Rising investments in semiconductor equipment support growth. | Equipment Suppliers | The installed base of semiconductor manufacturing equipment in India is increasing. |
The automotive sector is anticipated to require 30% more semiconductors by 2025, prompting higher purchases from manufacturers. India’s large population generates substantial demand for electronics, further bolstering the market. The concentration of semiconductor design houses in key tech hubs also improves production capacity.
Evaluation of Restraints in India Semiconductor Supply Chain Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited availability of skilled professionals hampers production capacity. | Wafer Fabrication | The semiconductor industry employs over 200,000 professionals, but demand exceeds supply. |
| High initial capital investment for semiconductor fabs restricts new entrants. | Foundries | Setting up a semiconductor fab can cost billions, deterring potential investors. |
| Regulatory hurdles delay project approvals for new facilities. | Semiconductor Fabs | Complex approval processes can extend timelines for establishing new fabs. |
| Intense competition from established global players affects local market share. | Design Houses | Local design houses face challenges competing against well-established international firms. |
| Supply chain disruptions due to global dependencies pose challenges for local producers. | OSAT | The semiconductor industry is heavily influenced by the global electronics supply chain. |
India Semiconductor Supply Chain Market Challenges
Buyers and suppliers in the India Semiconductor Supply Chain market encounter a notable skills shortage, resulting from insufficient specialised training programs. This gap leads to production delays, costing producers up to 20% more in operational expenses as they struggle to fill critical roles. Intense competition from international markets complicates the situation, as local firms often find it challenging to match the pricing of established global players, squeezing profit margins for suppliers. Furthermore, outdated technology in some manufacturing facilities causes inefficiencies, leading to longer lead times that impede buyers' ability to meet rising demand.
Trends in the India Semiconductor Supply Chain Market
Several trends are reshaping the India Semiconductor Supply Chain Market; the most important are set out below.
- Shift towards Local Semiconductor Manufacturing: India is increasingly focusing on local semiconductor production to reduce reliance on imports. The 'Make in India' initiative aims to strengthen domestic manufacturing capabilities, with substantial investments being made to support the local semiconductor ecosystem.
- Emergence of Automotive Electronics: The automotive sector is rapidly integrating advanced electronics, driving semiconductor demand. By 2025, India's automotive sector is expected to require 30% more semiconductors, reflecting the growing trend of smart vehicles.
- Growth of Semiconductor Design Houses: The number of semiconductor design houses in India is on the rise, particularly in tech hubs like Bengaluru. With over 20 design houses, this segment is vital for innovation and supporting local manufacturing.
- Expansion of Assembly and Testing Facilities: The assembly and testing segment is experiencing significant growth, with a CAGR of 12.0% projected from 2026 to 2032. This trend is evident in the establishment of new facilities in Maharashtra and Gujarat.
Investment Opportunities in the India Semiconductor Supply Chain Market
Some of the investment opportunities in the India Semiconductor Supply Chain Market are mentioned below.
- Bengaluru as a Tech Hub: Bengaluru is emerging as a prominent tech hub for semiconductor design and manufacturing. With over 20 design houses, the city offers opportunities for collaboration and investment in local production capabilities.
- Investment in Semiconductor Fabs: The semiconductor fab segment is poised for growth, driven by government incentives. The 'Production Linked Incentive Scheme' encourages investments from global players, boosting local manufacturing capabilities.
- Skill Development Programs: With a growing demand for skilled professionals, investment in training programs is crucial. The Electronics Sector Skill Council of India offers training for semiconductor manufacturing, addressing the skills gap.
- Research and Development Centers: The establishment of semiconductor R&D centers across major tech hubs presents a key opportunity. The government has announced initiatives to support these centers, fostering innovation and local talent.
Government Initiatives in the India Semiconductor Supply Chain Market
The semiconductor supply chain in India is shaped by several recent policies aimed at improving local manufacturing capabilities. The 'National Policy on Electronics 2019' seeks to achieve $400 billion in electronics manufacturing by 2025, promoting semiconductor production. Additionally, the 'Semiconductor Mission' launched in 2021 with a budget of $10 billion aims to attract investments and enhance domestic manufacturing. These measures are designed to create a supportive environment for semiconductor production and innovation in the country.
The 'Production Linked Incentive Scheme' introduced in 2021 incentivises semiconductor manufacturing by providing financial support to eligible companies. The Ministry of Electronics and Information Technology oversees this scheme, ensuring effective allocation of funds to improve local production capabilities. Furthermore, the 'Electronics Manufacturing Cluster Scheme' launched in 2020 supports the establishment of semiconductor manufacturing facilities, promoting regional development and job creation. These initiatives aim to strengthen India's semiconductor supply chain.
Future Insight of the India Semiconductor Supply Chain Market
The India Semiconductor Supply Chain market will undergo transformative changes by 2032, driven by several key initiatives. The government's 'Semiconductor Mission' will enhance local production capabilities, while the 'Make in India' initiative will further support domestic manufacturing. By 2025, India's automotive sector is projected to require 30% more semiconductors, highlighting the increasing need for local supply. Strengthened collaboration with R&D institutions will also facilitate innovation, enabling suppliers to better align with evolving market requirements.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Segment Type – Foundries Dominated, OSAT Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Foundries accounted for a 43% market share by segment type in 2025. Foundries dominate the semiconductor supply chain as they manufacture semiconductor wafers for various clients, which is essential for the overall supply chain. Their significance is underscored by the semiconductor fabs concentrated in Maharashtra and Gujarat, which support robust production capabilities. The quickest growth will come from OSAT, forecast to expand at a CAGR of 11.7% between 2026 and 2032. The OSAT segment is experiencing rapid growth due to the increasing demand for assembly and testing services, particularly as the automotive sector is projected to require 30% more semiconductors by 2025. This trend will likely continue as the installed base of semiconductor manufacturing equipment expands, reinforcing OSAT's critical role in the supply chain. Suppliers should focus on enhancing their capabilities in foundry and OSAT services to effectively capture the expanding market share.
By Activity Type – Wafer Fabrication Dominated, Assembly & Test Expected to Grow Fastest
In 2025, Wafer Fabrication led the activity type split with a 35% share. Wafer Fabrication leads the market share because it is the critical process for creating semiconductor wafers, which are foundational to the entire supply chain. The concentration of semiconductor fabs in Maharashtra and Gujarat further solidifies this segment's leading position. Assembly & Test is set to record the highest CAGR in this split, 12.0% over 2026–2032. Assembly & Test is the fastest-growing segment, driven by the increasing need for final assembly and testing of semiconductor devices as the electronics market expands. The government's initiatives to boost local manufacturing will likely accelerate this growth. Buyers should consider investing in assembly and testing capabilities to meet the rising demand for semiconductor devices.
By End User – Integrated Device Makers Dominated, Automotive/Electronics OEMs Expected to Grow Fastest
The largest end user category in 2025 was Integrated Device Makers, with a 40% share of total revenue. Integrated Device Makers hold the largest market share as they both design and manufacture semiconductors, making them integral to the supply chain. Their influence is substantial, with over 200,000 professionals employed in the semiconductor industry, highlighting their critical role in driving innovation. Automotive/Electronics OEMs are projected to grow fastest, at a CAGR of 11.2% during 2026–2032. Automotive/Electronics OEMs are the fastest-growing end user segment, propelled by the increasing integration of semiconductors in their products, which is essential for modern electronics. This trend is expected to persist as the automotive sector advances with more sophisticated technologies, further driving demand. Suppliers must align their strategies with the evolving requirements of automotive and electronics OEMs to effectively capture the growing market share.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Semiconductor Supply Chain Market Outlook
- Market Size of India Semiconductor Supply Chain Market, 2025
- Forecast of India Semiconductor Supply Chain Market, 2032
- Historical Data and Forecast of India Semiconductor Supply Chain Revenues & Volume for the Period 2022 - 2032F
- India Semiconductor Supply Chain Market Trend Evolution
- India Semiconductor Supply Chain Market Drivers and Challenges
- India Semiconductor Supply Chain Price Trends
- India Semiconductor Supply Chain Porter's Five Forces
- India Semiconductor Supply Chain Industry Life Cycle
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Segment Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Design Houses for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By OSAT for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Equipment Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Activity Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By IP/Chip Design for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Wafer Fabrication for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Assembly & Test for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Tool Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Fabless Companies for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Integrated Device Makers for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Automotive/Electronics OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Supply Chain Market Revenues & Volume By Semiconductor Fabs for the Period 2022 - 2032F
- India Semiconductor Supply Chain Import Export Trade Statistics
- Market Opportunity Assessment By Segment Type
- Market Opportunity Assessment By Activity Type
- Market Opportunity Assessment By End User
- India Semiconductor Supply Chain Top Companies Market Share
- India Semiconductor Supply Chain Competitive Benchmarking By Technical and Operational Parameters
- India Semiconductor Supply Chain Company Profiles
- India Semiconductor Supply Chain Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Segment Type
- Design Houses
- Foundries
- OSAT
- Equipment Suppliers
By Activity Type
- IP/Chip Design
- Wafer Fabrication
- Assembly & Test
- Tool Manufacturing
By End User
- Fabless Companies
- Integrated Device Makers
- Automotive/Electronics OEMs
- Semiconductor Fabs































