China Semiconductor Supply Chain Market Size & Growth Rate
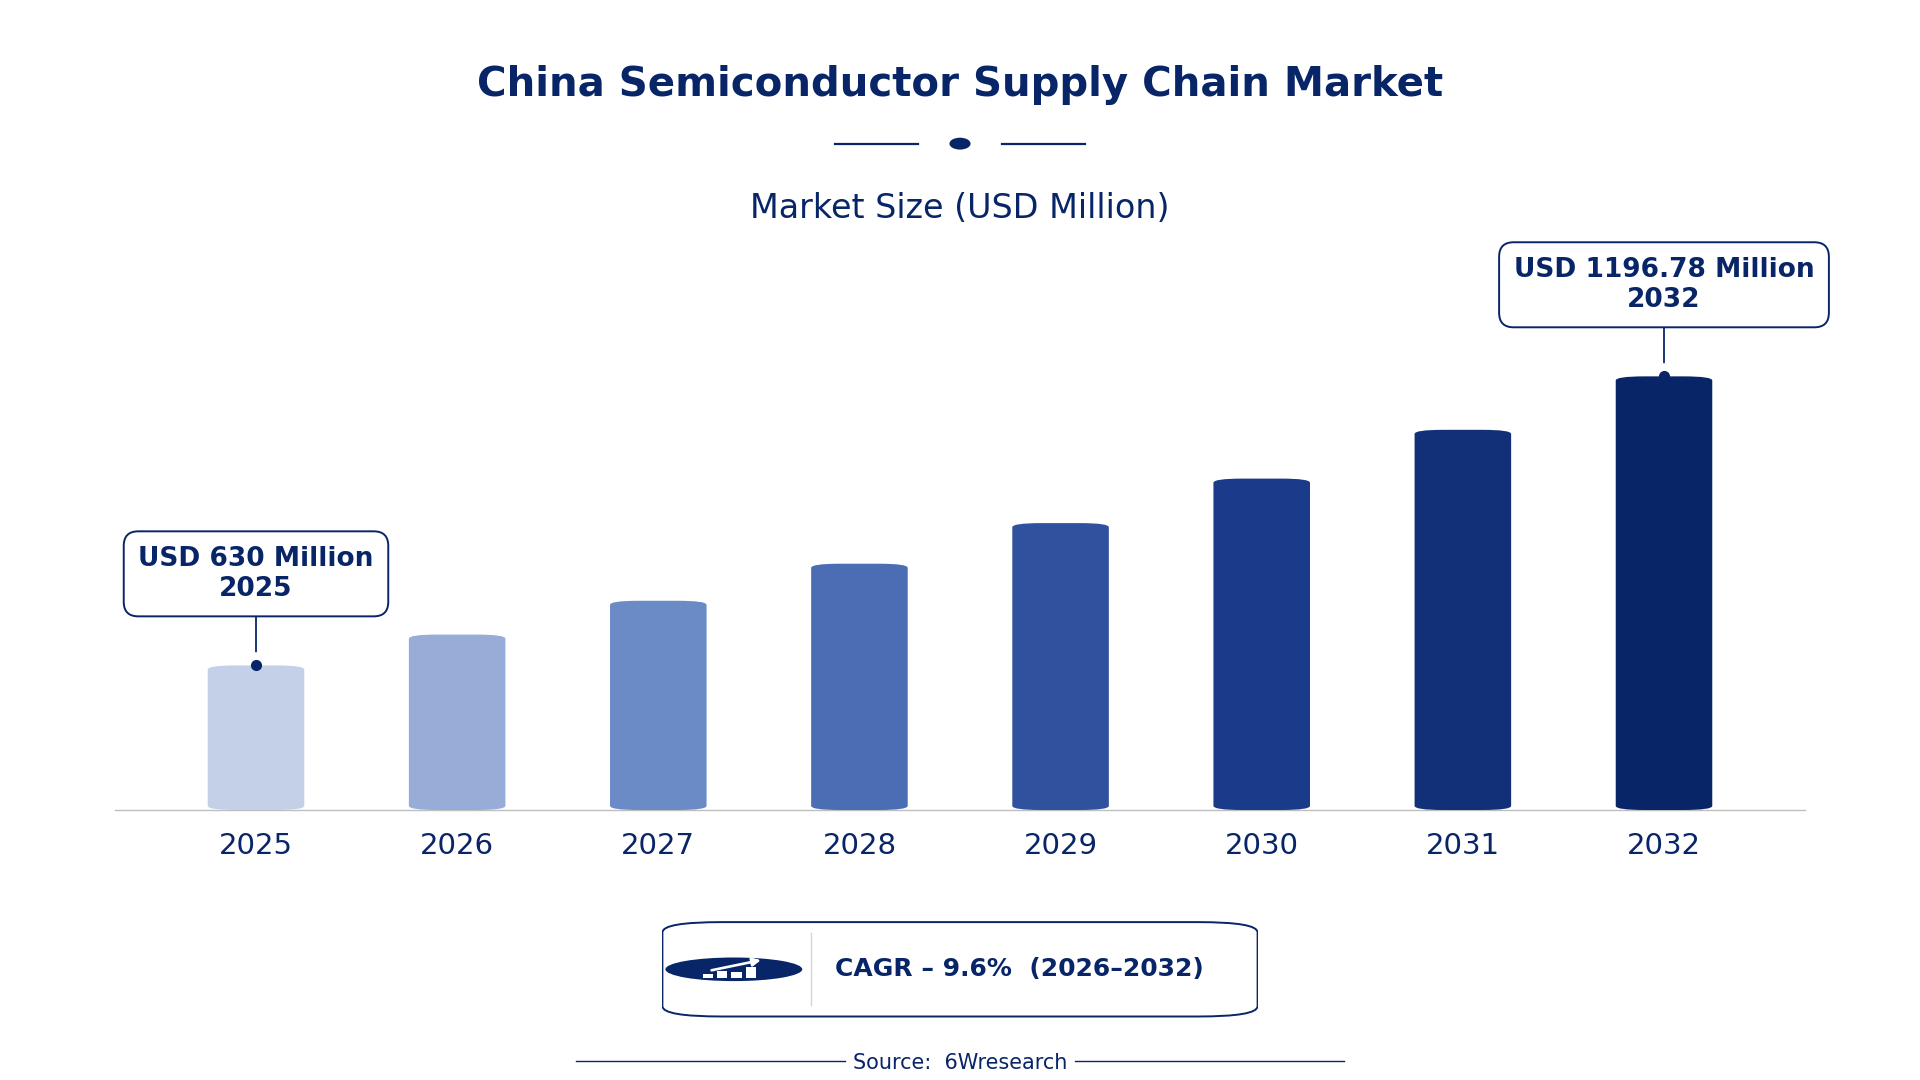
According to 6Wresearch internal database and industry insights, the China Semiconductor Supply Chain Market was valued at USD 630.0 million in 2025 and is projected to reach USD 1,196.78 million by 2032, growing at a CAGR of approximately 9.6% during 2026–2032.
China Semiconductor Supply Chain Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Supply Chain Market |
| Market Size 2025 | USD 630.0 million |
| Market Size 2032 | USD 1,196.78 million |
| Absolute Growth 2025–2032 | USD 566.78 million |
| CAGR 2026–2032 | 9.6% |
| Peak Annual Growth | 11.8% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Segment Type, 2025 | Foundries (49% share) |
| Leading Activity Type, 2025 | Wafer Fabrication (48% share) |
| Leading End User, 2025 | Integrated Device Makers (48% share) |
| Fastest-Growing Segment Type | OSAT (11.4% CAGR) |
| Fastest-Growing Activity Type | Assembly & Test (10.7% CAGR) |
| Fastest-Growing End User | Fabless Companies (11.1% CAGR) |
| Growing Sector | Semiconductor Manufacturing |
| Key End Users | Integrated Device Makers, Foundries, OSAT, Equipment Suppliers |
China Semiconductor Supply Chain Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
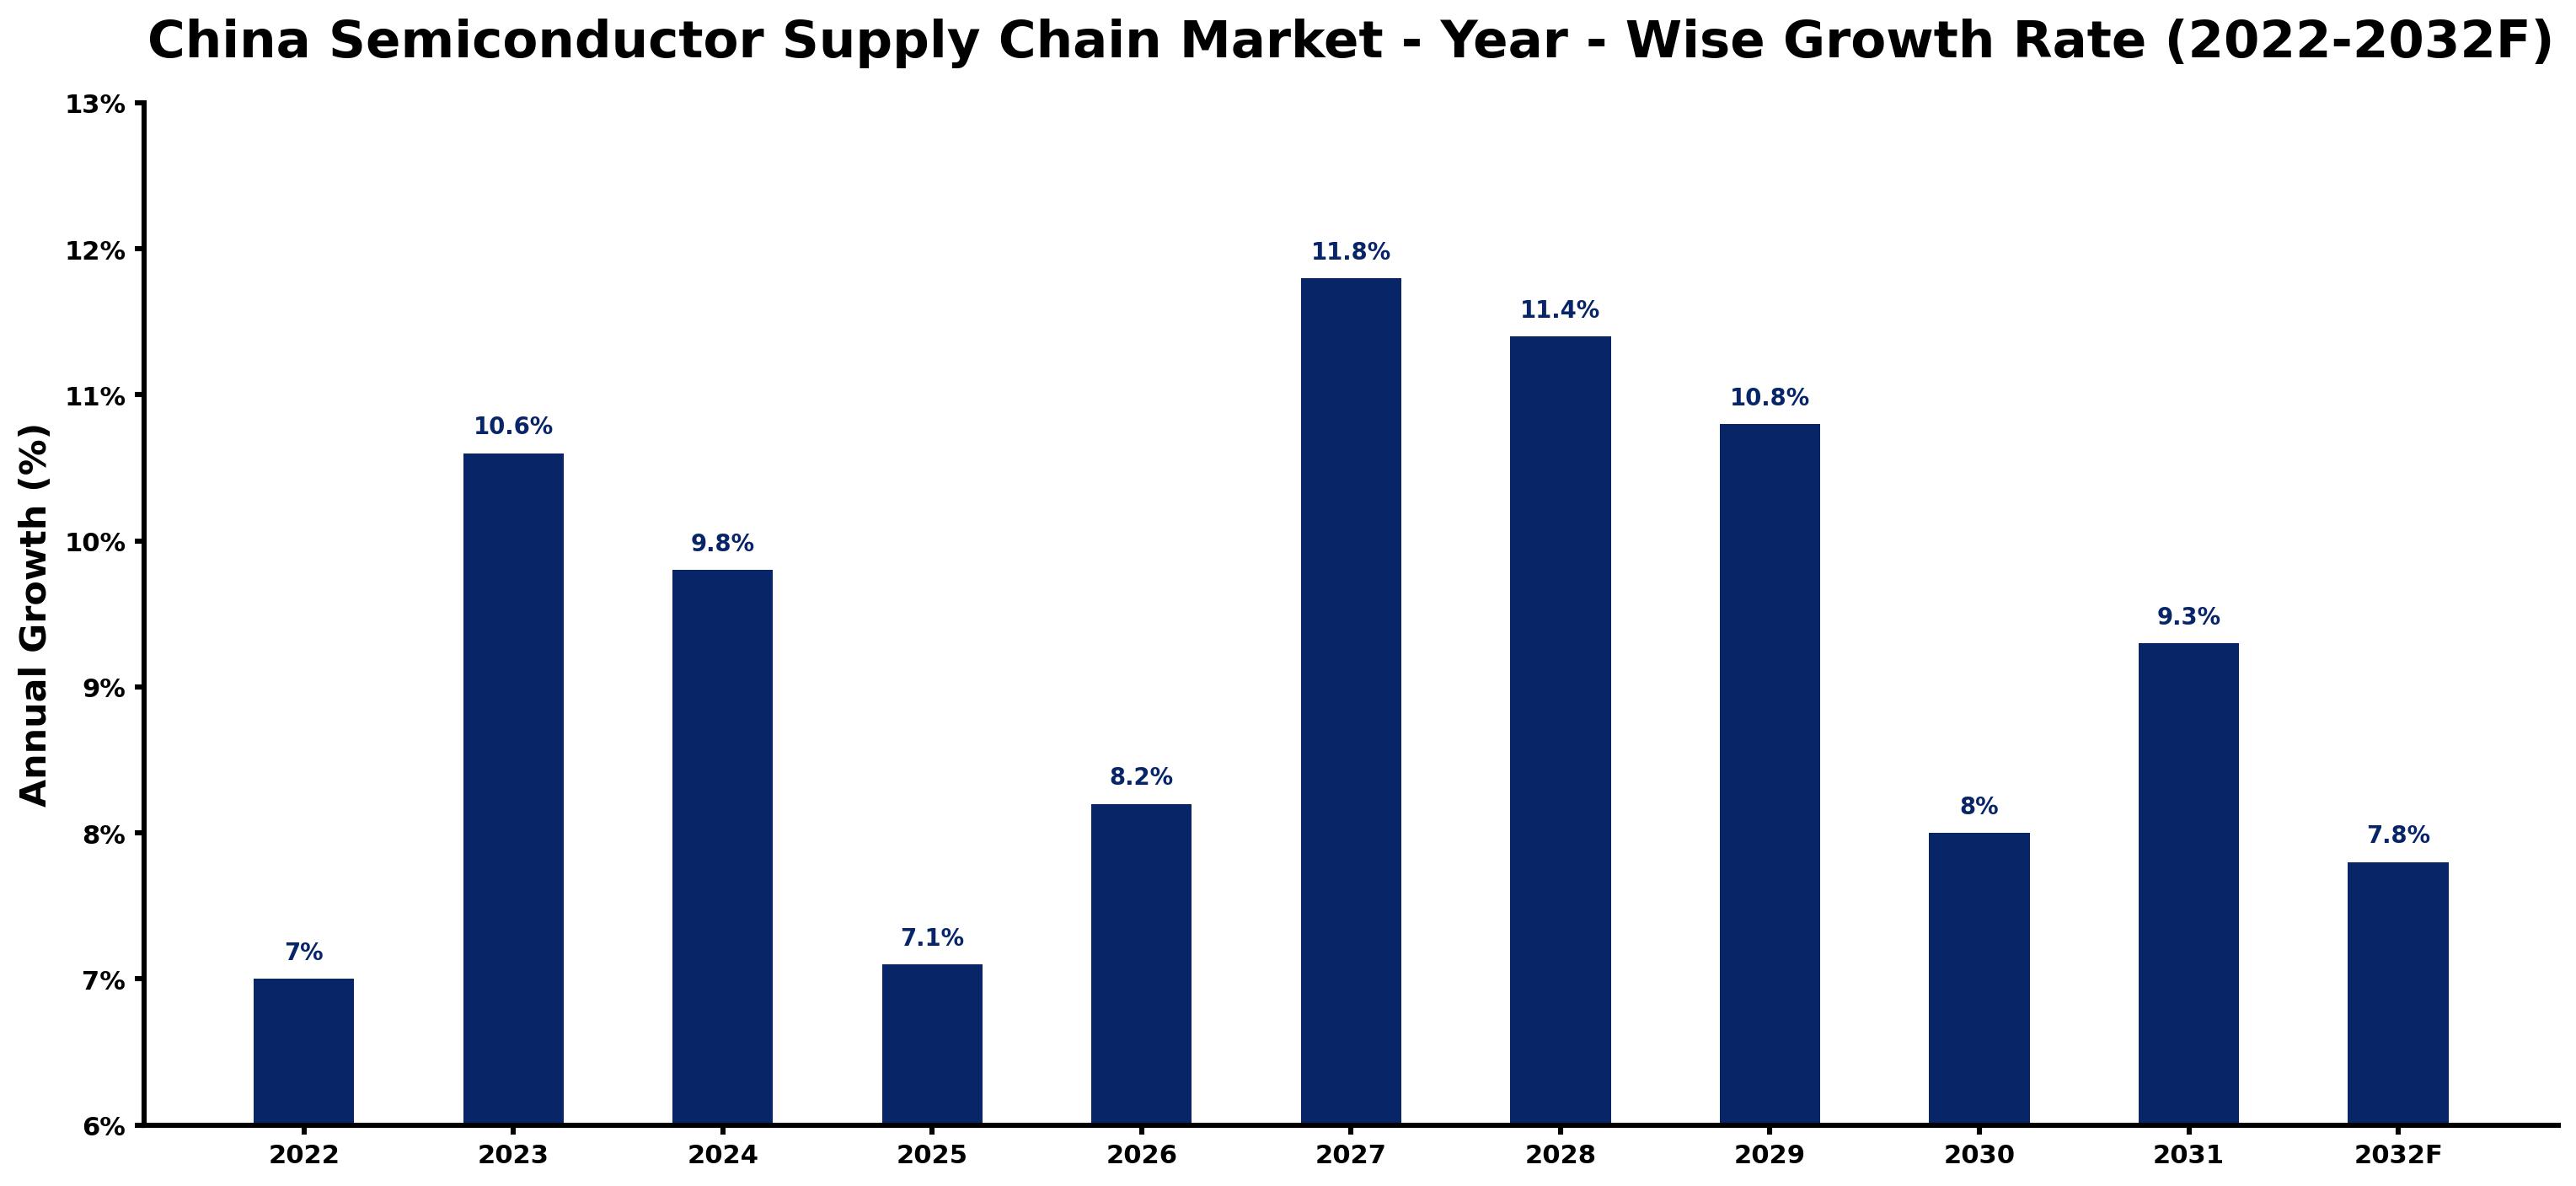
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.0 | The market experienced steady demand driven by local semiconductor production efforts. |
| 2023 | 10.6 | Growth accelerated due to increased investments in semiconductor technology and infrastructure. |
| 2024 | 9.8 | Demand growth slowed as companies adjusted to previous expansions and market conditions. |
| 2025 | 7.1 | The market continued to grow, albeit at a slower pace, due to ongoing domestic production initiatives. |
| 2026 | 8.2 | Growth is expected to resume as new projects and investments in semiconductor facilities gain momentum. |
| 2027 | 11.8 | The market will peak with substantial investments in advanced manufacturing technologies and capacity. |
| 2028 | 11.4 | Growth is projected to moderate slightly as the market adjusts to the previous year's peak demand. |
| 2029 | 10.8 | Demand will remain strong, although growth rates are expected to slow due to market saturation. |
| 2030 | 8.0 | The market will continue to grow, but at a slower pace as investments stabilise. |
| 2031 | 9.3 | Growth is anticipated to pick up again as new technologies and production capabilities are introduced. |
| 2032 | 7.8 | The market is projected to grow steadily, supported by ongoing domestic production initiatives. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Supply Chain Market Synopsis
The China Semiconductor Supply Chain Market encompasses the processes involved in designing, manufacturing, and distributing semiconductors. This industry includes design houses, foundries, and packaging companies, which are essential for electronics and automotive applications. The market is expanding due to strong domestic demand, driven by local manufacturers and investments in semiconductor technology. By 2025, the semiconductor industry in China is expected to reach a market size of 1 trillion yuan, supported by initiatives like "Made in China 2025."
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased domestic production capabilities driven by government initiatives | Driver | High | Foundries |
| Growing demand for advanced semiconductor technologies in consumer electronics | Driver | High | Integrated Device Makers |
| Investment opportunities in semiconductor manufacturing facilities | Opportunity | High | Semiconductor Fabs |
| Rising demand for packaging and testing services in the semiconductor sector | Opportunity | Medium | OSAT |
| High dependency on imported semiconductor equipment and materials | Restraint | High | Equipment Suppliers |
| Challenges in achieving self-sufficiency in semiconductor production | Restraint | Medium | Wafer Fabrication |
| Intense competition from international semiconductor markets | Challenge | High | Design Houses |
| Technological advancements requiring continuous investment in R&D | Challenge | Medium | IP/Chip Design |
Evaluation of Drivers in China Semiconductor Supply Chain Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Government initiatives to boost local production capabilities | Foundries | The "14th Five-Year Plan" aims for 70% domestic semiconductor production by 2025. |
| Growing demand for consumer electronics and automotive applications | Integrated Device Makers | The semiconductor market size is projected to reach 1 trillion yuan by 2025. |
| Investment in semiconductor manufacturing facilities | Semiconductor Fabs | China is home to over 300 semiconductor companies as of 2023. |
| Rising demand for packaging and testing services | Equipment Suppliers | In 2022, China imported semiconductor equipment worth approximately $20 billion. |
| Challenges in achieving self-sufficiency in semiconductor production | Wafer Fabrication | The government aims for 70% domestic production by 2025, but challenges remain. |
Growth in the Semiconductor Supply Chain market in China is driven by enhanced domestic production capabilities, increasing demand for consumer electronics, and significant investments in manufacturing facilities. The semiconductor market size is expected to hit 1 trillion yuan by 2025, encouraging integrated device makers to invest in advanced technologies. With over 300 semiconductor companies operating in the country, the demand for packaging and testing services is rising, especially in the OSAT segment. The semiconductor workforce is anticipated to surpass 1 million professionals, facilitating ongoing industry growth. Investment in semiconductor manufacturing facilities is essential for meeting the escalating demand.
Evaluation of Restraints in China Semiconductor Supply Chain Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High dependency on imported semiconductor equipment | Equipment Suppliers | In 2022, China imported semiconductor equipment worth approximately $20 billion. |
| Challenges in achieving self-sufficiency in semiconductor production | Wafer Fabrication | The government aims for 70% domestic production by 2025, but challenges remain. |
| Intense competition from international semiconductor markets | Design Houses | Local companies face competition from established international players, impacting market share. |
| Technological advancements require continuous investment in R&D | IP/Chip Design | Companies must invest to keep up with rapid technological changes. |
| Market saturation in certain semiconductor segments | Integrated Device Makers | As the market grows, competition increases, leading to potential oversupply. |
China Semiconductor Supply Chain Market Challenges
The semiconductor supply chain in China still has to solve a few problems, and the first is supply chain inefficiencies that cost producers up to 20% more in operational expenses. These inefficiencies stem from reliance on imported semiconductor equipment, which accounted for approximately $20 billion in 2022, delaying production timelines for local manufacturers. A shortage of skilled professionals also poses a challenge, as the industry struggles to fill roles within a workforce exceeding 1 million, hindering innovation. Buyers face price fluctuations due to government subsidies, which can increase costs by 15% for consumer electronics, impacting their profit margins.
Trends in the China Semiconductor Supply Chain Market
The trends below show where the China Semiconductor Supply Chain Market is heading.
- Launch of the China Semiconductor Innovation Fund: The China Semiconductor Innovation Fund, launched in 2023 with a budget of $10 billion, aims to promote R&D in semiconductor technologies. This initiative will drive innovation and attract investment into the sector.
- Increased focus on local production by Integrated Device Makers: Integrated Device Makers are prioritising local production capabilities to reduce dependency on imports. By 2025, they aim to achieve a 70% domestic production rate, strengthening supply chain resilience.
- Expansion of the Beijing Economic-Technological Development Area: The Beijing Economic-Technological Development Area is becoming a major hub for semiconductor manufacturing, hosting over 20 major fabs as of 2023. This concentration of facilities is attracting further investment and talent.
- Adoption of ISO/IEC 27001 standard: Many semiconductor companies in China are adopting the ISO/IEC 27001 standard for information security management. This trend is essential for ensuring data protection and compliance in an increasingly digital industry.
Investment Opportunities in the China Semiconductor Supply Chain Market
Investors looking at the China Semiconductor Supply Chain Market should consider the following areas.
- Growing demand for semiconductor manufacturing facilities: With the semiconductor industry expected to reach 1 trillion yuan by 2025, there is an opportunity to invest in new manufacturing facilities. Integrated Device Makers are looking for local partners to establish production capabilities.
- Investment in packaging and testing services: The OSAT segment is projected to grow rapidly, presenting opportunities for suppliers to provide advanced packaging solutions. Companies in the Beijing Economic-Technological Development Area are particularly well-positioned to capture this demand.
- Expansion of semiconductor R&D initiatives: The recent launch of the China Semiconductor Innovation Fund provides a unique opportunity for investment in R&D. Companies can collaborate with local universities and research institutions to develop new technologies.
- Partnerships for technology transfer: The current market environment encourages partnerships for technology transfer in semiconductor design and manufacturing. Companies can explore joint ventures with local firms to improve capabilities and market reach.
Government Initiatives in the China Semiconductor Supply Chain Market
The "14th Five-Year Plan for Economic and Social Development" issued by the National Development and Reform Commission in 2021 aims to improve semiconductor self-sufficiency by 2025. This plan outlines specific targets for domestic production and encourages investment in local semiconductor companies. Additionally, the "National Semiconductor Industry Development Strategy" launched in 2020 focuses on boosting local production capabilities through various initiatives and funding mechanisms, creating a supportive environment for industry growth.
The Integrated Circuit Industry Support Fund, established by the Ministry of Finance in 2021, provides financial backing for semiconductor projects. This fund aims to enhance local production capabilities and stimulate innovation within the semiconductor sector. Furthermore, the China Semiconductor Innovation Fund, launched in 2023, has a budget of $10 billion to promote R&D in semiconductor technologies, enabling companies to access funding for innovative projects.
Future Insight of the China Semiconductor Supply Chain Market
Several forward-looking factors are expected to propel the semiconductor supply chain market in China in the coming years. The "Made in China 2025" initiative aims for 70% domestic semiconductor production, promoting self-sufficiency. Investment in advanced manufacturing technologies will increase, with the National Integrated Circuit Industry Investment Fund's budget of $29 billion supporting this growth. The Shanghai International Semiconductor Technology Expo will continue to encourage innovation and collaboration, enabling local companies to strengthen their competitive edge globally. Enhanced information security standards like ISO/IEC 27001 will also boost operational efficiency.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Segment Type – Foundries Dominated, OSAT Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, in 2025, Foundries led the segment type split with a 49% share. Foundries dominate the semiconductor supply chain market due to their critical role in manufacturing semiconductor chips based on designs. With over 20 major facilities in China, they effectively cater to the growing domestic demand for semiconductors. OSAT is projected to grow fastest, at a CAGR of 11.4% during 2026–2032. OSAT is experiencing rapid growth as the demand for efficient packaging and testing of semiconductor chips rises, particularly in the booming electronics sector. The annual Shanghai International Semiconductor Technology Expo highlights the industry's focus on advancing these essential processes. Suppliers should enhance their OSAT capabilities to meet the increasing market demands and stay competitive.
By Activity Type – Wafer Fabrication Dominated, Assembly & Test Expected to Grow Fastest
Wafer Fabrication took a 48% share of activity type in 2025, more than any other category. Wafer Fabrication holds the largest market share as it is vital for producing semiconductor wafers, which form the basis of all semiconductor products. The extensive network of semiconductor companies in China emphasises the importance of this activity within the supply chain. The quickest growth will come from Assembly & Test, forecast to expand at a CAGR of 10.7% between 2026 and 2032. Assembly & Test is the fastest-growing segment, driven by the increasing complexity of semiconductor products that require sophisticated assembly and testing solutions. The government's focus on semiconductor self-sufficiency through the "14th Five-Year Plan" further accelerates this segment's growth. Suppliers that invest in Assembly & Test capabilities will be well-positioned to capture emerging opportunities in the market.
By End User – Integrated Device Makers Dominated, Fabless Companies Expected to Grow Fastest
Integrated Device Makers accounted for a 48% market share by end user in 2025. Integrated Device Makers lead the market as they design and manufacture their own semiconductor products, benefiting from the rising demand across various sectors. Their established operations and integrated approach give them a competitive advantage in the dynamic semiconductor landscape. Over 2026–2032, Fabless Companies are expected to post the fastest growth, at a CAGR of 11.1%. Fabless Companies are the fastest-growing segment, leveraging the trend of outsourcing manufacturing to foundries while concentrating on design. This shift towards collaboration indicates a more interconnected ecosystem within the semiconductor industry. This trend suggests that suppliers should develop partnerships with Fabless Companies to broaden their market reach.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Supply Chain Market Outlook
- Market Size of China Semiconductor Supply Chain Market, 2025
- Forecast of China Semiconductor Supply Chain Market, 2032
- Historical Data and Forecast of China Semiconductor Supply Chain Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Supply Chain Market Trend Evolution
- China Semiconductor Supply Chain Market Drivers and Challenges
- China Semiconductor Supply Chain Price Trends
- China Semiconductor Supply Chain Porter's Five Forces
- China Semiconductor Supply Chain Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Segment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Design Houses for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By OSAT for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Equipment Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Activity Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By IP/Chip Design for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Wafer Fabrication for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Assembly & Test for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Tool Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Fabless Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Integrated Device Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Automotive/Electronics OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Supply Chain Market Revenues & Volume By Semiconductor Fabs for the Period 2022 - 2032F
- China Semiconductor Supply Chain Import Export Trade Statistics
- Market Opportunity Assessment By Segment Type
- Market Opportunity Assessment By Activity Type
- Market Opportunity Assessment By End User
- China Semiconductor Supply Chain Top Companies Market Share
- China Semiconductor Supply Chain Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Supply Chain Company Profiles
- China Semiconductor Supply Chain Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Segment Type
- Design Houses
- Foundries
- OSAT
- Equipment Suppliers
By Activity Type
- IP/Chip Design
- Wafer Fabrication
- Assembly & Test
- Tool Manufacturing
By End User
- Fabless Companies
- Integrated Device Makers
- Automotive/Electronics OEMs
- Semiconductor Fabs































