India Smart Connectivity Market Size & Growth Rate
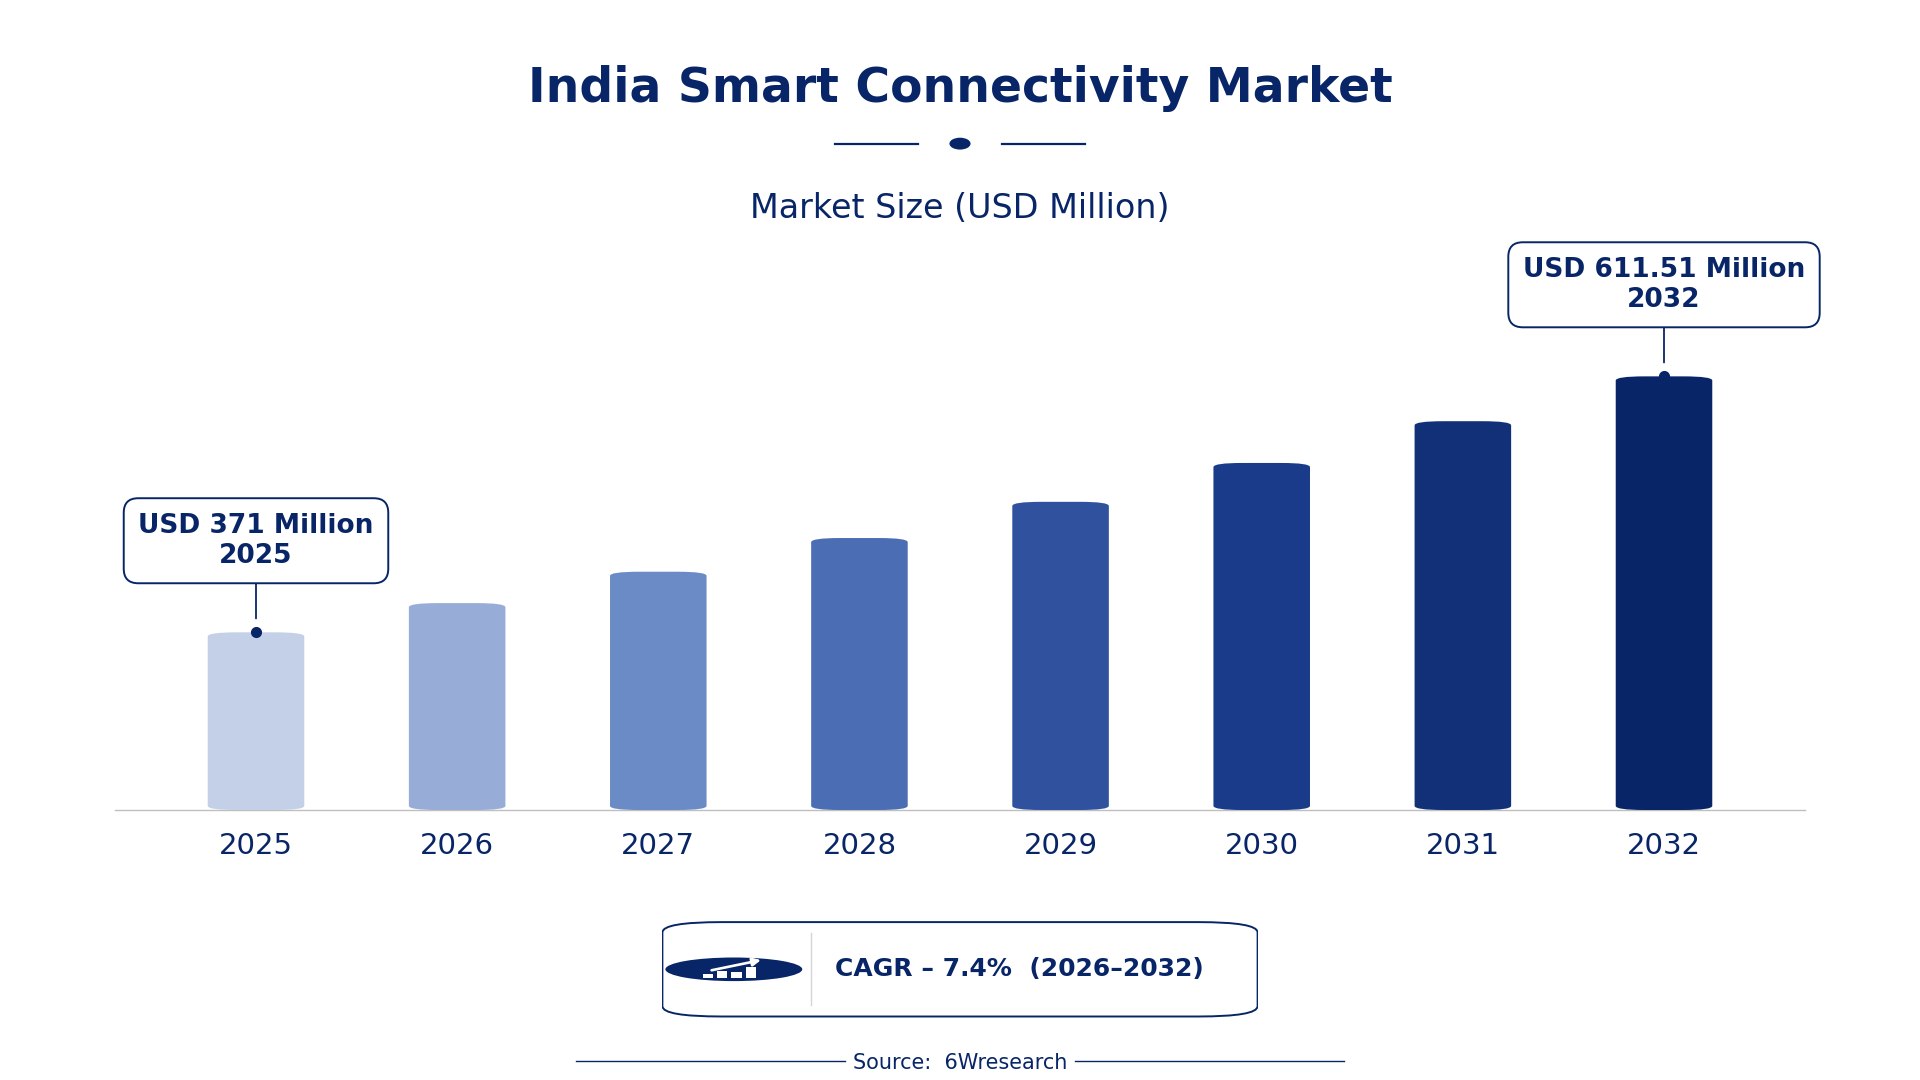
According to 6Wresearch internal database and industry insights, the India Smart Connectivity Market was valued at USD 371.0 million in 2025 and is projected to reach USD 611.51 million by 2032, growing at a CAGR of approximately 7.4% during 2026–2032.
India Smart Connectivity Market Highlights
| Report Metric | Details |
| Report Name | India Smart Connectivity Market |
| Market Size 2025 | USD 371.0 million |
| Market Size 2032 | USD 611.51 million |
| Absolute Growth 2025–2032 | USD 240.51 million |
| CAGR 2026–2032 | 7.4% |
| Peak Annual Growth | 9.4% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Connectivity Type, 2025 | 5G Connectivity (55% share) |
| Leading Network Layer, 2025 | High-Speed IoT (38% share) |
| Leading Target Devices, 2025 | Smart Cities (41% share) |
| Leading End User, 2025 | Telecom Operators (50% share) |
| Fastest-Growing Connectivity Type | LPWAN (LoRa, NB-IoT) (9.5% CAGR) |
| Fastest-Growing Network Layer | Low Power Devices (9.1% CAGR) |
| Fastest-Growing Target Devices | Agriculture (9.7% CAGR) |
| Fastest-Growing End User | Smart Grid/Infra Firms (9.6% CAGR) |
| Growing Sector | Smart Cities |
| Key End Users | Telecom Operators, Smart Grid/Infra Firms, Managed Network Providers, Global IoT Deployers |
India Smart Connectivity Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
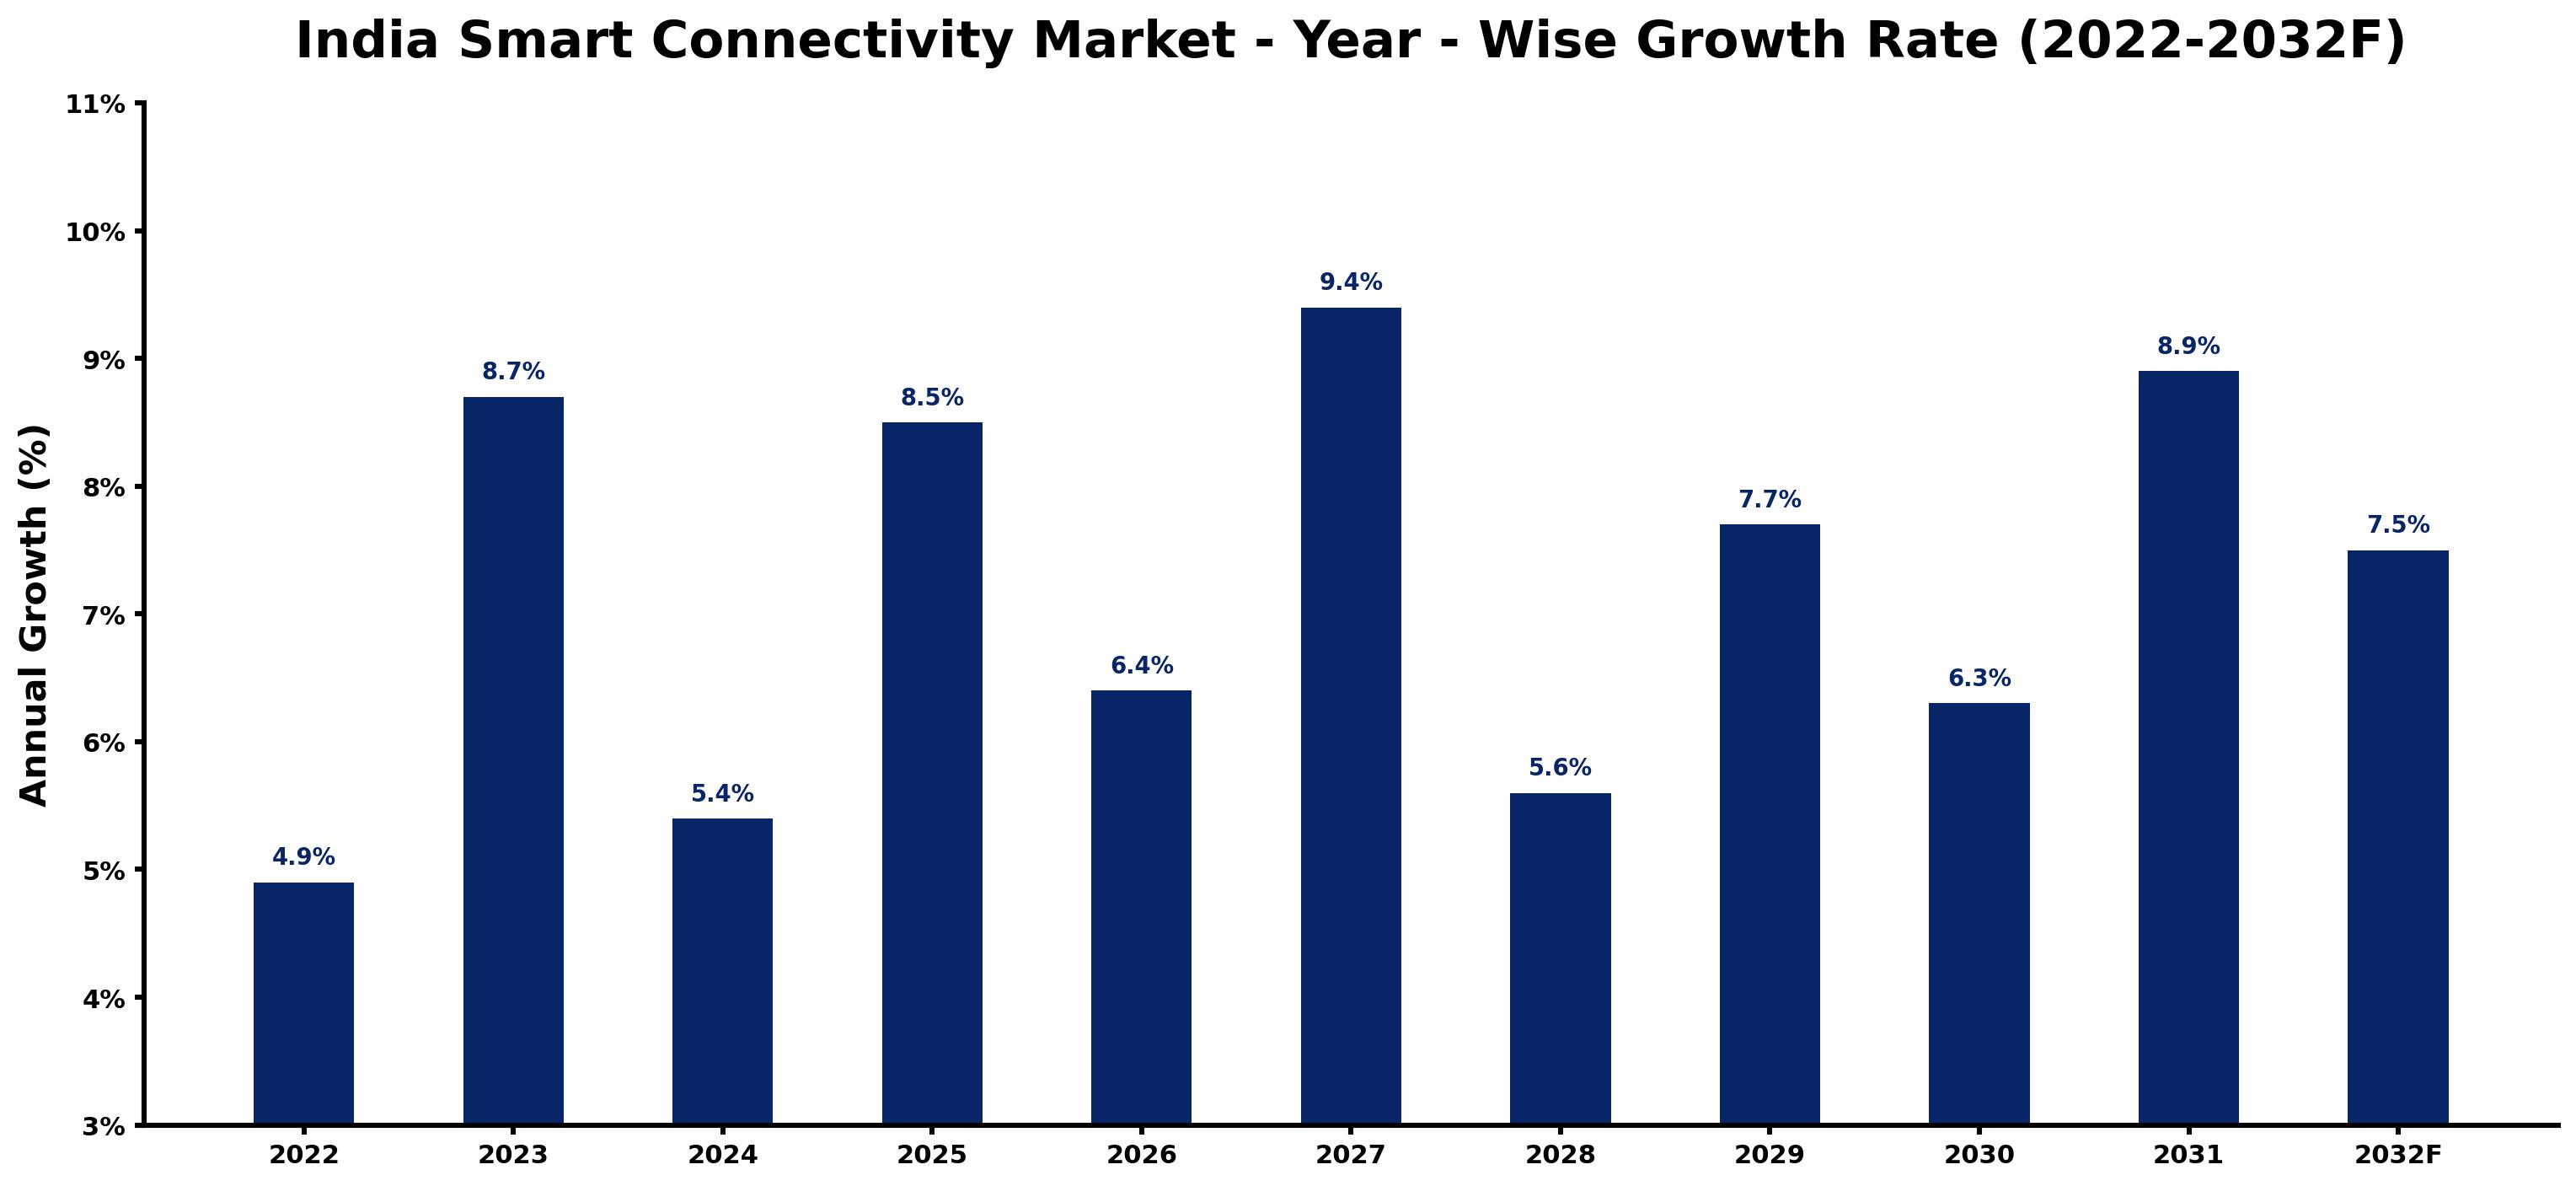
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.9 | The market experienced steady growth due to increasing urbanisation and demand for connectivity solutions. |
| 2023 | 8.7 | Growth accelerated as the Smart Cities Mission gained momentum, driving investments in infrastructure. |
| 2024 | 5.4 | A slight slowdown occurred as the market adjusted to the rapid expansion of 5G networks. |
| 2025 | 8.5 | Demand surged again as 5G services expanded to cover more cities, improving connectivity. |
| 2026 | 6.4 | Growth is expected to slow as the market faces challenges in rural connectivity and infrastructure development. |
| 2027 | 9.4 | A peak in growth is projected as urban areas rapidly adopt high-speed connectivity solutions. |
| 2028 | 5.6 | The market is expected to experience a slowdown as investments stabilise following rapid expansion in previous years. |
| 2029 | 7.7 | Growth is anticipated to rebound as smart agriculture initiatives gain traction in rural regions. |
| 2030 | 6.3 | A slowdown is expected as the market adjusts to evolving technology standards and user expectations. |
| 2031 | 8.9 | Demand is projected to increase again as telecom operators expand their service offerings and coverage. |
| 2032 | 7.5 | Growth is expected to slow slightly as the market matures, but demand for smart solutions will continue. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Smart Connectivity Market Synopsis
The India Smart Connectivity Market encompasses advanced communication technologies that enable devices to connect and communicate. This includes innovations in hardware and software, such as IoT devices and network infrastructure, crucial for urban development and smart agriculture. The market is driven by investments in smart city initiatives and the expansion of 5G services. With a population of approximately 1.4 billion, demand for connectivity solutions continues to rise, supported by government policies like the National Digital Communications Policy and the Smart Cities Mission.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rapid urbanisation and infrastructure development drive demand for high-speed connectivity solutions. | Driver | High | 5G Connectivity |
| Increasing adoption of IoT devices in urban areas creates a need for low-power, long-range connectivity. | Driver | High | LPWAN (LoRa, NB-IoT) |
| The growing need for efficient agricultural practices presents opportunities for smart farming technologies. | Opportunity | High | Agriculture |
| Investment in smart grid technology is projected to reach $5 billion by 2025, creating demand for connectivity solutions. | Opportunity | High | Smart Grid/Infra Firms |
| Challenges in rural connectivity hinder the expansion of smart connectivity solutions. | Restraint | High | Telecom Operators |
| High costs associated with implementing advanced connectivity infrastructure may limit market growth. | Restraint | Medium | Smart Cities |
| Limited infrastructure in rural areas poses challenges for connectivity providers and users. | Challenge | High | LPWAN (LoRa, NB-IoT) |
| The rapid pace of technological advancements can lead to obsolescence of existing solutions. | Challenge | Medium | High-Speed IoT |
Evaluation of Drivers in India Smart Connectivity Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Urbanisation and infrastructure development are increasing the demand for high-speed connectivity solutions. | 5G Connectivity | India's population of approximately 1.4 billion drives the need for communication services. |
| The rise of IoT devices in urban areas necessitates low-power, long-range connectivity. | LPWAN (LoRa, NB-IoT) | Technologies like NB-IoT are being adopted for smart metering in urban environments. |
| The Smart Cities Mission promotes investment in urban infrastructure, boosting demand for smart connectivity. | Smart Cities | The initiative aims to develop 100 smart cities across India by 2023. |
| Investment in smart agriculture technologies is increasing, driving demand for connectivity solutions. | Agriculture | Smart farming solutions are being deployed in states like Punjab and Haryana. |
| Telecom operators are expanding their networks to enhance connectivity in remote areas. | Telecom Operators | The government has allocated funds for rural connectivity projects under the BharatNet programme. |
Approximately 1.4 billion people drive demand for improved connectivity solutions, particularly in urban areas. Investment in smart grid technology is projected to reach $5 billion by 2025, further boosting demand. Smart agriculture technologies are increasingly being adopted, creating opportunities for connectivity providers. Telecom operators are expanding their networks to cover remote areas, supported by funding for rural connectivity projects.
Evaluation of Restraints in India Smart Connectivity Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited infrastructure in rural areas restricts the expansion of smart connectivity solutions. | LPWAN (LoRa, NB-IoT) | The BharatNet programme aims to connect 250,000 gram panchayats by 2025, but progress has been slow. |
| High implementation costs for advanced connectivity infrastructure may deter investment. | Smart Cities | The Smart Cities Mission requires substantial funding, which may not be available in all regions. |
| Regulatory challenges can slow down the deployment of new connectivity technologies. | Telecom Operators | The Telecom Regulatory Authority of India sets stringent standards that can delay approvals. |
| Technological obsolescence can lead to wasted investments in outdated infrastructure. | High-Speed IoT | Rapid advancements in technology mean older systems may quickly become irrelevant. |
| Market fragmentation can lead to inefficiencies in service delivery. | 5G Connectivity | With numerous operators competing, coordination and standardisation become challenging. |
India Smart Connectivity Market Challenges
The India Smart Connectivity Market encounters various practical issues, starting with supply chain inconsistencies. These challenges stem from uneven access to advanced communication technologies, which can delay project completions for telecom operators and affect service delivery. Buyers face rising costs, as fluctuating prices of IoT devices and network infrastructure can inflate budgets by up to 20%. Competition among service providers is intensifying as they employ aggressive pricing strategies to stand out, potentially squeezing profit margins for smaller players. Rapid technological advancements pose challenges in meeting changing standards, compelling suppliers to shift resources from operational needs to research and development.
Trends in the India Smart Connectivity Market
Several trends are reshaping the India Smart Connectivity Market; the most important are set out below.
- Shift towards Smart Agriculture Solutions: Investment in smart agriculture technologies is growing, particularly in states like Punjab and Haryana. Approximately 20% of farmers are adopting IoT solutions for precision farming, improving crop yields.
- Expansion of 5G Services: The rollout of 5G services is set to cover 1,000 cities by 2025, improving connectivity across urban areas. This expansion is expected to enhance internet access for millions.
- Adoption of Wi-Fi 6 in Urban Areas: Wi-Fi 6 is being implemented in major metropolitan areas to improve internet access. This technology supports high-density environments, catering to the growing number of connected devices.
- Focus on Rural Connectivity Initiatives: The BharatNet programme aims to connect all gram panchayats with high-speed internet by 2025. This initiative is essential for bridging the digital divide in rural regions.
Investment Opportunities in the India Smart Connectivity Market
Several openings in the India Smart Connectivity Market merit attention from investors.
- Telecom Operators Expanding Services: Telecom operators are looking to expand their service offerings, with rapid growth in 5G networks. This creates investment opportunities in urban areas, particularly for infrastructure development.
- Smart Cities Initiative Driving Demand: The Smart Cities Mission is generating a need for advanced connectivity solutions in urban settings. With plans for 100 smart cities, there is a clear opportunity for infrastructure investment.
- Investment in Smart Grid Technologies: Investment in smart grid technology is projected to reach $5 billion by 2025, offering a chance for connectivity providers. This demand is driven by the necessity for modern energy infrastructure.
- Growing Demand for Smart Agriculture: Smart farming technologies are being increasingly adopted in rural areas, especially in Punjab and Haryana. This trend opens up opportunities for suppliers of IoT solutions and connectivity services.
Government Initiatives in the India Smart Connectivity Market
The National Digital Communications Policy 2020 aims to provide broadband access to all citizens by 2022, overseen by the Department of Telecommunications. This policy enhances connectivity infrastructure, ensuring that both urban and rural areas benefit from improved digital services. The Smart Cities Mission, initiated in 2015, focuses on developing 100 smart cities with enhanced infrastructure and connectivity, managed by the Ministry of Housing and Urban Affairs. Additionally, the Digital India programme, launched in 2015, promotes digital infrastructure across the country, led by the Ministry of Electronics and Information Technology. These measures collectively aim to foster a more connected environment for citizens and businesses alike.
The BharatNet programme, which aims to connect all 250,000 gram panchayats with high-speed internet by 2025, is coordinated by the Ministry of Electronics and Information Technology. This initiative is crucial for improving rural connectivity, enabling access to smart solutions in underserved areas. Furthermore, the National IoT Policy, established by the Ministry of Electronics and Information Technology, aims to create a conducive environment for IoT innovation and deployment in India. This policy is expected to attract investments and enhance the overall connectivity landscape, supporting various sectors in their digital transformation efforts.
Future Insight of the India Smart Connectivity Market
The India Smart Connectivity Market is set for transformative changes by 2032, supported by several forward-looking factors. The rollout of 5G services is expected to enhance connectivity across 1,000 cities by 2025, improving access for urban users. Investment in smart grid technology is projected to reach $5 billion, signalling a strong commitment to infrastructure development. The National IoT Policy aims to establish India as a global hub for IoT by 2025, encouraging innovation and attracting international partnerships. Government initiatives will also improve rural connectivity, expanding access to smart solutions in underserved areas.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Connectivity Type – 5G Connectivity Dominated, LPWAN (LoRa, NB-IoT) Expected to Grow Fastest
According to Dhaval Chaurasia, Assistant Manager at 6Wresearch, the largest connectivity type category in 2025 was 5G Connectivity, with a 55% share of total revenue. 5G Connectivity secures the largest market share due to its critical role in facilitating high-speed communication and supporting diverse IoT applications. The rollout of 5G services to 1,000 cities by 2025 underscores its significance in enhancing smart connectivity across India. The quickest growth will come from LPWAN (LoRa, NB-IoT), forecast to expand at a CAGR of 9.5% between 2026 and 2032. LPWAN technologies like NB-IoT are rapidly gaining traction because they provide low-power, long-range connectivity essential for IoT devices. The increasing deployment of smart metering solutions in urban areas showcases the surging demand for these technologies. Suppliers must focus on expanding their LPWAN offerings to effectively address the growing need for energy-efficient IoT solutions.
By Network Layer – High-Speed IoT Dominated, Low Power Devices Expected to Grow Fastest
With a 38% revenue share in 2025, High-Speed IoT was the largest network layer category. High-Speed IoT dominates the market as it is essential for real-time data transmission across various applications, making it a cornerstone of smart connectivity. The rising demand for high-speed data in urban infrastructure development solidifies its leading position. Low Power Devices are set to record the highest CAGR in this split, 9.1% over 2026–2032. Low Power Devices are experiencing swift growth driven by the increasing demand for energy-efficient IoT solutions that operate over extended periods. The push for sustainable technology in smart connectivity applications is accelerating this segment's expansion. Buyers should consider investing in low power devices to enhance operational efficiency and sustainability in their IoT initiatives.
By Target Devices – Smart Cities Dominated, Agriculture Expected to Grow Fastest
Smart Cities accounted for a 41% market share by target devices in 2025. Smart Cities represent the largest share as they are crucial for urban development and management, bolstered by substantial government initiatives. The Smart Cities Mission, which aims to establish 100 smart cities by 2023, highlights the importance of this segment. Agriculture is projected to grow fastest, at a CAGR of 9.7% during 2026–2032. Agriculture is the fastest-growing segment, spurred by the rising adoption of precision farming technologies that enhance yield and resource management. The implementation of smart agriculture solutions in states like Punjab and Haryana exemplifies this growth trend. Suppliers should customise their offerings to meet the specific requirements of the agricultural sector, tapping into the demand for precision farming technologies.
By End User – Telecom Operators Dominated, Smart Grid/Infra Firms Expected to Grow Fastest
Telecom Operators held a 50% share of the India Smart Connectivity Market by end user in 2025. Telecom Operators lead the market as the primary providers of connectivity services, which are vital for enabling smart connectivity across various sectors. Their ongoing efforts to expand 4G and 5G networks are crucial for meeting the increasing demand for reliable connectivity. Over 2026–2032, Smart Grid/Infra Firms are expected to post the fastest growth, at a CAGR of 9.6%. Smart Grid/Infra Firms are witnessing rapid growth as they play a key role in modernising energy infrastructure, with investments projected to reach $5 billion by 2025. This focus on smart grid technology reflects the growing integration of IoT in energy management. Suppliers should align their strategies with the needs of smart grid firms to capitalise on the increasing investments in energy infrastructure modernisation.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Smart Connectivity Market Outlook
- Market Size of India Smart Connectivity Market, 2025
- Forecast of India Smart Connectivity Market, 2032
- Historical Data and Forecast of India Smart Connectivity Revenues & Volume for the Period 2022 - 2032F
- India Smart Connectivity Market Trend Evolution
- India Smart Connectivity Market Drivers and Challenges
- India Smart Connectivity Price Trends
- India Smart Connectivity Porter's Five Forces
- India Smart Connectivity Industry Life Cycle
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Connectivity Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By 5G Connectivity for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By LPWAN (LoRa, NB-IoT) for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Wi-Fi 6/6E for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Satellite IoT Links for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Network Layer for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By High-Speed IoT for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Low Power Devices for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By High-Density Networks for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Remote Area Coverage for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Target Devices for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Smart Cities, Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Sensors, Meters for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Commercial Buildings for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Agriculture, Maritime for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Telecom Operators for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Smart Grid/Infra Firms for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Managed Network Providers for the Period 2022 - 2032F
- Historical Data and Forecast of India Smart Connectivity Market Revenues & Volume By Global IoT Deployers for the Period 2022 - 2032F
- India Smart Connectivity Import Export Trade Statistics
- Market Opportunity Assessment By Connectivity Type
- Market Opportunity Assessment By Network Layer
- Market Opportunity Assessment By Target Devices
- Market Opportunity Assessment By End User
- India Smart Connectivity Top Companies Market Share
- India Smart Connectivity Competitive Benchmarking By Technical and Operational Parameters
- India Smart Connectivity Company Profiles
- India Smart Connectivity Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Connectivity Type
- 5G Connectivity
- LPWAN (LoRa, NB-IoT)
- Wi-Fi 6/6E
- Satellite IoT Links
By Network Layer
- High-Speed IoT
- Low Power Devices
- High-Density Networks
- Remote Area Coverage
By Target Devices
- Smart Cities
- Vehicles
- Sensors
- Meters
- Commercial Buildings
- Agriculture
- Maritime
By End User
- Telecom Operators
- Smart Grid/Infra Firms
- Managed Network Providers
- Global IoT Deployers































