India Specialty Injectable Drugs Market Size & Growth Rate
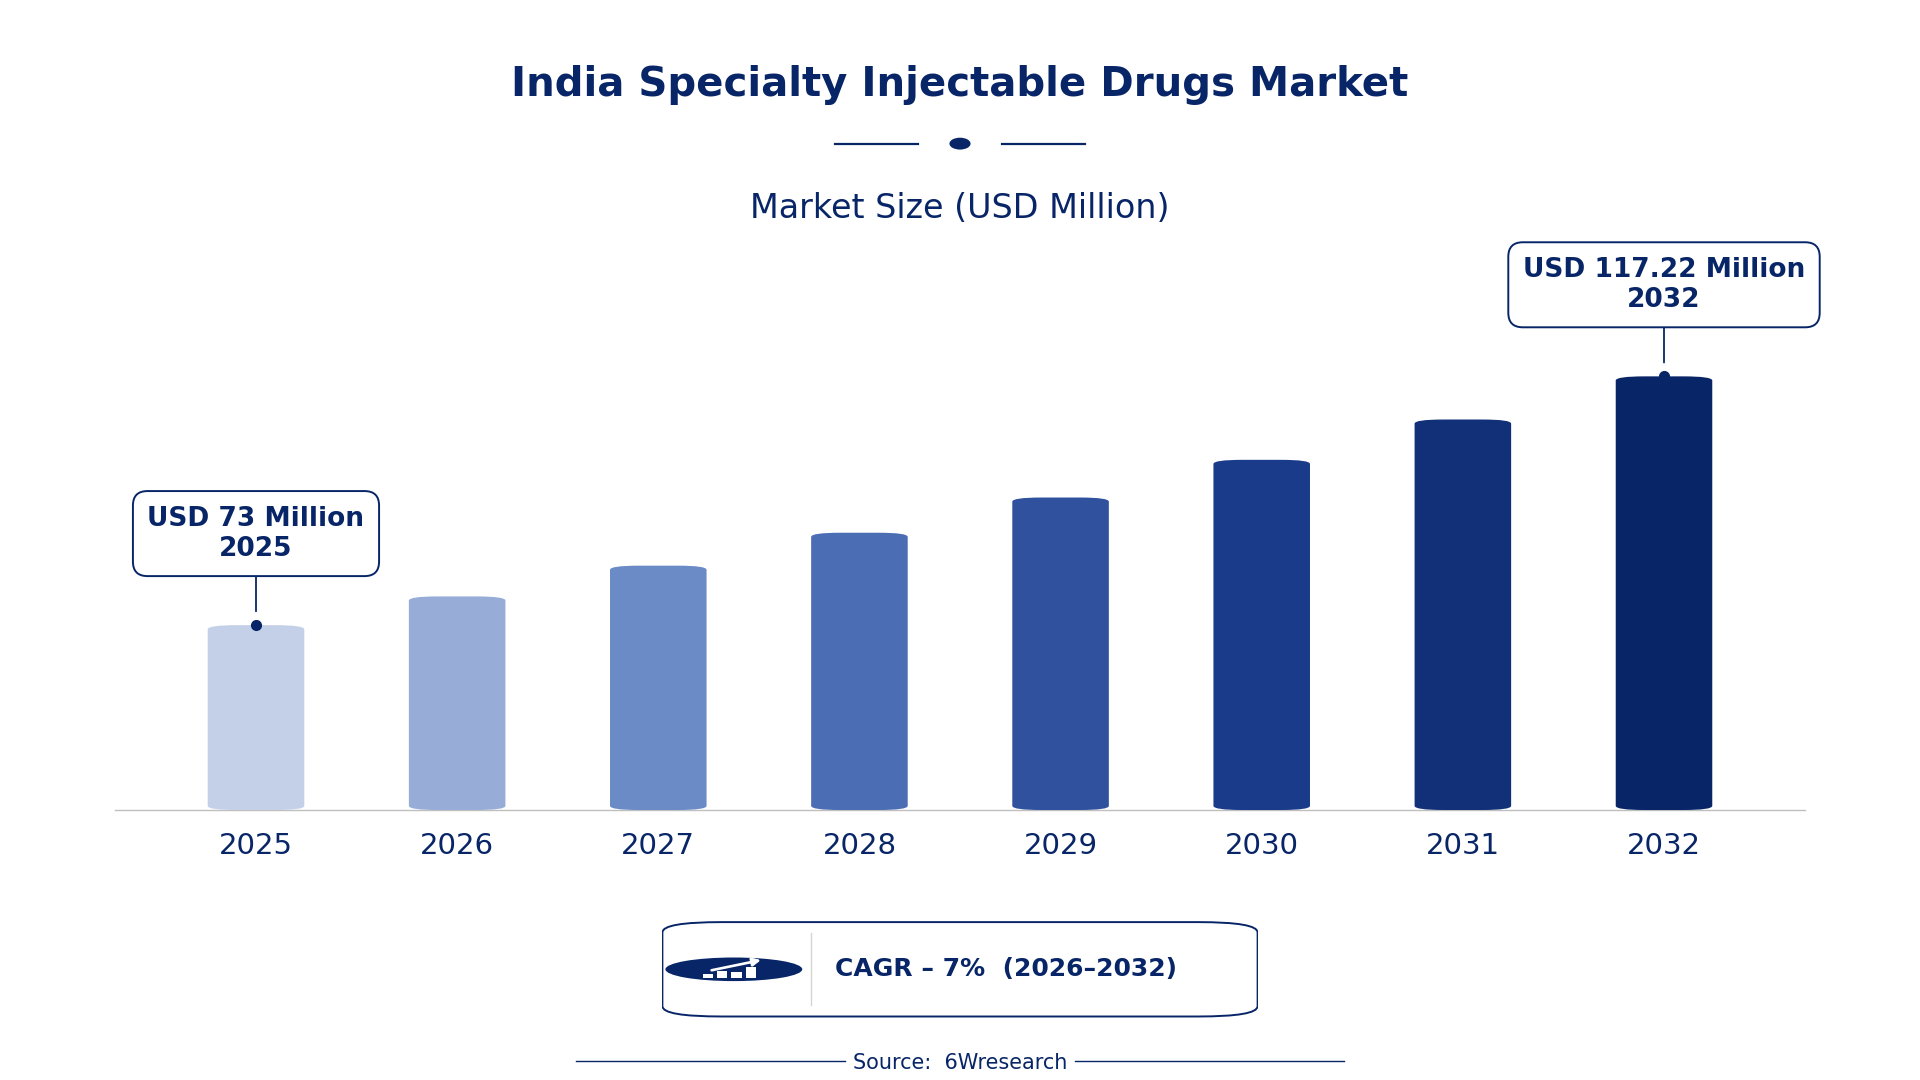
According to 6Wresearch internal database and industry insights, the India Specialty Injectable Drugs Market was valued at USD 73.0 million in 2025 and is projected to reach USD 117.22 million by 2032, growing at a CAGR of approximately 7% during 2026–2032.
India Specialty Injectable Drugs Market Highlights
| Report Metric | Details |
| Report Name | India Specialty Injectable Drugs Market |
| Market Size 2025 | USD 73.0 million |
| Market Size 2032 | USD 117.22 million |
| Absolute Growth 2025–2032 | USD 44.22 million |
| CAGR 2026–2032 | 7% |
| Peak Annual Growth | 9.0% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Drug Class, 2025 | Biologics (51% share) |
| Leading Delivery Type, 2025 | IV Infusion (40% share) |
| Leading Therapy Area, 2025 | Oncology (46% share) |
| Leading End User, 2025 | Hospitals (41% share) |
| Fastest-Growing Drug Class | Hormonal Injectables (9.4% CAGR) |
| Fastest-Growing Delivery Type | Subcutaneous (8.6% CAGR) |
| Fastest-Growing Therapy Area | Autoimmune Disorders (8.4% CAGR) |
| Fastest-Growing End User | Cancer Care Centers (9.2% CAGR) |
| Growing Sector | Oncology |
| Key End Users | Hospitals, Cancer Care Centers, Clinics, Rehabilitation Centers |
India Specialty Injectable Drugs Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
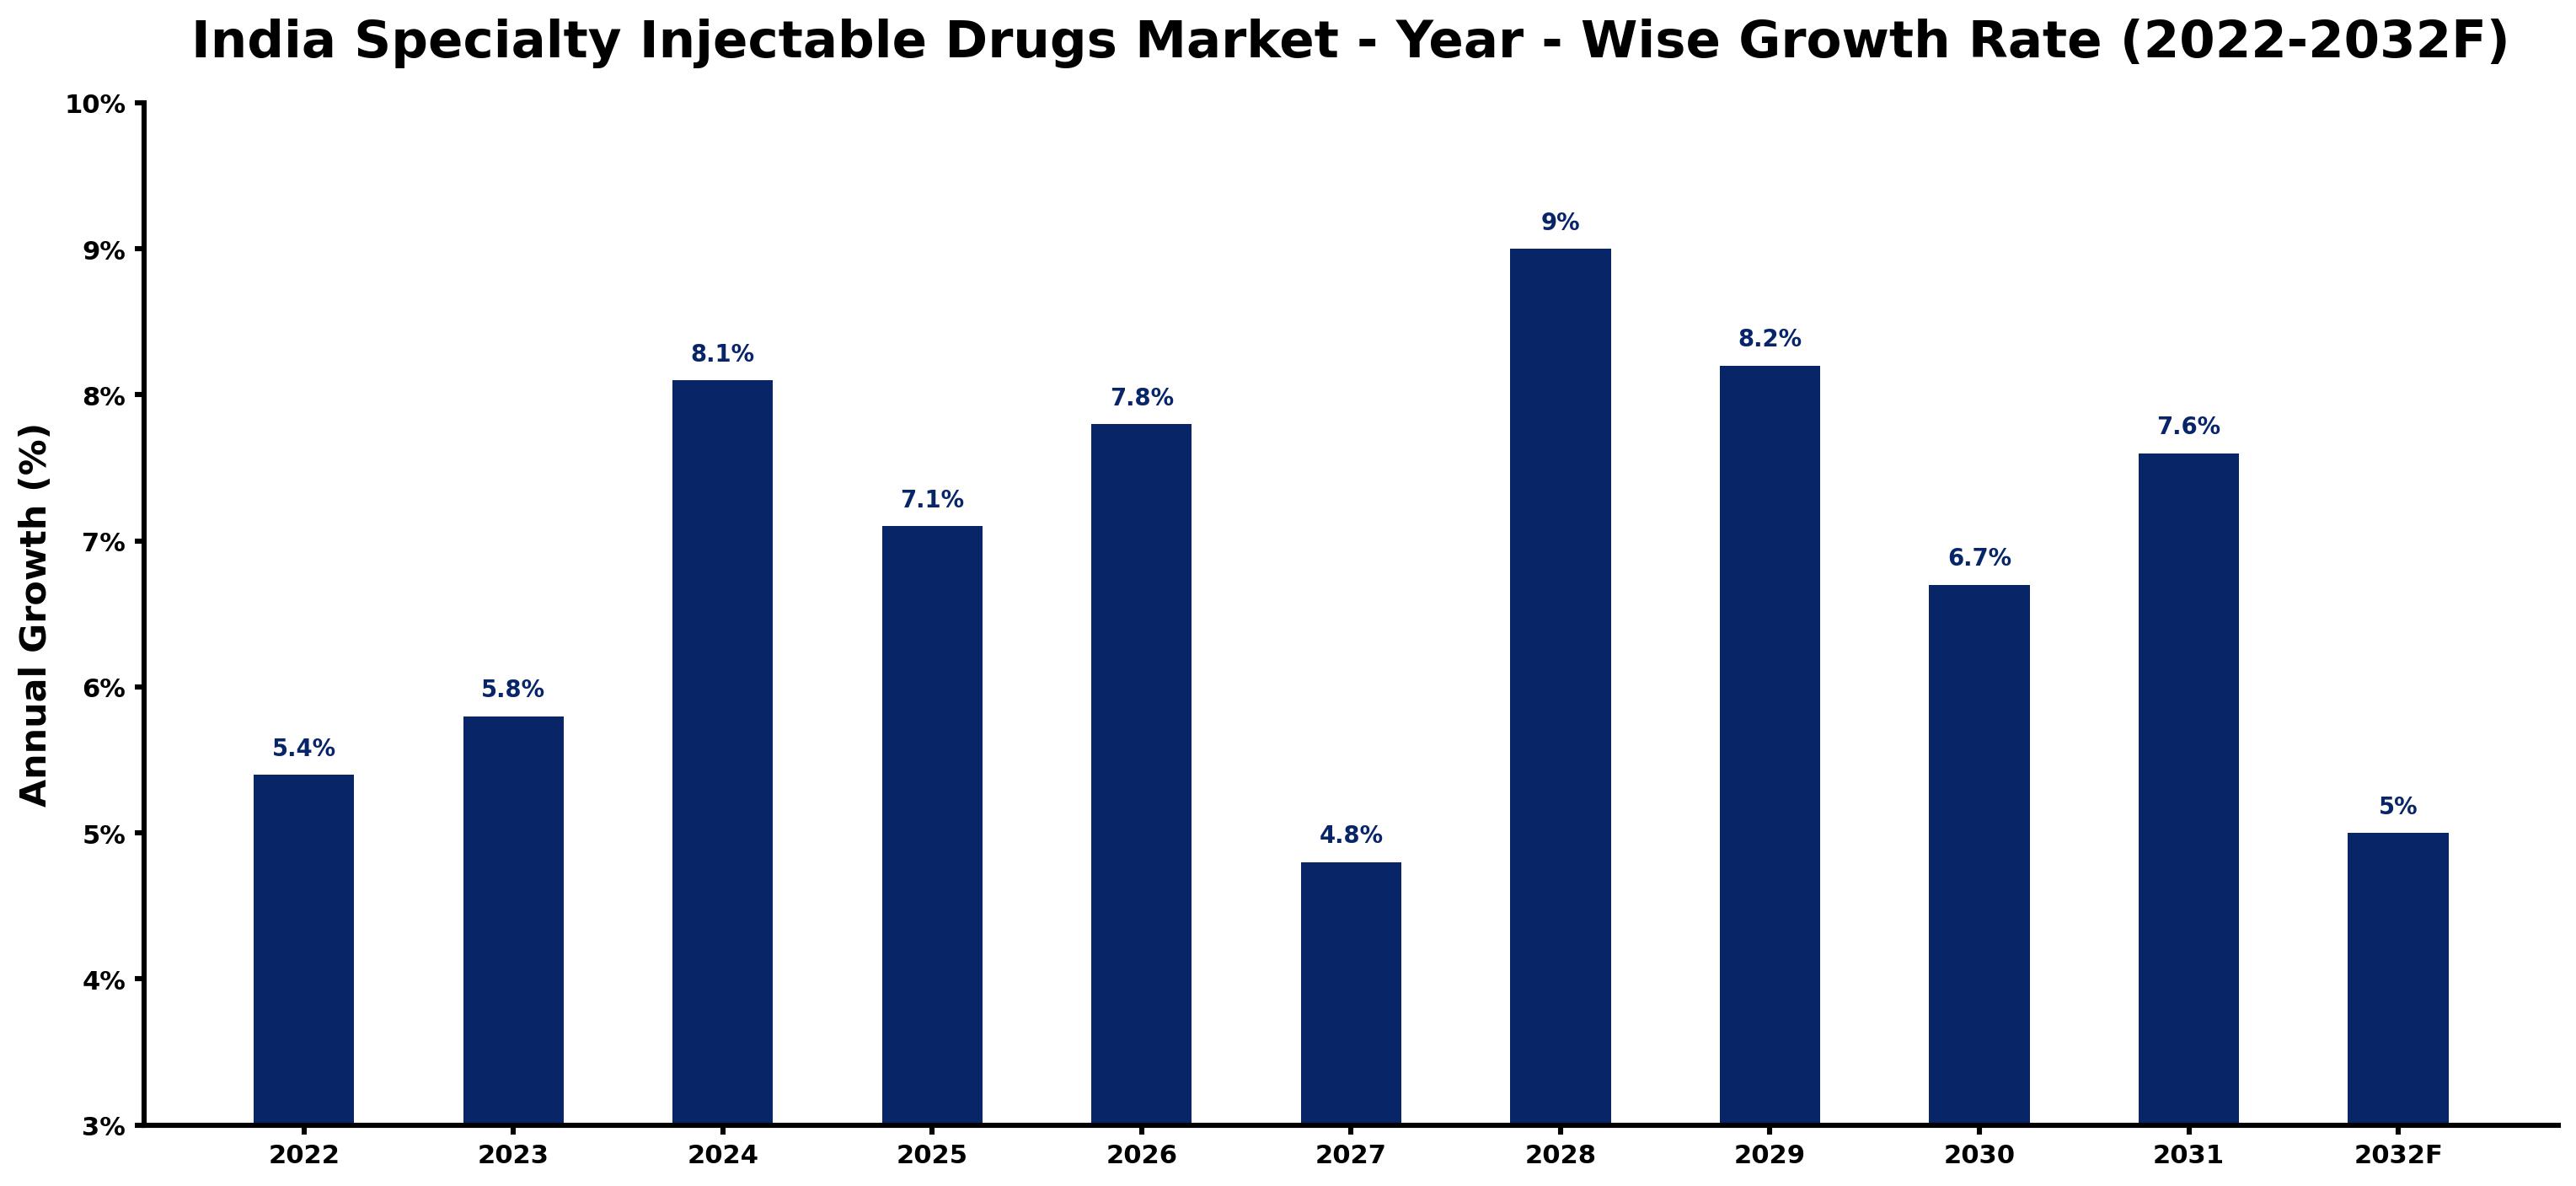
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.4 | The market experienced steady growth due to increasing healthcare demands from urban populations. |
| 2023 | 5.8 | Demand for injectable drugs rose as patient populations expanded and healthcare access improved through the National Health Mission. |
| 2024 | 8.1 | The introduction of new oncology treatments drove growth in the market, particularly in cancer care facilities. |
| 2025 | 7.1 | Growth slowed as the market adjusted to increased competition and supply chain challenges in the injectable sector. |
| 2026 | 7.8 | The market is expected to rebound with stronger demand from hospitals and cancer care centres. |
| 2027 | 4.8 | A slowdown is projected as growth moderates following the peak in 2024. |
| 2028 | 9.0 | The market is expected to surge again with a focus on innovative biologics and treatment protocols. |
| 2029 | 8.2 | Growth is projected to slow as the market stabilises after reaching new heights in 2028. |
| 2030 | 6.7 | Demand is expected to continue growing, supported by advancements in injectable drug formulations and production. |
| 2031 | 7.6 | Growth is projected to accelerate again as hospitals expand their injectable drug offerings and services. |
| 2032 | 5.0 | The market is expected to grow steadily, driven by ongoing healthcare improvements and government initiatives. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Specialty Injectable Drugs Market Synopsis
The Specialty Injectable Drugs Market in India encompasses pharmaceutical formulations designed for parenteral administration, focusing on treating chronic diseases and cancer. These drugs are produced using advanced biotechnological processes and are critical for patient care. The market is driven by the increasing number of healthcare facilities and patient populations, particularly in oncology and autoimmune disorders. With over 1,500 hospitals providing oncology services, demand for injectable therapies continues to rise, making this market a vital segment of the Indian pharmaceutical industry.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing patient populations and chronic disease prevalence | Driver | High | Oncology |
| Growing domestic production capabilities for biologics | Driver | High | Biologics |
| Expansion of cancer care centres across urban areas | Opportunity | High | Cancer Care Centers |
| Rising demand for hormonal injectables in fertility treatments | Opportunity | High | Hormonal Injectables |
| Regulatory hurdles in drug approvals | Restraint | High | Anti-Cancer Injectables |
| Limited access to specialty injectables in rural areas | Restraint | Medium | Pain Relief Drugs |
| High production costs for specialty injectables | Challenge | High | IV Infusion |
| Delays in regulatory approvals for new formulations | Challenge | Medium | Depot Injections |
Evaluation of Drivers in India Specialty Injectable Drugs Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising prevalence of chronic diseases | Oncology | This increases demand for injectable therapies in hospitals, with over 1 million patients treated annually. |
| Advancements in biotechnological processes | Biologics | These innovations improve production efficiency, leading to a 30% market share for biologics. |
| Government initiatives supporting healthcare access | Cancer Care Centers | The National Health Mission improves access to injectable therapies for underserved populations, increasing treatment availability. |
| Growing investment in domestic manufacturing | Hormonal Injectables | The Pharmaceuticals Mission 2021 aims to boost local production, increasing supply for fertility treatments. |
| Expansion of oncology services in hospitals | Anti-Cancer Injectables | With over 1,500 hospitals offering these services, demand for injectable cancer treatments rises. |
The increasing number of patients treated annually at cancer care centres drives demand for injectable therapies. Innovations in production processes lead to a 30% market share for biologics, improving availability. The Pharmaceuticals Mission 2021 supports local manufacturing, which increases supply for hormonal injectables, meeting growing patient needs. Hospitals are expanding their oncology services, further boosting demand for anti-cancer injectables.
Evaluation of Restraints in India Specialty Injectable Drugs Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory hurdles in drug approvals | Anti-Cancer Injectables | The Drug and Cosmetics Act updates can delay the introduction of new injectable therapies, affecting availability. |
| Limited access to specialty injectables in rural areas | Pain Relief Drugs | Patients in rural regions face challenges in obtaining essential injectable medications due to inadequate healthcare infrastructure. |
| High production costs for specialty injectables | IV Infusion | Manufacturers incur high expenses, impacting the pricing and availability of injectables in the market. |
| Market saturation in certain therapeutic areas | Hormonal Injectables | Increased competition among suppliers can limit growth potential in specific segments of the market. |
| Supply chain disruptions affecting availability | Biologics | Challenges in sourcing raw materials can lead to delays in product delivery, impacting patient care. |
India Specialty Injectable Drugs Market Challenges
The India Specialty Injectable Drugs Market encounters several challenges that impede its growth. First, outdated technology in production processes restricts efficiency, leading to delays in drug availability for hospitals and causing treatment interruptions for over 1 million patients each year. Second, high production costs associated with complex manufacturing requirements elevate prices for healthcare providers, limiting access to essential therapies for many patients. Third, a shortage of skilled professionals in biopharmaceuticals hinders the development of new injectable formulations, delaying innovation and restricting treatment options for clinics. Stringent regulatory requirements, such as ISO 13485 compliance, can extend approval timelines, affecting the timely delivery of critical drugs to end users.
Trends in the India Specialty Injectable Drugs Market
Buyers and suppliers in the India Specialty Injectable Drugs Market are adjusting to the following trends.
- Shift towards Biologics in Oncology: The focus on biologics for cancer treatment is increasing, with biologics accounting for 30% of the injectable drugs market in India. This trend is driven by advancements in biotechnology and patient demand for effective therapies.
- Rise of Home Healthcare Services: Home healthcare services are expanding, with a growing preference for self-administration of injectable therapies. Approximately 450 people per square kilometer in urban areas are increasing the need for accessible healthcare solutions.
- Increased Investment in Cancer Care Centers: Investment in cancer care centers is on the rise, with over 200 facilities focusing on injectable treatments. This growth supports the treatment of over 1 million patients annually, improving service availability.
- Emphasis on Quality Standards for Injectables: The adoption of ISO 13485 is becoming essential for manufacturers of injectable drugs. This standard ensures quality management systems are in place, improving product safety and efficacy.
Investment Opportunities in the India Specialty Injectable Drugs Market
Investors looking at the India Specialty Injectable Drugs Market should consider the following areas.
- Urban Hospitals Expanding Injectable Services: Urban hospitals are increasing their injectable drug offerings, driven by a growing patient base. With over 1,500 hospitals providing oncology services, there is a substantial opportunity for suppliers to meet this demand.
- Investing in Biologics Production Facilities: The market gap for biologics presents an opportunity for investment in production facilities. The Pharmaceuticals Mission 2021 supports local manufacturing, enabling suppliers to cater to rising demand for these therapies.
- Partnerships with Cancer Care Centers: Collaborating with cancer care centers can improve market reach for injectable drugs. These centers treat over 1 million patients annually, representing a lucrative opportunity for suppliers to expand their presence.
- Development of Hormonal Injectable Therapies: The increasing demand for hormonal injectables in fertility treatments creates a market gap. Suppliers can enter through partnerships or local approvals to meet this growing need in the healthcare sector.
Government Initiatives in the India Specialty Injectable Drugs Market
The National Health Mission, launched in 2020 by the Ministry of Health and Family Welfare, aims to improve healthcare delivery, including access to injectable drugs for underserved populations. The Pharmaceuticals Mission 2021, initiated by the Department of Pharmaceuticals, focuses on boosting domestic production of specialty injectables with a budget of INR 500 crores. The Drug and Cosmetics Act, updated in 2021, streamlines approval pathways for new injectable drugs, facilitating faster market entry for producers and improving access for patients.
The Central Drugs Standard Control Organization oversees the approval of injectable drugs, ensuring compliance with safety standards. The Indian Council of Medical Research supports research on injectable formulations, providing funding for innovative projects. Additionally, the Ayushman Bharat scheme, expanded in 2021, provides health coverage for injectable treatments, benefiting low-income families and increasing access to necessary therapies.
Future Insight of the India Specialty Injectable Drugs Market
The India Specialty Injectable Drugs Market is poised for substantial growth by 2032, driven by advancements in biotechnological processes and increased government support for domestic manufacturing. The National Health Mission is set to enhance access to injectable therapies, benefiting healthcare facilities and patients alike. By 2030, the Indian pharmaceutical industry is projected to reach $130 billion, with injectables playing a crucial role in this expansion. Research initiatives from the Indian Council of Medical Research are expected to produce new formulations, broadening treatment options for chronic diseases and cancer.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Drug Class – Biologics Dominated, Hormonal Injectables Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, with a 51% revenue share in 2025, Biologics was the largest drug class category. Biologics lead the market share in India's specialty injectable drugs sector due to their critical role in treating chronic diseases and cancers. Their importance is underscored by the fact that biologics account for approximately 30% of the injectable drugs market, making them essential for healthcare providers. Hormonal Injectables are projected to grow fastest, at a CAGR of 9.4% during 2026–2032. Hormonal injectables are experiencing rapid growth as they gain popularity for managing endocrine disorders and fertility treatments. This surge is driven by increasing awareness and acceptance of hormonal therapies among both patients and healthcare professionals. Suppliers should focus on expanding their offerings in hormonal injectables to address the growing demand in this segment.
By Delivery Type – IV Infusion Dominated, Subcutaneous Expected to Grow Fastest
IV Infusion took a 40% share of delivery type in 2025, more than any other category. IV infusion commands the largest market share as it is vital for medication delivery in acute care settings, particularly within hospitals. The established protocols and infrastructure for IV therapies solidify its dominant position in the specialty injectable drugs market. Subcutaneous is set to record the highest CAGR in this split, 8.6% over 2026–2032. Subcutaneous delivery is on the rise due to its convenience for self-administration, particularly for patients undergoing chronic therapies. This trend is likely to continue as patients increasingly seek manageable treatment options. Buyers can anticipate a wider range of subcutaneous delivery systems, potentially improving treatment adherence and patient satisfaction.
By Therapy Area – Oncology Dominated, Autoimmune Disorders Expected to Grow Fastest
Oncology accounted for a 46% market share by therapy area in 2025. Oncology is the leading therapy area, being central to cancer treatment protocols across numerous healthcare facilities in India. The presence of over 200 dedicated cancer care centers focusing on injectable treatments further underscores its importance in the specialty injectable drugs market. The quickest growth will come from Autoimmune Disorders, forecast to expand at a CAGR of 8.4% between 2026 and 2032. Autoimmune disorders are experiencing the fastest growth, driven by the rising prevalence of conditions such as rheumatoid arthritis that necessitate injectable therapies. This shift reflects a growing recognition of the need for effective management strategies for these diseases. Suppliers should consider expanding their offerings to cater to the increasing demand for injectable treatments in autoimmune disorders.
By End User – Hospitals Dominated, Cancer Care Centers Expected to Grow Fastest
The largest end user category in 2025 was Hospitals, with a 41% share of total revenue. Hospitals account for the largest end user share of specialty injectable drugs, acting as the primary providers of patient care involving these therapies. The extensive network of over 1,500 hospitals offering oncology services highlights their pivotal role in the market. Over 2026–2032, Cancer Care Centers are expected to post the fastest growth, at a CAGR of 9.2%. Cancer care centers are rapidly growing in response to the rising number of patients seeking injectable therapies for cancer treatment. This growth is fuelled by the increasing incidence of cancer within the population. Suppliers should strategically target cancer care centers to align with the increasing demand for specialized oncology injectable treatments.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Specialty Injectable Drugs Market Outlook
- Market Size of India Specialty Injectable Drugs Market, 2025
- Forecast of India Specialty Injectable Drugs Market, 2032
- Historical Data and Forecast of India Specialty Injectable Drugs Revenues & Volume for the Period 2022 - 2032F
- India Specialty Injectable Drugs Market Trend Evolution
- India Specialty Injectable Drugs Market Drivers and Challenges
- India Specialty Injectable Drugs Price Trends
- India Specialty Injectable Drugs Porter's Five Forces
- India Specialty Injectable Drugs Industry Life Cycle
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Drug Class for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Biologics for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Hormonal Injectables for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Anti-Cancer Injectables for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Pain Relief Drugs for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Delivery Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Subcutaneous for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Intramuscular for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By IV Infusion for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Depot Injections for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Therapy Area for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Autoimmune Disorders for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Endocrine Disorders for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Oncology for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Neurological Disorders for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Hospitals for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Cancer Care Centers for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Injectable Drugs Market Revenues & Volume By Rehabilitation Centers for the Period 2022 - 2032F
- India Specialty Injectable Drugs Import Export Trade Statistics
- Market Opportunity Assessment By Drug Class
- Market Opportunity Assessment By Delivery Type
- Market Opportunity Assessment By Therapy Area
- Market Opportunity Assessment By End User
- India Specialty Injectable Drugs Top Companies Market Share
- India Specialty Injectable Drugs Competitive Benchmarking By Technical and Operational Parameters
- India Specialty Injectable Drugs Company Profiles
- India Specialty Injectable Drugs Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Drug Class
- Biologics
- Hormonal Injectables
- Anti-Cancer Injectables
- Pain Relief Drugs
By Delivery Type
- Subcutaneous
- Intramuscular
- IV Infusion
- Depot Injections
By Therapy Area
- Autoimmune Disorders
- Endocrine Disorders
- Oncology
- Neurological Disorders
By End User
- Hospitals
- Clinics
- Cancer Care Centers
- Rehabilitation Centers































