India Telecom Optical Components Market Size & Growth Rate
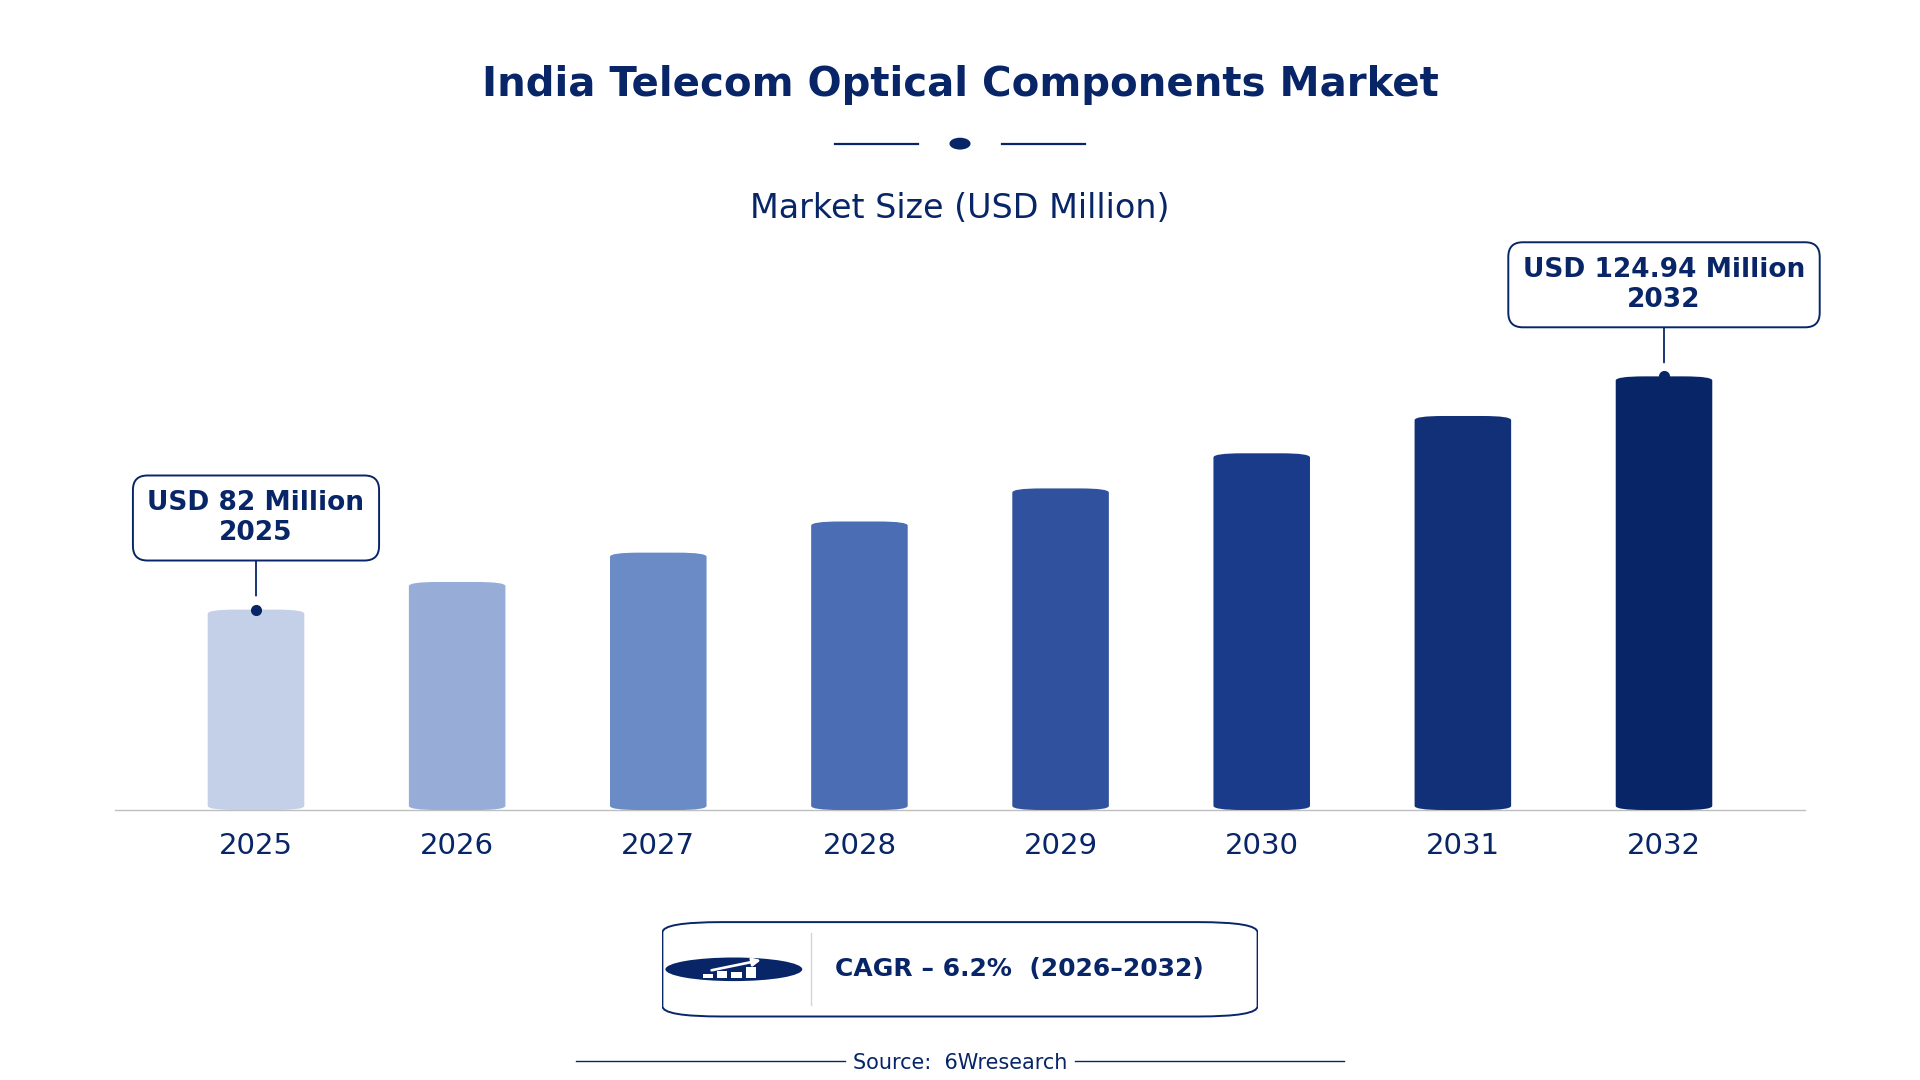
According to 6Wresearch internal database and industry insights, the India Telecom Optical Components Market was valued at USD 82.0 million in 2025 and is projected to reach USD 124.94 million by 2032, growing at a CAGR of approximately 6.2% during 2026–2032.
India Telecom Optical Components Market Highlights
| Report Metric | Details |
| Report Name | India Telecom Optical Components Market |
| Market Size 2025 | USD 82.0 million |
| Market Size 2032 | USD 124.94 million |
| Absolute Growth 2025–2032 | USD 42.94 million |
| CAGR 2026–2032 | 6.2% |
| Peak Annual Growth | 8.9% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Optical Components Type, 2025 | Optical Cables & Connectors (52% share) |
| Leading Product Type, 2025 | SFP/QSFP Modules (46% share) |
| Leading Component Type, 2025 | Fiber/Connector (48% share) |
| Leading Distribution Channel, 2025 | OEM Supply (39% share) |
| Leading End User Industry, 2025 | Data Centers (34% share) |
| Fastest-Growing Optical Components Type | Optical Transceivers (8.8% CAGR) |
| Fastest-Growing Component Type | DWDM/Coherent (8.6% CAGR) |
| Fastest-Growing Distribution Channel | Component Distributors (8.8% CAGR) |
| Fastest-Growing End User Industry | Telecom Exchanges (7.2% CAGR) |
| Growing Sector | Data Centers |
| Key End Users | Telecom Operators, Data Centers, Network Providers, Infrastructure Developers |
India Telecom Optical Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
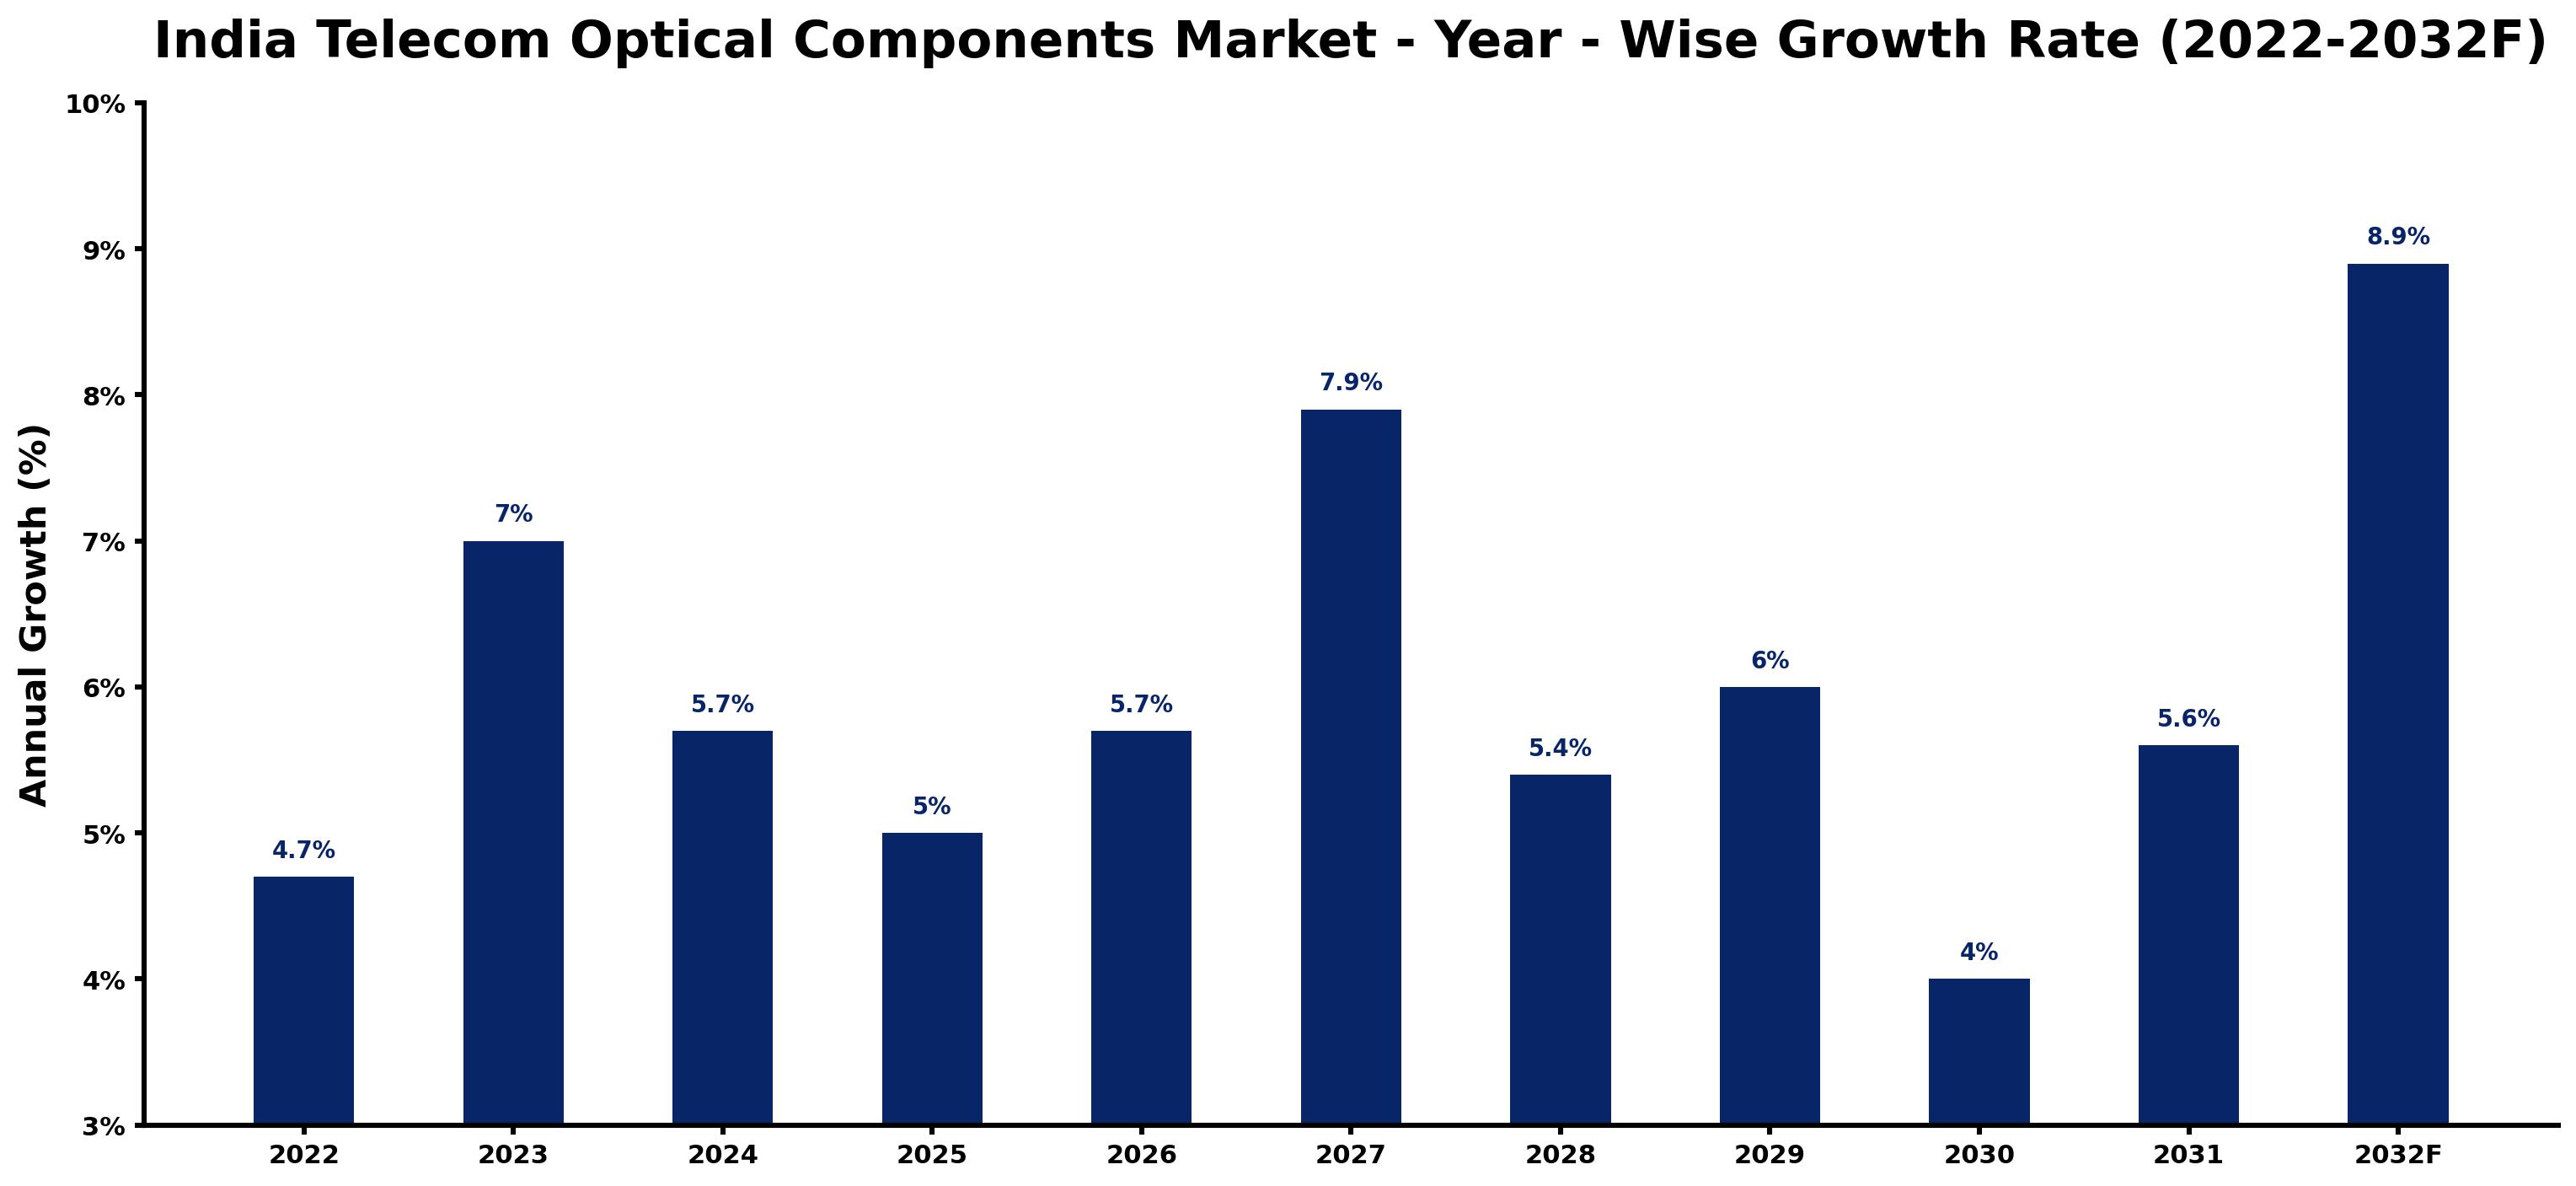
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.7 | The market showed steady growth due to ongoing infrastructure projects and demand from data centers. |
| 2023 | 7.0 | Growth accelerated as broadband subscribers increased, reflecting higher connectivity needs from the Digital India initiative. |
| 2024 | 5.7 | Demand stabilised as the market adjusted to previous rapid expansions and data center requirements. |
| 2025 | 5.0 | Demand from data centers and telecom exchanges contributed to slower growth rates as infrastructure projects matured. |
| 2026 | 5.7 | An increase in optical fiber connections for the Fiber to the Home initiative is expected to boost growth. |
| 2027 | 7.9 | Demand will rise as more users seek high-speed internet and data services from telecom exchanges. |
| 2028 | 5.4 | Growth is projected to slow as market saturation begins to take effect in urban areas. |
| 2029 | 6.0 | A resurgence in infrastructure investments from the National Broadband Mission will drive demand for optical components. |
| 2030 | 4.0 | Growth is expected to decelerate as the market approaches saturation levels in major cities. |
| 2031 | 5.6 | Increased demand from the telecom sector will support a recovery in growth rates from data centers. |
| 2032 | 8.9 | The market will peak as new technologies and infrastructure projects emerge from the National Digital Communications Policy. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Telecom Optical Components Market Synopsis
Telecom Optical Components in India are essential technologies for transmitting data over optical fibers, manufactured using advanced materials like glass and semiconductors. These components enable high-speed internet and telecommunications, with demand driven by over 1.2 billion mobile subscribers. The growing focus on local manufacturing further supports market expansion, as suppliers aim to meet rising domestic demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing mobile subscriptions drive demand for optical components. | Driver | High | Optical Transceivers |
| Rising data center requirements for connectivity fuels component purchases. | Driver | High | Data Centers |
| The Digital India initiative creates opportunities for local manufacturing. | Opportunity | High | Optical Cables & Connectors |
| The National Broadband Mission expands the market for optical components. | Opportunity | High | Optical Amplifiers |
| High initial investment costs limit market entry for new players. | Restraint | Medium | Optical Cables & Connectors |
| Stringent BIS standards may restrict certain product approvals. | Restraint | Medium | Optical Switches |
| Limited local manufacturing capabilities hinder supply chain efficiency. | Challenge | High | OEM Supply |
| Technological advancements may outpace existing production capabilities. | Challenge | Medium | Optical Vendors |
Evaluation of Drivers in India Telecom Optical Components Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising mobile subscriptions drive demand for optical transceivers. | Optical Transceivers | With over 1.2 billion mobile subscribers, demand for data transmission components increases. |
| Data center expansions require more optical components. | Data Centers | Projected need for 30 million fiber optic connections by 2025 stimulates purchasing. |
| The Digital India initiative promotes investments in optical technologies. | Optical Cables & Connectors | This programme encourages investments to improve telecommunications infrastructure across the country. |
| The National Broadband Mission aims for universal broadband access. | Optical Amplifiers | This initiative will increase demand for optical components to meet connectivity targets. |
| Local manufacturing initiatives under Make in India support growth. | Optical Cables & Connectors | Encouraging domestic production increases availability and reduces costs. |
Market growth in India for Telecom Optical Components hinges on the rise in mobile subscriptions, escalating data centre requirements, and local manufacturing efforts. The demand for optical transceivers stems from the necessity for efficient data transmission, supported by over 1.2 billion mobile subscribers. The anticipated need for 30 million fibre optic connections by 2025 will drive procurement in data centres. Investments in telecommunications infrastructure will further stimulate demand for optical amplifiers and connectors.
Evaluation of Restraints in India Telecom Optical Components Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High initial investment costs limit market entry for new players. | Optical Cables & Connectors | New entrants face financial barriers, restricting competition and innovation. |
| Stringent BIS standards may restrict certain product approvals. | Optical Switches | Compliance with standards can delay market entry and increase costs for suppliers. |
| Limited local manufacturing capabilities hinder supply chain efficiency. | OEM Supply | Dependence on imports can lead to delays and higher prices for components. |
| Market saturation in urban areas restricts growth potential. | Data Centers | Limited new projects in saturated regions may slow demand for optical components. |
| Technological advancements may outpace existing production capabilities. | Optical Vendors | Suppliers may struggle to keep up with rapid technological changes, affecting sales. |
India Telecom Optical Components Market Challenges
In the India Telecom Optical Components market, buyers face intense competition among numerous suppliers, leading to price wars that can reduce profit margins for producers. Rising costs of essential materials, particularly glass and semiconductors, have inflated production expenses by approximately 20%, forcing suppliers to increase prices unfavourably for buyers. Supply chain disruptions, exacerbated by global logistics issues, delay the delivery of key components, extending project timelines for buyers and risking contract penalties. Rapid technological advancements necessitate ongoing investment in R&D, straining smaller suppliers' financial resources and hindering their competitive edge.
Trends in the India Telecom Optical Components Market
The trends below show where the India Telecom Optical Components Market is heading.
- Shift from Traditional to Advanced Optical Technologies: Since 2020, India has experienced a shift towards advanced optical technologies in telecom infrastructure. The optical fibre cable market is projected to grow at a CAGR of 15% from 2023 to 2028, driven by the Digital India initiative.
- Increase in Fiber to the Home (FTTH) Initiatives: The FTTH initiative aims to connect 50 million homes by 2025, improving broadband access. This initiative will necessitate substantial investments in optical components, boosting demand in the residential sector.
- Expansion of Data Centers Across India: With over 300 data centres in 2023, the demand for optical components is escalating. This growth is expected to require 30 million fibre optic connections by 2025, highlighting the sector's expansion.
- Growing Focus on Local Manufacturing: The Make in India programme, launched in 2020, promotes local production of telecom components. This initiative seeks to enhance domestic manufacturing, reducing reliance on imports and increasing local supply.
Investment Opportunities in the India Telecom Optical Components Market
Several openings in the India Telecom Optical Components Market merit attention from investors.
- Partnerships for Local Manufacturing: Local manufacturers can collaborate with international firms to enhance production capabilities. With the optical components market expected to reach USD 82.0 million by 2025, such partnerships can address rising demand.
- Investment in Data Center Infrastructure: Data centres in Maharashtra and Karnataka are rapidly expanding, creating a demand for optical components. Investing in these regions can yield substantial returns as the need for high-speed connectivity increases.
- Certification for Optical Components: Achieving BIS certification can provide suppliers with access to the Indian market. As standards evolve, certified products will see higher demand, especially in urban areas with growing infrastructure needs.
- Supply Chain Development for Telecom Exchanges: Building supply chains for telecom exchanges will be crucial as infrastructure expands. This sector is poised for significant growth, driven by the National Broadband Mission's objectives for universal access.
Government Initiatives in the India Telecom Optical Components Market
The National Digital Communications Policy 2020 aims to improve broadband connectivity across India, targeting 50 Mbps for all citizens by 2025. This policy promotes investments in optical components to achieve connectivity goals. The Telecom Infrastructure Policy 2021 focuses on enhancing telecom infrastructure and lowering barriers for new installations, facilitating easier access to optical technologies. Additionally, the Digital India initiative, launched in 2020, seeks to transform India into a digitally empowered society, greatly influencing telecom infrastructure and optical component demand.
In 2023, the National Broadband Mission was launched to provide universal broadband access to all villages by 2025, increasing the demand for optical components. The Ministry of Communications oversees this mission, ensuring that all regions benefit from improved connectivity. The Make in India programme, also initiated in 2020, encourages local manufacturing of telecom components, including optical components, to boost domestic production and reduce reliance on imports. This initiative aims to increase local supply and create job opportunities in the manufacturing sector.
Future Insight of the India Telecom Optical Components Market
By 2032, buyers and suppliers in the India Telecom Optical Components market can anticipate considerable advancements, particularly due to the Digital India initiative and the National Digital Communications Policy. The government aims to provide 50 Mbps broadband access for all by 2025, dramatically increasing demand for optical components. Improved standards set by the Bureau of Indian Standards will ensure higher product quality, building trust among buyers. Investments in local manufacturing will drive innovation, enabling suppliers to effectively meet the growing needs of the telecommunications sector.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Optical Components Type – Optical Cables & Connectors Dominated, Optical Transceivers Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, Optical Cables & Connectors held a 52% share of the India Telecom Optical Components Market by optical components type in 2025. Optical Cables & Connectors dominate the market share due to their essential role in connecting and transmitting data across extensive fiber optic networks. With over 1.2 billion mobile subscribers in India, their widespread application is driven by the demand for reliable connectivity across various sectors. Optical Transceivers are set to record the highest CAGR in this split, 8.8% over 2026–2032. The growth of Optical Transceivers is propelled by the increasing need for high-speed data transmission, particularly as data centers are projected to require 30 million fiber optic connections by 2025. This segment's expansion aligns with the Digital India initiative, which focuses on enhancing telecommunications infrastructure. Suppliers should enhance their Optical Transceivers offerings to meet the rising demand for high-speed data transmission.
By Product Type – SFP/QSFP Modules Dominated and Is Expected to Record the Fastest Growth
With a 46% revenue share in 2025, SFP/QSFP Modules was the largest product type category. SFP/QSFP Modules hold the largest share due to their critical function in providing high-speed connectivity within networking equipment. The surge in broadband subscribers, reported at a 10% increase by TRAI in 2023, further solidifies their importance in the market. The same category are also set to grow fastest, at a CAGR of 8.6% during 2026–2032. SFP/QSFP Modules are also the fastest-growing segment, driven by the expanding demand for high-speed data services across various sectors. As more data centers emerge, the reliance on these modules for efficient data processing will continue to grow. Buyers should prioritise SFP/QSFP Modules to ensure they meet the increasing demands for high-speed connectivity in their networks.
By Component Type – Fiber/Connector Dominated, DWDM/Coherent Expected to Grow Fastest
In 2025, Fiber/Connector led the component type split with a 48% share. Fiber/Connector leads the market as they are crucial for establishing optical connections necessary for effective data transmission. Their pivotal role in the infrastructure of over 300 data centers in India underscores their dominance in this segment. DWDM/Coherent is projected to grow fastest, at a CAGR of 8.6% during 2026–2032. DWDM/Coherent technology is experiencing rapid growth due to its capability to facilitate high-capacity data transmission over long distances. This trend is particularly relevant as the National Digital Communications Policy aims to significantly enhance broadband access by 2025. Suppliers should increase their focus on DWDM/Coherent technologies to cater to the surging demand for high-capacity data solutions.
By Distribution Channel – OEM Supply Dominated, Component Distributors Expected to Grow Fastest
OEM Supply took a 39% share of distribution channel in 2025, more than any other category. OEM Supply is the leading distribution channel, providing essential components directly to manufacturers of telecom equipment, ensuring a consistent supply chain. This channel's strength is reflected in the increasing number of telecom infrastructure projects across states like Maharashtra and Karnataka. The quickest growth will come from Component Distributors, forecast to expand at a CAGR of 8.8% between 2026 and 2032. Component Distributors are the fastest-growing channel, driven by the rising need for a variety of optical components among end users. As the telecom market expands, these distributors play an increasingly vital role in supplying diverse components. Suppliers should strengthen relationships with Component Distributors to enhance market reach and accessibility.
By End User Industry – Data Centers Dominated, Telecom Exchanges Expected to Grow Fastest
The largest end user industry category in 2025 was Data Centers, with a 34% share of total revenue. Data Centers are the largest end users of optical components, requiring these technologies for high-speed data processing and connectivity. The substantial investment in optical technologies across over 300 data centers in India highlights their market leadership. Telecom Exchanges are set to record the highest CAGR in this split, 7.2% over 2026–2032. Telecom Exchanges are rapidly growing as they incorporate optical components for efficient communication, reflecting the increasing demand for robust telecommunications infrastructure. This growth is supported by government initiatives aimed at improving connectivity nationwide. Buyers in the telecom sector should prioritise investments in optical components to enhance the efficiency of their exchanges.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Telecom Optical Components Market Outlook
- Market Size of India Telecom Optical Components Market, 2025
- Forecast of India Telecom Optical Components Market, 2032
- Historical Data and Forecast of India Telecom Optical Components Revenues & Volume for the Period 2022 - 2032F
- India Telecom Optical Components Market Trend Evolution
- India Telecom Optical Components Market Drivers and Challenges
- India Telecom Optical Components Price Trends
- India Telecom Optical Components Porter's Five Forces
- India Telecom Optical Components Industry Life Cycle
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Optical Components Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Optical Transceivers for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Optical Amplifiers for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Optical Switches for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Optical Cables & Connectors for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By SFP/QSFP Modules for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By EDFA/Raman for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By OXC/MEMS for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Patch Cords/Plugs for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By DWDM/Coherent for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Long-Haul for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Photonic Layer for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Fiber/Connector for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By OEM Supply for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Component Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Optical Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Retail + Online for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Data Centers for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Metro Networks for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Telecom Exchanges for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Optical Components Market Revenues & Volume By Enterprise Networks for the Period 2022 - 2032F
- India Telecom Optical Components Import Export Trade Statistics
- Market Opportunity Assessment By Optical Components Type
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- India Telecom Optical Components Top Companies Market Share
- India Telecom Optical Components Competitive Benchmarking By Technical and Operational Parameters
- India Telecom Optical Components Company Profiles
- India Telecom Optical Components Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Optical Components Type
- Optical Transceivers
- Optical Amplifiers
- Optical Switches
- Optical Cables & Connectors
By Product Type
- SFP/QSFP Modules
- EDFA/Raman
- OXC/MEMS
- Patch Cords/Plugs
By Component Type
- DWDM/Coherent
- Long-Haul
- Photonic Layer
- Fiber/Connector
By Distribution Channel
- OEM Supply
- Component Distributors
- Optical Vendors
- Retail + Online
By End User Industry
- Data Centers
- Metro Networks
- Telecom Exchanges
- Enterprise Networks































