India Turbocharger Air Starter Market Size & Growth Rate
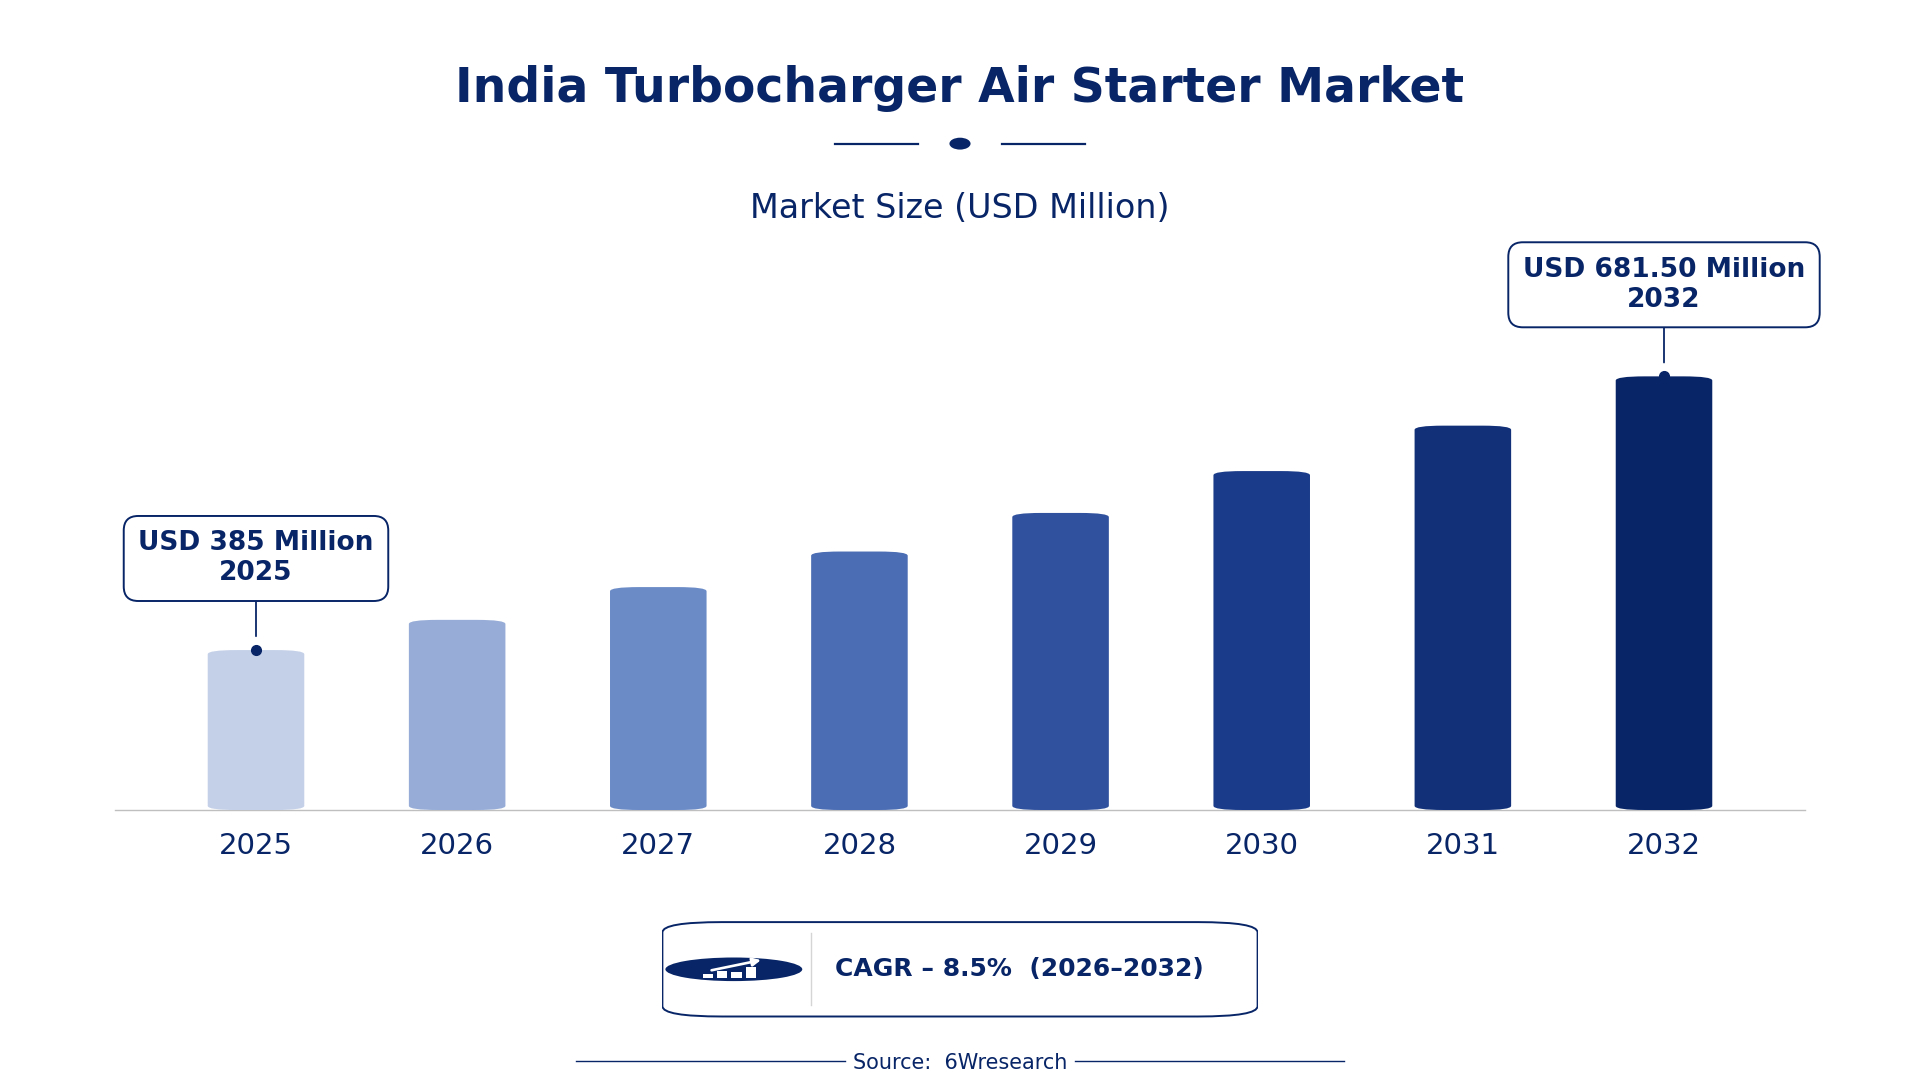
According to 6Wresearch internal database and industry insights, the India Turbocharger Air Starter Market was valued at USD 385.0 million in 2025 and is projected to reach USD 681.50 million by 2032, growing at a CAGR of approximately 8.5% during 2026–2032.
India Turbocharger Air Starter Market Highlights
| Report Metric | Details |
| Report Name | India Turbocharger Air Starter Market |
| Market Size 2025 | USD 385.0 million |
| Market Size 2032 | USD 681.50 million |
| Absolute Growth 2025–2032 | USD 296.50 million |
| CAGR 2026–2032 | 8.5% |
| Peak Annual Growth | 10.4% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Starter Type, 2025 | Axial Flow Starter (39% share) |
| Leading Air Source Type, 2025 | High Pressure Air Tanks (40% share) |
| Leading Application Area, 2025 | Aircraft Engines (52% share) |
| Leading End User, 2025 | Military OEMs (43% share) |
| Fastest-Growing Starter Type | Radial Air Starter (10.0% CAGR) |
| Fastest-Growing Air Source Type | Pneumatic Starter Systems (10.5% CAGR) |
| Fastest-Growing Application Area | Gas Turbines (10.5% CAGR) |
| Fastest-Growing End User | Aerospace Integrators (9.8% CAGR) |
| Growing Sector | Aerospace and Defense |
| Key End Users | Military OEMs, Aerospace Integrators, Turbine Builders |
India Turbocharger Air Starter Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
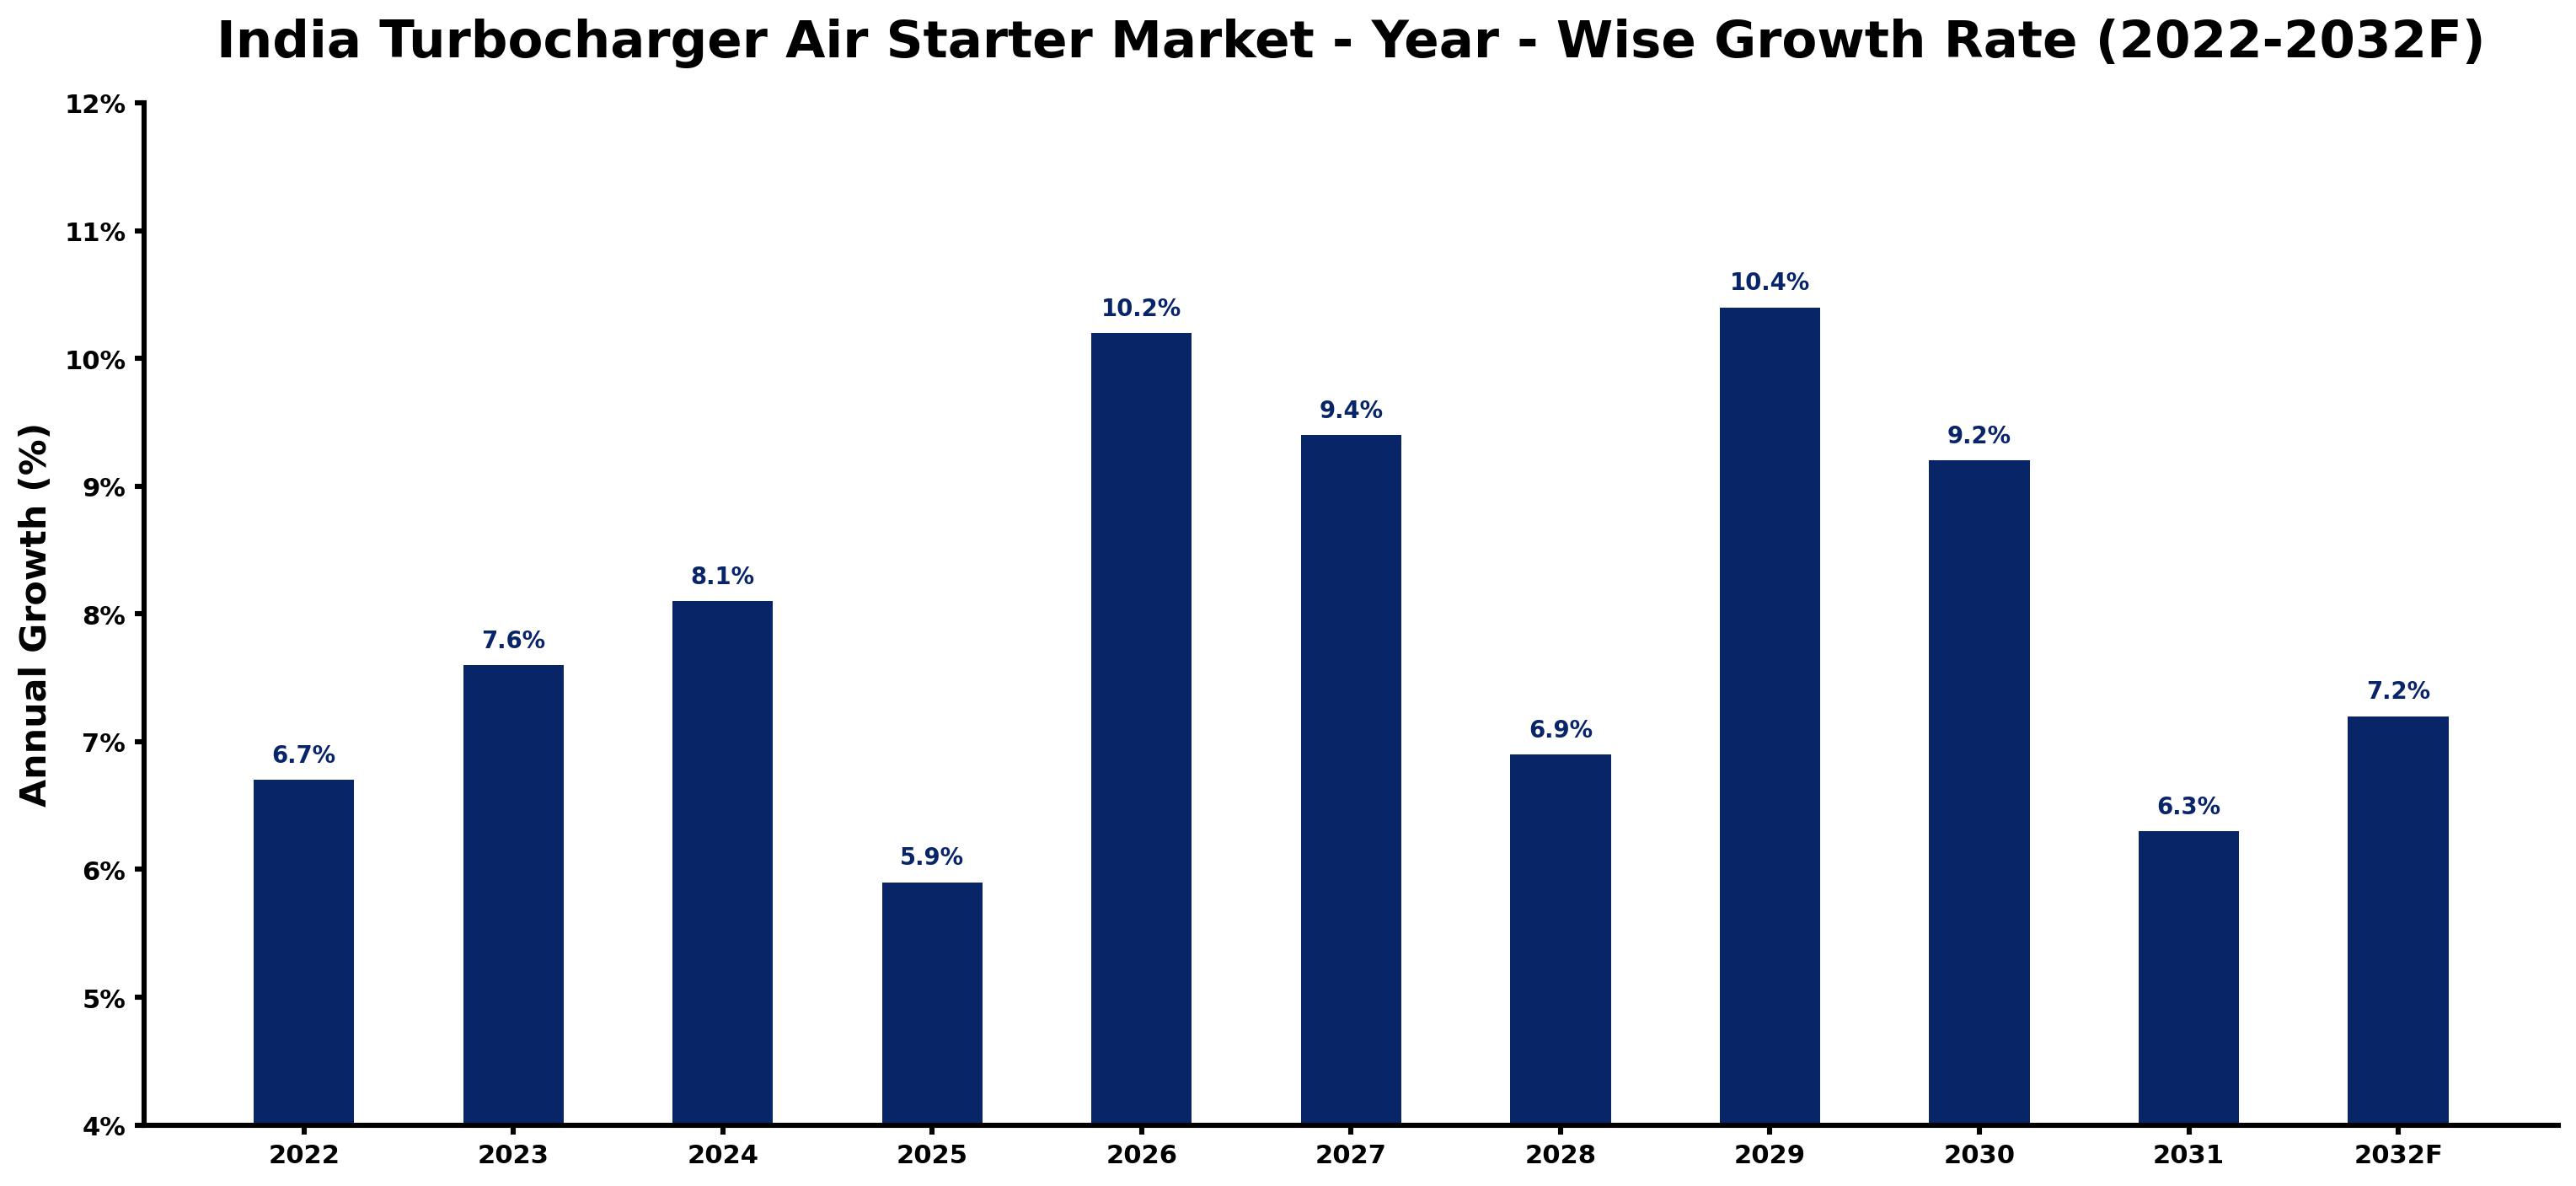
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.7 | The market experienced steady growth due to increased military aircraft operations. |
| 2023 | 7.6 | Demand rose as the Indian military expanded its fleet of operational aircraft. |
| 2024 | 8.1 | Growth accelerated with the aerospace sector's increasing investment in indigenous technologies. |
| 2025 | 5.9 | A slowdown occurred as the market adjusted to previous high growth rates. |
| 2026 | 10.2 | The market rebounded with renewed interest in domestic manufacturing capabilities. |
| 2027 | 9.4 | Growth slowed due to a shortage of skilled workforce affecting production efficiency. |
| 2028 | 6.9 | Demand continued to moderate as the market adjusted to new production capacities. |
| 2029 | 10.4 | Growth peaked as military procurement accelerated, necessitating more air starters. |
| 2030 | 9.2 | A slowdown followed as the market stabilised after reaching peak demand levels. |
| 2031 | 6.3 | Growth continued to slow as the market approached saturation in certain areas. |
| 2032 | 7.2 | Demand increased again with new military contracts and local aerospace projects. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Turbocharger Air Starter Market Synopsis
Turbocharger Air Starters in India are devices that utilize compressed air to start engines, primarily in aviation and industrial applications. These starters are crucial for starting aircraft engines and gas turbines, manufactured with high-strength materials to withstand extreme conditions. The India Turbocharger Air Starter Market is growing due to the expanding aviation sector, which includes over 300 operational airports as of 2023, and substantial military demand, with more than 2,000 aircraft requiring reliable starting systems. The aerospace industry is projected to reach $70 billion by 2030, driven by local manufacturing initiatives and government support.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing military aircraft operations drive demand for reliable starting systems. | Driver | High | Military OEMs |
| The growth of the aerospace sector stimulates demand for turbocharger air starters. | Driver | High | Aerospace Integrators |
| The push for local manufacturing creates opportunities for suppliers in the market. | Opportunity | High | Military OEMs |
| Investment in aerospace technologies opens new avenues for product development. | Opportunity | High | Aerospace Integrators |
| High costs of advanced manufacturing may limit some producers' capabilities. | Restraint | Medium | Military OEMs |
| Stringent regulatory standards can delay product approvals and market entry. | Restraint | Medium | Aerospace Integrators |
| Supply chain disruptions can hinder timely production and delivery of components. | Challenge | High | Military OEMs |
| Limited availability of skilled workforce affects production efficiency. | Challenge | Medium | Aerospace Integrators |
Evaluation of Drivers in India Turbocharger Air Starter Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising military aircraft operations increase demand for air starters. | Military OEMs | The Indian military operates over 2,000 aircraft, necessitating reliable starting systems for maintenance. |
| Expansion of the aerospace sector boosts demand for air starters. | Aerospace Integrators | The aerospace industry in India is projected to reach $70 billion by 2030, driving purchases. |
| Government initiatives support local manufacturing of aerospace components. | Military OEMs | The Make in India initiative encourages local production, improving supply chain reliability. |
| Investment in indigenous technologies increases demand for turbocharger air starters. | Aerospace Integrators | The Defense Research and Development Organization (DRDO) supports local aerospace technology development. |
| Increasing number of operational airports enhances market potential. | Aerospace Integrators | India has over 300 operational airports as of 2023, increasing the need for air starters. |
The Indian military operates over 2,000 aircraft, which creates a consistent demand for reliable starting systems. The aerospace industry is projected to reach $70 billion by 2030, prompting investments in advanced technologies. The presence of over 300 operational airports increases the need for turbocharger air starters in aviation applications.
Evaluation of Restraints in India Turbocharger Air Starter Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced manufacturing may limit some producers' capabilities. | Military OEMs | Producers face challenges in maintaining competitive pricing while ensuring quality and performance. |
| Stringent regulatory standards can delay product approvals and market entry. | Aerospace Integrators | Compliance with Bureau of Indian Standards (BIS) regulations can prolong the certification process. |
| Supply chain disruptions can hinder timely production and delivery of components. | Military OEMs | Global supply chain issues have affected the availability of critical materials for manufacturing. |
| Limited availability of skilled workforce affects production efficiency. | Aerospace Integrators | A shortage of trained personnel can slow down production and increase operational costs. |
| Market saturation in certain segments may limit growth potential. | Military OEMs | As the market matures, competition increases, making it harder to capture new customers. |
India Turbocharger Air Starter Market Challenges
The India Turbocharger Air Starter Market encounters several practical issues, starting with skills shortages among producers. Limited training programmes in advanced aerospace technologies impede workforce development, leading to production delays that can extend timelines by 20%. Rising costs also challenge importers, as fluctuating raw material prices can inflate expenses by 15%, affecting profit margins. Buyers in the aviation sector face reliability concerns; the Indian Air Force's fleet of over 1,200 aircraft requires dependable air starters, risking operational delays. Increased competition from international suppliers compels local producers to lower prices, potentially affecting product quality.
Trends in the India Turbocharger Air Starter Market
The trends below show where the India Turbocharger Air Starter Market is heading.
- Shift towards Indigenous Manufacturing: In 2023, the Indian government allocated ₹1,500 crore for the development of aerospace and defense industries. This funding supports local manufacturers, resulting in a greater reliance on domestic production of turbocharger air starters.
- Increase in Military Procurement: Since 2020, military procurement has intensified, driven by the Defense Production Policy aiming for $26 billion in turnover by 2025. This trend boosts demand for air starters as military operations expand.
- Growth in Aerospace Infrastructure: The National Civil Aviation Policy launched in 2016 has improved aviation infrastructure, increasing the number of operational airports to over 300 by 2023. This growth necessitates more reliable starting systems for aircraft.
- Emergence of Advanced Technologies: The Defense Research and Development Organization (DRDO) has focused on developing indigenous aerospace technologies, improving the capabilities of turbocharger air starters for military applications.
Investment Opportunities in the India Turbocharger Air Starter Market
Some of the investment opportunities in the India Turbocharger Air Starter Market are mentioned below.
- Local Partnerships for Manufacturing: Forming joint ventures with local manufacturers can facilitate entry into the market. The aerospace industry is projected to grow significantly, presenting opportunities for collaboration.
- Investment in Advanced Technologies: With the aerospace industry expanding, there is a gap for innovative turbocharger air starters. Targeting military OEMs can yield substantial returns as they seek reliable systems.
- Supply of High-Pressure Air Tanks: High Pressure Air Tanks are essential for turbocharger air starters, with a market share of 40% in 2025. Suppliers can enter by partnering with military OEMs to meet their needs.
- Focus on Aerospace Integrators: Aerospace Integrators are increasingly seeking reliable starting systems. Investing in product development tailored to their needs can open new market avenues.
Government Initiatives in the India Turbocharger Air Starter Market
The Aerospace and Defense Manufacturing Competitiveness Scheme (ADCMS) launched in 2020 by the Ministry of Defence promotes domestic manufacturing capabilities. This initiative encourages local production of turbocharger air starters, reducing reliance on imports and supporting sector growth. Additionally, the National Aerospace Policy introduced in 2021 fosters the growth of the aerospace sector, creating a conducive environment for manufacturers and suppliers alike.
Military buyers benefit from the Defense Production Policy, which aims for 70% indigenization in defense procurement by 2025. This policy encourages military OEMs to source locally produced turbocharger air starters, ensuring reliability and performance. The Ministry of Defence oversees the implementation of these policies, facilitating approvals and funding for relevant projects.
Future Insight of the India Turbocharger Air Starter Market
Several forward-looking factors should support the India Turbocharger Air Starter Market in the coming years. The aerospace industry aims to reach $70 billion by 2030, driving demand for reliable starting systems. Initiatives like the Aerospace and Defence Manufacturing Competitiveness Scheme will enhance local manufacturing capabilities, allowing suppliers to efficiently meet domestic requirements. The Defence Research and Development Organization's focus on indigenous technologies will also promote innovation in air starter systems, creating new opportunities for producers.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Starter Type – Axial Flow Starter Dominated, Radial Air Starter Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, in 2025, Axial Flow Starter led the starter type split with a 39% share. The Axial Flow Starter commands the largest share due to its efficiency and reliability in aircraft engines, which is critical for military operations. With over 1,200 aircraft in the Indian Air Force, the demand for this type of starter is consistently high. Over 2026–2032, Radial Air Starter is expected to post the fastest growth, at a CAGR of 10.0%. The Radial Air Starter is growing quickly as it becomes the preferred choice for gas turbines in industrial applications, supported by the aerospace sector's projected growth to $70 billion by 2030. This trend indicates a shift towards more efficient starting solutions, allowing the Radial Air Starter to gain traction. Suppliers should prioritise developing advanced Radial Air Starters to seize the opportunities presented by this growing segment.
By Air Source Type – High Pressure Air Tanks Dominated, Pneumatic Starter Systems Expected to Grow Fastest
High Pressure Air Tanks held a 40% share of the India Turbocharger Air Starter Market by air source type in 2025. High Pressure Air Tanks dominate the market as they are essential for storing the compressed air required for turbocharger air starters. Their critical role in maintaining operational efficiency in aviation applications solidifies their leading position. The quickest growth will come from Pneumatic Starter Systems, forecast to expand at a CAGR of 10.5% between 2026 and 2032. Pneumatic Starter Systems are growing quickly due to their widespread use in aviation for engine starts, reflecting the increasing demand for efficient and reliable starting solutions. This segment's growth is likely to continue as the aviation sector expands. Buyers should consider investing in Pneumatic Starter Systems to ensure they meet the demands of modern aviation technologies.
By Application Area – Aircraft Engines Dominated, Gas Turbines Expected to Grow Fastest
Aircraft Engines took a 52% share of application area in 2025, more than any other category. Aircraft Engines dominate the application area for turbocharger air starters, driven by the extensive fleet of military and commercial aircraft in India. The necessity for dependable starting systems in aviation underpins this segment's leading position. Gas Turbines are projected to grow fastest, at a CAGR of 10.5% during 2026–2032. Gas Turbines are experiencing the fastest growth, primarily due to their critical role in power generation as energy demand escalates. This shift suggests a growing need for versatile starting solutions that cater to both aviation and industrial sectors. Suppliers should consider expanding their product lines to include solutions tailored for Gas Turbines to capitalise on this emerging market.
By End User – Military OEMs Dominated, Aerospace Integrators Expected to Grow Fastest
The largest end user category in 2025 was Military OEMs, with a 43% share of total revenue. Military OEMs hold the largest share in the India Turbocharger Air Starter Market due to the substantial demand for reliable starting systems from defense manufacturers. With the Indian military operating over 2,000 aircraft, the need for these devices remains consistent and critical. Aerospace Integrators are set to record the highest CAGR in this split, 9.8% over 2026–2032. Aerospace Integrators are experiencing the fastest growth as they are crucial for integrating advanced systems in modern aircraft, driven by the increasing complexity of aerospace projects. This growth indicates a shift towards comprehensive solutions that cater to the evolving demands of the aviation sector. This trend suggests that suppliers must focus on building strong partnerships with Aerospace Integrators to effectively address the needs of the expanding aerospace market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Turbocharger Air Starter Market Outlook
- Market Size of India Turbocharger Air Starter Market, 2025
- Forecast of India Turbocharger Air Starter Market, 2032
- Historical Data and Forecast of India Turbocharger Air Starter Revenues & Volume for the Period 2022 - 2032F
- India Turbocharger Air Starter Market Trend Evolution
- India Turbocharger Air Starter Market Drivers and Challenges
- India Turbocharger Air Starter Price Trends
- India Turbocharger Air Starter Porter's Five Forces
- India Turbocharger Air Starter Industry Life Cycle
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Starter Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Axial Flow Starter for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Radial Air Starter for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Modular Starter Units for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Compact Starters for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Air Source Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By High Pressure Air Tanks for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By APU Integrated for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Pneumatic Starter Systems for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Lightweight Use for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Aircraft Engines for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Gas Turbines for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Emergency Startups for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By UAVs for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Military OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Turbine Builders for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Aviation Maintenance for the Period 2022 - 2032F
- Historical Data and Forecast of India Turbocharger Air Starter Market Revenues & Volume By Aerospace Integrators for the Period 2022 - 2032F
- India Turbocharger Air Starter Import Export Trade Statistics
- Market Opportunity Assessment By Starter Type
- Market Opportunity Assessment By Air Source Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- India Turbocharger Air Starter Top Companies Market Share
- India Turbocharger Air Starter Competitive Benchmarking By Technical and Operational Parameters
- India Turbocharger Air Starter Company Profiles
- India Turbocharger Air Starter Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Starter Type
- Axial Flow Starter
- Radial Air Starter
- Modular Starter Units
- Compact Starters
By Air Source Type
- High Pressure Air Tanks
- APU Integrated
- Pneumatic Starter Systems
- Lightweight Use
By Application Area
- Aircraft Engines
- Gas Turbines
- Emergency Startups
- UAVs
By End User
- Military OEMs
- Turbine Builders
- Aviation Maintenance
- Aerospace Integrators































