India Turboshaft Engine Market Size & Growth Rate
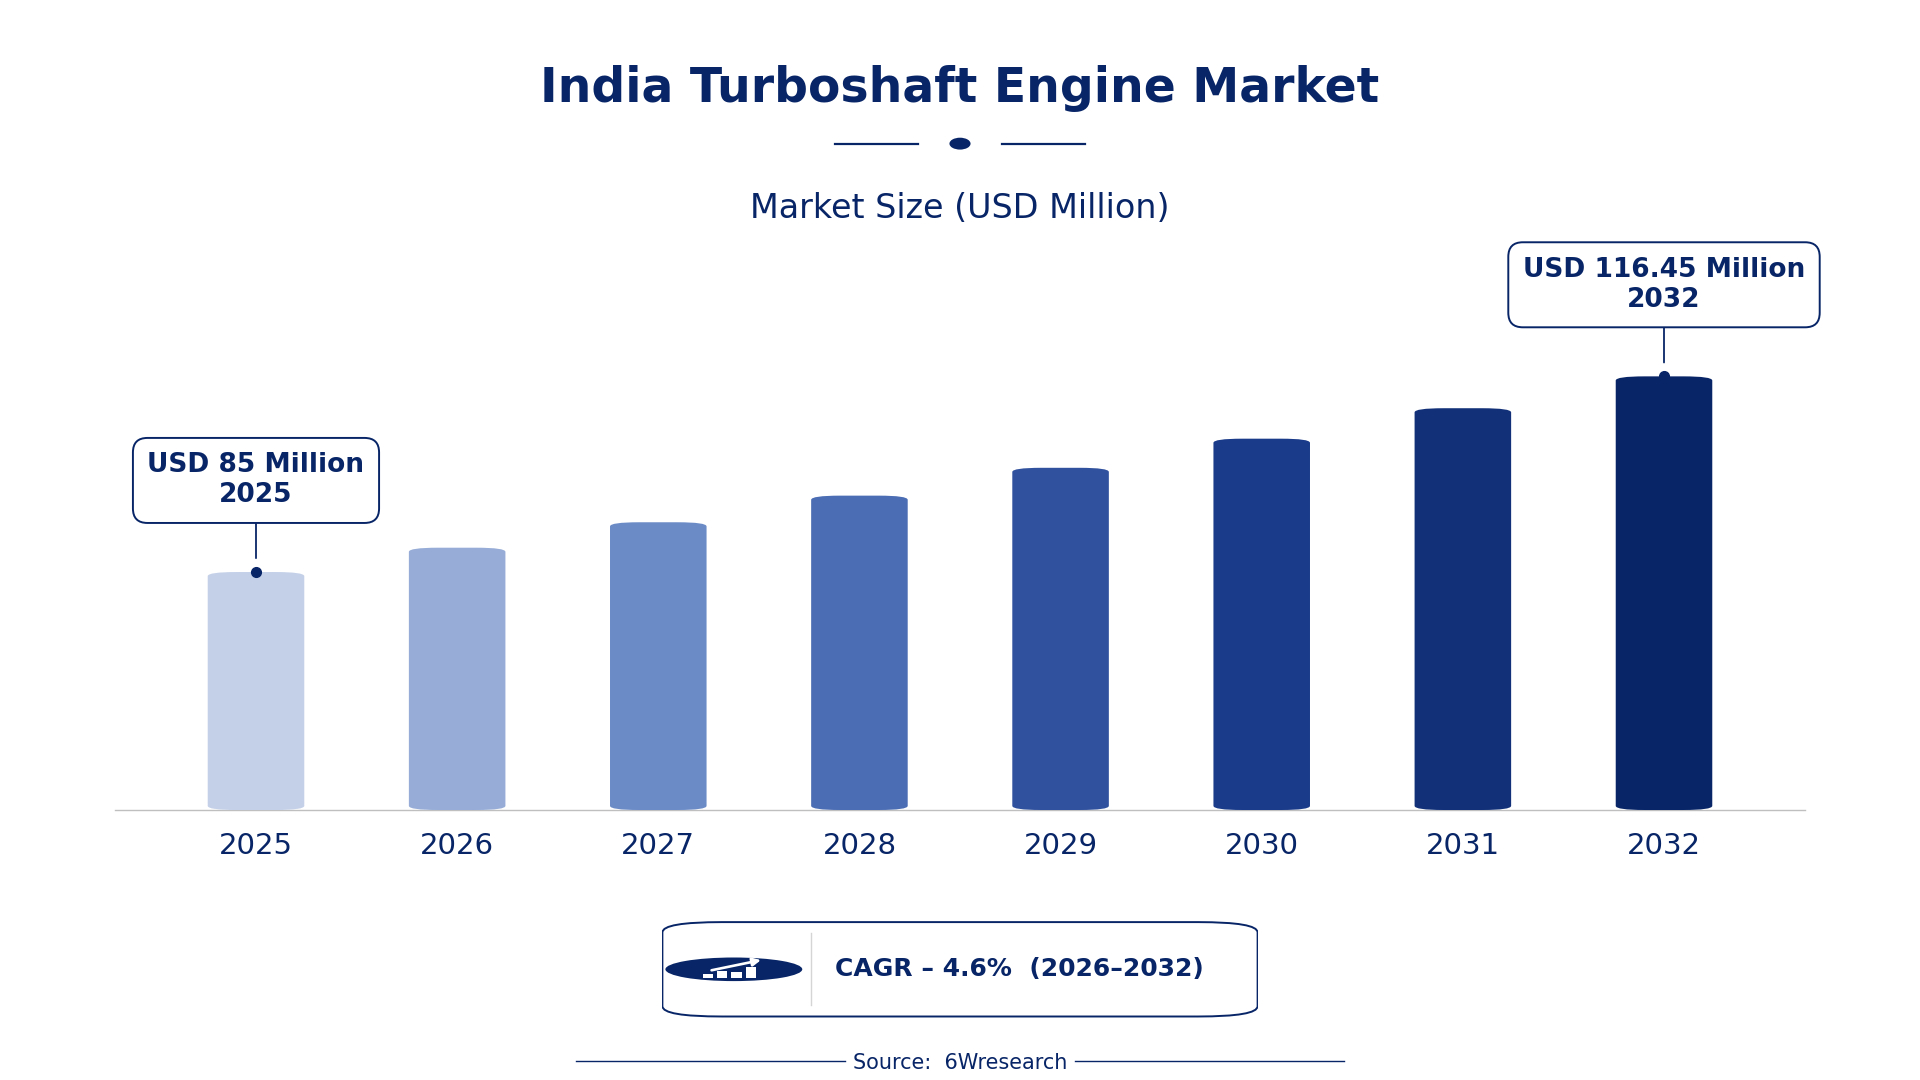
According to 6Wresearch internal database and industry insights, the India Turboshaft Engine Market was valued at USD 85.0 million in 2025 and is projected to reach USD 116.45 million by 2032, growing at a CAGR of approximately 4.6% during 2026–2032.
India Turboshaft Engine Market Highlights
| Report Metric | Details |
| Report Name | India Turboshaft Engine Market |
| Market Size 2025 | USD 85.0 million |
| Market Size 2032 | USD 116.45 million |
| Absolute Growth 2025–2032 | USD 31.45 million |
| CAGR 2026–2032 | 4.6% |
| Peak Annual Growth | 6.9% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Turboshaft Engine Type, 2025 | Helicopter Primary Engines (35% share) |
| Leading Engine Type, 2025 | >2 (42% share) |
| Leading HP Class, 2025 | Military/CSAR (47% share) |
| Leading Distribution Channel, 2025 | Engine OEMs (39% share) |
| Leading End User Industry, 2025 | Rotary-Wing Aircraft (41% share) |
| Fastest-Growing Turboshaft Engine Type | Light Turboshafts (5.6% CAGR) |
| Fastest-Growing Engine Type | APU Units (6.1% CAGR) |
| Fastest-Growing Distribution Channel | Aero Engine Suppliers (6.6% CAGR) |
| Fastest-Growing End User Industry | Civil & Helo Fleets (6.8% CAGR) |
| Growing Sector | Civil & Helo Fleets |
| Key End Users | Military, Civil Aviation, Helicopter Manufacturers |
India Turboshaft Engine Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
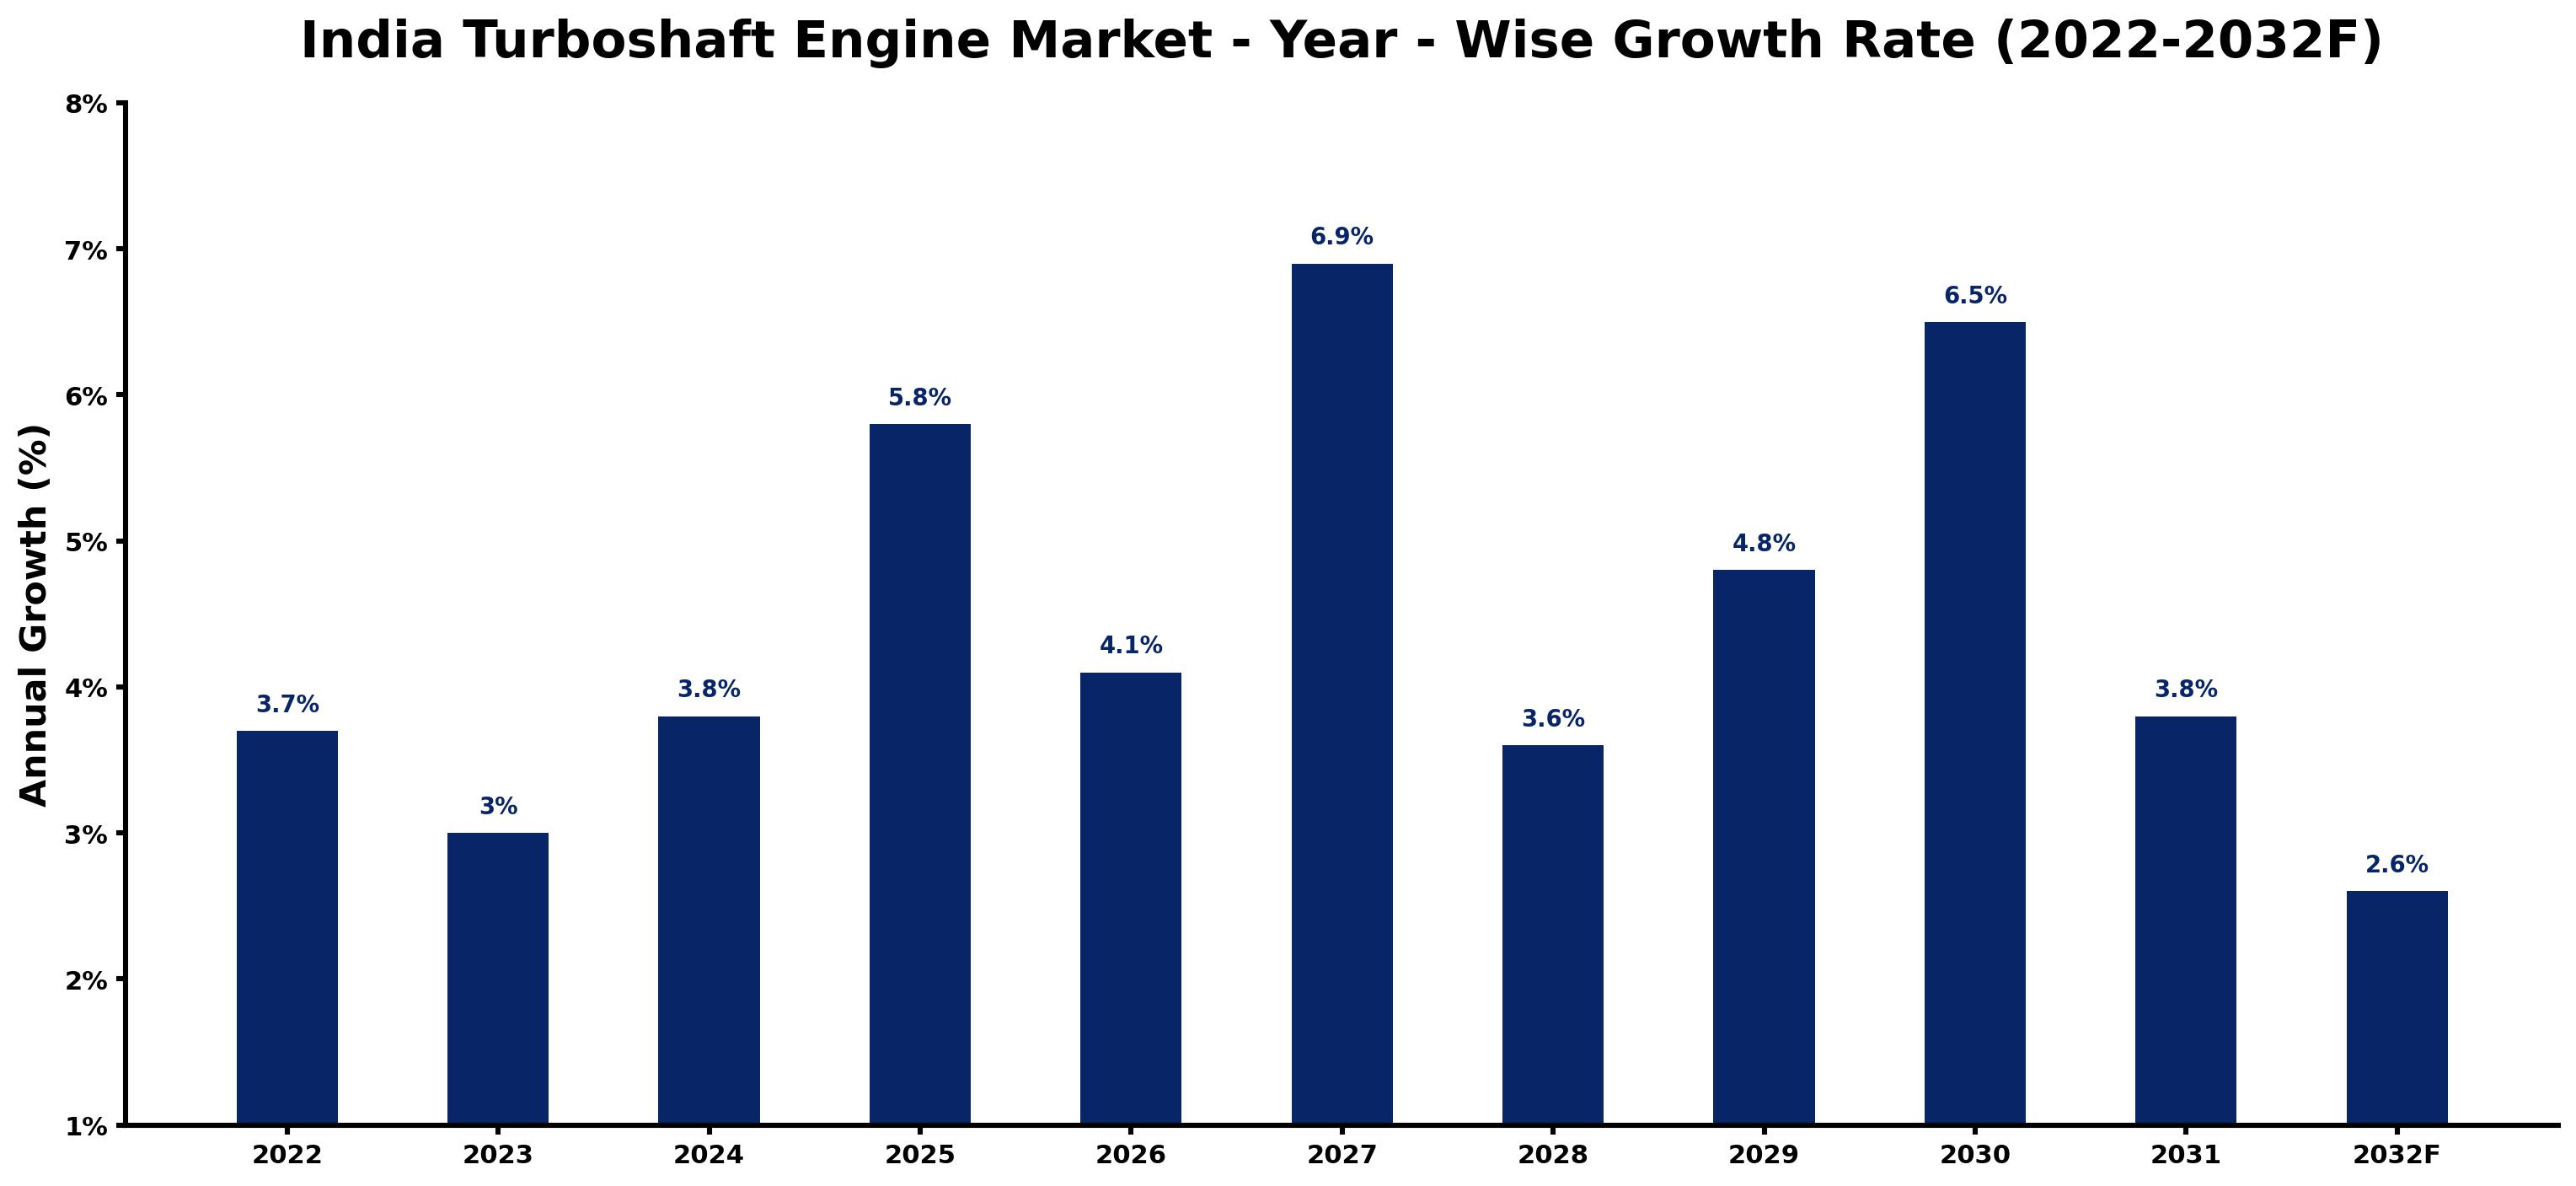
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.7 | The Indian armed forces operated over 600 helicopters requiring turboshaft engines. |
| 2023 | 3.0 | Growth slowed due to adjustments in defense procurement strategies and budget allocations. |
| 2024 | 3.8 | Increased demand for helicopter upgrades spurred growth in turboshaft engine procurement. |
| 2025 | 5.8 | The market peaked as the Indian Air Force focused on modernising its fleet with advanced engines. |
| 2026 | 4.1 | A slowdown occurred as the focus shifted to indigenous production capabilities and R&D. |
| 2027 | 6.9 | Growth accelerated with the Ministry of Defence's increased budget for defense procurement. |
| 2028 | 3.6 | Demand slowed as manufacturers adjusted to evolving military specifications and standards. |
| 2029 | 4.8 | A rise in civil aviation demand led to increased orders for turboshaft engines. |
| 2030 | 6.5 | Growth surged as civil aviation approaches 500 million passengers by 2030. |
| 2031 | 3.8 | The market experienced a slowdown as manufacturers faced challenges in meeting new standards. |
| 2032 | 2.6 | Demand growth slowed as the focus shifted towards sustainable and efficient engine technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Turboshaft Engine Market Synopsis
The Turboshaft Engine Market in India encompasses engines designed for helicopters and some fixed-wing aircraft, optimised for producing shaft power. These engines are manufactured through precision engineering and are vital for military and civil aviation operations. The market is expanding due to increasing orders from the Indian armed forces and civil aviation sectors, driven by initiatives like 'Make in India' and substantial government funding for local production. With over 600 helicopters in operation, the demand for turboshaft engines is projected to rise in the coming years.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased military spending and modernization of the armed forces. | Driver | High | Military/CSAR |
| Growing civil aviation market demands more efficient engines. | Driver | High | Civil/Multi-Role |
| Expansion of helicopter fleets in military operations. | Opportunity | High | Rotary-Wing Aircraft |
| Investment in indigenous manufacturing capabilities for turboshaft engines. | Opportunity | High | Engine OEMs |
| Challenges in meeting new aerospace standards and regulations. | Restraint | High | Helicopter Primary Engines |
| Dependence on imported components for engine manufacturing. | Restraint | Medium | Light Turboshafts |
| The high cost of R&D for developing indigenous engines. | Challenge | High | Auxiliary Power Units |
| Competition from established international manufacturers. | Challenge | Medium | Turboshaft Repower Kits |
Evaluation of Drivers in India Turboshaft Engine Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military budget allocations for modernization. | Military/CSAR | The Ministry of Defence allocated ₹1.5 trillion for defense procurement in 2023, boosting demand for turboshaft engines. |
| Growth in civil aviation passenger numbers. | Civil/Multi-Role | The Indian civil aviation market is expected to grow to 500 million passengers by 2030, increasing demand for helicopters. |
| Indigenous development of turboshaft engines. | Engine OEMs | The Defence Research and Development Organisation is developing indigenous turboshaft engines, which will support local production capabilities. |
| Expansion of military helicopter fleets. | Rotary-Wing Aircraft | The Indian Army's aviation wing is expanding its fleet, necessitating more turboshaft engines. |
| Focus on upgrading existing helicopter engines. | Turboshaft Repower Kits | The Indian Air Force is focusing on upgrading its fleet with modern turboshaft engines. |
Market growth for Turboshaft Engine in India is underpinned by increased military budget allocations, expanding civil aviation, and local development of engines. The civil aviation market is projected to grow significantly, necessitating more helicopters. Local manufacturers are developing indigenous turboshaft engines to meet growing demand. The Indian Army's aviation wing is expanding its fleet, requiring more engines for new helicopters.
Evaluation of Restraints in India Turboshaft Engine Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in meeting new aerospace standards and regulations. | Helicopter Primary Engines | The Bureau of Indian Standards has set specifications that manufacturers must comply with, increasing costs. |
| Dependence on imported components for engine manufacturing. | Light Turboshafts | The Indian government aims for a 20% reduction in defense equipment imports by 2025, complicating supply chains. |
| High costs associated with R&D for developing indigenous engines. | Auxiliary Power Units | The Defence Research and Development Organisation's budget for indigenous development is ₹1,000 crore, which may limit smaller firms. |
| Limited availability of skilled workforce for advanced manufacturing. | Turboshaft Repower Kits | The aerospace sector in India faces a talent shortage, affecting production timelines. |
| Competition from established international manufacturers. | Military/CSAR | Foreign companies dominate the market, making it challenging for local manufacturers to gain market share. |
India Turboshaft Engine Market Challenges
The India Turboshaft Engine Market faces a considerable supply challenge due to reliance on imported components, which delays production timelines for local manufacturers. This dependency often leads to longer lead times, costing producers up to 30% more in operational expenses. Rising raw material costs, influenced by global market fluctuations, inflate prices, impacting buyers who encounter higher procurement costs. Local suppliers find it difficult to compete with foreign firms that offer advanced technology at lower prices, forcing them to reduce margins and potentially compromise on quality, which affects the reliability of engines for end users such as the Indian armed forces.
Trends in the India Turboshaft Engine Market
Four trends stand out in the India Turboshaft Engine Market.
- Shift towards Indigenous Manufacturing: India is increasingly focusing on local production of turboshaft engines, emphasised by the 'Make in India' initiative. In 2023, the Ministry of Defence allocated ₹1.5 trillion for defense procurement, which supports local manufacturers.
- Growth in Civil Aviation Demand: The Indian civil aviation market is projected to grow to 500 million passengers by 2030, driving demand for turboshaft engines. This growth is prompting manufacturers to invest in more efficient engine technologies.
- Emphasis on Upgrading Existing Fleets: The Indian Air Force is prioritising the upgrade of its helicopter fleet with modern turboshaft engines. This trend is likely to increase engine orders, especially with a projected growth of 5.8% in 2025.
- Expansion of Military Helicopter Capabilities: The Indian Army is expanding its aviation capabilities, necessitating more turboshaft engines for new helicopters. This expansion is backed by a budget of ₹1.5 trillion for defense procurement in 2023.
Investment Opportunities in the India Turboshaft Engine Market
Below are the investment opportunities with the strongest case in the India Turboshaft Engine Market.
- Military Aviation Expansion: The Indian Army's aviation wing is growing its fleet, creating demand for new turboshaft engines. With a budget of ₹1.5 trillion for defence procurement, local manufacturers can collaborate with the army for supply.
- Investment in Indigenous Production: Local manufacturers have the opportunity to invest in developing indigenous turboshaft engines to meet the 50% local content requirement. The Defence Procurement Procedure 2020 encourages local production, providing a clear entry route.
- Civil Aviation Growth: The growth of the civil aviation market to 500 million passengers by 2030 presents opportunities for turboshaft engine suppliers. Collaborating with regional airlines can facilitate market entry and expansion.
- Upgrading Existing Helicopter Engines: The focus on upgrading existing helicopter fleets offers opportunities for suppliers of turboshaft repower kits. Establishing partnerships with maintenance overhaul shops can strengthen market presence.
Government Initiatives in the India Turboshaft Engine Market
The 'Aatmanirbhar Bharat' initiative, launched in 2020, promotes self-reliance in defence manufacturing, including turboshaft engines. This initiative encourages local production and reduces dependency on imports, enabling manufacturers to improve their capabilities. The Defence Procurement Procedure 2020 aims to increase indigenous production of military equipment, targeting a 50% local content requirement, which directly impacts turboshaft engine production. Additionally, the National Policy on Aerospace and Defence 2021 focuses on boosting domestic manufacturing capabilities in aerospace technologies, including turboshaft engines, by setting clear guidelines and support mechanisms.
The Defence Research and Development Organisation oversees the development and approval of indigenous turboshaft engines. This agency funds various projects aimed at supporting local manufacturing capabilities, ensuring compliance with national standards, and promoting innovation in aerospace technologies. The Directorate General of Civil Aviation regulates aircraft engine standards, ensuring that all engines meet safety and performance requirements.
Future Insight of the India Turboshaft Engine Market
By 2032, buyers and suppliers in the India Turboshaft Engine Market can expect substantial shifts driven by local development initiatives and government policies. The Defence Research and Development Organisation's focus on indigenous turboshaft engines will strengthen supply chain resilience. The 'Make in India' initiative aims to improve manufacturing capabilities, reducing reliance on imports. As the Indian Air Force upgrades its fleet and civil aviation demand increases, the emphasis on reliable turboshaft engines will drive innovation and competitive pricing among local manufacturers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Turboshaft Engine Type – Helicopter Primary Engines Dominated, Light Turboshafts Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, in 2025, Helicopter Primary Engines led the turboshaft engine type split with a 35% share. Helicopter Primary Engines hold the largest market share due to their essential role in powering over 600 helicopters within the Indian armed forces. Their importance in military operations guarantees a steady demand for these engines across various applications. Light Turboshafts are set to record the highest CAGR in this split, 5.6% over 2026–2032. Light Turboshafts are witnessing rapid growth as they are increasingly adopted in smaller helicopters and UAVs, particularly with the Indian Army's focus on expanding its aviation capabilities. This trend suggests that Helicopter Primary Engines will maintain their lead as they remain crucial for larger operations. Suppliers should enhance their offerings for Light Turboshafts to meet the rising demand in both military and civil aviation sectors.
By Engine Type – >2 Dominated, APU Units Expected to Grow Fastest
The largest engine type category in 2025 was >2, with a 42% share of total revenue. >2 engines dominate the market as they are crucial for larger helicopters requiring substantial power, especially in military applications. Their significant presence in the Indian Air Force's Mi-17 fleet underscores their importance in this segment. Over 2026–2032, APU Units are expected to post the fastest growth, at a CAGR of 6.1%. APU Units are rapidly growing as they provide essential auxiliary power for various aircraft, particularly with the expansion of the civil aviation market. The increasing reliance on reliable auxiliary systems will further propel this segment's growth. Manufacturers should focus on developing APU Units to satisfy the rising demand for auxiliary power solutions in military and civil aviation.
By HP Class – Military/CSAR Dominated and Is Expected to Record the Fastest Growth
With a 47% revenue share in 2025, Military/CSAR was the largest hp class category. Military/CSAR engines lead the market due to their critical role in military operations and search and rescue missions, reflecting the operational needs of the Indian armed forces. Their widespread application ensures a strong market presence and consistent demand. Its lead should widen, with a projected CAGR of 6.8% during 2026–2032, the highest in this split. Military/CSAR engines are also the fastest-growing segment as the Indian armed forces continue to upgrade their capabilities with advanced turboshaft engines. This dual role of leadership and growth indicates a robust demand trajectory for these engines. Suppliers must align their strategies to support the increasing demand for Military/CSAR engines, especially as defence procurement budgets expand.
By Distribution Channel – Engine OEMs Dominated, Aero Engine Suppliers Expected to Grow Fastest
Engine OEMs held a 39% share of the India Turboshaft Engine Market by distribution channel in 2025. Engine OEMs are the market leaders as they are the primary manufacturers of turboshaft engines, supplying directly to military and civil aviation sectors. Their established relationships with major helicopter manufacturers in India reinforce their dominant position in the market. Aero Engine Suppliers are projected to grow fastest, at a CAGR of 6.6% during 2026–2032. Aero Engine Suppliers are experiencing rapid growth as they cater to various aircraft manufacturers, driven by the increasing production of helicopters and UAVs. This segment's expansion reflects the broader growth in the aerospace industry and the rising demand for turboshaft engines. Suppliers should strengthen partnerships with Aero Engine Suppliers to leverage expanding market opportunities in the aerospace sector.
By End User Industry – Rotary-Wing Aircraft Dominated, Civil & Helo Fleets Expected to Grow Fastest
Rotary-Wing Aircraft took a 41% share of end user industry in 2025, more than any other category. Rotary-Wing Aircraft represent the largest share as they are the primary application for turboshaft engines, particularly in military and civil aviation. The significant operational requirements of helicopters ensure a steady demand for this segment within the market. Civil & Helo Fleets are set to record the highest CAGR in this split, 6.8% over 2026–2032. Civil & Helo Fleets are the fastest-growing segment, driven by the anticipated growth of the Indian civil aviation market, which is expected to reach 500 million passengers by 2030. This surge in passenger traffic is prompting an increase in helicopter usage and demand for associated engines. Suppliers should focus on the Civil & Helo Fleets segment to capture the growing opportunities presented by the expanding civil aviation market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Turboshaft Engine Market Outlook
- Market Size of India Turboshaft Engine Market, 2025
- Forecast of India Turboshaft Engine Market, 2032
- Historical Data and Forecast of India Turboshaft Engine Revenues & Volume for the Period 2022 - 2032F
- India Turboshaft Engine Market Trend Evolution
- India Turboshaft Engine Market Drivers and Challenges
- India Turboshaft Engine Price Trends
- India Turboshaft Engine Porter's Five Forces
- India Turboshaft Engine Industry Life Cycle
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Turboshaft Engine Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Helicopter Primary Engines for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Light Turboshafts for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Auxiliary Power Units for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Turboshaft Repower Kits for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Engine Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By >2,500 HP for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By <1,500 HP for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By APU Units for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Upgrade Engines for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By HP Class for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Military/CSAR for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Civil/Multi-Role for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By <500 HP for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Custom Horsepower for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Engine OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Aero Engine Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Aircraft MRO Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Maintenance Overhaul Shops for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Rotary-Wing Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Civil & Helo Fleets for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Fixed-Wing Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of India Turboshaft Engine Market Revenues & Volume By Special Ops Helos for the Period 2022 - 2032F
- India Turboshaft Engine Import Export Trade Statistics
- Market Opportunity Assessment By Turboshaft Engine Type
- Market Opportunity Assessment By Engine Type
- Market Opportunity Assessment By HP Class
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- India Turboshaft Engine Top Companies Market Share
- India Turboshaft Engine Competitive Benchmarking By Technical and Operational Parameters
- India Turboshaft Engine Company Profiles
- India Turboshaft Engine Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Turboshaft Engine Type
- Helicopter Primary Engines
- Light Turboshafts
- Auxiliary Power Units
- Turboshaft Repower Kits
By Engine Type
- >2
- 500 HP
- <1
- APU Units
- Upgrade Engines
By HP Class
- Military/CSAR
- Civil/Multi-Role
- <500 HP
- Custom Horsepower
By Distribution Channel
- Engine OEMs
- Aero Engine Suppliers
- Aircraft MRO Suppliers
- Maintenance Overhaul Shops
By End User Industry
- Rotary-Wing Aircraft
- Civil & Helo Fleets
- Fixed-Wing Aircraft
- Special Ops Helos































