Japan Additive Electronics Manufacturing Market Size & Growth Rate
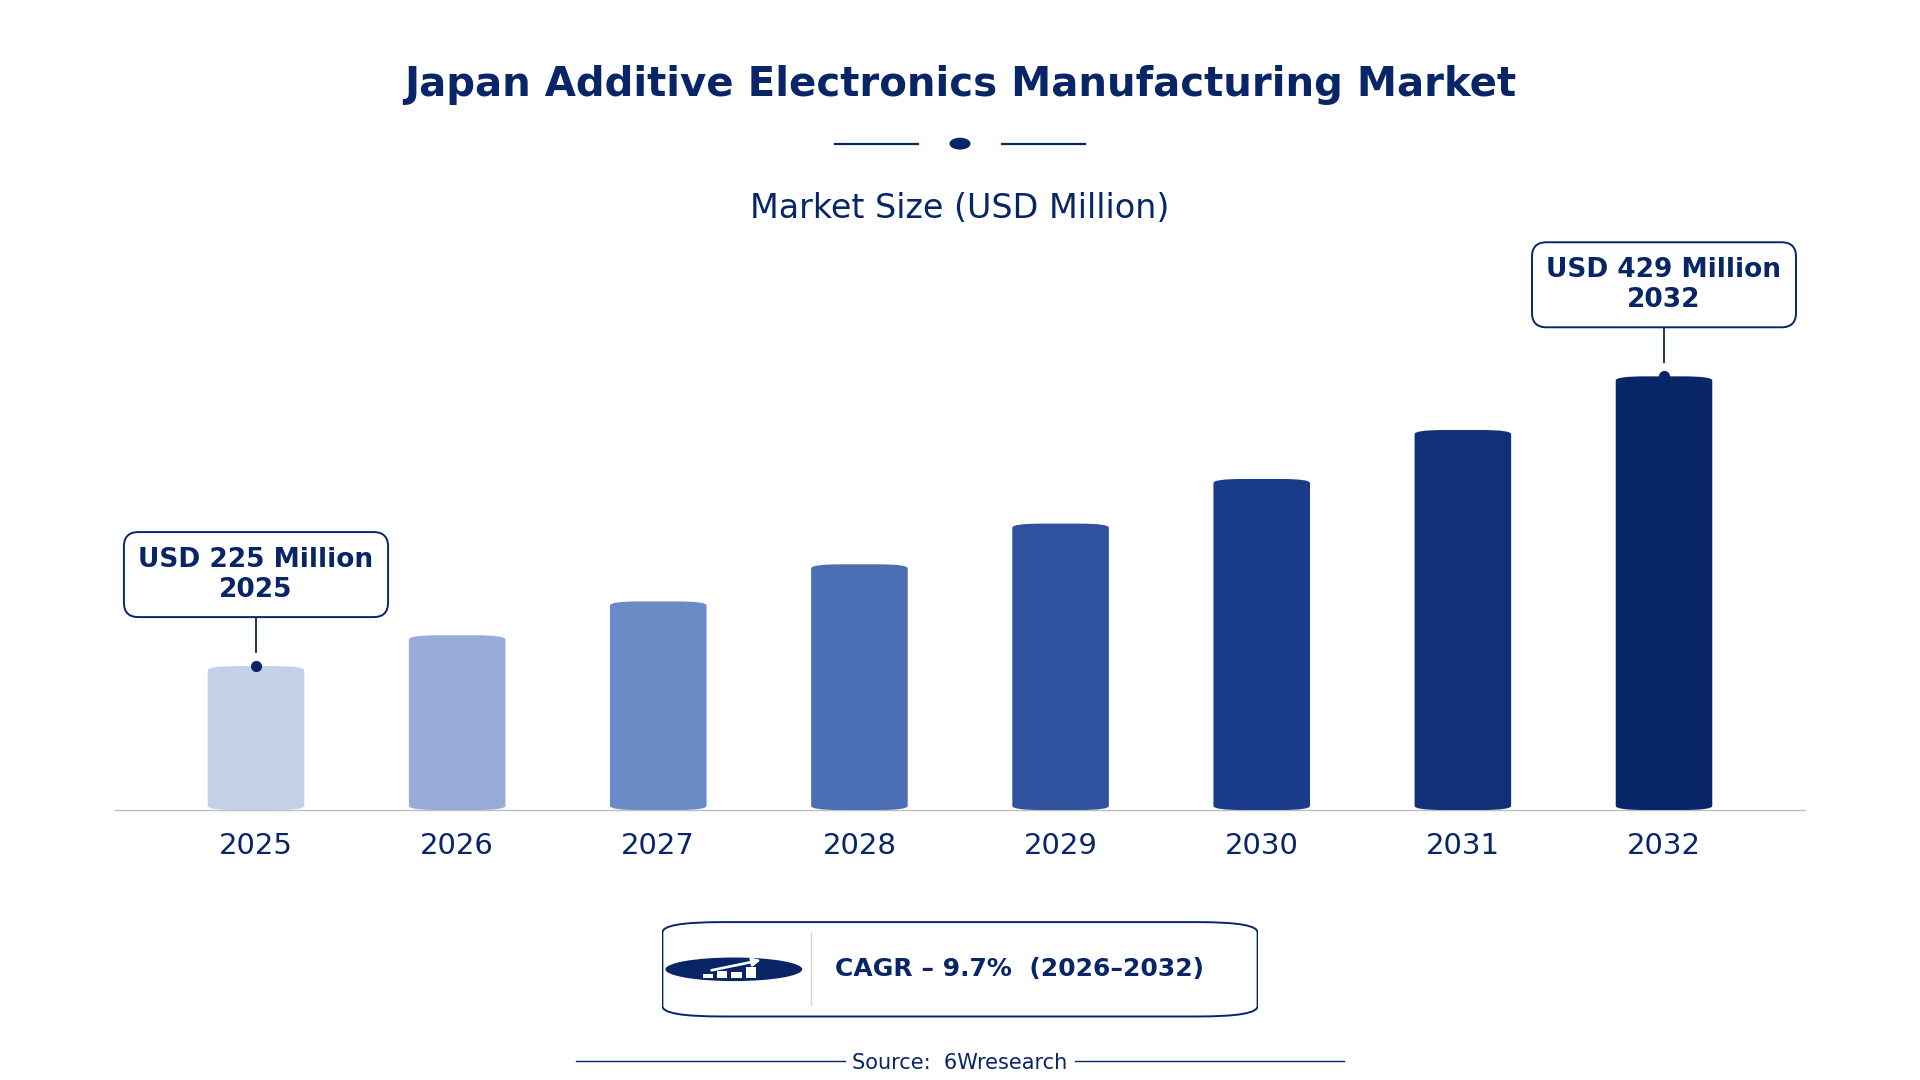
According to 6Wresearch internal database and industry insights, the Japan Additive Electronics Manufacturing Market was valued at USD 225 Million in 2025 and is projected to reach USD 429 Million by 2032, growing at a CAGR of approximately 9.7% during 2026–2032.
Japan Additive Electronics Manufacturing Market Highlights
| Report Metric | Details |
| Report Name | Japan Additive Electronics Manufacturing Market (2026-2032) |
| Market Size 2025 | USD 225 Million |
| Market Size 2032 | USD 429 Million |
| Absolute Growth 2025–2032 | USD 204 Million |
| CAGR 2026–2032 | 9.7% |
| Peak Annual Growth | 10.8% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Inkjet Printing for PCBs (49% share) |
| Leading Distribution Channel, 2025 | Direct Sales (35% share) |
| Leading End User, 2025 | Consumer Electronics (48% share) |
| Fastest-Growing Product Type | 3D Printed Sensors (14.6% CAGR) |
| Fastest-Growing Distribution Channel | OEM Partnerships (12.4% CAGR) |
| Fastest-Growing End User | Telecommunication (12.7% CAGR) |
| Growing Sector | Telecommunication |
| Key End Users | Consumer Electronics, Automotive Sector, Telecommunication, Wearable Devices |
Japan Additive Electronics Manufacturing Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
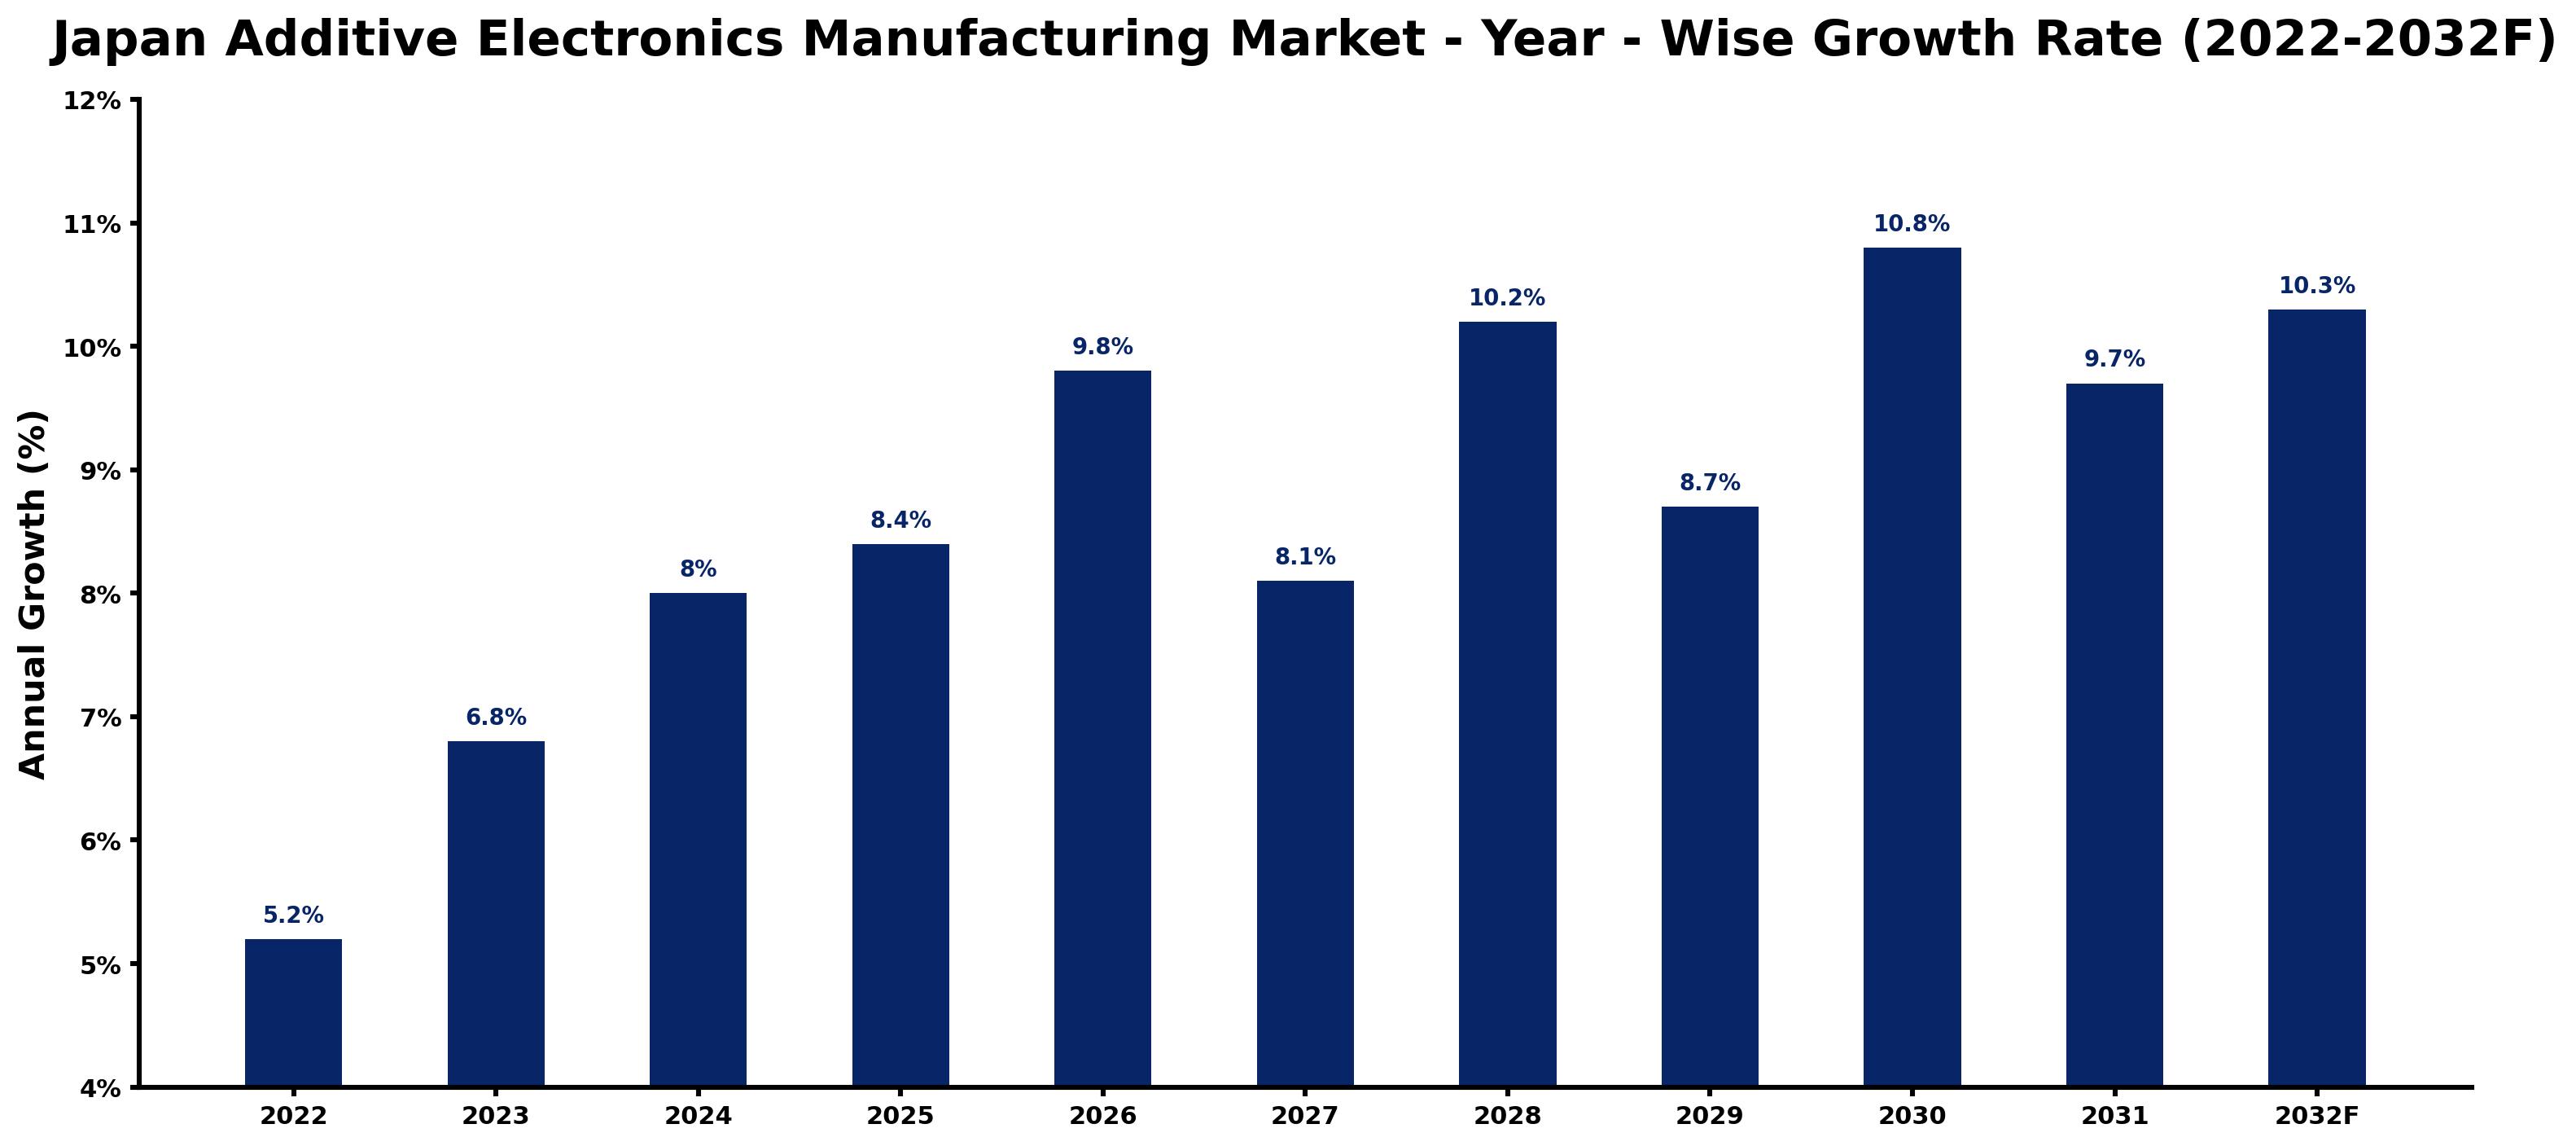
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.2 | The market maintained steady growth due to strong domestic demand for consumer electronics. |
| 2023 | 6.8 | Demand increased as manufacturers adopted advanced techniques like 3D printing in production. |
| 2024 | 8.0 | Growth accelerated with rising investments in automotive electronics and smart devices. |
| 2025 | 8.4 | The market peaked as consumer electronics sales surged, reaching 10 trillion JPY. |
| 2026 | 9.8 | Growth is expected to continue as 3D printing adoption in electronics expands. |
| 2027 | 8.1 | The market will see a slowdown as growth rates normalise after the previous peak. |
| 2028 | 10.2 | Demand is projected to rebound with increased focus on advanced manufacturing technologies. |
| 2029 | 8.7 | Growth will slow again as the market adjusts to the previous year's surge. |
| 2030 | 10.8 | The market is expected to peak again as advancements in EV technology spur electronics demand. |
| 2031 | 9.7 | Growth is projected to decelerate slightly as the market stabilises after rapid expansions. |
| 2032 | 10.3 | The market is expected to grow steadily as new technologies gain traction. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Additive Electronics Manufacturing Market Synopsis
Additive Electronics Manufacturing involves advanced techniques for creating electronic components through processes like printing. The Japan Additive Electronics Manufacturing Market is driven by strong domestic demand from the consumer electronics sector, valued at approximately 10 trillion JPY, and a growing automotive industry producing over 8 million vehicles annually. The adoption of advanced manufacturing technologies and rising demand from sectors like telecommunication further fuel growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing adoption of 3D printing in electronics manufacturing | Driver | High | 3D Printed Sensors |
| Rising demand for automotive electronics due to EV advancements | Driver | High | Automotive Sector |
| Growing consumer electronics market in Japan | Opportunity | High | Consumer Electronics |
| Expansion of telecommunication infrastructure | Opportunity | Medium | Telecommunication |
| Supply chain vulnerabilities affecting material availability | Restraint | High | Aerosol Jet Printing |
| High costs of advanced manufacturing technologies | Restraint | Medium | Inkjet Printing for PCBs |
| Limited skilled workforce for advanced manufacturing processes | Challenge | High | 3D Printed Sensors |
| Regulatory compliance costs for hazardous materials | Challenge | Medium | Antenna Printing |
Evaluation of Drivers in Japan Additive Electronics Manufacturing Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Adoption of 3D printing technologies | 3D Printed Sensors | This technology enhances production efficiency, leading to increased purchases by manufacturers, with a projected adoption rate increase by 2025. |
| Growth in the automotive sector | Automotive Sector | The production of over 8 million vehicles in 2022 has heightened demand for advanced electronics, driving investment in manufacturing. |
| Strong consumer electronics market | Consumer Electronics | This sector drives substantial purchases of additive manufacturing components, supported by a market valued at approximately 10 trillion JPY. |
| Telecommunication infrastructure expansion | Telecommunication | The ongoing development of communication networks increases the need for advanced electronic components, particularly in new device designs. |
| Rising demand for wearable devices | Wearable Devices | The wearable devices market is projected to reach 1 trillion JPY by 2025, encouraging manufacturers to invest in additive techniques. |
What keeps demand rising is the adoption of 3D printing technologies in the Tokyo region, which improves production efficiency and design flexibility. The automotive sector, producing over 8 million vehicles in 2022, boosts demand for advanced electronics. Japan's consumer electronics market, valued at approximately 10 trillion JPY, continues to drive purchases of additive manufactured components. The expansion of telecommunication infrastructure increases the need for sophisticated electronic devices. The wearable devices market, projected to reach 1 trillion JPY by 2025, fuels this interest as manufacturers seek new solutions.
Evaluation of Restraints in Japan Additive Electronics Manufacturing Market
Several factors work against faster growth; the main ones are summarised below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Compliance with ISO 9001 standards raises production costs for manufacturers | Inkjet Printing for PCBs | This leads to an average increase of 15% in operational expenses. |
| Regulatory requirements in Japan are stringent | Aerosol Jet Printing | This causes delays in product launches for producers, extending timelines by up to six months. |
| Skills shortages in advanced manufacturing techniques hinder the ability of clinics to adopt new technologies | 3D Printed Sensors | This results in a 20% decrease in efficiency. |
| Rapid technological advancements leave many suppliers struggling to keep pace | Antenna Printing | This forces them to invest heavily in R&D, consuming up to 30% of their annual budget. |
| High costs of specialized materials limit production capabilities | Telecommunication | This restricts the ability to scale operations effectively. |
Japan Additive Electronics Manufacturing Market Challenges
High production costs due to strict JIS standards burden manufacturers, raising operational expenses by approximately 15%. Regulatory challenges in Japan can delay product launches for producers by up to six months, limiting market responsiveness. A shortage of skilled workers in additive manufacturing techniques restricts clinics from adopting advanced technologies, resulting in a 20% decline in productivity. Rapid technological advancements compel suppliers to allocate up to 30% of their budgets to R&D, which can postpone product availability for buyers.
Trends in the Japan Additive Electronics Manufacturing Market
Four trends stand out in the Japan Additive Electronics Manufacturing Market.
- Shift from Traditional to Additive Manufacturing Techniques: Since 2022, Japan has experienced a shift towards additive manufacturing techniques, particularly in the Tokyo region, where 3D printing adoption is on the rise. This trend is reflected in the projected growth of the 3D printing market in electronics, expected to reach substantial levels by 2025.
- Transition from Conventional to Smart Manufacturing: In 2023, the Tokyo Metropolitan Government initiated programmes to promote smart manufacturing technologies, encouraging factories to embrace automation and data analytics. This transition is anticipated to improve production efficiency and competitiveness in the sector.
- Emergence of Telecommunication as a Key End User: With the telecommunication sector projected to grow at a CAGR of 12.7% by 2032, manufacturers are concentrating on developing advanced electronic components tailored for communication devices. This trend is reshaping product offerings in the market.
- Prioritisation of Sustainability in Manufacturing: The GX Promotion Act, enacted in 2023, has prompted manufacturers to adopt sustainable practices in production. This shift is important as the industry aims to meet environmental standards and consumer expectations.
Investment Opportunities in the Japan Additive Electronics Manufacturing Market
The openings below show where demand in the Japan Additive Electronics Manufacturing Market is visible and how suppliers can enter.
- Timing for Investment in 3D Printed Sensors: With the 3D printing adoption rate expected to increase by 2025, manufacturers should invest in 3D printed sensors. The automotive sector is a key buyer group, and partnerships with local firms can facilitate market entry.
- Growing Demand in the Telecommunication Sector: As the telecommunication market expands, there is an opportunity to supply advanced electronic components. Collaborating with OEMs in the Tokyo region can enhance market presence and meet increasing demand.
- Focus on Wearable Devices: With the wearable devices market projected to reach 1 trillion JPY by 2025, manufacturers can invest in miniaturization technologies. Partnering with consumer electronics firms will be essential for successful market penetration.
- Investment in Smart Manufacturing Technologies: The current push for smart manufacturing creates opportunities for suppliers of automation technologies. Engaging with initiatives by the Tokyo Metropolitan Government can provide access to funding and support.
Government Initiatives in the Japan Additive Electronics Manufacturing Market
The Act on the Rational Use of Energy, established in 1979, mandates large energy users to improve energy efficiency and report usage. This law has encouraged manufacturers to adopt energy-efficient practices, impacting production costs and sustainability efforts. Additionally, the Industrial Safety and Health Act, enacted in 1972, sets employer duties for hazardous substances, ensuring safer working environments in manufacturing facilities.
The Ministry of Economy, Trade and Industry (METI) funds projects aimed at advancing manufacturing technologies. Initiatives under the Economic Security Promotion Act, enacted in 2022, support supply-chain resilience for critical products, enhancing the capabilities of manufacturers in the sector.
Future Insight of the Japan Additive Electronics Manufacturing Market
The policy-driven shift towards smart manufacturing will reshape the market, encouraging suppliers to adopt advanced technologies like 3D printing. By 2032, the automotive electronics sector is expected to grow by 25% as EV technology advances. Enhanced collaboration between manufacturers and the Ministry of Economy, Trade and Industry will facilitate the adoption of new standards, elevating production quality. As Japan's wearable devices market approaches 1 trillion JPY by 2025, buyers will benefit from a broader array of tailored products.
Market Segmentation Analysis
Japan Additive Electronics Manufacturing Market report covers a detailed analysis of the following market segments:
By Product Type – Inkjet Printing for PCBs Lead, 3D Printed Sensors Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, Inkjet Printing for PCBs took 49% of product type revenue in 2025, more than any other category. Inkjet Printing for PCBs holds the largest share as it is the primary method for fabricating printed circuit boards, essential for numerous electronic devices. This technique is particularly prevalent in the Tokyo region, a key area for electronics manufacturing. 3D Printed Sensors are set to record the highest CAGR in this split, 14.6% over 2026–2032. The rapid increase in 3D Printed Sensors is propelled by their growing application across various electronic devices, indicating a shift towards more adaptable manufacturing methods. The anticipated rise in the adoption rate of 3D printing in electronics by 2025 will further boost this segment's expansion. Suppliers need to focus on advancements in 3D printing technologies to meet the rising demand for flexible sensor solutions.
By Distribution Channel – Direct Sales Leads, OEM Partnerships Expected to Grow Fastest
Direct Sales held 35% of the Japan Additive Electronics Manufacturing Market by distribution channel in 2025. Direct Sales captures the largest share as it functions as the primary channel for manufacturers to connect directly with customers, providing tailored solutions and support. This method proves particularly effective in Japan's competitive additive electronics market. OEM Partnerships are projected to grow fastest, at a CAGR of 12.4% during 2026–2032. OEM Partnerships are witnessing the fastest growth due to their critical role in incorporating additive manufacturing into larger systems, enhancing overall product capabilities. The collaboration between manufacturers and OEMs is vital for promoting the adoption of advanced manufacturing technologies. Suppliers should enhance their OEM partnerships to leverage the increasing integration of additive manufacturing in diverse applications.
By End User – Consumer Electronics Leads, Telecommunication Expected to Grow Fastest
In 2025, Consumer Electronics led the end user split with a 48% share. Consumer Electronics constitutes the largest share as it is the primary end user of additive manufactured components, reflecting Japan's robust domestic demand for electronic devices. The sector's growth is bolstered by the country's substantial consumer electronics market, valued at approximately 10 trillion JPY. The quickest growth will come from Telecommunication, forecast to expand at a CAGR of 12.7% between 2026 and 2032. Telecommunication is the fastest-growing end user due to its essential role in the production of communication devices, which increasingly depend on advanced manufacturing techniques. Continuous advancements in telecommunication technology are expected to drive further demand for additive manufacturing solutions. Buyers in the telecommunication sector should investigate additive manufacturing options to improve the efficiency and performance of their communication devices.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Additive Electronics Manufacturing Market Outlook
- Market Size of Japan Additive Electronics Manufacturing Market, 2025
- Forecast of Japan Additive Electronics Manufacturing Market, 2032
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Revenues & Volume for the Period 2022-2032F
- Japan Additive Electronics Manufacturing Market Trend Evolution
- Japan Additive Electronics Manufacturing Market Drivers and Challenges
- Japan Additive Electronics Manufacturing Price Trends
- Japan Additive Electronics Manufacturing Porter's Five Forces
- Japan Additive Electronics Manufacturing Industry Life Cycle
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Product Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Inkjet Printing for PCBs for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Aerosol Jet Printing for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By 3D Printed Sensors for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Antenna Printing for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Direct Sales for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Online Platforms for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Industrial Suppliers for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By OEM Partnerships for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Consumer Electronics for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Wearable Devices for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Automotive Sector for the Period 2022-2032F
- Historical Data and Forecast of Japan Additive Electronics Manufacturing Market Revenues & Volume By Telecommunication for the Period 2022-2032F
- Japan Additive Electronics Manufacturing Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Japan Additive Electronics Manufacturing Top Companies Market Share
- Japan Additive Electronics Manufacturing Competitive Benchmarking By Technical and Operational Parameters
- Japan Additive Electronics Manufacturing Company Profiles
- Japan Additive Electronics Manufacturing Key Strategic Recommendations
Market Covered
Coverage by segment is as follows.
By Product Type
- Inkjet Printing for PCBs
- Aerosol Jet Printing
- 3D Printed Sensors
- Antenna Printing
By Distribution Channel
- Direct Sales
- Online Platforms
- Industrial Suppliers
- OEM Partnerships
By End User
- Consumer Electronics
- Wearable Devices
- Automotive Sector
- Telecommunication































