Japan Advanced Materials for Aerospace Market Size & Growth Rate
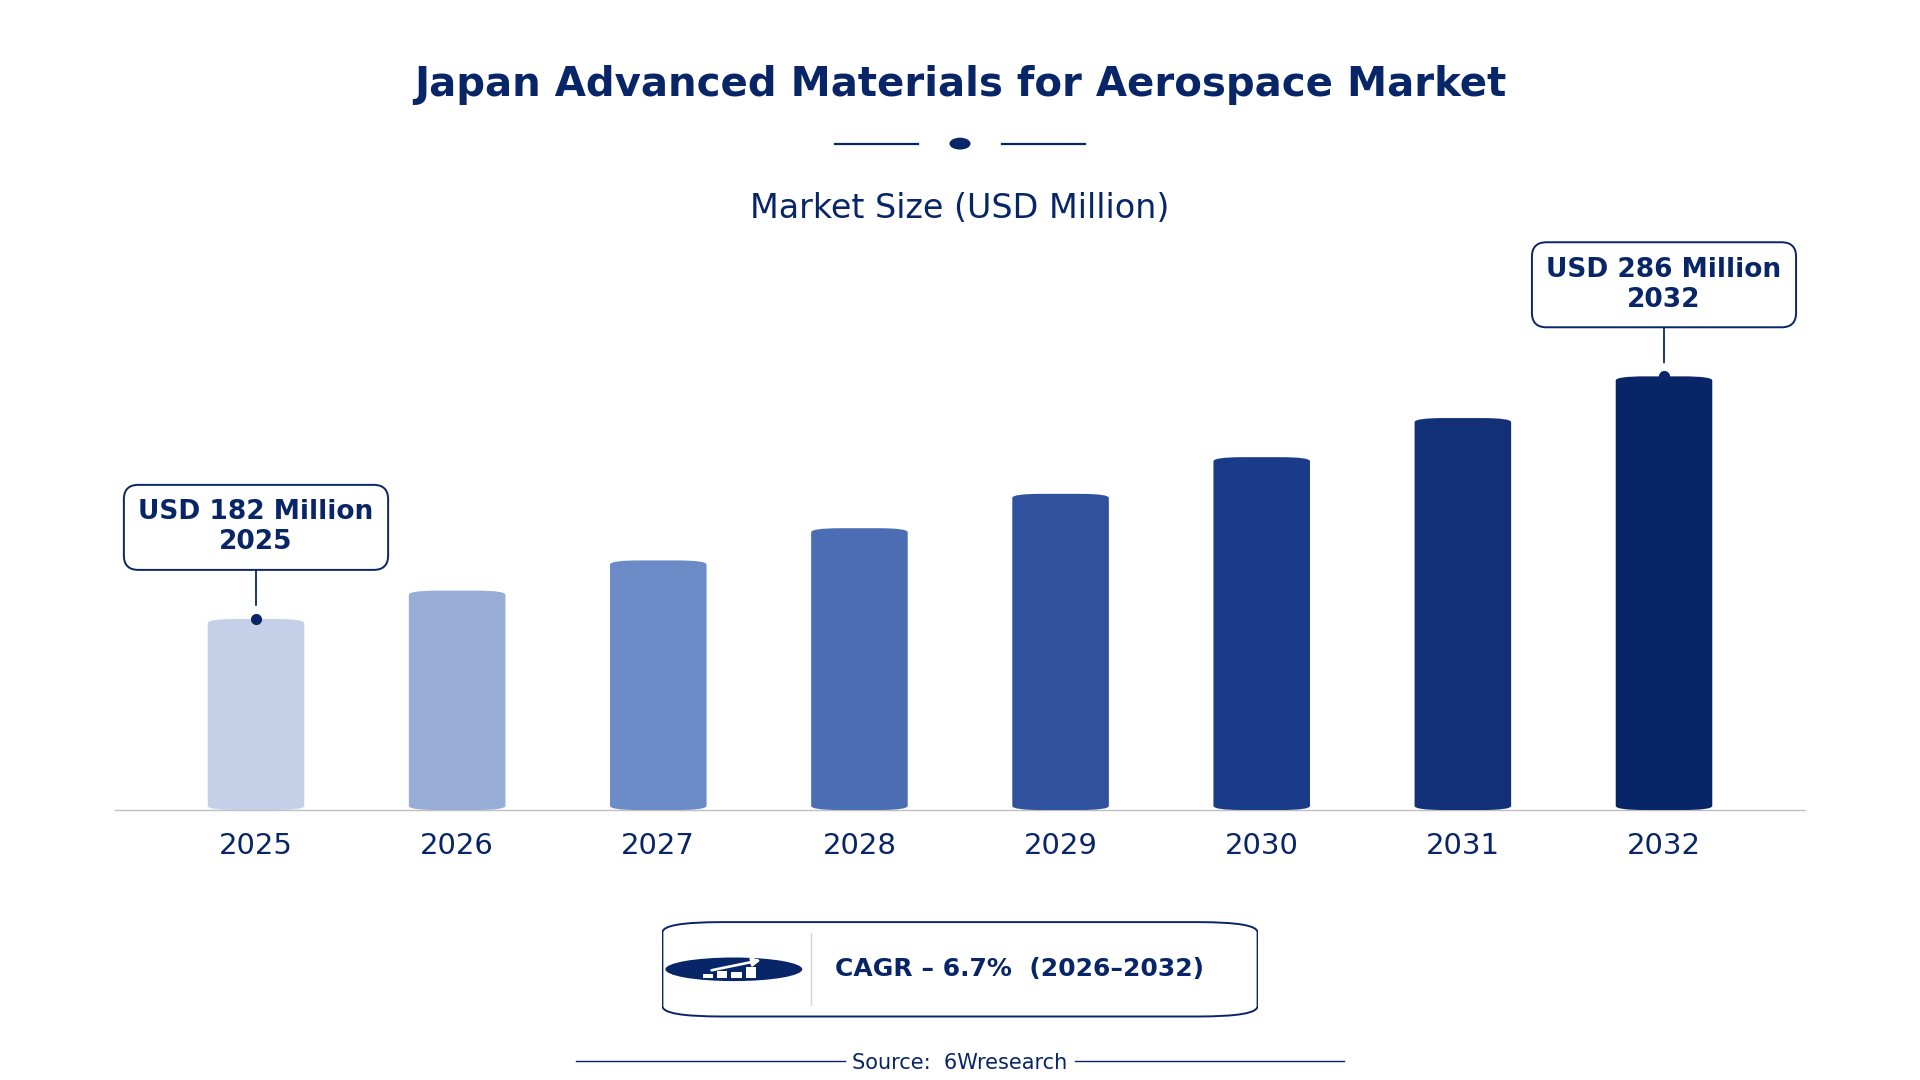
According to 6Wresearch internal database and industry insights, the Japan Advanced Materials for Aerospace Market was valued at USD 182 Million in 2025 and is projected to reach USD 286 Million by 2032, growing at a CAGR of approximately 6.7% during 2026–2032.
Japan Advanced Materials for Aerospace Market Highlights
| Report Metric | Details |
| Report Name | Japan Advanced Materials for Aerospace Market (2026-2032) |
| Market Size 2025 | USD 182 Million |
| Market Size 2032 | USD 286 Million |
| Absolute Growth 2025–2032 | USD 104 Million |
| CAGR 2026–2032 | 6.7% |
| Peak Annual Growth | 7.8% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Advanced Materials for Aerospace Market, 2025 | Titanium Alloys (42% share) |
| Leading Material Type, 2025 | Lightweight Metal (44% share) |
| Leading Form Type, 2025 | Sheet & Plates (41% share) |
| Leading Application Area, 2025 | Aircraft Structures (37% share) |
| Leading End User, 2025 | Aerospace OEMs (51% share) |
| Fastest-Growing Advanced Materials for Aerospace Market | Ceramic Matrix Composites (9.9% CAGR) |
| Fastest-Growing Material Type | High-Temp Composite (9.5% CAGR) |
| Fastest-Growing Form Type | Molded Shapes (10.3% CAGR) |
| Fastest-Growing Application Area | Jet Engine Components (8.3% CAGR) |
| Fastest-Growing End User | Defense Contractors (8.7% CAGR) |
| Growing Sector | Aerospace |
| Key End Users | Aerospace OEMs, Defense Contractors, Aviation Industry |
Japan Advanced Materials for Aerospace Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
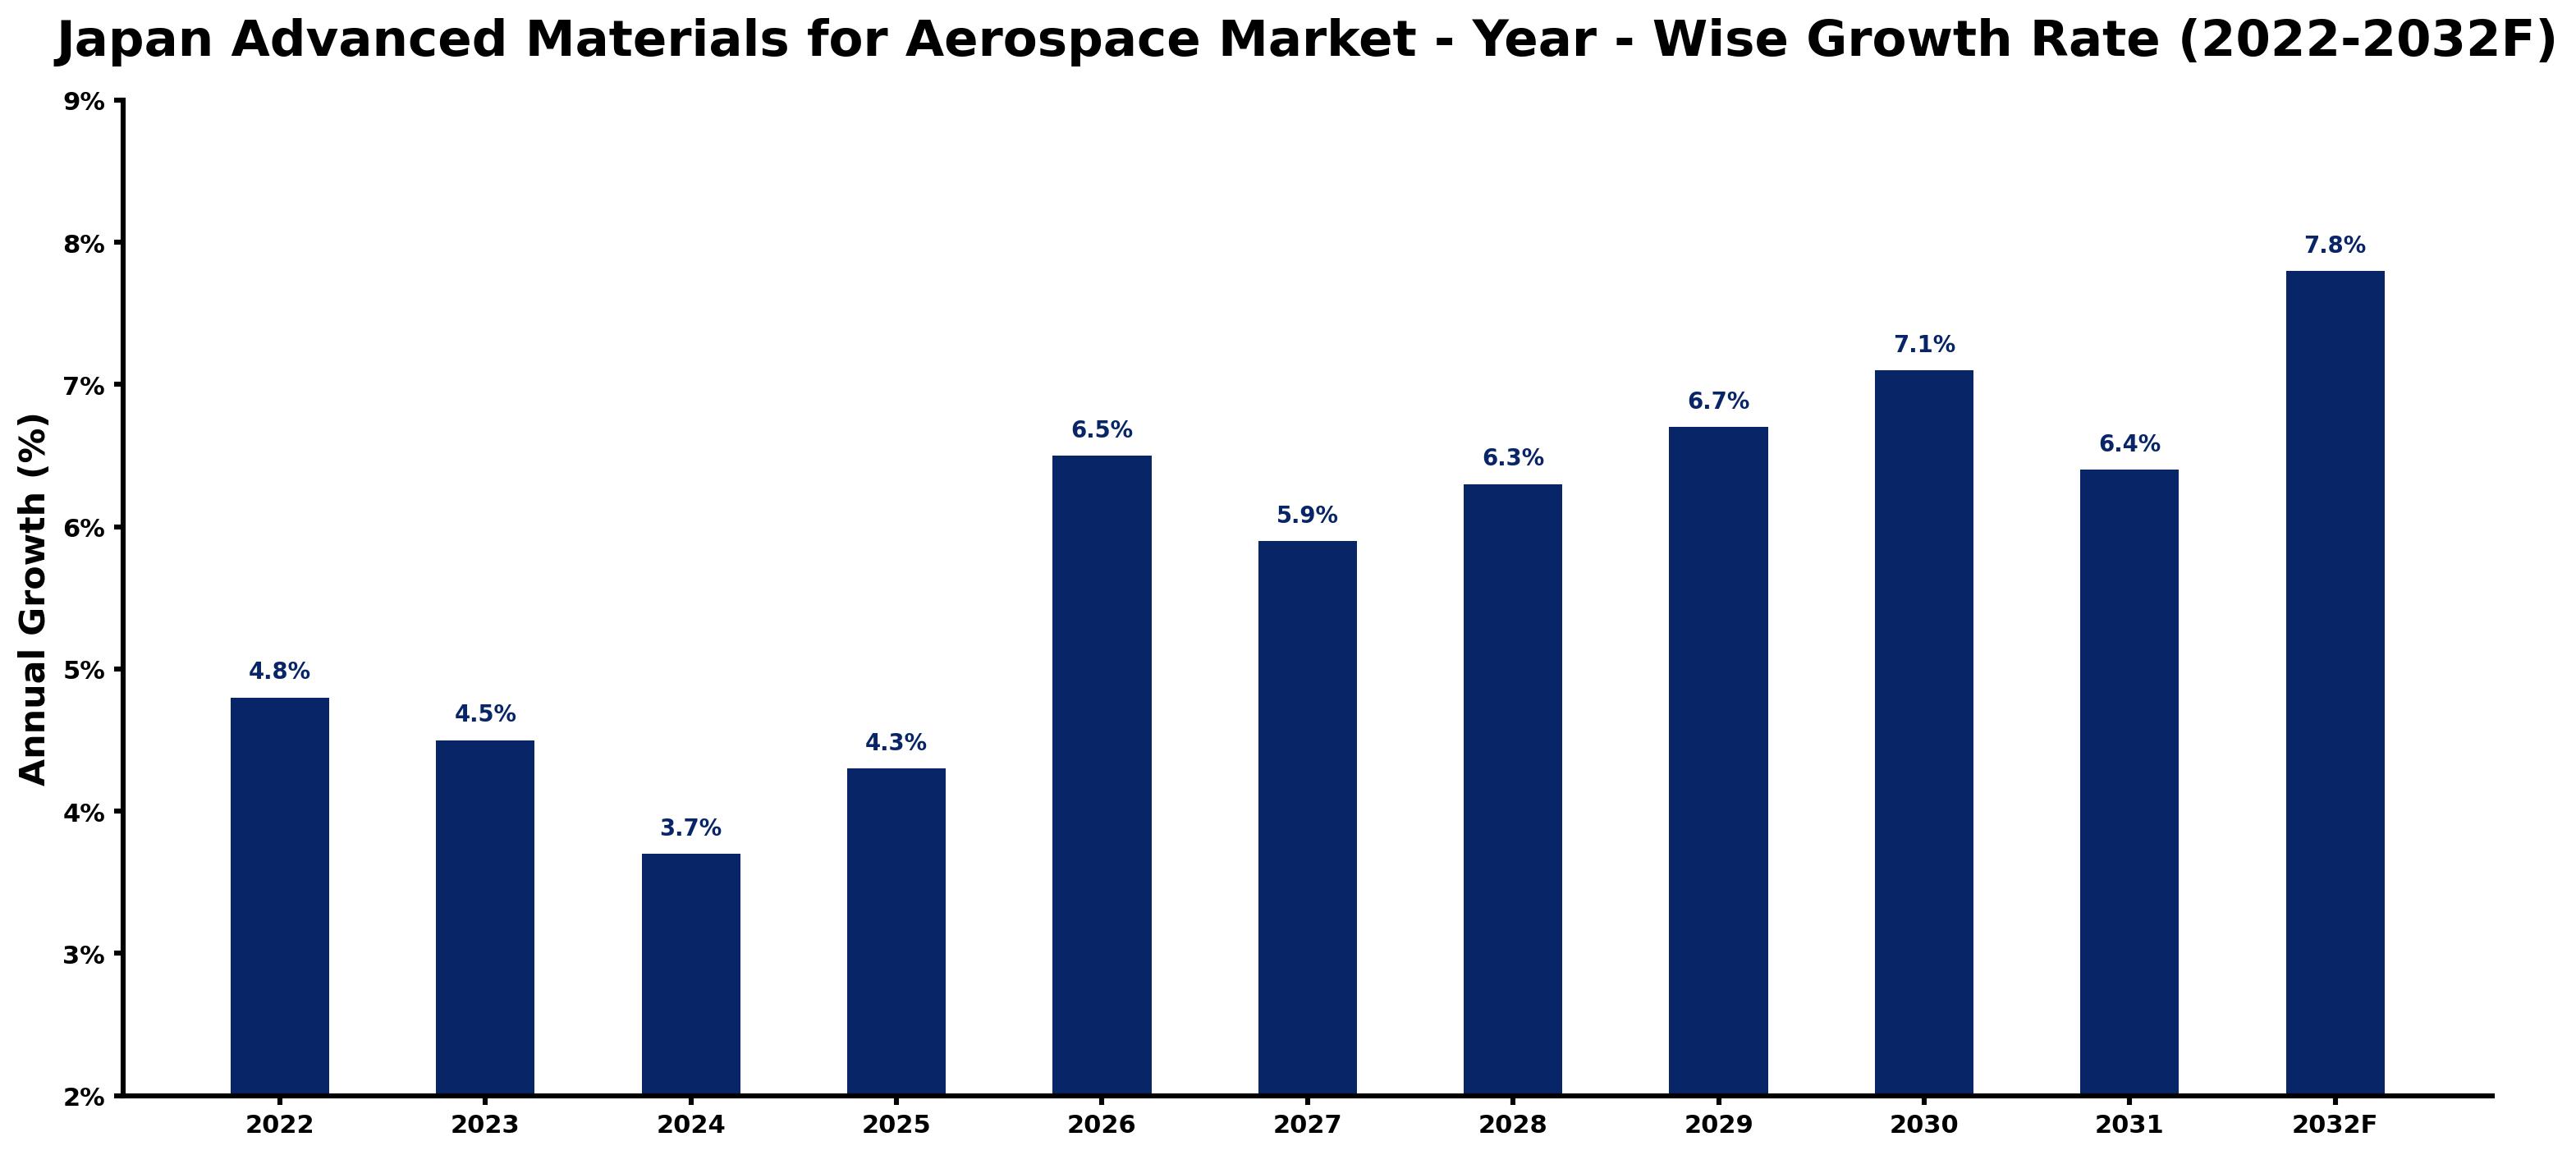
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.8 | Demand was strong, supported by ongoing defense contracts and local production. |
| 2023 | 4.5 | Growth slowed slightly as manufacturers adjusted to supply chain challenges. |
| 2024 | 3.7 | Continued adjustments in production processes led to a further slowdown in growth. |
| 2025 | 4.3 | Demand increased as manufacturers ramped up production to meet rising orders. |
| 2026 | 6.5 | Growth is expected to accelerate due to heightened investments in aerospace technology. |
| 2027 | 5.9 | A slight slowdown is projected as the market stabilises after rapid growth. |
| 2028 | 6.3 | Demand is expected to rise again as new aircraft designs are introduced to the market. |
| 2029 | 6.7 | Manufacturers will expand capacity, responding to increasing global aerospace demand. |
| 2030 | 7.1 | Growth is projected to continue as Japan aims for reductions in emissions by 2030. |
| 2031 | 6.4 | A slowdown is anticipated as the market adjusts to previous growth rates. |
| 2032 | 7.8 | Demand is expected to surge again as new aerospace projects come online. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Advanced Materials for Aerospace Market Synopsis
Advanced materials for aerospace, such as titanium alloys and carbon fiber composites, are engineered to withstand extreme conditions. These materials are essential for structural components, engine parts, and interiors in aircraft. The Japan Advanced Materials for Aerospace Market is expanding due to strong domestic manufacturing, ongoing defense contracts, and international collaborations.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in aerospace technology | Driver | High | Titanium Alloys |
| Increased demand for lightweight materials | Driver | High | Carbon Fiber Composites |
| Growing need for high-temperature applications | Opportunity | Medium | Ceramic Matrix Composites |
| Expansion of aerospace manufacturing hubs | Opportunity | Medium | Lightweight Metal |
| High production costs for advanced materials | Restraint | High | High-Performance Thermoplastics |
| Limited availability of skilled workforce | Restraint | Medium | Polymer Matrix Composite |
| Supply chain disruptions affecting material availability | Challenge | High | Sheet & Plates |
| Technological advancements outpacing current production methods | Challenge | Medium | Molded Shapes |
Evaluation of Drivers in Japan Advanced Materials for Aerospace Market (2026–2032)
The following drivers explain most of the expected growth.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased defense spending | Titanium Alloys | Japan's Ministry of Defense allocated ¥30 billion for aerospace technology development in 2023, driving demand for advanced materials. |
| Growing aircraft production | Carbon Fiber Composites | Carbon fiber composites are used in over 50% of new aircraft designs, prompting manufacturers to purchase more materials. |
| Technological advancements in material science | Ceramic Matrix Composites | Innovations in heat-resistant materials have led to their increased use in jet engines, boosting demand, with a projected growth of 20% in this area. |
| Focus on reducing aircraft weight | Lightweight Metal | The installed base of commercial aircraft in Japan is approximately 400 units, increasing the need for lightweight materials to enhance fuel efficiency. |
| Investment in aerospace innovation | High-Performance Thermoplastics | Japan's GX Basic Policy targets about JPY 150 trillion in decarbonisation investment over 10 years, stimulating demand for advanced materials. |
Buyers are adding capacity as Japan's defense spending increases, with a ¥30 billion allocation for aerospace technology development in 2023. The installed base of approximately 400 commercial aircraft drives demand for carbon fiber composites, which are used in over 50% of new designs. Innovations in material science have led to increased applications in jet engines, further boosting demand. Investment in aerospace innovation is projected to reach JPY 150 trillion, encouraging the adoption of high-performance thermoplastics in aerospace applications.
Evaluation of Restraints in Japan Advanced Materials for Aerospace Market
Below are the constraints most often cited by buyers and suppliers, with the segment each affects.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs for advanced materials | Titanium Alloys | The production of titanium alloys remains expensive, limiting accessibility for some manufacturers. |
| Limited availability of skilled workforce | Ceramic Matrix Composites | A shortage of skilled professionals in the aerospace sector affects production capabilities, with estimates showing a gap of over 10,000 workers. |
| Supply chain disruptions affecting material availability | Carbon Fiber Composites | Recent global supply chain issues have led to delays in material procurement for manufacturers, causing project delays of up to three months. |
| Regulatory compliance costs | High-Performance Thermoplastics | Compliance with stringent regulations increases the overall costs for producers, with estimates suggesting an increase of up to 15% in production costs. |
| Technological advancements outpacing current production methods | Molded Shapes | Rapid technological changes create challenges for manufacturers to keep up with production standards, leading to potential production downtimes. |
Japan Advanced Materials for Aerospace Market Challenges
Japan's aerospace sector faces supply chain disruptions, as reliance on a limited number of suppliers can delay production timelines by six months for manufacturers. International firms are increasing competition, which drives local producers to reduce prices by 10% to maintain market share. Buyers encounter rising material costs, where sudden spikes can inflate project budgets by 15%, complicating procurement strategies. Cost pressures mount due to strict environmental regulations, forcing manufacturers to allocate up to 20% of their operational budgets for compliance measures, impacting their financial flexibility.
Trends in the Japan Advanced Materials for Aerospace Market
Several trends are reshaping the Japan Advanced Materials for Aerospace Market; the most important are set out below.
- Aerospace OEMs Prioritising Lightweight Materials: Aerospace OEMs are increasingly prioritising lightweight materials to improve fuel efficiency. In 2023, over 50% of new aircraft designs incorporated carbon fiber composites, reflecting this shift.
- Transition from Traditional to Advanced Composites: The aerospace industry is moving from traditional materials to advanced composites. In Japan, the use of ceramic matrix composites in jet engines has risen significantly, with a notable increase in demand.
- Shift Towards Sustainable Manufacturing Practices: Manufacturers are adopting sustainable practices in production. The Tokyo Aerospace and Defense Industry Association supports initiatives that promote eco-friendly materials, aligning with Japan's decarbonisation targets.
- Emergence of New Aerospace Hubs: New aerospace manufacturing hubs are developing in Japan, particularly in the Tokyo region. This growth is expected to enhance local production capabilities and attract investments.
Investment Opportunities in the Japan Advanced Materials for Aerospace Market
Where to invest in the Japan Advanced Materials for Aerospace Market: the main openings are set out below.
- Investment in High-Temperature Composites: With a projected growth rate of 9.5% for high-temperature composites, manufacturers should invest in this area. Defense contractors are increasingly seeking these materials for jet engine applications.
- Supply of Lightweight Metal for Aircraft Structures: The demand for lightweight metal is on the rise, with a 44% market share expected by 2025. Aerospace OEMs are looking for suppliers to meet their production needs.
- Development of Advanced Molded Shapes: The market for molded shapes is growing rapidly, with a CAGR of 10.3%. Manufacturers should target the aerospace industry to supply these complex geometries.
- Expansion of Aerospace Innovation Initiatives: Japan's government initiative with a ¥50 billion budget for aerospace innovation creates opportunities for suppliers. Engaging with local aerospace firms can facilitate entry into this market.
Government Initiatives in the Japan Advanced Materials for Aerospace Market
Japan's recent initiative to promote aerospace innovation, launched in 2023 with a budget of ¥50 billion, adds support to existing laws like the Green Growth Strategy. This funding aims to enhance research and development in advanced materials, encouraging manufacturers to adopt innovative technologies.
Aerospace OEMs are utilising the funding from the 2023 initiative to explore new materials and technologies. This scheme allows them to access resources for research, ultimately improving production capabilities and product offerings.
Future Insight of the Japan Advanced Materials for Aerospace Market
The establishment of advanced research facilities will transform material technology by 2032, allowing suppliers to implement more efficient production processes. New government programmes will promote the development of high-temperature composites, improving jet engine performance. As Japan's installed base of commercial aircraft remains around 400 units, demand for advanced materials will surge, prompting buyers to seek innovative and sustainable solutions. With JPY 150 trillion planned for decarbonisation investments, suppliers must align their products with emerging environmental standards to remain competitive.
Market Segmentation Analysis
Japan Advanced Materials for Aerospace Market report covers a detailed analysis of the following market segments:
By Advanced Materials for Aerospace Market – Titanium Alloys Lead, Ceramic Matrix Composites Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, with 42% of advanced materials for aerospace market revenue in 2025, Titanium Alloys was the largest category. Titanium alloys hold the largest market share due to their essential use in aircraft structures, where both strength and weight reduction are critical. The installed base of approximately 400 commercial aircraft in Japan creates a robust demand for these materials. Ceramic Matrix Composites are set to record the highest CAGR in this split, 9.9% over 2026–2032. Ceramic matrix composites are experiencing rapid growth as they are increasingly utilised in high-temperature applications like jet engines, which are crucial for modern aerospace technology. The ongoing research by the Aerospace Research and Development Agency will further stimulate this segment's expansion. Suppliers should focus on developing ceramic matrix composites to meet the rising demand in high-temperature aerospace applications.
By Material Type – Lightweight Metal Leads, High-Temp Composite Expected to Grow Fastest
The largest material type category in 2025 was Lightweight Metal, at 44% of revenue. Lightweight metals lead the market as they are extensively used in aerospace applications to achieve weight reduction, which is essential for fuel efficiency. Their widespread application in the Tokyo region's aerospace manufacturing underscores their significance in the industry. High-Temp Composite is projected to grow fastest, at a CAGR of 9.5% during 2026–2032. High-temperature composites are the fastest-growing segment, driven by their critical role in components exposed to extreme heat, particularly in jet engines. The increasing focus on performance and efficiency in aerospace design is propelling this segment's growth. Buyers should prioritise sourcing high-temperature composites to ensure optimal performance in demanding aerospace applications.
By Form Type – Sheet & Plates Lead, Molded Shapes Expected to Grow Fastest
In 2025, Sheet & Plates led the form type split with a 41% share. Sheet and plates are the leading form type, widely used for structural components in aircraft that require robust materials for safety and performance. Their extensive application across various aerospace projects reinforces their strong market position. The quickest growth will come from Molded Shapes, forecast to expand at a CAGR of 10.3% between 2026 and 2032. Molded shapes are experiencing rapid growth due to their ability to accommodate complex geometries in aerospace parts, which are increasingly required for advanced designs. The trend towards more intricate designs in aircraft components is driving this segment's expansion. Suppliers must invest in capabilities to produce molded shapes to meet the evolving design requirements of the aerospace industry.
By Application Area – Aircraft Structures Lead, Jet Engine Components Expected to Grow Fastest
Aircraft Structures took 37% of application area revenue in 2025, more than any other category. Aircraft structures represent the largest application area for advanced materials, as they are vital for ensuring the integrity and performance of aircraft. The substantial installed base of commercial aircraft in Japan necessitates the use of these materials in structural applications. Over 2026–2032, Jet Engine Components are expected to post the fastest growth, at a CAGR of 8.3%. Jet engine components are the fastest-growing application area, propelled by the demand for high-performance materials that can withstand extreme conditions. The increasing complexity and efficiency requirements of modern jet engines are accelerating this segment's growth. Buyers should focus on sourcing advanced materials specifically tailored for jet engine components to enhance performance and reliability.
By End User – Aerospace OEMs Lead, Defense Contractors Expected to Grow Fastest
Aerospace OEMs accounted for 51% of the market by end user in 2025. Aerospace OEMs are the primary end users of advanced materials, requiring high-quality components for aircraft manufacturing. Their considerable investment in new aircraft designs ensures a consistent demand for these materials. Defense Contractors are set to record the highest CAGR in this split, 8.7% over 2026–2032. Defense contractors represent the fastest-growing end user segment, as military applications increasingly necessitate advanced materials for improved performance and durability. The Ministry of Defense's substantial budget allocation for aerospace technology development supports this growth. Suppliers should target defense contractors to capture emerging opportunities in the military aerospace sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Advanced Materials for Aerospace Market Outlook
- Market Size of Japan Advanced Materials for Aerospace Market, 2025
- Forecast of Japan Advanced Materials for Aerospace Market, 2032
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Revenues & Volume for the Period 2022-2032F
- Japan Advanced Materials for Aerospace Market Trend Evolution
- Japan Advanced Materials for Aerospace Market Drivers and Challenges
- Japan Advanced Materials for Aerospace Price Trends
- Japan Advanced Materials for Aerospace Porter's Five Forces
- Japan Advanced Materials for Aerospace Industry Life Cycle
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Advanced Materials for Aerospace Market for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Titanium Alloys for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Ceramic Matrix Composites for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Carbon Fiber Composites for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By High-Performance Thermoplastics for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Material Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Lightweight Metal for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By High-Temp Composite for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Polymer Matrix Composite for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Polymer-Based Material for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Form Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Sheet & Plates for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Molded Shapes for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Fabric & Panels for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Pellets/Granules for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Application Area for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Aircraft Structures for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Jet Engine Components for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Aircraft Interiors for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Cabin Panels & Seating for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Aerospace OEMs for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Defense Contractors for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Aviation Industry for the Period 2022-2032F
- Historical Data and Forecast of Japan Advanced Materials for Aerospace Market Revenues & Volume By Aircraft Maintenance Firms for the Period 2022-2032F
- Japan Advanced Materials for Aerospace Import Export Trade Statistics
- Market Opportunity Assessment By Advanced Materials for Aerospace Market
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Form Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- Japan Advanced Materials for Aerospace Top Companies Market Share
- Japan Advanced Materials for Aerospace Competitive Benchmarking By Technical and Operational Parameters
- Japan Advanced Materials for Aerospace Company Profiles
- Japan Advanced Materials for Aerospace Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Advanced Materials for Aerospace Market
- Titanium Alloys
- Ceramic Matrix Composites
- Carbon Fiber Composites
- High-Performance Thermoplastics
By Material Type
- Lightweight Metal
- High-Temp Composite
- Polymer Matrix Composite
- Polymer-Based Material
By Form Type
- Sheet & Plates
- Molded Shapes
- Fabric & Panels
- Pellets/Granules
By Application Area
- Aircraft Structures
- Jet Engine Components
- Aircraft Interiors
- Cabin Panels & Seating
By End User
- Aerospace OEMs
- Defense Contractors
- Aviation Industry
- Aircraft Maintenance Firms






































