Japan Aerospace Alloys Market Size & Growth Rate
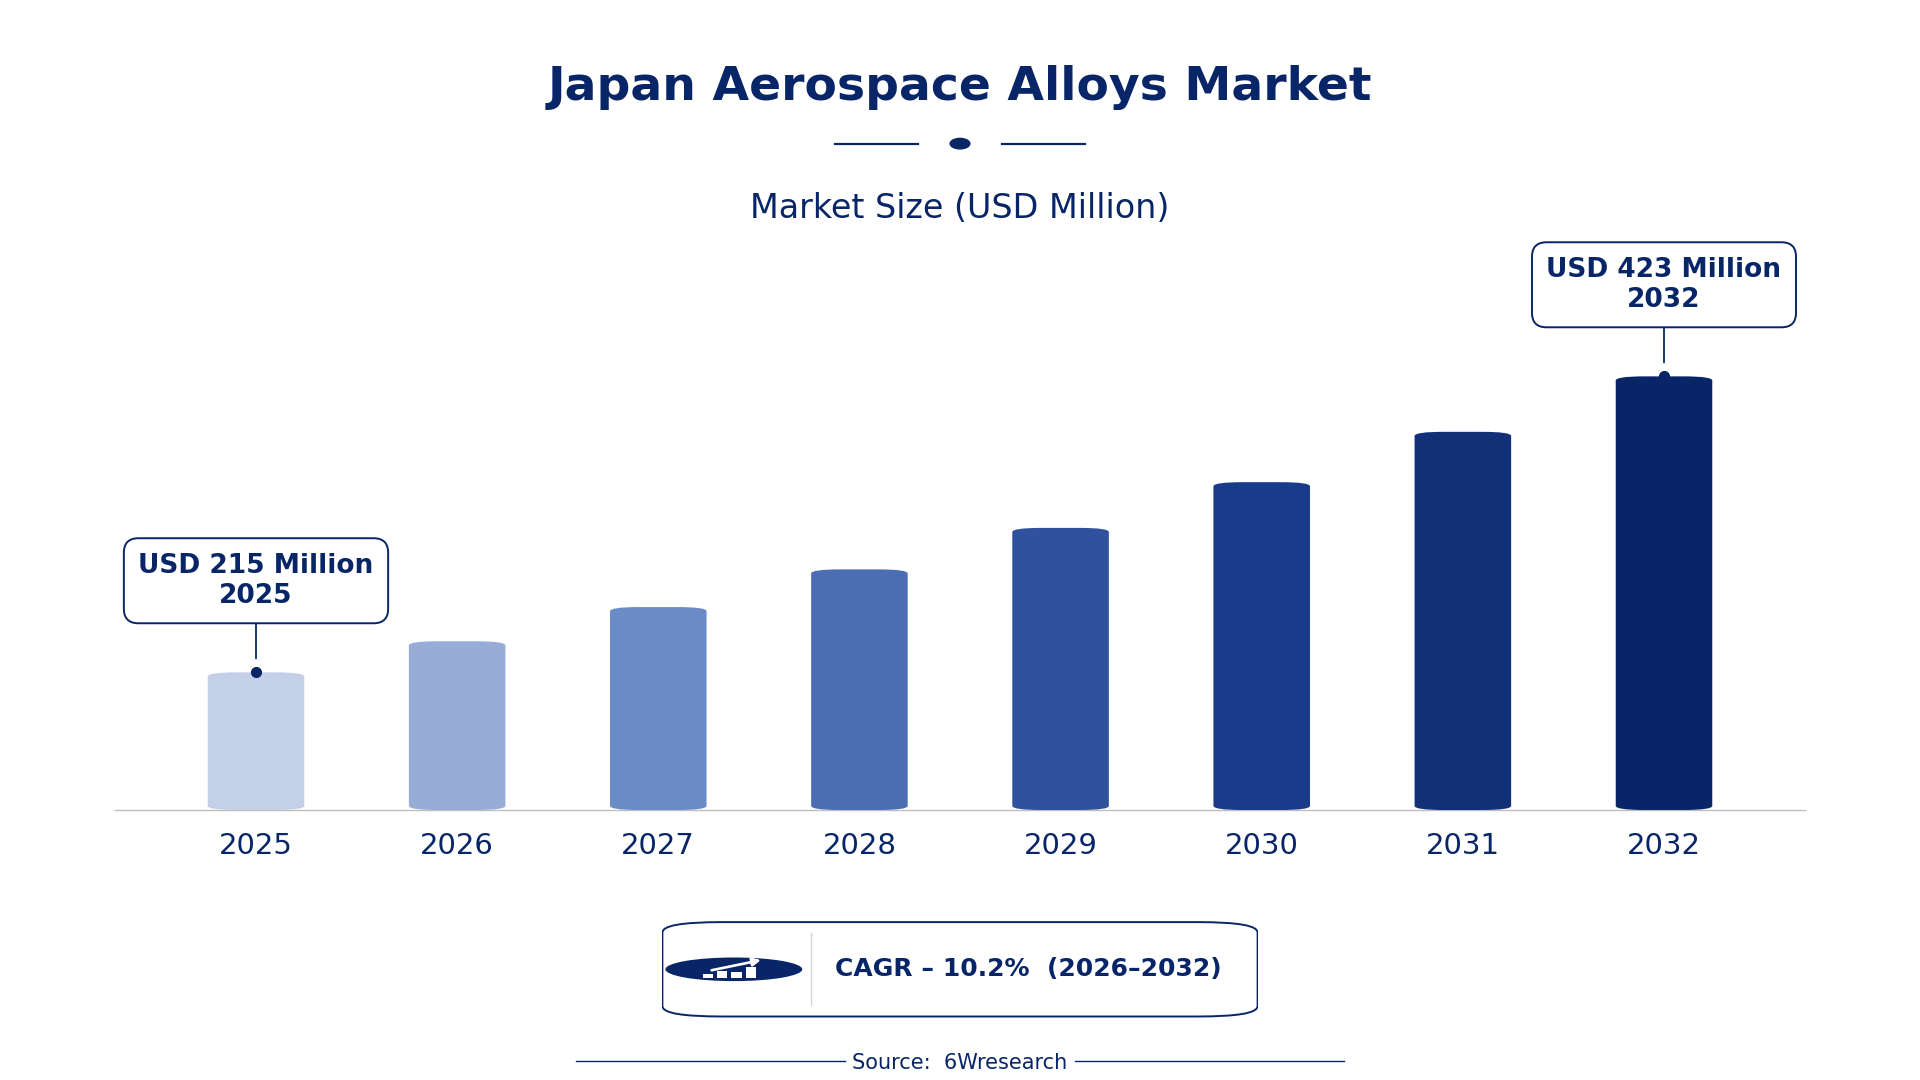
According to 6Wresearch internal database and industry insights, the Japan Aerospace Alloys Market was valued at USD 215 Million in 2025 and is projected to reach USD 423 Million by 2032, growing at a CAGR of approximately 10.2% during 2026–2032.
Japan Aerospace Alloys Market Highlights
| Report Metric | Details |
| Report Name | Japan Aerospace Alloys Market (2026-2032) |
| Market Size 2025 | USD 215 Million |
| Market Size 2032 | USD 423 Million |
| Absolute Growth 2025–2032 | USD 208 Million |
| CAGR 2026–2032 | 10.2% |
| Peak Annual Growth | 11.1% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Alloy Type, 2025 | Titanium Alloys (37% share) |
| Leading Material Base, 2025 | Titanium-Based (42% share) |
| Leading Distribution Channel, 2025 | OEMs (50% share) |
| Leading End User, 2025 | Aircraft Manufacturers (46% share) |
| Fastest-Growing Alloy Type | Aluminum Alloys (14.3% CAGR) |
| Fastest-Growing Material Base | Aluminum-Based (14.4% CAGR) |
| Fastest-Growing Distribution Channel | Industrial Suppliers (13.6% CAGR) |
| Fastest-Growing End User | Commercial Aviation (13.2% CAGR) |
| Growing Sector | Commercial Aviation |
| Key End Users | Aircraft Manufacturers, Jet Engine OEMs, Spacecraft Component Makers, Industrial Suppliers |
Japan Aerospace Alloys Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
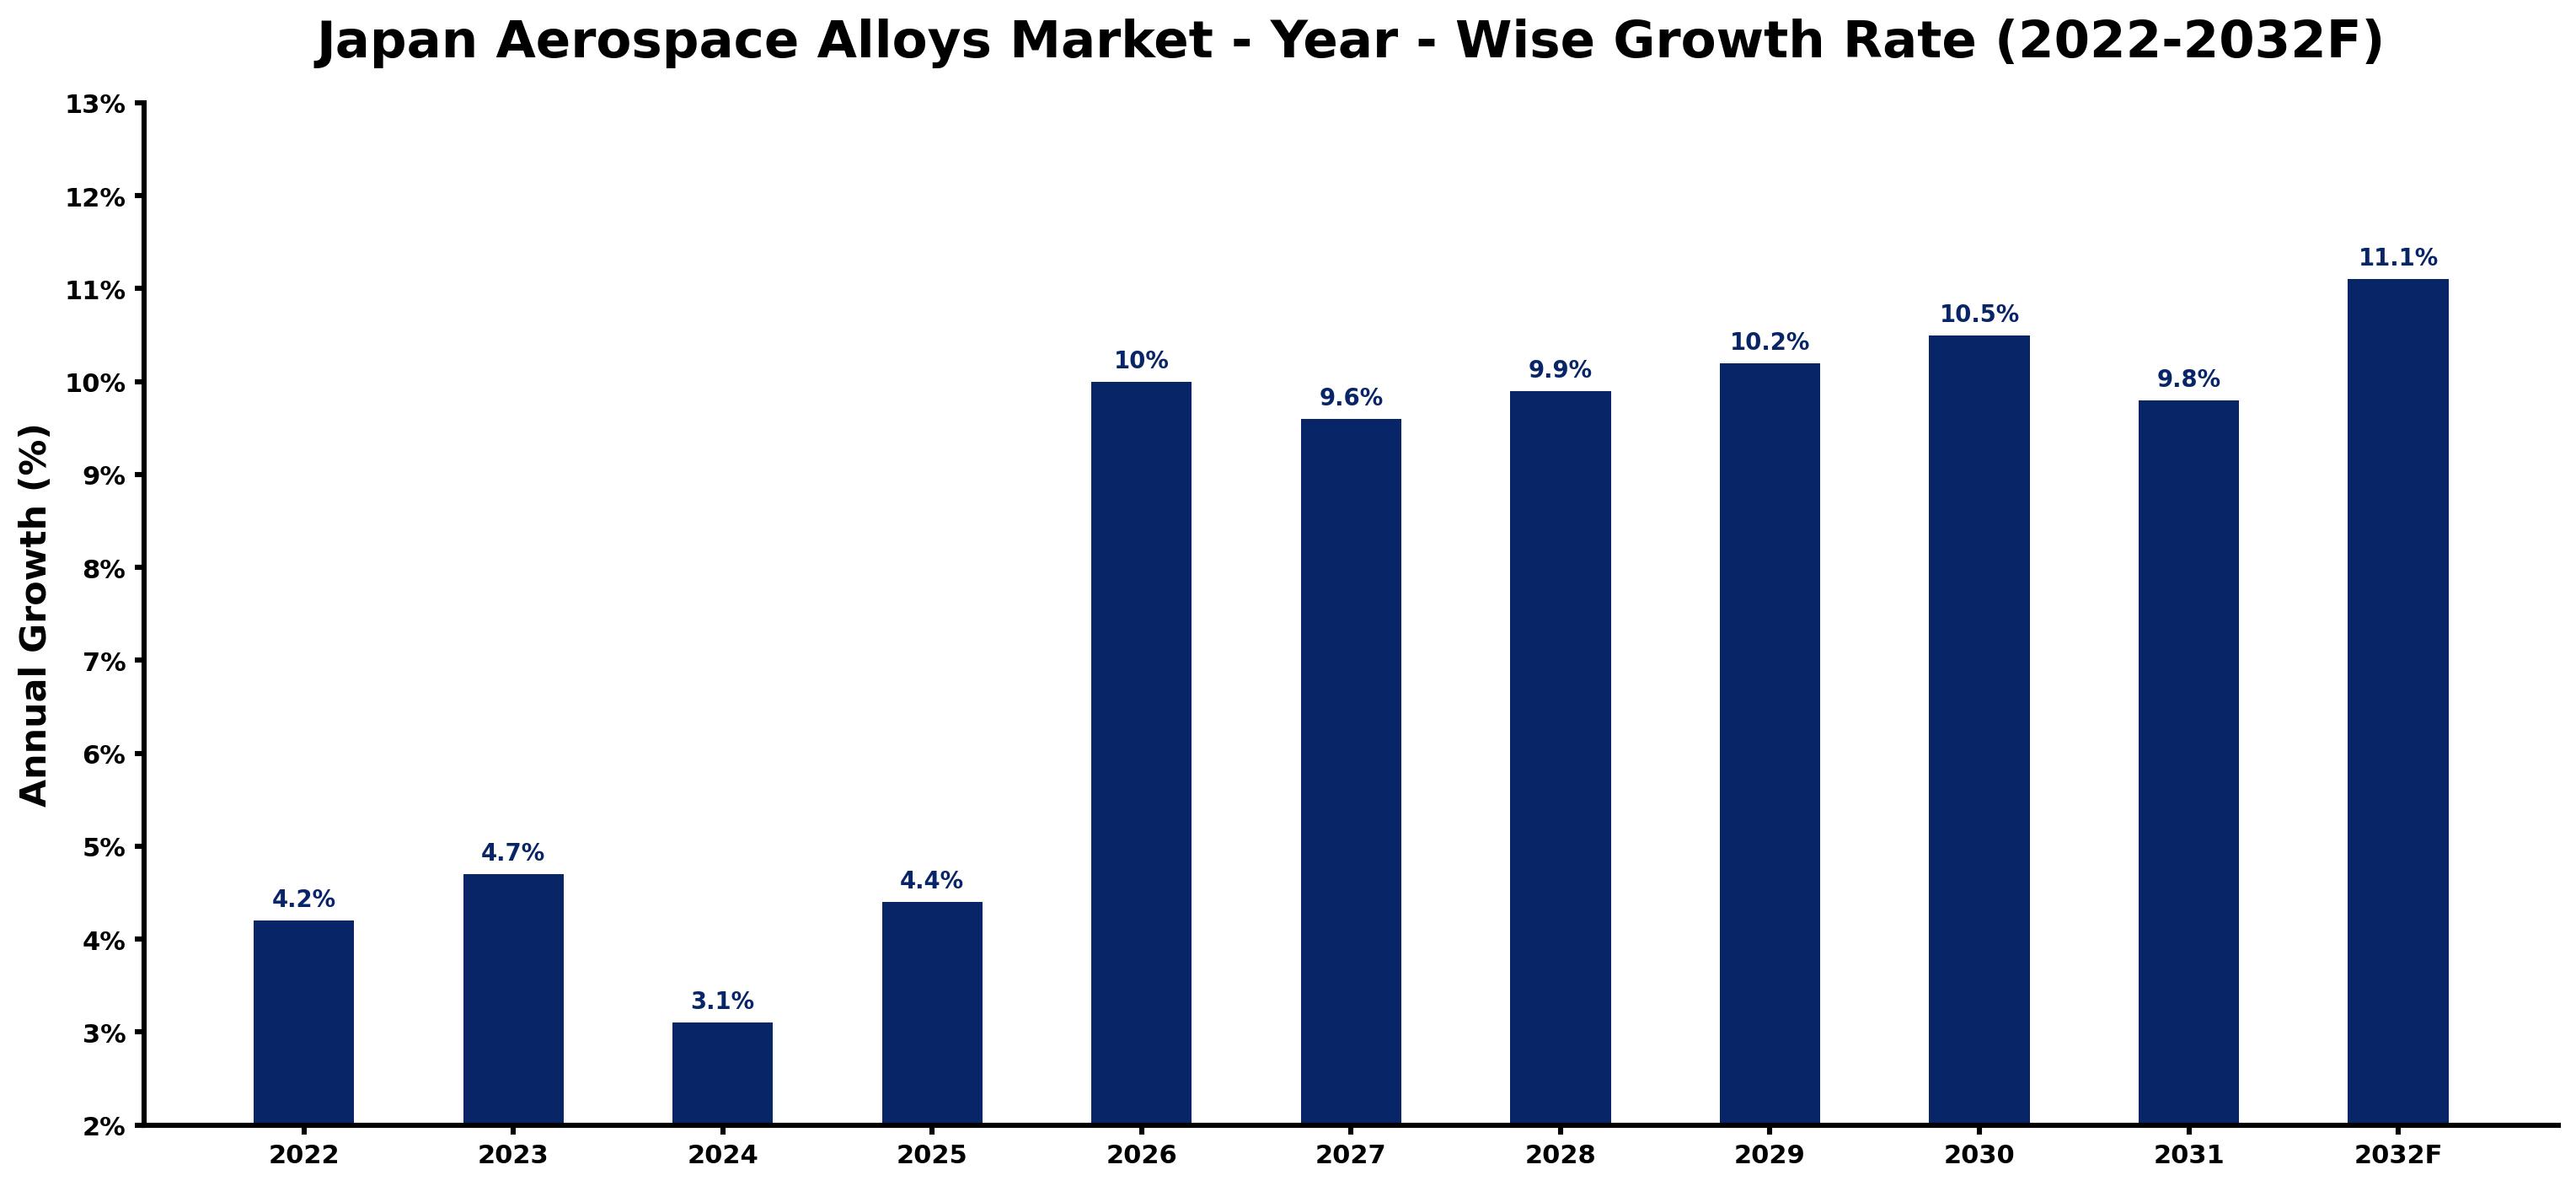
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.2 | The market showed steady growth due to ongoing aerospace projects. |
| 2023 | 4.7 | Growth accelerated as domestic manufacturers increased production capacity. |
| 2024 | 3.1 | Growth slowed as some manufacturers faced supply chain issues. |
| 2025 | 4.4 | Demand rose again as new aircraft models entered production. |
| 2026 | 10.0 | The market is expected to surge with increased investments in aerospace. |
| 2027 | 9.6 | Growth slows slightly as competition intensifies among suppliers. |
| 2028 | 9.9 | Demand rebounds as technological advancements improve production. |
| 2029 | 10.2 | The market grows rapidly due to rising commercial aviation needs. |
| 2030 | 10.5 | Continued investments in R&D drive further growth in aerospace. |
| 2031 | 9.8 | Growth slows as market reaches a more mature phase. |
| 2032 | 11.1 | The market peaks with substantial demand for advanced alloys. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Aerospace Alloys Market Synopsis
Aerospace alloys are specialised metal alloys used in aircraft and spacecraft applications, produced through casting and forging processes to improve strength and thermal resistance. The Japan Aerospace Alloys Market, valued at approximately 1.5 trillion JPY as of 2023, is primarily driven by domestic manufacturers and backed by investments in technology development. The demand for aluminium alloys, which account for about 70% of materials in commercial aircraft, along with titanium alloys, used in over 50% of modern jet engines, are key growth factors. The government's focus on aerospace innovation boosts the market's potential.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased production of commercial aircraft | Driver | High | Aluminum Alloys |
| Rising demand for advanced materials in aerospace | Driver | High | Titanium Alloys |
| Growing need for lightweight materials | Opportunity | High | Aluminum-Based |
| Expansion of aerospace manufacturing hubs | Opportunity | Medium | Titanium-Based |
| Supply chain disruptions affecting material availability | Restraint | High | Nickel Alloys |
| High costs associated with advanced alloy production | Restraint | Medium | Titanium Alloys |
| Intense competition among suppliers | Challenge | High | Aluminum Alloys |
| Technological advancements requiring constant updates | Challenge | Medium | Titanium Alloys |
Evaluation of Drivers in Japan Aerospace Alloys Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of commercial aircraft | Aluminum Alloys | This demand arises from the production of various aircraft models, which heavily rely on aluminum, accounting for about 70% of materials used. |
| Rising demand for advanced materials in aerospace | Titanium Alloys | Titanium alloys are essential for high-performance applications, with over 50% used in modern jet engines. |
| Expansion of aerospace manufacturing hubs | Titanium-Based | Key regions like Tokyo and Nagoya strengthen local supply chains, boosting production capabilities. |
| Growing investment in aerospace R&D | Nickel Alloys | Japan allocated 100 billion JPY for aerospace R&D in 2023, promoting innovation in materials. |
| Technological advancements in manufacturing processes | Aluminum-Based | ISO 9001 standards are widely adopted, ensuring quality in aerospace manufacturing. |
Several shifts outside the market lift sales. The production of commercial aircraft has increased, with various models relying heavily on aluminum alloys, which constitute about 70% of materials used. Japan's allocation of 100 billion JPY for aerospace R&D in 2023 promotes innovation in advanced materials. The expansion of aerospace manufacturing hubs in key regions strengthens local supply chains. Demand for titanium alloys, essential in modern jet engines, is notable, as over 50% of these engines utilize such materials.
Evaluation of Restraints in Japan Aerospace Alloys Market
These restraints slow adoption and weigh on supplier margins.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions affecting material availability | Nickel Alloys | Supply chain issues have led to delays in the availability of nickel alloys, impacting production timelines. |
| High costs associated with advanced alloy production | Titanium Alloys | The production of titanium alloys is costly, which can deter smaller manufacturers from entering the market. |
| Regulatory compliance costs for aerospace materials | Aluminum Alloys | Compliance with ISO 9001 standards incurs costs for manufacturers, affecting pricing. |
| Limited availability of skilled workforce | Titanium-Based | The aerospace sector faces a shortage of skilled workers, which can hinder production capacity. |
| Market saturation in certain alloy types | Nickel-Based | The nickel alloy market is becoming saturated, limiting growth opportunities for new entrants. |
Japan Aerospace Alloys Market Challenges
Japan's advanced manufacturing techniques lead to high production costs, raising expenses by up to 20% for producers. Buyers face delays in receiving aerospace alloys due to stringent quality standards, often extending lead times by several weeks. Increased competition from international suppliers pressures domestic producers, as foreign manufacturers can offer lower prices, forcing local firms to reduce margins. Slow technology adoption results in inefficiencies, costing manufacturers up to 15% in lost productivity annually, impacting their ability to compete effectively.
Trends in the Japan Aerospace Alloys Market
The trends below show where the Japan Aerospace Alloys Market is heading.
- Shift towards Titanium Alloys: Since 2023, there has been a notable shift towards titanium alloys in aircraft manufacturing, driven by their superior strength-to-weight ratio. This trend is reflected in modern jet engines, where titanium alloys are used in over 50% of components.
- Emergence of Advanced Manufacturing Techniques: The launch of new manufacturing initiatives has introduced advanced techniques, improving production efficiency. This has led to a significant reduction in production times for aerospace components.
- Increased Focus on Sustainable Materials: Starting in 2021, the industry has prioritised sustainable materials, aligning with the Green Growth Strategy aiming for carbon neutrality by 2050. This shift is reflected in the increased use of recyclable materials in aircraft production.
- Growth in Aerospace R&D Investments: The Japanese government allocated 100 billion JPY for aerospace R&D in 2023, promoting innovation in materials and technologies. This investment is expected to boost the development of next-generation aerospace alloys.
Investment Opportunities in the Japan Aerospace Alloys Market
The openings below show where demand in the Japan Aerospace Alloys Market is visible and how suppliers can enter.
- Aerospace Alloys for Commercial Aviation: With the commercial aviation sector expanding, there is a growing need for aluminium alloys, which account for about 70% of materials used. Aircraft manufacturers are looking for reliable suppliers to meet this demand.
- Investment in Advanced Alloys: Now is an opportune time to invest in titanium alloys, as their demand is increasing due to their use in modern jet engines. Collaborating with aerospace manufacturers in Tokyo can facilitate market entry.
- Supply of Lightweight Materials: The demand for lightweight materials is surging, particularly in commercial aviation. Industrial suppliers in Nagoya are seeking partnerships to provide aluminium-based alloys to meet this need.
- Development of Sustainable Aerospace Materials: The focus on sustainable aviation is creating opportunities for suppliers of eco-friendly materials. Engaging with the Japan Society for Aeronautical and Space Sciences can help in gaining insights into market needs.
Government Initiatives in the Japan Aerospace Alloys Market
The Economic Security Promotion Act, enacted in 2022, supports supply-chain resilience for critical materials, including aerospace alloys. This measure builds on previous laws by ensuring that manufacturers can secure essential materials without disruption, thereby supporting production stability in the aerospace sector. The Japanese government allocated 100 billion JPY for aerospace R&D in 2023, promoting innovation in the industry.
The Ministry of Economy, Trade and Industry (METI) oversees the implementation of various aerospace initiatives, funding projects that promote innovation and collaboration among manufacturers. The PRTR Law requires businesses to report releases of designated chemical substances, ensuring compliance and safety in aerospace production.
Future Insight of the Japan Aerospace Alloys Market
By 2032, the Aerospace Industry Development Strategy will drive suppliers to adopt cutting-edge manufacturing technologies, enhancing product offerings. The Japan Aerospace Exploration Agency will lead research into advanced materials, fostering innovation. With the government investing 100 billion JPY in aerospace R&D, new market opportunities will emerge. As the installed base of commercial aircraft grows, suppliers will need to align with evolving demands for high-performance alloys.
Market Segmentation Analysis
Japan Aerospace Alloys Market report covers a detailed analysis of the following market segments:
By Alloy Type – Titanium Alloys Lead, Aluminum Alloys Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, the largest alloy type category in 2025 was Titanium Alloys, at 37% of revenue. Titanium alloys hold a substantial share in the market as they are essential for critical structural components in aerospace, particularly in jet engines. Their high strength-to-weight ratio makes them indispensable for meeting stringent performance and safety standards in aircraft manufacturing. Aluminum Alloys are set to record the highest CAGR in this split, 14.3% over 2026–2032. Aluminum alloys are witnessing rapid growth due to their extensive use in aircraft structures, notably in the production of the Boeing 787. This shift towards lightweight materials is pivotal for enhancing fuel efficiency and overall aircraft performance. Suppliers need to focus on aluminium alloy innovations to meet the increasing demand in the aerospace sector.
By Material Base – Titanium-Based Leads, Aluminum-Based Expected to Grow Fastest
Titanium-Based took 42% of material base revenue in 2025, more than any other category. Titanium-based materials are crucial for high-performance aerospace applications, particularly in components that require exceptional strength and durability. Their significant use in modern jet engines highlights their importance in the aerospace alloys market. Over 2026–2032, Aluminum-Based is expected to post the fastest growth, at a CAGR of 14.4%. Aluminum-based materials are becoming increasingly popular as they dominate the production of aircraft fuselage and wings, driven by the industry's focus on lightweight solutions. This trend is crucial for improving fuel efficiency and reducing emissions in aviation. Buyers should prioritise sourcing aluminium-based materials to align with industry trends towards lightweight aircraft designs.
By Distribution Channel – OEMs Lead, Industrial Suppliers Expected to Grow Fastest
OEMs accounted for 50% of the market by distribution channel in 2025. OEMs are the leading customers for aerospace alloys, as they directly manufacture aircraft and require substantial volumes of materials. Their established relationships with suppliers ensure consistent demand and reliability in the supply chain. The quickest growth will come from Industrial Suppliers, forecast to expand at a CAGR of 13.6% between 2026 and 2032. Industrial suppliers are experiencing rapid growth as they play a vital role in providing essential materials to OEMs and manufacturers, streamlining the supply chain process. This segment's expansion reflects the increasing complexity and demand in aerospace manufacturing. Suppliers should enhance partnerships with industrial suppliers to improve market reach and distribution efficiency.
By End User – Aircraft Manufacturers Lead, Commercial Aviation Expected to Grow Fastest
In 2025, Aircraft Manufacturers led the end user split with a 46% share. Aircraft manufacturers represent the largest end-users of aerospace alloys, as they are responsible for producing a wide range of aircraft models. Their scale of operations guarantees a steady and robust demand for high-quality aerospace materials. Commercial Aviation is projected to grow fastest, at a CAGR of 13.2% during 2026–2032. Commercial aviation is expanding rapidly due to a surge in passenger numbers and the corresponding need for new aircraft, which significantly drives demand for aerospace alloys. This growth is crucial for the overall health and sustainability of the aerospace market. Suppliers must align their production capabilities with the increasing demands of the commercial aviation sector to capitalise on emerging market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Aerospace Alloys Market Outlook
- Market Size of Japan Aerospace Alloys Market, 2025
- Forecast of Japan Aerospace Alloys Market, 2032
- Historical Data and Forecast of Japan Aerospace Alloys Revenues & Volume for the Period 2022-2032F
- Japan Aerospace Alloys Market Trend Evolution
- Japan Aerospace Alloys Market Drivers and Challenges
- Japan Aerospace Alloys Price Trends
- Japan Aerospace Alloys Porter's Five Forces
- Japan Aerospace Alloys Industry Life Cycle
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Alloy Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Titanium Alloys for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Aluminum Alloys for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Nickel Alloys for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Magnesium Alloys for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Material Base for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Titanium-Based for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Aluminum-Based for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Nickel-Based for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Magnesium-Based for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By OEMs for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Industrial Suppliers for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Direct Sales for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Specialty Stores for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Aircraft Manufacturers for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Commercial Aviation for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Jet Engine OEMs for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace Alloys Market Revenues & Volume By Spacecraft Component Makers for the Period 2022-2032F
- Japan Aerospace Alloys Import Export Trade Statistics
- Market Opportunity Assessment By Alloy Type
- Market Opportunity Assessment By Material Base
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Japan Aerospace Alloys Top Companies Market Share
- Japan Aerospace Alloys Competitive Benchmarking By Technical and Operational Parameters
- Japan Aerospace Alloys Company Profiles
- Japan Aerospace Alloys Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Alloy Type
- Titanium Alloys
- Aluminum Alloys
- Nickel Alloys
- Magnesium Alloys
By Material Base
- Titanium-Based
- Aluminum-Based
- Nickel-Based
- Magnesium-Based
By Distribution Channel
- OEMs
- Industrial Suppliers
- Direct Sales
- Specialty Stores
By End User
- Aircraft Manufacturers
- Commercial Aviation
- Jet Engine OEMs
- Spacecraft Component Makers






































