Japan Aerospace & Defense Components Market Size & Growth Rate
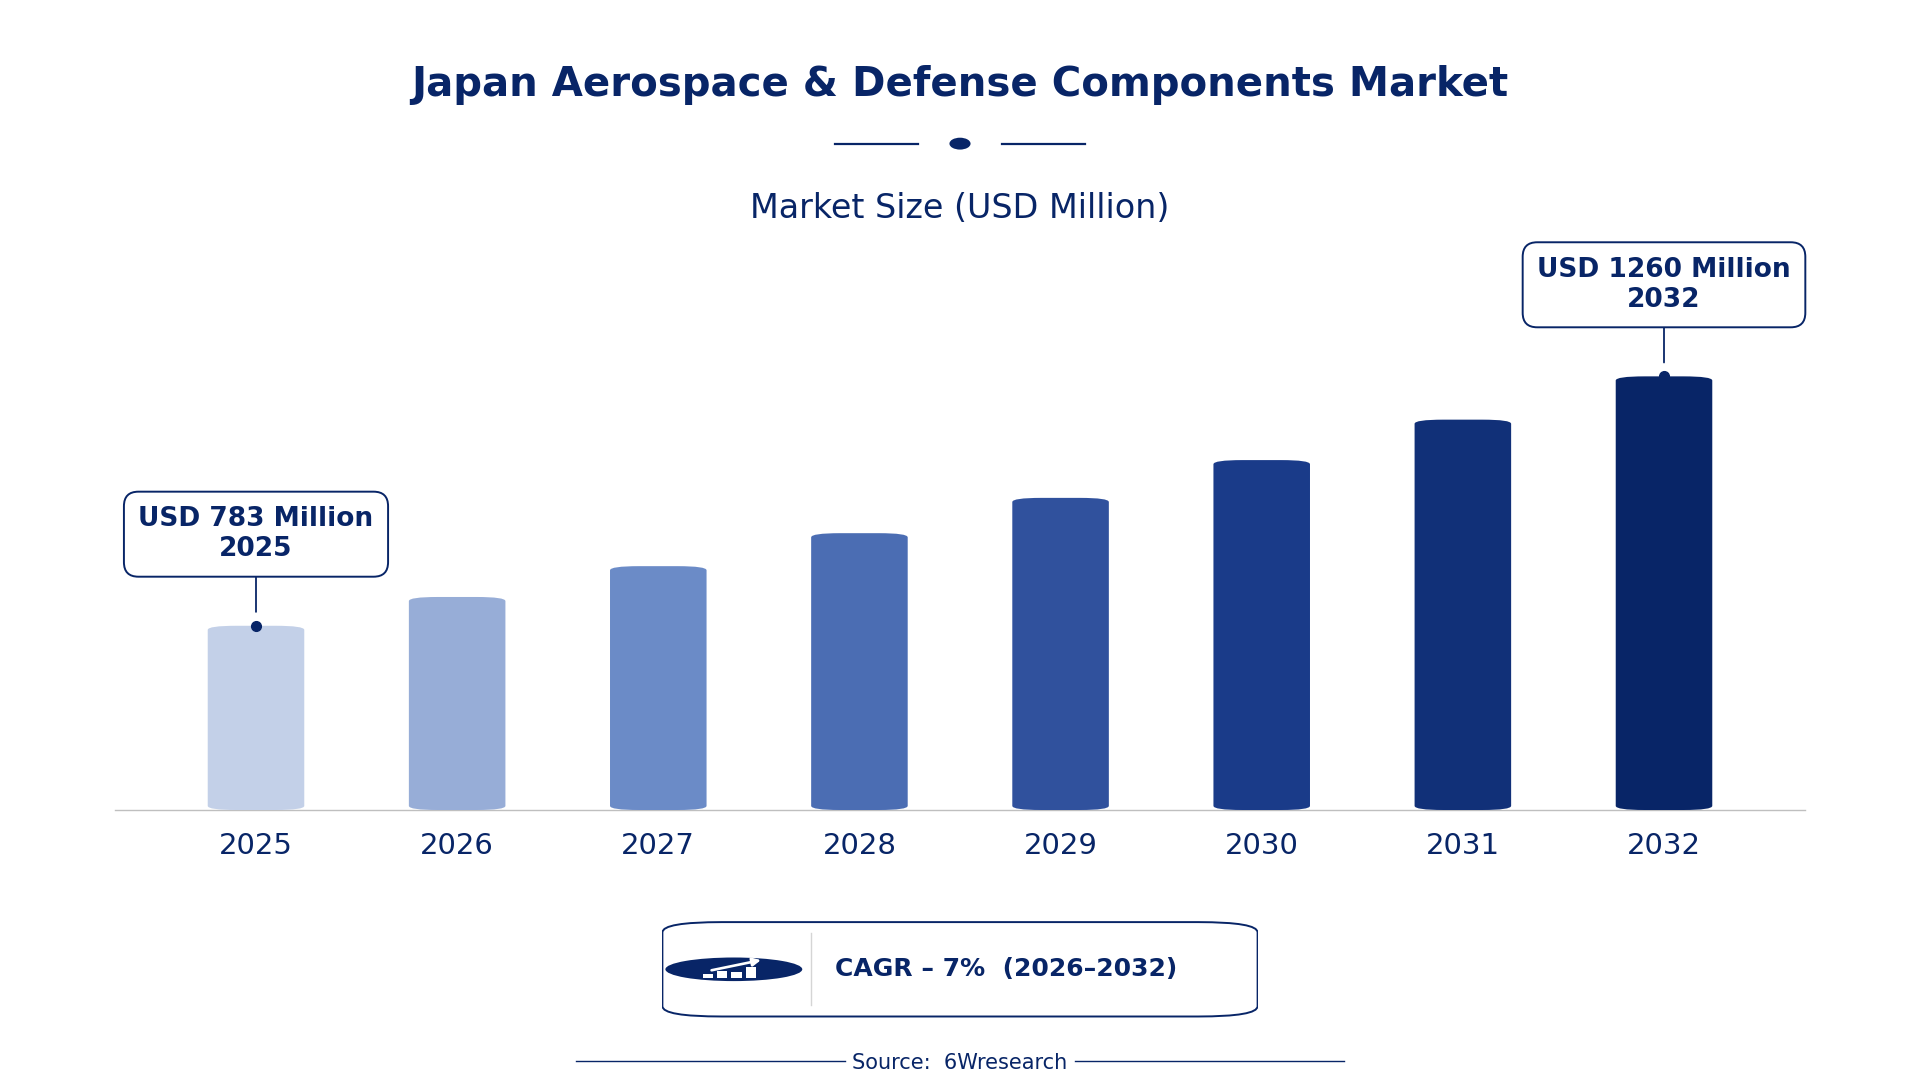
According to 6Wresearch internal database and industry insights, the Japan Aerospace & Defense Components Market was valued at USD 783 Million in 2025 and is projected to reach USD 1,260 Million by 2032, growing at a CAGR of approximately 7% during 2026–2032.
Japan Aerospace & Defense Components Market Highlights
| Report Metric | Details |
| Report Name | Japan Aerospace & Defense Components Market (2026-2032) |
| Market Size 2025 | USD 783 Million |
| Market Size 2032 | USD 1,260 Million |
| Absolute Growth 2025–2032 | USD 477 Million |
| CAGR 2026–2032 | 7% |
| Peak Annual Growth | 7.7% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Structural Components (45% share) |
| Leading Material Type, 2025 | Titanium Alloys (35% share) |
| Leading Distribution Channel, 2025 | Government Contracts (42% share) |
| Leading End User, 2025 | Aircraft Manufacturers (40% share) |
| Fastest-Growing Component Type | Avionics (9.7% CAGR) |
| Fastest-Growing Material Type | Composites (10.0% CAGR) |
| Fastest-Growing Distribution Channel | OEMs (8.7% CAGR) |
| Fastest-Growing End User | Defense Equipment Vendors (9.0% CAGR) |
| Growing Sector | Aerospace Manufacturing |
| Key End Users | Aircraft Manufacturers, Defense Equipment Vendors, Military Aviation Units |
Japan Aerospace & Defense Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
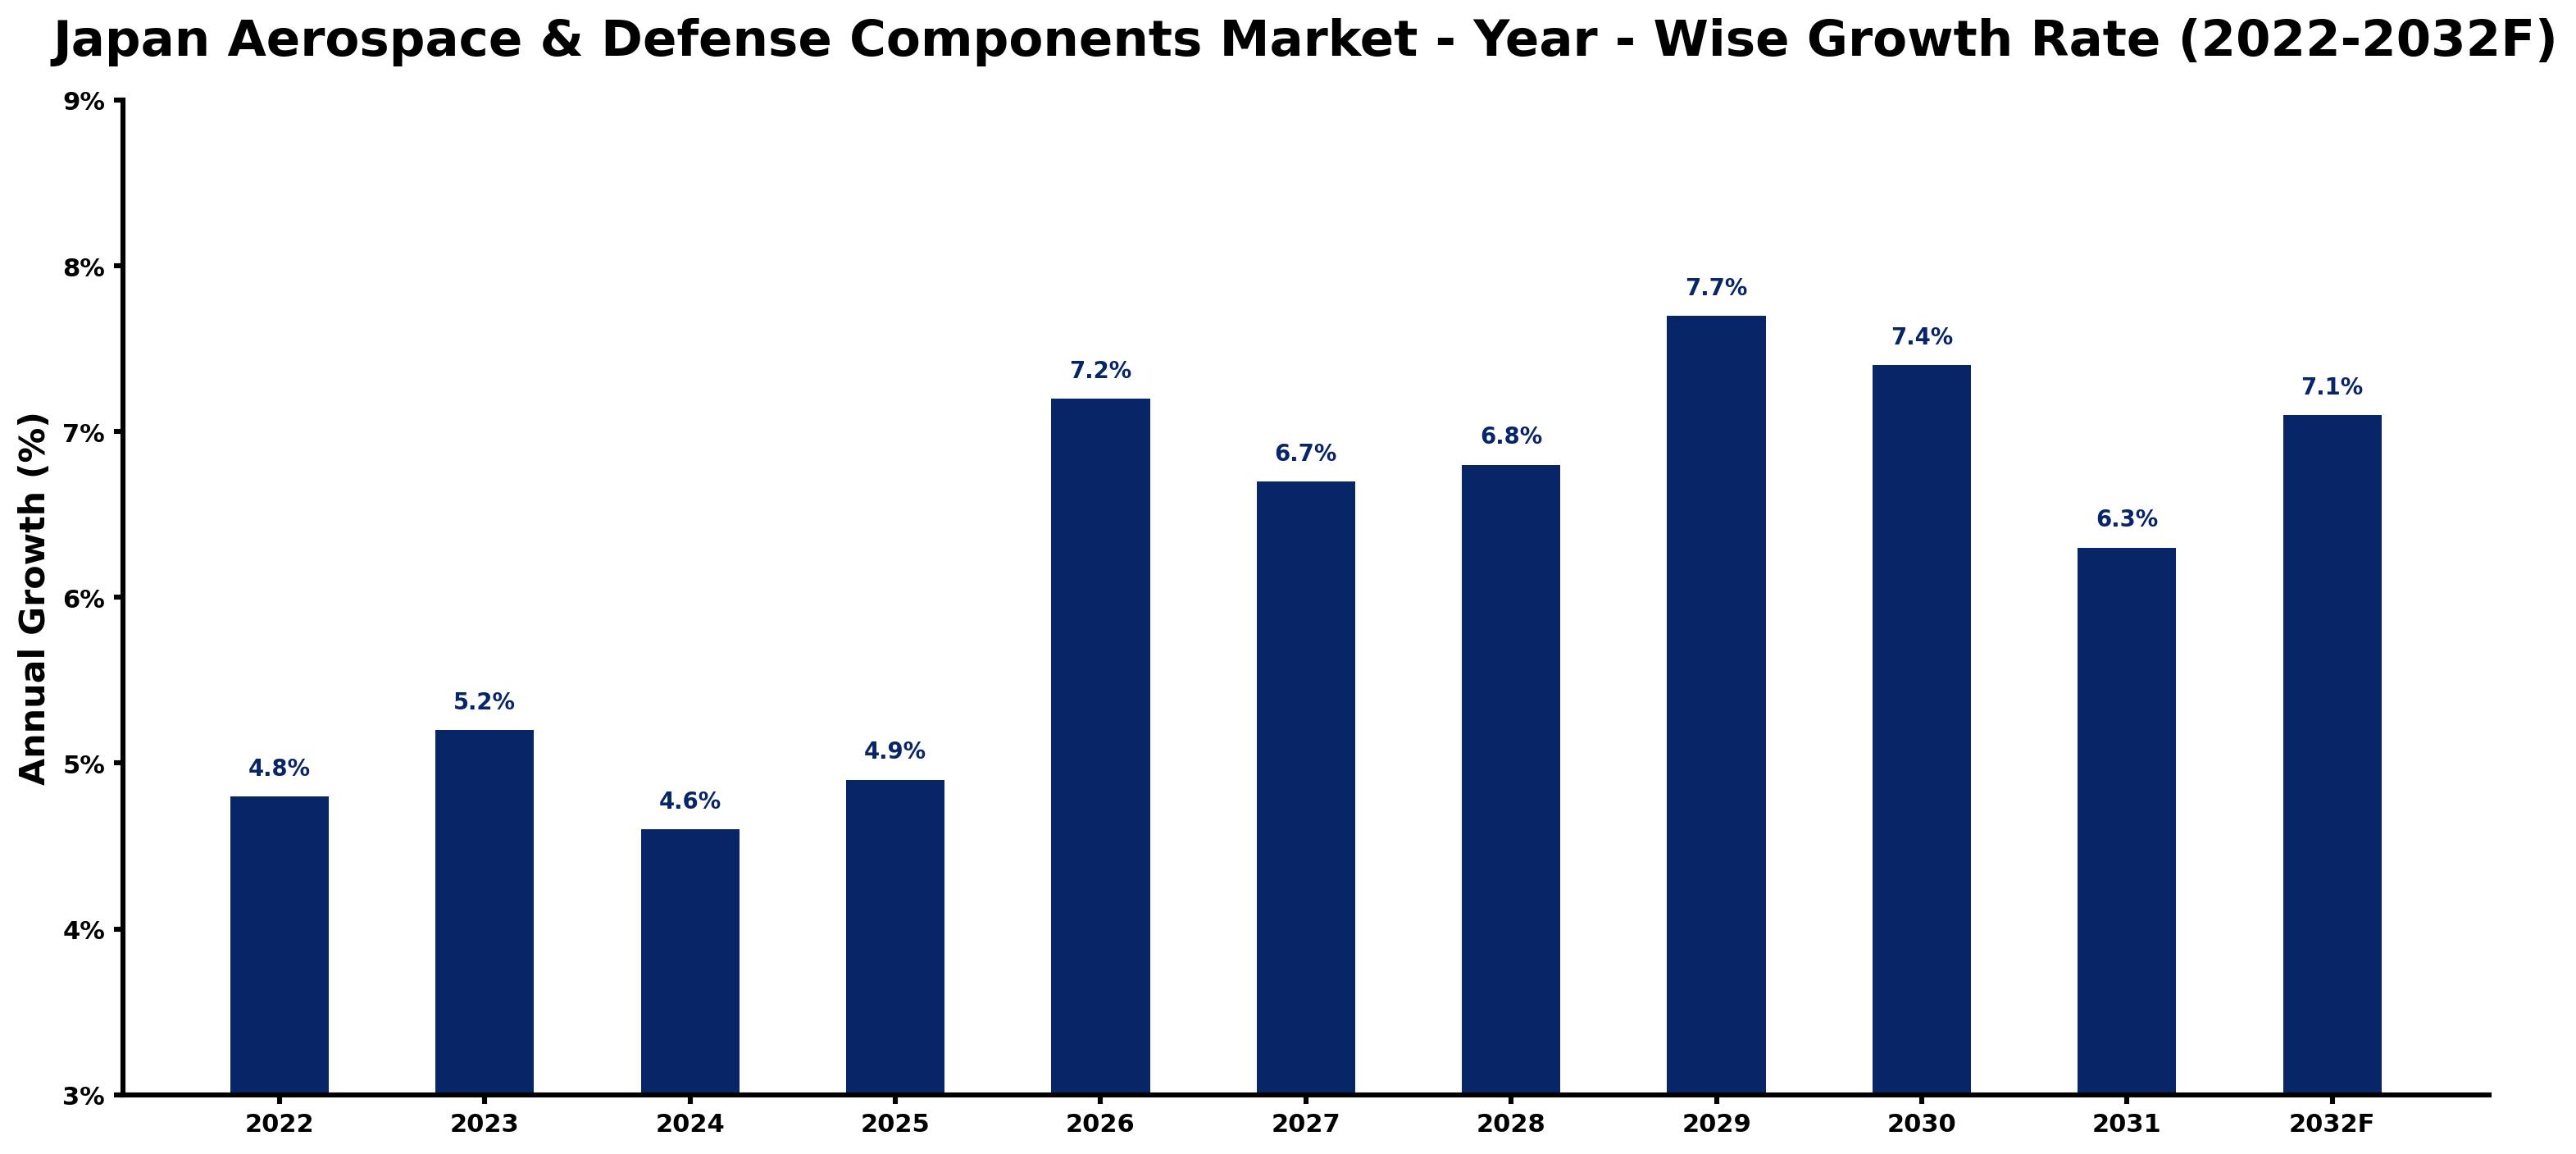
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.8 | The market showed steady growth due to increased domestic demand for aerospace components. |
| 2023 | 5.2 | Growth accelerated as Japan's defense modernization program gained momentum. |
| 2024 | 4.6 | Growth slowed slightly as manufacturers adjusted to supply chain challenges. |
| 2025 | 4.9 | The market rebounded with renewed investment in aerospace technologies and components. |
| 2026 | 7.2 | Growth is expected to rise as government contracts expand for advanced aerospace projects. |
| 2027 | 6.7 | A slight slowdown is projected as production capacities are optimised. |
| 2028 | 6.8 | Demand is expected to increase again as new technologies are integrated into aircraft designs. |
| 2029 | 7.7 | The market is projected to peak with substantial investments in aerospace technologies. |
| 2030 | 7.4 | Growth is expected to moderate as the market stabilises after rapid expansion. |
| 2031 | 6.3 | A further slowdown is expected as manufacturers focus on efficiency improvements. |
| 2032 | 7.1 | Growth is projected to pick up again as new defense contracts are awarded. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Aerospace & Defense Components Market Synopsis
Aerospace and defense components are critical parts used in aircraft and military equipment, produced using advanced materials and technologies. The Japan Aerospace & Defense Components Market is expanding due to strong domestic demand from manufacturers and government contracts. Valued at approximately 1.5 trillion yen, the aerospace industry is supported by over 200 manufacturers and suppliers, particularly in Tokyo and Nagoya. Key drivers of growth include the ongoing defense modernization program and investments in aerospace innovation.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased government spending on defense modernization | Driver | High | Government Contracts |
| Growing demand for advanced materials in aerospace manufacturing | Driver | High | Titanium Alloys |
| Rising need for high-performance components in military applications | Opportunity | High | Defense Equipment Vendors |
| Expansion of aircraft manufacturing capabilities in Japan | Opportunity | High | Aircraft Manufacturers |
| Supply chain disruptions affecting component availability | Restraint | High | Structural Components |
| High production costs impacting profit margins | Restraint | Medium | Avionics |
| Limited access to advanced manufacturing technologies | Challenge | High | Propulsion Systems |
| Competition from international suppliers | Challenge | Medium | Interior Components |
Evaluation of Drivers in Japan Aerospace & Defense Components Market (2026–2032)
Below are the drivers that matter most for revenue growth, with supporting evidence.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Government contracts for defense projects | Government Contracts | The Ministry of Defense allocated 5 billion yen for aerospace innovation in 2023, increasing procurement from local manufacturers. |
| Demand for lightweight and durable materials | Titanium Alloys | Japan's aerospace industry values titanium alloys for their strength-to-weight ratio, driving purchases from aircraft manufacturers. |
| Investment in advanced manufacturing technologies | Avionics | The adoption of ISO 9001 standards has improved production quality, leading to higher demand from OEMs. |
| Expansion of military aviation units | Defense Equipment Vendors | Military aviation units are increasing their procurement of advanced components to support operational capabilities. |
| Technological advancements in aerospace design | Composites | The integration of composites in aircraft structures drives demand for materials among manufacturers. |
Demand for lightweight and durable materials is rising, particularly for titanium alloys, which are essential for aircraft manufacturers. Investment in advanced manufacturing technologies is also increasing, as ISO 9001 standards improve production quality in avionics. The expansion of military aviation units leads to increased procurement of advanced components, while technological advancements in aerospace design drive demand for composites among manufacturers.
Evaluation of Restraints in Japan Aerospace & Defense Components Market
Several factors work against faster growth; the main ones are summarised below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions affecting component availability | Structural Components | Recent global supply chain issues have delayed deliveries, impacting production schedules for aircraft manufacturers. |
| High production costs impacting profit margins | Avionics | Rising costs of raw materials have squeezed profit margins for manufacturers, affecting pricing strategies. |
| Limited access to advanced manufacturing technologies | Propulsion Systems | The need for specialised equipment has restricted some manufacturers' ability to scale production effectively. |
| Regulatory compliance costs for aerospace components | Superalloys | Compliance with stringent safety and quality standards increases operational costs for producers. |
| Competition from international suppliers | Interior Components | Local manufacturers face pressure from lower-cost international suppliers, affecting market share. |
Japan Aerospace & Defense Components Market Challenges
Japan's aerospace components market faces regulatory hurdles that extend production timelines for manufacturers, delaying project completions for government contracts. Intense competition among over 200 local companies drives prices down, squeezing profit margins for suppliers and limiting their ability to invest in innovation. A shortage of skilled workers in advanced manufacturing techniques reduces production efficiency, causing delays that affect timely delivery to buyers. Rapid technological advancements necessitate continuous upgrades, which can incur high costs for producers, ultimately increasing operational expenses that impact pricing for buyers.
Trends in the Japan Aerospace & Defense Components Market
These developments are changing demand patterns in the Japan Aerospace & Defense Components Market.
- Shift towards Advanced Materials in Aerospace: Japan's aerospace sector is increasingly adopting advanced materials like composites for aircraft design. This shift began in 2020, driven by the need for lighter and more fuel-efficient aircraft. The Japan Aerospace Exploration Agency (JAXA) has been instrumental in promoting these technologies, improving competitiveness.
- Transition from Traditional Manufacturing to Additive Manufacturing: Since 2021, the aerospace industry has been moving towards additive manufacturing techniques. This change allows for more complex designs and reduced waste, as seen in new projects in Tokyo that focus on 3D printing aerospace components.
- Emergence of Smart Avionics Systems: The introduction of smart avionics systems has transformed aircraft navigation and control since 2022. The integration of AI technologies in avionics is being led by initiatives from the Japan Aerospace Industry Association, improving operational efficiency.
- Growing Focus on Sustainable Aerospace Practices: In 2023, Japan launched initiatives aimed at achieving carbon neutrality in aerospace production. This focus is clear in the Green Growth Strategy, promoting sustainable practices among manufacturers in Nagoya.
Investment Opportunities in the Japan Aerospace & Defense Components Market
The opportunities below stand out in the Japan Aerospace & Defense Components Market for new entrants and existing suppliers.
- Aircraft Manufacturers seeking lightweight materials: Aircraft manufacturers are increasingly looking for lightweight materials like composites to improve fuel efficiency. The Tokyo Metropolitan area is a key hub for these manufacturers, presenting opportunities for suppliers to enter the market.
- Defense Equipment Vendors needing advanced components: Defense equipment vendors are actively seeking advanced components to improve military capabilities. Collaborating with local manufacturers in Nagoya can facilitate access to this growing market segment.
- Government Contracts for aerospace solutions: The Japanese government is prioritising contracts for aerospace solutions, particularly in defense. Establishing joint ventures with local firms can provide a pathway to access these lucrative opportunities.
- Investment in Aerospace Innovation Facilities: Investment in aerospace innovation facilities is on the rise, particularly in Tokyo. Suppliers can enter this market by partnering with local firms to develop new technologies.
Government Initiatives in the Japan Aerospace & Defense Components Market
The Economic Security Promotion Act of 2022 supports supply-chain resilience for critical products, including aerospace components. This law mandates that producers ensure the reliability of their supply chains, which directly impacts the procurement processes of manufacturers. In 2023, the Ministry of Defense allocated 5 billion yen for aerospace innovation, further supporting the sector's growth potential.
The Japan Aerospace Exploration Agency (JAXA) oversees the funding of aerospace technology development projects. In 2023, JAXA approved multiple initiatives aimed at improving domestic capabilities, with a focus on advanced materials and manufacturing techniques. This support is vital for improving the production capabilities of aerospace and defense components.
Future Insight of the Japan Aerospace & Defense Components Market
Investment in aerospace innovation will surge, with the Ministry of Defense allocating 5 billion yen for aerospace innovation in 2023, creating substantial demand for advanced components. By 2032, the introduction of new manufacturing technologies will improve production capabilities, benefiting both buyers and suppliers. Collaboration with the Japan Aerospace Exploration Agency will accelerate developments in additive manufacturing, boosting efficiency. The focus on advanced aerospace technologies will drive growth, resulting in better quality and reliability in the components supplied to the market.
Market Segmentation Analysis
Japan Aerospace & Defense Components Market report covers a detailed analysis of the following market segments:
By Component Type – Structural Components Lead, Avionics Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, with 45% of component type revenue in 2025, Structural Components was the largest category. Structural components are essential for ensuring the integrity and safety of aircraft, making them vital for manufacturers. The strong demand from over 200 aircraft manufacturers in Japan solidifies their leading position in the market. Over 2026–2032, Avionics are expected to post the fastest growth, at a CAGR of 9.7%. Avionics is witnessing rapid growth due to an increasing emphasis on advanced navigation and control systems in modern aircraft. The launch of new defense modernization programmes in 2023 is expected to further accelerate this segment's expansion. Suppliers should prioritise avionics offerings to capitalise on the increasing demand.
By Material Type – Titanium Alloys Lead, Composites Expected to Grow Fastest
Titanium Alloys held 35% of the Japan Aerospace & Defense Components Market by material type in 2025. Titanium alloys are extensively utilised in the aerospace sector for their superior strength-to-weight ratio, making them a preferred choice for various applications. Their widespread use in aircraft manufacturing across Japan reinforces their dominant market share. Composites are projected to grow fastest, at a CAGR of 10.0% during 2026–2032. Composites are gaining traction as they are crucial for developing lightweight structures in modern aircraft, which improves fuel efficiency. The ongoing focus on advanced materials in aerospace design is projected to drive their rapid growth. Buyers should consider sourcing more composite materials to meet the rising demand for lightweight aerospace solutions.
By Distribution Channel – Government Contracts Lead, OEMs Expected to Grow Fastest
Government Contracts accounted for 42% of the market by distribution channel in 2025. Government contracts represent a major revenue source for defense components, reflecting strong governmental backing for aerospace initiatives. The allocation of 5 billion yen for aerospace innovation in 2023 highlights the significance of this distribution channel. The quickest growth will come from OEMs, forecast to expand at a CAGR of 8.7% between 2026 and 2032. OEMs are experiencing swift growth as they are the primary manufacturers of aerospace components, quickly adapting to the increasing production requirements of aircraft manufacturers. Their central role in the supply chain ensures continued rapid expansion. Suppliers need to strengthen partnerships with OEMs to establish a presence in the expanding aerospace market.
By End User – Aircraft Manufacturers Lead, Defense Equipment Vendors Expected to Grow Fastest
In 2025, Aircraft Manufacturers led the end user split with a 40% share. Aircraft manufacturers are the primary consumers of aerospace components, driving substantial demand within the sector. Their strong presence in key regions like Tokyo and Nagoya ensures a robust market for these components. Defense Equipment Vendors are set to record the highest CAGR in this split, 9.0% over 2026–2032. Defense equipment vendors are significantly increasing their procurement of aerospace components as military applications expand. The focus on advanced aerospace technologies in defence modernization initiatives is likely to further accelerate this growth. Suppliers should strategically target defense equipment vendors to take advantage of the rising demand for military aerospace components.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Aerospace & Defense Components Market Outlook
- Market Size of Japan Aerospace & Defense Components Market, 2025
- Forecast of Japan Aerospace & Defense Components Market, 2032
- Historical Data and Forecast of Japan Aerospace & Defense Components Revenues & Volume for the Period 2022-2032F
- Japan Aerospace & Defense Components Market Trend Evolution
- Japan Aerospace & Defense Components Market Drivers and Challenges
- Japan Aerospace & Defense Components Price Trends
- Japan Aerospace & Defense Components Porter's Five Forces
- Japan Aerospace & Defense Components Industry Life Cycle
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Component Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Structural Components for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Avionics for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Propulsion Systems for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Interior Components for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Material Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Titanium Alloys for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Semiconductors for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Superalloys for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Composites for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By OEMs for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Direct Sales for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Government Contracts for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Industrial Suppliers for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Aircraft Manufacturers for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Defense Equipment Vendors for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Military Aviation Units for the Period 2022-2032F
- Historical Data and Forecast of Japan Aerospace & Defense Components Market Revenues & Volume By Commercial Airlines for the Period 2022-2032F
- Japan Aerospace & Defense Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Japan Aerospace & Defense Components Top Companies Market Share
- Japan Aerospace & Defense Components Competitive Benchmarking By Technical and Operational Parameters
- Japan Aerospace & Defense Components Company Profiles
- Japan Aerospace & Defense Components Key Strategic Recommendations
Market Covered
The following segment groups are covered in the report.
By Component Type
- Structural Components
- Avionics
- Propulsion Systems
- Interior Components
By Material Type
- Titanium Alloys
- Semiconductors
- Superalloys
- Composites
By Distribution Channel
- OEMs
- Direct Sales
- Government Contracts
- Industrial Suppliers
By End User
- Aircraft Manufacturers
- Defense Equipment Vendors
- Military Aviation Units
- Commercial Airlines






































