Japan Aircraft Braking Components Market Size & Growth Rate
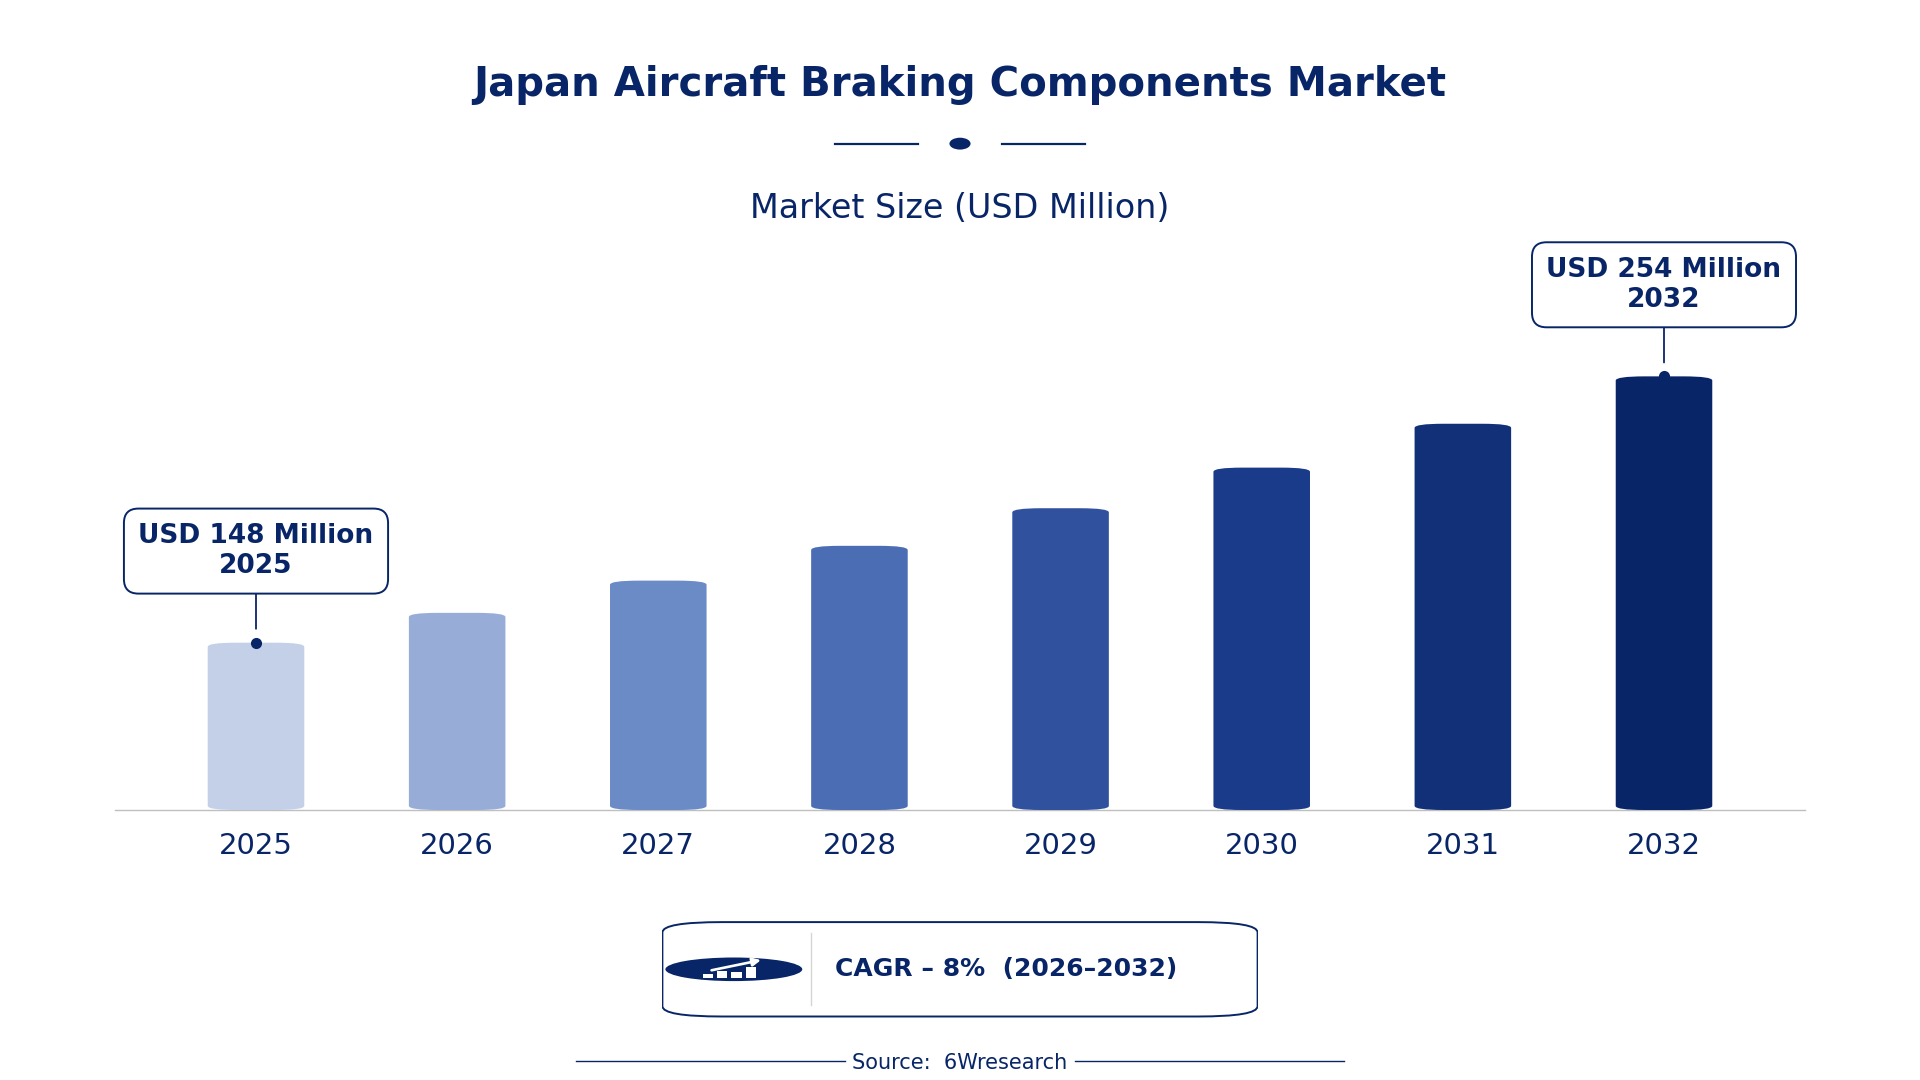
According to 6Wresearch internal database and industry insights, the Japan Aircraft Braking Components Market was valued at USD 148 Million in 2025 and is projected to reach USD 254 Million by 2032, growing at a CAGR of approximately 8% during 2026–2032.
Japan Aircraft Braking Components Market Highlights
| Report Metric | Details |
| Report Name | Japan Aircraft Braking Components Market (2026-2032) |
| Market Size 2025 | USD 148 Million |
| Market Size 2032 | USD 254 Million |
| Absolute Growth 2025–2032 | USD 106 Million |
| CAGR 2026–2032 | 8% |
| Peak Annual Growth | 8.9% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Brake Pads (50% share) |
| Leading Material Type, 2025 | Carbon Composite (39% share) |
| Leading Distribution Channel, 2025 | Aircraft Part Distributors (36% share) |
| Leading End User, 2025 | Aviation MRO Facilities (53% share) |
| Fastest-Growing Component Type | Brake Discs (11.0% CAGR) |
| Fastest-Growing Material Type | Steel Alloy (11.5% CAGR) |
| Fastest-Growing Distribution Channel | OEM Partners (10.3% CAGR) |
| Fastest-Growing End User | Airplane Manufacturers (10.1% CAGR) |
| Growing Sector | Airplane Manufacturers |
| Key End Users | Aviation MRO Facilities, Airplane Manufacturers, Defense Aviation Units, Civil Aircraft OEMs |
Japan Aircraft Braking Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
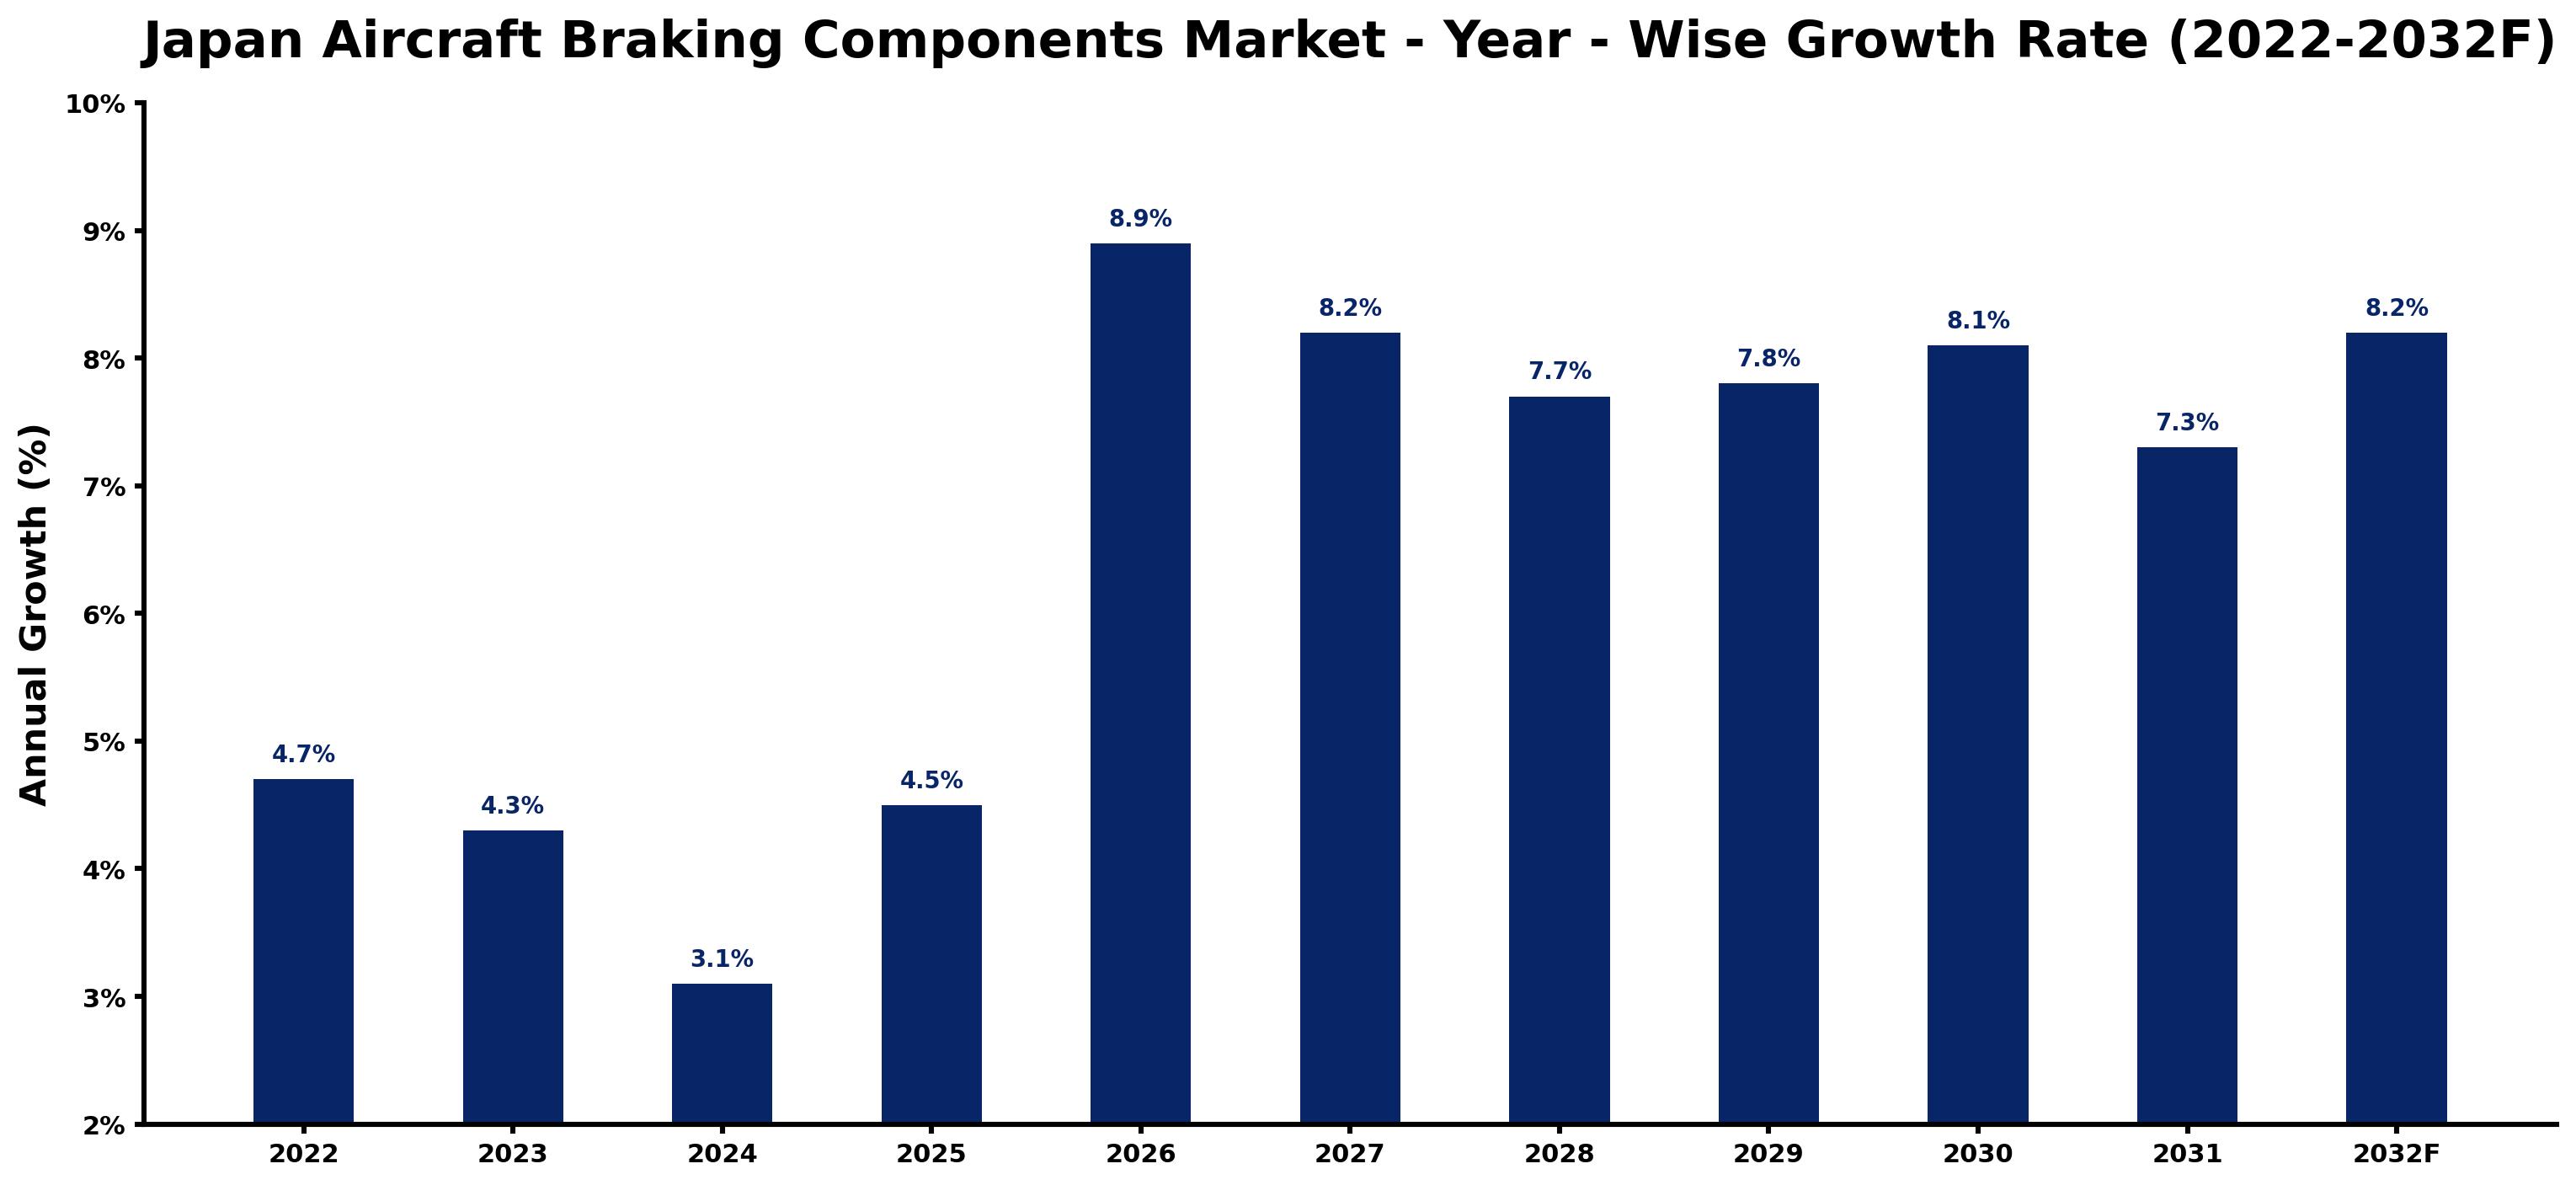
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.7 | The aviation market showed steady demand due to ongoing MRO activities and a stable number of flights. |
| 2023 | 4.3 | Demand growth slowed slightly as the market adjusted to previous high activity levels in MRO services. |
| 2024 | 3.1 | Market growth continued to decelerate as the aviation sector faced challenges in supply chain management. |
| 2025 | 4.5 | Increased military spending on aircraft upgrades spurred faster growth in the aviation components market. |
| 2026 | 8.9 | The peak growth rate is expected to be driven by investments in new aircraft and modernization of existing fleets. |
| 2027 | 8.2 | A slight slowdown is projected as the market stabilises after the peak growth year. |
| 2028 | 7.7 | Demand is expected to remain strong, although growth rates will begin to moderate as the market matures. |
| 2029 | 7.8 | The market is projected to experience renewed interest due to rising commercial flight numbers and MRO activities. |
| 2030 | 8.1 | Continued investments in aviation infrastructure will support a rebound in growth rates. |
| 2031 | 7.3 | Growth is expected to slow as the market begins to normalise after several years of rapid expansion. |
| 2032 | 8.2 | A resurgence in military and commercial aviation demand is projected to drive growth higher. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Aircraft Braking Components Market Synopsis
Aircraft braking components are critical safety devices in aviation, ensuring safe landings and stops. Made from advanced materials like carbon composites and steel alloys, they are vital in both commercial and military aircraft. The Japan Aircraft Braking Components Market is expanding, driven by a growing number of commercial flights and increased military budgets for aircraft upgrades. The Tokyo metropolitan area serves as a key hub for MRO facilities, which further boosts demand for these components, with annual demand influenced by the increasing number of flights.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing number of commercial flights | Driver | High | Brake Pads |
| Increased military aircraft upgrades | Driver | High | Brake Discs |
| Rising demand for lightweight components | Opportunity | High | Carbon Composite |
| Expansion of MRO services in urban areas | Opportunity | Medium | Aviation MRO Facilities |
| High certification standards for manufacturers | Restraint | High | Steel Alloy |
| Supply chain disruptions affecting availability | Restraint | Medium | Actuators |
| Rising costs of raw materials | Challenge | High | Anti-Skid Units |
| Technological advancements requiring constant updates | Challenge | Medium | Electronic |
Evaluation of Drivers in Japan Aircraft Braking Components Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increase in domestic air travel | Brake Pads | The annual demand for aircraft braking components is influenced by the growing number of commercial flights, leading to higher purchases by aviation MRO facilities. |
| Military budget allocations for upgrades | Brake Discs | Japan's defense budget in 2023 allocated funds for upgrading military aircraft, driving demand for critical braking components. |
| Shift towards lightweight materials | Carbon Composite | Carbon composite brake pads are increasingly used in new aircraft designs, prompting manufacturers to invest in these advanced materials. |
| Expansion of MRO facilities in Tokyo | Aviation MRO Facilities | The Tokyo metropolitan area is a key hub for aviation MRO facilities, increasing demand for aircraft braking components. |
| Adoption of advanced braking technologies | Actuators | Technological advancements in braking systems are pushing manufacturers to integrate more sophisticated actuators into their designs. |
Behind the steady rise in orders sits the increasing domestic air travel, which reached approximately 90 million passengers in 2023, boosting demand for braking components. Budget allocations for military aircraft upgrades, amounting to JPY 6 trillion in 2023, are driving purchases of critical braking systems. The shift towards lightweight materials is evident as carbon composite brake pads have gained traction, with a substantial increase in their usage in new aircraft designs. The expansion of MRO facilities in the Tokyo region, which has seen a notable rise in operations, further supports the demand for aircraft braking components. The adoption of advanced braking technologies is prompting manufacturers to invest in sophisticated actuators, improving system performance.
Evaluation of Restraints in Japan Aircraft Braking Components Market
These restraints slow adoption and weigh on supplier margins.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions due to reliance on imported materials | Brake Pads | This reliance causes delays in production timelines for manufacturers, affecting timely deliveries to aviation MRO facilities. |
| Skills shortages in advanced manufacturing techniques | Brake Discs | These shortages hinder local producers from meeting the growing demand for high-performance braking solutions, impacting overall market supply. |
| Rapid technological advancements outpacing supplier capabilities | Actuators | Some suppliers struggle to keep up, creating potential safety risks for buyers relying on outdated technologies. |
| Rising costs associated with compliance to ISO 9001 certification | Carbon Composite | Compliance increases operational expenses for manufacturers, impacting their pricing strategies and raising costs for airlines. |
| Limited domestic production capacity for advanced components | Anti-Skid Units | This limitation restricts the ability to meet the increasing demand, affecting the overall market supply chain. |
Japan Aircraft Braking Components Market Challenges
Japan's aviation market faces supply chain disruptions due to reliance on imported materials, causing production delays for manufacturers that can extend timelines by up to three months. Local producers encounter skills shortages in advanced manufacturing techniques, limiting their ability to meet the rising demand for high-performance braking systems. Some suppliers struggle to keep pace with rapid technological advancements, which raises safety concerns for buyers and could lead to increased maintenance costs. Compliance with ISO 9001 certification incurs operational expenses that can inflate prices for airlines and MRO service providers, potentially increasing costs by 15%.
Trends in the Japan Aircraft Braking Components Market
Below are the shifts with the largest effect on the Japan Aircraft Braking Components Market.
- Shift from Steel to Carbon Composite Materials: The Tokyo International Air Show in 2023 showcased the shift towards carbon composite materials in aircraft braking systems, with increased adoption. This transition enables manufacturers to create lighter and more efficient components.
- Emergence of Advanced Braking Technologies: Since 2023, advancements in braking technologies have led to the integration of electronic systems in aircraft. These developments enhance safety and performance, resulting in a notable rise in demand for actuators.
- Growth in MRO Facilities in Tokyo: The number of aviation MRO facilities in the Tokyo metropolitan area has grown considerably since 2023. This increase is driven by rising maintenance needs from the expanding fleet of commercial aircraft.
- Increased Collaboration in R&D: The Japan Aerospace Exploration Agency has partnered with manufacturers since 2023 to develop new braking solutions. This collaboration aims to improve the efficiency and reliability of braking systems.
Investment Opportunities in the Japan Aircraft Braking Components Market
The openings below show where demand in the Japan Aircraft Braking Components Market is visible and how suppliers can enter.
- Supply of Carbon Composite Brake Pads: The demand for carbon composite brake pads is on the rise, with projected growth in new aircraft designs. Suppliers can target aviation MRO facilities for partnerships to satisfy this demand.
- Investment in Advanced Actuators: With the emergence of advanced braking technologies, there is an increasing need for sophisticated actuators. Manufacturers should invest in R&D to create effective solutions for the aviation sector.
- Expansion of MRO Facilities: The MRO facilities in the Tokyo region are expanding, presenting opportunities for suppliers to provide components and services. Collaborating with local partners can facilitate market entry.
- Development of Lightweight Braking Systems: The shift towards lightweight braking systems offers opportunities for manufacturers to innovate. Targeting aircraft manufacturers for collaborations can ease entry into this growing market.
Government Initiatives in the Japan Aircraft Braking Components Market
The Ministry of Economy, Trade and Industry supports the growth of the aviation sector in Japan through various initiatives. These efforts include funding for research and development projects and assistance for manufacturers to improve their competitiveness in the global market. The Civil Aviation Bureau of Japan establishes regulatory standards for aircraft safety, ensuring compliance with safety regulations that impact both manufacturers and buyers.
The Japan Aerospace Exploration Agency collaborates with manufacturers to support research and development in aviation technologies. This partnership provides funding for projects aimed at enhancing braking systems, benefiting both producers and buyers.
Future Insight of the Japan Aircraft Braking Components Market
Investment in aviation technology will create a pipeline for new aircraft braking solutions by 2032. The increasing number of commercial flights will drive demand for braking components, compelling suppliers to improve their production capabilities. Collaborations between government agencies and manufacturers will establish new standards that enhance efficiency and reliability in braking systems. By 2032, the integration of advanced materials in braking systems will reduce weight and improve fuel efficiency for airlines, benefiting both buyers and suppliers.
Market Segmentation Analysis
Japan Aircraft Braking Components Market report covers a detailed analysis of the following market segments:
By Component Type – Brake Pads Lead, Brake Discs Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, the largest component type category in 2025 was Brake Pads, at 50% of revenue. Brake pads hold the largest share due to their critical role in ensuring aircraft safety and performance. Their widespread use in both commercial and military aircraft highlights their essential function in the aviation sector. Brake Discs are projected to grow fastest, at a CAGR of 11.0% during 2026–2032. Brake discs are experiencing rapid growth as they are crucial for the effective operation of braking systems. The increase in commercial flights in Japan has led to a notable rise in demand for these components. Suppliers should focus on enhancing brake disc production to align with the growing market demand.
By Material Type – Carbon Composite Leads, Steel Alloy Expected to Grow Fastest
Carbon Composite accounted for 39% of the market by material type in 2025. Carbon composite materials dominate the market because they are favoured for their lightweight and high-performance characteristics in braking components. This preference is particularly pronounced in modern aircraft designs that prioritise efficiency and weight reduction. Over 2026–2032, Steel Alloy is expected to post the fastest growth, at a CAGR of 11.5%. Steel alloy materials are witnessing the fastest growth owing to their strength and durability in braking systems. The ongoing upgrades of military aircraft in Japan are significantly driving the demand for steel alloy components. Manufacturers need to improve their steel alloy product lines to meet the increasing demands of the aviation sector.
By Distribution Channel – Aircraft Part Distributors Lead, OEM Partners Expected to Grow Fastest
Aircraft Part Distributors held 36% of the Japan Aircraft Braking Components Market by distribution channel in 2025. Aircraft part distributors lead the market as they effectively supply components to end users, ensuring timely access to essential parts. Their well-established distribution networks are vital for supporting the operational needs of aviation MRO facilities. The quickest growth will come from OEM Partners, forecast to expand at a CAGR of 10.3% between 2026 and 2032. OEM partners are rapidly gaining traction as they integrate components directly into new aircraft, reflecting a shift towards streamlined production. This trend is expected to continue as manufacturers seek to enhance operational efficiency. Distributors must strengthen their partnerships with OEMs to maintain a competitive edge in the market.
By End User – Aviation MRO Facilities Lead, Airplane Manufacturers Expected to Grow Fastest
With 53% of end user revenue in 2025, Aviation MRO Facilities was the largest category. Aviation MRO facilities represent the largest segment due to their responsibility for maintaining and repairing aircraft braking systems. Their crucial role in ensuring safety and compliance drives consistent demand for braking components. Airplane Manufacturers are set to record the highest CAGR in this split, 10.1% over 2026–2032. Airplane manufacturers are the fastest-growing segment as they incorporate braking components into new aircraft designs. The rising production rates of commercial aircraft in Japan are significantly contributing to this growth. Suppliers should tailor their offerings to meet the specific needs of airplane manufacturers to leverage this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Aircraft Braking Components Market Outlook
- Market Size of Japan Aircraft Braking Components Market, 2025
- Forecast of Japan Aircraft Braking Components Market, 2032
- Historical Data and Forecast of Japan Aircraft Braking Components Revenues & Volume for the Period 2022-2032F
- Japan Aircraft Braking Components Market Trend Evolution
- Japan Aircraft Braking Components Market Drivers and Challenges
- Japan Aircraft Braking Components Price Trends
- Japan Aircraft Braking Components Porter's Five Forces
- Japan Aircraft Braking Components Industry Life Cycle
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Component Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Brake Pads for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Brake Discs for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Actuators for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Anti-Skid Units for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Material Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Carbon Composite for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Steel Alloy for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Hydraulic for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Electronic for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Aircraft Part Distributors for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By OEM Partners for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Online Aviation Marketplaces for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By System Integrators for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Aviation MRO Facilities for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Airplane Manufacturers for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Defense Aviation Units for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Braking Components Market Revenues & Volume By Civil Aircraft OEMs for the Period 2022-2032F
- Japan Aircraft Braking Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Japan Aircraft Braking Components Top Companies Market Share
- Japan Aircraft Braking Components Competitive Benchmarking By Technical and Operational Parameters
- Japan Aircraft Braking Components Company Profiles
- Japan Aircraft Braking Components Key Strategic Recommendations
Market Covered
The report covers the following segments.
By Component Type
- Brake Pads
- Brake Discs
- Actuators
- Anti-Skid Units
By Material Type
- Carbon Composite
- Steel Alloy
- Hydraulic
- Electronic
By Distribution Channel
- Aircraft Part Distributors
- OEM Partners
- Online Aviation Marketplaces
- System Integrators
By End User
- Aviation MRO Facilities
- Airplane Manufacturers
- Defense Aviation Units
- Civil Aircraft OEMs






































