Japan Aircraft Engine Starter Market Size & Growth Rate
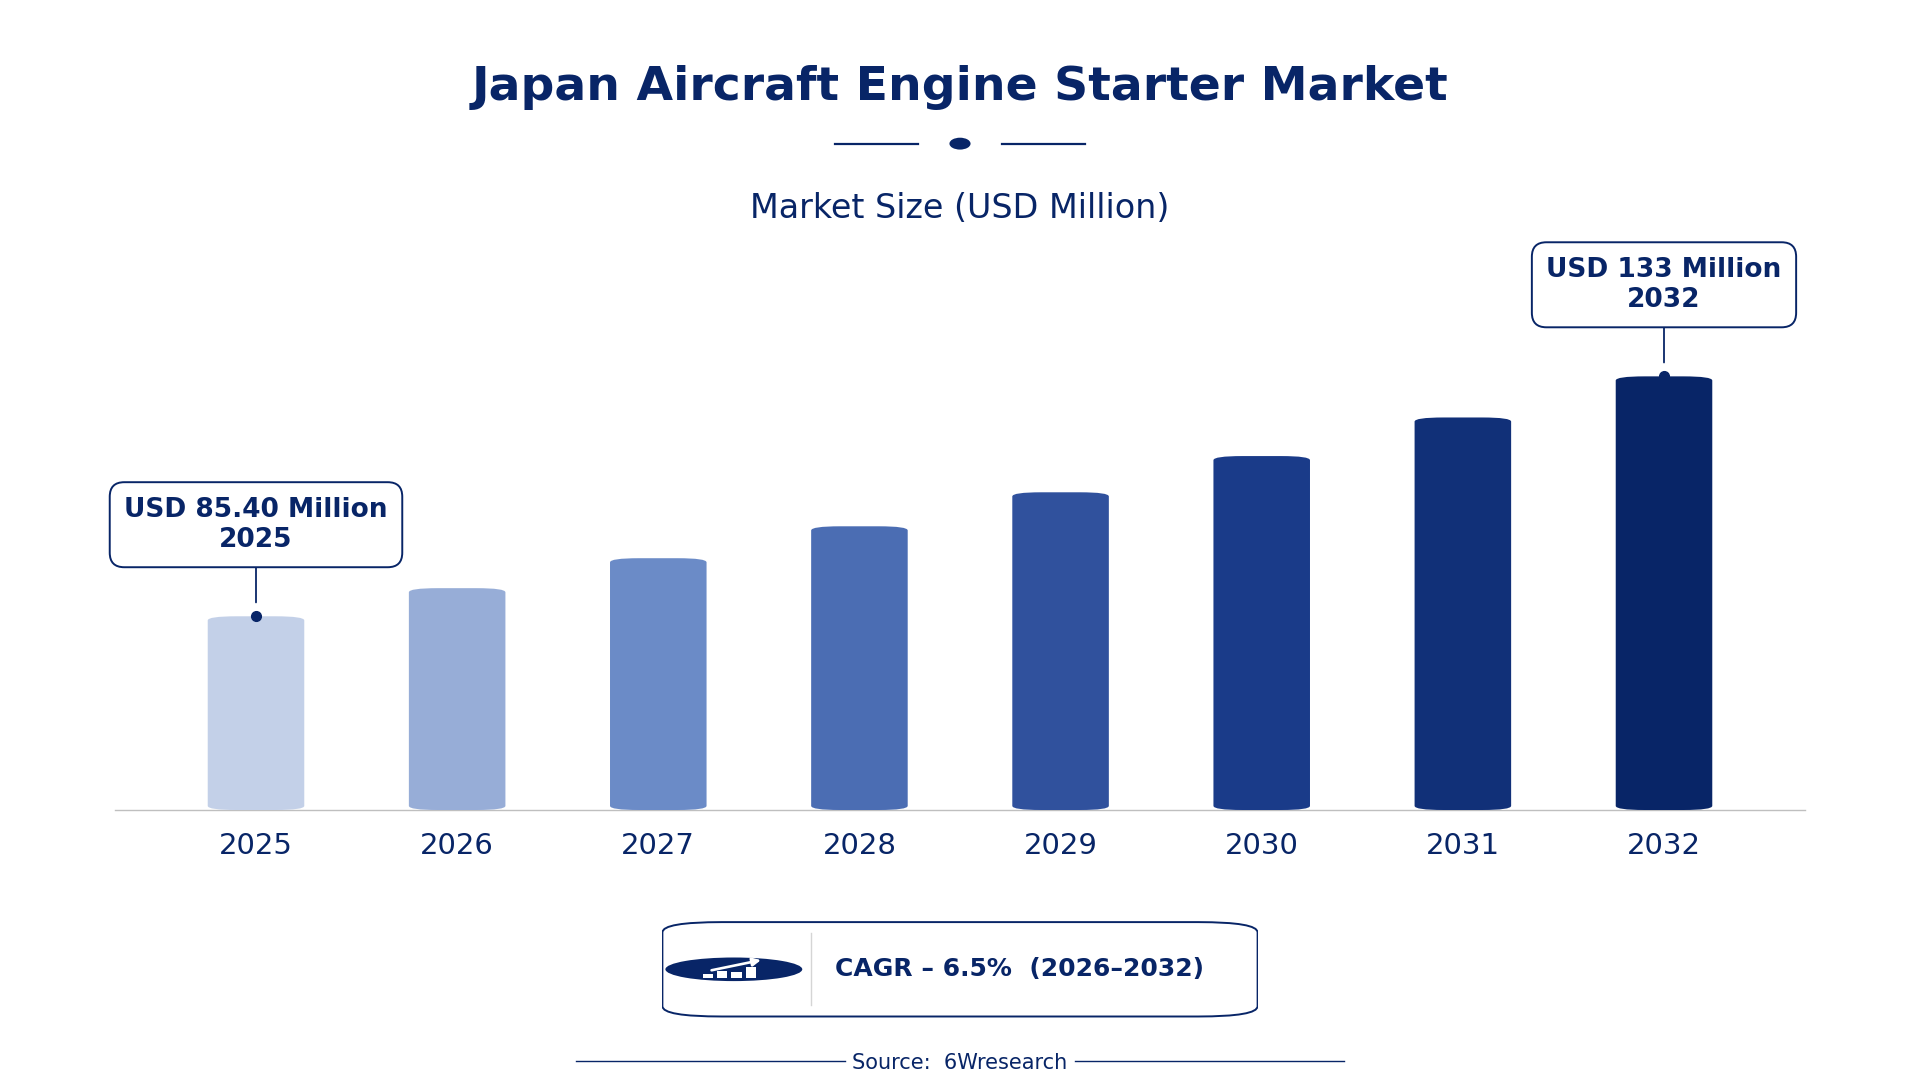
According to 6Wresearch internal database and industry insights, the Japan Aircraft Engine Starter Market was valued at USD 85.40 Million in 2025 and is projected to reach USD 133 Million by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
Japan Aircraft Engine Starter Market Highlights
| Report Metric | Details |
| Report Name | Japan Aircraft Engine Starter Market (2026-2032) |
| Market Size 2025 | USD 85.40 Million |
| Market Size 2032 | USD 133 Million |
| Absolute Growth 2025–2032 | USD 47.60 Million |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 7.1% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Electric Starter Systems (44% share) |
| Leading Starter Technology, 2025 | DC Motor (51% share) |
| Leading Distribution Channel, 2025 | Direct Sales (37% share) |
| Leading End User, 2025 | Commercial Aircraft OEMs (44% share) |
| Fastest-Growing Product Type | Air Turbine Starters (9.5% CAGR) |
| Fastest-Growing Starter Technology | Pneumatic (10.0% CAGR) |
| Fastest-Growing Distribution Channel | Industrial Suppliers (8.1% CAGR) |
| Fastest-Growing End User | Military Aviation Units (8.3% CAGR) |
| Growing Sector | Aerospace Manufacturing |
| Key End Users | Commercial Aircraft OEMs, Military Aviation Units, Helicopter Operators, Private Jets Manufacturers |
Japan Aircraft Engine Starter Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
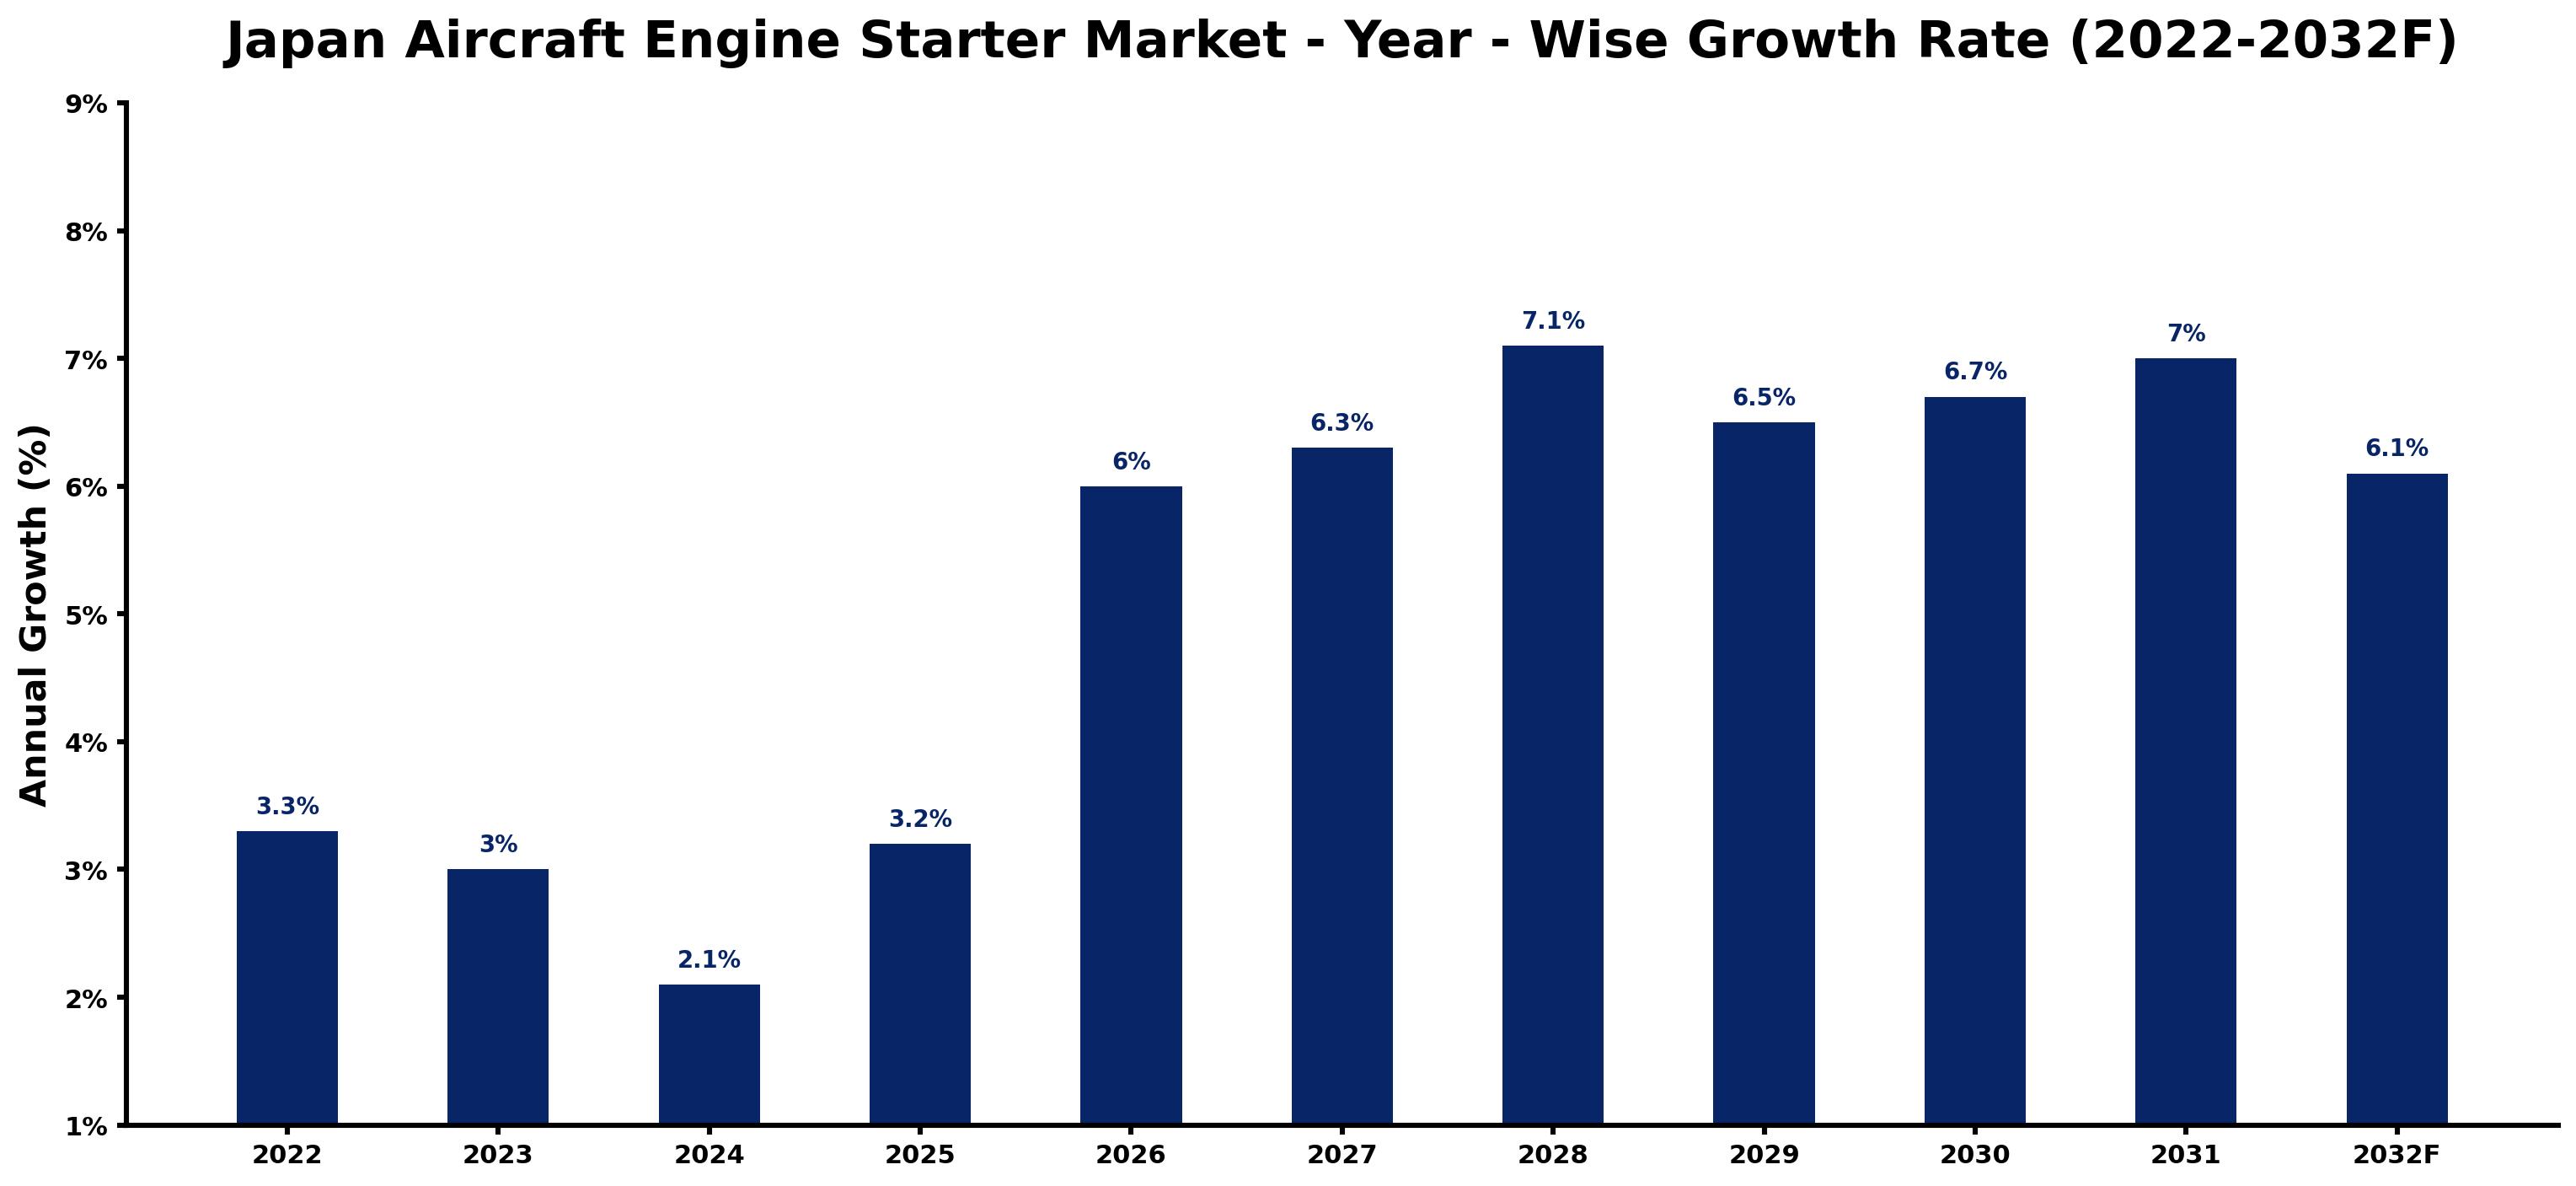
The yearly estimates that follow link every growth rate to its principal driver, so readers can see why the pace changed in each period.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.3 | The market experienced steady growth, driven by strong demand from military aviation units. |
| 2023 | 3.0 | Growth slowed as the market adjusted to new standards and technologies being introduced. |
| 2024 | 2.1 | Demand continued to grow, albeit at a slower pace as manufacturers adapted to changing industry requirements. |
| 2025 | 3.2 | Growth accelerated due to increased orders from commercial aircraft OEMs for new models. |
| 2026 | 6.0 | A surge in demand is expected as electric starter systems become more prevalent in new aircraft. |
| 2027 | 6.3 | Growth will continue as military aviation units seek advanced starter systems for modernization. |
| 2028 | 7.1 | The market will peak with substantial orders for integrated starter-generator technologies from OEMs. |
| 2029 | 6.5 | Growth will slow slightly as the market stabilises after the peak in 2028. |
| 2030 | 6.7 | Demand will rise again as new military projects initiate requirements for advanced starters. |
| 2031 | 7.0 | The market will continue to grow with ongoing investments in aerospace technology and innovation. |
| 2032 | 6.1 | Growth will slow as the market matures, reflecting established demand patterns. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Aircraft Engine Starter Market Synopsis
Aircraft engine starters are essential devices that initiate aircraft engine operations, combining electrical and mechanical components for high reliability. The Japan Aircraft Engine Starter Market is expanding due to increasing demand from commercial aircraft OEMs and military aviation units, driven by technological advancements such as electric starter systems and integrated starter-generators. With a population of approximately 126 million, Japan's aviation sector supports both domestic use and international exports, creating a thriving environment for manufacturers and suppliers.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand for electric starter systems due to their reliability and efficiency. | Driver | High | Electric Starter Systems |
| Increased military aviation projects necessitating advanced starter systems. | Driver | High | Air Turbine Starters |
| Growing need for integrated starter-generator technology among commercial aircraft manufacturers. | Opportunity | High | Integrated Starter-Generator |
| Expansion of aerospace manufacturing hubs in the Tokyo region attracting investments. | Opportunity | Medium | Electric Starter Systems |
| Regulatory compliance with JIS standards impacting production timelines. | Restraint | High | Electric Starter Systems |
| Limited application of hydraulic starters in modern aircraft designs. | Restraint | Medium | Hydraulic Starters |
| High production costs affecting pricing strategies for manufacturers. | Challenge | High | Electric Starter Systems |
| Capacity constraints in meeting increasing military orders for new aircraft. | Challenge | Medium | Air Turbine Starters |
Evaluation of Drivers in Japan Aircraft Engine Starter Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military spending on advanced aviation technologies | Air Turbine Starters | In 2023, Japan's defense budget included funding for modernization, driving demand for advanced starters. |
| Growing adoption of electric starter systems in new aircraft models | Electric Starter Systems | Electric starter systems accounted for a large share of new aircraft introduced in 2023. |
| Rising orders from commercial aircraft manufacturers for reliable starters | Integrated Starter-Generator | Commercial Aircraft OEMs represented 44% of the market share in 2025, boosting starter orders. |
| Technological advancements in starter systems improving performance | Integrated Starter-Generator | The Integrated Starter-Generator technology is gaining traction among manufacturers, increasing demand. |
| Expansion of aerospace manufacturing hubs in Tokyo | Electric Starter Systems | The Tokyo region is a key aerospace hub, attracting investments and increasing production capacity. |
Behind the steady rise in orders sits increased military spending on aviation technologies, with Japan's defense budget for 2023 including funding for modernization. The growing adoption of electric starter systems in new aircraft models is clear, as they accounted for a large share in 2023. Orders from commercial aircraft manufacturers further boost starter demand, with these OEMs representing a substantial portion of the market. Advancements in integrated starter-generators improve performance, making them increasingly popular among manufacturers. The expansion of aerospace manufacturing hubs in Tokyo attracts investments, thereby increasing production capacity for starters.
Evaluation of Restraints in Japan Aircraft Engine Starter Market
These are the pressures that could keep growth below its potential.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Strict compliance with JIS standards affecting production timelines. | Electric Starter Systems | Manufacturers must adhere to JIS standards, which can delay production schedules. |
| Limited application of hydraulic starters in modern aircraft designs. | Hydraulic Starters | Hydraulic starters are less common due to the shift towards electric systems in new aircraft. |
| High production costs impacting pricing strategies for manufacturers. | Electric Starter Systems | Manufacturers face rising costs, which can limit competitive pricing in the market. |
| Capacity constraints in meeting increasing military orders for new aircraft. | Air Turbine Starters | Manufacturers struggle to scale up production to meet the surge in military demand. |
| Dependence on specific technologies that may not be widely adopted. | Integrated Starter-Generator | The reliance on integrated starter-generators may hinder flexibility in production. |
Japan Aircraft Engine Starter Market Challenges
In 2023, military aviation units in Japan reported urgent needs for advanced starter devices, leading to increased procurement costs of approximately 15% for defence contractors. Intense competition among suppliers results in price wars, which can erode margins and delay product availability for buyers in the aerospace sector. The shift towards electric starter technologies in new aircraft models creates a technology gap, causing production delays of up to six months for manufacturers reliant on traditional components. Stringent regulations from the Japan Civil Aviation Bureau impose compliance costs of about ¥500 million that hinder operational efficiency for producers, complicating supply chains further.
Trends in the Japan Aircraft Engine Starter Market
These developments are changing demand patterns in the Japan Aircraft Engine Starter Market.
- Shift from Hydraulic to Electric Starter Systems: Since 2023, there has been a marked shift towards electric starter systems in new aircraft designs, as they offer improved reliability and efficiency. This trend is seen among commercial aircraft manufacturers, with electric systems projected to dominate future models.
- Emergence of Integrated Starter-Generator Technology: The Integrated Starter-Generator technology has gained traction among manufacturers since 2023, combining starting and generating functions. This shift is particularly beneficial for commercial aircraft OEMs, who are increasingly adopting this technology to improve performance.
- Increased Military Demand for Advanced Starters: Starting in 2022, military aviation units have reported a growing need for advanced starter systems, particularly for new fighter jets. This demand is likely to drive innovation and production in the sector, with substantial orders anticipated.
- Focus on Aerospace Manufacturing in Tokyo: The Tokyo region has emerged as a key hub for aerospace manufacturing, attracting investments and driving growth since 2023. This focus on aerospace is expected to improve production capabilities and drive technological advancements.
Investment Opportunities in the Japan Aircraft Engine Starter Market
Where to invest in the Japan Aircraft Engine Starter Market: the main openings are set out below.
- ¥10 billion allocated for aerospace R&D in 2023: With the Japanese government allocating ¥10 billion for aerospace research and development in 2023, there is a strong opportunity for investment in advanced starter technologies. Aerospace manufacturers in the Tokyo region can utilise this funding to improve their product offerings.
- Growing military aviation projects creating demand: The ongoing military aviation projects are creating a demand for advanced starter systems, with military aviation units reporting needs for new fighter jets. This presents an opportunity for manufacturers to develop and supply tailored starter solutions.
- Emerging need for integrated starter-generators: As integrated starter-generators gain popularity, manufacturers can invest in this technology to meet the growing demand. Commercial aircraft OEMs are increasingly seeking these systems for new aircraft models, creating a market opportunity.
- Increased focus on quality standards: The emphasis on JIS standards for aircraft components presents an opportunity for manufacturers to invest in quality assurance processes. Meeting these standards can improve product credibility and attract more buyers.
Government Initiatives in the Japan Aircraft Engine Starter Market
The Electrical Appliance and Material Safety Act (1961) regulates the safety of electrical appliances, including aircraft starters. Compliance with this law ensures that manufacturers produce reliable and safe products, which is critical for maintaining buyer confidence in the aviation sector. Additionally, the Japan Civil Aviation Bureau sets stringent standards for aircraft components, ensuring quality and safety in the market.
In 2023, the Ministry of Economy, Trade and Industry allocated ¥10 billion for aerospace research and development. This funding supports projects aimed at advancing aerospace technology, with the Japan Civil Aviation Bureau overseeing the implementation of related standards and regulations. Such initiatives are expected to improve the capabilities of aircraft engine starters and promote innovation in the industry.
Future Insight of the Japan Aircraft Engine Starter Market
New aerospace research and development projects will emerge by 2032, spurred by the ¥10 billion allocated by the government for innovation. Advanced technologies like electric starter systems will become standard in commercial aircraft, improving performance and reliability. Increased collaboration among industry stakeholders will promote innovation in starter technologies, benefiting both buyers and suppliers. The ongoing modernisation of military aviation equipment will create demand for advanced starter devices, ensuring that Japan remains competitive in the global aerospace market.
Market Segmentation Analysis
Japan Aircraft Engine Starter Market report covers a detailed analysis of the following market segments:
By Product Type – Electric Starter Systems Lead, Air Turbine Starters Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, Electric Starter Systems accounted for 44% of the market by product type in 2025. Electric starter systems hold the largest share in the market due to their essential role in modern aircraft, ensuring high reliability and performance. Their widespread use is highlighted by the introduction of new aircraft models in 2023 that depend on this technology. The quickest growth will come from Air Turbine Starters, forecast to expand at a CAGR of 9.5% between 2026 and 2032. Air turbine starters are experiencing rapid growth as they are crucial for starting turbine engines, particularly with the military's heightened demand for advanced aviation capabilities. The military's reported need for these systems to support new fighter jets is a significant factor in this growth. Suppliers should focus on developing air turbine starters to align with the increasing demand from military aviation.
By Starter Technology – DC Motor Leads, Pneumatic Expected to Grow Fastest
With 51% of starter technology revenue in 2025, DC Motor was the largest category. DC motor technology has historically been significant in older aircraft systems, maintaining a user base that still relies on it for specific applications. Its relevance persists in scenarios where reliability is crucial, despite a decrease in prevalence. Pneumatic is set to record the highest CAGR in this split, 10.0% over 2026–2032. Pneumatic technology is gaining popularity as a preferred option for specialised aircraft, driven by the need for efficient starting solutions in military aviation. The focus on advanced starter systems for new military aircraft is propelling this segment's growth. Buyers may benefit from considering pneumatic options as they become more prominent in specialised applications.
By Distribution Channel – Direct Sales Leads, Industrial Suppliers Expected to Grow Fastest
Direct Sales held 37% of the Japan Aircraft Engine Starter Market by distribution channel in 2025. Direct sales serve as the primary channel for manufacturers to engage customers, facilitating tailored solutions that address specific aviation sector needs. This method allows manufacturers to effectively respond to the unique requirements of their clients. Over 2026–2032, Industrial Suppliers are expected to post the fastest growth, at a CAGR of 8.1%. Industrial suppliers are increasingly important as they cater to various sectors, signalling a shift in how starters are distributed across different markets. Their growing role in supporting military aviation units reflects a broader trend in distribution strategies. Suppliers should explore strengthening partnerships with industrial suppliers to enhance market access.
By End User – Commercial Aircraft OEMs Lead, Military Aviation Units Expected to Grow Fastest
The largest end user category in 2025 was Commercial Aircraft OEMs, at 44% of revenue. Commercial aircraft OEMs are the largest user group for aircraft engine starters, driven by the ongoing production of new aircraft models. Their substantial purchasing power ensures a consistent demand for reliable starter systems. Military Aviation Units are projected to grow fastest, at a CAGR of 8.3% during 2026–2032. Military aviation units are experiencing a surge in demand for advanced starter systems, particularly as Japan focuses on modernising its military aircraft fleet. This emphasis on upgrading capabilities is expected to sustain high growth rates in this segment. Suppliers must adjust their strategies to meet the growing needs of military aviation units.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Aircraft Engine Starter Market Outlook
- Market Size of Japan Aircraft Engine Starter Market, 2025
- Forecast of Japan Aircraft Engine Starter Market, 2032
- Historical Data and Forecast of Japan Aircraft Engine Starter Revenues & Volume for the Period 2022-2032F
- Japan Aircraft Engine Starter Market Trend Evolution
- Japan Aircraft Engine Starter Market Drivers and Challenges
- Japan Aircraft Engine Starter Price Trends
- Japan Aircraft Engine Starter Porter's Five Forces
- Japan Aircraft Engine Starter Industry Life Cycle
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Product Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Electric Starter Systems for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Air Turbine Starters for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Hydraulic Starters for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Integrated Starter-Generator for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Starter Technology for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By DC Motor for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Pneumatic for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Hydraulic Pump-Based for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Hybrid Systems for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Direct Sales for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Industrial Suppliers for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By MRO Distributors for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By OEM Partnerships for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Commercial Aircraft OEMs for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Military Aviation Units for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Helicopter Operators for the Period 2022-2032F
- Historical Data and Forecast of Japan Aircraft Engine Starter Market Revenues & Volume By Private Jets Manufacturers for the Period 2022-2032F
- Japan Aircraft Engine Starter Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Starter Technology
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Japan Aircraft Engine Starter Top Companies Market Share
- Japan Aircraft Engine Starter Competitive Benchmarking By Technical and Operational Parameters
- Japan Aircraft Engine Starter Company Profiles
- Japan Aircraft Engine Starter Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Product Type
- Electric Starter Systems
- Air Turbine Starters
- Hydraulic Starters
- Integrated Starter-Generator
By Starter Technology
- DC Motor
- Pneumatic
- Hydraulic Pump-Based
- Hybrid Systems
By Distribution Channel
- Direct Sales
- Industrial Suppliers
- MRO Distributors
- OEM Partnerships
By End User
- Commercial Aircraft OEMs
- Military Aviation Units
- Helicopter Operators
- Private Jets Manufacturers






































