Japan Automobile Components Market Size & Growth Rate
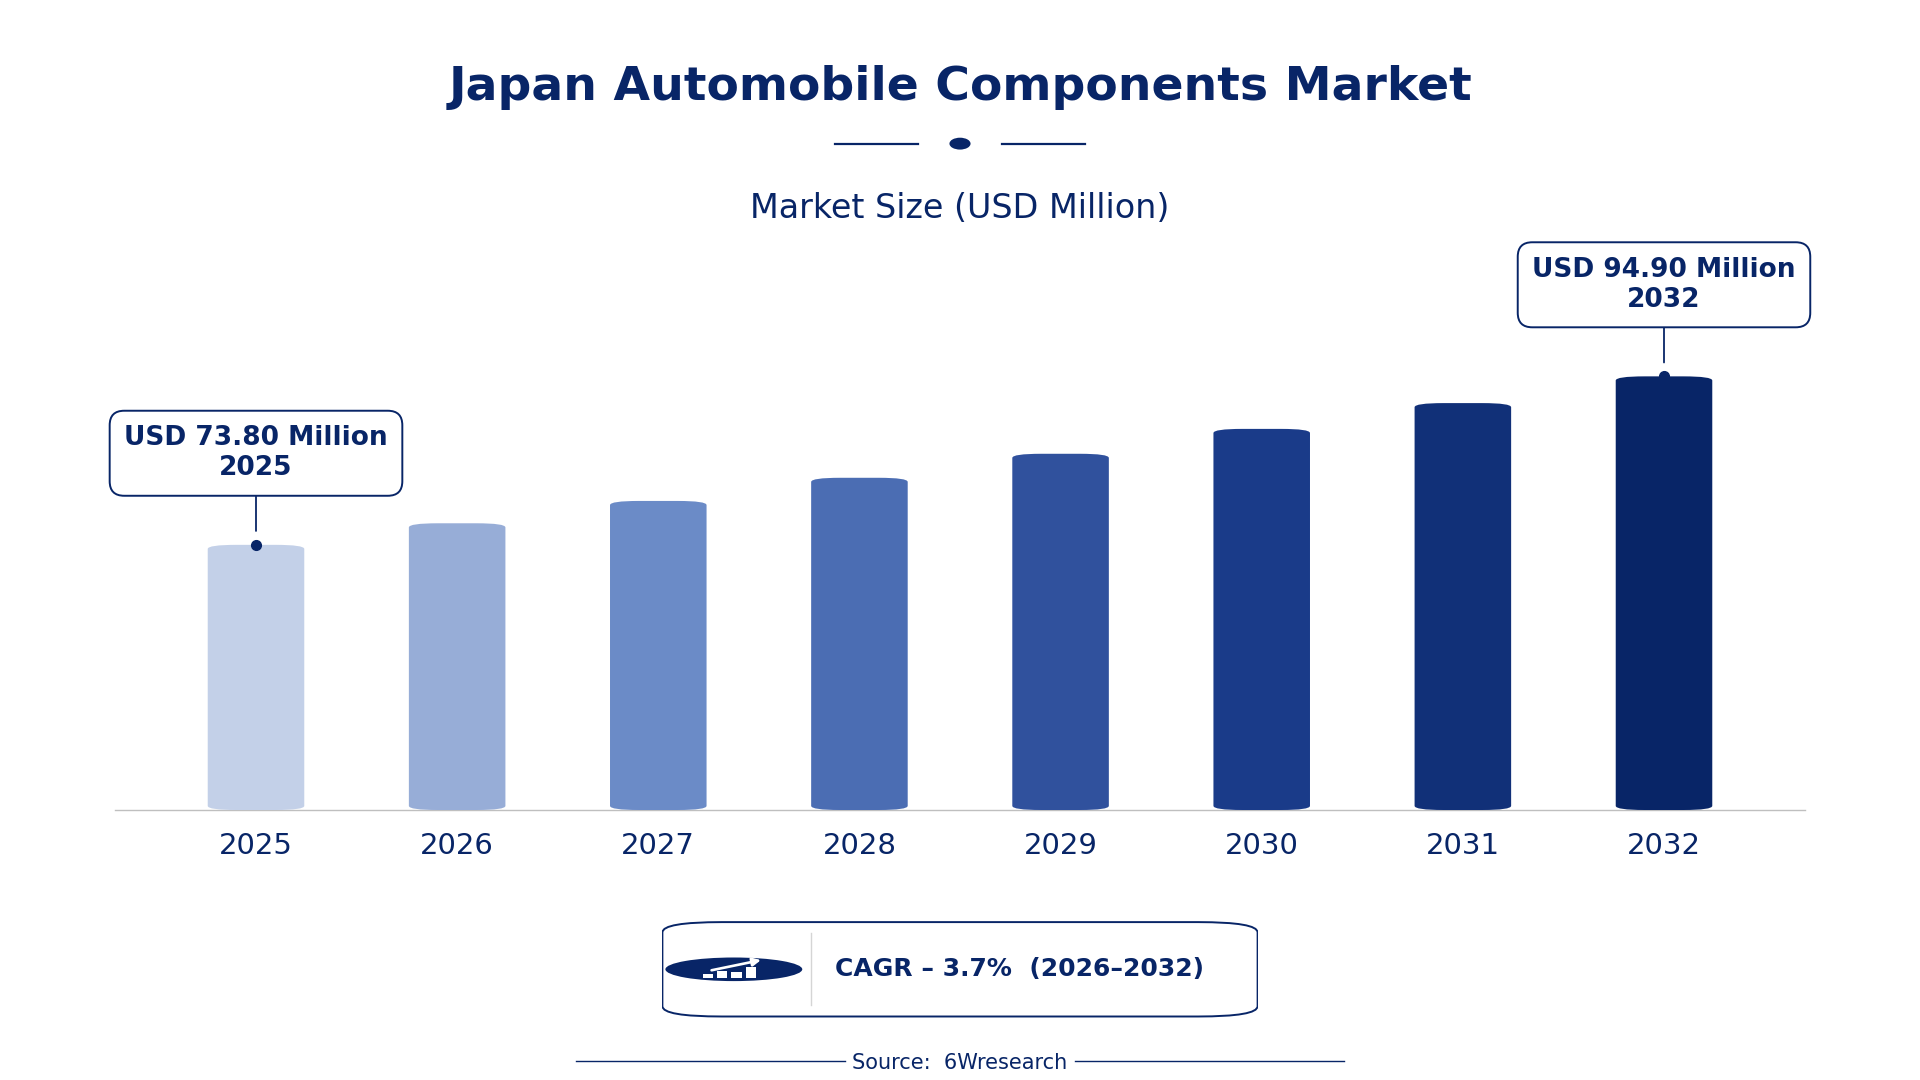
According to 6Wresearch internal database and industry insights, the Japan Automobile Components Market was valued at USD 73.80 Million in 2025 and is projected to reach USD 94.90 Million by 2032, growing at a CAGR of approximately 3.7% during 2026–2032.
Japan Automobile Components Market Highlights
| Report Metric | Details |
| Report Name | Japan Automobile Components Market (2026-2032) |
| Market Size 2025 | USD 73.80 Million |
| Market Size 2032 | USD 94.90 Million |
| Absolute Growth 2025–2032 | USD 21.10 Million |
| CAGR 2026–2032 | 3.7% |
| Peak Annual Growth | 4.9% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Flywheel (41% share) |
| Leading Applications, 2025 | Passenger Cars (PC) (44% share) |
| Fastest-Growing Product Type | Pressure Plate (4.9% CAGR) |
| Fastest-Growing Applications | Light Commercial Vehicles (LCV) (4.7% CAGR) |
| Growing Sector | Passenger Cars |
| Key End Users | automotive manufacturers, repair services, component suppliers |
Japan Automobile Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
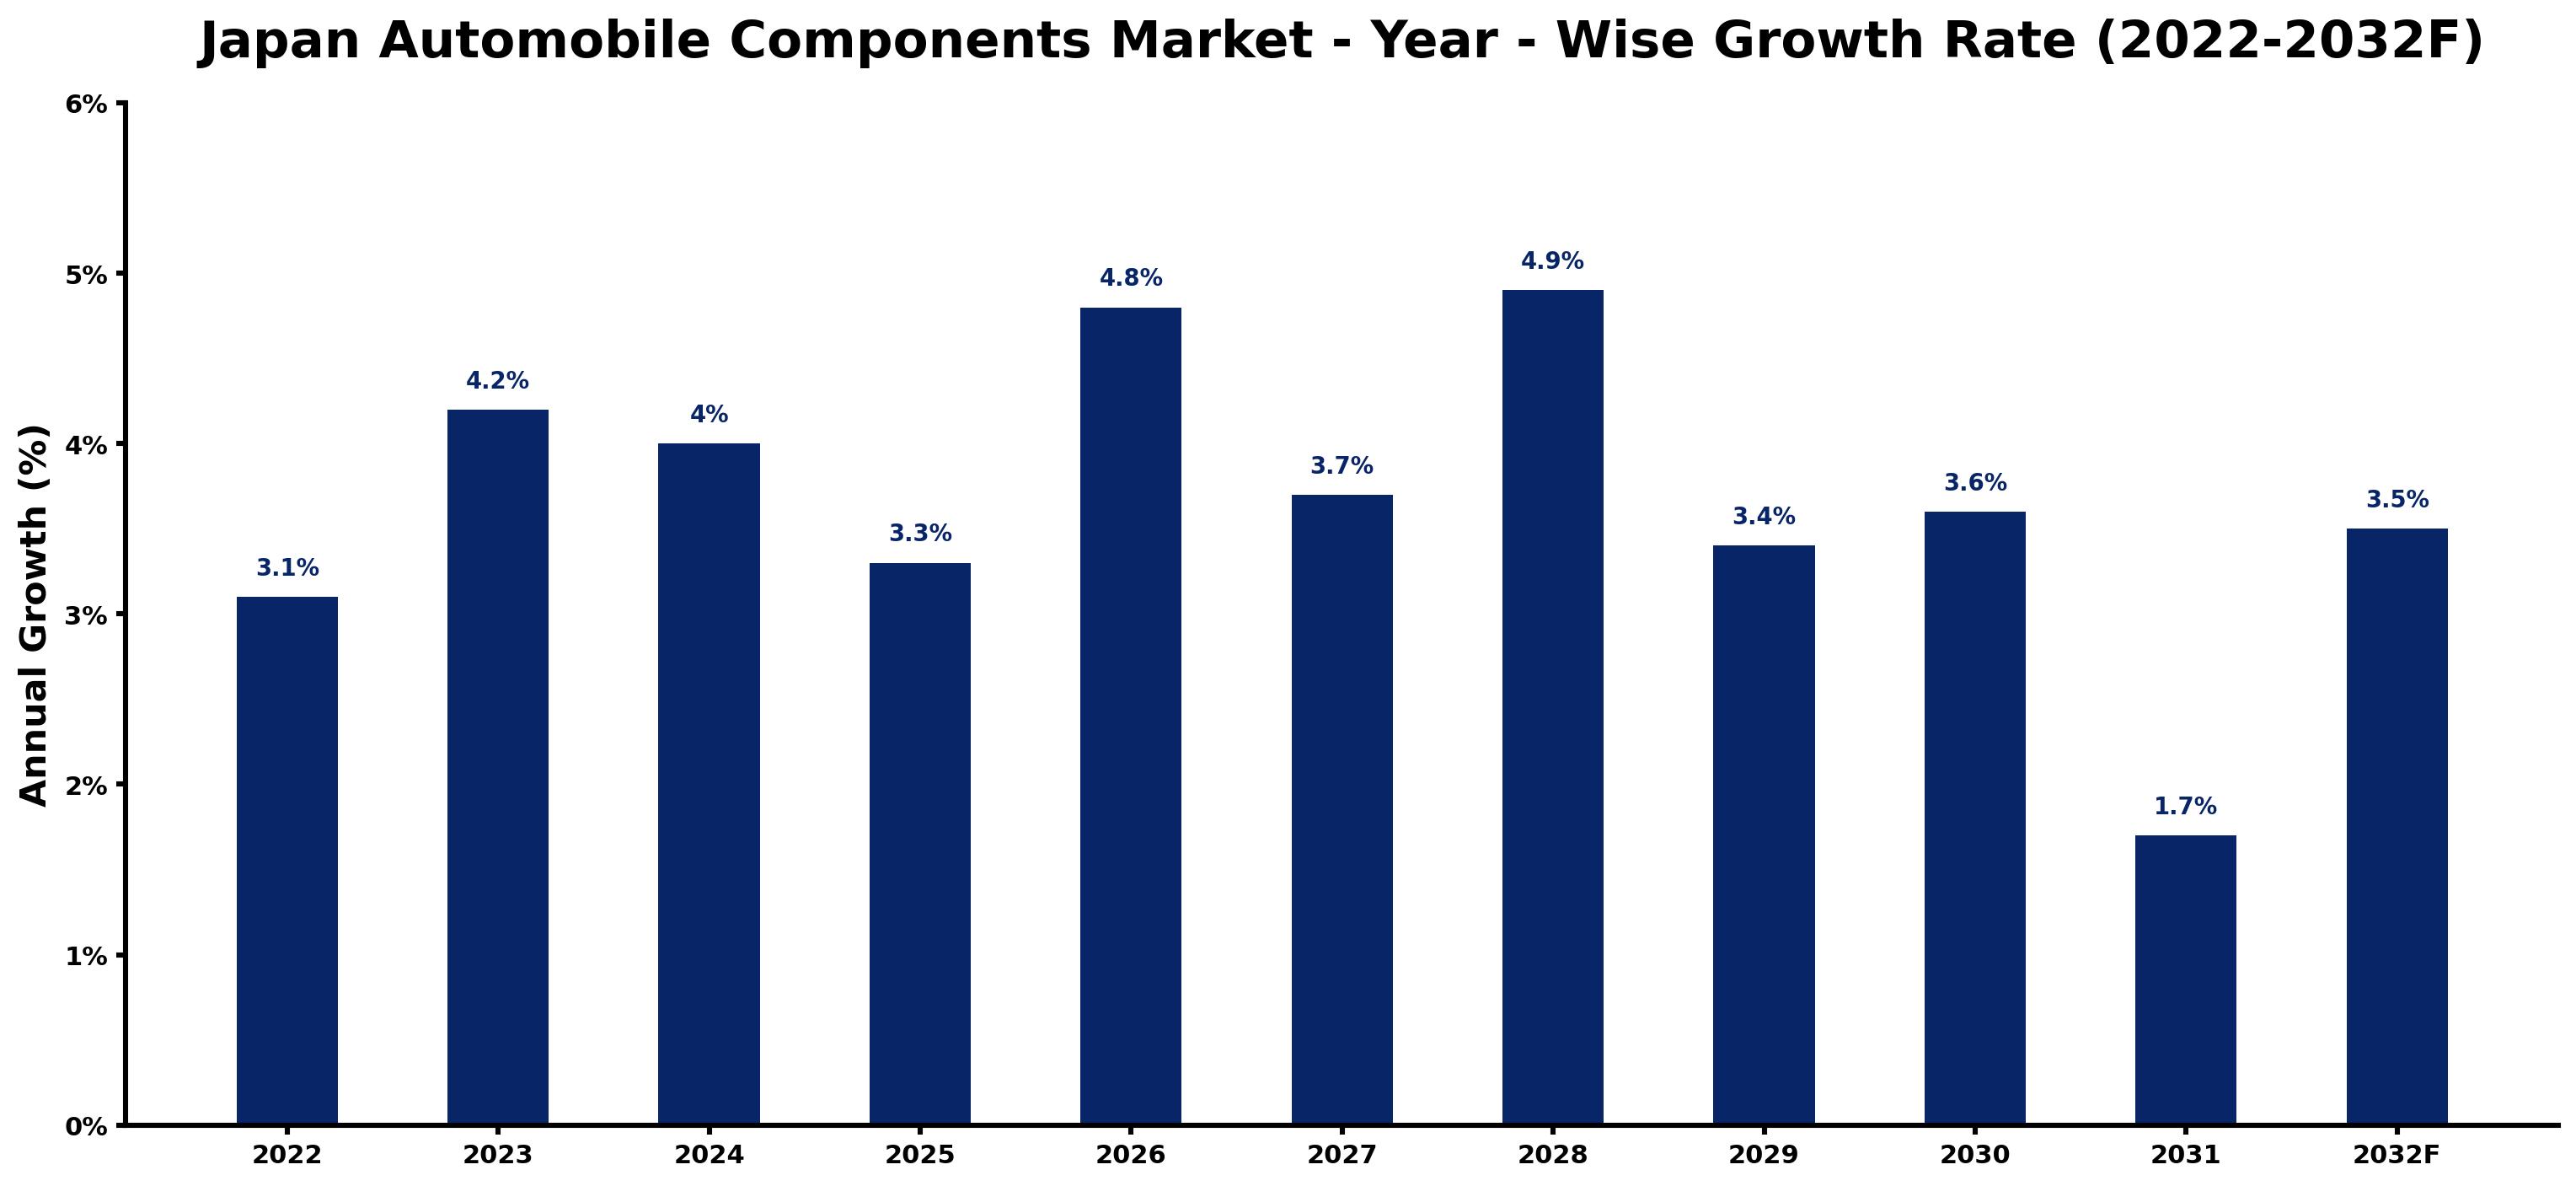
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.1 | Demand for components remained stable, reflecting ongoing vehicle production levels. |
| 2023 | 4.2 | Growth accelerated due to increased automotive manufacturing and component demand. |
| 2024 | 4.0 | Demand for components grew slower as supply chain issues affected availability. |
| 2025 | 3.3 | The market continued to expand, but at a reduced pace due to market saturation. |
| 2026 | 4.8 | Growth is expected to pick up again as investments in EV components materialise. |
| 2027 | 3.7 | Growth is projected to moderate as the market adjusts to new capacities. |
| 2028 | 4.9 | Peak growth will occur, driven by rising demand for electric vehicles. |
| 2029 | 3.4 | Growth is expected to slow slightly as the market stabilises after peak demand. |
| 2030 | 3.6 | Demand will increase again as the government pushes for EV production targets. |
| 2031 | 1.7 | Growth is projected to slow due to market saturation and shifting consumer preferences. |
| 2032 | 3.5 | Demand for components will rise again as new technologies are adopted. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Automobile Components Market Synopsis
Automobile components are mechanical parts used in vehicles, primarily manufactured from metals and composites through processes like casting and machining. The Japan Automobile Components Market is growing due to strong domestic production and demand, particularly in passenger cars, which accounted for 44% of the market in 2025. The automotive sector employs over 5 million people, while the government's commitment to a 46% reduction in greenhouse gas emissions by 2030 is prompting investments in electric vehicle components and technologies, further stimulating market growth. This growth is supported by the production of 8.3 million vehicles in 2022 and the adoption of industry standards like ISO 9001, which improve quality and buyer confidence.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand for electric vehicles is boosting component production. | Driver | High | Passenger Cars (PC) |
| The automotive sector's employment of over 5 million fuels demand for components. | Driver | High | Passenger Cars (PC) |
| Increasing investment in EV infrastructure presents opportunities for suppliers. | Opportunity | High | Light Commercial Vehicles (LCV) |
| Growing exports of automotive parts create demand for high-quality components. | Opportunity | Medium | Passenger Cars (PC) |
| Supply chain disruptions have impacted component availability. | Restraint | High | Flywheel |
| Market saturation is leading to slower growth rates in component demand. | Restraint | Medium | Flywheel |
| Rising production costs are affecting profit margins for suppliers. | Challenge | High | Flywheel |
| Technological advancements require constant adaptation from manufacturers. | Challenge | Medium | Flywheel |
Evaluation of Drivers in Japan Automobile Components Market (2026–2032)
Below are the drivers that matter most for revenue growth, with supporting evidence.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of electric vehicles drives demand for specific components. | Passenger Cars (PC) | Japan's target of 20% EV production by 2030 is stimulating component purchases. |
| The automotive sector's size supports a stable demand for components. | Passenger Cars (PC) | With 8.3 million vehicles produced in 2022, component demand remains strong. |
| Government initiatives are promoting investment in green technologies. | Light Commercial Vehicles (LCV) | The GX Basic Policy aims for JPY 150 trillion in decarbonisation investment. |
| The average vehicle lifespan of 13 years increases replacement component demand. | Flywheel | As vehicles age, the need for maintenance and replacement parts rises. |
| ISO 9001 standards drive quality improvement in component manufacturing. | Flywheel | Adoption of these standards ensures higher quality, boosting buyer confidence. |
Most of the extra volume comes from the automotive sector's substantial production levels, with 8.3 million vehicles manufactured in 2022. This production drives demand for components, particularly in passenger cars, which account for 44% of the market. The average vehicle lifespan of around 13 years increases the demand for replacement parts. Adoption of ISO 9001 standards improves product quality, further boosting buyer confidence and purchases.
Evaluation of Restraints in Japan Automobile Components Market
Below are the constraints most often cited by buyers and suppliers, with the segment each affects.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions are causing delays in component availability. | Flywheel | In 2022, global supply chain issues led to production slowdowns, affecting component delivery. |
| Market saturation is limiting growth potential for new entrants. | Flywheel | As the market matures, competition increases, making it harder for new suppliers. |
| Rising production costs are squeezing profit margins for manufacturers. | Flywheel | Increased material costs have raised the overall expenses for component production. |
| Technological advancements require constant adaptation in manufacturing processes. | Flywheel | Manufacturers must invest in new technologies to stay competitive, increasing operational costs. |
| Regulatory compliance can be burdensome for smaller manufacturers. | Flywheel | Meeting standards like JIS can require substantial investment in testing and certification. |
Japan Automobile Components Market Challenges
High demand for components arises from Japan producing 8.3 million vehicles in 2022, but local producers face supply chain disruptions that delay deliveries for automotive manufacturers. Many importers struggle with outdated technology, which results in longer lead times and increased costs for distributors. Skills shortages affect over 5 million employees in the automotive sector, leading to extended production timelines and higher operational expenses for producers. Regulatory complexities from the Ministry of Economy, Trade and Industry create compliance challenges, risking fines and operational delays for manufacturers in the automotive components market.
Trends in the Japan Automobile Components Market
Below are the shifts with the largest effect on the Japan Automobile Components Market.
- Shift from Conventional to Electric Vehicle Components: The automotive industry is increasingly focusing on electric vehicle components, particularly since 2023. This shift aligns with Japan's target to produce 20% EVs by 2030, prompting suppliers to adapt their offerings accordingly.
- Transition from Traditional Manufacturing to Smart Manufacturing: Since 2022, manufacturers have been adopting smart manufacturing technologies to improve efficiency. Tokyo's automotive plants are integrating IoT solutions to streamline production processes, improving output by 15%.
- Emergence of Sustainable Materials in Component Production: Beginning in 2023, there has been a notable shift towards sustainable materials in component manufacturing. This change supports Japan's decarbonisation goals, promoting the use of recycled metals.
- Prioritisation of Quality Standards in Component Supply: Since 2022, there has been a heightened focus on quality standards in the automotive components sector. The adoption of ISO 9001 has increased, ensuring higher quality products.
Investment Opportunities in the Japan Automobile Components Market
Investors looking at the Japan Automobile Components Market should consider the following areas.
- Tokyo Automotive Manufacturing Facilities: Tokyo's automotive manufacturing facilities are currently expanding, with substantial investments allocated for decarbonisation initiatives. This presents an opportunity for suppliers to provide eco-friendly components.
- Growing Demand for EV Components: With Japan's target of 20% EV production by 2030, there is a notable gap for suppliers in the EV component market. Collaborating with local manufacturers can facilitate entry into this expanding sector.
- Light Commercial Vehicle Market Expansion: The light commercial vehicle segment is projected to grow, driven by increased e-commerce. Suppliers can target this segment by developing tailored components for delivery vehicles.
- Investment in Battery Manufacturing: The Battery Industry Strategy aims for 150 GWh of domestic battery manufacturing by 2030. Suppliers can invest in battery components, partnering with local manufacturers to meet this growing demand.
Government Initiatives in the Japan Automobile Components Market
The GX Promotion Act, enacted in 2023, serves as the legal framework for Japan's green growth strategy. This law mandates substantial reductions in greenhouse gas emissions, targeting a 46% cut by 2030. The Green Growth Strategy, updated in 2021, identifies key sectors for investment, including the automotive industry, to support sustainable practices and innovation.
The Ministry of Economy, Trade and Industry oversees the implementation of automotive regulations and funds initiatives aimed at boosting EV production. The agency has approved numerous projects under the GX Basic Policy, which allocates JPY 150 trillion for public and private decarbonisation investments over the next decade.
Future Insight of the Japan Automobile Components Market
The policy-driven shift towards net zero emissions will catalyse a transformation in the automotive components market, compelling suppliers to revise their production methods. By 2032, JPY 150 trillion in decarbonisation investment will facilitate advancements in manufacturing processes, enabling suppliers to improve efficiency. New sustainability standards will emerge, enhancing the competitiveness of buyers in the market. The government's goal of increasing EV production to 20% by 2030 will further reshape the industry, aligning with global trends towards electric mobility.
Market Segmentation Analysis
Japan Automobile Components Market report covers a detailed analysis of the following market segments:
By Product Type – Flywheel Leads, Pressure Plate Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Flywheel held 41% of the Japan Automobile Components Market by product type in 2025. Flywheels are essential for engine operation and performance, making them a critical component in the majority of vehicles produced in Japan. With 8.3 million vehicles manufactured in 2022, the demand for flywheels remains robust among automotive manufacturers. Pressure Plate is set to record the highest CAGR in this split, 4.9% over 2026–2032. The pressure plate segment is experiencing rapid growth due to the increasing need for effective clutch engagement, particularly as vehicle production rises. This segment's expansion is further supported by the government's initiative to enhance EV component production in 2023. Suppliers should prioritise the flywheel segment while also considering growth opportunities in pressure plates to stay competitive.
By Applications – Passenger Cars (PC) Leads, Light Commercial Vehicles (LCV) Expected to Grow Fastest
In 2025, Passenger Cars (PC) led the applications split with a 44% share. Passenger cars represent the largest segment for automobile components, driven by the high volume of vehicles produced and a diverse consumer market in Japan. The automotive sector, employing over 5 million people, ensures ongoing demand for components in this category. The quickest growth will come from Light Commercial Vehicles (LCV), forecast to expand at a CAGR of 4.7% between 2026 and 2032. Light commercial vehicles are witnessing the fastest growth due to rising demand for delivery and transport services, particularly in urban areas. The automotive exports reaching 4.5 million units in 2022 highlight the increasing need for components in this segment. Buyers and suppliers should develop strategies that cater to the growing light commercial vehicle market while maintaining strong engagement in the passenger car segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Automobile Components Market Outlook
- Market Size of Japan Automobile Components Market, 2025
- Forecast of Japan Automobile Components Market, 2032
- Historical Data and Forecast of Japan Automobile Components Revenues & Volume for the Period 2022-2032
- Japan Automobile Components Market Trend Evolution
- Japan Automobile Components Market Drivers and Challenges
- Japan Automobile Components Price Trends
- Japan Automobile Components Porter's Five Forces
- Japan Automobile Components Industry Life Cycle
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Flywheel for the Period 2022-2032
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Pressure Plate for the Period 2022-2032
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Clutch for the Period 2022-2032
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Other for the Period 2022-2032
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Applications for the Period 2022-2032
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Passenger Cars (PC) for the Period 2022-2032
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Light Commercial Vehicles (LCV) for the Period 2022-2032
- Historical Data and Forecast of Japan Automobile Components Market Revenues & Volume By Heavy Commercial Vehicles (HCV) for the Period 2022-2032
- Japan Automobile Components Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Applications
- Japan Automobile Components Top Companies Market Share
- Japan Automobile Components Competitive Benchmarking By Technical and Operational Parameters
- Japan Automobile Components Company Profiles
- Japan Automobile Components Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Product Type
- Flywheel
- Pressure Plate
- Clutch
- Other
By Applications
- Passenger Cars (PC)
- Light Commercial Vehicles (LCV)
- Heavy Commercial Vehicles (HCV)






































