Japan Automotive Semiconductor Market Size & Growth Rate
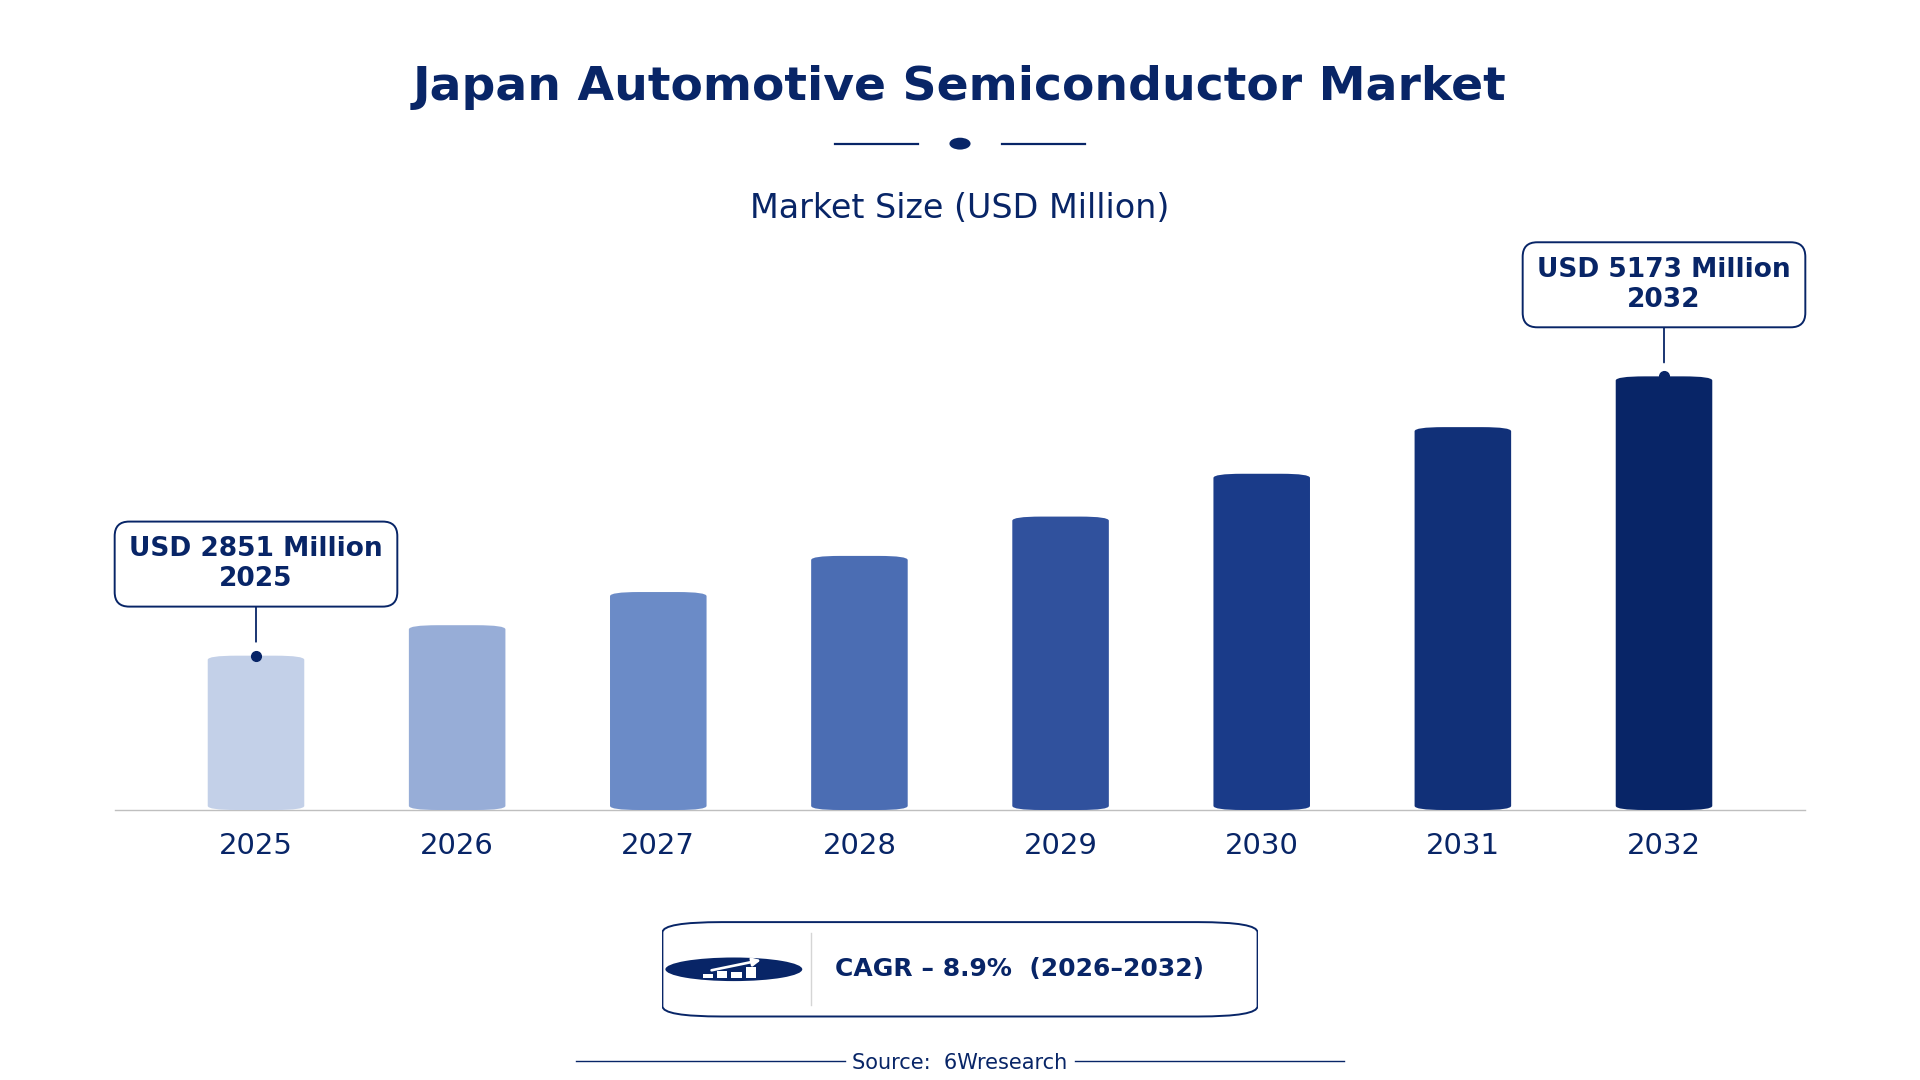
According to 6Wresearch internal database and industry insights, the Japan Automotive Semiconductor Market was valued at USD 2,851 Million in 2025 and is projected to reach USD 5,173 Million by 2032, growing at a CAGR of approximately 8.9% during 2026–2032.
Japan Automotive Semiconductor Market Highlights
| Report Metric | Details |
| Report Name | Japan Automotive Semiconductor Market (2026-2032) |
| Market Size 2025 | USD 2,851 Million |
| Market Size 2032 | USD 5,173 Million |
| Absolute Growth 2025–2032 | USD 2,322 Million |
| CAGR 2026–2032 | 8.9% |
| Peak Annual Growth | 9.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component, 2025 | Processor (39% share) |
| Leading Vehicle Type, 2025 | Passenger Car (48% share) |
| Leading Fuel Type, 2025 | Gasoline (43% share) |
| Leading Application, 2025 | Powertrain (44% share) |
| Fastest-Growing Component | Analog IC (13.1% CAGR) |
| Fastest-Growing Vehicle Type | LCV (12.2% CAGR) |
| Fastest-Growing Fuel Type | Diesel (12.9% CAGR) |
| Fastest-Growing Application | Safety (12.7% CAGR) |
| Growing Sector | Safety |
| Key End Users | Powertrain, Safety, Body Electronics, Chassis |
Japan Automotive Semiconductor Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
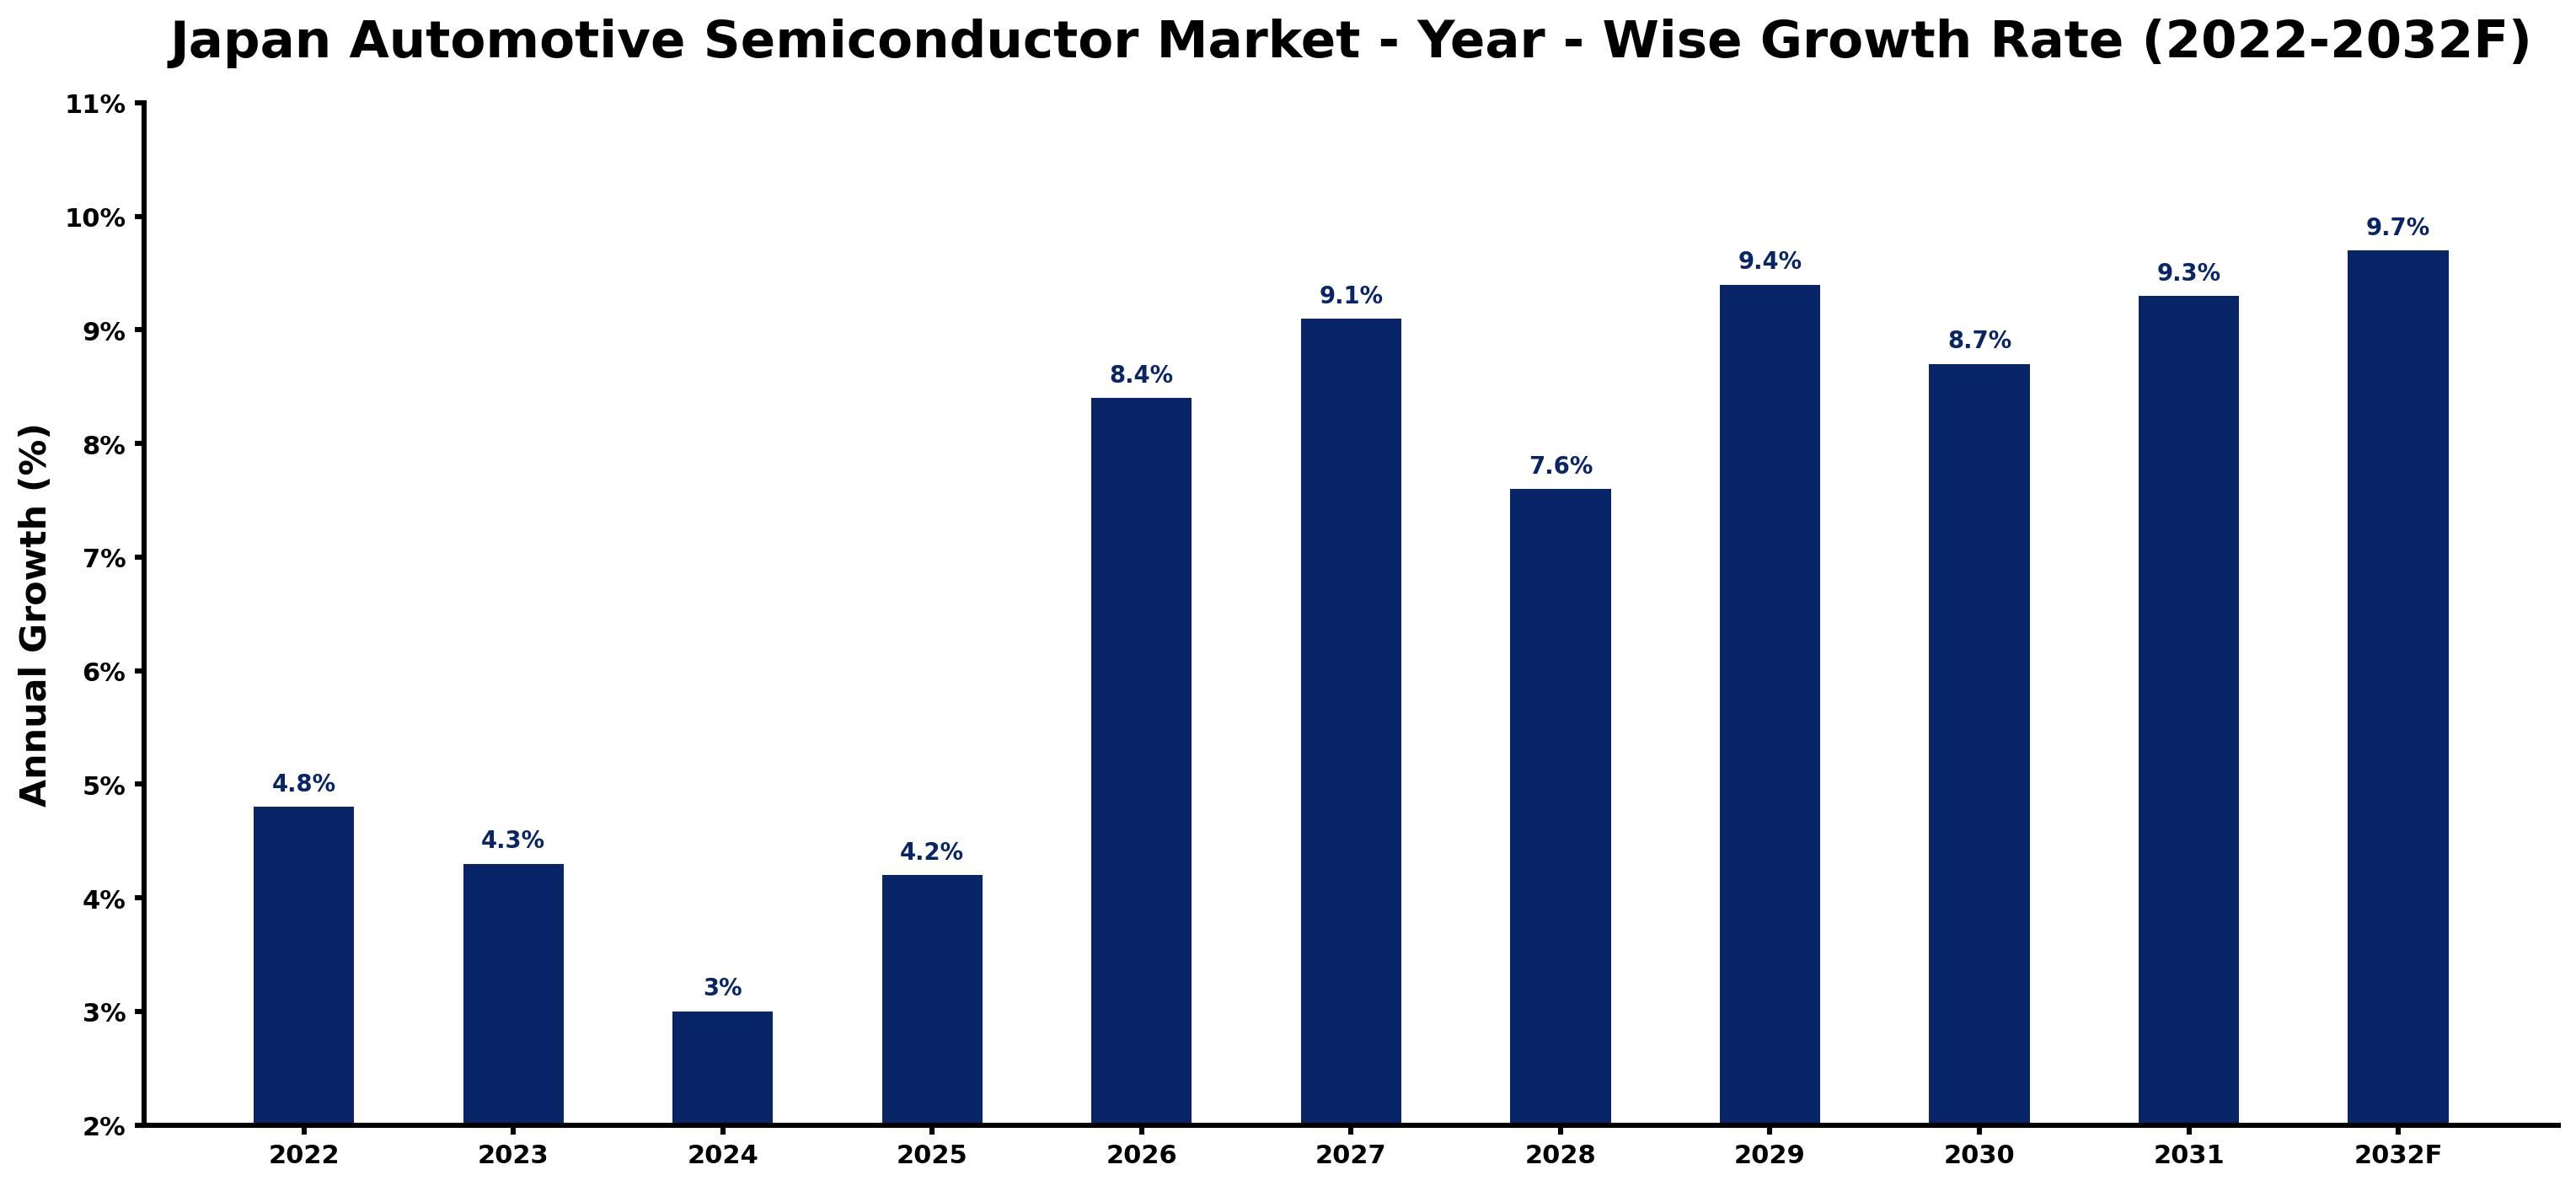
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.8 | The market experienced solid growth due to strong automotive production levels. |
| 2023 | 4.3 | Growth slowed as supply chain issues continued to affect semiconductor availability. |
| 2024 | 3.0 | Demand persisted, but growth decelerated amid ongoing supply constraints. |
| 2025 | 4.2 | A recovery in production boosted growth as manufacturers adapted to supply challenges. |
| 2026 | 8.4 | Demand surged as investments in electric vehicles increased semiconductor requirements. |
| 2027 | 9.1 | Continued investments in technology drove higher growth rates in the market. |
| 2028 | 7.6 | Growth slowed slightly as the market stabilised after rapid expansion. |
| 2029 | 9.4 | Demand increased again as automotive production ramped up. |
| 2030 | 8.7 | Growth moderated as the market adjusted to new production capacities. |
| 2031 | 9.3 | A surge in electric vehicle production spurred renewed demand for semiconductors. |
| 2032 | 9.7 | The market peaked as investments in advanced technologies reached new heights. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Automotive Semiconductor Market Synopsis
Automotive semiconductors are essential components in modern vehicles, enabling functions such as power management, safety systems, and infotainment applications. The Japan Automotive Semiconductor Market is valued at approximately 1 trillion yen, driven by the production of over 8 million vehicles in 2023. Factors propelling growth include increasing investments in electric vehicles, a strong domestic automotive industry, and government initiatives aimed at boosting semiconductor production and sustainability efforts.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand for electric vehicles | Driver | High | EV/HEV |
| Rising production of passenger cars | Driver | High | Passenger Car |
| Growing demand for advanced driver-assistance systems | Opportunity | High | Safety |
| Need for enhanced power management in vehicles | Opportunity | Medium | Powertrain |
| Supply chain disruptions affecting production | Restraint | High | Processor |
| High costs of semiconductor manufacturing | Restraint | Medium | Analog IC |
| Competition from international semiconductor markets | Challenge | High | Discrete Power Device |
| Technological advancements outpacing local production capabilities | Challenge | Medium | Sensor |
Evaluation of Drivers in Japan Automotive Semiconductor Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of electric vehicles | EV/HEV | The EV market in Japan is projected to expand by 25% annually through 2025, leading to higher semiconductor demand. |
| Rising automotive production levels | Passenger Car | In 2023, Japan produced over 8 million vehicles, driving semiconductor demand. |
| Demand for advanced safety features | Safety | The adoption of the ISO 26262 standard for automotive safety semiconductors is increasing, pushing demand higher. |
| Technological advancements in vehicle electronics | Powertrain | The average passenger car in Japan contains over 1,000 semiconductor components, reflecting growing complexity. |
| Government support for semiconductor production | Analog IC | The Ministry of Economy, Trade and Industry launched a program to boost semiconductor production in 2023. |
Most of the extra volume comes from the increasing production of electric vehicles, projected to grow by 25% annually through 2025. This surge in the EV market raises semiconductor demand, particularly for components related to power management and safety systems. In 2023, Japan produced over 8 million vehicles, which increases the need for automotive semiconductors. The adoption of the ISO 26262 standard drives demand for safety-related semiconductors, as manufacturers focus on advanced driver-assistance systems. The average passenger car in Japan contains over 1,000 semiconductor components, indicating the growing complexity of automotive electronics.
Evaluation of Restraints in Japan Automotive Semiconductor Market
Several factors work against faster growth; the main ones are summarised below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Rising costs due to decarbonisation targets | Analog IC | Producers face increased expenses from investments needed to meet Japan's 46% greenhouse-gas emissions reduction target by 2030. |
| Technological hurdles in standard compliance | Powertrain | Suppliers encounter challenges adapting to the JASPAR and ISO 26262 standards, which require advanced capabilities. |
| Skills shortages in semiconductor manufacturing | EV/HEV | The automotive sector needs specialised training for over 5 million workers to meet evolving demands. |
| Increasing average age of vehicles | Passenger Car | The average age of vehicles on Japanese roads exceeds 10 years, driving up replacement demand for semiconductors. |
| Supply chain disruptions | Safety | Ongoing global supply chain issues continue to impact semiconductor availability for automotive applications. |
Japan Automotive Semiconductor Market Challenges
Automotive manufacturers face rising costs as Japan's decarbonisation targets necessitate substantial investments in new technologies. The requirement for a 46% reduction in greenhouse-gas emissions by 2030 strains budgets, potentially delaying vehicle production schedules. Suppliers encounter difficulties in adapting to the JASPAR and ISO 26262 standards, which demand advanced capabilities that vary across the industry, resulting in slower integration of new components. Skills shortages in semiconductor manufacturing hinder progress, as over 5 million workers in the automotive sector require specialised training to meet industry demands, ultimately affecting production timelines for buyers.
Trends in the Japan Automotive Semiconductor Market
Several trends are reshaping the Japan Automotive Semiconductor Market; the most important are set out below.
- Shift Towards Electric Vehicle Integration: Starting in 2023, Japan's automotive sector is increasingly integrating electric vehicle technologies, with over 8 million vehicles produced. This shift drives semiconductor demand, particularly for power management systems.
- Focus on Advanced Driver-Assistance Systems: Beginning in 2022, the emphasis on safety features in vehicles has surged, following the adoption of the ISO 26262 standard. This trend drives the demand for safety-related semiconductors.
- Growth in Semiconductor Complexity: In 2023, the average passenger car in Japan contained over 1,000 semiconductor components, reflecting the growing complexity of automotive electronics. This trend indicates a rising demand for advanced semiconductor technologies.
- Government Initiatives for Semiconductor Production: In 2023, the Ministry of Economy, Trade and Industry launched a program to boost semiconductor production. This initiative aims to strengthen Japan's domestic semiconductor capabilities.
Investment Opportunities in the Japan Automotive Semiconductor Market
The following areas offer the clearest openings for investors and suppliers in the Japan Automotive Semiconductor Market.
- Joint Ventures for Semiconductor Production: With Japan targeting a 20% increase in domestic semiconductor production by 2025, opportunities exist for joint ventures in manufacturing. This is essential for suppliers looking to enter the market.
- Investment in EV Semiconductor Technologies: The projected 25% annual growth in the EV market through 2025 creates opportunities for suppliers of power management semiconductors. Collaborating with automotive manufacturers can facilitate market entry.
- Expansion of Safety Semiconductor Applications: As the demand for advanced driver-assistance systems grows, suppliers can invest in safety semiconductors. The adoption of ISO 26262 standards will drive this market segment.
- Development of Smart Mobility Solutions: The government's focus on smart mobility initiatives presents opportunities for semiconductor manufacturers. Investments in new technologies can meet the evolving needs of the automotive sector.
Government Initiatives in the Japan Automotive Semiconductor Market
The Semiconductor and Digital Industry Strategy, established by METI in June 2021, set measures to secure domestic semiconductor manufacturing. This framework aims to strengthen Japan's semiconductor capabilities and support the automotive sector's needs. The Economic Security Promotion Act of 2022 further enhances supply-chain resilience for critical products, ensuring stability in semiconductor availability for automotive manufacturers.
The Ministry of Economy, Trade and Industry's program launched in 2023 supports semiconductor production, benefiting automotive manufacturers. This initiative aims to increase domestic semiconductor output, addressing the growing demand from the automotive sector. The government allocated 100 billion yen for this purpose, boosting the industry's capacity to meet evolving market needs.
Future Insight of the Japan Automotive Semiconductor Market
Japan's commitment to net zero emissions by 2050 will reshape the automotive semiconductor market by 2032, prompting substantial policy-driven shifts. The government aims to increase domestic semiconductor production by 20% by 2025, stimulating investment in advanced manufacturing technologies. With the average age of vehicles on Japanese roads exceeding 10 years, replacement demand for semiconductors will rise significantly. As the electric vehicle market is expected to expand by 25% annually through 2025, suppliers must strengthen collaboration with automotive manufacturers to address these emerging needs.
Market Segmentation Analysis
Japan Automotive Semiconductor Market report covers a detailed analysis of the following market segments:
By Component – Processor Leads, Analog IC Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Processor accounted for 39% of the market by component in 2025. Processors are vital for vehicle control systems, ensuring optimal performance in modern automobiles. Their integration across Japan's automotive sector, which produced over 8 million vehicles in 2023, solidifies their leading position in the market. Analog IC is projected to grow fastest, at a CAGR of 13.1% during 2026–2032. The Analog IC segment is growing swiftly due to rising demand for signal processing in vehicles, particularly with the increasing prevalence of advanced infotainment systems. This trend is bolstered by the automotive sector's substantial investment of 500 billion yen in semiconductor R&D in 2023. Suppliers should enhance their Analog IC offerings to effectively capitalise on the segment's growth potential.
By Vehicle Type – Passenger Car Leads, LCV Expected to Grow Fastest
In 2025, Passenger Car led the vehicle type split with a 48% share. Passenger cars represent the largest segment for automotive semiconductors, driven by high production volumes and extensive reliance on electronic components. The production of over 8 million vehicles in Japan in 2023 underscores the importance of this category in the market. LCV is set to record the highest CAGR in this split, 12.2% over 2026–2032. Light Commercial Vehicles (LCVs) are witnessing increased demand, propelled by the growth of e-commerce and the need for efficient delivery solutions. This trend highlights the automotive sector's responsiveness to changing consumer preferences and market conditions. Buyers should explore semiconductor solutions specifically designed for LCVs to address the burgeoning market demand.
By Fuel Type – Gasoline Leads, Diesel Expected to Grow Fastest
Gasoline took 43% of fuel type revenue in 2025, more than any other category. Gasoline is the dominant fuel type in Japan, widely used in traditional vehicles that continue to lead the automotive market. This established preference ensures steady demand for gasoline-related automotive semiconductors, reflecting market stability. The quickest growth will come from Diesel, forecast to expand at a CAGR of 12.9% between 2026 and 2032. Diesel is experiencing notable growth, primarily due to its efficiency in commercial applications, despite its declining presence in newer models. This shift indicates a continued focus on enhancing diesel technologies and their applications. Suppliers may need to diversify their product offerings to accommodate the growing demand within the diesel segment.
By Application – Powertrain Leads, Safety Expected to Grow Fastest
With 44% of application revenue in 2025, Powertrain was the largest category. Powertrain applications are crucial for managing engine and drivetrain functions, making them a primary focus for automotive semiconductor use. The significant investments in semiconductor R&D highlight the critical importance of this application area in the industry. Over 2026–2032, Safety is expected to post the fastest growth, at a CAGR of 12.7%. Safety applications are expanding rapidly as more vehicles incorporate advanced driver-assistance systems, reflecting a strong commitment to improving safety standards. This growth signifies a shift towards prioritising safety in automotive design and technology. Suppliers should prioritise developing safety-related semiconductor solutions to align with the increasing market emphasis on vehicle safety.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Automotive Semiconductor Market Outlook
- Market Size of Japan Automotive Semiconductor Market, 2025
- Forecast of Japan Automotive Semiconductor Market, 2032
- Historical Data and Forecast of Japan Automotive Semiconductor Revenues & Volume for the Period 2022-2032
- Japan Automotive Semiconductor Market Trend Evolution
- Japan Automotive Semiconductor Market Drivers and Challenges
- Japan Automotive Semiconductor Price Trends
- Japan Automotive Semiconductor Porter's Five Forces
- Japan Automotive Semiconductor Industry Life Cycle
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Component for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Processor for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Analog IC for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Discrete Power Device for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Sensor for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Memory for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Lighting Device for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Vehicle Type for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Passenger Car for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By LCV for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By HCV for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Fuel Type for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Gasoline for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Diesel for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By EV/HEV for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Powertrain for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Safety for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Body Electronics for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Chassis for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Semiconductor Market Revenues & Volume By Telematics and Infotainment for the Period 2022-2032
- Japan Automotive Semiconductor Import Export Trade Statistics
- Market Opportunity Assessment By Component
- Market Opportunity Assessment By Vehicle Type
- Market Opportunity Assessment By Fuel Type
- Market Opportunity Assessment By Application
- Japan Automotive Semiconductor Top Companies Market Share
- Japan Automotive Semiconductor Competitive Benchmarking By Technical and Operational Parameters
- Japan Automotive Semiconductor Company Profiles
- Japan Automotive Semiconductor Key Strategic Recommendations
Market Covered
The following segment groups are covered in the report.
By Component
- Processor
- Analog IC
- Discrete Power Device
- Sensor
- Memory
- Lighting Device
By Vehicle Type
- Passenger Car
- LCV
- HCV
By Fuel Type
- Gasoline
- Diesel
- EV/HEV
By Application
- Powertrain
- Safety
- Body Electronics
- Chassis
- Telematics and Infotainment































