Japan Broadcasting & Cable TV Market Size & Growth Rate
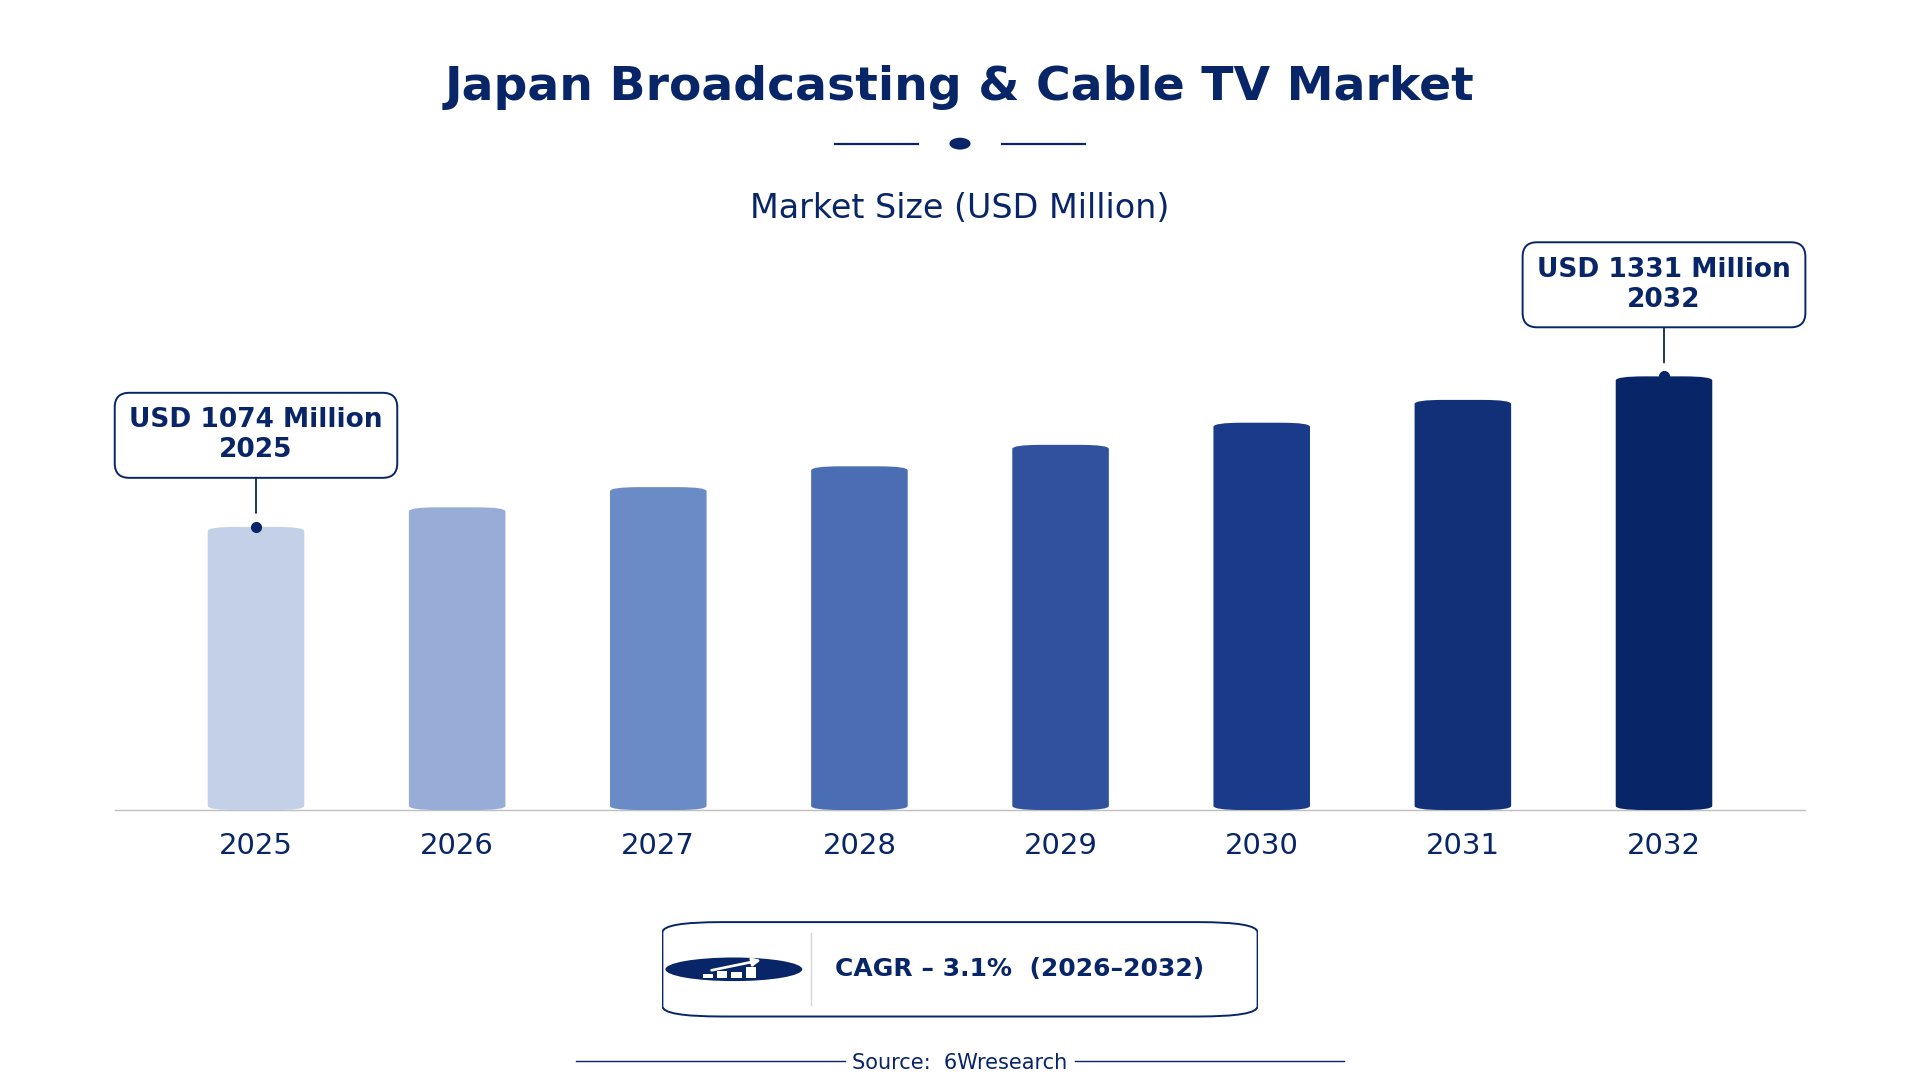
According to 6Wresearch internal database and industry insights, the Japan Broadcasting & Cable TV Market was valued at USD 1,074 Million in 2025 and is projected to reach USD 1,331 Million by 2032, growing at a CAGR of approximately 3.1% during 2026–2032.
Japan Broadcasting & Cable TV Market Highlights
| Report Metric | Details |
| Report Name | Japan Broadcasting & Cable TV Market (2026-2032) |
| Market Size 2025 | USD 1,074 Million |
| Market Size 2032 | USD 1,331 Million |
| Absolute Growth 2025–2032 | USD 257 Million |
| CAGR 2026–2032 | 3.1% |
| Peak Annual Growth | 3.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Technology, 2025 | Cable TV (44% share) |
| Leading Revenue Channel, 2025 | Advertising (63% share) |
| Fastest-Growing Technology | Satellite TV (4.6% CAGR) |
| Fastest-Growing Revenue Channel | Subscription (4.1% CAGR) |
| Growing Sector | Broadcasting and Cable TV |
| Key End Users | Content creators, cable operators, IPTV providers, advertising agencies |
Japan Broadcasting & Cable TV Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
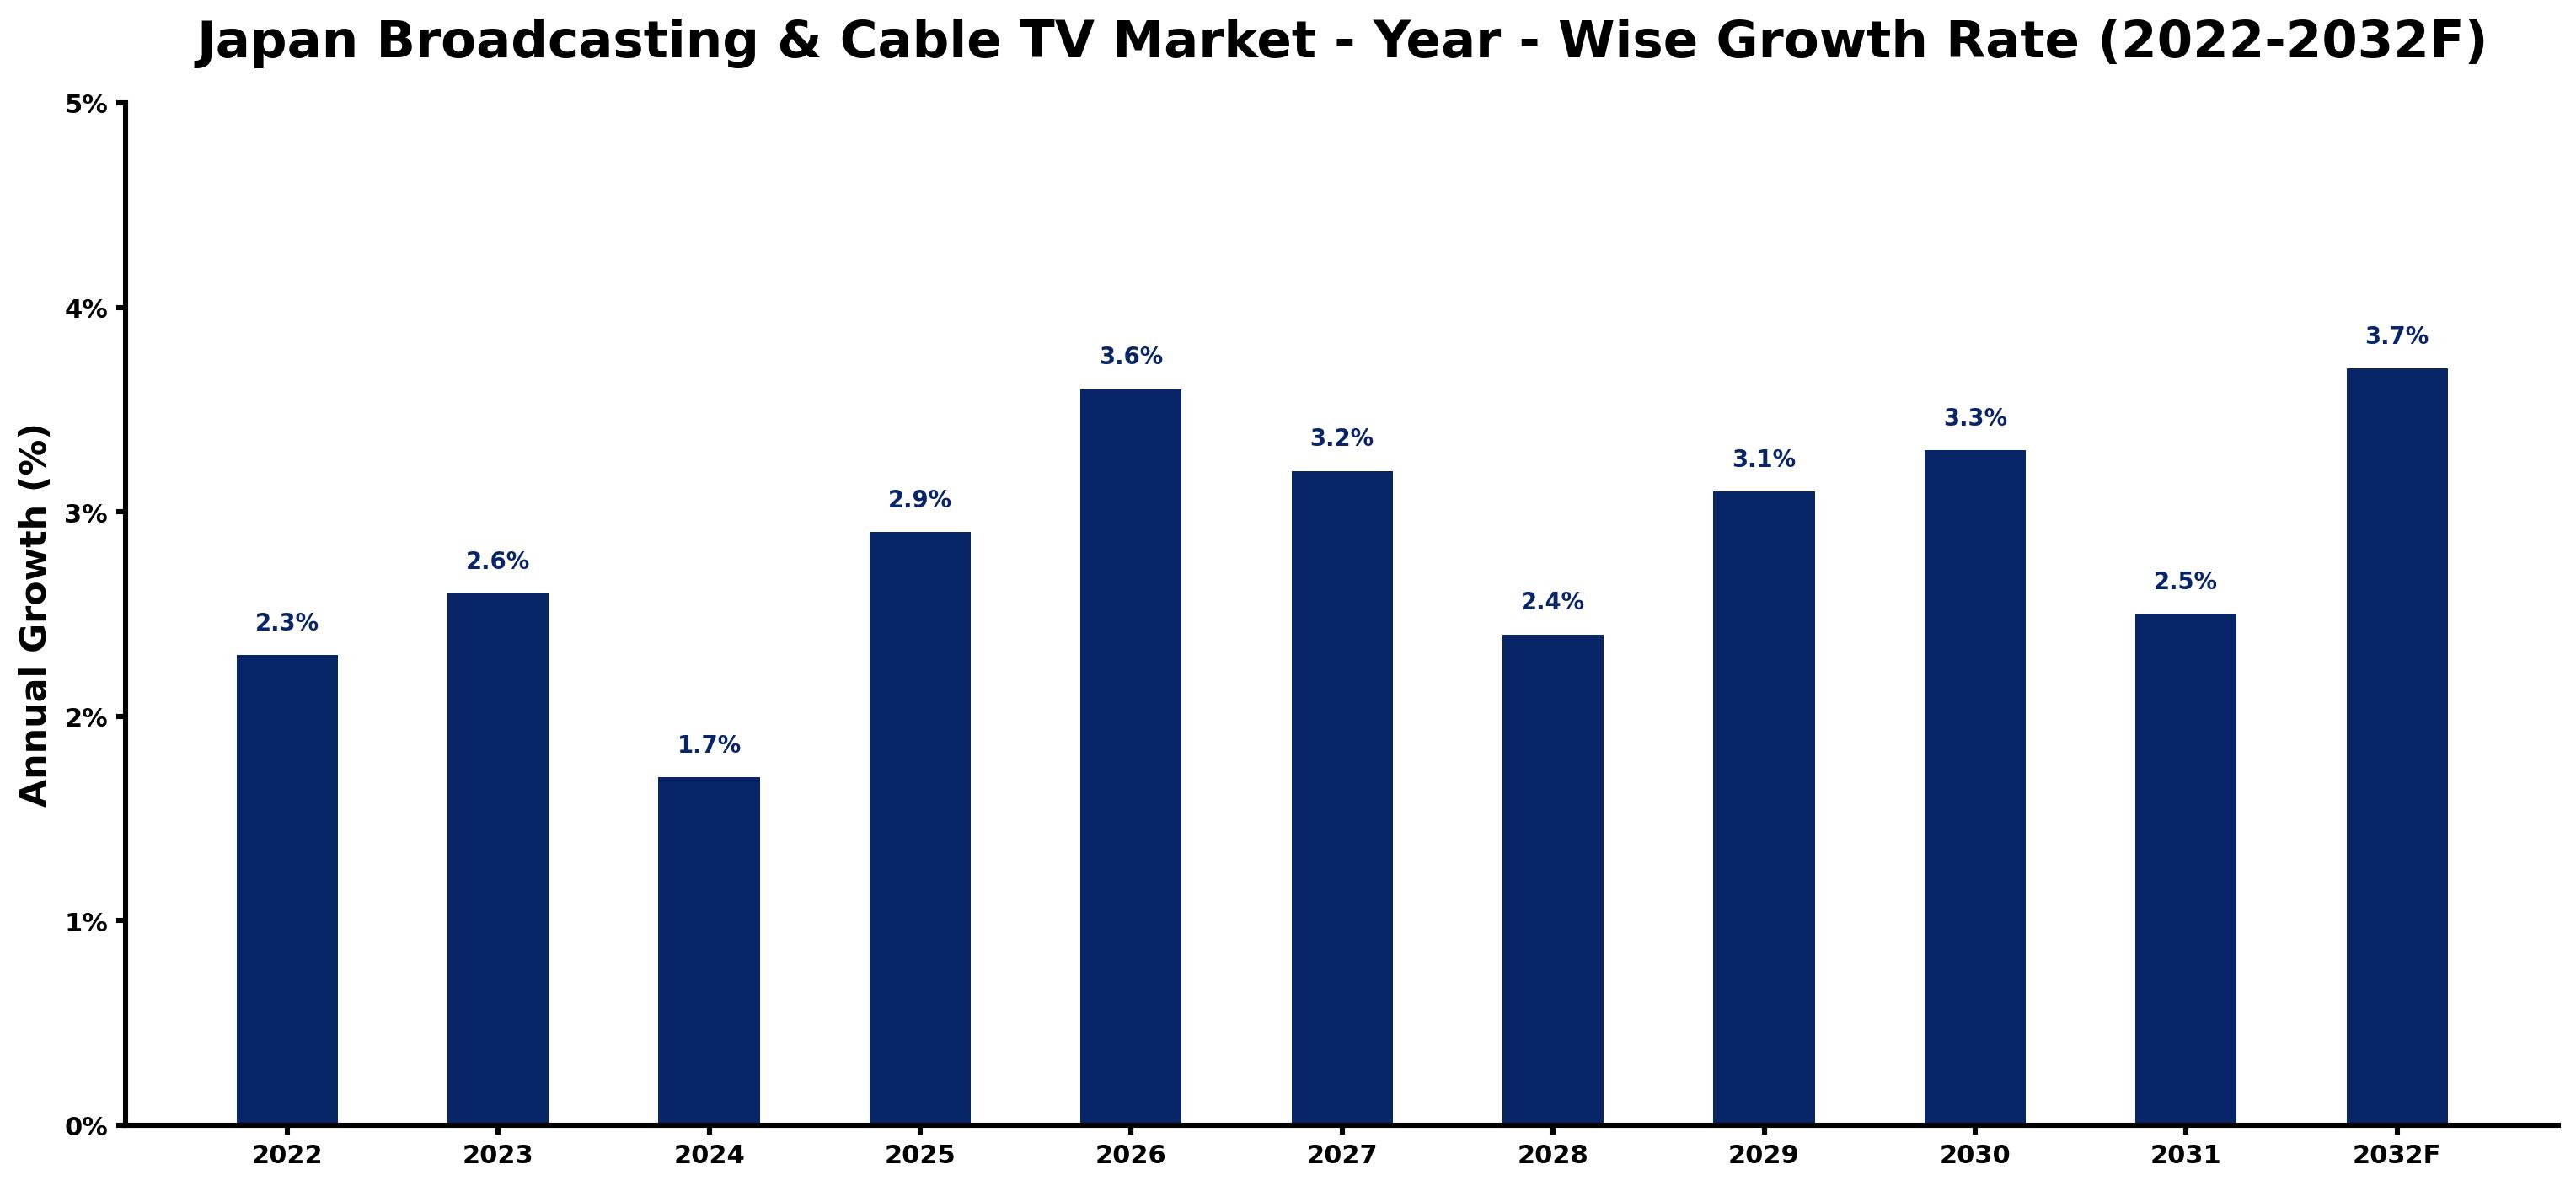
The following figures match every annual growth estimate with the main market development of that year, giving the reasoning behind each rise or slowdown.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.3 | The market experienced steady growth, supported by existing demand for entertainment and information. |
| 2023 | 2.6 | Growth accelerated due to increased consumer interest in diverse programming options. |
| 2024 | 1.7 | Growth slowed as competition intensified among service providers for market share. |
| 2025 | 2.9 | A surge in subscriptions and advertising revenue contributed to faster growth. |
| 2026 | 3.6 | Investment in new technologies and services is projected to lead to a further increase in demand. |
| 2027 | 3.2 | Growth is expected to slow as market saturation begins to impact new subscriber acquisitions. |
| 2028 | 2.4 | Consumer preferences will shift towards on-demand content, affecting traditional services. |
| 2029 | 3.1 | A resurgence in advertising spending is anticipated to boost market growth once again. |
| 2030 | 3.3 | Continued investment in IPTV services will support a rise in subscriptions. |
| 2031 | 2.5 | Growth is projected to slow as the market stabilises and competition intensifies further. |
| 2032 | 3.7 | The market is expected to peak due to increased digital content consumption. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Broadcasting & Cable TV Market Synopsis
Broadcasting and cable TV in Japan encompasses technologies such as cable, satellite, IPTV, and DTT, primarily catering to entertainment, news, and educational programming needs. The Japan Broadcasting & Cable TV Market is expanding due to high cable penetration, with over 30 million subscribers and a 99% DTT coverage rate in urban areas. The increase in IPTV subscriptions, which rose by 15% last year, reflects shifting consumer preferences and the demand for on-demand content. This growth is further supported by substantial investments in content delivery infrastructure and changing consumer habits.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| High penetration of cable TV services drives subscription growth. | Driver | High | Cable TV |
| Increasing demand for on-demand content fuels IPTV subscriptions. | Driver | High | Internet Protocol TV (IPTV) |
| Expansion of digital services presents new revenue opportunities. | Opportunity | High | Digital Terrain TV (DTT) |
| Growing interest in subscription models opens doors for new entrants. | Opportunity | Medium | Subscription |
| Intense competition among service providers may limit growth potential. | Restraint | High | Cable TV |
| Market saturation could hinder new subscriber acquisitions. | Restraint | Medium | Internet Protocol TV (IPTV) |
| High operational costs can pressure smaller operators' profitability. | Challenge | High | Cable TV |
| Technological advancements require continuous investment from providers. | Challenge | Medium | Satellite TV |
Evaluation of Drivers in Japan Broadcasting & Cable TV Market (2026–2032)
Below are the drivers that matter most for revenue growth, with supporting evidence.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| High cable TV penetration drives subscription growth. | Cable TV | With over 30 million subscribers, cable TV remains a primary choice for entertainment. |
| Growing demand for on-demand content boosts IPTV subscriptions. | Internet Protocol TV (IPTV) | A 15% increase in IPTV subscriptions in the last year reflects changing consumer preferences. |
| Digital Terrain TV (DTT) coverage ensures service accessibility. | Digital Terrain TV (DTT) | DTT's coverage rate of over 99% in urban areas guarantees access to free-to-air broadcasting. |
| Advertising revenue supports broadcasters' financial stability. | Advertising | Total revenue from subscription services reached approximately 1 trillion yen in 2022. |
| Increasing competition drives innovation in service offerings. | Satellite TV | The need to differentiate services leads to improved programming and technology investments. |
Much of the new demand stems from Japan's high cable TV penetration, which supports over 30 million subscribers. The rise in IPTV subscriptions last year indicates a shift towards on-demand content, with a 15% increase demonstrating changing consumer preferences. Total revenue from subscription services reached approximately 1 trillion yen in 2022, highlighting strong advertising support for broadcasters. The competitive environment encourages service providers to improve their offerings and enhance customer satisfaction.
Evaluation of Restraints in Japan Broadcasting & Cable TV Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition among service providers may limit growth potential. | Cable TV | The fierce rivalry among operators can lead to price wars, reducing profitability for smaller players. |
| Market saturation could hinder new subscriber acquisitions. | Internet Protocol TV (IPTV) | As the market matures, attracting new subscribers becomes increasingly challenging for service providers. |
| High operational costs can pressure smaller operators' profitability. | Satellite TV | Smaller operators face challenges in maintaining service quality while managing rising operational expenses. |
| Technological advancements require continuous investment from providers. | Digital Terrain TV (DTT) | Operators must invest heavily in new technologies to remain competitive, impacting their financial resources. |
| Regulatory compliance can add to operational complexities for broadcasters. | Cable TV | Broadcasters must navigate complex regulations, which can increase operational costs and limit flexibility. |
Japan Broadcasting & Cable TV Market Challenges
Buyers face intense competition as over 30 million cable TV subscribers compete for attention, leading to pricing wars that can compromise service quality. A shortage of skilled technicians limits suppliers' ability to maintain and upgrade broadcasting systems, delaying improvements for operators. Rising subscription fees, averaging around 4,000 yen monthly, deter potential new subscribers, restricting market growth for service providers. Regulatory changes create compliance challenges, resulting in increased costs for suppliers, which they often pass on to consumers, further straining buyers' budgets.
Trends in the Japan Broadcasting & Cable TV Market
The following changes are redrawing the Japan Broadcasting & Cable TV Market.
- Shift to On-Demand Content: The rise of on-demand content is reshaping consumer habits, with IPTV subscriptions increasing by 15% last year. This trend reflects a growing preference for flexibility in viewing options, prompting broadcasters to adjust their offerings.
- Kanto Region Leading Broadcasting Services: The Kanto region, including Tokyo, remains the largest market for broadcasting services, accounting for over 40% of total subscriptions. This concentration of demand drives investment in content creation and delivery infrastructure.
- Increased Focus on Digital Transformation: The establishment of the Digital Agency in September 2021 has accelerated digital transformation across broadcasting. This initiative aims to standardise systems and improve service delivery, affecting how content is produced and consumed.
- Emergence of Subscription Models: The subscription revenue channel is gaining traction, with a projected CAGR of 4.1% for the next several years. This shift indicates a move towards recurring revenue models, appealing to both consumers and service providers.
Investment Opportunities in the Japan Broadcasting & Cable TV Market
Below are the investment opportunities with the strongest case in the Japan Broadcasting & Cable TV Market.
- Local Partnerships for Content Delivery: Establishing joint ventures with local content creators can improve service offerings. The Kanto region's demand for diverse programming presents a prime opportunity for collaboration, especially with a market of over 30 million cable TV subscribers.
- Investing in IPTV Infrastructure: Now is the time to invest in IPTV infrastructure, as subscriptions have surged by 15%. Targeting urban areas with high internet penetration can yield substantial returns, particularly in the Kanto region.
- Focus on Subscription Services: With subscription revenue growing, targeting households in urban centres can be profitable. Engaging with local cable operators to expand service offerings can facilitate market entry, especially given the average monthly fee of around 4,000 yen.
- Advertising Revenue Opportunities: The advertising segment, accounting for 63% of revenue, presents opportunities for new entrants. Collaborating with regional broadcasters can enhance visibility and market presence, especially in the competitive Kanto region.
Government Initiatives in the Japan Broadcasting & Cable TV Market
The Broadcasting Act of 1950 regulates the broadcasting industry, ensuring compliance with safety and content standards. This law has undergone amendments to adapt to technological advancements, promoting a competitive environment for broadcasters. The Electrical Appliance and Material Safety Act of 1961 further ensures the safety of electrical appliances used in broadcasting, contributing to consumer protection and industry integrity.
The Japan Cable Television Association supports cable operators, providing resources for compliance and advocacy. These agencies facilitate the growth of the broadcasting sector by promoting best practices and ensuring adherence to safety standards.
Future Insight of the Japan Broadcasting & Cable TV Market
A policy-driven shift will initiate the adoption of advanced broadcasting technologies, improving viewer experiences. The growth of digital infrastructure in urban centres will enable broader access to diverse content. Emerging standards for content delivery will ensure better quality and consistency. An expected rise in IPTV subscriptions will motivate suppliers to expand their service offerings, aligning with changing consumer demands.
Market Segmentation Analysis
Japan Broadcasting & Cable TV Market report covers a detailed analysis of the following market segments:
By Technology – Cable TV Leads, Satellite TV Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, with 44% of technology revenue in 2025, Cable TV was the largest category. Cable TV holds the largest share as it is widely used for entertainment and information delivery, with over 30 million subscribers in Japan. The Kanto region, particularly Tokyo, showcases this dominance with its high penetration rates and established user base. The quickest growth will come from Satellite TV, forecast to expand at a CAGR of 4.6% between 2026 and 2032. Satellite TV is experiencing rapid growth by providing services in areas without cable access, addressing the needs of a substantial part of the population. This segment's expansion is driven by the increasing demand for diverse content in remote locations. Suppliers should focus on enhancing satellite service offerings to capture the growing audience in underserved regions.
By Revenue Channel – Advertising Leads, Subscription Expected to Grow Fastest
Advertising took 63% of revenue channel revenue in 2025, more than any other category. Advertising leads the revenue channels as it generates substantial income for broadcasters through commercial content. The strong advertising market in Japan, supported by high viewership, highlights its critical role in the broadcasting sector. Over 2026–2032, Subscription is expected to post the fastest growth, at a CAGR of 4.1%. Subscription revenue is growing quickly, indicating a shift towards direct payment models for content access. The increase in cable TV subscribers reflects a willingness to invest in quality programming, fuelling this revenue stream's growth. Buyers may find competitive subscription pricing as providers aim to attract and retain customers in a thriving market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Broadcasting & Cable TV Market Outlook
- Market Size of Japan Broadcasting & Cable TV Market, 2025
- Forecast of Japan Broadcasting & Cable TV Market, 2032
- Historical Data and Forecast of Japan Broadcasting & Cable TV Revenues & Volume for the Period 2022-2032
- Japan Broadcasting & Cable TV Market Trend Evolution
- Japan Broadcasting & Cable TV Market Drivers and Challenges
- Japan Broadcasting & Cable TV Price Trends
- Japan Broadcasting & Cable TV Porter's Five Forces
- Japan Broadcasting & Cable TV Industry Life Cycle
- Historical Data and Forecast of Japan Broadcasting & Cable TV Market Revenues & Volume By Technology for the Period 2022-2032
- Historical Data and Forecast of Japan Broadcasting & Cable TV Market Revenues & Volume By Cable TV for the Period 2022-2032
- Historical Data and Forecast of Japan Broadcasting & Cable TV Market Revenues & Volume By Satellite TV for the Period 2022-2032
- Historical Data and Forecast of Japan Broadcasting & Cable TV Market Revenues & Volume By Internet Protocol TV (IPTV) for the Period 2022-2032
- Historical Data and Forecast of Japan Broadcasting & Cable TV Market Revenues & Volume By Digital Terrain TV (DTT) for the Period 2022-2032
- Historical Data and Forecast of Japan Broadcasting & Cable TV Market Revenues & Volume By Revenue Channel for the Period 2022-2032
- Historical Data and Forecast of Japan Broadcasting & Cable TV Market Revenues & Volume By Advertising for the Period 2022-2032
- Historical Data and Forecast of Japan Broadcasting & Cable TV Market Revenues & Volume By Subscription for the Period 2022-2032
- Japan Broadcasting & Cable TV Import Export Trade Statistics
- Market Opportunity Assessment By Technology
- Market Opportunity Assessment By Revenue Channel
- Japan Broadcasting & Cable TV Top Companies Market Share
- Japan Broadcasting & Cable TV Competitive Benchmarking By Technical and Operational Parameters
- Japan Broadcasting & Cable TV Company Profiles
- Japan Broadcasting & Cable TV Key Strategic Recommendations
Market Covered
The report covers the following segments.
By Technology
- Cable TV
- Satellite TV
- Internet Protocol TV (IPTV)
- Digital Terrain TV (DTT)
By Revenue Channel
- Advertising
- Subscription































