Japan District Heating and Cooling Market Size & Growth Rate
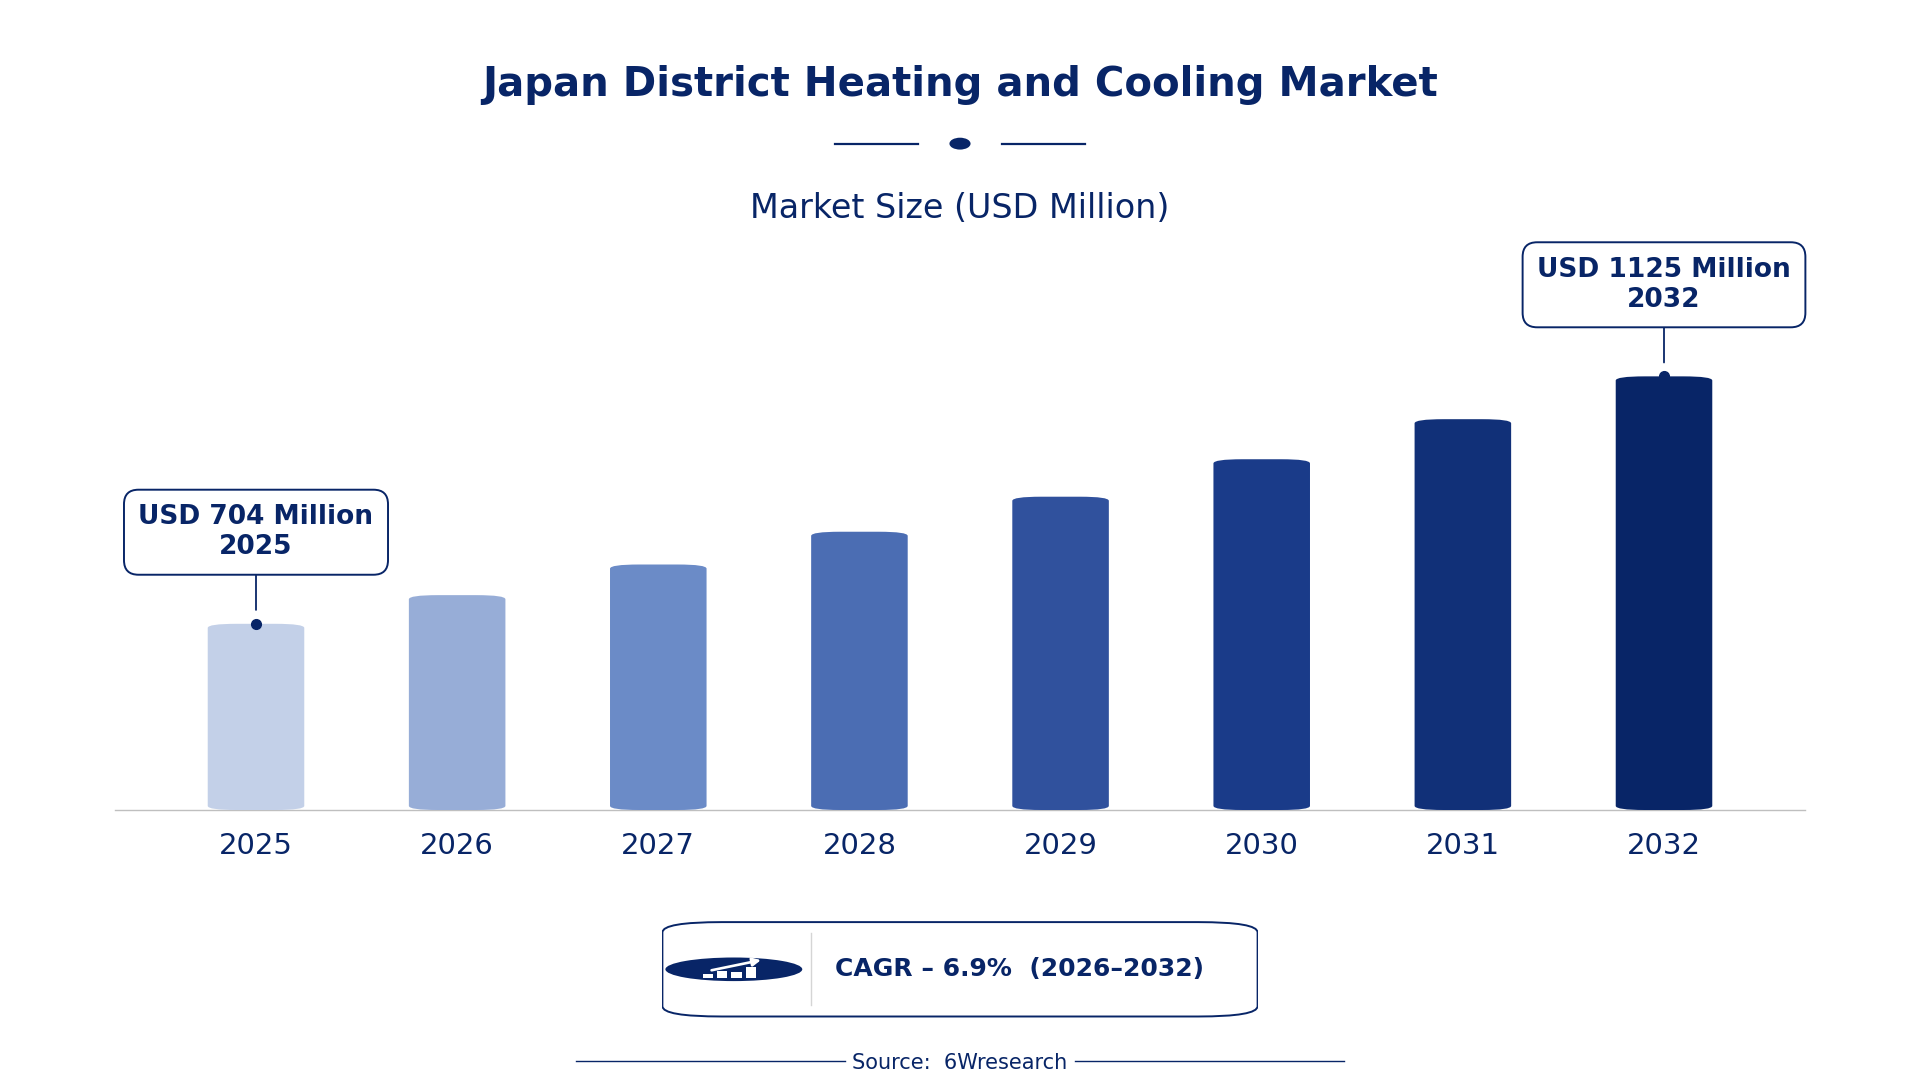
According to 6Wresearch internal database and industry insights, the Japan District Heating and Cooling Market was valued at USD 704 Million in 2025 and is projected to reach USD 1,125 Million by 2032, growing at a CAGR of approximately 6.9% during 2026–2032.
Japan District Heating and Cooling Market Highlights
| Report Metric | Details |
| Report Name | Japan District Heating and Cooling Market (2026-2032) |
| Market Size 2025 | USD 704 Million |
| Market Size 2032 | USD 1,125 Million |
| Absolute Growth 2025–2032 | USD 421 Million |
| CAGR 2026–2032 | 6.9% |
| Peak Annual Growth | 7.7% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Heating Systems (51% share) |
| Leading Application, 2025 | District Heating (50% share) |
| Leading End Use, 2025 | Commercial Buildings (55% share) |
| Leading Form, 2025 | Waterbased (55% share) |
| Leading Distribution Channel, 2025 | B2B Sales (45% share) |
| Fastest-Growing Product Type | Heat Pumps (9.4% CAGR) |
| Fastest-Growing Application | Energy Efficiency (9.0% CAGR) |
| Fastest-Growing End Use | Residential Buildings (8.6% CAGR) |
| Fastest-Growing Distribution Channel | Offline Retail (8.7% CAGR) |
| Growing Sector | residential heating and cooling |
| Key End Users | commercial buildings, residential buildings, industrial sector |
Japan District Heating and Cooling Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
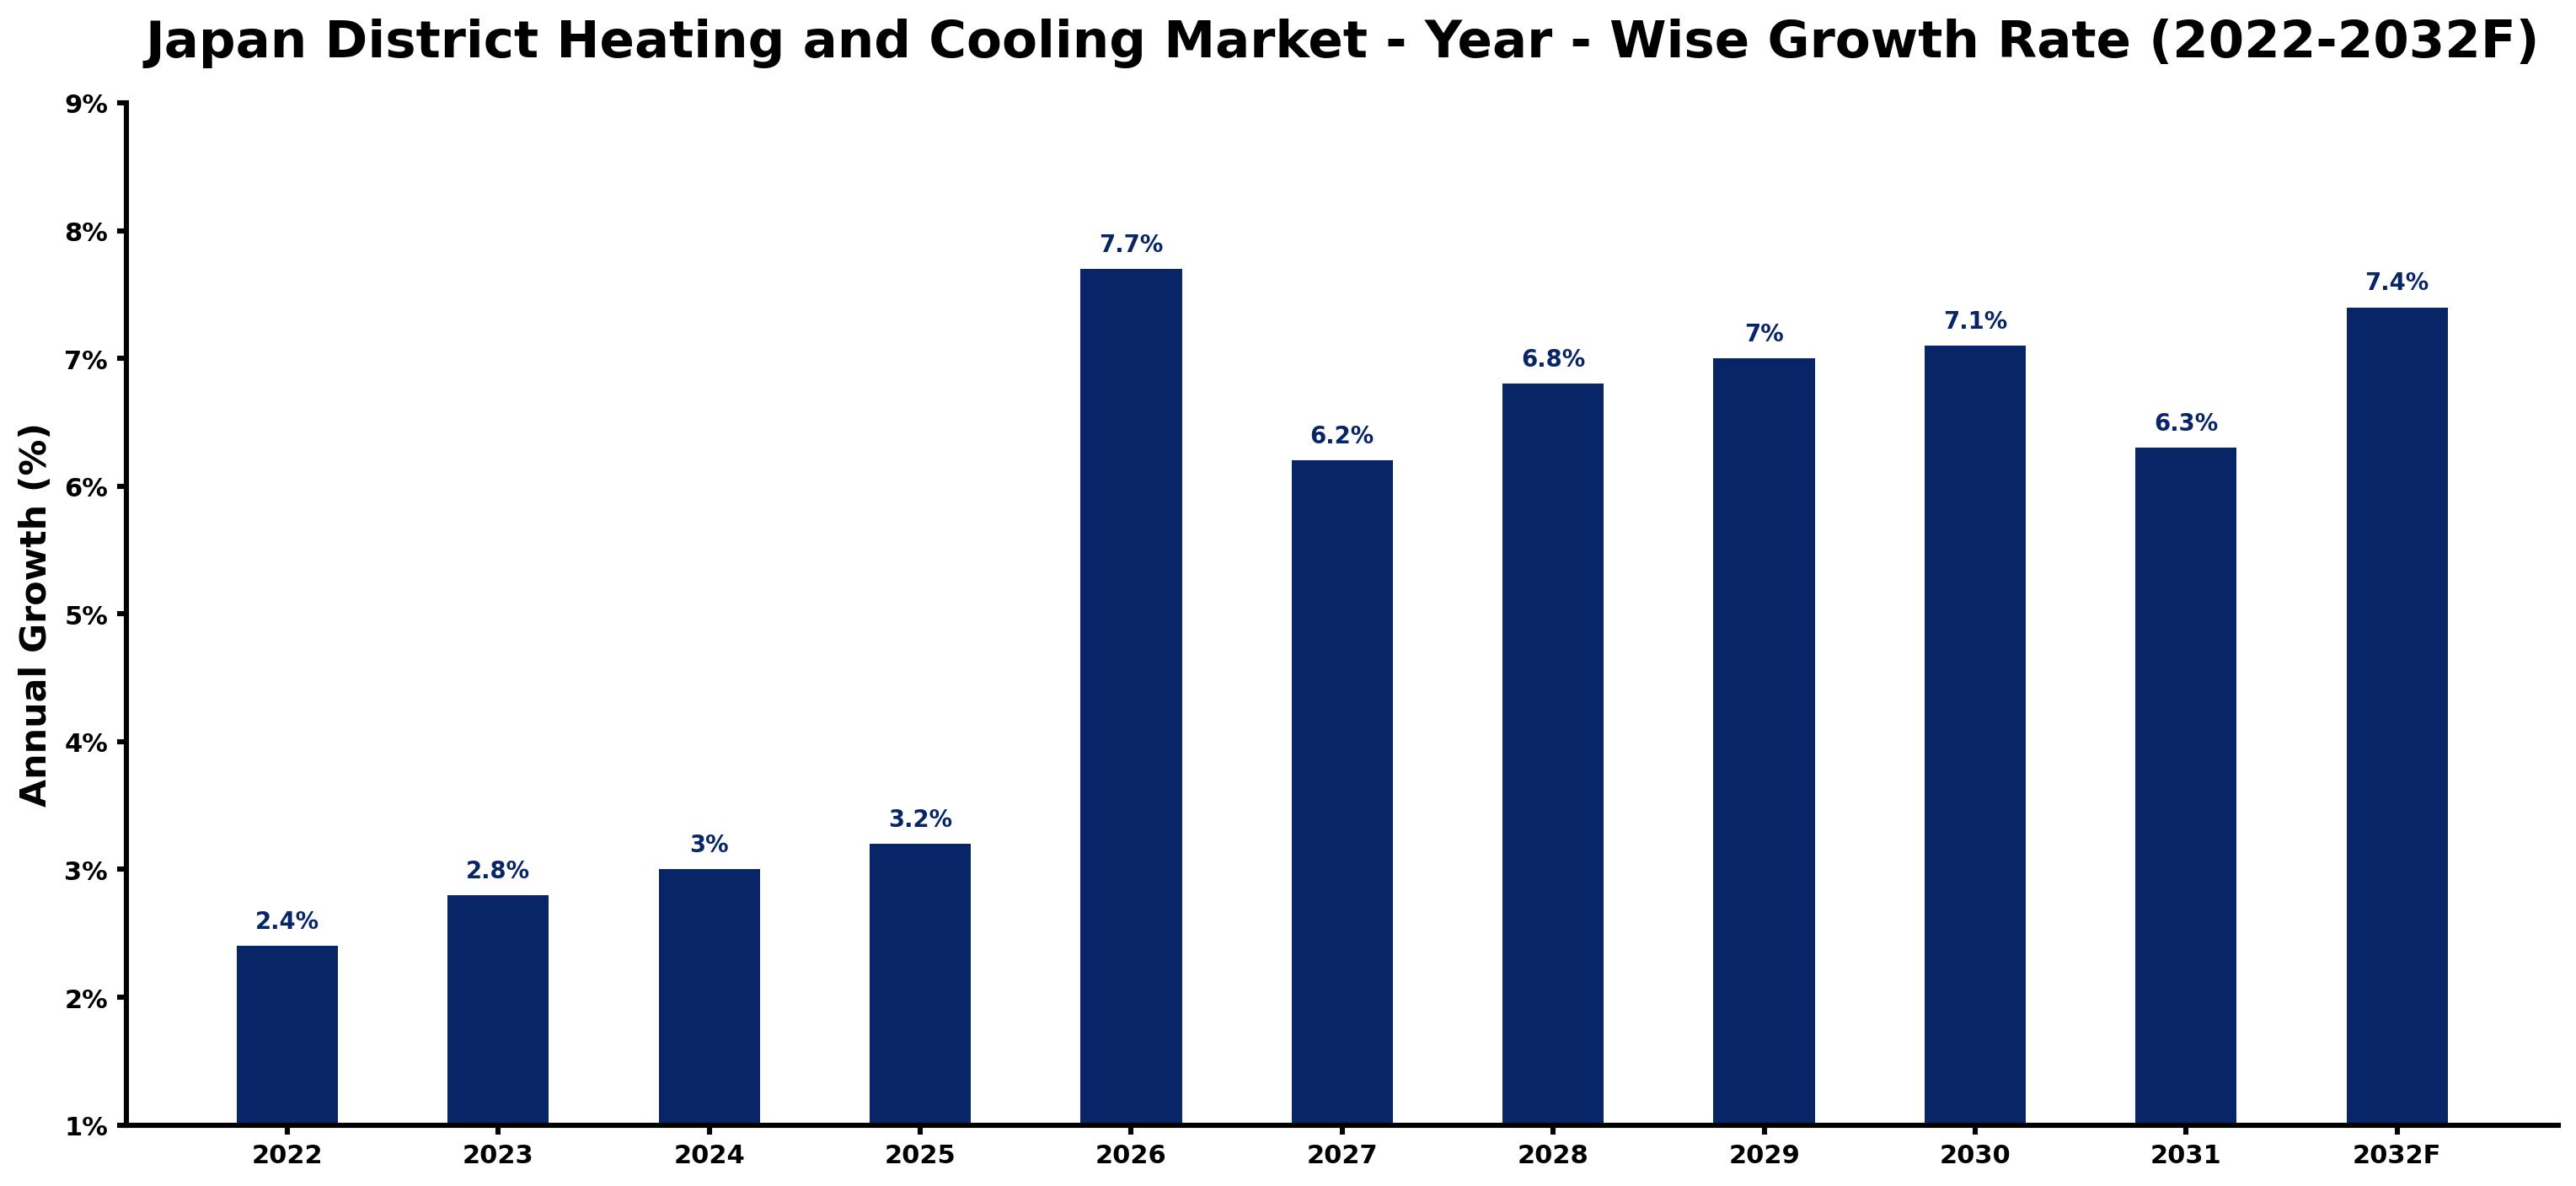
For each year, the table pairs the estimated growth rate with the leading influence on demand, showing how the drivers changed across the period.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.4 | The market showed steady growth, driven by urban demand for energy-efficient solutions. |
| 2023 | 2.8 | Demand for district heating and cooling systems continued to rise due to urbanisation. |
| 2024 | 3.0 | Increased investments in energy-efficient infrastructure supported further growth. |
| 2025 | 3.2 | The market reached a peak growth rate as energy efficiency became a priority. |
| 2026 | 7.7 | A surge in demand for heat pumps is expected to boost market growth. |
| 2027 | 6.2 | Growth is projected to slow slightly as the market adjusts to new capacity levels. |
| 2028 | 6.8 | Demand is expected to increase again, driven by new energy efficiency standards. |
| 2029 | 7.0 | Continued investments in urban infrastructure are projected to support market expansion. |
| 2030 | 7.1 | The market is expected to maintain growth as energy efficiency initiatives gain traction. |
| 2031 | 6.3 | Growth is projected to slow as market maturity begins to set in, but demand will remain strong. |
| 2032 | 7.4 | The market is expected to grow as energy-efficient technologies become standard. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan District Heating and Cooling Market Synopsis
District heating and cooling systems are centralized solutions that deliver heating and cooling to multiple buildings via insulated pipes. In Japan, urban areas with high population density, such as Tokyo, drive demand for these systems due to their energy efficiency and lower emissions. The Japan District Heating and Cooling Market is expanding due to increased investments in energy-efficient infrastructure, supported by government initiatives like the Energy Efficiency Act, which promotes the adoption of these technologies across various sectors, with Tokyo accounting for 70% of district heating demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Urbanisation and population density drive demand for energy-efficient heating solutions. | Driver | High | District Heating |
| Investment in energy-efficient technologies is increasing among commercial buildings. | Driver | High | District Cooling |
| The rising need for energy-efficient solutions presents a significant opportunity. | Opportunity | High | Energy Efficiency |
| Growing residential demand for heating and cooling systems offers investment potential. | Opportunity | High | Residential Buildings |
| High installation costs of district heating systems can deter new projects. | Restraint | High | District Heating |
| Limited awareness of district cooling benefits restricts market growth. | Restraint | Medium | District Cooling |
| The complexity of integrating new systems into existing infrastructure poses challenges. | Challenge | Medium | District Heating |
| Competition from alternative cooling solutions can limit market share. | Challenge | Medium | District Cooling |
Evaluation of Drivers in Japan District Heating and Cooling Market (2026–2032)
Demand rests on the following drivers, each shown with the segment it touches most.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased urban population density drives demand for district heating systems. | District Heating | Tokyo's metropolitan area accounts for 70% of district heating demand, resulting in more installations. |
| Rising energy costs encourage investments in energy-efficient technologies. | District Cooling | The average annual energy consumption for heating in residential buildings is 1,200 kWh, prompting a push for efficiency. |
| Government initiatives promote the adoption of energy-efficient building standards. | Energy Efficiency | The Energy Efficiency Act mandates compliance, stimulating demand for district heating and cooling technologies. |
| Technological advancements in heat pump systems improve efficiency and performance. | Heat Pumps | Japan's total installed capacity for heat pumps is approximately 5 million units, increasing market interest in these solutions. |
| Commercial buildings are increasingly adopting district cooling solutions for cost savings. | Commercial Buildings | With a 55% share in 2025, commercial buildings are major users of these systems. |
Volumes grow on the back of urbanisation, with Tokyo's population density driving demand for district heating systems. The average annual energy consumption for heating in residential buildings is 1,200 kWh, prompting investments in energy-efficient technologies. Technological advancements in heat pump systems, with approximately 5 million units installed, improve efficiency and attract buyers. The commercial sector is increasingly adopting these solutions for cost savings, further boosting market growth. Rising energy costs are prompting more investments in district cooling systems, as businesses seek to reduce operational expenses.
Evaluation of Restraints in Japan District Heating and Cooling Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High installation costs deter new district heating projects. | District Heating | The initial investment for infrastructure can be prohibitive for many developers, often exceeding millions of yen. |
| Limited awareness of district cooling benefits restricts adoption rates. | District Cooling | Many potential users remain unaware of the advantages of district cooling systems, resulting in lower market penetration. |
| Complex integration into existing infrastructure poses challenges for new installations. | District Heating | Upgrading or retrofitting existing systems can be costly and time-consuming, often delaying project timelines significantly. |
| Competition from alternative cooling solutions limits market share. | District Cooling | Emerging technologies may offer cheaper or more efficient alternatives, reducing the attractiveness of district cooling systems. |
| Regulatory hurdles can delay project approvals and implementation. | District Heating | Compliance with multiple regulations can slow down new developments, extending timelines for approvals. |
Japan District Heating and Cooling Market Challenges
Producers face increased costs due to limited local resource availability, raising expenses by up to 15% for heating systems. Distributors encounter delays from a shortage of skilled technicians, which can decrease their revenue by around 10%. Buyers struggle with regulatory compliance under the Energy Efficiency Act, necessitating significant investments that can prolong project timelines by 20%. Competition from alternative energy sources compels buyers to seek lower-cost solutions, risking a 5% reduction in market share for those relying on traditional district heating systems.
Trends in the Japan District Heating and Cooling Market
The shifts below are changing how Japan District Heating and Cooling Market products are bought and supplied.
- Shift towards Energy Efficiency: Japan is increasingly prioritising energy efficiency in building designs, as seen in the Tokyo Metropolitan Government's program promoting energy-efficient buildings. This initiative aims to reduce energy consumption by 20% by 2030.
- Transition from Traditional to Centralised Systems: The shift from traditional heating methods to centralised district heating systems began in 2022, driven by urbanisation. Tokyo's extensive network now supports over 1 million residential units, showcasing the trend's impact.
- Emergence of Heat Pumps as a Preferred Solution: Heat pumps are gaining traction in Japan’s market, with a projected CAGR of 9.4% from 2026 to 2032. This trend is evident in new residential developments across Chiba Prefecture, which are integrating these systems.
- Increase in Commercial Adoption of District Cooling: Commercial buildings are increasingly adopting district cooling solutions, driven by rising energy costs. This trend is evident in the Tokyo metropolitan area, where demand for cooling capacity reached 1,500 MW in 2022.
Investment Opportunities in the Japan District Heating and Cooling Market
Several openings in the Japan District Heating and Cooling Market merit attention from investors.
- District Heating Systems Expansion: With over 1 million residential units connected, there is a strong opportunity to expand district heating systems in urban areas. The Tokyo metropolitan area, accounting for 70% of demand, presents a prime market for investments.
- Growing Demand for Energy Efficiency Solutions: The need for energy-efficient solutions is growing, with a target of 20% reduction in energy consumption by 2030. Residential buildings in urban areas are prime candidates for these upgrades, creating significant market potential.
- Heat Pump Technologies Development: The installed capacity for heat pumps is approximately 5 million units, indicating a gap for further development. Collaborating with local builders in urban regions can facilitate market entry and expansion.
- District Cooling Market Growth: The district cooling market is expanding, with a capacity of 1,500 MW in 2022. Targeting commercial buildings in metropolitan areas can yield substantial returns, as demand continues to rise.
Government Initiatives in the Japan District Heating and Cooling Market
The Building Energy Efficiency Act, amended in 2022, mandates that all new buildings meet energy standards by April 2025. This law drives producers to adopt energy-efficient technologies, ensuring compliance with national energy goals. The Act aims to reduce overall energy consumption in Japan's building sector, promoting sustainability and efficiency.
The Japan District Heating Association supports energy-efficient building initiatives, providing funding for projects that meet specific criteria. This association plays a role in promoting district heating technologies, facilitating approvals for new installations. These efforts aim to improve energy efficiency across the country.
Future Insight of the Japan District Heating and Cooling Market
By 2032, government policies will drive a transition towards energy-efficient building initiatives, reshaping market dynamics. Suppliers will implement ISO 50001 standards for energy management, aligning with national objectives. The Tokyo Metropolitan Government's programme will encourage the adoption of advanced heat pump technologies, improving overall system efficiency. District cooling capacity is expected to reach 2,000 MW, offering buyers substantial energy savings while urban developments in Chiba Prefecture will further integrate district heating systems, creating a more effective energy network.
Market Segmentation Analysis
Japan District Heating and Cooling Market report covers a detailed analysis of the following market segments:
By Product Type – Heating Systems Lead, Heat Pumps Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Heating Systems accounted for 51% of the market by product type in 2025. Heating systems dominate the market due to their essential role in supplying heat to both residential and commercial buildings, particularly in densely populated areas. The extensive network in Tokyo, which connects over 1 million residential units, exemplifies the critical reliance on these systems. The quickest growth will come from Heat Pumps, forecast to expand at a CAGR of 9.4% between 2026 and 2032. Heat pumps are witnessing rapid growth as they offer dual functionality for both heating and cooling, catering to the increasing demand for energy-efficient solutions. With an installed capacity of approximately 5 million units, the market potential for heat pumps is robust and expanding. Suppliers should focus on enhancing their heat pump product lines to capitalise on the growing market demand.
By Application – District Heating Leads, Energy Efficiency Expected to Grow Fastest
With 50% of application revenue in 2025, District Heating was the largest category. District heating is the leading application because it efficiently supplies multiple buildings from a central source, particularly in densely populated areas like Tokyo. This metropolitan area accounts for 70% of the overall district heating demand in Japan, underscoring its significance. Energy Efficiency is projected to grow fastest, at a CAGR of 9.0% during 2026–2032. Energy efficiency is emerging as the fastest-growing focus, spurred by initiatives such as the Energy Efficiency Act that encourages reduced energy consumption. This trend is essential as urban regions strive to lower emissions and promote sustainability. Buyers will increasingly seek solutions that emphasise energy efficiency to adhere to regulatory requirements.
By End Use – Commercial Buildings Lead, Residential Buildings Expected to Grow Fastest
The largest end use category in 2025 was Commercial Buildings, at 55% of revenue. Commercial buildings lead the end-use segment as they require substantial heating and cooling systems to maintain comfortable environments for occupants. This sector's significant demand drives market growth and technological advancements. Residential Buildings are set to record the highest CAGR in this split, 8.6% over 2026–2032. Residential buildings are growing the fastest as consumers become more aware of the need for effective home heating and cooling solutions. The average annual energy consumption for heating in these buildings is around 1,200 kWh, highlighting a substantial opportunity in this segment. Suppliers should tailor their offerings to meet the unique requirements of residential customers.
By Form – Waterbased Leads and Records the Fastest Growth
In 2025, Waterbased led the form split with a 55% share. Waterbased systems are the predominant form for heating due to their efficiency and effectiveness in delivering heat across various applications. Their widespread use in district heating networks solidifies their position as the market leader. Waterbased is also forecast to expand faster than any other category, at a CAGR of 8.6% over 2026–2032. Waterbased systems are also the fastest-growing form, as they are increasingly recognised for their versatility in both heating and cooling applications. This dual functionality supports their expanding adoption in the market. Suppliers should continue to innovate within the waterbased segment to maintain competitive advantage.
By Distribution Channel – B2B Sales Leads, Offline Retail Expected to Grow Fastest
B2B Sales held 45% of the Japan District Heating and Cooling Market by distribution channel in 2025. B2B sales are the primary distribution channel, catering to large installations that are common in commercial and industrial settings. This channel effectively meets the needs of major buyers looking for comprehensive heating and cooling solutions. The quickest growth will come from Offline Retail, forecast to expand at a CAGR of 8.7% between 2026 and 2032. Offline retail is the fastest-growing distribution channel, serving smaller-scale purchases and immediate consumer needs, despite being less common. This trend indicates a shift towards more accessible purchasing options for end-users. Suppliers should strengthen their offline retail strategies to capture emerging market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan District Heating and Cooling Market Outlook
- Market Size of Japan District Heating and Cooling Market,2025
- Forecast of Japan District Heating and Cooling Market, 2032
- Historical Data and Forecast of Japan District Heating and Cooling Revenues & Volume for the Period 2022-2032
- Japan District Heating and Cooling Market Trend Evolution
- Japan District Heating and Cooling Market Drivers and Challenges
- Japan District Heating and Cooling Price Trends
- Japan District Heating and Cooling Porter's Five Forces
- Japan District Heating and Cooling Industry Life Cycle
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Heating Systems for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Cooling Systems for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Heat Pumps for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By District Heating for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By District Cooling for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Energy Efficiency for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By End Use for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Commercial Buildings for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Residential Buildings for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Industrial for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Form for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Waterbased for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Airbased for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Refrigerant for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Distribution Channel for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Online Retail for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By Offline Retail for the Period 2022-2032
- Historical Data and Forecast of Japan District Heating and Cooling Market Revenues & Volume By B2B Sales for the Period 2022-2032
- Japan District Heating and Cooling Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By End Use
- Market Opportunity Assessment By Form
- Market Opportunity Assessment By Distribution Channel
- Japan District Heating and Cooling Top Companies Market Share
- Japan District Heating and Cooling Competitive Benchmarking By Technical and Operational Parameters
- Japan District Heating and Cooling Company Profiles
- Japan District Heating and Cooling Key Strategic Recommendations
Market Covered
The following segment groups are covered in the report.
By Product Type
- Heating Systems
- Cooling Systems
- Heat Pumps
By Application
- District Heating
- District Cooling
- Energy Efficiency
By End Use
- Commercial Buildings
- Residential Buildings
- Industrial
By Form
- Waterbased
- Airbased
- Refrigerant
By Distribution Channel
- Online Retail
- Offline Retail
- B2B Sales































