Japan IDG/ACG Generator Market Size & Growth Rate
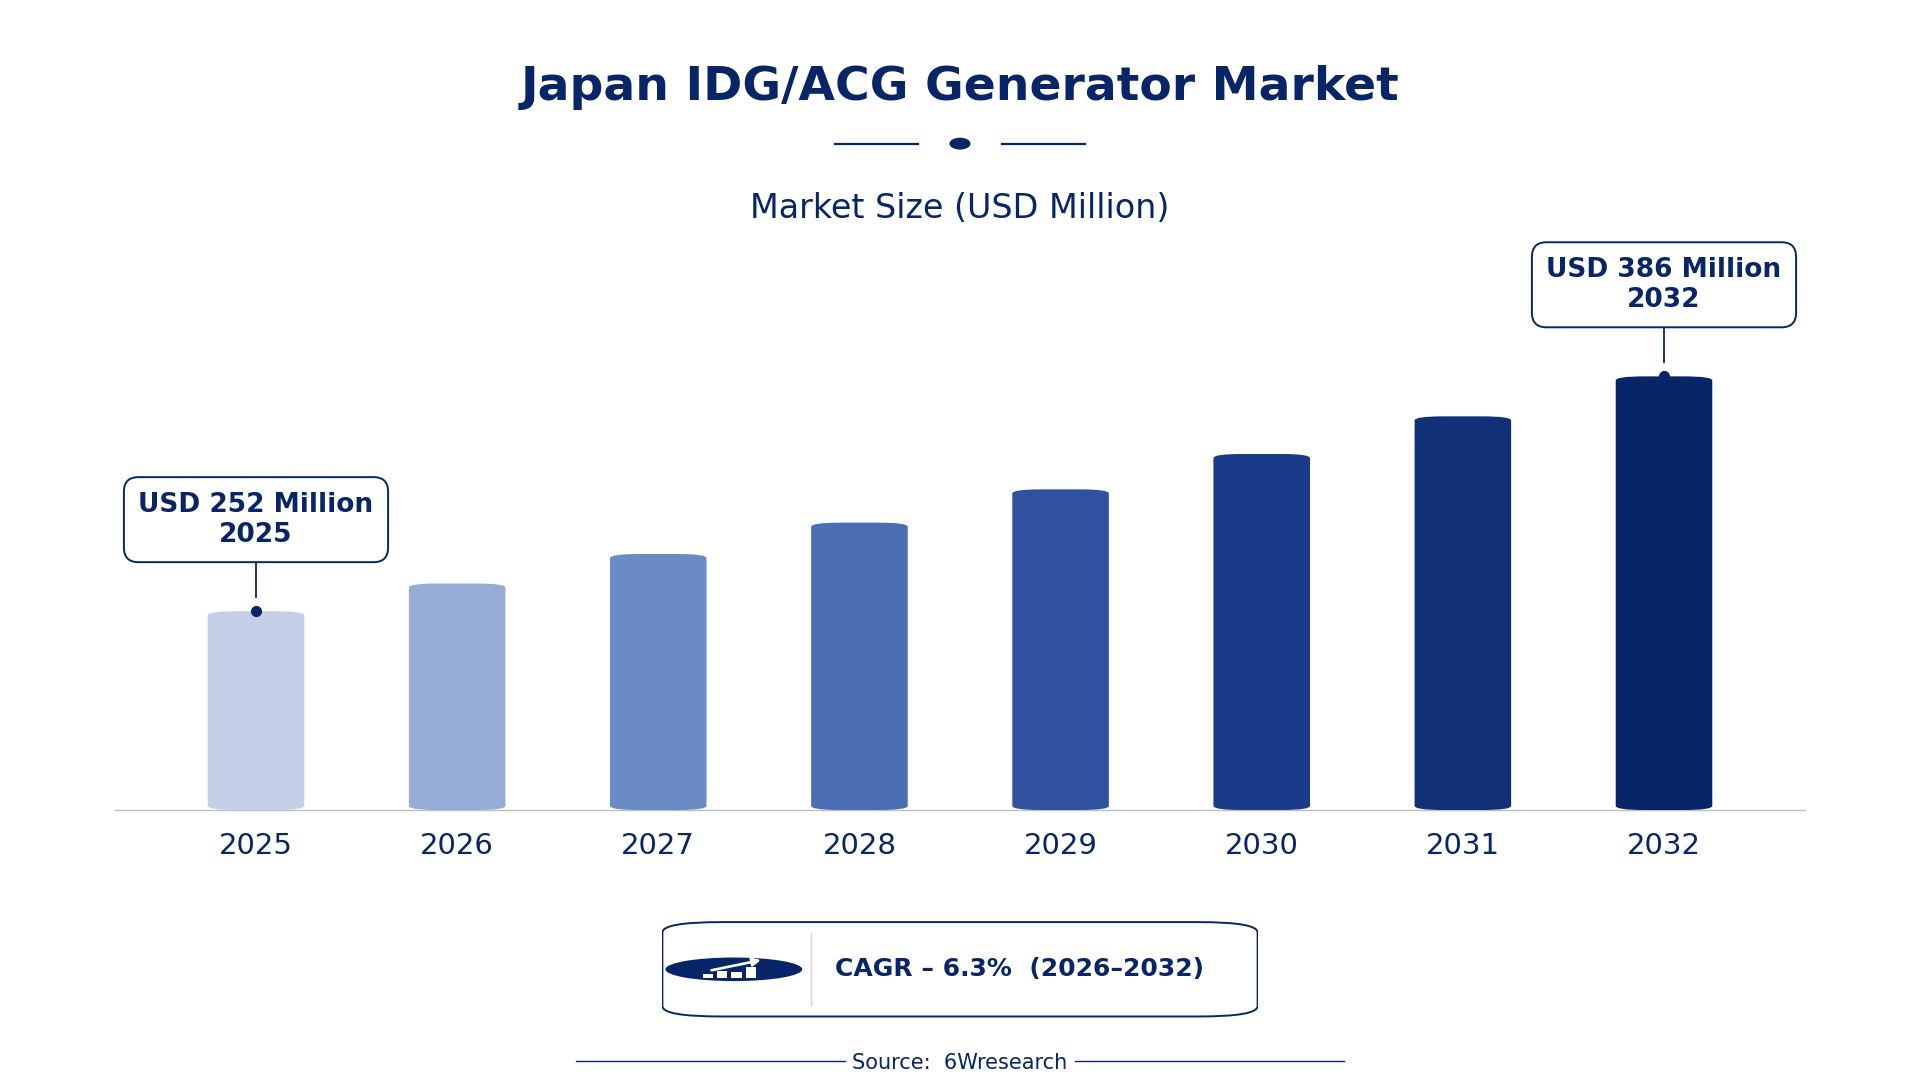
According to 6Wresearch internal database and industry insights, the Japan IDG/ACG Generator Market was valued at USD 252 Million in 2025 and is projected to reach USD 386 Million by 2032, growing at a CAGR of approximately 6.3% during 2026–2032.
Japan IDG/ACG Generator Market Highlights
| Report Metric | Details |
| Report Name | Japan IDG/ACG Generator Market (2026-2032) |
| Market Size 2025 | USD 252 Million |
| Market Size 2032 | USD 386 Million |
| Absolute Growth 2025–2032 | USD 134 Million |
| CAGR 2026–2032 | 6.3% |
| Peak Annual Growth | 7.3% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Generator Type, 2025 | IDG (Integrated Drive Gen) (40% share) |
| Leading Technology Used, 2025 | Constant-Speed Drive (45% share) |
| Leading Aircraft Type, 2025 | Commercial Jets (43% share) |
| Leading End User, 2025 | Aerospace OEMs (41% share) |
| Fastest-Growing Generator Type | Hybrid Gen Units (9.1% CAGR) |
| Fastest-Growing Technology Used | Auxiliary Power Conversion (9.3% CAGR) |
| Fastest-Growing Aircraft Type | Regional Aircraft (8.7% CAGR) |
| Fastest-Growing End User | Maintenance Operators (8.0% CAGR) |
| Growing Sector | Aerospace |
| Key End Users | Aerospace OEMs, Maintenance Operators, Defense Contractors |
Japan IDG/ACG Generator Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
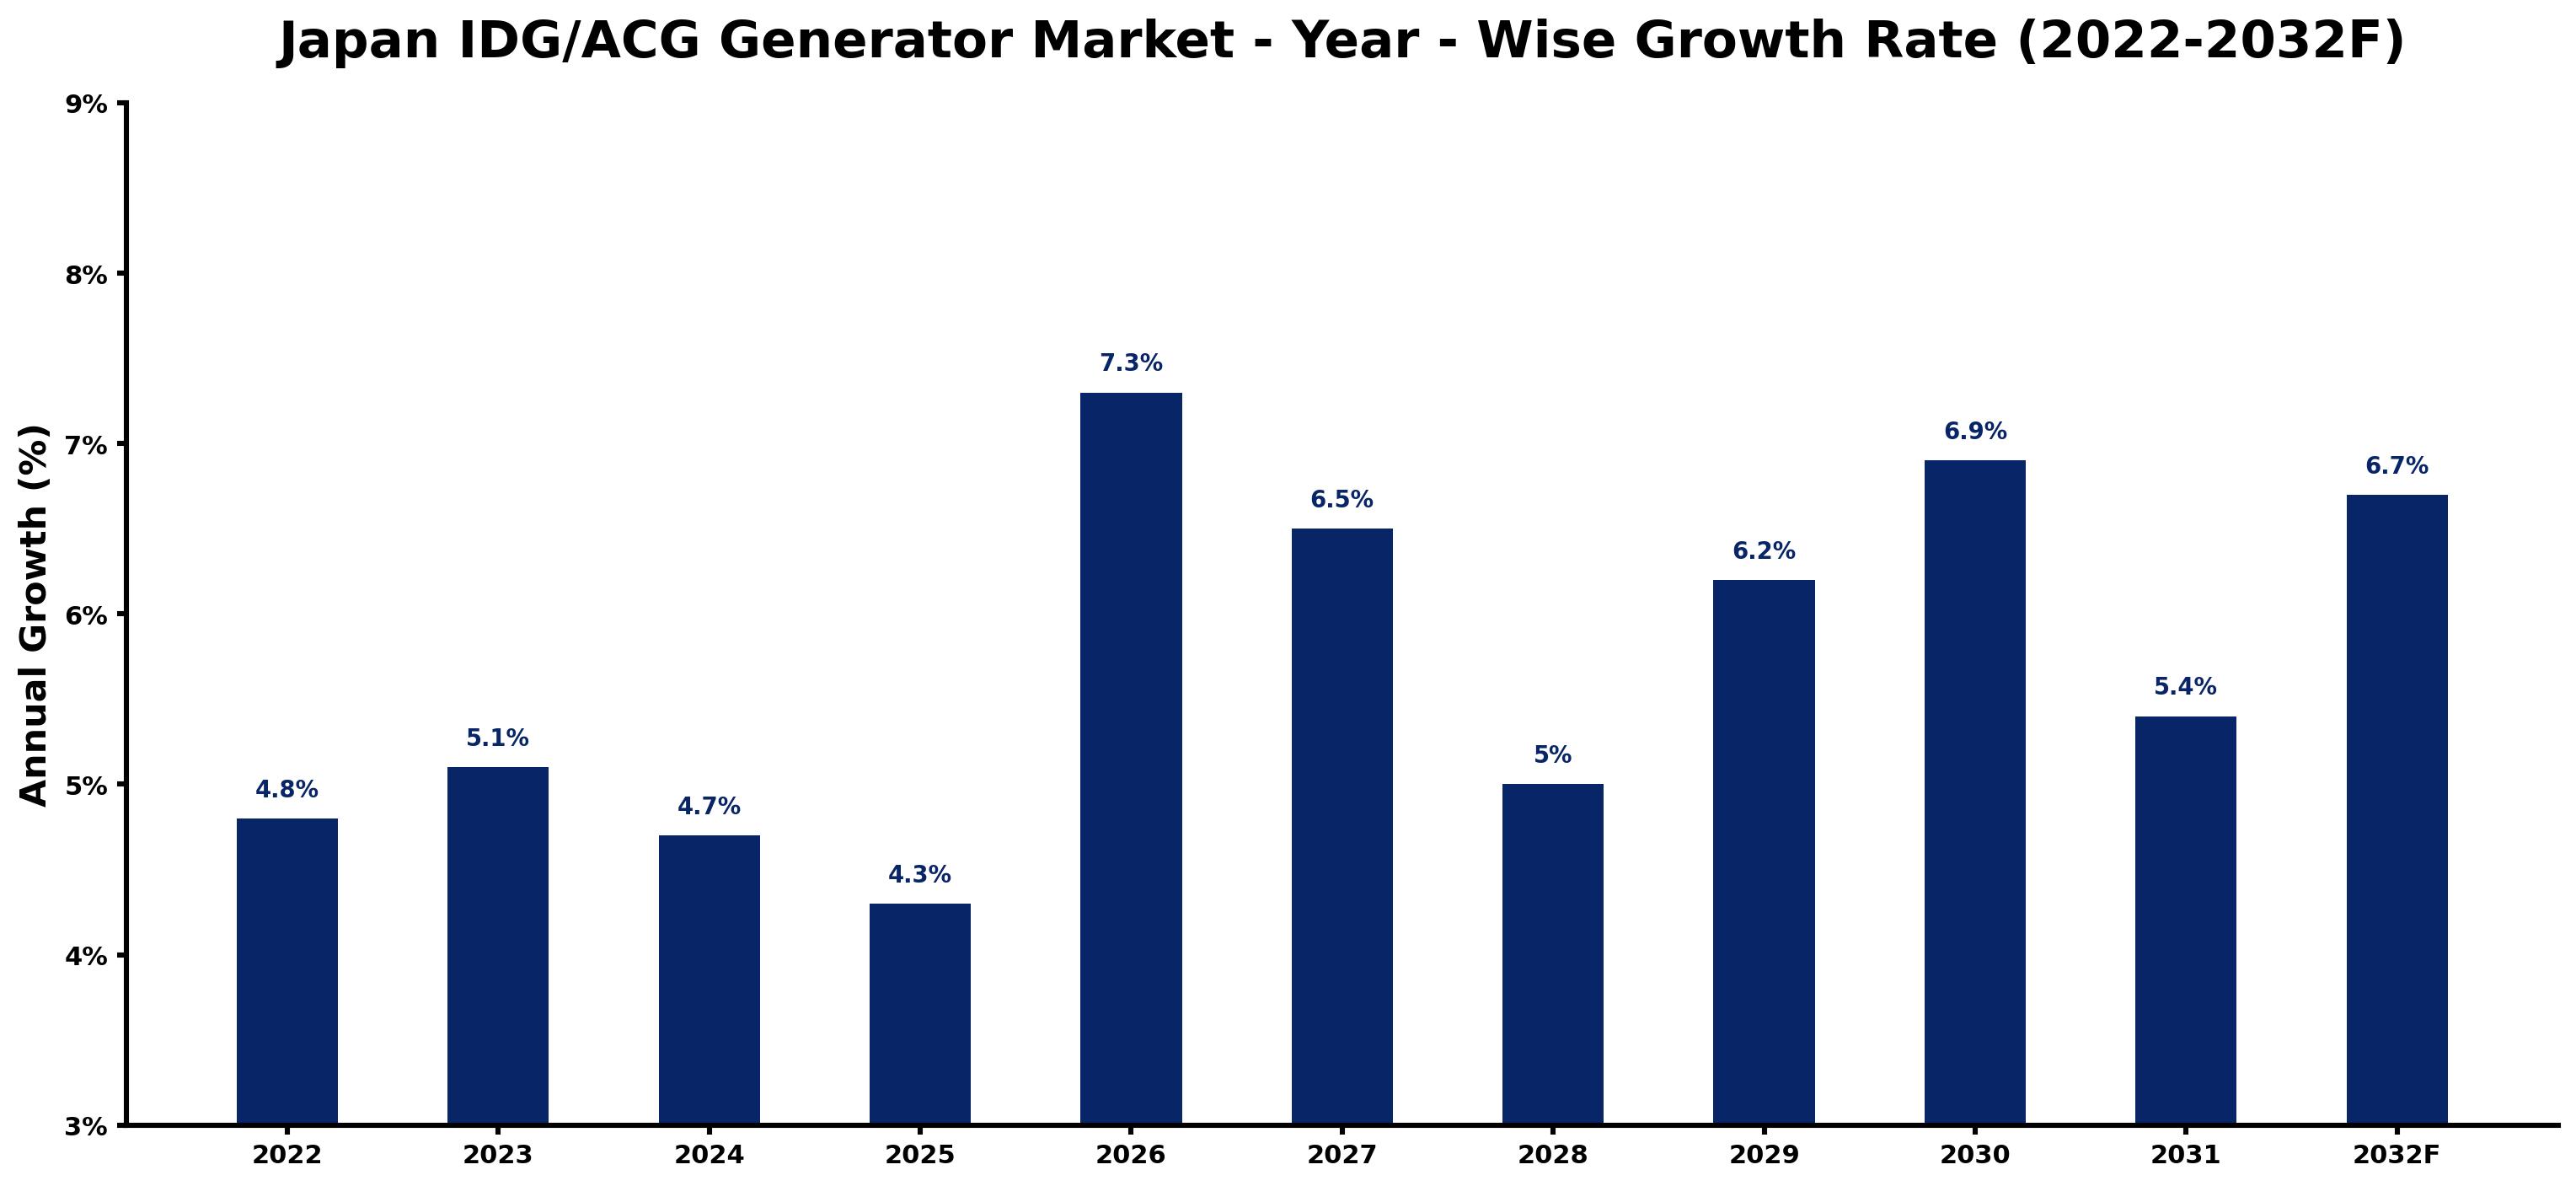
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.8 | The market experienced steady growth due to ongoing aerospace projects and demand from manufacturers. |
| 2023 | 5.1 | Growth was supported by increased production rates in the aerospace sector and rising defense spending. |
| 2024 | 4.7 | A slight slowdown occurred as manufacturers adjusted to supply chain challenges and market conditions. |
| 2025 | 4.3 | The market continued to slow as manufacturers focused on efficiency and cost management amid fluctuating demand. |
| 2026 | 7.3 | Growth is expected to accelerate as domestic aircraft production initiatives gain traction, driving demand for generators. |
| 2027 | 6.5 | A moderate slowdown is projected as manufacturers face challenges in sourcing materials and components. |
| 2028 | 5.0 | The market is expected to experience another slowdown as demand stabilises, reflecting a mature phase in production. |
| 2029 | 6.2 | Growth is projected to pick up again, driven by increased orders from regional aircraft manufacturers and maintenance operators. |
| 2030 | 6.9 | A continued rise in demand is anticipated as the aerospace sector expands its production capabilities. |
| 2031 | 5.4 | The market is projected to slow slightly as manufacturers face competition and pricing pressures from international suppliers. |
| 2032 | 6.7 | Growth is expected to accelerate again, supported by new aerospace projects and increased defense budgets. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan IDG/ACG Generator Market Synopsis
IDG/ACG generators are advanced electrical power generation systems primarily used in aircraft, ensuring reliable power for various systems. In Japan, the aerospace industry contributes approximately 1.2 trillion yen to the economy, with strong demand from domestic manufacturers and maintenance operators. The market is expanding due to rising defense spending, projected to reach 5 trillion yen by 2025, alongside initiatives aimed at increasing domestic aircraft production by 30%.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising defense spending increases demand for military aircraft, driving generator sales. | Driver | High | IDG (Integrated Drive Gen) |
| Aerospace OEMs are investing in new aircraft designs, boosting generator requirements. | Driver | High | ACG (Auxiliary Gen) |
| The growing focus on regional aircraft production presents opportunities for suppliers. | Opportunity | High | Regional Aircraft |
| Increased demand for maintenance services creates openings for generator suppliers. | Opportunity | Medium | Maintenance Operators |
| Supply chain disruptions hinder timely production and delivery of generators. | Restraint | High | DC Starter Generator |
| High production costs limit the competitiveness of local manufacturers. | Restraint | Medium | Constant-Speed Drive |
| Intense competition from international suppliers pressures local pricing strategies. | Challenge | High | Aerospace OEMs |
| Technological advancements in alternative power systems challenge traditional generators. | Challenge | Medium | Hybrid Gen Units |
Evaluation of Drivers in Japan IDG/ACG Generator Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased defense spending drives demand for military aircraft, boosting IDG sales. | IDG (Integrated Drive Gen) | Defense spending in Japan for aerospace is projected to reach 5 trillion yen by 2025. |
| Aerospace OEMs are investing in new aircraft designs, increasing ACG demand. | ACG (Auxiliary Gen) | The Japanese government aims to increase domestic aircraft production by 30% by 2025. |
| Rising passenger traffic fuels demand for commercial jets, boosting generator sales. | Commercial Jets | The installed base of commercial jets in Japan is around 500 units. |
| Regional aircraft production is expanding, creating demand for generators. | Regional Aircraft | The segment is growing as manufacturers respond to the increasing need for short-haul flights. |
| Maintenance operators are expanding their services, increasing demand for replacement generators. | Maintenance Operators | Aerospace OEMs in Japan employ over 50,000 skilled workers, increasing service capacity. |
A wider customer base explains much of the growth, as increased defense spending is projected to reach 5 trillion yen by 2025, prompting military aircraft manufacturers to invest in IDG systems. The goal to boost domestic aircraft production by 30% by 2025 stimulates demand for ACG units. The installed base of commercial jets in Japan is around 500 units, driving the need for reliable power systems. The expansion of regional aircraft production creates new opportunities for generator suppliers, while maintenance operators are increasing their service offerings, further driving demand for replacement generators.
Evaluation of Restraints in Japan IDG/ACG Generator Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder timely production and delivery of generators. | DC Starter Generator | Challenges in sourcing materials lead to delays in generator availability for manufacturers. |
| High production costs limit the competitiveness of local manufacturers. | Constant-Speed Drive | Rising costs of materials and labour affect pricing strategies for local producers. |
| Intense competition from international suppliers pressures local pricing strategies. | Aerospace OEMs | Foreign manufacturers often offer lower prices, impacting local sales. |
| Technological advancements in alternative power systems challenge traditional generators. | Hybrid Gen Units | Emerging technologies attract investment, diverting attention from conventional generator systems. |
| Regulatory compliance increases operational costs for manufacturers. | ACG (Auxiliary Gen) | Strict standards require substantial investment in testing and certification processes. |
Japan IDG/ACG Generator Market Challenges
Japan's aerospace industry encounters intense competition from global manufacturers, forcing local producers to reduce prices and diminishing profit margins for suppliers. High-performance material shortages disrupt supply chains, leading to production delays that can extend timelines by up to six months for manufacturers. Regulatory requirements from the Ministry of Economy, Trade and Industry raise compliance costs, imposing additional financial burdens on producers. Rapid technological changes create a gap for local firms, risking obsolescence and limiting access to modern solutions for buyers who depend on advanced systems.
Trends in the Japan IDG/ACG Generator Market
The shifts below are changing how Japan IDG/ACG Generator Market products are bought and supplied.
- Launch of the Economic Security Promotion Act: The Economic Security Promotion Act, enacted in 2022, supports supply-chain resilience for critical aerospace products. This initiative aims to secure the production of essential components, ensuring that manufacturers can meet demand without interruption.
- Increase in Domestic Aircraft Production: Japan's government aims to boost domestic aircraft production by 30% by 2025, creating a surge in demand for IDG/ACG generators. This initiative is expected to drive investments in local manufacturing capabilities, improving the supply chain.
- Focus on Regional Aircraft Growth: The regional aircraft segment is gaining traction, with a projected CAGR of 8.7% from 2026 to 2032. This trend reflects the increasing need for short-haul flights, prompting manufacturers to invest in efficient power generation solutions.
- Expansion of Maintenance Services: Maintenance operators are expanding their service offerings, leading to increased demand for replacement generators. The growing emphasis on aircraft reliability and performance is driving this trend, with operators seeking advanced generator systems.
Investment Opportunities in the Japan IDG/ACG Generator Market
The following opportunities in the Japan IDG/ACG Generator Market pair current demand with a clear way in.
- Growing Demand for Regional Aircraft: The regional aircraft segment presents opportunities for suppliers, with growth driven by increasing passenger traffic. Manufacturers can target this segment by partnering with local aerospace OEMs to meet rising demand.
- Investment in Maintenance Services: The expansion of maintenance services creates a gap in generator supply, with a need for reliable systems. Suppliers can enter this market by collaborating with maintenance operators to provide tailored solutions.
- Focus on Aerospace Supply Chain Resilience: The Economic Security Promotion Act supports investments in supply chain resilience. Suppliers can benefit by aligning with local manufacturers to strengthen production capabilities and meet demand.
- Emerging Technologies in Hybrid Systems: The growing interest in hybrid systems creates opportunities for suppliers to innovate. By investing in research and development, companies can cater to the evolving needs of aerospace manufacturers.
Government Initiatives in the Japan IDG/ACG Generator Market
The Economic Security Promotion Act, enacted in 2022, impacts buyers by supporting supply-chain resilience for critical aerospace products. This measure ensures that manufacturers can secure essential components, improving production reliability and reducing delays in aircraft systems. The Japanese government aims to increase domestic aircraft production by 30% by 2025, which is expected to boost local manufacturing capabilities and create jobs in the aerospace sector.
The Battery Industry Strategy, launched by METI in August 2022, targets substantial domestic battery manufacturing capacity by 2030. This initiative aims to support the aerospace sector by ensuring a steady supply of batteries for power generation systems, thereby improving operational efficiency for manufacturers.
Future Insight of the Japan IDG/ACG Generator Market
The investment pipeline for aerospace technology will expand, with government initiatives aimed at increasing domestic aircraft production by 30% by 2025, generating new opportunities for suppliers. By 2032, demand for IDG/ACG generators will grow as the installed base of commercial jets reaches around 600 units, necessitating enhanced production capabilities. New aerospace programmes will facilitate collaboration among industry stakeholders, driving innovation. Adoption of ISO 9001 standards will improve manufacturing processes, ensuring quality and reliability for buyers.
Market Segmentation Analysis
Japan IDG/ACG Generator Market report covers a detailed analysis of the following market segments:
By Generator Type – IDG (Integrated Drive Gen) Leads, Hybrid Gen Units Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, IDG (Integrated Drive Gen) took 40% of generator type revenue in 2025, more than any other category. IDG units hold the largest share as they are essential for providing primary power to aircraft systems, which is critical for operational efficiency. The installed base of around 500 commercial jets in Japan predominantly utilises IDG technology, reinforcing its preference among manufacturers. Over 2026–2032, Hybrid Gen Units are expected to post the fastest growth, at a CAGR of 9.1%. The rapid growth of Hybrid Gen Units is attributed to the increasing adoption of advanced aircraft designs that require versatile power solutions. As the aerospace sector in Japan aims to enhance domestic production, the demand for these units is projected to rise significantly. Suppliers should focus on developing Hybrid Gen technologies to capitalise on emerging market opportunities.
By Technology Used – Constant-Speed Drive Leads, Auxiliary Power Conversion Expected to Grow Fastest
Constant-Speed Drive held 45% of the Japan IDG/ACG Generator Market by technology used in 2025. Constant-Speed Drive technology leads the market as it ensures stable power output, which is vital for the reliability of aircraft systems. This technology is widely implemented across the existing aircraft fleet, solidifying its dominant position in the industry. Auxiliary Power Conversion is projected to grow fastest, at a CAGR of 9.3% during 2026–2032. Auxiliary Power Conversion is experiencing swift growth due to the rising need for efficient power management across various aircraft systems. As aircraft designs advance, the demand for this technology is expected to increase, further solidifying its market presence. Buyers will benefit from investing in advanced power conversion technologies to improve aircraft operational efficiency.
By Aircraft Type – Commercial Jets Lead, Regional Aircraft Expected to Grow Fastest
In 2025, Commercial Jets led the aircraft type split with a 43% share. Commercial Jets represent the largest segment, serving as the primary mode of passenger transport and accounting for a substantial share of the installed aircraft in Japan. The ongoing demand for air travel ensures that this segment remains a focal point for manufacturers. The quickest growth will come from Regional Aircraft, forecast to expand at a CAGR of 8.7% between 2026 and 2032. Regional Aircraft are witnessing the fastest growth, driven by the increasing popularity of short-haul flights among travellers. This trend indicates a shift in market dynamics, prompting more investments in the production of regional aircraft. Suppliers should adapt their strategies to meet the rising requirements of regional aircraft manufacturers.
By End User – Aerospace OEMs Lead, Maintenance Operators Expected to Grow Fastest
Aerospace OEMs accounted for 41% of the market by end user in 2025. Aerospace OEMs are the leading end users, acting as the primary manufacturers of IDG systems and thus driving demand for these technologies. Their pivotal role in the aerospace supply chain ensures they maintain a considerable market share. Maintenance Operators are set to record the highest CAGR in this split, 8.0% over 2026–2032. Maintenance Operators are experiencing the fastest growth as the need for aircraft maintenance services escalates with the expanding fleet size. This trend highlights the importance of reliable power generation systems in sustaining operational efficiency. Suppliers must enhance their focus on maintenance solutions to address the increasing demands of service providers.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan IDG/ACG Generator Market Outlook
- Market Size of Japan IDG/ACG Generator Market, 2025
- Forecast of Japan IDG/ACG Generator Market, 2032
- Historical Data and Forecast of Japan IDG/ACG Generator Revenues & Volume for the Period 2022-2032F
- Japan IDG/ACG Generator Market Trend Evolution
- Japan IDG/ACG Generator Market Drivers and Challenges
- Japan IDG/ACG Generator Price Trends
- Japan IDG/ACG Generator Porter's Five Forces
- Japan IDG/ACG Generator Industry Life Cycle
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Generator Type for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By IDG (Integrated Drive Gen) for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By ACG (Auxiliary Gen) for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Hybrid Gen Units for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By DC Starter Generator for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Technology Used for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Constant-Speed Drive for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Auxiliary Power Conversion for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By IDG + Battery Backup for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Starter/Power Hybrid for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Aircraft Type for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Commercial Jets for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Regional Aircraft for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Military Aircraft for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Helicopters for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Aerospace OEMs for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Maintenance Operators for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Defense Contractors for the Period 2022-2032F
- Historical Data and Forecast of Japan IDG/ACG Generator Market Revenues & Volume By Rotorcraft Manufacturers for the Period 2022-2032F
- Japan IDG/ACG Generator Import Export Trade Statistics
- Market Opportunity Assessment By Generator Type
- Market Opportunity Assessment By Technology Used
- Market Opportunity Assessment By Aircraft Type
- Market Opportunity Assessment By End User
- Japan IDG/ACG Generator Top Companies Market Share
- Japan IDG/ACG Generator Competitive Benchmarking By Technical and Operational Parameters
- Japan IDG/ACG Generator Company Profiles
- Japan IDG/ACG Generator Key Strategic Recommendations
Market Covered
The report covers the following segments.
By Generator Type
- IDG (Integrated Drive Gen)
- ACG (Auxiliary Gen)
- Hybrid Gen Units
- DC Starter Generator
By Technology Used
- Constant-Speed Drive
- Auxiliary Power Conversion
- IDG + Battery Backup
- Starter/Power Hybrid
By Aircraft Type
- Commercial Jets
- Regional Aircraft
- Military Aircraft
- Helicopters
By End User
- Aerospace OEMs
- Maintenance Operators
- Defense Contractors
- Rotorcraft Manufacturers































