Japan Semiconductor Etchant / Etchants Market Size & Growth Rate
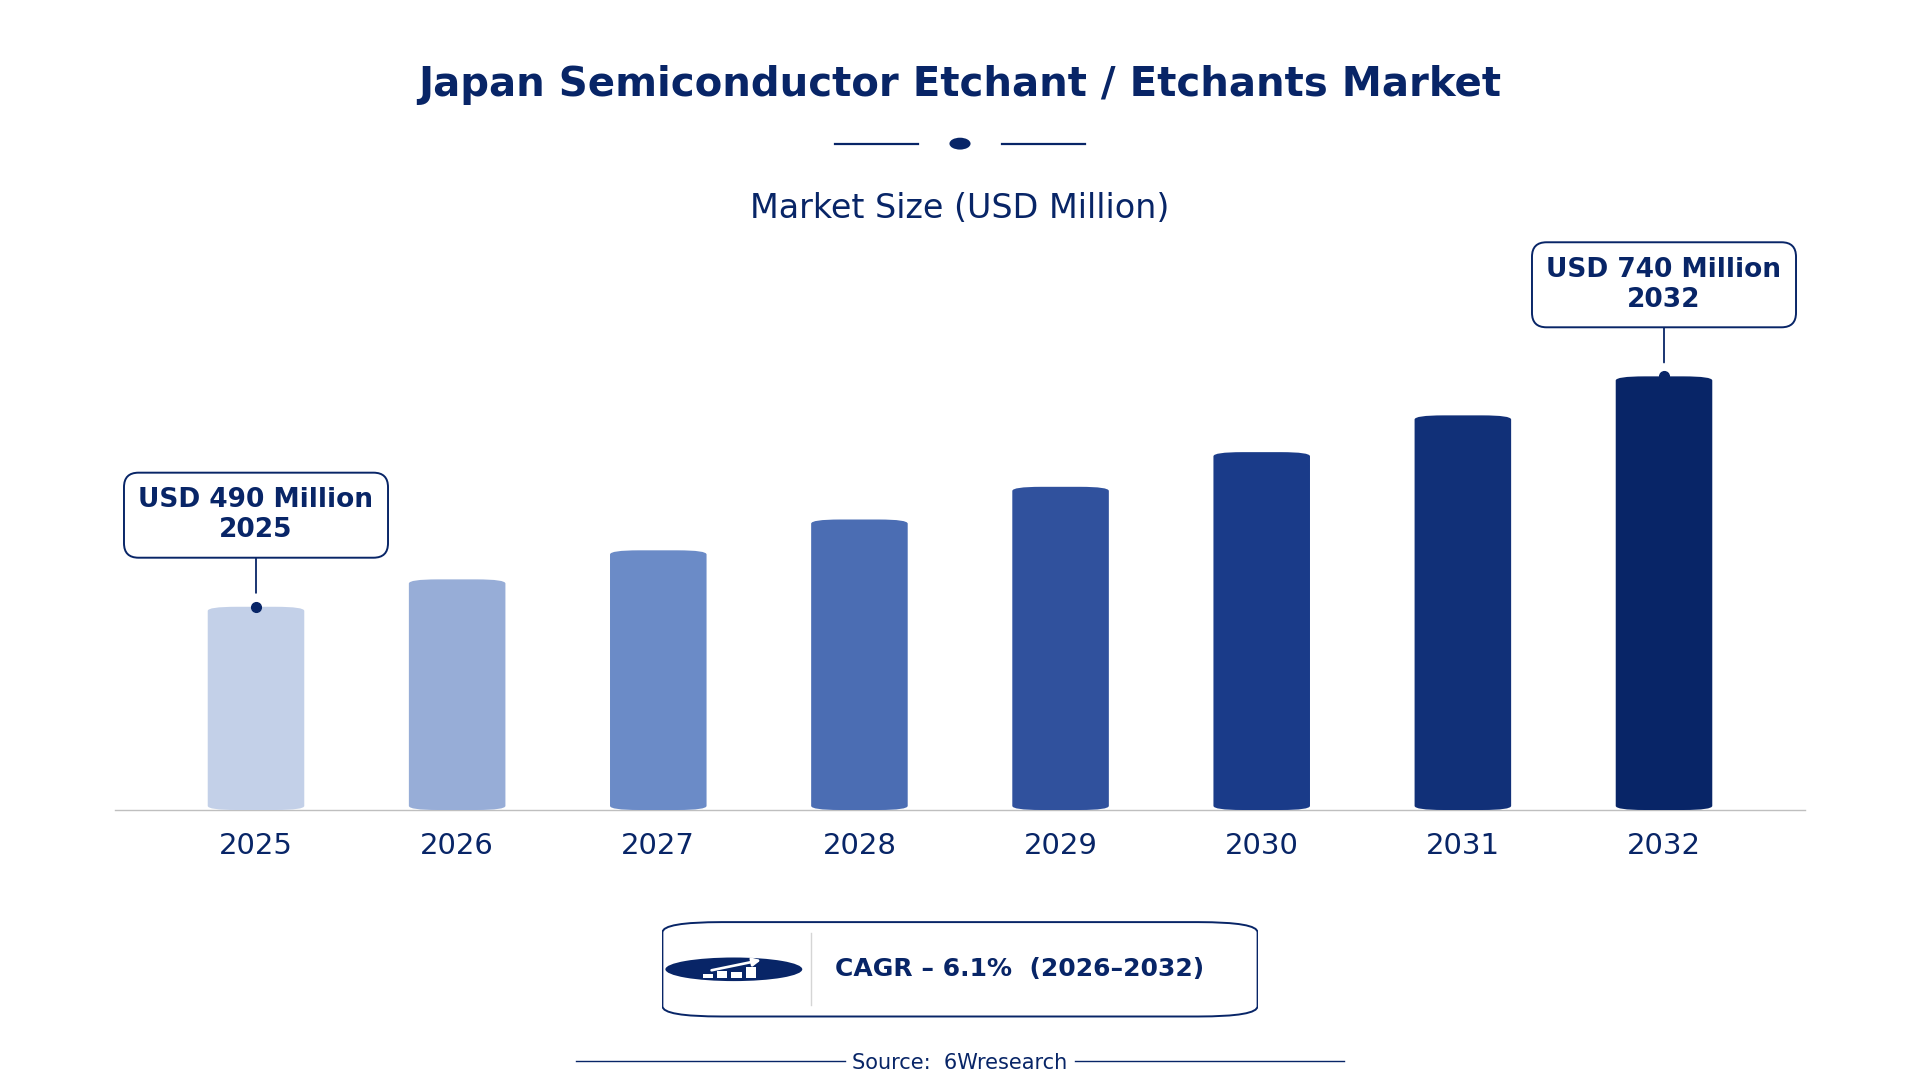
According to 6Wresearch internal database and industry insights, the Japan Semiconductor Etchant / Etchants Market was valued at USD 490 Million in 2025 and is projected to reach USD 740 Million by 2032, growing at a CAGR of approximately 6.1% during 2026–2032.
Japan Semiconductor Etchant / Etchants Market Highlights
| Report Metric | Details |
| Report Name | Japan Semiconductor Etchant / Etchants Market (2026-2032) |
| Market Size 2025 | USD 490 Million |
| Market Size 2032 | USD 740 Million |
| Absolute Growth 2025–2032 | USD 250 Million |
| CAGR 2026–2032 | 6.1% |
| Peak Annual Growth | 7.4% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Etchant Type, 2025 | Wet Etchants (49% share) |
| Leading Target Material, 2025 | Silicon/Oxides (43% share) |
| Leading Application Type, 2025 | Wet Bench Etching (51% share) |
| Leading End User, 2025 | Foundries (49% share) |
| Fastest-Growing Etchant Type | Dry Etchants (8.5% CAGR) |
| Fastest-Growing Target Material | Metal Layers (8.6% CAGR) |
| Fastest-Growing Application Type | Plasma Etching (8.2% CAGR) |
| Fastest-Growing End User | Memory Device Makers (8.1% CAGR) |
| Growing Sector | semiconductor manufacturing |
| Key End Users | foundries, memory device makers, advanced node fabs, wafer processing plants |
Japan Semiconductor Etchant / Etchants Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
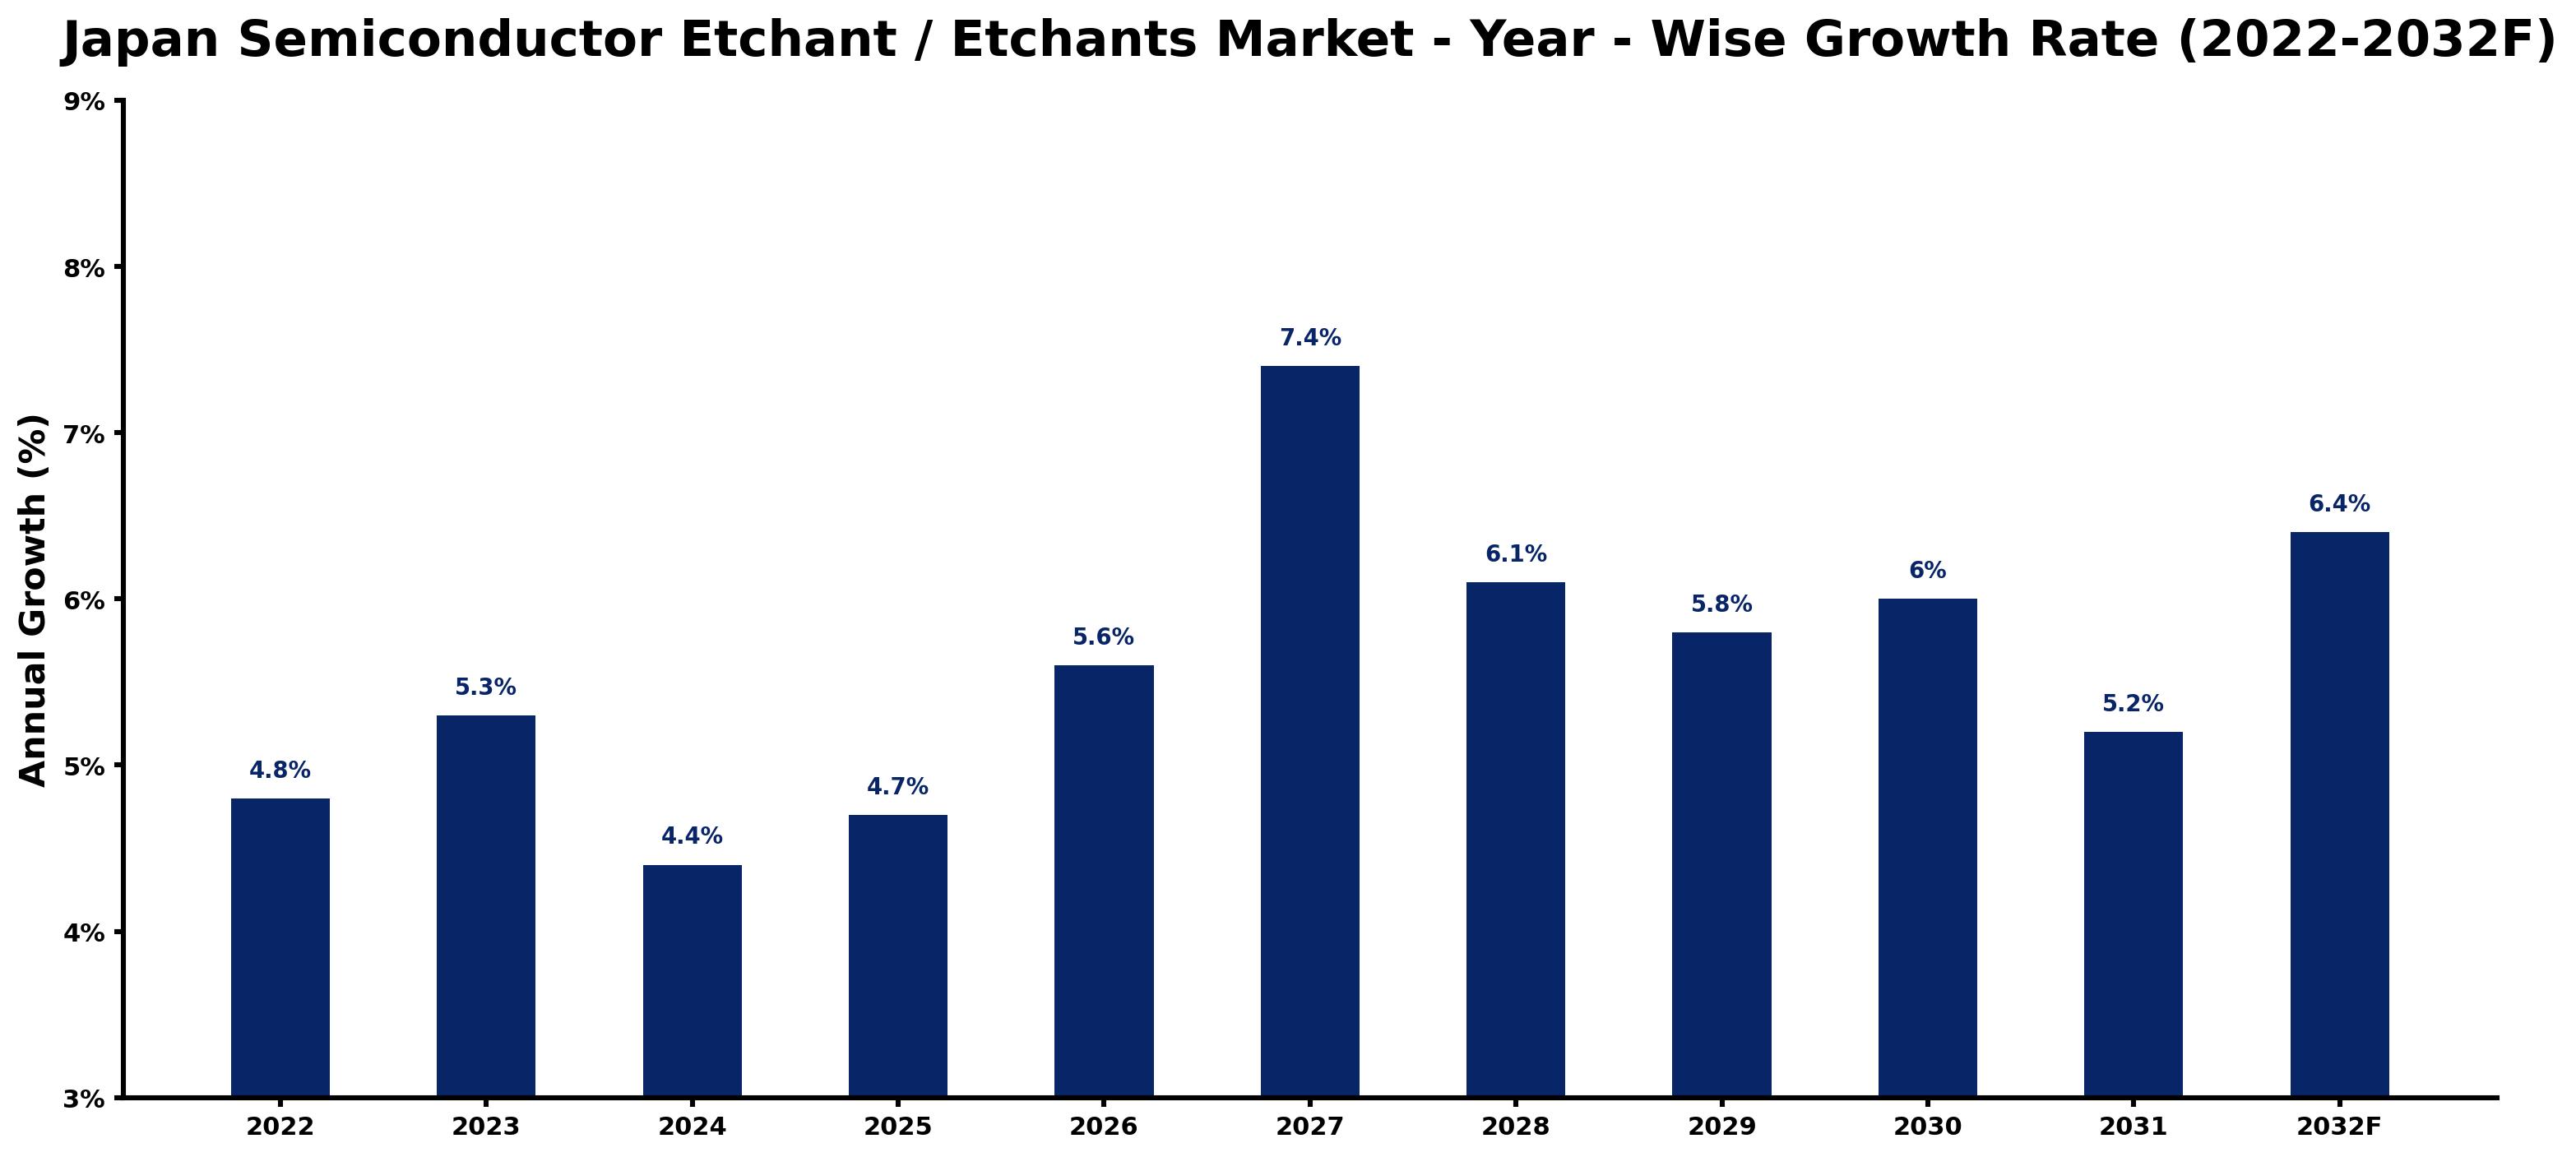
The yearly estimates that follow link every growth rate to its principal driver, so readers can see why the pace changed in each period.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.8 | The semiconductor market was stable, reflecting ongoing investments in technology. |
| 2023 | 5.3 | Growth was supported by a 10% increase in domestic semiconductor production. |
| 2024 | 4.4 | The market experienced a slowdown as demand stabilised after rapid growth. |
| 2025 | 4.7 | Growth accelerated again due to rising investments in semiconductor facilities. |
| 2026 | 5.6 | Demand is projected to increase as manufacturers adopt advanced etching techniques. |
| 2027 | 7.4 | The market is expected to peak with strong demand from foundries and memory makers. |
| 2028 | 6.1 | Growth is anticipated to slow slightly as the market begins to stabilise after peak levels. |
| 2029 | 5.8 | The market will continue to grow, albeit at a slower rate than before. |
| 2030 | 6.0 | Demand is expected to rise again as new technologies are introduced in fabrication. |
| 2031 | 5.2 | A slight slowdown is projected as the market adjusts to new standards. |
| 2032 | 6.4 | Growth is anticipated to rebound with increased investments in R&D. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Semiconductor Etchant / Etchants Market Synopsis
Japan Semiconductor Etchant / Etchants Market encompasses chemical solutions used to selectively remove layers from semiconductor wafers during fabrication. The market was valued at approximately 4 trillion JPY in 2022, reflecting strong domestic demand. Growth is driven by increased production capacity, advancements in etching technologies, and government support for semiconductor development, including the 2023 program launched by the Ministry of Economy, Trade and Industry.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased domestic semiconductor production | Driver | High | Wet Etchants |
| Growing investments in advanced fabrication technologies | Driver | High | Dry Etchants |
| Rising demand for advanced etching solutions | Opportunity | High | Selective Etchants |
| Need for improved cleaning processes in fabs | Opportunity | Medium | Buffered HF |
| High costs associated with R&D and production | Restraint | High | Metal Layers |
| Limited availability of skilled workforce in semiconductor sector | Restraint | Medium | Layer-Specific |
| Increasing competition from international markets | Challenge | High | Oxide Etching |
| Technological obsolescence of existing etching solutions | Challenge | Medium | Plasma Etching |
Evaluation of Drivers in Japan Semiconductor Etchant / Etchants Market (2026–2032)
These are the developments adding the most demand over the forecast period.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased domestic semiconductor production | Wet Etchants | This growth led to higher demand for etchants, with production increasing by 10% in 2023. |
| Investment in advanced fabrication technologies | Dry Etchants | Such investments are pushing manufacturers to adopt more sophisticated etching solutions. |
| Rising demand for advanced etching solutions | Selective Etchants | The need for precise material removal is driving purchases from advanced node fabs. |
| Need for improved cleaning processes in fabs | Buffered HF | As fabs expand, the demand for effective cleaning solutions continues to rise. |
| Technological advancements in etching processes | Plasma Etching | These advancements are important for maintaining competitive production capabilities. |
Orders keep climbing as Japan's semiconductor market was valued at approximately 4 trillion JPY in 2022. Increased domestic semiconductor production, which rose by 10% in 2023, has led to higher demand for etchants, especially in foundries. Investment in advanced fabrication technologies is pushing manufacturers to adopt sophisticated etching solutions, driving purchases of Dry Etchants. The need for precise material removal is elevating demand for Selective Etchants, particularly from advanced node fabs. As fabs expand, the demand for effective cleaning solutions, such as Buffered HF, continues to rise, further stimulating market growth.
Evaluation of Restraints in Japan Semiconductor Etchant / Etchants Market
These restraints slow adoption and weigh on supplier margins.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with R&D and production | Metal Layers | These costs can deter smaller manufacturers from entering the market, limiting competition. |
| Limited availability of skilled workforce in semiconductor sector | Layer-Specific | A shortage of skilled professionals can slow down production and innovation. |
| Increasing competition from international markets | Oxide Etching | This competition pressures local producers to reduce prices, affecting profit margins. |
| Technological obsolescence of existing etching solutions | Plasma Etching | Older technologies may not meet the latest production standards, leading to decreased sales. |
| Regulatory compliance costs for manufacturers | Wet Etchants | Compliance with standards like JIS Z 8724 can increase operational expenses. |
Japan Semiconductor Etchant / Etchants Market Challenges
Japan's semiconductor etchant market faces intense competition from international suppliers, which pressures local producers to lower their prices. This competition stems from the globalisation of the semiconductor supply chain, leading to potential revenue losses for domestic manufacturers. High production costs arise from complex chemical synthesis processes, costing producers up to 20% more than their foreign counterparts. Buyers experience delays in obtaining etchants as suppliers struggle to maintain quality under financial strain, potentially extending lead times by two weeks. A shortage of skilled workers in advanced etching techniques limits production efficiency, impacting output levels for manufacturers reliant on specialised talent.
Trends in the Japan Semiconductor Etchant / Etchants Market
The following changes are redrawing the Japan Semiconductor Etchant / Etchants Market.
- Tokyo Region Adopting Advanced Etching Techniques: The Tokyo region is experiencing a shift towards advanced etching techniques, driven by the need for precision. In 2023, the government allocated 300 billion JPY for semiconductor subsidies, encouraging innovation.
- Transition from Traditional to Plasma Etching: The semiconductor industry is moving from traditional etching methods to plasma etching for greater precision. The Tokyo Institute of Technology is researching advanced techniques, important for maintaining a competitive edge.
- Foundries Prioritising Efficiency: Foundries are increasingly focusing on efficiency in their operations, leading to greater investments in etching technologies. The demand for Wet Bench Etching has grown, accounting for 51% of the application type in 2025.
- Emerging Emphasis on Environmental Standards: There is a growing focus on environmental standards in semiconductor manufacturing, with new regulations being implemented. The Green Growth Strategy aims for carbon neutrality by 2050, impacting etchant production processes.
Investment Opportunities in the Japan Semiconductor Etchant / Etchants Market
The following opportunities in the Japan Semiconductor Etchant / Etchants Market pair current demand with a clear way in.
- Current Demand for Advanced Etchants: With Japan's semiconductor market valued at approximately 4 trillion JPY, it is an opportune time to invest in advanced etchants. Foundries are seeking effective solutions to improve production efficiency.
- Addressing the Skilled Workforce Gap: The semiconductor sector faces a gap in skilled workforce, with about 1.5 million jobs reported in 2022. Training programs for technicians can help fill this gap and support industry growth.
- Tokyo Region's Semiconductor Manufacturing Hub: The Tokyo region serves as a major hub for semiconductor manufacturing, creating opportunities for suppliers of etchants. Collaborating with local firms can facilitate market entry and expansion.
- Memory Device Makers Seeking Advanced Solutions: Memory device makers are increasingly looking for advanced etching solutions, with a projected growth rate of 8.1% from 2026 to 2032. Suppliers should focus on developing tailored products for this buyer group.
Government Initiatives in the Japan Semiconductor Etchant / Etchants Market
The Semiconductor and Digital Industry Strategy, introduced in June 2021, set measures to secure domestic semiconductor manufacturing. This strategy aims to support R&D funding and strengthen local production capabilities, ensuring the sector remains competitive. The government allocated 300 billion JPY for semiconductor industry subsidies in 2023, which directly benefits etchant producers and users.
The Ministry of Economy, Trade and Industry (METI) oversees the implementation of various programs, including the Economic Security Promotion Act of 2022, which supports supply-chain resilience for critical products. METI also funds initiatives that enhance R&D in the semiconductor sector, ensuring that etchant manufacturers can innovate and meet evolving market demands.
Future Insight of the Japan Semiconductor Etchant / Etchants Market
The Advanced Semiconductor Manufacturing Program will enhance research and development capabilities by 2032. Government support, including 300 billion JPY in subsidies, will drive innovation in the sector. As domestic production increases, Japan's semiconductor exports are expected to rise to 1.5 trillion JPY, reflecting growing international demand. Stricter adherence to standards like JIS Z 8724 will ensure improved etchant quality, benefiting both buyers and suppliers.
Market Segmentation Analysis
Japan Semiconductor Etchant / Etchants Market report covers a detailed analysis of the following market segments:
By Etchant Type – Wet Etchants Lead, Dry Etchants Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, Wet Etchants held 49% of the Japan Semiconductor Etchant / Etchants Market by etchant type in 2025. Wet etchants hold the largest share due to their critical role in cleaning and etching processes within semiconductor manufacturing. Their prevalent use in the Tokyo region, a key hub for semiconductor production, reinforces their dominant position. Dry Etchants are set to record the highest CAGR in this split, 8.5% over 2026–2032. The rapid growth of dry etchants is attributed to their essential function in plasma etching techniques, which are increasingly utilised in advanced fabrication processes. As manufacturers seek greater precision in etching patterns, the demand for dry etchants is expected to surge. Suppliers must prioritise the development of dry etchant products to capitalise on this growing demand.
By Target Material – Silicon/Oxides Lead, Metal Layers Expected to Grow Fastest
The largest target material category in 2025 was Silicon/Oxides, at 43% of revenue. Silicon and oxides are the primary materials processed using etchants in semiconductor fabs, accounting for a substantial share of etchant consumption. Their integral role in the production of semiconductor devices ensures consistent demand from manufacturers. The quickest growth will come from Metal Layers, forecast to expand at a CAGR of 8.6% between 2026 and 2032. The metal layers segment is experiencing rapid growth due to their critical importance in etching metal interconnects within devices. As technology advances, the need for intricate metal layer designs is increasing, driving this segment forward. Suppliers must adapt to the growing need for etchants tailored for metal layer applications.
By Application Type – Wet Bench Etching Leads, Plasma Etching Expected to Grow Fastest
In 2025, Wet Bench Etching led the application type split with a 51% share. Wet bench etching holds the largest share due to its status as the standard method for etching in semiconductor cleanrooms. This application is widely adopted across various manufacturing environments, ensuring a robust installed base and consistent demand. Plasma Etching is projected to grow fastest, at a CAGR of 8.2% during 2026–2032. The rapid advancement in integrated circuit design is propelling the growth of plasma etching, which is essential for creating intricate patterns. This shift towards miniaturisation in semiconductor devices is expected to accelerate the adoption of plasma etching technologies. Suppliers must prioritise the development of plasma etching solutions to capitalise on the growing complexity of semiconductor manufacturing.
By End User – Foundries Lead, Memory Device Makers Expected to Grow Fastest
With 49% of end user revenue in 2025, Foundries was the largest category. Foundries are the major users of etchants for chip production, reflecting their dominant role in the semiconductor supply chain. Their extensive operations require a consistent supply of etchants to meet production demands. Over 2026–2032, Memory Device Makers are expected to post the fastest growth, at a CAGR of 8.1%. Memory device makers are rapidly increasing their consumption of etchants due to the surging demand for memory chip fabrication. The expansion of memory technologies is driving this segment's growth at a fast pace. This trend highlights the need for suppliers to strengthen relationships with memory device manufacturers.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Semiconductor Etchant / Etchants Market Outlook
- Market Size of Japan Semiconductor Etchant / Etchants Market, 2025
- Forecast of Japan Semiconductor Etchant / Etchants Market, 2032
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Revenues & Volume for the Period 2022-2032F
- Japan Semiconductor Etchant / Etchants Market Trend Evolution
- Japan Semiconductor Etchant / Etchants Market Drivers and Challenges
- Japan Semiconductor Etchant / Etchants Price Trends
- Japan Semiconductor Etchant / Etchants Porter's Five Forces
- Japan Semiconductor Etchant / Etchants Industry Life Cycle
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Etchant Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Wet Etchants for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Dry Etchants for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Selective Etchants for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Buffered HF for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Target Material for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Silicon/Oxides for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Metal Layers for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Layer-Specific for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Oxide Etching for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Application Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Wet Bench Etching for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Plasma Etching for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Critical Dimension Control for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Cleaning and Etching for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Foundries for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Memory Device Makers for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Advanced Node Fabs for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Etchant / Etchants Market Revenues & Volume By Wafer Processing Plants for the Period 2022-2032F
- Japan Semiconductor Etchant / Etchants Import Export Trade Statistics
- Market Opportunity Assessment By Etchant Type
- Market Opportunity Assessment By Target Material
- Market Opportunity Assessment By Application Type
- Market Opportunity Assessment By End User
- Japan Semiconductor Etchant / Etchants Top Companies Market Share
- Japan Semiconductor Etchant / Etchants Competitive Benchmarking By Technical and Operational Parameters
- Japan Semiconductor Etchant / Etchants Company Profiles
- Japan Semiconductor Etchant / Etchants Key Strategic Recommendations
Market Covered
The report covers the following segments.
By Etchant Type
- Wet Etchants
- Dry Etchants
- Selective Etchants
- Buffered HF
By Target Material
- Silicon/Oxides
- Metal Layers
- Layer-Specific
- Oxide Etching
By Application Type
- Wet Bench Etching
- Plasma Etching
- Critical Dimension Control
- Cleaning and Etching
By End User
- Foundries
- Memory Device Makers
- Advanced Node Fabs
- Wafer Processing Plants































