China 3D Semiconductor Market Size & Growth Rate
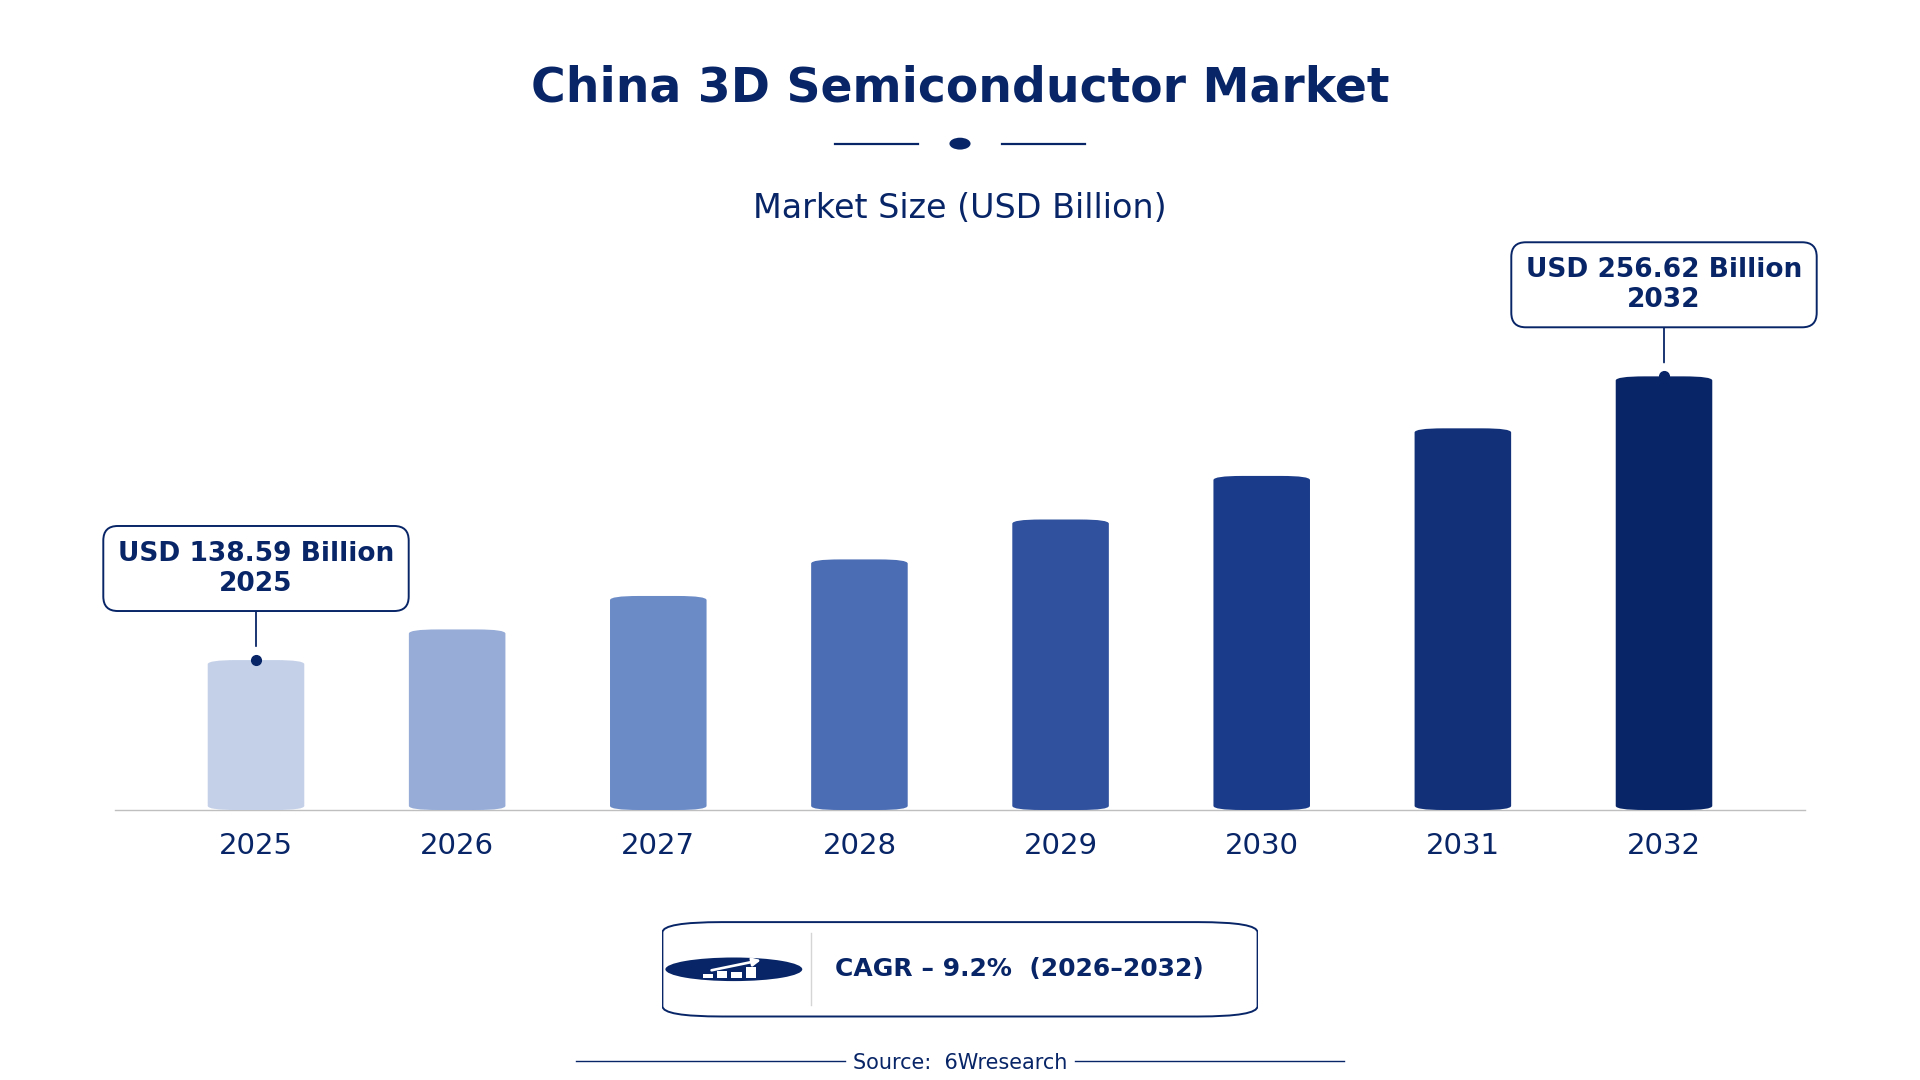
According to 6Wresearch internal database and industry insights, the China 3D Semiconductor Market was valued at USD 138.59 billion in 2025 and is projected to reach USD 256.62 billion by 2032, growing at a CAGR of approximately 9.2% during 2026–2032.
China 3D Semiconductor Market Highlights
| Report Metric | Details |
| Report Name | China 3D Semiconductor Market |
| Market Size 2025 | USD 138.59 billion |
| Market Size 2032 | USD 256.62 billion |
| Absolute Growth 2025–2032 | USD 118.03 billion |
| CAGR 2026–2032 | 9.2% |
| Peak Annual Growth | 11.2% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Technology Type, 2025 | 3D TSV (50% share) |
| Leading Packaging Type, 2025 | Chip-Stacking (35% share) |
| Leading Wafer Type, 2025 | Silicon-On-Insulator (36% share) |
| Leading Distribution Channel, 2025 | Direct Sales (36% share) |
| Leading End User Industry, 2025 | Data Centers (45% share) |
| Fastest-Growing Technology Type | Monolithic 3D IC (11.2% CAGR) |
| Fastest-Growing Packaging Type | Wire Bonded (11.1% CAGR) |
| Fastest-Growing Wafer Type | Silicon Wafer (11.2% CAGR) |
| Fastest-Growing Distribution Channel | Online Distributors (11.4% CAGR) |
| Fastest-Growing End User Industry | Consumer Electronics (11.1% CAGR) |
| Growing Sector | Consumer Electronics |
| Key End Users | Data Centers, Consumer Electronics, IoT Devices, Automotive Electronics |
China 3D Semiconductor Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
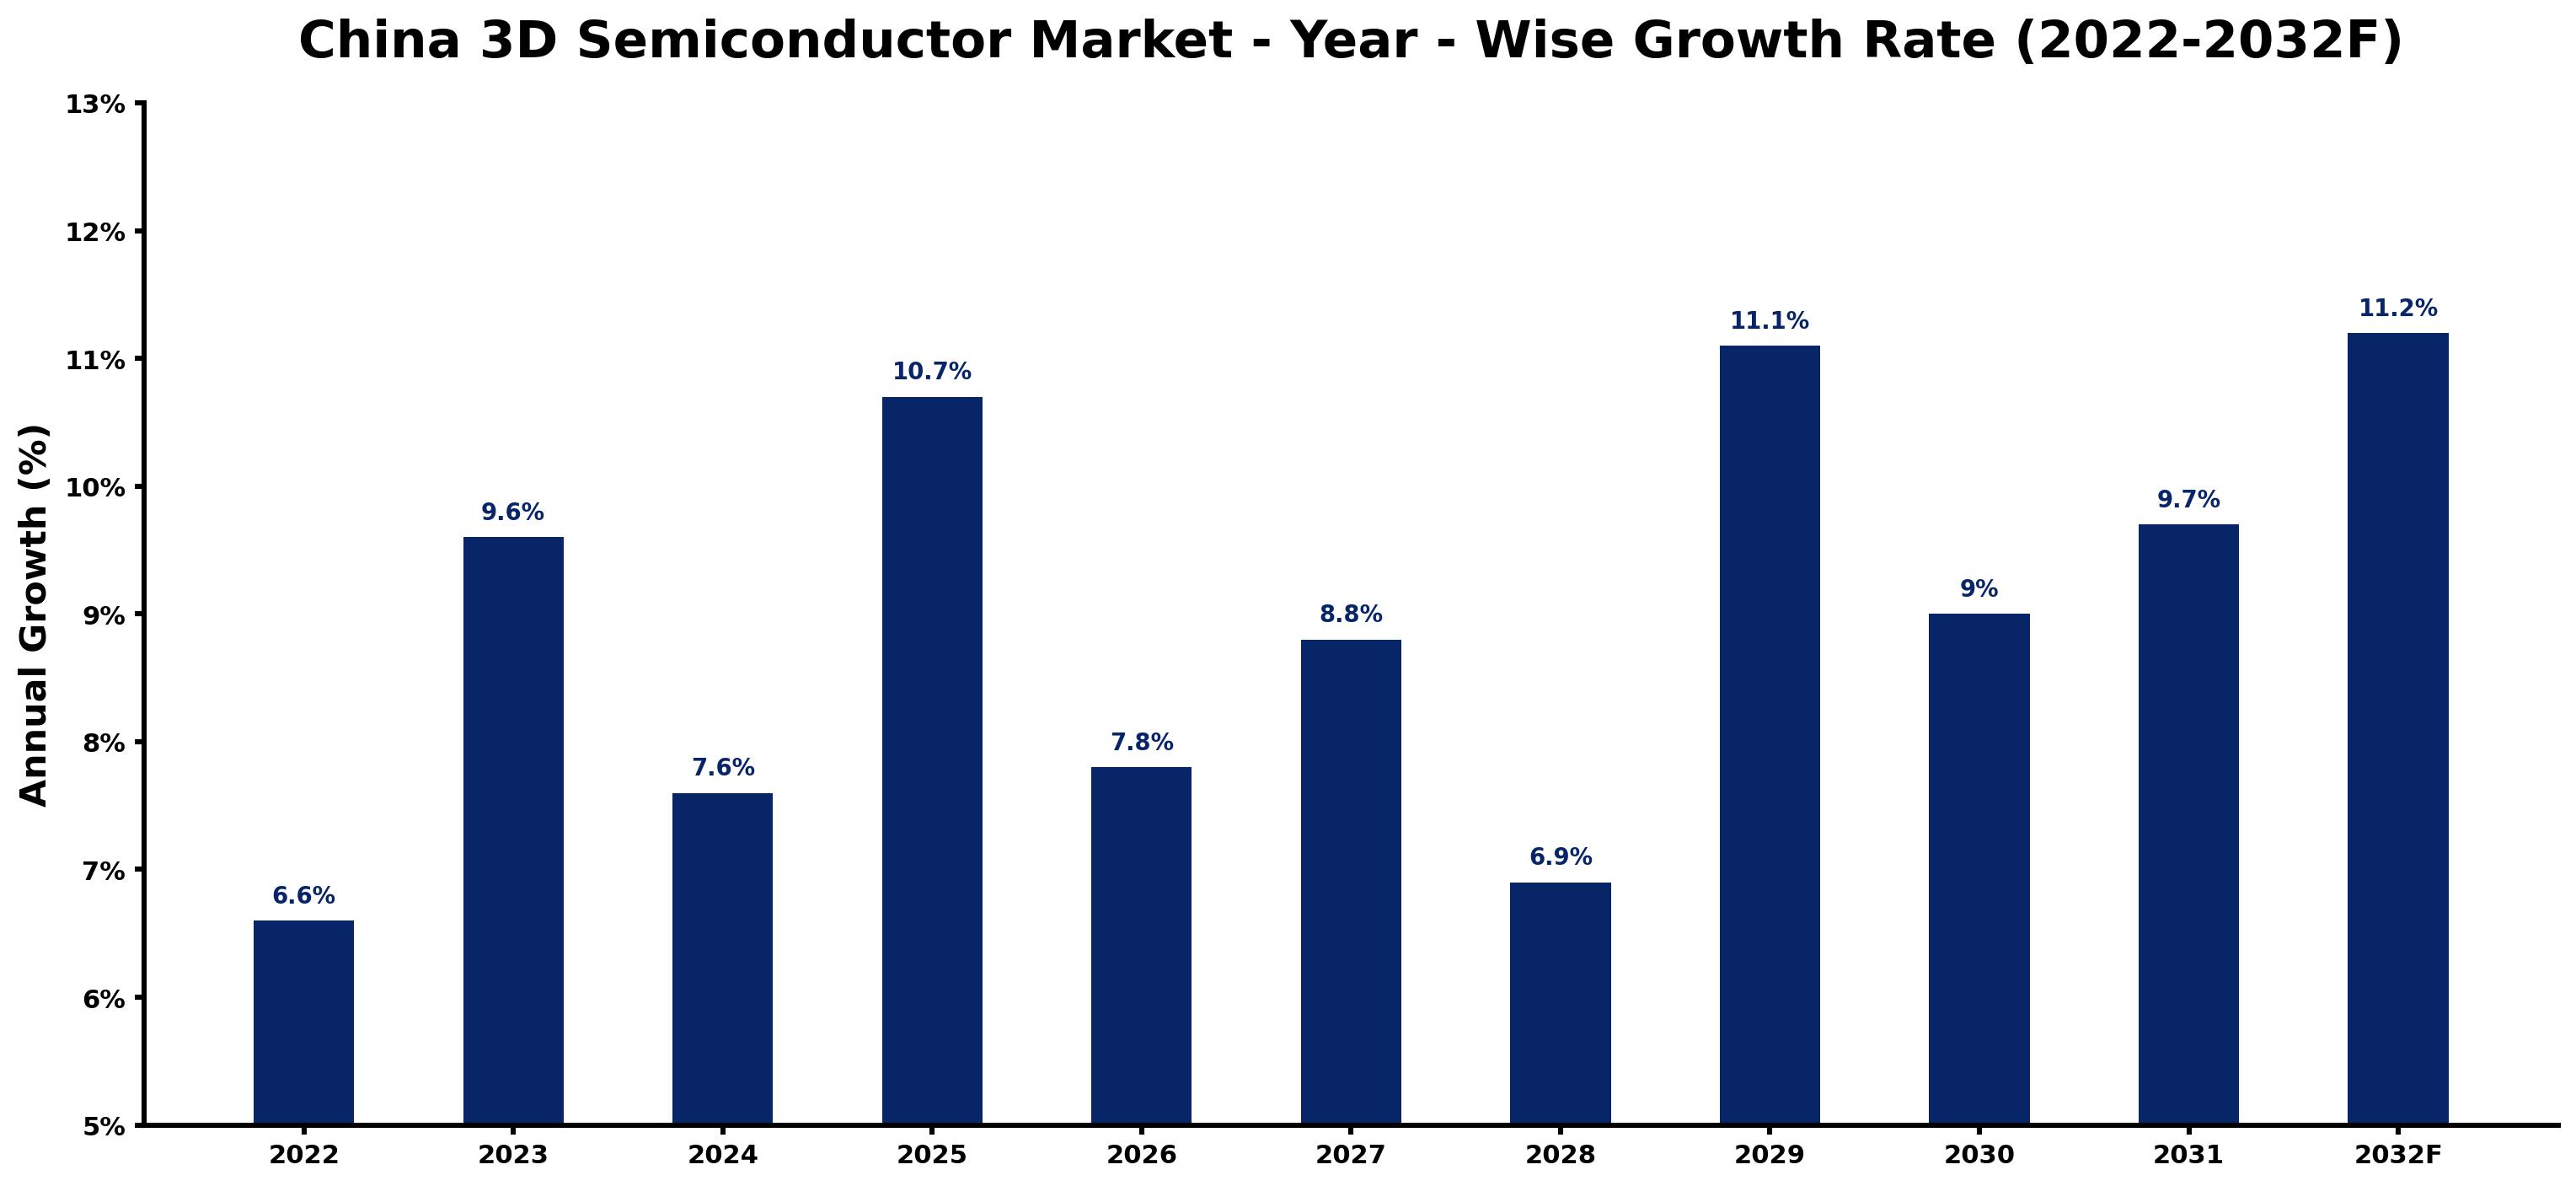
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.6 | The market showed steady growth amid increasing domestic semiconductor demand driven by local manufacturers. |
| 2023 | 9.6 | Growth accelerated due to rising investments in semiconductor manufacturing technologies and the '14th Five-Year Plan'. |
| 2024 | 7.6 | The market experienced a slowdown as demand stabilised after rapid growth from automotive electronics. |
| 2025 | 10.7 | Growth surged again, driven by strong demand from data centers and automotive sectors projected to reach 1.5 trillion CNY. |
| 2026 | 7.8 | A slowdown occurred as market growth moderated following the previous peak in 2025. |
| 2027 | 8.8 | Growth picked up due to expanding applications in consumer electronics and IoT devices. |
| 2028 | 6.9 | The market slowed again as demand reached a temporary plateau amid competitive pressures. |
| 2029 | 11.1 | Growth accelerated with rising automotive electronics production and demand for advanced semiconductors. |
| 2030 | 9.0 | A slowdown was observed as the market adjusted to previous growth rates and increased competition. |
| 2031 | 9.7 | Growth rebounded due to increased investments in semiconductor R&D and the National Integrated Circuit Industry Investment Fund. |
| 2032 | 11.2 | The market peaked with strong demand from high-performance computing and automotive applications, supported by government initiatives. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China 3D Semiconductor Market Synopsis
3D semiconductors in China represent advanced integrated circuits that utilise three-dimensional structures to improve performance and efficiency. They are produced through techniques like 3D TSV and hybrid bonding, primarily catering to high-performance computing, consumer electronics, and automotive applications. The China 3D Semiconductor Market is growing swiftly, generating approximately 1 trillion CNY in revenue in 2022. Key drivers of this growth include the automotive electronics market, which is projected to reach 1.5 trillion CNY by 2025, along with an increasing reliance on advanced technologies in data centres.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in semiconductor manufacturing technologies are boosting demand. | Driver | High | 3D TSV |
| The growing automotive electronics market is driving the need for advanced semiconductors. | Driver | High | Automotive Electronics |
| The increasing number of data centers is creating a significant demand for 3D semiconductors. | Opportunity | High | Data Centers |
| The expansion of IoT devices is leading to higher demand for advanced semiconductor technologies. | Opportunity | High | IoT Devices |
| Supply chain disruptions can hinder semiconductor production capabilities. | Restraint | High | Silicon Wafer |
| High R&D costs can limit investment in new semiconductor technologies. | Restraint | Medium | Hybrid Bonding |
| The shortage of skilled workforce in semiconductor manufacturing affects production. | Challenge | High | Chip-Stacking |
| Regulatory challenges can delay the approval of new semiconductor technologies. | Challenge | Medium | Monolithic 3D IC |
Evaluation of Drivers in China 3D Semiconductor Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in semiconductor manufacturing technologies. | 3D TSV | This has led to improved production capabilities, with China producing over 50% of global silicon wafers. |
| Growing demand from the automotive electronics sector. | Automotive Electronics | The market is projected to reach 1.5 trillion CNY by 2025, increasing semiconductor purchases significantly. |
| Surging number of data centers in China. | Data Centers | With over 5,000 data centers installed in 2023, demand for advanced semiconductors is increasing rapidly. |
| Expansion of IoT devices and applications. | IoT Devices | China's IoT market is projected to grow to 1 trillion CNY by 2025, driving semiconductor demand further. |
| Support from government initiatives and funding. | Chip-Stacking | The National Integrated Circuit Industry Investment Fund has a budget of 139 billion CNY to support development. |
Growth in the 3D Semiconductor market in China comes from increased investments in semiconductor manufacturing technologies, which have led to improved production capabilities. China produces over 50% of global silicon wafers, boosting local supply. Demand from the automotive electronics sector is evident, with projections indicating the market will reach 1.5 trillion CNY by 2025. The increasing number of data centers, exceeding 5,000 in 2023, drives the need for advanced semiconductors. The rapid expansion of IoT devices is also notable, with the market expected to grow significantly by 2025, further increasing demand for 3D semiconductor technologies.
Evaluation of Restraints in China 3D Semiconductor Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions affecting production capabilities. | Silicon Wafer | These disruptions can lead to delays in manufacturing and increased costs for producers. |
| High R&D costs limiting investment in new technologies. | Hybrid Bonding | This can slow down innovation and the introduction of advanced semiconductor solutions. |
| Shortage of skilled workforce in semiconductor manufacturing. | Chip-Stacking | This shortage can hinder production efficiency and increase operational costs. |
| Regulatory challenges delaying technology approvals. | Monolithic 3D IC | These delays can slow market entry for new products and technologies. |
| Competition from international semiconductor manufacturers. | 3D TSV | This can pressure local producers to innovate and reduce prices. |
China 3D Semiconductor Market Challenges
Buyers in the China 3D Semiconductor market face regulatory hurdles that can delay product approvals, extending timelines by six months for new technologies. Suppliers encounter high production costs, as advanced manufacturing techniques can inflate prices by 20%, impacting their pricing strategies. Intense competition among local manufacturers aiming for 70% self-sufficiency by 2025 compels suppliers to lower prices, potentially jeopardising profitability. Supply chain disruptions complicate operations, causing delivery delays that can halt production for buyers, leading to potential revenue losses in critical sectors like automotive and consumer electronics.
Trends in the China 3D Semiconductor Market
The trends below show where the China 3D Semiconductor Market is heading.
- Launch of the 'China Semiconductor Innovation and Development Program': The 'China Semiconductor Innovation and Development Program' initiated in 2021 aims to boost R&D in semiconductor technologies, with a budget of 50 billion CNY allocated in 2023. This initiative supports innovation and development, benefiting local manufacturers.
- Rapid Growth of Data Centers in China: China has seen a rapid increase in data centres, with over 5,000 established in 2023. This growth is driving demand for advanced semiconductors, particularly in high-performance computing applications, enhancing the market's potential.
- Shift towards IoT Device Integration: The integration of IoT devices is expanding rapidly, with China's IoT market anticipated to grow significantly by 2025. This trend is pushing the demand for advanced semiconductor technologies to support enhanced connectivity and functionality.
- Emphasis on Automotive Electronics: The automotive electronics market in China is projected to reach 1.5 trillion CNY by 2025. This shift is increasing the need for advanced 3D semiconductors to support smart vehicle technologies.
Investment Opportunities in the China 3D Semiconductor Market
Several openings in the China 3D Semiconductor Market merit attention from investors.
- Growth in Data Center Infrastructure: The demand for advanced semiconductors is increasing due to the establishment of over 5,000 data centres in China, driving a need for high-performance solutions. Investing in semiconductor technologies tailored for data centres presents a key opportunity.
- Expansion of IoT Device Market: With China's IoT market projected to grow significantly by 2025, there is a substantial gap in advanced semiconductor supply. Suppliers can enter this market by partnering with IoT device manufacturers.
- Automotive Electronics Demand Surge: As the automotive electronics market is expected to reach 1.5 trillion CNY by 2025, suppliers can focus on providing 3D semiconductors for smart vehicle applications. Collaborating with automotive manufacturers will be key.
- Support from Government Initiatives: The National Integrated Circuit Industry Investment Fund's expanded budget of 50 billion CNY in 2023 presents an opportunity for investment in semiconductor development. Engaging with government initiatives can facilitate market entry.
Government Initiatives in the China 3D Semiconductor Market
The '14th Five-Year Plan for the Development of the Integrated Circuit Industry', released by the MIIT in 2021, aims for a 70% self-sufficiency rate in semiconductor manufacturing by 2025. This measure sets clear targets for domestic production and innovation in the semiconductor sector, enhancing local manufacturing capabilities and reducing reliance on imports.
The Ministry of Industry and Information Technology (MIIT) oversees the implementation of various semiconductor initiatives, including funding for research and development projects. The MIIT has approved multiple projects under the National Integrated Circuit Industry Investment Fund, which provides financial support to emerging semiconductor companies, ensuring they can innovate and compete effectively in the market.
Future Insight of the China 3D Semiconductor Market
Several forward-looking factors should support the China 3D Semiconductor market in the coming years. The 'Made in China 2025' initiative will drive investment in semiconductor production, boosting local capabilities. By 2025, the automotive electronics market is projected to reach 1.5 trillion CNY, significantly increasing demand for advanced semiconductor solutions. The IoT market is expected to grow to 1 trillion CNY by 2025, further heightening the need for innovative semiconductor technologies. Enhanced R&D funding, targeting 10% of industry revenue, will promote innovation and improve manufacturing processes.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Technology Type – 3D TSV Dominated, Monolithic 3D IC Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, the largest technology type category in 2025 was 3D TSV, with a 50% share of total revenue. 3D TSV commands the largest share due to its critical role in achieving high-density interconnections in advanced chips, especially for high-performance computing applications. Its widespread use in sectors demanding superior processing capabilities underpins its strong market position. Monolithic 3D IC is set to record the highest CAGR in this split, 11.2% over 2026–2032. Monolithic 3D IC is experiencing rapid growth as it allows for the integration of multiple functions within a single chip, addressing the increasing complexity of electronic devices. This trend is propelled by the surging demand for high-performance computing across various industries, ensuring 3D TSV's lead continues to widen. Suppliers should prioritise 3D TSV and Monolithic 3D IC technologies to effectively meet the rising demand in the semiconductor market.
By Packaging Type – Chip-Stacking Dominated, Wire Bonded Expected to Grow Fastest
With a 35% revenue share in 2025, Chip-Stacking was the largest packaging type category. Chip-Stacking dominates the market due to its critical role in increasing chip density and performance, making it a preferred choice among manufacturers. This technique is particularly vital for advanced semiconductors used in data centers and high-performance applications, solidifying its market share. The quickest growth will come from Wire Bonded, forecast to expand at a CAGR of 11.1% between 2026 and 2032. Wire Bonded packaging is experiencing a decline as manufacturers transition towards more efficient designs, while Chip-Stacking remains essential for modern applications. This shift towards advanced packaging methods is driving growth in this segment. Buyers should prioritise suppliers that specialise in Chip-Stacking technologies to access high-performance semiconductor solutions.
By Wafer Type – Silicon-On-Insulator Dominated, Silicon Wafer Expected to Grow Fastest
Silicon-On-Insulator held a 36% share of the China 3D Semiconductor Market by wafer type in 2025. Silicon-On-Insulator leads the market by enhancing performance through reduced parasitic capacitance, making it particularly suitable for high-speed applications. Its growing preference in the production of advanced integrated circuits reinforces its dominant market share. Silicon Wafer is projected to grow fastest, at a CAGR of 11.2% during 2026–2032. Silicon Wafer is witnessing rapid growth as it remains the essential material for semiconductor manufacturing, catering to the increasing demand for advanced semiconductor technologies. This foundational role ensures its ongoing relevance and importance in the industry. Suppliers must focus on Silicon-On-Insulator and Silicon Wafer production to satisfy the escalating demand in the semiconductor market.
By Distribution Channel – Direct Sales Dominated, Online Distributors Expected to Grow Fastest
In 2025, Direct Sales led the distribution channel split with a 36% share. Direct Sales serves as the primary channel for manufacturers to connect with customers, facilitating a streamlined approach for larger orders and nurturing strong relationships. This method is vital for established players in the semiconductor market to sustain their competitive advantage. Over 2026–2032, Online Distributors are expected to post the fastest growth, at a CAGR of 11.4%. Online Distributors are rapidly growing as they meet the needs of smaller orders and startups, reflecting a shift in purchasing behaviour among new market entrants. This trend highlights the increasing acceptance of digital channels in the semiconductor industry. Suppliers should enhance their online distribution strategies to capture the expanding segment of smaller buyers in the semiconductor market.
By End User Industry – Data Centers Dominated, Consumer Electronics Expected to Grow Fastest
Data Centers took a 45% share of end user industry in 2025, more than any other category. Data Centers represent the largest consumers of 3D semiconductors, driven by their need for processing power and efficiency in managing extensive data volumes. The presence of over 5,000 data centers in China significantly bolsters this demand, solidifying its market share. Consumer Electronics is set to record the highest CAGR in this split, 11.1% over 2026–2032. Consumer Electronics is rapidly emerging as a key market for 3D semiconductor applications, reflecting the growing reliance on advanced technologies in everyday devices. This growth is further supported by China's thriving consumer electronics sector, which reached over 1.2 trillion CNY in 2022. Suppliers should concentrate on addressing the specific needs of the consumer electronics sector to capitalise on the expanding market for 3D semiconductors.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China 3D Semiconductor Market Outlook
- Market Size of China 3D Semiconductor Market, 2025
- Forecast of China 3D Semiconductor Market, 2032
- Historical Data and Forecast of China 3D Semiconductor Revenues & Volume for the Period 2022 - 2032F
- China 3D Semiconductor Market Trend Evolution
- China 3D Semiconductor Market Drivers and Challenges
- China 3D Semiconductor Price Trends
- China 3D Semiconductor Porter's Five Forces
- China 3D Semiconductor Industry Life Cycle
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By 3D TSV for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Monolithic 3D IC for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Hybrid Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Fan-Out Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Packaging Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Chip-Stacking for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Wire Bonded for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Flip-Chip for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Package-on-Package for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Wafer Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Silicon-On-Insulator for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Silicon Wafer for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Bulk Silicon for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Epitaxial Wafer for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Online Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Contract Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Semiconductor Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Data Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Consumer Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By IoT Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Semiconductor Market Revenues & Volume By Automotive Electronics for the Period 2022 - 2032F
- China 3D Semiconductor Import Export Trade Statistics
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By Wafer Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China 3D Semiconductor Top Companies Market Share
- China 3D Semiconductor Competitive Benchmarking By Technical and Operational Parameters
- China 3D Semiconductor Company Profiles
- China 3D Semiconductor Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Technology Type
- 3D TSV
- Monolithic 3D IC
- Hybrid Bonding
- Fan-Out Packaging
By Packaging Type
- Chip-Stacking
- Wire Bonded
- Flip-Chip
- Package-on-Package
By Wafer Type
- Silicon-On-Insulator
- Silicon Wafer
- Bulk Silicon
- Epitaxial Wafer
By Distribution Channel
- Direct Sales
- Online Distributors
- Contract Manufacturing
- Semiconductor Suppliers
By End User Industry
- Data Centers
- Consumer Electronics
- IoT Devices
- Automotive Electronics































