China 3D Stacked IC Market Size & Growth Rate
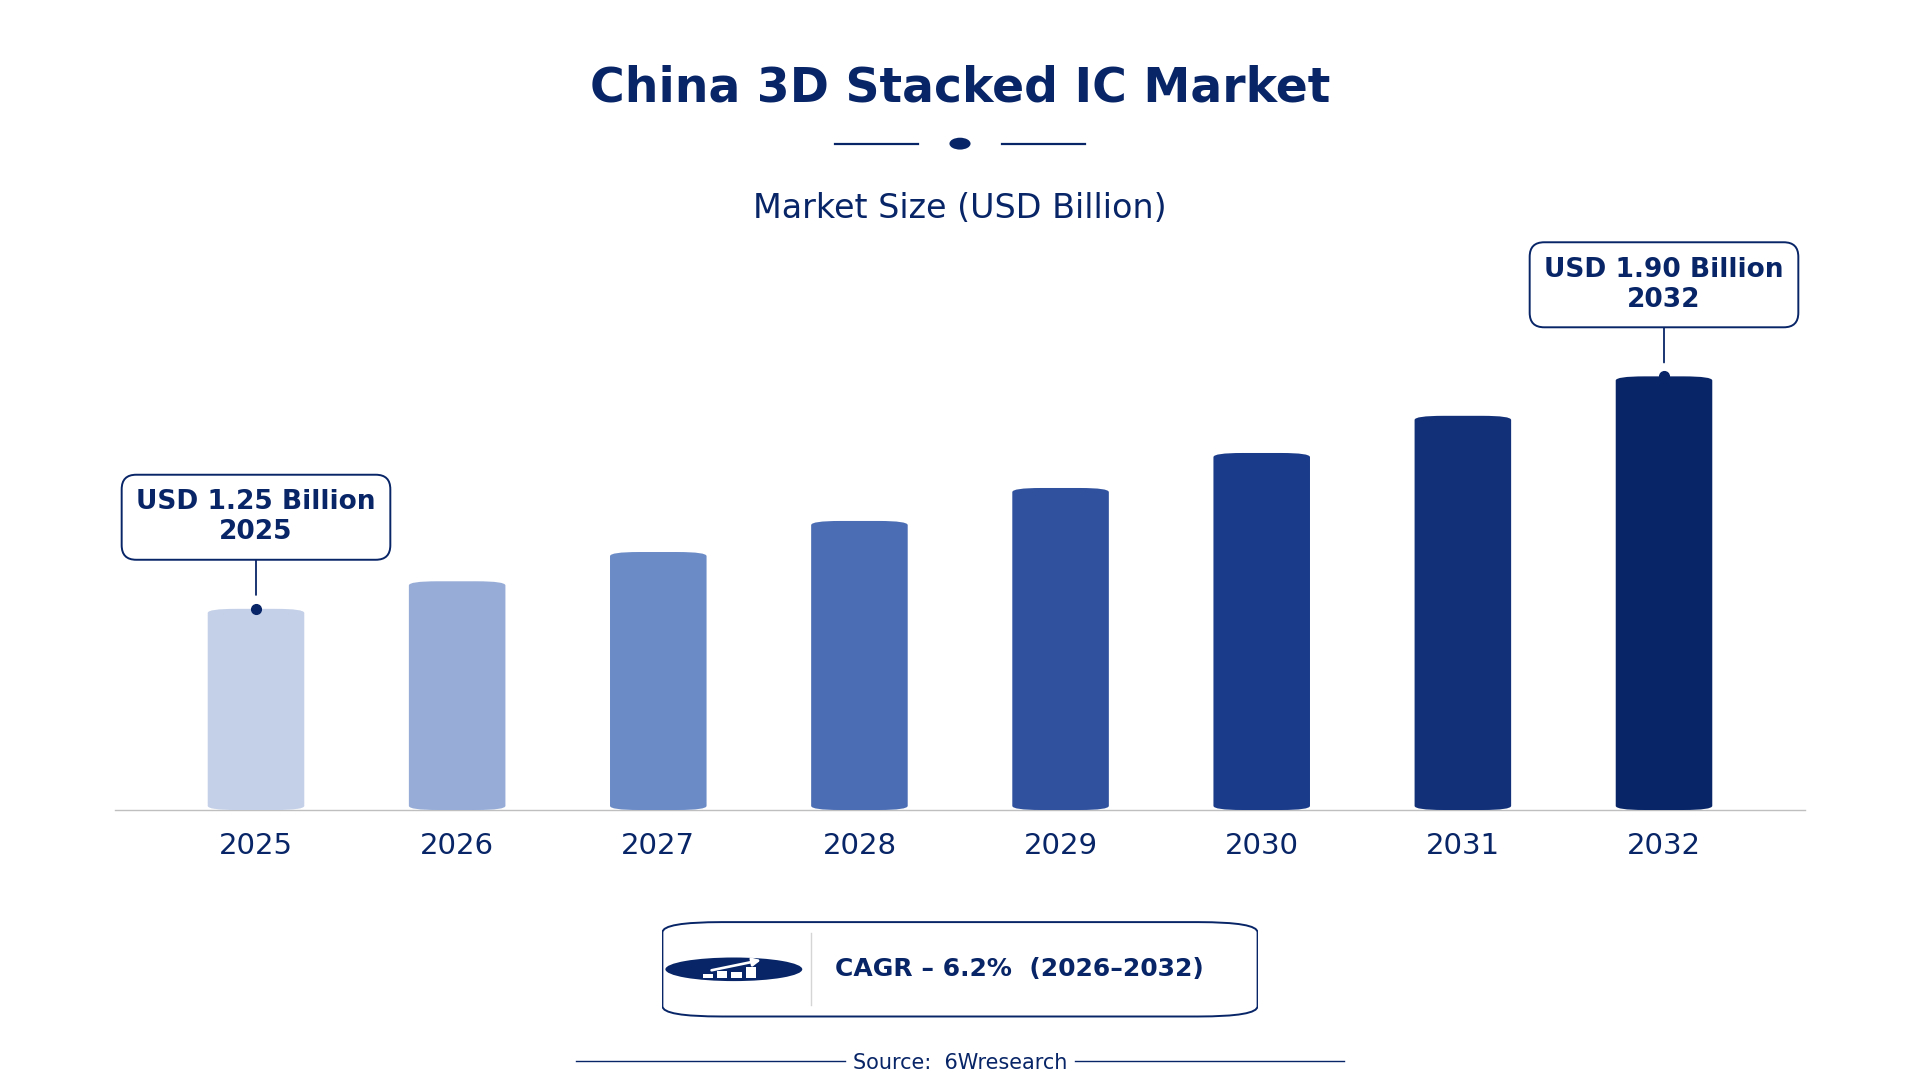
According to 6Wresearch internal database and industry insights, the China 3D Stacked IC Market was valued at USD 1.25 billion in 2025 and is projected to reach USD 1.90 billion by 2032, growing at a CAGR of approximately 6.2% during 2026–2032.
China 3D Stacked IC Market Highlights
| Report Metric | Details |
| Report Name | China 3D Stacked IC Market |
| Market Size 2025 | USD 1.25 billion |
| Market Size 2032 | USD 1.90 billion |
| Absolute Growth 2025–2032 | USD 0.65 billion |
| CAGR 2026–2032 | 6.2% |
| Peak Annual Growth | 8.9% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Packaging Technology, 2025 | Through Silicon Via (38% share) |
| Leading Integration Level, 2025 | Heterogeneous (47% share) |
| Leading Memory Type, 2025 | DRAM (40% share) |
| Leading Distribution Channel, 2025 | Semiconductor Distributors (41% share) |
| Leading End User Industry, 2025 | Mobile Devices (47% share) |
| Fastest-Growing Packaging Technology | Wafer-on-Wafer (8.8% CAGR) |
| Fastest-Growing Memory Type | NAND Flash (7.6% CAGR) |
| Fastest-Growing Distribution Channel | Direct Sales (8.1% CAGR) |
| Fastest-Growing End User Industry | Cloud Computing (8.8% CAGR) |
| Growing Sector | Cloud Computing |
| Key End Users | Mobile Devices, Cloud Computing, Telecom Infrastructure, Networking Equipment |
China 3D Stacked IC Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
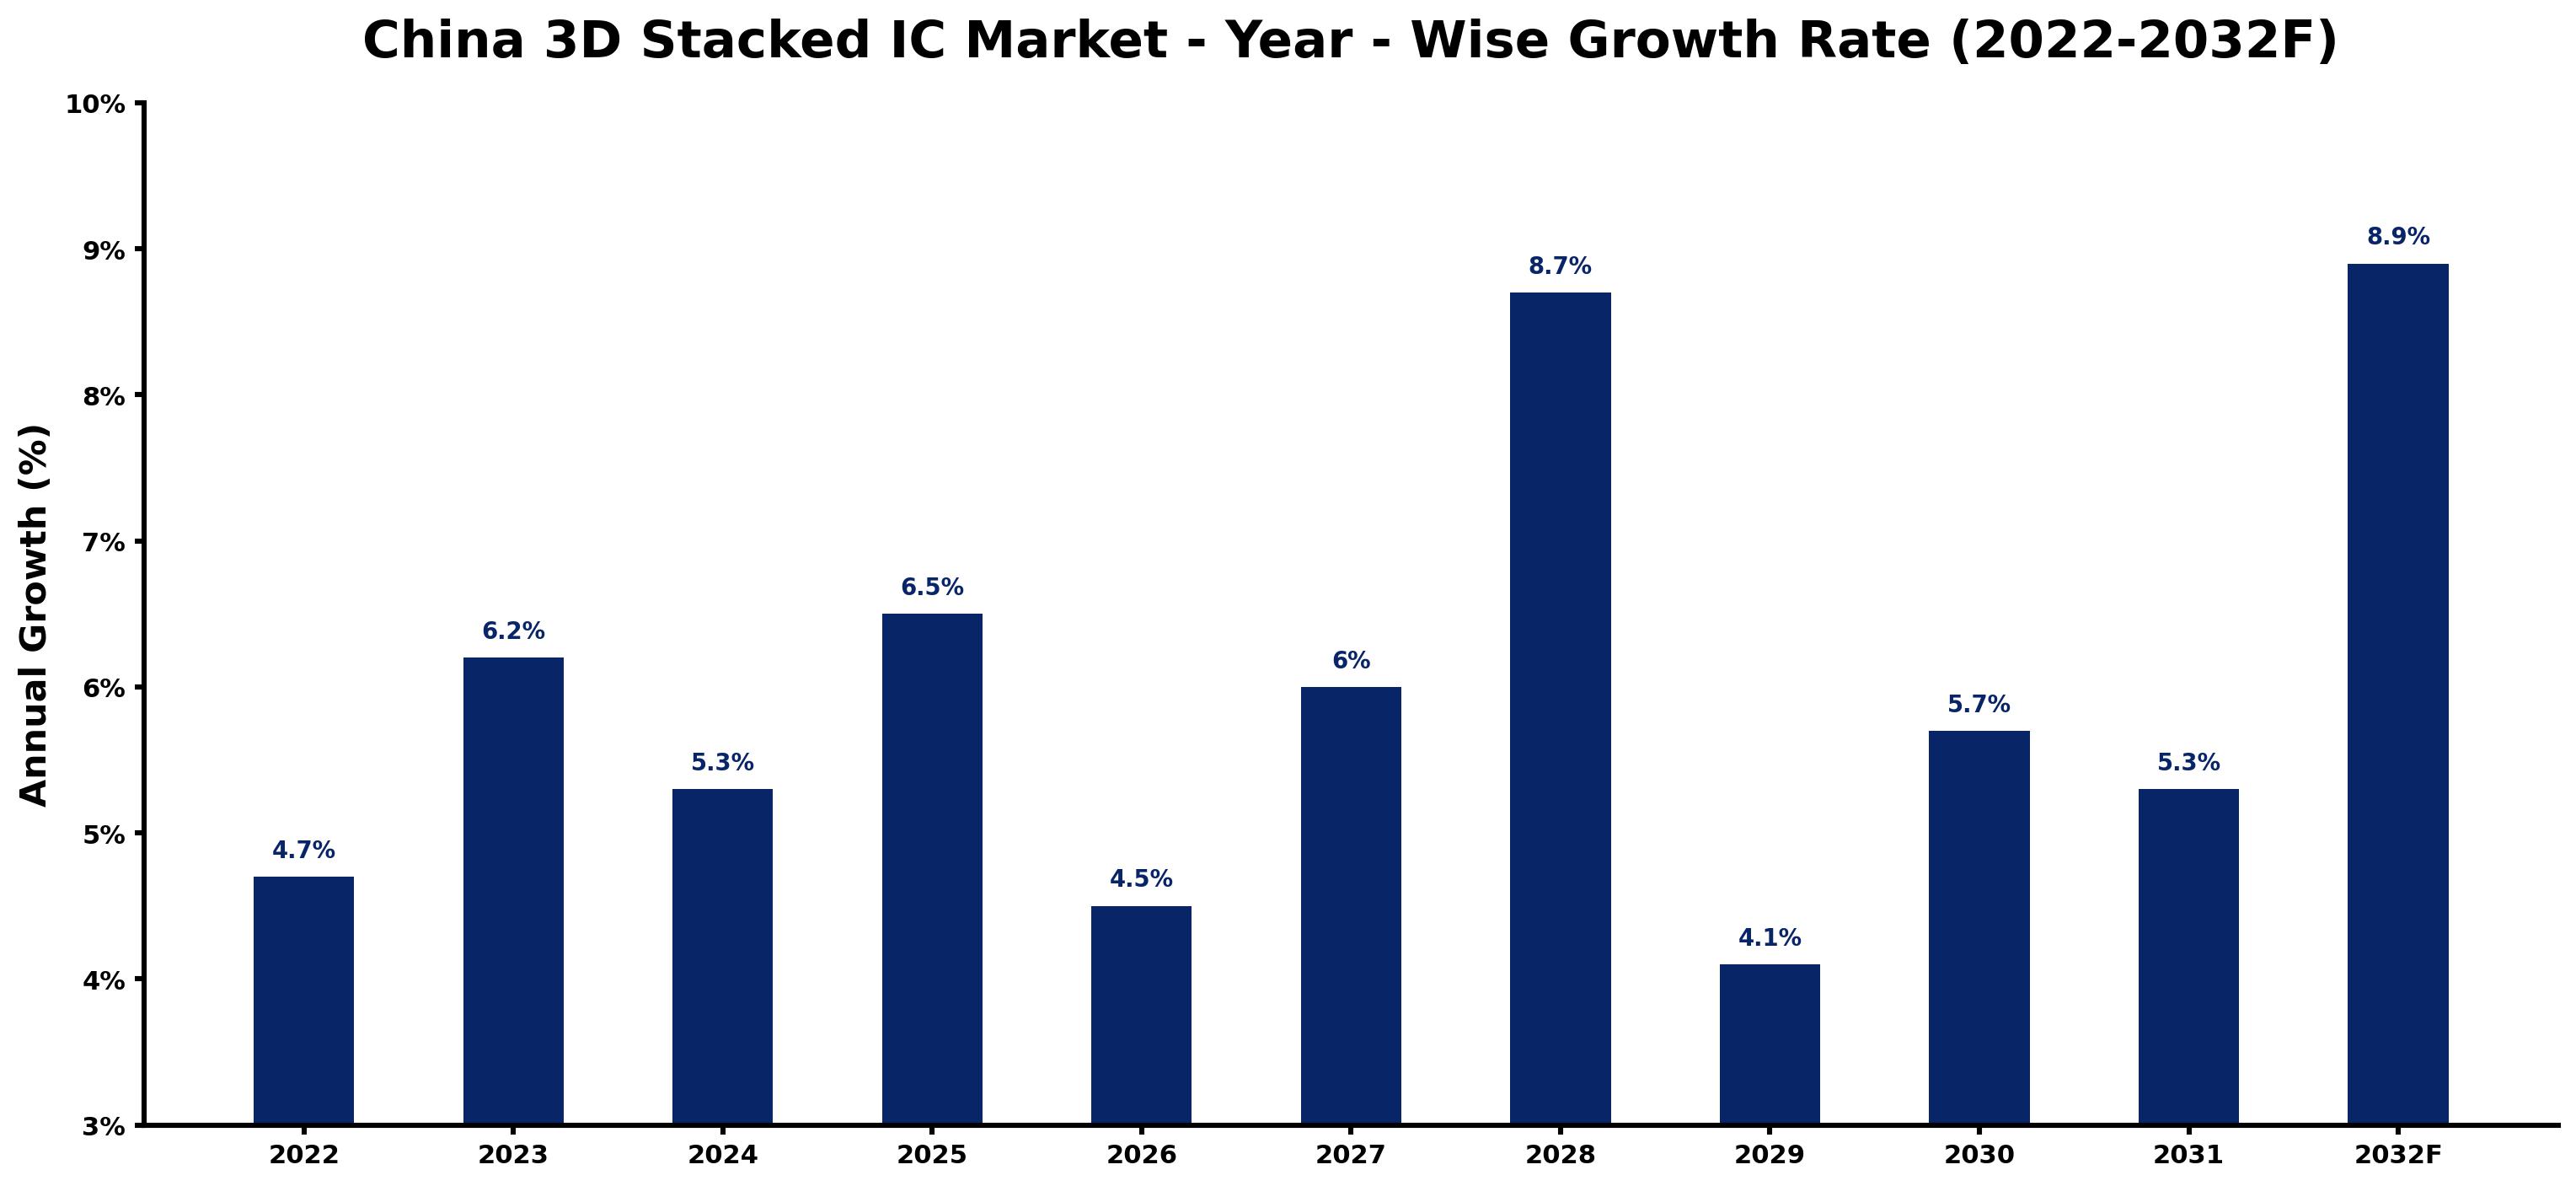
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.7 | Demand for 3D Stacked ICs was supported by the production of 1.5 billion mobile devices. |
| 2023 | 6.2 | Growth was driven by a 10% increase in chip production reported by the China Semiconductor Industry Association. |
| 2024 | 5.3 | The market experienced a slowdown as manufacturers adjusted to changing demand patterns for mobile devices. |
| 2025 | 6.5 | Increased investments in semiconductor technology contributed to faster growth in this year, particularly from the National Semiconductor Industry Development Strategy. |
| 2026 | 4.5 | The market is expected to slow as companies focus on improving production efficiency in response to international standards. |
| 2027 | 6.0 | Growth is projected to accelerate again due to rising demand from the mobile devices sector, particularly in Guangdong. |
| 2028 | 8.7 | The market is expected to surge as cloud computing requirements drive higher performance needs in data centers. |
| 2029 | 4.1 | A slowdown is anticipated as the market adjusts to the previous year's rapid growth in mobile device production. |
| 2030 | 5.7 | Growth is expected to revitalise by renewed investments in semiconductor innovation, especially in high-performance computing. |
| 2031 | 5.3 | The market will continue to grow, albeit at a slower pace as companies stabilise operations and meet new standards. |
| 2032 | 8.9 | The market is projected to peak with strong demand from high-performance computing applications, driven by the Digital Economy Development Plan. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China 3D Stacked IC Market Synopsis
The 3D Stacked IC Market in China encompasses advanced semiconductor devices that integrate multiple chip layers for optimal performance. These devices are manufactured using techniques such as Through Silicon Via and wafer bonding, primarily used in high-performance computing, mobile devices, and data centers. The market is expanding due to rising demand from domestic manufacturers, with the semiconductor industry projected to reach $100 billion by 2025. Factors such as the 'Made in China 2025' initiative and increased production of mobile devices are driving this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in semiconductor technology | Driver | High | Heterogeneous |
| Increasing demand for high-performance computing | Driver | High | Mobile Devices |
| Growing demand for NAND Flash memory | Opportunity | Medium | NAND Flash |
| Expanding cloud computing sector | Opportunity | High | Cloud Computing |
| High production costs for advanced semiconductor technologies | Restraint | High | Through Silicon Via |
| Limited access to advanced manufacturing technologies | Restraint | Medium | Wafer-on-Wafer |
| Challenges in meeting international quality standards | Challenge | High | 2.5D Stacking |
| Dependence on foreign technology for innovation | Challenge | Medium | Heterogeneous |
Evaluation of Drivers in China 3D Stacked IC Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in semiconductor technology | Heterogeneous | The National Integrated Circuit Industry Investment Fund, with a budget of $29 billion, supports advancements in semiconductor manufacturing. |
| Rising demand for high-performance computing | Mobile Devices | China produced 1.5 billion mobile devices in 2022, driving the need for improved performance through advanced ICs. |
| Growing demand for NAND Flash memory | NAND Flash | The eMMC market is growing, with a 15% increase in demand expected by 2025, leading to higher purchases of 3D Stacked ICs. |
| Expanding cloud computing sector | Cloud Computing | The total installed base of networking equipment in China reached 1 billion units in 2023, increasing demand for advanced chips. |
| Support from government initiatives | 2.5D Stacking | The 'Made in China 2025' initiative aims to improve domestic semiconductor capabilities, boosting investments in advanced technologies. |
Market growth in China for 3D Stacked IC rests on increased investments in semiconductor technology and rising demand for high-performance computing. The National Integrated Circuit Industry Investment Fund, with a budget of $29 billion, supports advancements in semiconductor manufacturing. In 2022, China produced 1.5 billion mobile devices, driving the need for improved performance through advanced ICs. The total installed base of networking equipment in China reached 1 billion units in 2023, increasing demand for advanced chips.
Evaluation of Restraints in China 3D Stacked IC Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs for advanced semiconductor technologies | Through Silicon Via | Production costs for Through Silicon Via technology are high, impacting profitability and pricing strategies. |
| Limited access to advanced manufacturing technologies | Wafer-on-Wafer | Manufacturers face challenges in acquiring the latest technologies, hindering their ability to compete effectively. |
| Challenges in meeting international quality standards | 2.5D Stacking | Compliance with international standards requires substantial investment in quality assurance processes. |
| Dependence on foreign technology for innovation | Heterogeneous | A leading supplier on foreign technology limits domestic innovation capabilities and increases vulnerability to supply chain disruptions. |
| Market volatility due to geopolitical tensions | Mobile Devices | Geopolitical issues can disrupt supply chains, affecting the availability of critical components. |
China 3D Stacked IC Market Challenges
The China 3D Stacked IC market faces a few practical problems, and the first is cost. High production costs for advanced semiconductor devices can inflate prices for domestic manufacturers, reducing their competitiveness in both local and export markets. Supply chain disruptions frequently occur due to reliance on specific regions like Guangdong, leading to delays in component availability that can extend lead times for producers by several weeks. Technology gaps arise from rapid advancements, making it difficult for manufacturers to keep pace, which can result in outdated products that do not satisfy market demands. Regulatory hurdles, such as compliance with updated national standards, can delay product launches and increase costs for suppliers, complicating market entry for new players.
Trends in the China 3D Stacked IC Market
Several trends are reshaping the China 3D Stacked IC Market; the most important are set out below.
- Shift towards Cloud Computing: The cloud computing sector is increasingly adopting 3D Stacked ICs to meet performance demands, particularly in data centers. This shift began in 2022, with demand expected to rise as more companies migrate to cloud solutions.
- Growing Mobile Device Integration: Mobile device manufacturers are integrating 3D Stacked ICs to improve performance and reduce space. This trend started in 2022, as the production of 1.5 billion mobile devices highlighted the need for advanced semiconductor solutions.
- Emphasis on High-Performance Computing: High-performance computing applications are prioritising 3D Stacked ICs for their efficiency and speed. This change is evident in 2023, as demand from data centers and AI applications continues to grow.
- Advancements in Semiconductor Manufacturing: Manufacturers are investing in new technologies to improve 3D Stacked IC production. This trend is particularly noticeable in Guangdong, where significant investments are being made to enhance capabilities.
Investment Opportunities in the China 3D Stacked IC Market
Investors looking at the China 3D Stacked IC Market should consider the following areas.
- Investment in Advanced Manufacturing: Investing in advanced manufacturing technologies for 3D Stacked ICs is timely, with the National Integrated Circuit Industry Investment Fund supporting innovation. This presents opportunities for local manufacturers to improve production capabilities.
- Expansion in Cloud Computing Facilities: With a projected 30% increase in semiconductor production capacity by 2025, cloud computing facilities are key investment areas. Companies should consider partnerships in regions like Guangdong to tap into this growing market.
- Supply of High-Density Memory Solutions: The demand for high-density memory solutions is rising, particularly in mobile devices. Suppliers should focus on providing DRAM and NAND Flash products to meet this increasing need.
- Collaboration with OEM Partners: Collaborating with OEM partners is essential for integrating 3D Stacked ICs into final products. This opportunity is particularly relevant as mobile device production continues to surge.
Government Initiatives in the China 3D Stacked IC Market
The 'Digital Economy Development Plan' launched in 2021 aims to increase semiconductor production capacity by 30% by 2025, enhancing the manufacturing landscape for 3D Stacked ICs. This initiative, overseen by the Ministry of Industry and Information Technology, builds on earlier strategies, such as the '14th Five-Year Plan for Economic and Social Development', which emphasises semiconductor self-sufficiency. The combination of these policies fosters an environment conducive to innovation and expansion in the semiconductor sector, directly benefiting producers of 3D Stacked ICs.
The State Council approved a budget of $15 billion in 2022 for semiconductor technology research and development, administered by the Ministry of Industry and Information Technology. This funding supports various projects aimed at enhancing technological capabilities in the semiconductor industry, ensuring that manufacturers can meet the evolving demands of the market. Additionally, the 'China Semiconductor Innovation Fund', established in 2021, focuses on supporting startups and fostering innovation within the sector, further driving growth.
Future Insight of the China 3D Stacked IC Market
The China 3D Stacked IC market will undergo significant changes by 2032, primarily driven by advancements in semiconductor technology. The National Integrated Circuit Industry Investment Fund's budget of $29 billion will support innovation and production capabilities, improving the overall quality of 3D Stacked ICs. By 2025, the semiconductor industry in China is projected to reach $100 billion, indicating robust growth opportunities. The implementation of the 'Made in China 2025' initiative will further strengthen domestic capabilities, enabling suppliers to effectively meet increasing demand from sectors such as data centers.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Packaging Technology – Through Silicon Via Dominated, Wafer-on-Wafer Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Through Silicon Via accounted for a 38% market share by packaging technology in 2025. Through Silicon Via technology holds the largest share due to its critical role in establishing high-density interconnections between stacked chips, essential for advanced semiconductor applications. This method is particularly prominent in Shanghai, a major hub for semiconductor manufacturing, where demand for efficient solutions is robust. The quickest growth will come from Wafer-on-Wafer, forecast to expand at a CAGR of 8.8% between 2026 and 2032. Wafer-on-Wafer is experiencing rapid growth as it allows for efficient stacking and integration of multiple wafers, increasingly preferred in high-performance computing applications. The rising demand for compact and powerful devices will likely drive further adoption of this technique. Suppliers should enhance their Wafer-on-Wafer capabilities to align with the growing market demand.
By Integration Level – Heterogeneous Dominated and Is Expected to Record the Fastest Growth
Heterogeneous held a 47% share of the China 3D Stacked IC Market by integration level in 2025. Heterogeneous integration leads the market as it enables the combination of different technologies in one package, significantly improving functionality across multiple applications. This integration level is particularly sought after in sectors requiring advanced performance, such as high-performance computing. The same category is also set to grow fastest, at a CAGR of 8.0% during 2026–2032. Heterogeneous is also the fastest-growing segment due to its adaptability to diverse technological needs, which is crucial as industries increasingly seek more integrated solutions. This growth reinforces its market dominance as more applications emerge that benefit from this integration. Buyers will increasingly prefer suppliers that offer Heterogeneous solutions to remain competitive in technological advancements.
By Memory Type – DRAM Dominated, NAND Flash Expected to Grow Fastest
With a 40% revenue share in 2025, DRAM was the largest memory type category. DRAM commands the largest share in the market as it is essential for high-speed data access in computing devices, which are proliferating across various sectors. Its extensive use in mobile devices and data centres solidifies its position as a key memory type in the semiconductor market. NAND Flash is set to record the highest CAGR in this split, 7.6% over 2026–2032. NAND Flash is the fastest-growing memory type, primarily due to its application in storage for mobile devices and data centres, both of which are expanding rapidly. As the demand for data storage increases, NAND Flash's growth trajectory is expected to accelerate significantly. Suppliers must invest in NAND Flash technologies to capitalise on the rising storage demands in the semiconductor market.
By Distribution Channel – Semiconductor Distributors Dominated, Direct Sales Expected to Grow Fastest
In 2025, Semiconductor Distributors led the distribution channel split with a 41% share. Semiconductor Distributors dominate the market share as they play a pivotal role in the supply chain for 3D Stacked ICs, ensuring efficient delivery of products to manufacturers. Their established networks facilitate the distribution of these advanced semiconductor devices across various regions in China. Direct Sales is projected to grow fastest, at a CAGR of 8.1% during 2026–2032. Direct Sales is the fastest-growing channel, essential for securing large contracts and B2B transactions within the semiconductor industry. This trend indicates a movement towards more personalised engagement with clients, enhancing supplier relationships. Suppliers should refine their direct sales strategies to capture larger contracts and strengthen client relationships.
By End User Industry – Mobile Devices Dominated, Cloud Computing Expected to Grow Fastest
Mobile Devices took a 47% share of end user industry in 2025, more than any other category. Mobile Devices lead the market due to their substantial consumption of 3D Stacked ICs, which are crucial for enhancing performance in smartphones and tablets. The production of 1.5 billion mobile devices in 2022 underscores the immense demand in this sector. The quickest growth will come from Cloud Computing, forecast to expand at a CAGR of 8.8% between 2026 and 2032. Cloud Computing is the fastest-growing end user industry, driven by the increasing need for high-performance chips for data processing and storage. As cloud services expand, the demand for advanced semiconductor solutions will continue to rise, further boosting this segment. Suppliers should focus on developing solutions tailored for the cloud computing sector to meet its escalating demands.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China 3D Stacked IC Market Outlook
- Market Size of China 3D Stacked IC Market, 2025
- Forecast of China 3D Stacked IC Market, 2032
- Historical Data and Forecast of China 3D Stacked IC Revenues & Volume for the Period 2022 - 2032F
- China 3D Stacked IC Market Trend Evolution
- China 3D Stacked IC Market Drivers and Challenges
- China 3D Stacked IC Price Trends
- China 3D Stacked IC Porter's Five Forces
- China 3D Stacked IC Industry Life Cycle
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Packaging Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Through Silicon Via for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Wafer-on-Wafer for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Die-on-Die for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By 2.5D Stacking for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Integration Level for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Heterogeneous for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Homogeneous for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By High-Density for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Moderate Density for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Memory Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By DRAM for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By NAND Flash for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By SRAM for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By eMMC for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Semiconductor Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By OEM Partners for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Mobile Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Cloud Computing for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Telecom Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Stacked IC Market Revenues & Volume By Networking Equipment for the Period 2022 - 2032F
- China 3D Stacked IC Import Export Trade Statistics
- Market Opportunity Assessment By Packaging Technology
- Market Opportunity Assessment By Integration Level
- Market Opportunity Assessment By Memory Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China 3D Stacked IC Top Companies Market Share
- China 3D Stacked IC Competitive Benchmarking By Technical and Operational Parameters
- China 3D Stacked IC Company Profiles
- China 3D Stacked IC Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Packaging Technology
- Through Silicon Via
- Wafer-on-Wafer
- Die-on-Die
- 2.5D Stacking
By Integration Level
- Heterogeneous
- Homogeneous
- High-Density
- Moderate Density
By Memory Type
- DRAM
- NAND Flash
- SRAM
- eMMC
By Distribution Channel
- Semiconductor Distributors
- Online Platforms
- Direct Sales
- OEM Partners
By End User Industry
- Mobile Devices
- Cloud Computing
- Telecom Infrastructure
- Networking Equipment































