China 3D Vision Systems Market Size & Growth Rate
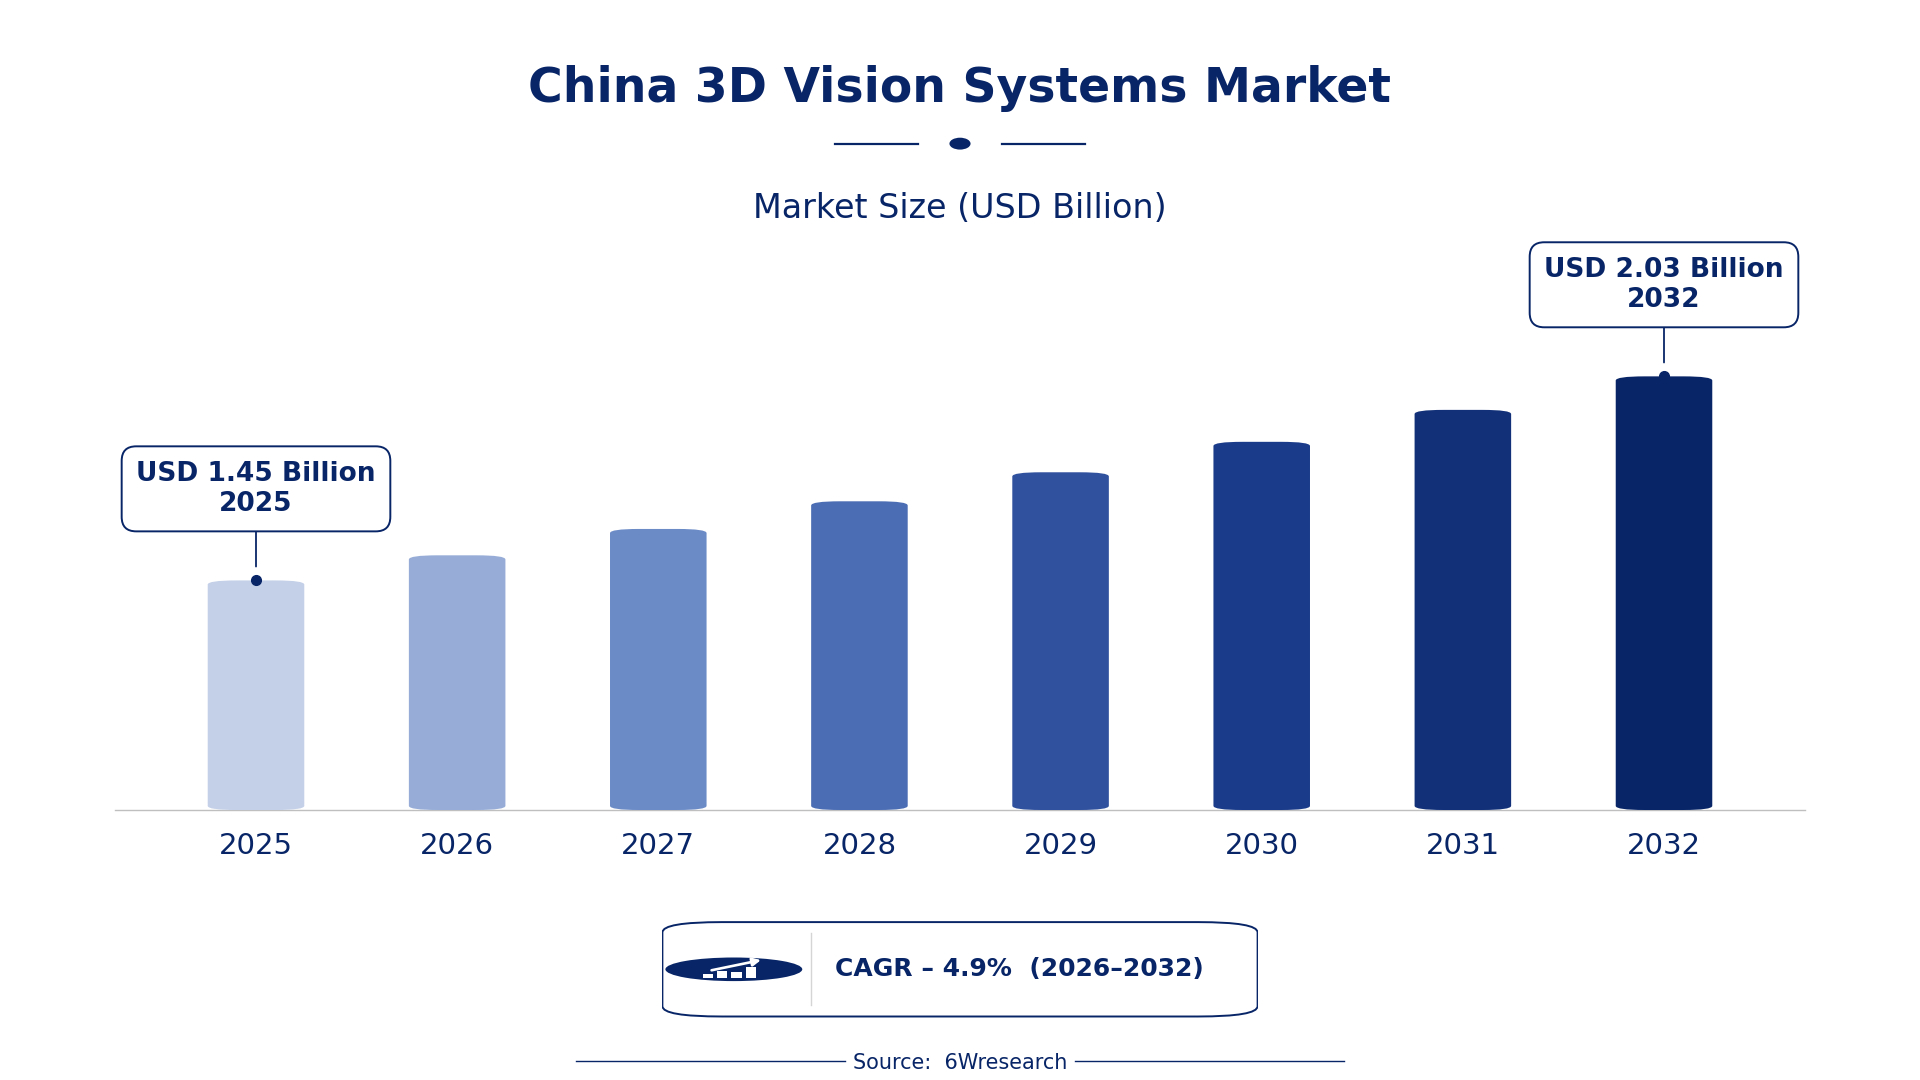
According to 6Wresearch internal database and industry insights, the China 3D Vision Systems Market was valued at USD 1.45 billion in 2025 and is projected to reach USD 2.03 billion by 2032, growing at a CAGR of approximately 4.9% during 2026–2032.
China 3D Vision Systems Market Highlights
| Report Metric | Details |
| Report Name | China 3D Vision Systems Market |
| Market Size 2025 | USD 1.45 billion |
| Market Size 2032 | USD 2.03 billion |
| Absolute Growth 2025–2032 | USD 0.58 billion |
| CAGR 2026–2032 | 4.9% |
| Peak Annual Growth | 8.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Hardware (46% share) |
| Leading Technology Type, 2025 | Stereoscopic Vision (50% share) |
| Leading Sensing Type, 2025 | Active Sensing (40% share) |
| Leading Distribution Channel, 2025 | Direct Sales (35% share) |
| Leading End User Industry, 2025 | Industrial Automation (43% share) |
| Fastest-Growing Component Type | Software (6.3% CAGR) |
| Fastest-Growing Technology Type | Time-of-Flight (7.0% CAGR) |
| Fastest-Growing Distribution Channel | System Integrators (7.6% CAGR) |
| Fastest-Growing End User Industry | Robotics Industry (6.7% CAGR) |
| Growing Sector | Industrial Automation |
| Key End Users | Manufacturers, Robotics Developers, System Integrators, OEMs |
China 3D Vision Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
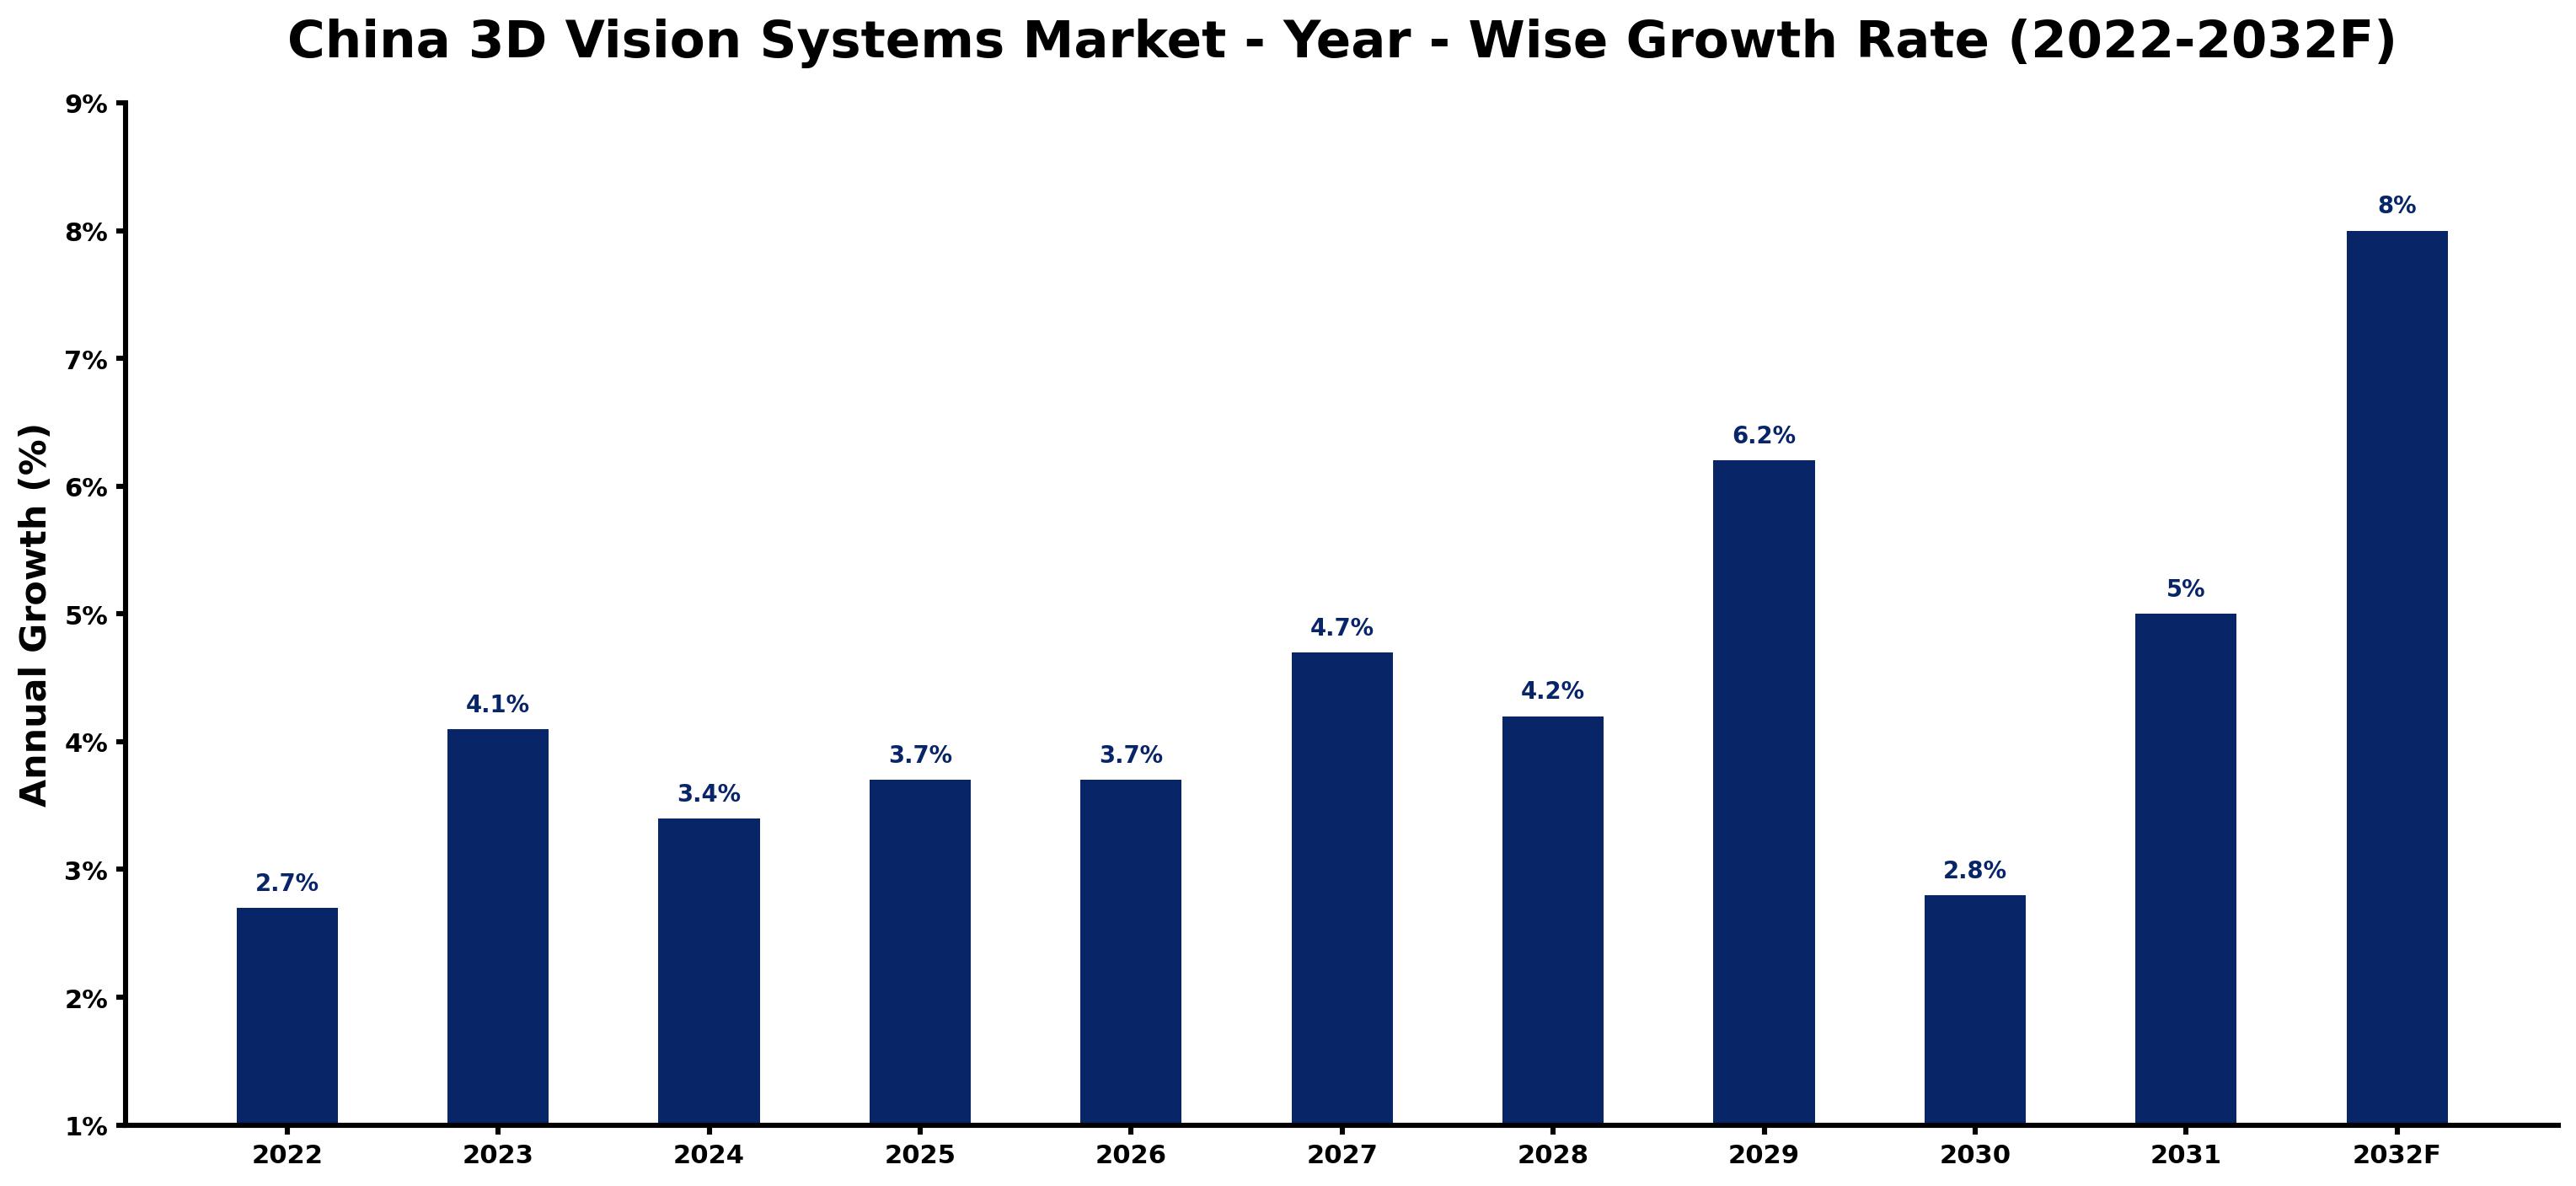
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.7 | The market showed steady growth due to increasing automation in various industries. |
| 2023 | 4.1 | Demand surged as the automotive assembly sector produced over 25 million vehicles. |
| 2024 | 3.4 | Growth slowed as manufacturers adjusted to new automation technologies and standards. |
| 2025 | 3.7 | A resurgence in investment in smart manufacturing boosted demand for 3D vision systems. |
| 2026 | 3.7 | Market growth decelerated as companies faced challenges in integrating advanced systems. |
| 2027 | 4.7 | Increased production in the robotics industry spurred demand for 3D vision technologies. |
| 2028 | 4.2 | Growth moderated as the market adapted to evolving consumer needs and technologies. |
| 2029 | 6.2 | A significant rise in demand for precision in manufacturing led to faster growth. |
| 2030 | 2.8 | The market slowed as companies reassessed their automation strategies and investments. |
| 2031 | 5.0 | An uptick in robotics applications revitalised demand for 3D vision systems. |
| 2032 | 8.0 | The market is expected to peak as investments in automation and robotics escalate. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China 3D Vision Systems Market Synopsis
The 3D Vision Systems Market in China includes technologies that enable machines to interpret three-dimensional environments. These systems utilise sensors, cameras, and software algorithms, primarily serving automation, quality control, and robotics. The market is expanding due to the growth of industrial automation and robotics, with the automotive assembly sector producing over 25 million vehicles in 2022. Investment in smart manufacturing reached $30 billion in 2021, further driving demand for these systems. The 'Made in China 2025' initiative is improving automation capabilities across various industries.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing investment in smart manufacturing technologies | Driver | High | Integrated Systems |
| Rising demand from the automotive assembly sector | Driver | High | Industrial Automation |
| Growing opportunities for system integrators in automation | Opportunity | High | System Integrators |
| Expansion of robotics applications in manufacturing | Opportunity | High | Robotics Industry |
| Challenges in integrating advanced technologies | Restraint | High | Hardware |
| Limited awareness of 3D vision systems benefits | Restraint | Medium | Software |
| The 3D Vision Systems Market in China faces high integration costs | Challenge | High | Integrated Systems |
| Competition from alternative automation technologies | Challenge | Medium | Robotics Industry |
Evaluation of Drivers in China 3D Vision Systems Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing investment in smart manufacturing | Integrated Systems | In 2021, China's investment in smart manufacturing reached $30 billion, increasing demand for integrated solutions. |
| High vehicle production rates | Industrial Automation | The automotive assembly sector in China produced over 25 million vehicles in 2022, driving demand for automation technologies. |
| Increased adoption of robotics | Robotics Industry | The Robotics Industry in China is projected to grow at a CAGR of 20% from 2023 to 2028, boosting demand for vision systems. |
| Expansion of manufacturing capabilities | Hardware | The 'Made in China 2025' initiative aims to enhance automation, increasing the need for advanced hardware solutions. |
| Rising demand for precision and efficiency | Software | The demand for 3D vision systems in manufacturing is driven by the need for accuracy, leading to higher software purchases. |
Market growth in China for 3D Vision Systems rests on substantial investments in smart manufacturing, rising end-use demand from the automotive sector, and the rapid expansion of robotics applications. In 2021, investment in smart manufacturing reached $30 billion, prompting manufacturers to adopt advanced technologies. The automotive assembly sector produced over 25 million vehicles in 2022, increasing the demand for automation solutions. The Robotics Industry is projected to grow at 20% from 2023 to 2028, further driving the need for 3D vision systems.
Evaluation of Restraints in China 3D Vision Systems Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with technology integration | Integrated Systems | Integration costs can exceed 30% of project budgets, deterring adoption among smaller manufacturers. |
| Lack of awareness about 3D vision benefits | Software | Many manufacturers remain unaware of the advantages of 3D vision systems, limiting market growth. |
| Limited skilled workforce for advanced systems | Hardware | The shortage of skilled technicians hampers the effective implementation of 3D vision technologies. |
| Regulatory hurdles for automation technologies | Industrial Automation | Compliance with ISO 9001 standards can delay project timelines, affecting market entry. |
| Technological obsolescence due to rapid advancements | Robotics Industry | Emerging technologies may divert investment away from 3D vision systems, impacting market dynamics. |
China 3D Vision Systems Market Challenges
Buyers in the China 3D Vision Systems market encounter regulatory hurdles, as compliance with ISO 9001 standards can delay product approvals by up to six months, affecting production timelines. Technology gaps exist because many manufacturers lack the infrastructure for advanced 3D systems, resulting in inefficiencies that can raise operational costs by 15% for these producers. Rising component prices create cost pressures, inflating system costs by 20%, which forces buyers to reassess their automation budgets. Supply chain disruptions arise from reliance on imported components, leading to project delivery delays that impact manufacturers' competitiveness in the market.
Trends in the China 3D Vision Systems Market
Below mentioned are some of the trends shaping the China 3D Vision Systems Market growth.
- Shift towards Active Sensing Technologies: Active Sensing is becoming more common in 3D vision systems, driven by the need for dynamic interaction in manufacturing. In 2025, Active Sensing is projected to hold a 40% market share, improving operational efficiency.
- Increase in Robotics Applications: The demand for robotics in manufacturing is on the rise, with the Robotics Industry projected to grow at 20% from 2023 to 2028. This trend is prompting higher investments in 3D vision systems.
- Expansion of Direct Sales Channels: Direct Sales is the leading distribution channel, expected to account for 35% of the market share in 2025. This shift allows manufacturers to reach customers more effectively.
- Growth of Integrated Systems: Integrated Systems are gaining traction as manufacturers seek complete solutions. The market for these systems is projected to grow significantly, driven by the 'National Key R&D Program'.
Investment Opportunities in the China 3D Vision Systems Market
Some of the investment opportunities in the China 3D Vision Systems Market are mentioned below.
- Partnerships with System Integrators: Now is an opportune time for partnerships with system integrators, as they are essential for implementing 3D vision systems. The Guangdong province, a major manufacturing hub, presents collaboration opportunities.
- Investment in Robotics Technologies: With the Robotics Industry projected to grow at 20%, there is a strong opportunity for investment in 3D vision systems. Targeting manufacturers in the Beijing-Tianjin-Hebei region can yield substantial returns.
- Expansion into Industrial Automation: The industrial automation sector is rapidly growing, creating demand for 3D vision systems. Engaging with OEMs in the automotive assembly sector can facilitate market entry.
- Focus on Smart Manufacturing Initiatives: Investing in technologies that align with the 'National Key R&D Program' can yield high returns. Collaborating with local partners can improve market penetration.
Government Initiatives in the China 3D Vision Systems Market
The 'Made in China 2025' initiative, launched by the Ministry of Industry and Information Technology in 2015, aims to boost automation and robotics capabilities in manufacturing. This initiative encourages investment in advanced manufacturing technologies, supporting the development of 3D vision systems. In 2021, the State Council approved the '14th Five-Year Plan for National Economic and Social Development,' which emphasises the importance of integrating AI in manufacturing processes. This plan supports the growth of automation technologies, directly benefiting producers of 3D vision systems.
Buyers in the 3D Vision Systems market benefit from the 'National Key R&D Program', initiated by the Ministry of Science and Technology in 2020, which funds the development of intelligent manufacturing technologies. This program supports projects that enhance automation capabilities and improve efficiency in production processes.
Future Insight of the China 3D Vision Systems Market
The China 3D Vision Systems market will evolve significantly by 2032, driven by advancements in automation and smart manufacturing initiatives. The 'Made in China 2025' programme will strengthen local production capabilities, while investments in AI integration are projected to reach $50 billion, improving operational efficiency. The Guangdong province will remain a key hub for automation technologies, encouraging innovation and collaboration. Events like the Shanghai International Robotics Week will facilitate partnerships between technology providers and manufacturers, ensuring alignment on future developments.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Component Type – Hardware Dominated, Software Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, the largest component type category in 2025 was Hardware, with a 46% share of total revenue. Hardware holds the largest market share due to its essential role in the functionality of 3D Vision Systems, particularly in sectors like industrial automation. For instance, the reliance on critical hardware components such as sensors and cameras is paramount for effective system operation. Software is projected to grow fastest, at a CAGR of 6.3% during 2026–2032. Software is experiencing rapid growth as it is essential for processing and analysing visual data captured by hardware. The increasing complexity of data requirements in automation applications is driving this demand, indicating a notable rise in software adoption. Suppliers must focus on enhancing software solutions to capture the growing market share in the 3D Vision Systems sector.
By Technology Type – Stereoscopic Vision Dominated, Time-of-Flight Expected to Grow Fastest
Stereoscopic Vision accounted for a 50% market share by technology type in 2025. Stereoscopic Vision commands the largest market share due to its extensive use for depth perception in various applications, particularly in industrial settings. Its established presence in the industry makes it a preferred choice among users seeking reliable 3D imaging solutions. Time-of-Flight is set to record the highest CAGR in this split, 7.0% over 2026–2032. Time-of-Flight technology is gaining traction because of its significance in accurate distance measurement, which is critical for advanced automation processes. As industries pursue more precise solutions, this technology's adoption is expected to accelerate significantly. Buyers should consider investing in Time-of-Flight technology to stay competitive in the rapidly advancing 3D Vision Systems market.
By Sensing Type – Active Sensing Dominated and Is Expected to Record the Fastest Growth
With a 40% revenue share in 2025, Active Sensing was the largest sensing type category. Active Sensing leads the market share as it is crucial for interaction in dynamic environments, making it indispensable in automation and robotics applications. Its ability to provide real-time data enhances operational efficiency across various sectors. Its lead should widen, with a projected CAGR of 6.4% during 2026–2032, the highest in this split. Active Sensing is also the fastest-growing segment, as its capabilities are increasingly recognised in advanced robotics and automation. The synergy between its established use and growing demand ensures its lead will continue to expand. Suppliers should prioritise the development of Active Sensing technologies to meet the escalating demands of the 3D Vision Systems market.
By Distribution Channel – Direct Sales Dominated, System Integrators Expected to Grow Fastest
In 2025, Direct Sales led the distribution channel split with a 35% share. Direct Sales captures the largest share as it serves as a primary channel for reaching customers directly, facilitating immediate transactions. This model is particularly effective in sectors where buyers prefer direct engagement with suppliers, ensuring a streamlined purchasing process. Over 2026–2032, System Integrators are expected to post the fastest growth, at a CAGR of 7.6%. System Integrators are the fastest-growing distribution channel, as they play a critical role in implementing 3D systems tailored to specific industry needs. Their expertise in integrating complex technologies is driving increased demand for their services. Suppliers should strengthen partnerships with System Integrators to enhance market penetration in the 3D Vision Systems sector.
By End User Industry – Industrial Automation Dominated, Robotics Industry Expected to Grow Fastest
Industrial Automation took a 43% share of end user industry in 2025, more than any other category. Industrial Automation commands the largest market share as it is the major user of 3D Vision technology, utilising these systems for quality control and process optimisation. The sector's growth is propelled by the ongoing push for smart manufacturing solutions and efficiency improvements. Robotics Industry is projected to grow fastest, at a CAGR of 6.7% during 2026–2032. The Robotics Industry is the fastest-growing segment, heavily relying on vision systems for operational efficiency and precision. As robotics applications expand, the demand for advanced 3D Vision Systems will continue to surge, further driving market growth. Buyers in the Robotics Industry should prioritise the adoption of 3D Vision Systems to enhance their operational capabilities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China 3D Vision Systems Market Outlook
- Market Size of China 3D Vision Systems Market, 2025
- Forecast of China 3D Vision Systems Market, 2032
- Historical Data and Forecast of China 3D Vision Systems Revenues & Volume for the Period 2022 - 2032F
- China 3D Vision Systems Market Trend Evolution
- China 3D Vision Systems Market Drivers and Challenges
- China 3D Vision Systems Price Trends
- China 3D Vision Systems Porter's Five Forces
- China 3D Vision Systems Industry Life Cycle
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Hardware for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Software for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Services for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Integrated Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Stereoscopic Vision for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Time-of-Flight for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Structured Light for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Laser Triangulation for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Sensing Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Passive Sensing for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Active Sensing for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Binocular Vision for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Monocular Vision for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Industrial Automation for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Robotics Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China 3D Vision Systems Market Revenues & Volume By Automotive Assembly for the Period 2022 - 2032F
- China 3D Vision Systems Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Sensing Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China 3D Vision Systems Top Companies Market Share
- China 3D Vision Systems Competitive Benchmarking By Technical and Operational Parameters
- China 3D Vision Systems Company Profiles
- China 3D Vision Systems Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Component Type
- Hardware
- Software
- Services
- Integrated Systems
By Technology Type
- Stereoscopic Vision
- Time-of-Flight
- Structured Light
- Laser Triangulation
By Sensing Type
- Passive Sensing
- Active Sensing
- Binocular Vision
- Monocular Vision
By Distribution Channel
- Online Platforms
- System Integrators
- Direct Sales
- OEMs
By End User Industry
- Industrial Automation
- Robotics Industry
- Manufacturing
- Automotive Assembly































