China 5G Cloud Service Market Size & Growth Rate
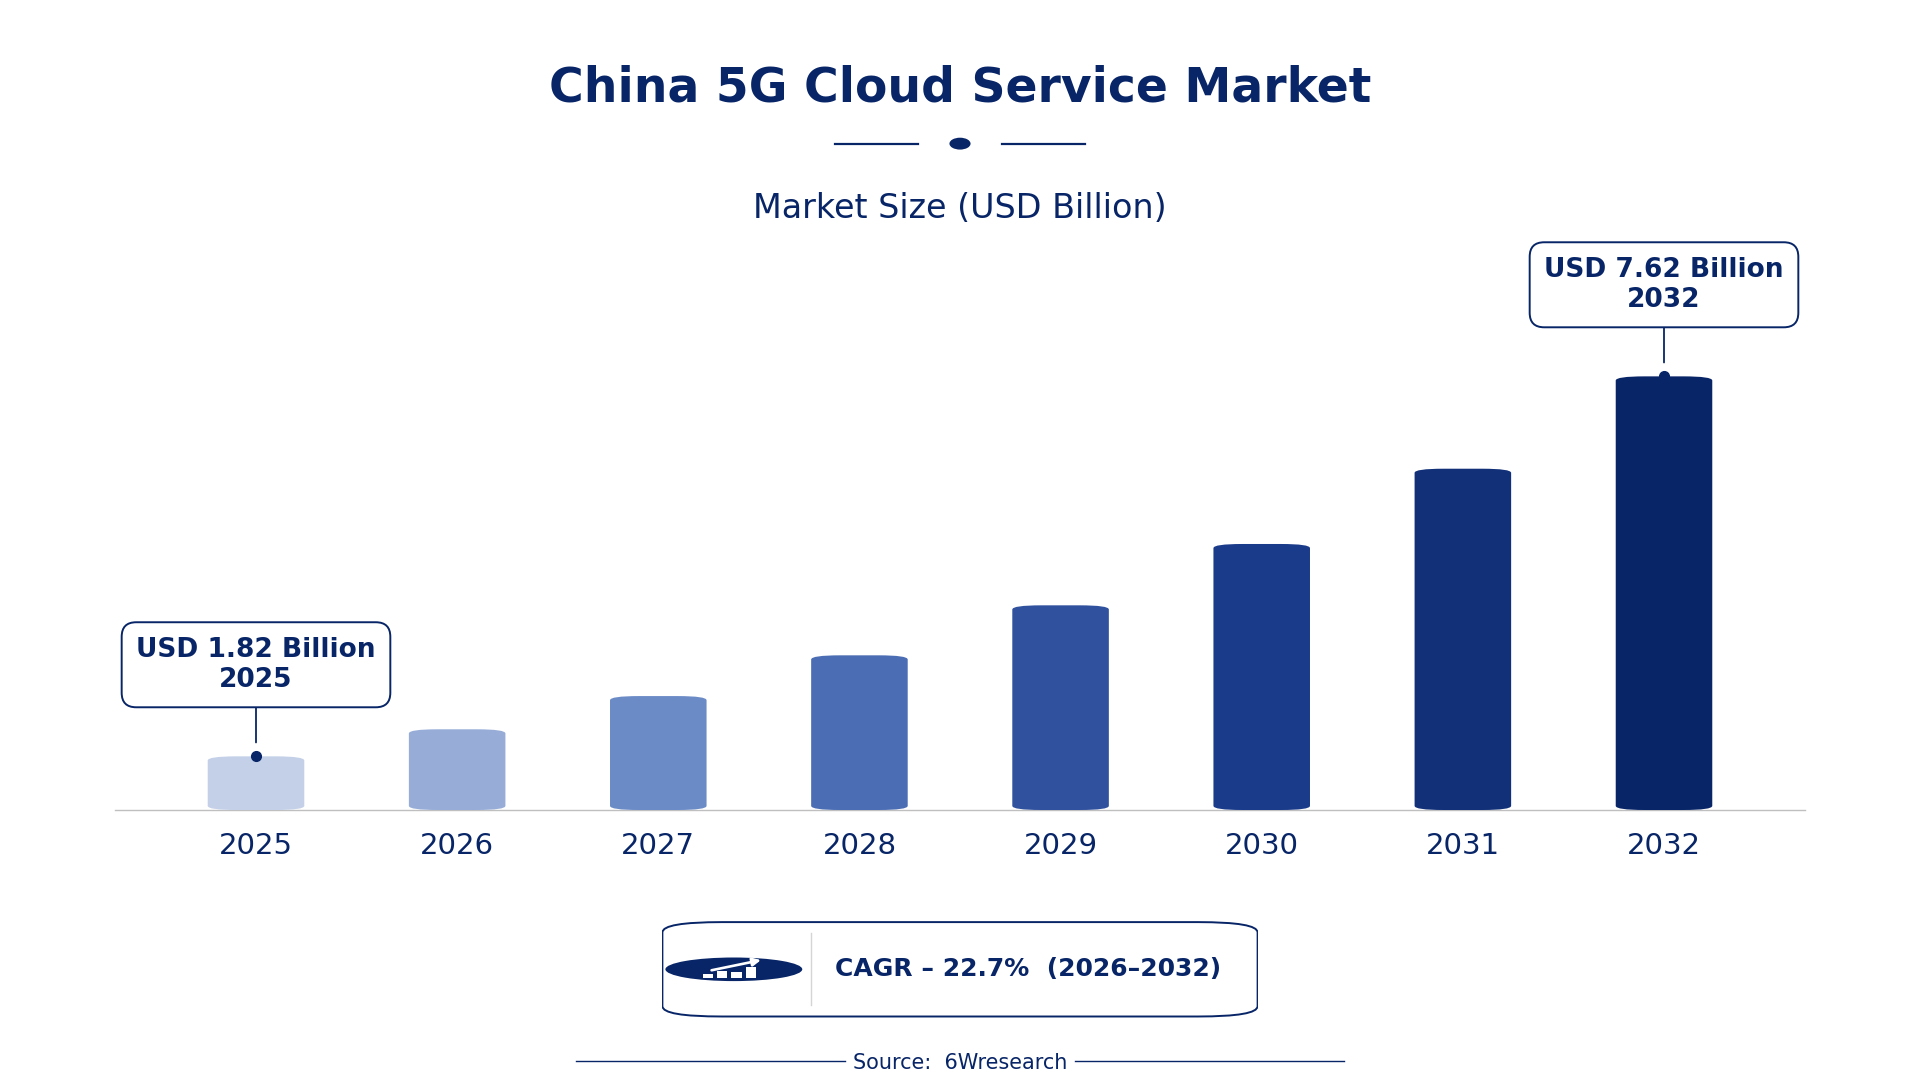
According to 6Wresearch internal database and industry insights, the China 5G Cloud Service Market was valued at USD 1.82 billion in 2025 and is projected to reach USD 7.62 billion by 2032, growing at a CAGR of approximately 22.7% during 2026–2032.
China 5G Cloud Service Market Highlights
| Report Metric | Details |
| Report Name | China 5G Cloud Service Market |
| Market Size 2025 | USD 1.82 billion |
| Market Size 2032 | USD 7.62 billion |
| Absolute Growth 2025–2032 | USD 5.80 billion |
| CAGR 2026–2032 | 22.7% |
| Peak Annual Growth | 25.4% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Service Type, 2025 | Network Slicing (42% share) |
| Leading Cloud Model, 2025 | IaaS (42% share) |
| Leading Deployment Type, 2025 | Public Cloud (44% share) |
| Leading End User, 2025 | Telecom Providers (33% share) |
| Leading Distribution Channel, 2025 | Direct Sales (40% share) |
| Fastest-Growing Service Type | Edge Cloud Services (24.4% CAGR) |
| Fastest-Growing Cloud Model | PaaS (25.5% CAGR) |
| Fastest-Growing Deployment Type | Hybrid Cloud (24.5% CAGR) |
| Fastest-Growing End User | Enterprise Customers (24.9% CAGR) |
| Fastest-Growing Distribution Channel | Online Platforms (24.5% CAGR) |
| Growing Sector | Telecommunications |
| Key End Users | Telecom Providers, Enterprise Customers, Industrial Plants |
China 5G Cloud Service Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
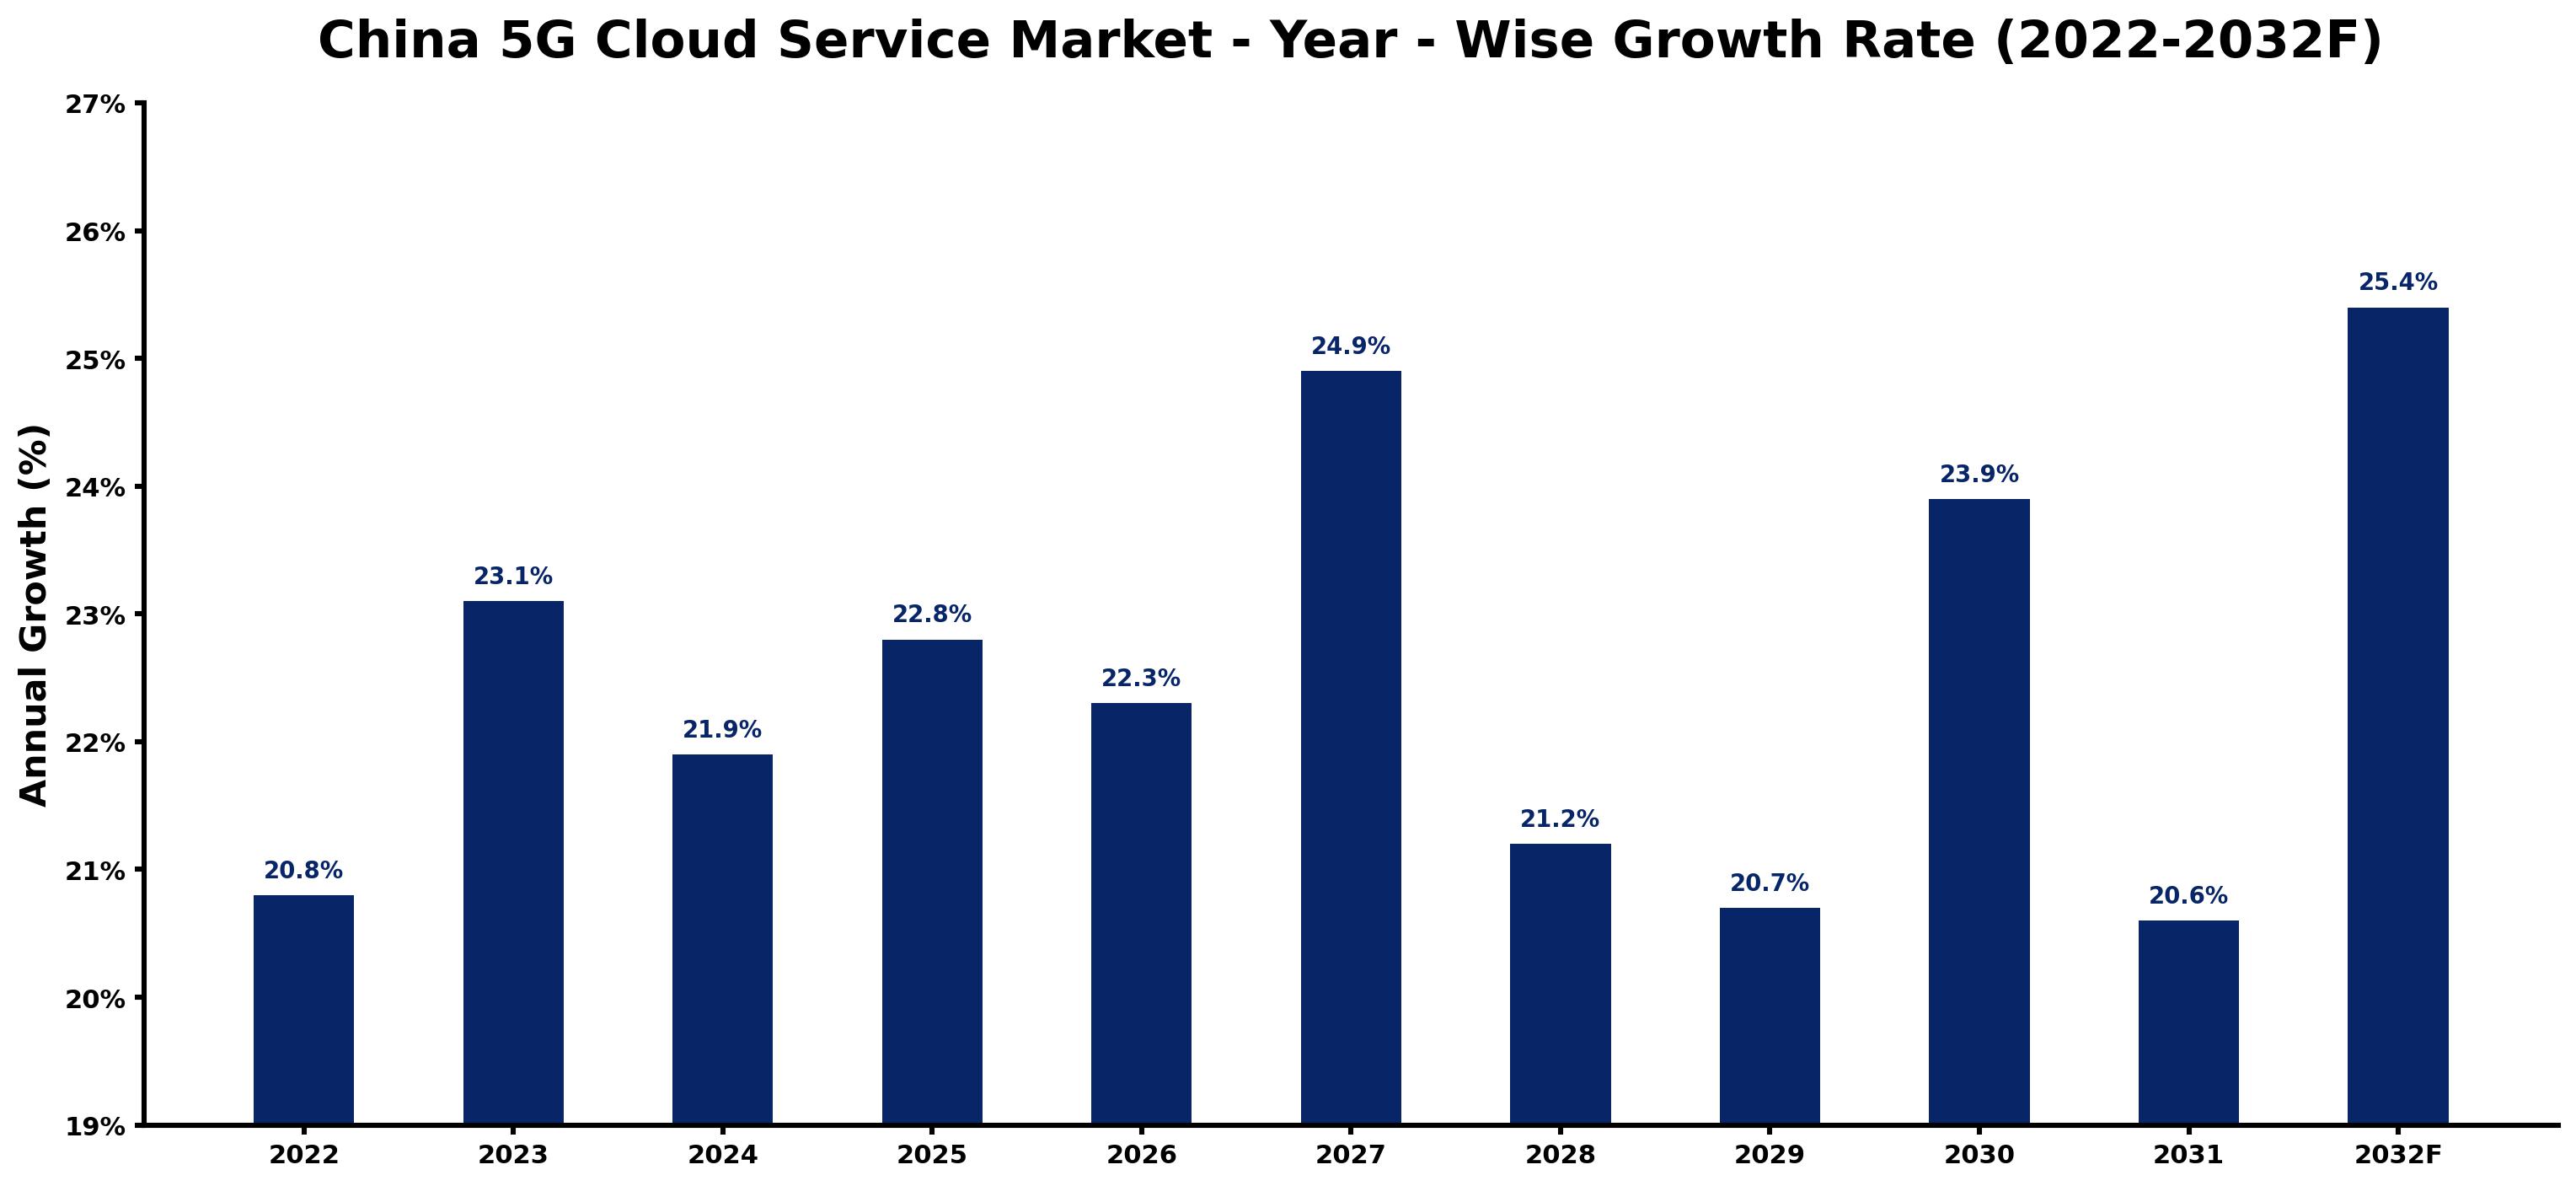
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 20.8 | The market experienced steady growth due to increasing investments in 5G infrastructure. |
| 2023 | 23.1 | Growth accelerated as the user base reached 1.6 billion, driving demand for services. |
| 2024 | 21.9 | The market growth slowed slightly as investments adjusted to meet demand levels. |
| 2025 | 22.8 | Demand surged again, driven by the government's push for urban 5G coverage. |
| 2026 | 22.3 | A slight slowdown is expected as the market adjusts to the previous year's rapid growth. |
| 2027 | 24.9 | Growth is projected to rebound strongly, propelled by the expansion of edge cloud services. |
| 2028 | 21.2 | The market is anticipated to slow down as competition intensifies among service providers. |
| 2029 | 20.7 | Growth is expected to continue decelerating as market saturation begins to take effect. |
| 2030 | 23.9 | Demand is projected to pick up again, supported by new applications in smart cities. |
| 2031 | 20.6 | The market is expected to experience another slowdown as consolidation among providers occurs. |
| 2032 | 25.4 | A peak in growth is anticipated as 5G applications expand across various sectors. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China 5G Cloud Service Market Synopsis
The 5G Cloud Service market in China combines advanced networking with cloud computing to improve data processing and storage. It supports faster data transfer and IoT applications, making it essential for telecom providers and enterprises. The market is growing due to a user base of 1.6 billion 5G users by 2023. Government initiatives like the 5G Innovation and Development Action Plan and substantial investments are driving this growth, leading to increased adoption across various sectors.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in 5G infrastructure by telecom providers | Driver | High | Telecom Providers |
| Growing demand for IoT applications among enterprises | Driver | High | Enterprise Customers |
| Increased funding for smart city projects | Opportunity | High | Telecom Providers |
| Expansion of edge cloud services for reduced latency | Opportunity | High | Edge Cloud Services |
| High costs associated with 5G infrastructure deployment | Restraint | High | Telecom Providers |
| Regulatory hurdles in 5G application approvals | Restraint | Medium | Enterprise Customers |
| Intense competition among service providers | Challenge | High | Telecom Providers |
| Delays in achieving full urban 5G coverage | Challenge | Medium | Telecom Providers |
Evaluation of Drivers in China 5G Cloud Service Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in 5G infrastructure | Telecom Providers | China's 5G network investment is projected at 1 trillion RMB by 2025, improving service capabilities. |
| Growing demand for IoT applications | Enterprise Customers | 5G-enabled IoT devices are expected to exceed 1 billion units by 2025, driving enterprise adoption. |
| Government initiatives for smart city development | Telecom Providers | The National Internet Information Office promotes 5G for smart cities, boosting demand for related services. |
| Expansion of edge cloud services | Edge Cloud Services | Edge cloud services reduce latency, improving user experience and driving adoption among enterprises. |
| Support for innovative projects in 5G applications | Enterprise Customers | The Ministry of Science and Technology aims to support over 100 projects by 2025, increasing enterprise engagement. |
The 5G Cloud Service market in China is expanding as telecom providers and enterprise customers increase investments in infrastructure and IoT applications. China's 5G network investment is projected at 1 trillion RMB by 2025, which will improve service delivery capabilities. Demand for 5G-enabled IoT devices is expected to exceed 1 billion units by 2025, driving enterprise adoption of cloud services. The expansion of edge cloud services reduces latency, improving user experiences and attracting more enterprise customers.
Evaluation of Restraints in China 5G Cloud Service Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of deploying 5G infrastructure | Telecom Providers | Deployment costs can reach billions, limiting smaller providers' market entry. |
| Regulatory hurdles in obtaining approvals for new applications | Enterprise Customers | Approval delays can hinder timely implementation of 5G solutions. |
| Intense competition among service providers | Telecom Providers | Price wars may reduce profit margins, affecting service quality. |
| Market saturation in urban areas | Telecom Providers | As coverage increases, growth opportunities in major cities diminish. |
| Limited awareness of 5G benefits among enterprises | Enterprise Customers | Many enterprises remain hesitant to invest in new technologies without clear ROI. |
China 5G Cloud Service Market Challenges
The China 5G Cloud Service market encounters fierce competition, leading to price reductions that can diminish producers' revenues by as much as 20%. Regulatory challenges from the Ministry of Industry and Information Technology can delay service deployment by several months, impacting telecom providers' ability to launch new offerings. Buyers face difficulties in integrating 5G cloud services with existing infrastructure, resulting in implementation delays that may last up to a year. Additionally, rising operational costs, anticipated to increase by 15% annually, place financial pressure on enterprises seeking to adopt these advanced technologies.
Trends in the China 5G Cloud Service Market
Below mentioned are some of the trends shaping the China 5G Cloud Service Market growth.
- Shift towards Edge Cloud Services: In 2022, demand for edge cloud services surged as enterprises sought to reduce latency. With over 1,000 5G applications in healthcare and education, this trend is reshaping service delivery.
- Increasing Integration of 5G in Smart Cities: The National Internet Information Office's 2023 strategy promotes 5G's role in smart city development, with urban infrastructure improvements expected to boost adoption rates by 30%.
- Growth in Private 5G Cloud Solutions: As enterprises seek dedicated networks, the demand for private 5G cloud solutions has risen. This trend is projected to grow, particularly among industrial plants aiming for automation.
- Expansion of 5G Applications in Transportation: 5G technology is being integrated into public transportation systems across major cities, enhancing operational efficiency and user experience, with investments of 200 billion RMB supporting this shift.
Investment Opportunities in the China 5G Cloud Service Market
Below are the investment opportunities with the strongest case in the China 5G Cloud Service Market.
- Partnerships for Smart City Projects: Now is the time to invest in partnerships for smart city projects, as the National Internet Information Office promotes 5G integration. This presents opportunities for telecom providers to collaborate with local governments, with an estimated budget of 500 billion RMB.
- Investment in Edge Cloud Infrastructure: With edge cloud services projected to grow, investing in infrastructure to support these services is essential. Telecom providers can benefit from this shift by enhancing service offerings, with a market potential of 1 trillion RMB.
- Supply of Private 5G Solutions: The demand for private 5G solutions is increasing among industrial plants. Suppliers can enter this market by forming joint ventures with local firms to provide tailored solutions.
- Expansion into Rural Areas: As 5G coverage expands to rural areas, there is an opportunity to invest in telecom infrastructure. Collaborating with local governments can facilitate entry into these emerging markets.
Government Initiatives in the China 5G Cloud Service Market
The 5G Innovation and Development Action Plan issued by the Ministry of Industry and Information Technology in 2021 aims to improve 5G technology integration across various sectors. This plan encourages telecom providers to innovate and expand their service offerings, ultimately benefiting enterprise customers. The National Development and Reform Commission's 2022 5G Infrastructure Development Initiative, with a budget of 500 billion RMB, focuses on improving network capabilities, further supporting the growth of 5G services in urban areas. The State Council's 14th Five-Year Plan outlines specific targets for expanding 5G coverage to all urban areas by 2025, impacting telecom investments and infrastructure development.
The Ministry of Science and Technology's 2020 initiative promotes research and development in 5G applications, aiming to support over 100 projects by 2025. This initiative provides funding for projects that utilize 5G technology, benefiting enterprises looking to integrate these solutions. The National Internet Information Office's 2023 strategy emphasizes the role of 5G in developing smart cities, focusing on urban infrastructure improvements. This strategy encourages telecom providers to collaborate with local governments, facilitating the implementation of 5G solutions in urban settings.
Future Insight of the China 5G Cloud Service Market
The China 5G Cloud Service market will undergo transformative changes by 2032, driven by robust government initiatives and technological progress. The 5G Infrastructure Development Initiative is set to enhance network capabilities, aiming for full urban coverage by 2025. By that same year, over 1 billion 5G-enabled IoT devices will emerge, unlocking new opportunities for buyers in various industries. The integration of 5G in smart agriculture projects will further expand applications, providing benefits for both suppliers and enterprises.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Service Type – Network Slicing Dominated, Edge Cloud Services Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Network Slicing took a 42% share of service type in 2025, more than any other category. Network Slicing holds the largest share in the China 5G Cloud Service Market due to its ability to allocate tailored network resources for diverse applications. This is particularly important for telecom providers managing extensive 5G networks, ensuring optimal performance across over 300 cities. The quickest growth will come from Edge Cloud Services, forecast to expand at a CAGR of 24.4% between 2026 and 2032. Edge Cloud Services is witnessing rapid growth because it significantly reduces latency by processing data closer to the source, essential for real-time applications. The expected rise in 5G-enabled IoT devices, projected to exceed 1 billion units by 2025, further drives this demand. Suppliers should focus on enhancing Edge Cloud Services to address the increasing need for low-latency solutions.
By Cloud Model – IaaS Dominated, PaaS Expected to Grow Fastest
In 2025, IaaS led the cloud model split with a 42% share. IaaS leads the market as it effectively supports the core infrastructure needs of telecom providers and enterprises utilising 5G technology. Its flexibility in resource allocation is crucial for the ongoing expansion of 5G services throughout China. PaaS are set to record the highest CAGR in this split, 25.5% over 2026–2032. PaaS is the fastest-growing segment as it accelerates application development, allowing businesses to innovate and adapt swiftly to market demands. The growing number of 5G applications in sectors like healthcare and education propels this growth. Buyers should consider PaaS solutions to optimise their application development processes and improve service offerings.
By Deployment Type – Public Cloud Dominated, Hybrid Cloud Expected to Grow Fastest
Public Cloud held a 44% share of the China 5G Cloud Service Market by deployment type in 2025. Public Cloud leads the market as it provides general services that are widely accessible, making it the go-to option for many enterprises adopting 5G. Its scalability is particularly appealing to telecom providers expanding their service capabilities. Hybrid Cloud is projected to grow fastest, at a CAGR of 24.5% during 2026–2032. Hybrid Cloud is growing quickly as it combines the benefits of public and private clouds, allowing businesses to optimise their 5G deployments. This flexibility supports diverse operational needs across various sectors. Suppliers must adapt their offerings to include Hybrid Cloud solutions to meet the evolving demands of enterprises.
By End User – Telecom Providers Dominated, Enterprise Customers Expected to Grow Fastest
The largest end user category in 2025 was Telecom Providers, with a 33% share of total revenue. Telecom Providers represent the largest user group of 5G Cloud Services, primarily for managing and optimising their network operations. Their substantial investment in 5G infrastructure directly correlates with their dominant market share. Over 2026–2032, Enterprise Customers are expected to post the fastest growth, at a CAGR of 24.9%. Enterprise Customers are swiftly increasing their adoption of 5G Cloud Services to improve operational efficiency and drive innovation. This trend highlights the growing importance of 5G in enabling competitive advantages for businesses. Providers should tailor their services to address the specific needs of enterprise customers to maintain competitiveness in the market.
By Distribution Channel – Direct Sales Dominated, Online Platforms Expected to Grow Fastest
With a 40% revenue share in 2025, Direct Sales was the largest distribution channel category. Direct Sales is the primary distribution channel, enabling personalised service delivery, which is vital for the complexities of 5G Cloud Services. This approach allows providers to cultivate strong relationships with telecom operators and enterprises. The quickest growth will come from Online Platforms, forecast to expand at a CAGR of 24.5% between 2026 and 2032. Online Platforms are rapidly expanding as they serve as effective marketing channels for 5G Cloud Services, reaching a broader audience. The shift in purchasing behaviour among enterprises towards digital channels accelerates this trend. Suppliers should enhance their online presence to capture the growing interest in 5G Cloud Services through digital platforms.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China 5G Cloud Service Market Outlook
- Market Size of China 5G Cloud Service Market, 2025
- Forecast of China 5G Cloud Service Market, 2032
- Historical Data and Forecast of China 5G Cloud Service Revenues & Volume for the Period 2022 - 2032F
- China 5G Cloud Service Market Trend Evolution
- China 5G Cloud Service Market Drivers and Challenges
- China 5G Cloud Service Price Trends
- China 5G Cloud Service Porter's Five Forces
- China 5G Cloud Service Industry Life Cycle
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Network Slicing for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Edge Cloud Services for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Private 5G Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Virtual RAN for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Cloud Model for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By IaaS for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By PaaS for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By SaaS for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Custom Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Deployment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Public Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Hybrid Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Private Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Community Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Telecom Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Enterprise Customers for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Industrial Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Network Infrastructure Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Cloud Service Market Revenues & Volume By Specialty Stores for the Period 2022 - 2032F
- China 5G Cloud Service Import Export Trade Statistics
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Cloud Model
- Market Opportunity Assessment By Deployment Type
- Market Opportunity Assessment By End User
- Market Opportunity Assessment By Distribution Channel
- China 5G Cloud Service Top Companies Market Share
- China 5G Cloud Service Competitive Benchmarking By Technical and Operational Parameters
- China 5G Cloud Service Company Profiles
- China 5G Cloud Service Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Service Type
- Network Slicing
- Edge Cloud Services
- Private 5G Cloud
- Virtual RAN
By Cloud Model
- IaaS
- PaaS
- SaaS
- Custom Cloud
By Deployment Type
- Public Cloud
- Hybrid Cloud
- Private Cloud
- Community Cloud
By End User
- Telecom Providers
- Enterprise Customers
- Industrial Plants
- Network Infrastructure Firms
By Distribution Channel
- Direct Sales
- Online Platforms
- Industrial Suppliers
- Specialty Stores































