China 5G Infrastructure Components Market Size & Growth Rate
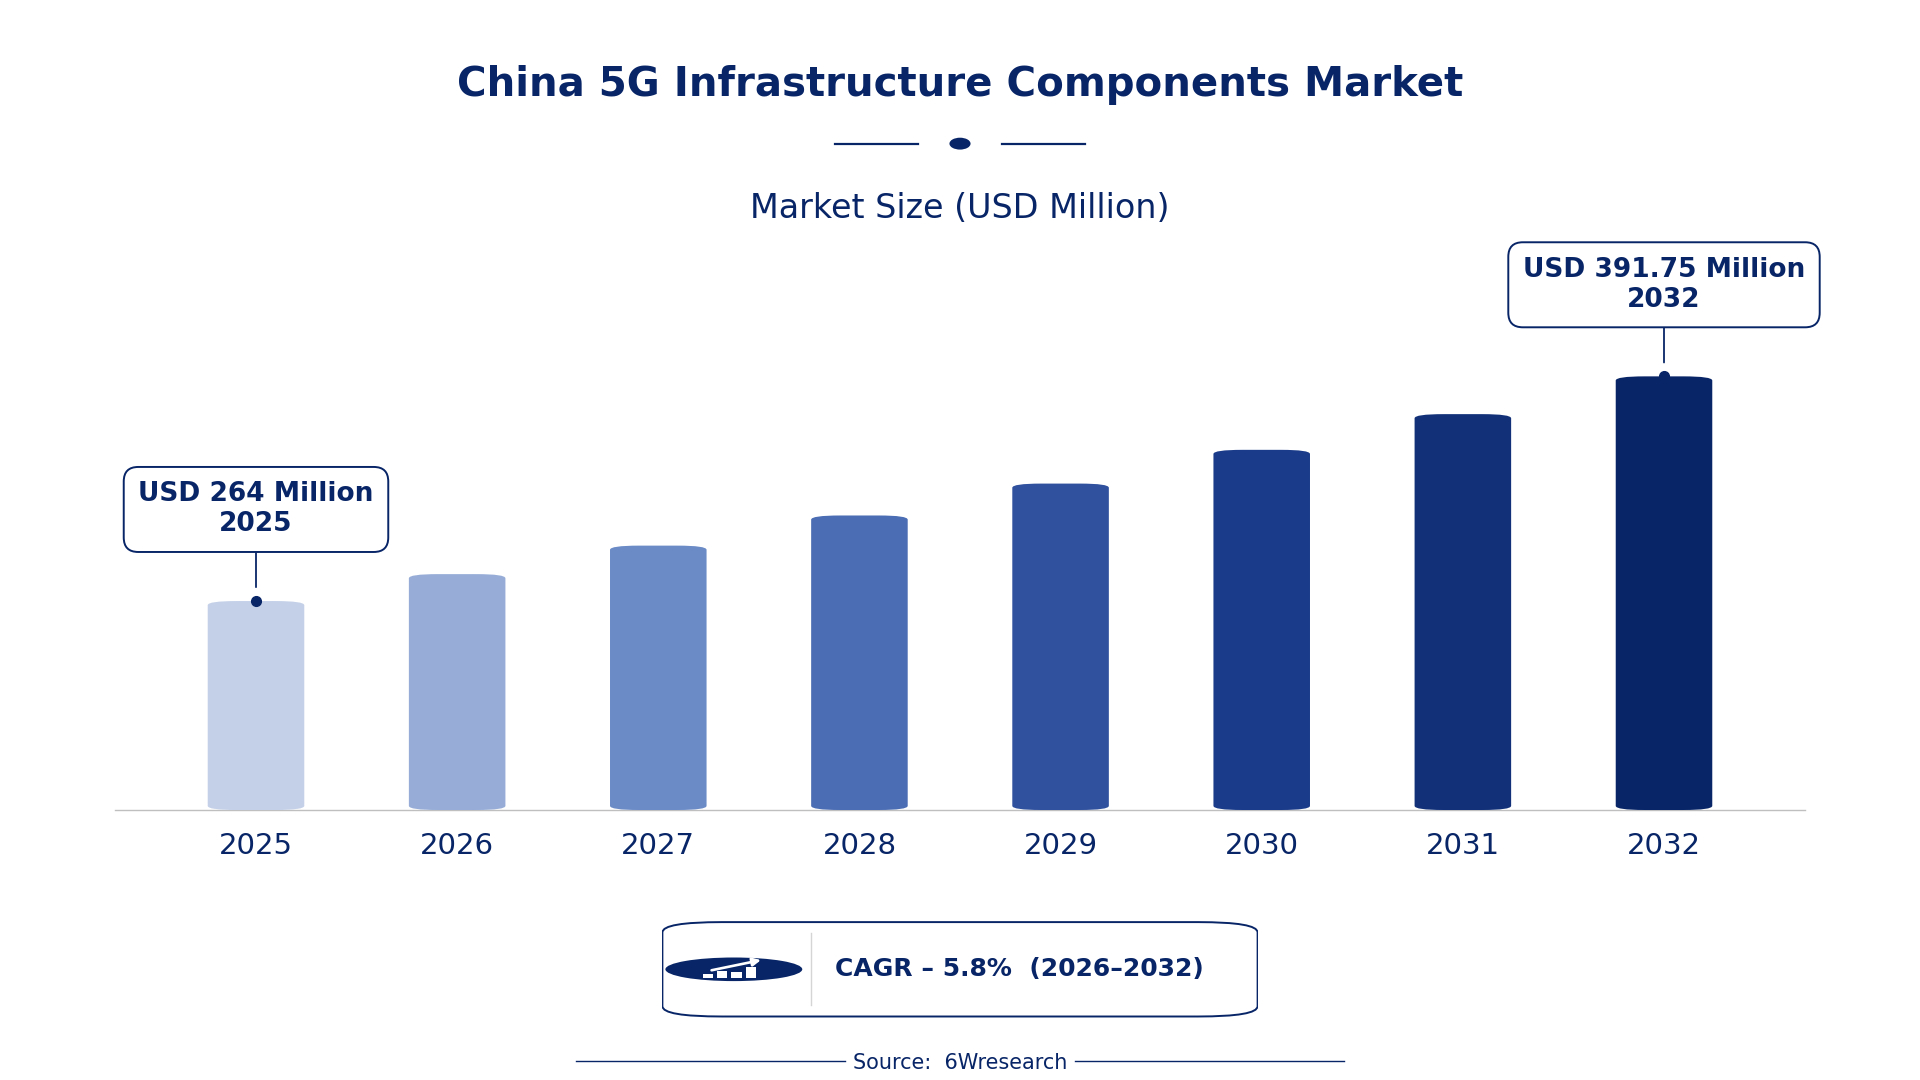
According to 6Wresearch internal database and industry insights, the China 5G Infrastructure Components Market was valued at USD 264.0 million in 2025 and is projected to reach USD 391.75 million by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China 5G Infrastructure Components Market Highlights
| Report Metric | Details |
| Report Name | China 5G Infrastructure Components Market |
| Market Size 2025 | USD 264.0 million |
| Market Size 2032 | USD 391.75 million |
| Absolute Growth 2025–2032 | USD 127.75 million |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 8.0% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Antennas (49% share) |
| Leading Material/Tech, 2025 | MIMO Technology (37% share) |
| Leading Application, 2025 | Base Stations (39% share) |
| Leading Distribution Channel, 2025 | OEMs (41% share) |
| Leading End User, 2025 | Mobile Network Operators (42% share) |
| Fastest-Growing Component Type | Optical Fiber Cables (7.9% CAGR) |
| Fastest-Growing Application | Backhaul Connectivity (7.1% CAGR) |
| Fastest-Growing Distribution Channel | Industrial Suppliers (7.6% CAGR) |
| Fastest-Growing End User | Data Centers (8.0% CAGR) |
| Growing Sector | telecommunications |
| Key End Users | Mobile Network Operators, Telecom Companies, Data Centers |
China 5G Infrastructure Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
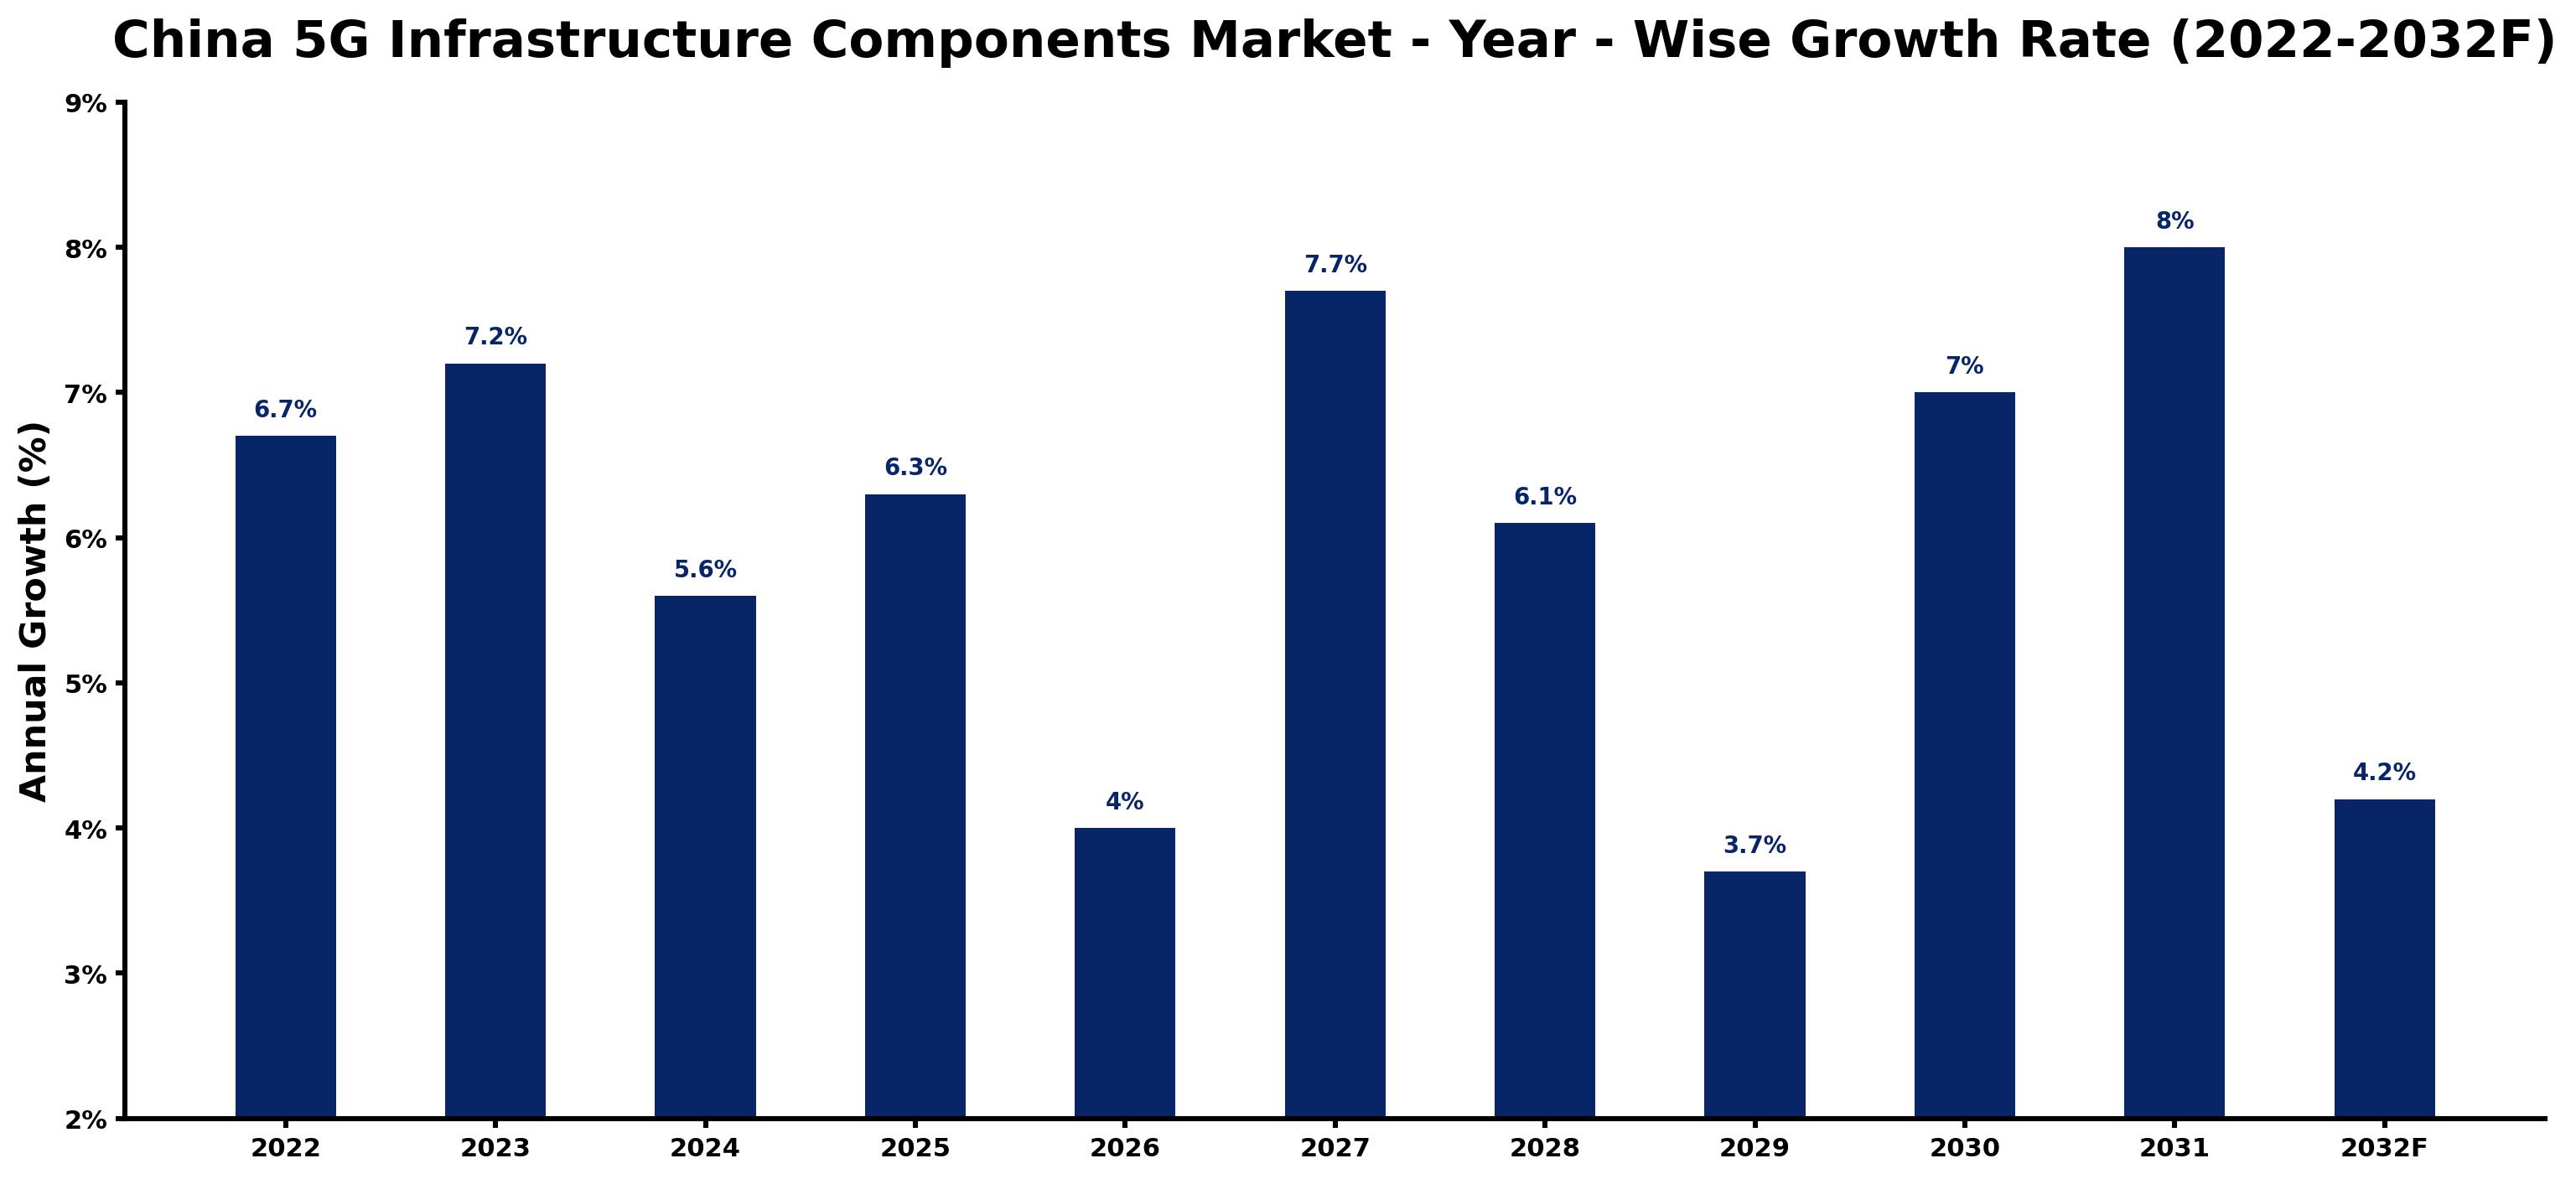
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.7 | The market experienced solid growth due to ongoing infrastructure investments. |
| 2023 | 7.2 | Demand surged as 5G coverage expanded to over 1 billion people. |
| 2024 | 5.6 | Growth slowed as the market adjusted to previous rapid expansions. |
| 2025 | 6.3 | Increased installations of base stations drove faster growth again. |
| 2026 | 4.0 | A slowdown occurred as the market stabilised after previous peaks. |
| 2027 | 7.7 | Demand rose significantly due to heightened investments in rural areas. |
| 2028 | 6.1 | Growth moderated as the market adjusted to new standards and technologies. |
| 2029 | 3.7 | Continued investments led to slower growth as the market matured. |
| 2030 | 7.0 | A resurgence in demand was noted as new applications emerged. |
| 2031 | 8.0 | The market peaked with strong investments and heightened competition. |
| 2032 | 4.2 | Growth slowed as the market began to stabilise after rapid expansions. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China 5G Infrastructure Components Market Synopsis
5G Infrastructure Components in China are crucial technologies enabling high-speed wireless communication. These components, including MIMO technology and optical fiber cables, support mobile networks and improve connectivity. The China 5G Infrastructure Components Market is expanding due to substantial investments from mobile network operators and telecom companies, driven by the '14th Five-Year Plan' which focuses on network expansion across various industries. As of 2023, over 400 million users are benefiting from these advancements, further increasing demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Expansion of mobile networks and infrastructure investments | Driver | High | Base Stations |
| Increased demand for high-speed data transfer solutions | Driver | High | Optical Fiber Cables |
| Growing need for connectivity in rural areas | Opportunity | High | Power Units |
| Investment in advanced technologies for network enhancement | Opportunity | Medium | MIMO Technology |
| High costs associated with infrastructure deployment | Restraint | High | Enclosures & Cabinets |
| Regulatory challenges in standardisation and compliance | Restraint | Medium | Antennas |
| Supply chain disruptions affecting component availability | Challenge | High | Fiber Optics |
| Technological advancements requiring constant upgrades | Challenge | Medium | Cell Towers |
Evaluation of Drivers in China 5G Infrastructure Components Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Expansion of mobile networks in urban and rural areas | Base Stations | In 2022, approximately 1.4 million 5G base stations were installed, increasing demand for components. |
| Rising user base of 5G technology | Optical Fiber Cables | As of 2023, there are over 400 million 5G users, driving the need for high-speed data transfer. |
| Government initiatives promoting 5G applications | MIMO Technology | The '5G Application Action Plan' aims to promote 5G applications across various sectors. |
| Increased investment in telecom infrastructure | Power Units | China's telecom sector is expected to invest over 1 trillion yuan in 5G by 2025. |
| National standards enhancing interoperability | Antennas | The Standardization Administration of China updated national standards in 2023 to ensure quality. |
Market growth in China for 5G Infrastructure Components rests on rising end-use demand, expanding capacity, and substantial investments in infrastructure. The installation of approximately 1.4 million 5G base stations in 2022 has increased the need for various components. With over 400 million users in 2023, mobile network operators are investing heavily in optical fiber cables to improve data transfer speeds. The expected investment of over 1 trillion yuan by 2025 will support the expansion of telecom infrastructure. The '5G Application Action Plan' promotes advanced technologies, further driving demand for components across the industry.
Evaluation of Restraints in China 5G Infrastructure Components Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with infrastructure deployment | Enclosures & Cabinets | Deployment costs can exceed millions, limiting investment in new infrastructure projects. |
| Regulatory challenges in standardisation and compliance | Antennas | Compliance with updated standards can delay project timelines and increase costs for telecom companies. |
| Supply chain disruptions affecting component availability | Fiber Optics | Global supply chain issues have led to shortages, impacting production schedules for 5G components. |
| Technological advancements requiring constant upgrades | Cell Towers | Rapid technology changes necessitate frequent updates, increasing operational costs for network operators. |
| Limited skilled workforce for installation and maintenance | Power Units | A shortage of trained technicians can delay project execution and increase costs for service providers. |
China 5G Infrastructure Components Market Challenges
China's 5G Infrastructure Components market faces several challenges, starting with buyer resistance to high costs. The rapid expansion of 5G networks has led to rising prices for essential components, potentially delaying project timelines for telecom companies. Technology integration remains a hurdle; outdated systems can impede the deployment of advanced 5G features, resulting in inefficiencies for network operators. Workforce skills shortages also present a challenge, as the demand for trained technicians exceeds supply, leading to project delays and higher operational costs for service providers. Compliance with national standards can complicate the rollout of new infrastructure, affecting the overall pace of network expansion for telecom companies.
Trends in the China 5G Infrastructure Components Market
Buyers and suppliers in the China 5G Infrastructure Components Market are adjusting to the following trends.
- Focus on Rural Connectivity Improvements: China is prioritising rural 5G connectivity, with funding initiatives from the National Development and Reform Commission. In 2022, significant investments were made to enhance infrastructure, benefiting underserved communities and increasing access to telecommunications.
- Transition to MIMO Technology Dominance: MIMO Technology has become the leading solution for enhancing network capacity, supported by the Ministry of Science and Technology's '5G+ Industrial Internet' initiative launched in 2023. This shift is vital for meeting increasing data demands and improving service quality.
- Emergence of Backhaul Connectivity Solutions: Backhaul Connectivity is gaining importance as the fastest-growing application segment, with a CAGR of 7.1% projected through 2032. This trend is driven by the need for efficient data transfer between base stations and core networks, enhancing overall network performance.
- Focus on Standardisation and Quality Assurance: The Standardization Administration of China updated 5G technology standards in 2023, ensuring interoperability and quality across networks. This shift enhances consumer trust and encourages investment in infrastructure, benefiting both producers and buyers.
Investment Opportunities in the China 5G Infrastructure Components Market
Several openings in the China 5G Infrastructure Components Market merit attention from investors.
- Investment in Rural 5G Infrastructure: With over 400 million users as of 2023, there is a strong opportunity to invest in rural 5G infrastructure. The National Development and Reform Commission's funding initiatives support this expansion, making it an attractive market for suppliers to enter.
- Supply of MIMO Technology Components: MIMO Technology is projected to grow at a CAGR of 8.2% through 2032, driven by rising demand for high-capacity networks. Suppliers can enter this market through partnerships with mobile network operators to provide essential components.
- Development of Optical Fiber Cable Solutions: China's optical fiber cable production reached 400 million kilometers in 2022, indicating a strong demand for advanced connectivity solutions. Suppliers can target telecom companies looking to enhance their network capabilities through innovative products.
- Expansion of Base Station Installations: As the market for base stations grows, driven by the installation of 1.4 million units in 2022, suppliers can capitalise by providing essential components. Collaborating with OEMs can facilitate market entry and strengthen supplier relationships.
Government Initiatives in the China 5G Infrastructure Components Market
In 2021, the State Council launched the 'New Infrastructure Plan' to accelerate 5G network deployment, improving connectivity in urban and rural areas. This initiative builds on earlier measures such as the '5G Application Action Plan' introduced by the Ministry of Industry and Information Technology (MIIT) in 2021. These policies are expected to enhance network coverage and performance significantly, benefiting both producers and consumers in the 5G infrastructure market. The '14th Five-Year Plan' further emphasises the expansion of 5G networks across various industries, targeting increased investment and application development.
The Ministry of Industry and Information Technology (MIIT) oversees the approval of 5G applications and technologies. Additionally, the National Development and Reform Commission (NDRC) funds rural 5G deployment initiatives, facilitating access to telecommunications in underserved areas. The China Communications Industry Association (CCIA) plays a role in supporting the development of 5G technologies. These agencies are essential in ensuring that 5G infrastructure meets national standards and addresses regional connectivity needs, enhancing the overall quality and reliability of 5G services across China.
Future Insight of the China 5G Infrastructure Components Market
The outlook for the 5G Infrastructure Components market in China through 2032 is promising, driven by several key factors. The government's '14th Five-Year Plan' will prioritise 5G expansion across industries, leading to increased demand for components. Telecom investments are projected to exceed 1 trillion yuan by 2025, creating growth opportunities for suppliers. The launch of the '5G+ Industrial Internet' initiative will enhance integration across sectors, fostering new applications and use cases. Additionally, the production of optical fiber cables, reaching 400 million kilometers in 2022, ensures a steady supply for ongoing infrastructure projects.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Component Type – Antennas Dominated, Optical Fiber Cables Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, the largest component type category in 2025 was Antennas, with a 49% share of total revenue. Antennas hold the largest market share as they are crucial for effective signal transmission in 5G networks. With a vast 5G network covering over 1 billion people in China, the demand for reliable antennas is essential for ensuring seamless connectivity. The quickest growth will come from Optical Fiber Cables, forecast to expand at a CAGR of 7.9% between 2026 and 2032. Optical Fiber Cables are experiencing rapid growth due to their critical role in facilitating high-speed data transfer, especially following the installation of approximately 1.4 million 5G base stations in 2022. This trend underscores the increasing reliance on optical fiber as 5G applications proliferate. Suppliers should focus on enhancing their optical fiber cable offerings to capitalise on the growing demand in the market.
By Material/Tech – MIMO Technology Dominated and Is Expected to Record the Fastest Growth
In 2025, MIMO Technology led the material/tech split with a 37% share. MIMO Technology commands the largest market share because it significantly enhances capacity and coverage for 5G networks. The substantial investments in 5G infrastructure, projected to exceed 1 trillion yuan by 2025, further solidify its dominant position. MIMO Technology is also forecast to expand faster than any other category, at a CAGR of 8.2% over 2026–2032. MIMO Technology is also the fastest-growing segment, as its capabilities are essential for meeting the escalating data demands of 5G users. The simultaneous increase in capacity and coverage ensures that MIMO Technology will continue to strengthen its lead in the market. Suppliers should prioritise MIMO Technology in their product strategies to remain aligned with market trends and user needs.
By Application – Base Stations Dominated, Backhaul Connectivity Expected to Grow Fastest
Base Stations accounted for a 39% market share by application in 2025. Base Stations hold the largest market share as they are fundamental to the 5G network infrastructure, enabling communication over extensive areas. The growth of 5G users, which has surpassed 400 million, highlights the urgent need for additional base stations to support this expansion. Backhaul Connectivity is projected to grow fastest, at a CAGR of 7.1% during 2026–2032. Backhaul Connectivity is the fastest-growing application, as it connects base stations to core networks, essential for sustaining high data transfer speeds. The increasing complexity of network demands drives the necessity for improved backhaul solutions. Buyers should invest in advanced backhaul connectivity solutions to ensure optimal performance of their networks.
By Distribution Channel – OEMs Dominated, Industrial Suppliers Expected to Grow Fastest
OEMs took a 41% share of distribution channel in 2025, more than any other category. OEMs command the largest market share as they are the primary manufacturers of essential components for 5G infrastructure. Their established relationships with telecom companies ensure a steady demand for their products. Industrial Suppliers are set to record the highest CAGR in this split, 7.6% over 2026–2032. Industrial Suppliers are the fastest-growing distribution channel, as they provide a variety of components needed for 5G deployment. The diversification of supply chains in response to market needs is fuelling this growth. Suppliers should explore partnerships with industrial suppliers to expand their reach in the 5G infrastructure market.
By End User – Mobile Network Operators Dominated, Data Centers Expected to Grow Fastest
With a 42% revenue share in 2025, Mobile Network Operators was the largest end user category. Mobile Network Operators represent the largest share as they are the primary end users of 5G infrastructure components, significantly impacting demand for network expansion. Their extensive investments in infrastructure underscore their critical role within the telecommunications sector. The quickest growth will come from Data Centers, forecast to expand at a CAGR of 8.0% between 2026 and 2032. Data Centers are the fastest-growing end user segment, driven by the increasing need for robust connectivity to manage the rising data loads associated with 5G applications. The growth in cloud services and data processing requirements is propelling this segment forward. Suppliers must tailor their offerings to address the specific needs of data centers to capture this expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China 5G Infrastructure Components Market Outlook
- Market Size of China 5G Infrastructure Components Market, 2025
- Forecast of China 5G Infrastructure Components Market, 2032
- Historical Data and Forecast of China 5G Infrastructure Components Revenues & Volume for the Period 2022 - 2032F
- China 5G Infrastructure Components Market Trend Evolution
- China 5G Infrastructure Components Market Drivers and Challenges
- China 5G Infrastructure Components Price Trends
- China 5G Infrastructure Components Porter's Five Forces
- China 5G Infrastructure Components Industry Life Cycle
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Antennas for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Optical Fiber Cables for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Power Units for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Enclosures & Cabinets for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Material/Tech for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By MIMO Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Fiber Optics for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By High Efficiency for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Weatherproof Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Base Stations for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Backhaul Connectivity for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Cell Towers for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Outdoor Deployment for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Specialty Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Mobile Network Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Data Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Telecom Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China 5G Infrastructure Components Market Revenues & Volume By Network Infrastructure Firms for the Period 2022 - 2032F
- China 5G Infrastructure Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Material/Tech
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China 5G Infrastructure Components Top Companies Market Share
- China 5G Infrastructure Components Competitive Benchmarking By Technical and Operational Parameters
- China 5G Infrastructure Components Company Profiles
- China 5G Infrastructure Components Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Component Type
- Antennas
- Optical Fiber Cables
- Power Units
- Enclosures & Cabinets
By Material/Tech
- MIMO Technology
- Fiber Optics
- High Efficiency
- Weatherproof Coating
By Application
- Base Stations
- Backhaul Connectivity
- Cell Towers
- Outdoor Deployment
By Distribution Channel
- OEMs
- Industrial Suppliers
- Direct Sales
- Specialty Distributors
By End User
- Mobile Network Operators
- Data Centers
- Telecom Companies
- Network Infrastructure Firms































