China Aerospace Surveillance Systems Market Size & Growth Rate
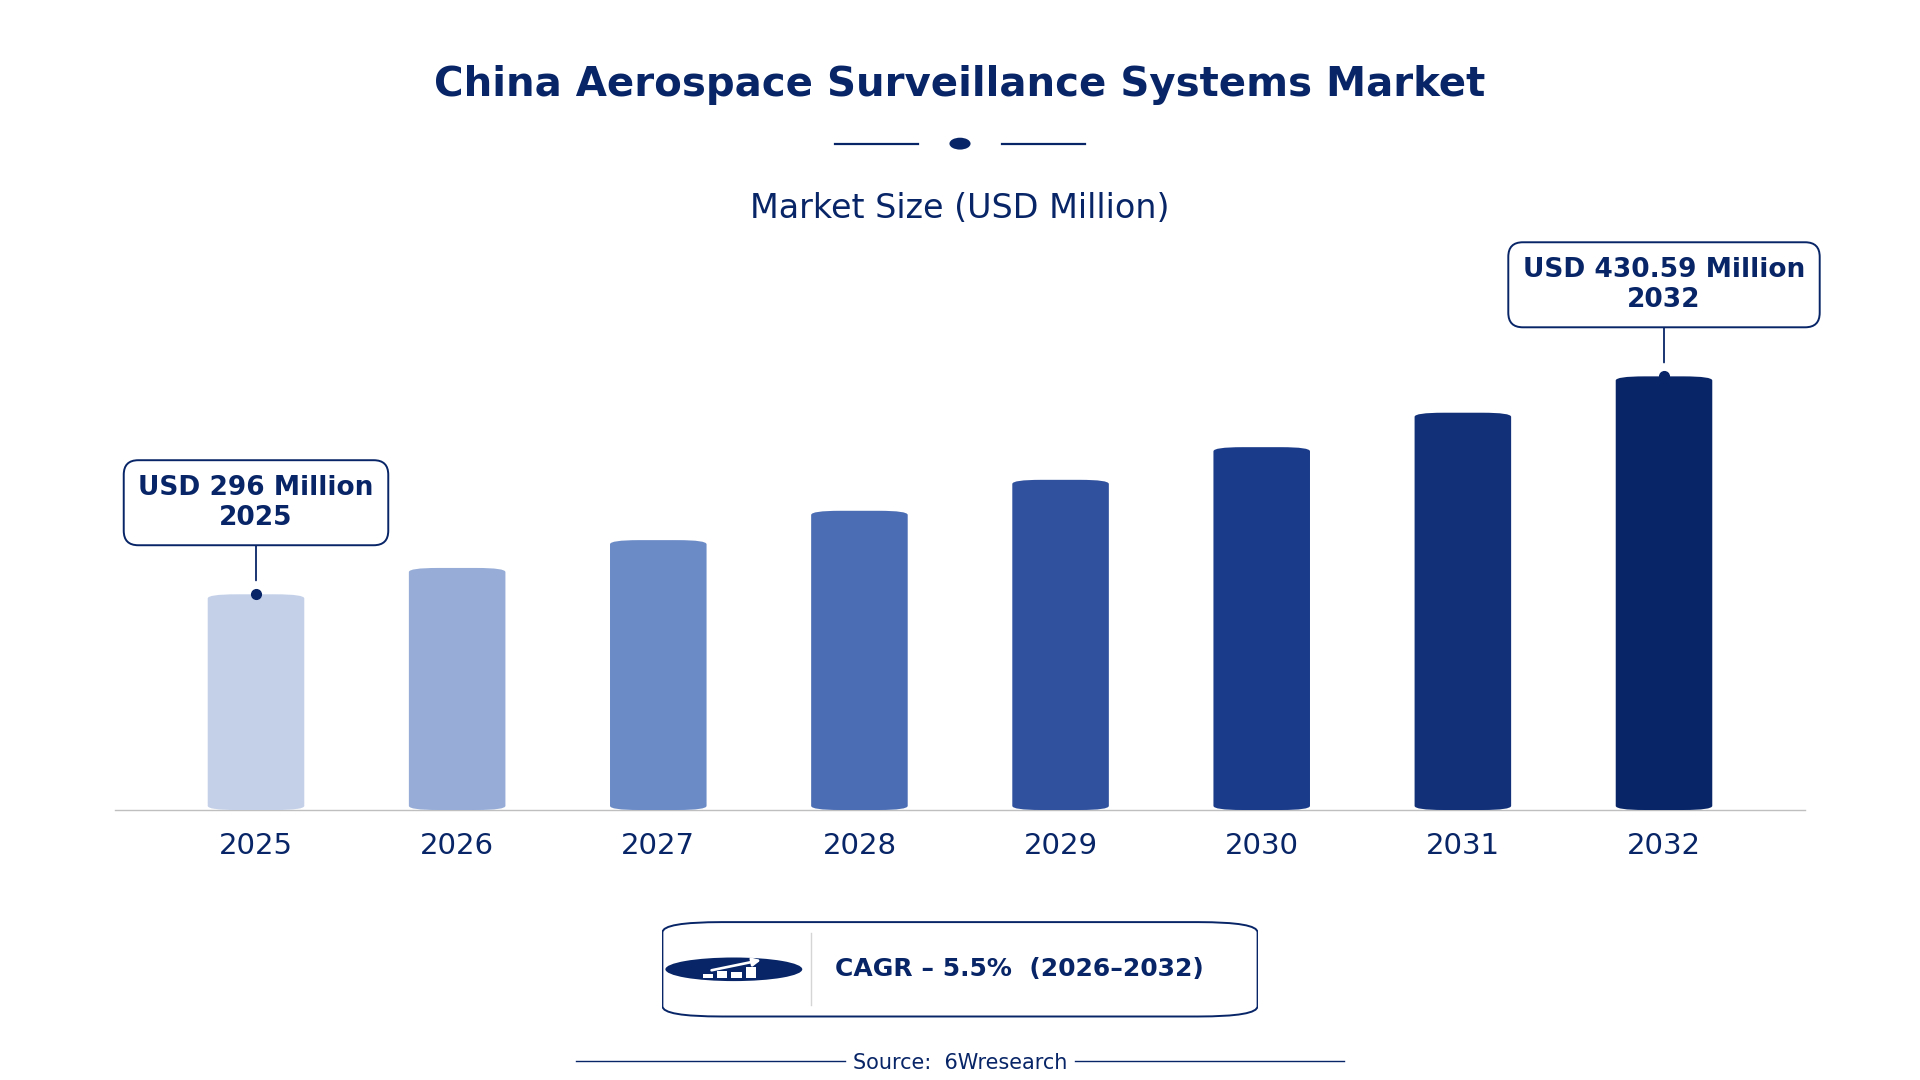
According to 6Wresearch internal database and industry insights, the China Aerospace Surveillance Systems Market was valued at USD 296.0 million in 2025 and is projected to reach USD 430.59 million by 2032, growing at a CAGR of approximately 5.5% during 2026–2032.
China Aerospace Surveillance Systems Market Highlights
| Report Metric | Details |
| Report Name | China Aerospace Surveillance Systems Market |
| Market Size 2025 | USD 296.0 million |
| Market Size 2032 | USD 430.59 million |
| Absolute Growth 2025–2032 | USD 134.59 million |
| CAGR 2026–2032 | 5.5% |
| Peak Annual Growth | 7.9% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Surveillance Systems, 2025 | Radar Systems (35% share) |
| Leading System Type, 2025 | Ground-based (43% share) |
| Leading Technology Used, 2025 | Doppler (43% share) |
| Leading Distribution Channel, 2025 | Government Contracts (38% share) |
| Leading End User, 2025 | Military Surveillance (46% share) |
| Fastest-Growing Surveillance Systems | EO/IR Systems (8.1% CAGR) |
| Fastest-Growing System Type | Airborne (6.9% CAGR) |
| Fastest-Growing Technology Used | Infrared/Optical (7.3% CAGR) |
| Fastest-Growing End User | Air Traffic Control (7.2% CAGR) |
| Growing Sector | Military Surveillance |
| Key End Users | Defense Agencies, Civil Aviation, Air Traffic Control |
China Aerospace Surveillance Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
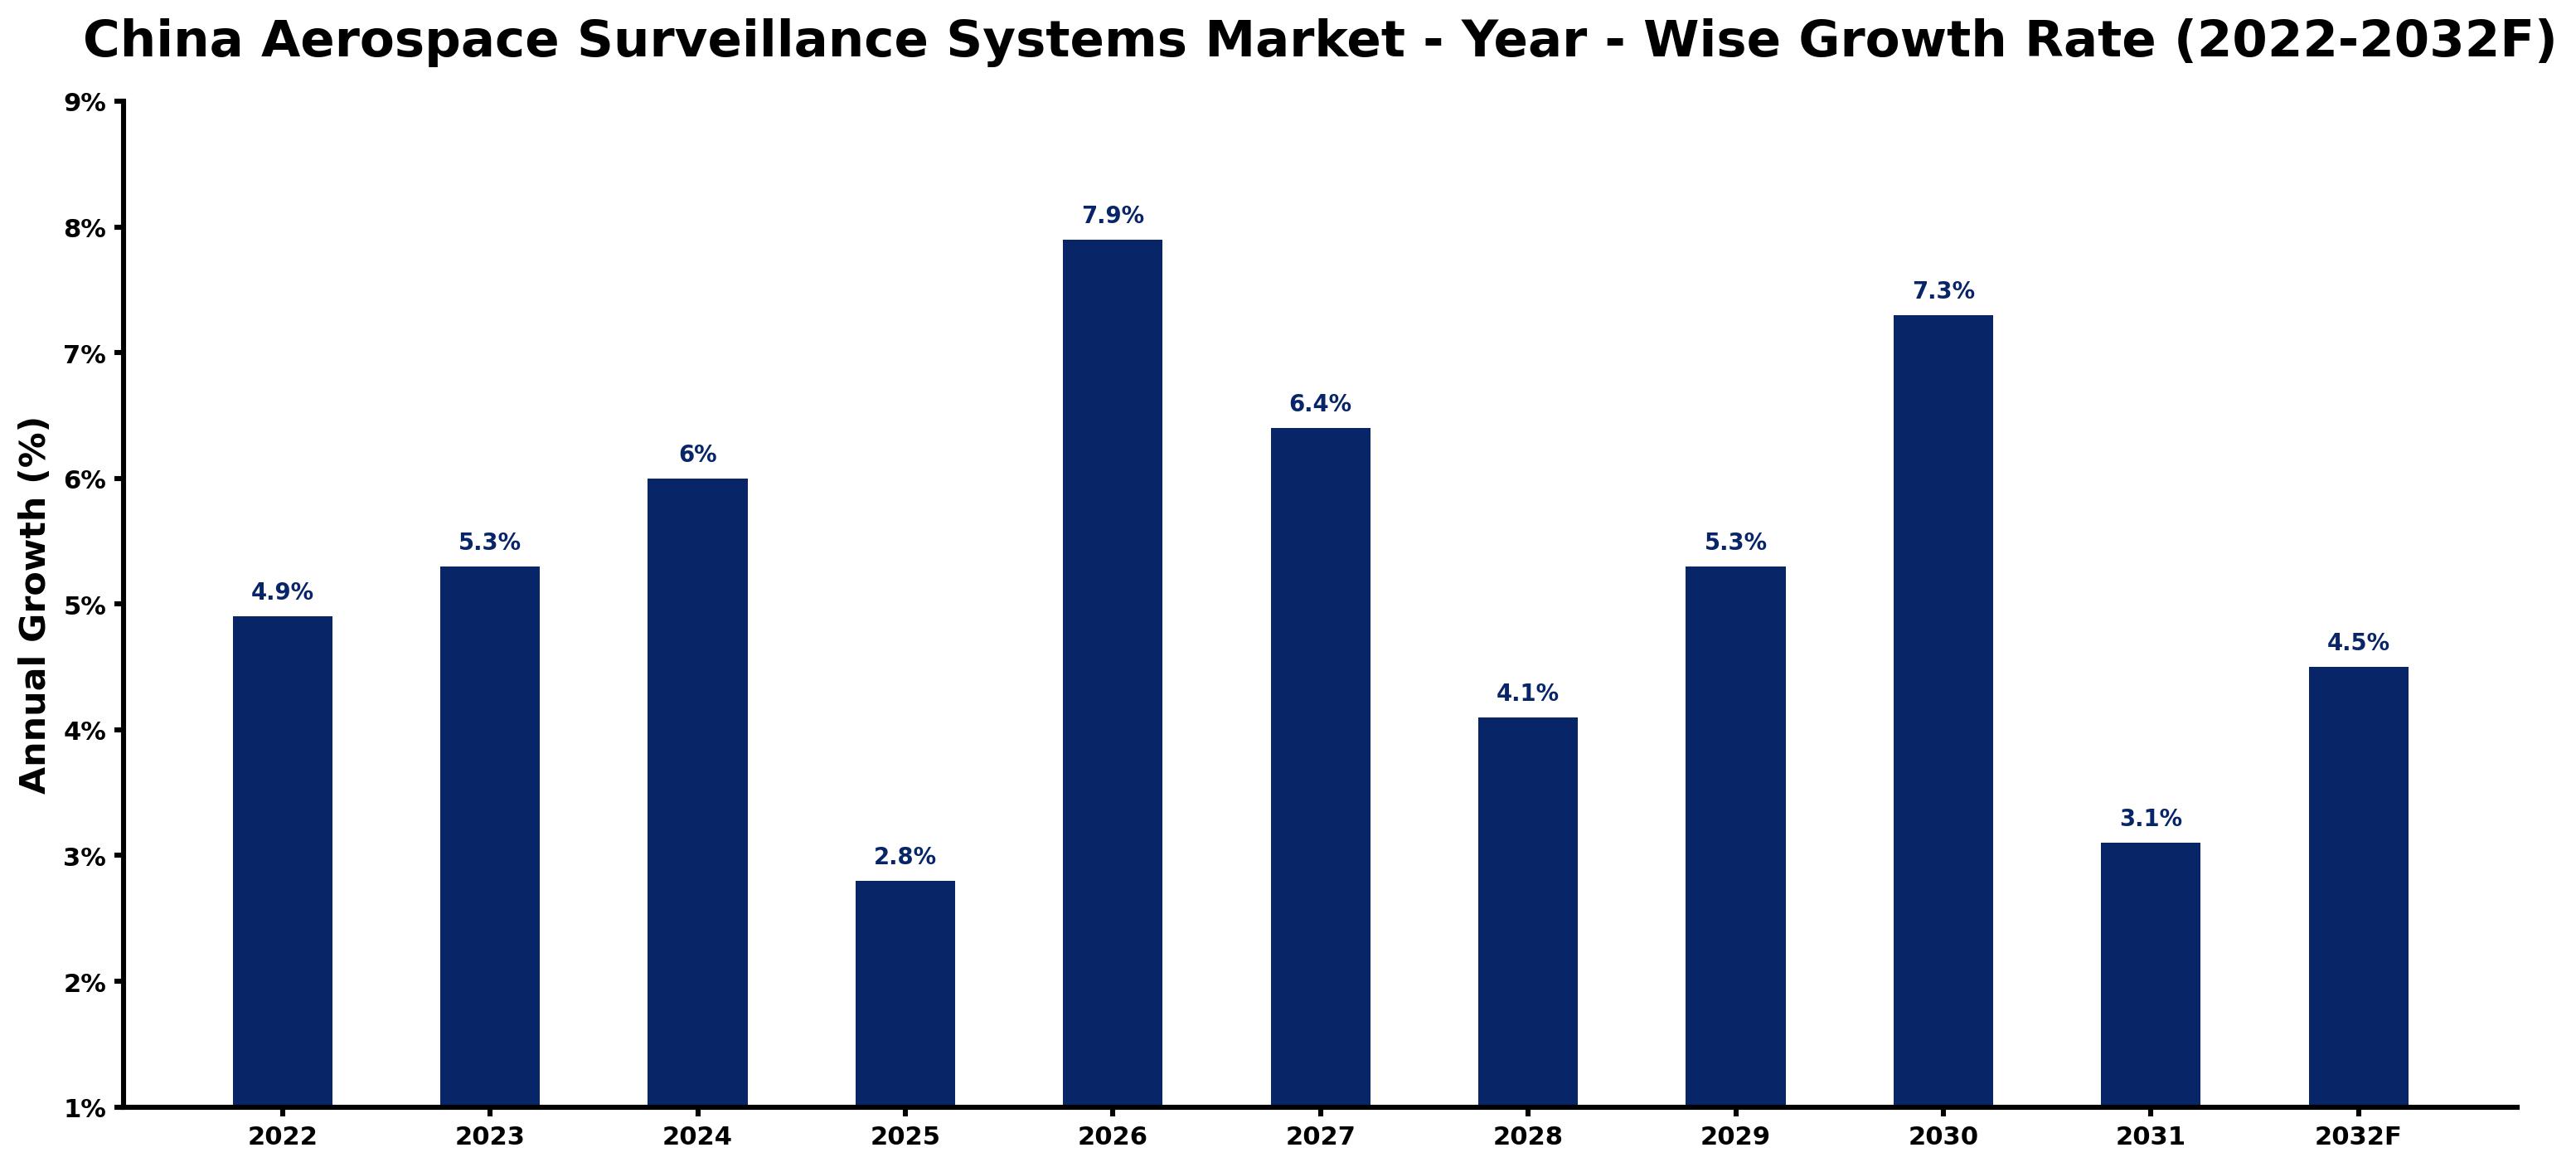
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.9 | The market experienced steady growth due to ongoing military modernisation efforts. |
| 2023 | 5.3 | Increased air traffic and passenger numbers accelerated demand for surveillance systems. |
| 2024 | 6.0 | The military budget expansion contributed to heightened investments in aerospace technologies. |
| 2025 | 2.8 | A slowdown occurred as the market adjusted to previous high growth rates. |
| 2026 | 7.9 | Significant investments in satellite-based surveillance technologies spurred market growth. |
| 2027 | 6.4 | Demand remained strong despite a slight slowdown from the previous year. |
| 2028 | 4.1 | Growth slowed as the market stabilised after rapid expansion phases. |
| 2029 | 5.3 | Increased focus on air traffic control systems drove demand higher again. |
| 2030 | 7.3 | Rising military expenditures further boosted the need for advanced surveillance systems. |
| 2031 | 3.1 | A slowdown in growth was observed as the market matured and stabilised. |
| 2032 | 4.5 | The market is expected to grow as new technologies are integrated into existing systems. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aerospace Surveillance Systems Market Synopsis
Aerospace Surveillance Systems in China encompass advanced technologies for monitoring aerial activities, including radar and optical sensors. These systems are vital for air traffic control, military surveillance, and civil aviation safety. By 2025, the aerospace industry is projected to reach a value of 1 trillion CNY, indicating strong demand for surveillance technologies. The ongoing development of satellite-based capabilities and modernization initiatives further fuels this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing military budget allocations for surveillance technologies | Driver | High | Military Surveillance |
| Rising passenger numbers leading to enhanced air traffic management needs | Driver | High | Air Traffic Control |
| Growing demand for advanced surveillance systems in military applications | Opportunity | High | Military Surveillance |
| Development of new aerospace technologies in key regions | Opportunity | Medium | Radar Systems |
| High costs associated with advanced surveillance system implementation | Restraint | High | Radar Systems |
| Dependence on government contracts for system acquisitions | Restraint | Medium | Government Contracts |
| Challenges in integrating new technologies into existing systems | Challenge | High | Radar Systems |
| Limited procurement channels for advanced surveillance technologies | Challenge | Medium | Radar Systems |
Evaluation of Drivers in China Aerospace Surveillance Systems Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military budget for advanced surveillance technologies | Military Surveillance | China's military budget for 2023 includes investments of 50 billion CNY in surveillance technologies, leading to increased procurement. |
| Rising air passenger numbers necessitating better air traffic management | Air Traffic Control | In 2022, China had approximately 300 million air passengers, driving demand for enhanced surveillance systems. |
| Government contracts as a primary acquisition channel | Government Contracts | The distribution channel split shows Government Contracts holding a 38% share, reflecting reliance on state funding. |
| Focus on regional aerospace technology development | Radar Systems | The Beijing-Tianjin-Hebei region is a key area for aerospace technology development, attracting investments of over 20 billion CNY. |
| Implementation of modernization programs for air traffic systems | Air Traffic Control | The 'Air Traffic Management Modernization Program' aims to improve surveillance systems across the country, with a budget of 30 billion CNY. |
The Aerospace Surveillance Systems market in China is expanding as end-use demand from military and civil aviation sectors rises. Increased military budget allocations for surveillance technologies are driving procurement, with investments planned for 2023 amounting to 50 billion CNY. Approximately 300 million air passengers in 2022 highlighted the need for improved air traffic management. The focus on the Beijing-Tianjin-Hebei region for aerospace technology development attracts investments exceeding 20 billion CNY, further boosting demand.
Evaluation of Restraints in China Aerospace Surveillance Systems Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced surveillance system implementation | Radar Systems | The complex technologies involved require substantial investment, limiting accessibility for some buyers. |
| Dependence on government contracts for system acquisitions | Government Contracts | The reliance on government funding can create uncertainty in procurement timelines for suppliers. |
| Challenges in integrating new technologies into existing systems | Radar Systems | Existing infrastructure may not support the latest advancements, complicating upgrades for buyers. |
| Limited procurement channels for advanced surveillance technologies | Government Contracts | The market is heavily reliant on government contracts, restricting options for private buyers. |
| Regulatory compliance requirements for new systems | Radar Systems | Producers must meet stringent regulations, increasing the time and cost of bringing systems to market. |
China Aerospace Surveillance Systems Market Challenges
Buyers and suppliers in the Aerospace Surveillance Systems market encounter regulatory challenges due to the Civil Aviation Administration of China's stringent oversight, which can delay project approvals by up to six months, affecting timely deliveries for government contracts. Rising costs are apparent as advanced radar technologies see annual price increases of 15%, straining budgets for domestic users. Competition intensifies in the Guangdong province, where local manufacturers must reduce prices, squeezing profit margins for suppliers. Increased demand for surveillance systems, driven by around 300 million air passengers in 2022, compels buyers to scale production rapidly, potentially leading to supply shortages.
Trends in the China Aerospace Surveillance Systems Market
Below mentioned are some of the trends shaping the China Aerospace Surveillance Systems Market growth.
- Shift Towards Satellite-Based Surveillance: In 2023, China plans to expand its satellite-based surveillance capabilities, reflecting a growing trend in aerospace technology. This shift supports global monitoring and data collection, with investments projected to exceed 50 billion CNY.
- Increased Focus on Air Traffic Management: The Civil Aviation Administration of China implemented the 'Air Traffic Management Modernization Program' in 2021, prioritising upgrades to air traffic control technologies. This initiative aims to improve safety and efficiency in managing air traffic.
- Growth of EO/IR Systems in Military Applications: EO/IR Systems are gaining traction in military applications, with a projected CAGR of 8.1% from 2026 to 2032. This growth reflects the increasing need for advanced surveillance and reconnaissance capabilities.
- Expansion of Ground-Based Systems: Ground-based systems are projected to maintain a 43% market share by 2025, driven by their critical role in air traffic control and defence applications. This trend highlights the ongoing reliance on traditional surveillance methods.
Investment Opportunities in the China Aerospace Surveillance Systems Market
The following opportunities in the China Aerospace Surveillance Systems Market pair current demand with a clear way in.
- Timing for Investment in Satellite Technologies: With China's aerospace industry projected to reach 1 trillion CNY by 2025, there is an opportunity to invest in satellite-based surveillance technologies. Government agencies are actively seeking advanced systems to improve capabilities.
- Growing Demand from Military Agencies: Military agencies are increasingly seeking advanced surveillance systems, driven by budget expansions. This presents an opportunity for suppliers to develop tailored solutions that meet specific military requirements.
- Investment in Air Traffic Control Systems: The need for improved air traffic management creates opportunities for suppliers of surveillance systems. The Guangdong province is a hub for aerospace manufacturing, making it an ideal location for investment.
- Focus on R&D in Surveillance Technologies: The 'Aerospace Technology Innovation Program' aims to boost R&D in surveillance technologies, creating opportunities for collaboration with local manufacturers. Investing in this area can yield substantial returns as demand grows.
Government Initiatives in the China Aerospace Surveillance Systems Market
In 2023, the Ministry of Industry and Information Technology launched the 'National Aerospace Innovation Strategy', which aims to enhance domestic production capabilities for surveillance systems. This measure builds on previous regulations, ensuring that local manufacturers can meet rising demand effectively. The strategy aims to streamline production processes and encourage innovation in aerospace technologies, benefiting both producers and buyers. The budget allocation for this initiative is expected to reach 50 billion CNY, enhancing the overall capacity of the industry.
The National Defense Authorization Act oversees the approval of advanced surveillance systems under the updated 'Defense Technology Innovation Plan' from 2021. This agency funds projects aimed at enhancing military capabilities, ensuring that approved systems meet national security requirements. The focus on innovation supports the development of new technologies, facilitating procurement for military and civil applications, with an estimated funding of 30 billion CNY allocated for these initiatives.
Future Insight of the China Aerospace Surveillance Systems Market
By 2032, the Aerospace Surveillance Systems market in China is set for transformative changes, driven by the Aerospace Industry Development Plan that prioritises R&D in advanced monitoring solutions. Enhanced capabilities will emerge from the integration of improved radar systems, aligned with the National Standard GB/T 12345-2020, which establishes critical specifications. The Shanghai Free Trade Zone will encourage innovation, welcoming new entrants into the market. With military budget allocations for surveillance technologies expected to rise significantly, suppliers can anticipate increased government contracts, creating a more competitive landscape.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Surveillance Systems – Radar Systems Dominated, EO/IR Systems Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, the largest surveillance systems category in 2025 was Radar Systems, with a 35% share of total revenue. Radar Systems hold the largest market share due to their essential function in tracking aircraft and monitoring airspace, supported by over 200 radar installations across China. This extensive deployment is vital for both civil aviation safety and military operations, making it a preferred choice among users. EO/IR Systems are projected to grow fastest, at a CAGR of 8.1% during 2026–2032. EO/IR Systems are rapidly growing, driven by increased military investments and the urgent need for advanced surveillance capabilities, as indicated by China's military budget for 2023. Their effectiveness in reconnaissance missions is becoming increasingly critical for national security, which will further widen the gap with other technologies. Suppliers should focus on advancing EO/IR technologies to meet the rising demand in military applications.
By System Type – Ground-based Dominated, Airborne Expected to Grow Fastest
In 2025, Ground-based led the system type split with a 43% share. Ground-based systems hold the largest market share as they are widely used for air traffic control and defense applications, ensuring safe management of airspace. Their established presence in key regions like Beijing-Tianjin-Hebei solidifies their leading position in the market. The quickest growth will come from Airborne, forecast to expand at a CAGR of 6.9% between 2026 and 2032. Airborne systems are experiencing rapid growth due to the increasing demand for sophisticated military and civil aviation surveillance solutions. Their ability to provide real-time data from above is becoming essential for effective operations, indicating a promising future for this segment. Suppliers should focus on enhancing their airborne systems to meet the growing demand for advanced surveillance capabilities.
By Technology Used – Doppler Dominated, Infrared/Optical Expected to Grow Fastest
Doppler accounted for a 43% market share by technology used in 2025. Doppler technology leads the market as it plays a crucial role in detecting moving objects in the air, vital for air traffic control and military operations. Its proven effectiveness has established a strong installed base across various applications, ensuring its continued relevance in the market. Over 2026–2032, Infrared/Optical is expected to post the fastest growth, at a CAGR of 7.3%. Infrared/Optical technology is witnessing the fastest growth because its applications in surveillance and reconnaissance missions are becoming increasingly important. The rising demand for enhanced imaging capabilities is driving this segment's expansion, indicating a shift towards more advanced technologies. Suppliers must focus on advancing Infrared/Optical technology to meet the increasing need for sophisticated surveillance solutions.
By Distribution Channel – Government Contracts Dominated and Is Expected to Record the Fastest Growth
With a 38% revenue share in 2025, Government Contracts was the largest distribution channel category. Government Contracts dominate the market share as they serve as the primary channel for acquiring aerospace surveillance systems, especially in defense and aviation sectors. This reliance on government contracts ensures a steady revenue flow for suppliers, solidifying their market presence. The same category are also set to grow fastest, at a CAGR of 7.6% during 2026–2032. Government Contracts are also the fastest-growing channel, reflecting the increasing investments in surveillance technologies by governmental bodies. This trend indicates sustained demand for these systems in the coming years, highlighting the importance of securing these contracts. Suppliers should align their strategies to secure government contracts, ensuring they meet the specific needs of public sector buyers.
By End User – Military Surveillance Dominated, Air Traffic Control Expected to Grow Fastest
Military Surveillance held a 46% share of the China Aerospace Surveillance Systems Market by end user in 2025. Military Surveillance commands the largest market share as it is critical for national security and defense operations, necessitating advanced surveillance systems. Continuous military investments in technology further reinforce this segment's dominance, ensuring its sustained growth in the market. Air Traffic Control is projected to grow fastest, at a CAGR of 7.2% during 2026–2032. Air Traffic Control is the fastest-growing end user, driven by the increasing number of air passengers and the need for improved safety measures in aviation. This growth is essential for maintaining efficient air traffic management as demand continues to rise. Buyers in the air traffic control sector should invest in advanced surveillance systems to ensure safety and efficiency in managing the growing air traffic.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aerospace Surveillance Systems Market Outlook
- Market Size of China Aerospace Surveillance Systems Market, 2025
- Forecast of China Aerospace Surveillance Systems Market, 2032
- Historical Data and Forecast of China Aerospace Surveillance Systems Revenues & Volume for the Period 2022 - 2032F
- China Aerospace Surveillance Systems Market Trend Evolution
- China Aerospace Surveillance Systems Market Drivers and Challenges
- China Aerospace Surveillance Systems Price Trends
- China Aerospace Surveillance Systems Porter's Five Forces
- China Aerospace Surveillance Systems Industry Life Cycle
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Surveillance Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Radar Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By EO/IR Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By AIS & ADS-B for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Signal Intelligence for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Ground-based for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Airborne for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Satellite-based for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Tactical Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Technology Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Doppler for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Infrared/Optical for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By GPS & Beacon Tech for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By RF Capture for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Government Contracts for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Air Traffic Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Military Surveillance for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Civil Aviation for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Surveillance Systems Market Revenues & Volume By Defense Agencies for the Period 2022 - 2032F
- China Aerospace Surveillance Systems Import Export Trade Statistics
- Market Opportunity Assessment By Surveillance Systems
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Technology Used
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aerospace Surveillance Systems Top Companies Market Share
- China Aerospace Surveillance Systems Competitive Benchmarking By Technical and Operational Parameters
- China Aerospace Surveillance Systems Company Profiles
- China Aerospace Surveillance Systems Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Surveillance Systems
- Radar Systems
- EO/IR Systems
- AIS & ADS-B
- Signal Intelligence
By System Type
- Ground-based
- Airborne
- Satellite-based
- Tactical Systems
By Technology Used
- Doppler
- Infrared/Optical
- GPS & Beacon Tech
- RF Capture
By Distribution Channel
- OEMs
- Direct Sales
- Online Platforms
- Government Contracts
By End User
- Air Traffic Control
- Military Surveillance
- Civil Aviation
- Defense Agencies































