China Agri-Tech Software Market Size & Growth Rate
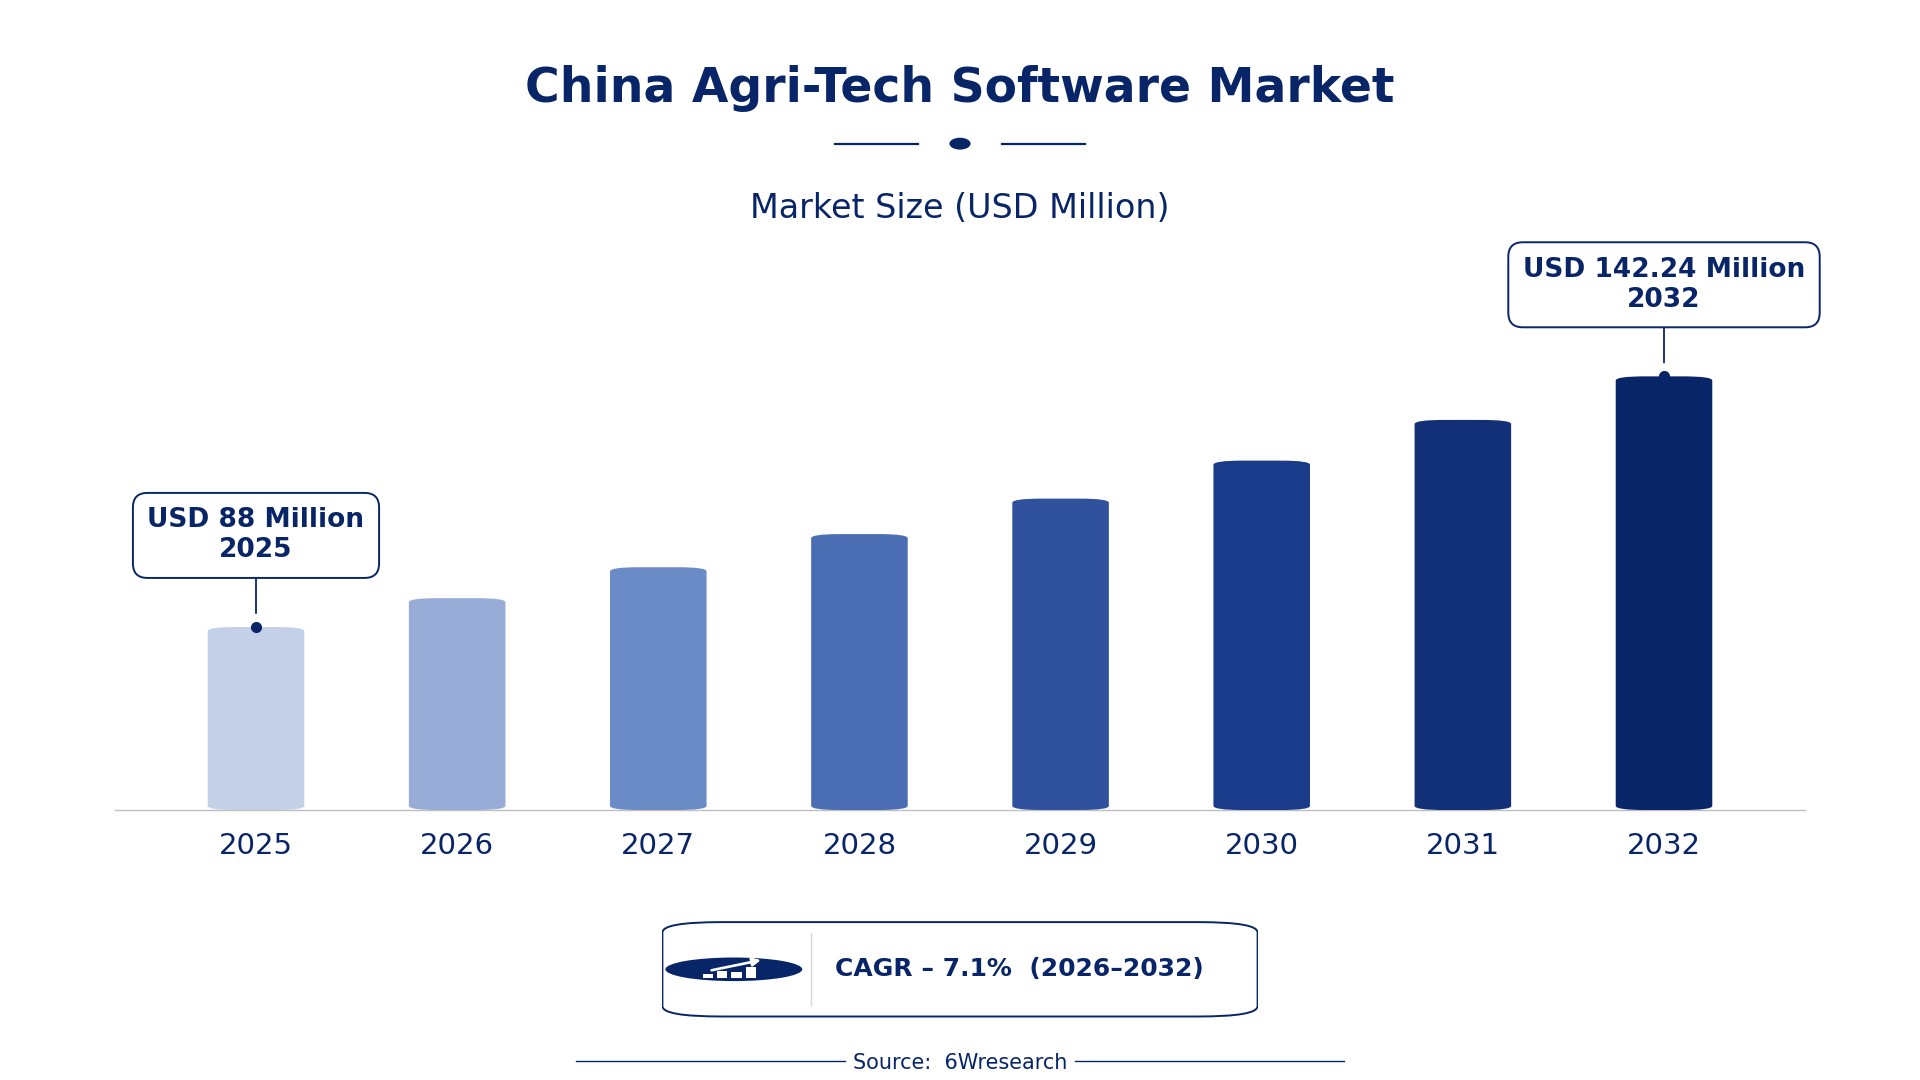
According to 6Wresearch internal database and industry insights, the China Agri-Tech Software Market was valued at USD 88.0 million in 2025 and is projected to reach USD 142.24 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China Agri-Tech Software Market Highlights
| Report Metric | Details |
| Report Name | China Agri-Tech Software Market |
| Market Size 2025 | USD 88.0 million |
| Market Size 2032 | USD 142.24 million |
| Absolute Growth 2025–2032 | USD 54.24 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 9.9% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Software Type, 2025 | Farm Management System (40% share) |
| Leading Feature Focus, 2025 | Crop Planning (42% share) |
| Leading Distribution Channel, 2025 | Online Subscription (35% share) |
| Leading End User, 2025 | Agronomists & Farmers (44% share) |
| Fastest-Growing Software Type | Precision Ag Software (9.5% CAGR) |
| Fastest-Growing Feature Focus | Forecasting & Analysis (9.1% CAGR) |
| Fastest-Growing Distribution Channel | B2B Platforms (9.0% CAGR) |
| Fastest-Growing End User | Agri Enterprises (9.6% CAGR) |
| Growing Sector | Agriculture |
| Key End Users | Agronomists & Farmers, Agri Enterprises, Smart Farm Operators, Agri Research Institutes |
China Agri-Tech Software Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
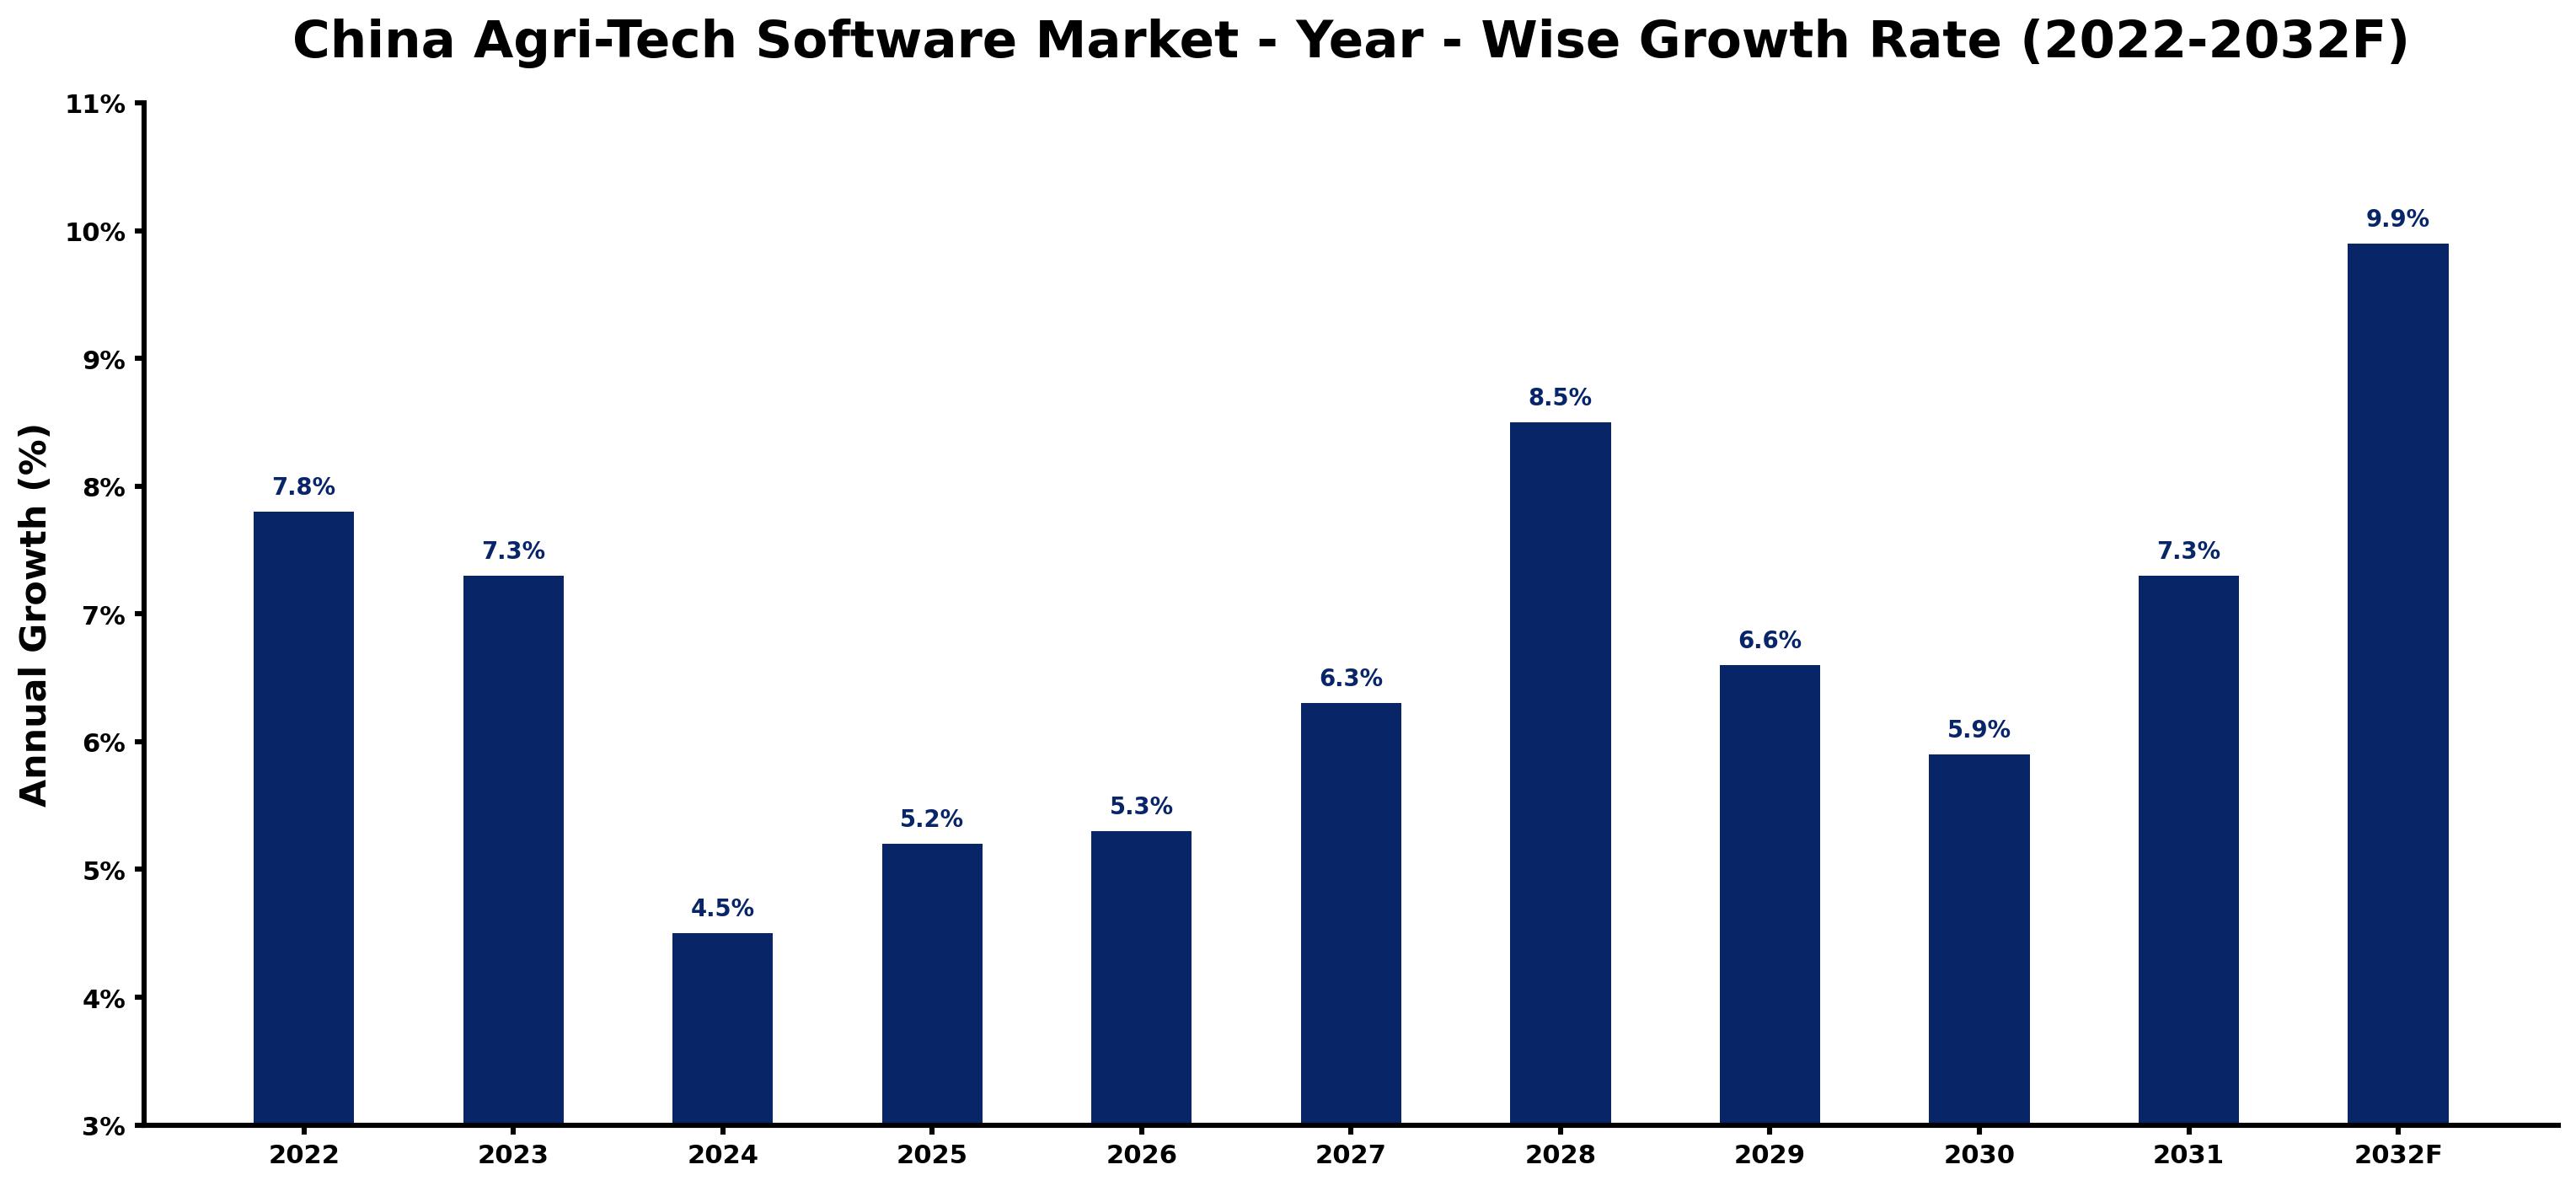
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.8 | The agricultural sector employed over 300 million people, driving demand for agri-tech solutions. |
| 2023 | 7.3 | Adoption of digital farming technologies continued to grow, with over 60% of farmers using them. |
| 2024 | 4.5 | Growth slowed as the market adjusted to the rapid technology adoption in previous years. |
| 2025 | 5.2 | Investment in smart farming technologies increased, supported by government funding initiatives. |
| 2026 | 5.3 | The Digital Agriculture Development Plan is expected to enhance technology integration in farming. |
| 2027 | 6.3 | Precision agriculture technologies gained traction in major agricultural provinces like Shandong. |
| 2028 | 8.5 | A rise in crop monitoring and management solutions is anticipated as farmers seek efficiency. |
| 2029 | 6.6 | The market experiences a slowdown as initial adoption peaks, yet demand remains strong. |
| 2030 | 5.9 | Growth slows as the market matures, but continued investment in technology sustains interest. |
| 2031 | 7.3 | Demand for agri-tech solutions rises as agronomists and farmers seek better management tools. |
| 2032 | 9.9 | The market is projected to peak as innovative software solutions transform agricultural practices. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Agri-Tech Software Market Synopsis
Agri-Tech Software in China encompasses digital solutions designed to improve agricultural productivity through data management and analysis. It includes farm management, crop monitoring, and supply chain optimisation. The China Agri-Tech Software Market is expanding due to strong demand from domestic users and the integration of advanced technologies in farming practices. Initiatives like the Digital Agriculture Development Plan and the Smart Agriculture Pilot Program are propelling this growth. With over 300 million people employed in agriculture, the need for efficient management tools is paramount.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing adoption of precision agriculture technologies in provinces like Shandong | Driver | High | Precision Ag Software |
| Increased investment in smart farming technologies due to government support | Driver | High | Farm Management System |
| Rising demand for crop monitoring tools among agronomists and farmers | Opportunity | High | Farm Management System |
| Expansion of digital agriculture initiatives across various provinces | Opportunity | High | Farm Management System |
| Limited access to advanced technology in rural areas | Restraint | Medium | Precision Ag Software |
| High initial costs of implementing agri-tech solutions for small farmers | Restraint | Medium | Farm Management System |
| Challenges in integrating new technologies with existing farming practices | Challenge | High | Crop Modeling Tools |
| Need for continuous training and support for farmers using new software | Challenge | Medium | Agri Enterprises |
Evaluation of Drivers in China Agri-Tech Software Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in smart farming technologies | Farm Management System | The Chinese government allocated 1 billion CNY to support smart farming technologies, leading to higher adoption rates among farmers. |
| Growing adoption of precision agriculture technologies | Precision Ag Software | Provinces like Henan are implementing precision agriculture, driving demand for software that optimizes farming practices. |
| Rising demand for crop monitoring solutions | Farm Management System | With agricultural output value reaching 6 trillion CNY, farmers are seeking effective monitoring tools to boost productivity. |
| Expansion of digital agriculture initiatives | Farm Management System | The Smart Agriculture Pilot Program promotes technology use, increasing demand for related software solutions. |
| Surge in the use of forecasting and analysis tools | Forecasting & Analysis | As farmers aim for better yield predictions, the need for sophisticated forecasting tools is increasing. |
Expansion of the Agri-Tech Software market in China is backed by increased investment in smart farming technologies, precision agriculture adoption, and the rising need for crop monitoring solutions. Agricultural output value reached 6 trillion CNY, prompting farmers to seek effective monitoring tools to improve productivity. Precision agriculture technologies are gaining traction in provinces like Henan, driving demand for software that optimizes farming practices.
Evaluation of Restraints in China Agri-Tech Software Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited access to advanced technology in rural areas | Precision Ag Software | Farmers in remote areas struggle to access advanced technologies, hindering their ability to adopt agri-tech solutions. |
| High initial costs of implementing agri-tech solutions | Farm Management System | Small farmers face financial barriers to adopting new technologies, which can delay implementation. |
| Challenges in integrating new technologies with existing practices | Crop Modeling Tools | Farmers often find it difficult to adapt new software to their current farming methods, limiting usage. |
| Need for continuous training and support for farmers | Agri Enterprises | Without proper training, farmers may not fully utilize the capabilities of new software, affecting productivity. |
| Concerns over data privacy and security | Farm Management System | Farmers are hesitant to adopt software that requires sharing sensitive information, limiting market growth. |
China Agri-Tech Software Market Challenges
Buyers and suppliers in the China Agri-Tech Software market face a skills shortage, as many agricultural workers lack the digital literacy necessary for effective software use. This gap exists due to limited training initiatives in rural areas, which hinders technology adoption among farmers. High costs also pose a challenge; the average investment in agri-tech software can exceed 200,000 CNY per farm, making it prohibitively expensive for smaller operations. Supply chain issues arise from software not integrating well with traditional farming methods, leading to delays in crop monitoring and management that negatively affect farmers' productivity.
Trends in the China Agri-Tech Software Market
Below mentioned are some of the trends shaping the China Agri-Tech Software Market growth.
- Digital Agriculture Development Plan Drives Adoption: The Digital Agriculture Development Plan initiated in 2021 has accelerated the adoption of agri-tech software across China. By 2023, over 60% of farmers were using digital farming technologies, reflecting a growing trend towards data-driven farming.
- Shift Towards Precision Agriculture: Since 2020, there has been a notable shift towards precision agriculture practices in provinces like Henan. With the area of farmland in China being approximately 120 million hectares, this trend is expected to improve productivity and efficiency.
- Increased Focus on Crop Monitoring Solutions: Agronomists and farmers are increasingly prioritising crop monitoring solutions to optimise yields. This shift is evidenced by the rising demand for forecasting and analysis tools, with a projected growth rate of 9.1% by 2032.
- Emergence of B2B Platforms for Agri-Tech: B2B platforms have emerged as a key distribution channel for agri-tech software, growing at a rate of 9.0% from 2026 to 2032. This trend facilitates business transactions in the agri-tech sector, broadening market reach.
Investment Opportunities in the China Agri-Tech Software Market
The following opportunities in the China Agri-Tech Software Market pair current demand with a clear way in.
- Supply of Precision Ag Software: With precision agriculture technologies gaining traction, there is a strong opportunity to supply precision ag software. Agronomists and farmers are actively seeking these solutions, especially in regions like Henan, where technology adoption is high.
- Investment in Crop Monitoring Tools: Now is the time to invest in crop monitoring tools, as demand is rising among agronomists and farmers. Collaborating with local agricultural cooperatives can facilitate entry into this growing market.
- Development of Forecasting & Analysis Solutions: There is an opportunity to develop forecasting and analysis solutions tailored for the agricultural sector. The increasing need for yield predictions among farmers makes this a timely investment.
- Expansion of B2B Platforms: The growth of B2B platforms presents an opportunity for software suppliers to reach a wider audience. Establishing partnerships with local distributors can improve market penetration.
Government Initiatives in the China Agri-Tech Software Market
The Agricultural Technology Promotion Law, revised in 2020, supports agri-tech innovations and their adoption. This law encourages producers to invest in technology and ensures that they meet quality standards. The National Standard for Agricultural Information Technology (GB/T 33400-2016), updated in 2021, outlines requirements for agri-tech software, promoting interoperability and quality assurance in the sector. Additionally, the Digital Agriculture Development Plan launched in 2021 aims to promote digital technology use in agriculture, providing a framework for software development and implementation.
The National Agricultural Technology Extension and Service Center actively promotes agri-tech software usage. It provides funding for projects that integrate technology into farming practices, ensuring that farmers receive the necessary training and support to adopt these innovations effectively. The Ministry of Agriculture and Rural Affairs oversees these initiatives, facilitating the adoption of advanced agricultural technologies across the country.
Future Insight of the China Agri-Tech Software Market
The China Agri-Tech Software market is set to evolve significantly by 2032, influenced by several strategic factors. The 'Digital Agriculture Development Plan' will facilitate broader technology adoption, enabling more farmers to embrace advanced solutions. Precision agriculture technologies will gain traction in productive provinces like Shandong and Henan, enhancing operational efficiency. With government backing of 1 billion CNY for smart farming initiatives, investment in agri-tech software will rise, encouraging innovation. By 2023, over 60% of farmers are projected to adopt digital farming technology, indicating a transformative shift in agricultural practices.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Software Type – Farm Management System Dominated, Precision Ag Software Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Farm Management System took a 40% share of software type in 2025, more than any other category. Farm Management Systems hold the largest market share because they are crucial for managing farm operations and resources effectively. Their significance is particularly pronounced in regions like Shandong and Henan, which are known for their substantial agricultural output. Over 2026–2032, Precision Ag Software is expected to post the fastest growth, at a CAGR of 9.5%. Precision Ag Software is witnessing rapid growth due to its role in optimising farming practices through data-driven insights. The increasing adoption of precision agriculture technologies in key agricultural provinces is a major factor contributing to this trend. Suppliers should focus on enhancing precision ag software capabilities to cater to the rising demand from farmers.
By Feature Focus – Crop Planning Dominated, Forecasting & Analysis Expected to Grow Fastest
In 2025, Crop Planning led the feature focus split with a 42% share. Crop Planning holds the largest market share as it is vital for scheduling planting and harvesting activities, ensuring optimal crop yields. This feature is particularly important in a country with extensive farmland like China, where efficient planning is essential. The quickest growth will come from Forecasting & Analysis, forecast to expand at a CAGR of 9.1% between 2026 and 2032. Forecasting & Analysis is the fastest-growing segment due to its critical role in making informed agricultural decisions. The increasing complexity of farming operations necessitates advanced analytical tools to predict outcomes and trends. Buyers will benefit from investing in forecasting tools that provide deeper insights for better decision-making in their agricultural practices.
By Distribution Channel – Online Subscription Dominated, B2B Platforms Expected to Grow Fastest
With a 35% revenue share in 2025, Online Subscription was the largest distribution channel category. Online Subscription captures the largest market share as it is a widely used distribution method for software services, ensuring easy access for users. This model aligns well with the growing trend of digital adoption among farmers and agronomists in China. B2B Platforms are set to record the highest CAGR in this split, 9.0% over 2026–2032. B2B Platforms are experiencing swift growth as they facilitate efficient business transactions in the agri-tech sector, connecting suppliers directly with agricultural enterprises. The emergence of agri-tech startups is a key driver of demand for these platforms. Suppliers should improve their presence on B2B platforms to enhance visibility and increase sales opportunities.
By End User – Agronomists & Farmers Dominated, Agri Enterprises Expected to Grow Fastest
Agronomists & Farmers held a 44% share of the China Agri-Tech Software Market by end user in 2025. Agronomists & Farmers dominate the market share as they are the primary users of agri-tech software solutions, directly benefiting from enhanced productivity. The extensive workforce of over 300 million in agriculture underscores the strong demand within this segment. Agri Enterprises are projected to grow fastest, at a CAGR of 9.6% during 2026–2032. Agri Enterprises are the fastest-growing end user segment, motivated by their need for operational efficiency through advanced agri-tech solutions. The rising demand for large-scale management tools within these enterprises is propelling their growth. Suppliers need to tailor their offerings to meet the specific needs of agri enterprises to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Agri-Tech Software Market Outlook
- Market Size of China Agri-Tech Software Market, 2025
- Forecast of China Agri-Tech Software Market, 2032
- Historical Data and Forecast of China Agri-Tech Software Revenues & Volume for the Period 2022 - 2032F
- China Agri-Tech Software Market Trend Evolution
- China Agri-Tech Software Market Drivers and Challenges
- China Agri-Tech Software Price Trends
- China Agri-Tech Software Porter's Five Forces
- China Agri-Tech Software Industry Life Cycle
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Software Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Farm Management System for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By ERP Solutions for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Precision Ag Software for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Crop Modeling Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Feature Focus for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Crop Planning for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Supply Chain Mgmt for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Sensor Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Forecasting & Analysis for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Online Subscription for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By App Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By B2B Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Agronomists & Farmers for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Agri Enterprises for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Smart Farm Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Agri-Tech Software Market Revenues & Volume By Agri Research Institutes for the Period 2022 - 2032F
- China Agri-Tech Software Import Export Trade Statistics
- Market Opportunity Assessment By Software Type
- Market Opportunity Assessment By Feature Focus
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Agri-Tech Software Top Companies Market Share
- China Agri-Tech Software Competitive Benchmarking By Technical and Operational Parameters
- China Agri-Tech Software Company Profiles
- China Agri-Tech Software Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Software Type
- Farm Management System
- ERP Solutions
- Precision Ag Software
- Crop Modeling Tools
By Feature Focus
- Crop Planning
- Supply Chain Mgmt
- Sensor Integration
- Forecasting & Analysis
By Distribution Channel
- Online Subscription
- Direct Sales
- App Stores
- B2B Platforms
By End User
- Agronomists & Farmers
- Agri Enterprises
- Smart Farm Operators
- Agri Research Institutes































