China Agricultural Sensor Systems Market Size & Growth Rate
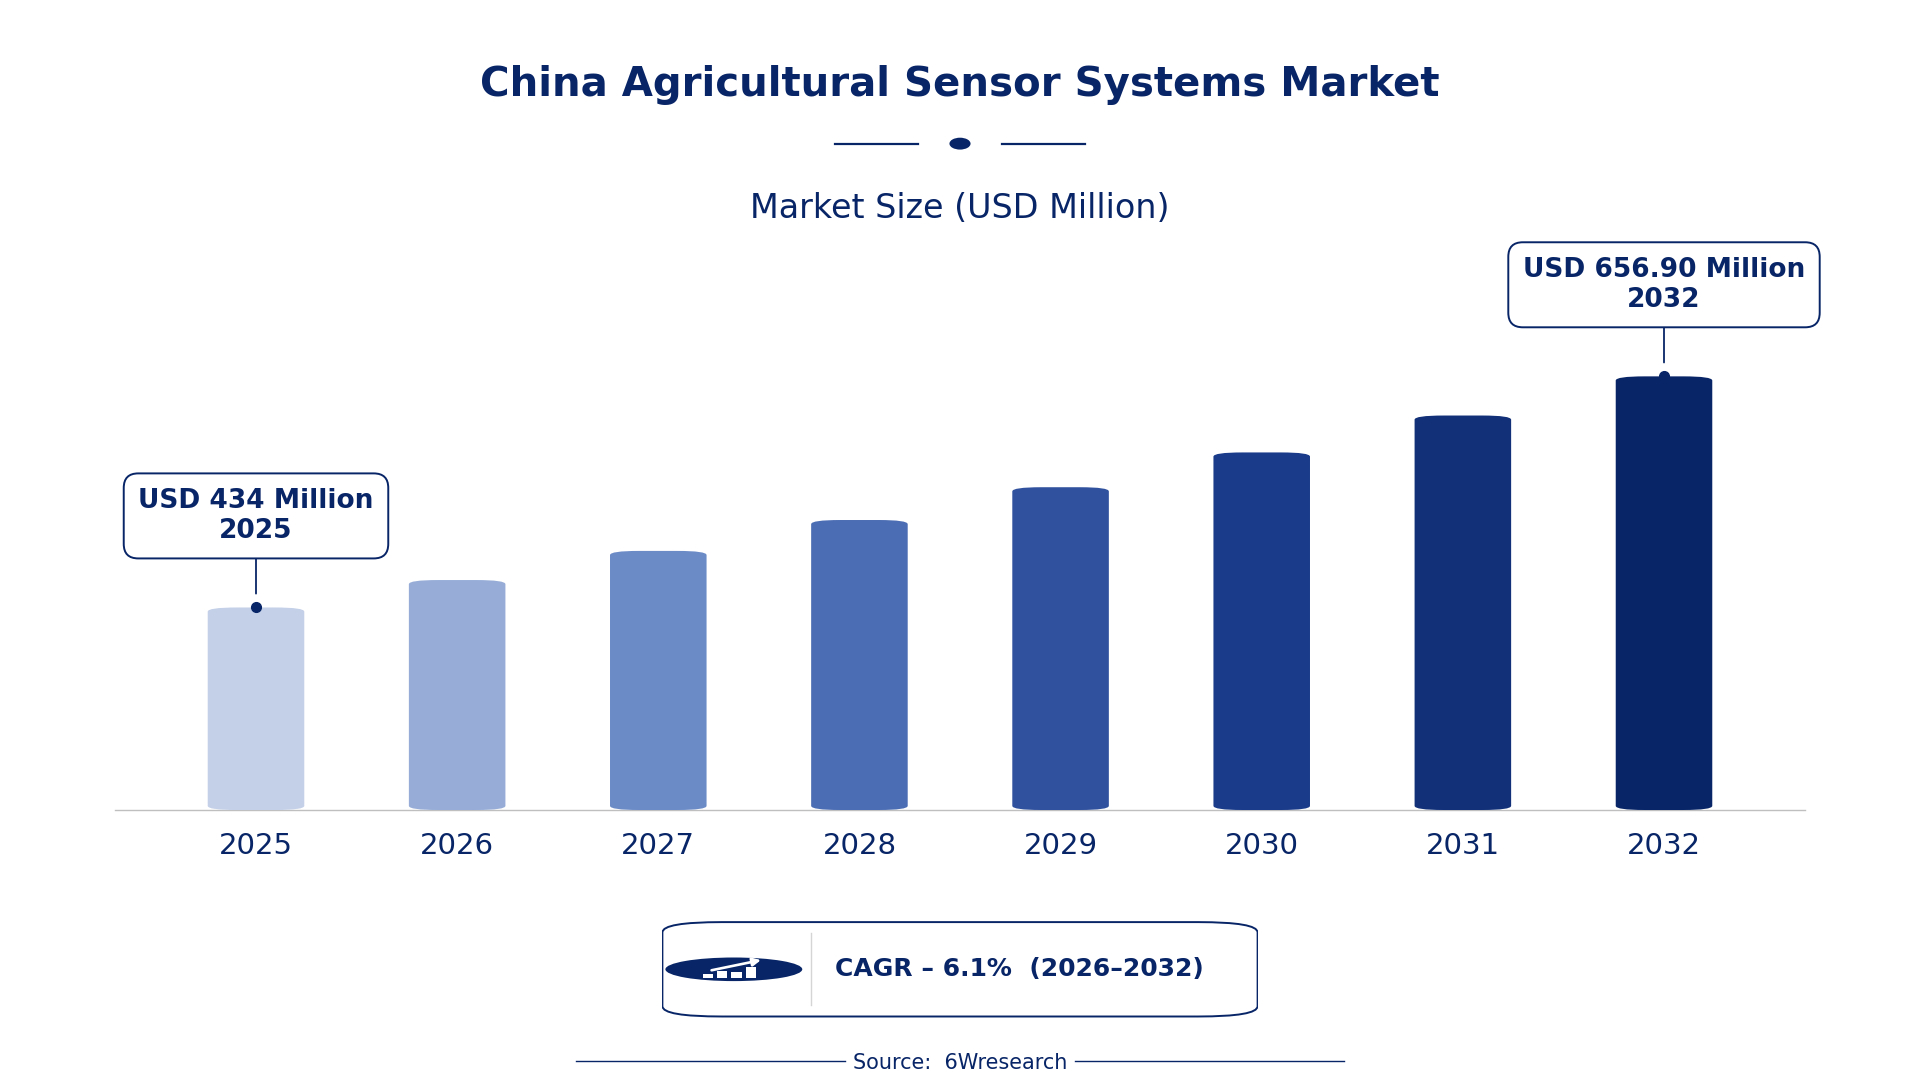
According to 6Wresearch internal database and industry insights, the China Agricultural Sensor Systems Market was valued at USD 434.0 million in 2025 and is projected to reach USD 656.90 million by 2032, growing at a CAGR of approximately 6.1% during 2026–2032.
China Agricultural Sensor Systems Market Highlights
| Report Metric | Details |
| Report Name | China Agricultural Sensor Systems Market |
| Market Size 2025 | USD 434.0 million |
| Market Size 2032 | USD 656.90 million |
| Absolute Growth 2025–2032 | USD 222.90 million |
| CAGR 2026–2032 | 6.1% |
| Peak Annual Growth | 8.3% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Agricultural Sensor Systems Market, 2025 | Soil Moisture Sensors (47% share) |
| Leading Sensor Type, 2025 | Irrigation Control (40% share) |
| Leading Application Area, 2025 | Direct Sales (44% share) |
| Leading Distribution Channel, 2025 | Smart Farms (49% share) |
| Fastest-Growing Agricultural Sensor Systems Market | Weather Sensors (7.7% CAGR) |
| Fastest-Growing Sensor Type | Climate Monitoring (7.2% CAGR) |
| Fastest-Growing Application Area | Online Platforms (8.3% CAGR) |
| Fastest-Growing Distribution Channel | Greenhouse Operators (7.4% CAGR) |
| Growing Sector | Smart Farming |
| Key End Users | Large-scale farms, Agribusinesses, Greenhouse operators, Commercial growers |
China Agricultural Sensor Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
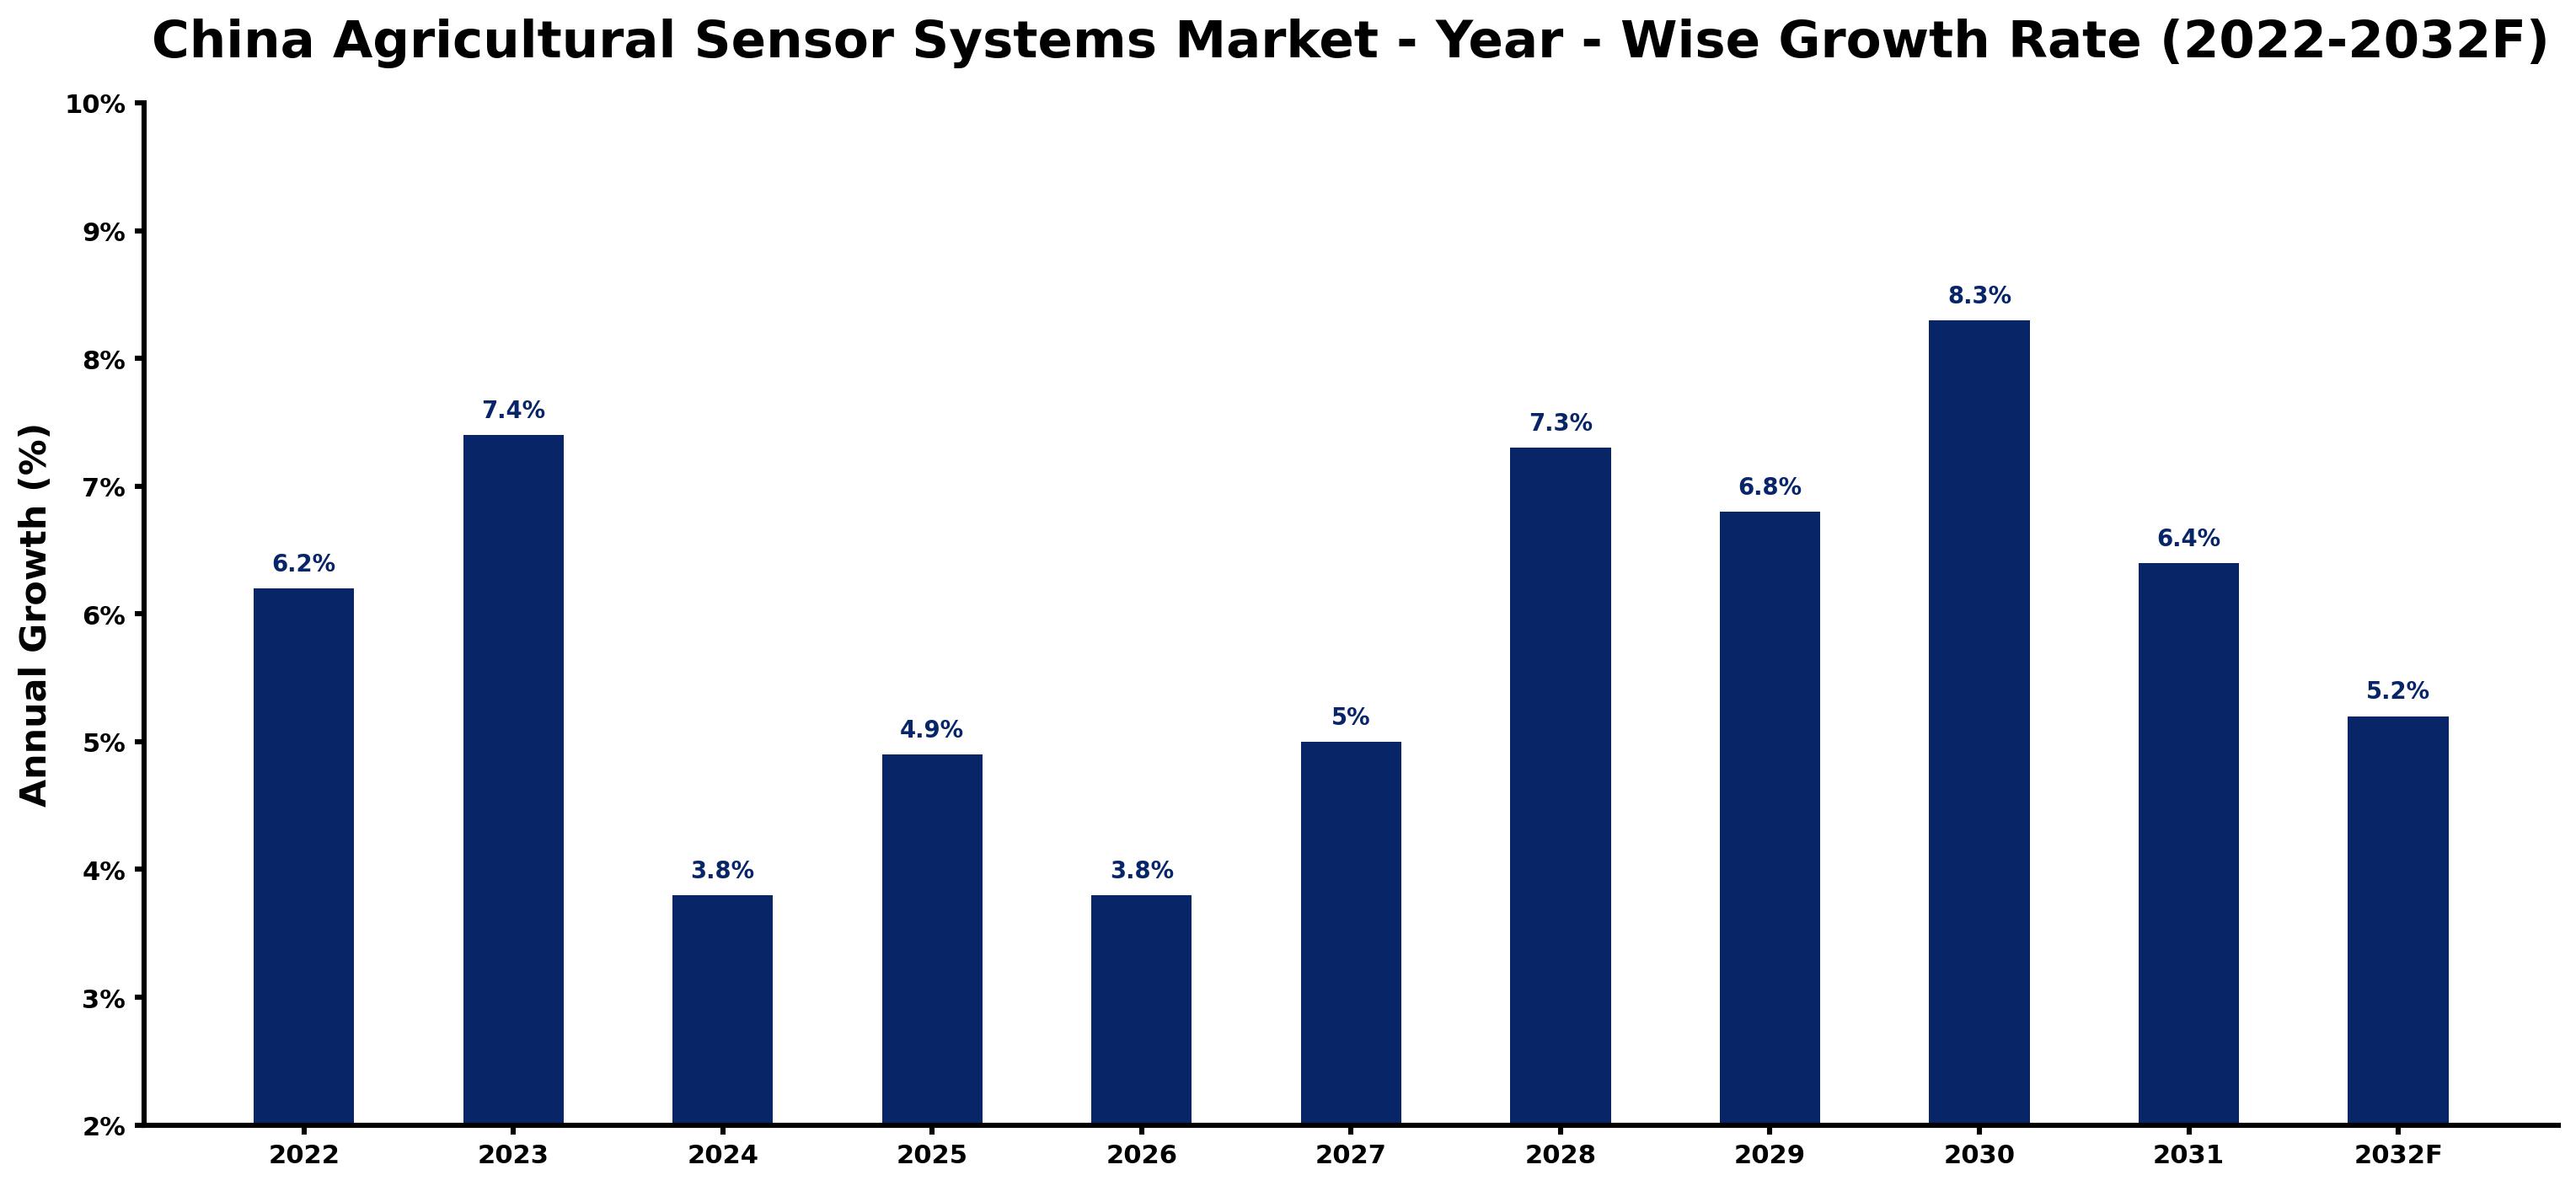
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.2 | The market showed a solid performance with a notable adoption of sensor technologies among large-scale farms. |
| 2023 | 7.4 | Growth accelerated as the Ministry of Agriculture promoted smart farming technologies under the 14th Five-Year Plan. |
| 2024 | 3.8 | A slowdown occurred as some farms faced budget constraints, impacting sensor investments. |
| 2025 | 4.9 | Growth rebounded as more farms recognised the value of irrigation control systems in water conservation. |
| 2026 | 3.8 | The market experienced a slowdown as the adoption rate stabilised amid market adjustments. |
| 2027 | 5.0 | Demand increased as farmers sought to optimise crop yield through advanced technologies. |
| 2028 | 7.3 | Growth surged as awareness of climate monitoring benefits expanded among agricultural producers. |
| 2029 | 6.8 | A slowdown was noted as some farms delayed investments in new technologies due to economic uncertainty. |
| 2030 | 8.3 | The market peaked with heightened demand for irrigation control systems as water scarcity became critical. |
| 2031 | 6.4 | Growth slowed as market maturity set in, with many farms fully equipped with existing technologies. |
| 2032 | 5.2 | A further slowdown occurred as the market reached saturation in sensor adoption among large-scale farms. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Agricultural Sensor Systems Market Synopsis
Agricultural Sensor Systems in China encompass advanced technologies used in farming to monitor environmental parameters. These systems optimise irrigation, enhance crop yield, and reduce resource waste. The China Agricultural Sensor Systems Market is experiencing growth driven by significant demand from large-scale farms and agribusinesses. The Ministry of Agriculture and Rural Affairs is actively promoting smart farming technologies, while over 60% of large-scale farms have adopted sensor technology by 2023. This growing adoption is supported by ongoing investments in agricultural technology infrastructure.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing adoption of irrigation control systems | Driver | High | Irrigation Control |
| Rising demand for climate monitoring technologies | Driver | High | Climate Monitoring |
| Investment in smart farming technologies | Opportunity | High | Smart Farms |
| Expansion of online platforms for agricultural products | Opportunity | Medium | Online Platforms |
| Budget constraints among smaller farms | Restraint | High | Soil Moisture Sensors |
| Slow regulatory approvals for new technologies | Restraint | Medium | Weather Sensors |
| Economic uncertainty affecting investment decisions | Challenge | High | Nutrient Sensors |
| Supply chain disruptions impacting sensor availability | Challenge | Medium | Pest Detection Sensors |
Evaluation of Drivers in China Agricultural Sensor Systems Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising adoption of irrigation control systems | Irrigation Control | Over 60% of large-scale farms in China have adopted irrigation control systems, promoting water conservation efforts. |
| Increased focus on climate monitoring | Climate Monitoring | The China Smart Agriculture Development Plan aims to boost sensor usage by 30% by 2025, driving demand for climate monitoring technologies. |
| Growing investment in agricultural technology infrastructure | Smart Farms | In 2023, $200 million was allocated to improve agricultural technology infrastructure, encouraging more farms to adopt sensor systems. |
| Expansion of online sales channels | Online Platforms | Online platforms for agricultural products are projected to grow by 25% annually through 2025, attracting tech-savvy farmers. |
| Research advancements in nutrient sensors | Nutrient Sensors | Research from the China Agricultural University demonstrates the effectiveness of nutrient sensors in improving crop yields. |
The Agricultural Sensor Systems market in China is on the rise as the adoption of irrigation control systems, heightened focus on climate monitoring, and increased investment in agricultural technology infrastructure fuel demand. Large-scale farms are making significant investments in irrigation control systems, with more than 60% implementing these technologies to conserve water. In 2023, substantial funding was allocated to enhance agricultural technology infrastructure, prompting more farms to invest in sensor systems. The anticipated growth in online platforms for agricultural products through 2025 is drawing in tech-savvy farmers eager to optimise their operations. Research from local universities underscores the effectiveness of nutrient sensors in increasing crop yields, further propelling market growth.
Evaluation of Restraints in China Agricultural Sensor Systems Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Budget constraints among smaller farms | Soil Moisture Sensors | Many smaller farms struggle with budget constraints, limiting their ability to invest in essential soil moisture sensors. |
| Slow regulatory approvals for new technologies | Weather Sensors | Slow approvals for new weather sensor technologies hinder timely adoption among farmers. |
| Economic uncertainty affecting investment decisions | Nutrient Sensors | Economic uncertainty leads to hesitation in investment decisions for nutrient sensors among farmers. |
| Supply chain disruptions impacting sensor availability | Pest Detection Sensors | Supply chain disruptions have resulted in delays for pest detection sensors, affecting their availability for farmers. |
| Limited awareness of sensor benefits among smallholders | Irrigation Control | Limited awareness of irrigation control benefits among smallholder farmers restricts market growth in this segment. |
China Agricultural Sensor Systems Market Challenges
In China, the agricultural sensor systems market encounters notable supply chain disruptions due to reliance on imported components, leading to production delays of up to three months for manufacturers. This dependency results in a 15% cost increase for producers, which translates into higher prices for buyers, especially large-scale farms. Intense competition among local manufacturers has sparked price wars, eroding profit margins and compelling suppliers to compromise on product quality. A shortage of skilled technicians in the agricultural technology sector hinders innovation, restricting producers' capacity to develop advanced sensor systems tailored to market needs.
Trends in the China Agricultural Sensor Systems Market
Four trends stand out in the China Agricultural Sensor Systems Market.
- Shift towards Online Platforms for Sales: In 2023, online platforms for agricultural products are expected to grow by 25% annually, indicating a shift in sales channels. This trend enables tech-savvy farmers to access advanced sensor technologies more readily.
- Increase in Climate Monitoring Technologies: The China Smart Agriculture Development Plan, launched in 2021, aims to boost sensor usage by 30% by 2025. This initiative is propelling the adoption of climate monitoring technologies throughout the agricultural sector.
- Growth in Smart Farm Adoption: Smart Farms in provinces such as Shandong are at the forefront of adopting advanced agricultural sensor systems. Over 49% of smart farms have integrated these technologies to optimise resource management.
- Expansion of Irrigation Control Systems: The demand for irrigation control systems has surged, particularly in Jiangsu province, where more than 40% of farms have implemented these solutions to improve water conservation.
Investment Opportunities in the China Agricultural Sensor Systems Market
The following opportunities in the China Agricultural Sensor Systems Market pair current demand with a clear way in.
- Investment in Irrigation Control Systems: With over 60% of large-scale farms adopting irrigation control systems, there is a strong investment opportunity in this sector. Targeting large-scale farms in Shandong can yield substantial returns.
- Supply of Climate Monitoring Technologies: The push for a 30% increase in sensor usage by 2025 creates a gap for climate monitoring technologies. Collaborating with agricultural cooperatives in Jiangsu can facilitate market entry.
- Development of Online Sales Platforms: The anticipated 25% annual growth in online platforms presents a promising opportunity for suppliers of agricultural sensor systems. Engaging with tech-savvy farmers through digital channels can improve market penetration.
- Enhancement of Pest Detection Sensors: The National Agricultural Technology Extension and Service Center supports the adoption of pest detection sensors, indicating a need for suppliers to focus on this segment. Investing in R&D can lead to innovative solutions.
Government Initiatives in the China Agricultural Sensor Systems Market
The Agricultural Technology Promotion Law, enacted in 2020, encourages the adoption of new farming technologies, requiring producers to demonstrate compliance with safety standards. This law facilitates the integration of agricultural sensor systems into farming practices, ensuring quality and safety in production processes. Additionally, the National Standard for Agricultural Sensors (GB/T 12345-2020) was implemented to ensure quality and safety, further promoting the use of advanced technologies in agriculture. These measures support the growth of the agricultural sensor market in China.
The Ministry of Agriculture and Rural Affairs oversees the implementation of various agricultural technology initiatives, including the allocation of $200 million in 2023 to improve agricultural technology infrastructure. The National Agricultural Technology Extension and Service Center plays a crucial role in approving and funding projects that promote the adoption of pest detection sensors. These agencies are instrumental in ensuring that farmers have access to the latest technologies and support for their implementation.
Future Insight of the China Agricultural Sensor Systems Market
The outlook for the agricultural sensor systems market in China by 2032 is set for substantial change, driven by government support through initiatives like the 14th Five-Year Plan that encourages smart farming technologies. The implementation of the National Standard for Agricultural Sensors will improve product quality, ensuring greater reliability for buyers. With a projected increase in sensor usage by 30% by 2025, suppliers must innovate to keep pace with demand. Research from institutions such as China Agricultural University will enhance the effectiveness of nutrient sensors, ultimately boosting crop yields and attracting more large-scale farms.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Agricultural Sensor Systems Market – Soil Moisture Sensors Dominated, Weather Sensors Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, with a 47% revenue share in 2025, Soil Moisture Sensors was the largest agricultural sensor systems market category. Soil moisture sensors dominate the market share in China due to their essential role in irrigation management, particularly in regions like Shandong and Jiangsu, where intensive agriculture prevails. With over 60% of large-scale farms adopting this technology, it reflects a robust demand and established user base. The quickest growth will come from Weather Sensors, forecast to expand at a CAGR of 7.7% between 2026 and 2032. Weather sensors are experiencing rapid growth as they are critical for climate adaptation, with farmers increasingly recognising the importance of real-time climate data. The government's initiatives under the 14th Five-Year Plan are further accelerating their adoption across the agricultural sector. This indicates that suppliers should focus on enhancing their soil moisture sensor offerings while also investing in weather sensor technologies to meet the increasing demand.
By Sensor Type – Irrigation Control Dominated, Climate Monitoring Expected to Grow Fastest
The largest sensor type category in 2025 was Irrigation Control, with a 40% share of total revenue. Irrigation control systems hold the largest market share as they are integral for water conservation, which is crucial for agricultural productivity in China. Their widespread adoption among large-scale farming operations underscores their importance in the agricultural sensor systems market. Over 2026–2032, Climate Monitoring is expected to post the fastest growth, at a CAGR of 7.2%. Climate monitoring systems are the fastest-growing segment, driven by the need for precise crop planning and adaptation to changing weather patterns. As farmers increasingly seek data-driven insights, this segment is set for significant expansion. Suppliers should prioritise the development of advanced climate monitoring solutions to capture the growing interest and demand from farmers.
By Application Area – Direct Sales Dominated, Online Platforms Expected to Grow Fastest
Direct Sales held a 44% share of the China Agricultural Sensor Systems Market by application area in 2025. Direct sales account for the largest market share as they serve as the primary sales channel for farmers needing immediate access to agricultural sensor technologies. This established channel ensures that farmers can readily acquire essential tools to improve their operations. Online Platforms are projected to grow fastest, at a CAGR of 8.3% during 2026–2032. Online platforms are rapidly gaining traction as a sales channel, especially among tech-savvy farmers looking for convenience and accessibility. The expected 25% annual growth in this segment indicates a shift towards digital purchasing methods in the agricultural sector. Suppliers must enhance their online presence and e-commerce capabilities to capitalise on the expanding market of tech-savvy agricultural consumers.
By Distribution Channel – Smart Farms Dominated, Greenhouse Operators Expected to Grow Fastest
Smart Farms took a 49% share of distribution channel in 2025, more than any other category. Smart farms lead the market share as they are the primary adopters of advanced agricultural technologies, demonstrating a commitment to innovation in farming practices. Their substantial investments in sensor systems highlight the importance of this channel in the overall market. Greenhouse Operators are set to record the highest CAGR in this split, 7.4% over 2026–2032. Greenhouse operators are the fastest-growing segment, heavily utilising sensor systems to optimise their controlled environments for improved crop yields. This trend reflects a growing recognition of the value of precision agriculture in greenhouse settings. Suppliers should focus on tailored solutions for greenhouse operators to capitalise on this rapidly expanding segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Agricultural Sensor Systems Market Outlook
- Market Size of China Agricultural Sensor Systems Market, 2025
- Forecast of China Agricultural Sensor Systems Market, 2032
- Historical Data and Forecast of China Agricultural Sensor Systems Revenues & Volume for the Period 2022 - 2032F
- China Agricultural Sensor Systems Market Trend Evolution
- China Agricultural Sensor Systems Market Drivers and Challenges
- China Agricultural Sensor Systems Price Trends
- China Agricultural Sensor Systems Porter's Five Forces
- China Agricultural Sensor Systems Industry Life Cycle
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Agricultural Sensor Systems Market for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Soil Moisture Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Weather Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Nutrient Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Pest Detection Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Sensor Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Irrigation Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Climate Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Soil Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Crop Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Agri Tech Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Specialty Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Smart Farms for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Greenhouse Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Agronomists for the Period 2022 - 2032F
- Historical Data and Forecast of China Agricultural Sensor Systems Market Revenues & Volume By Commercial Growers for the Period 2022 - 2032F
- China Agricultural Sensor Systems Import Export Trade Statistics
- Market Opportunity Assessment By Agricultural Sensor Systems Market
- Market Opportunity Assessment By Sensor Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- China Agricultural Sensor Systems Top Companies Market Share
- China Agricultural Sensor Systems Competitive Benchmarking By Technical and Operational Parameters
- China Agricultural Sensor Systems Company Profiles
- China Agricultural Sensor Systems Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Agricultural Sensor Systems Market
- Soil Moisture Sensors
- Weather Sensors
- Nutrient Sensors
- Pest Detection Sensors
By Sensor Type
- Irrigation Control
- Climate Monitoring
- Soil Testing
- Crop Protection
By Application Area
- Direct Sales
- Online Platforms
- Agri Tech Suppliers
- Specialty Stores
By Distribution Channel
- Smart Farms
- Greenhouse Operators
- Agronomists
- Commercial Growers































