China Agro Commodities Market Size & Growth Rate
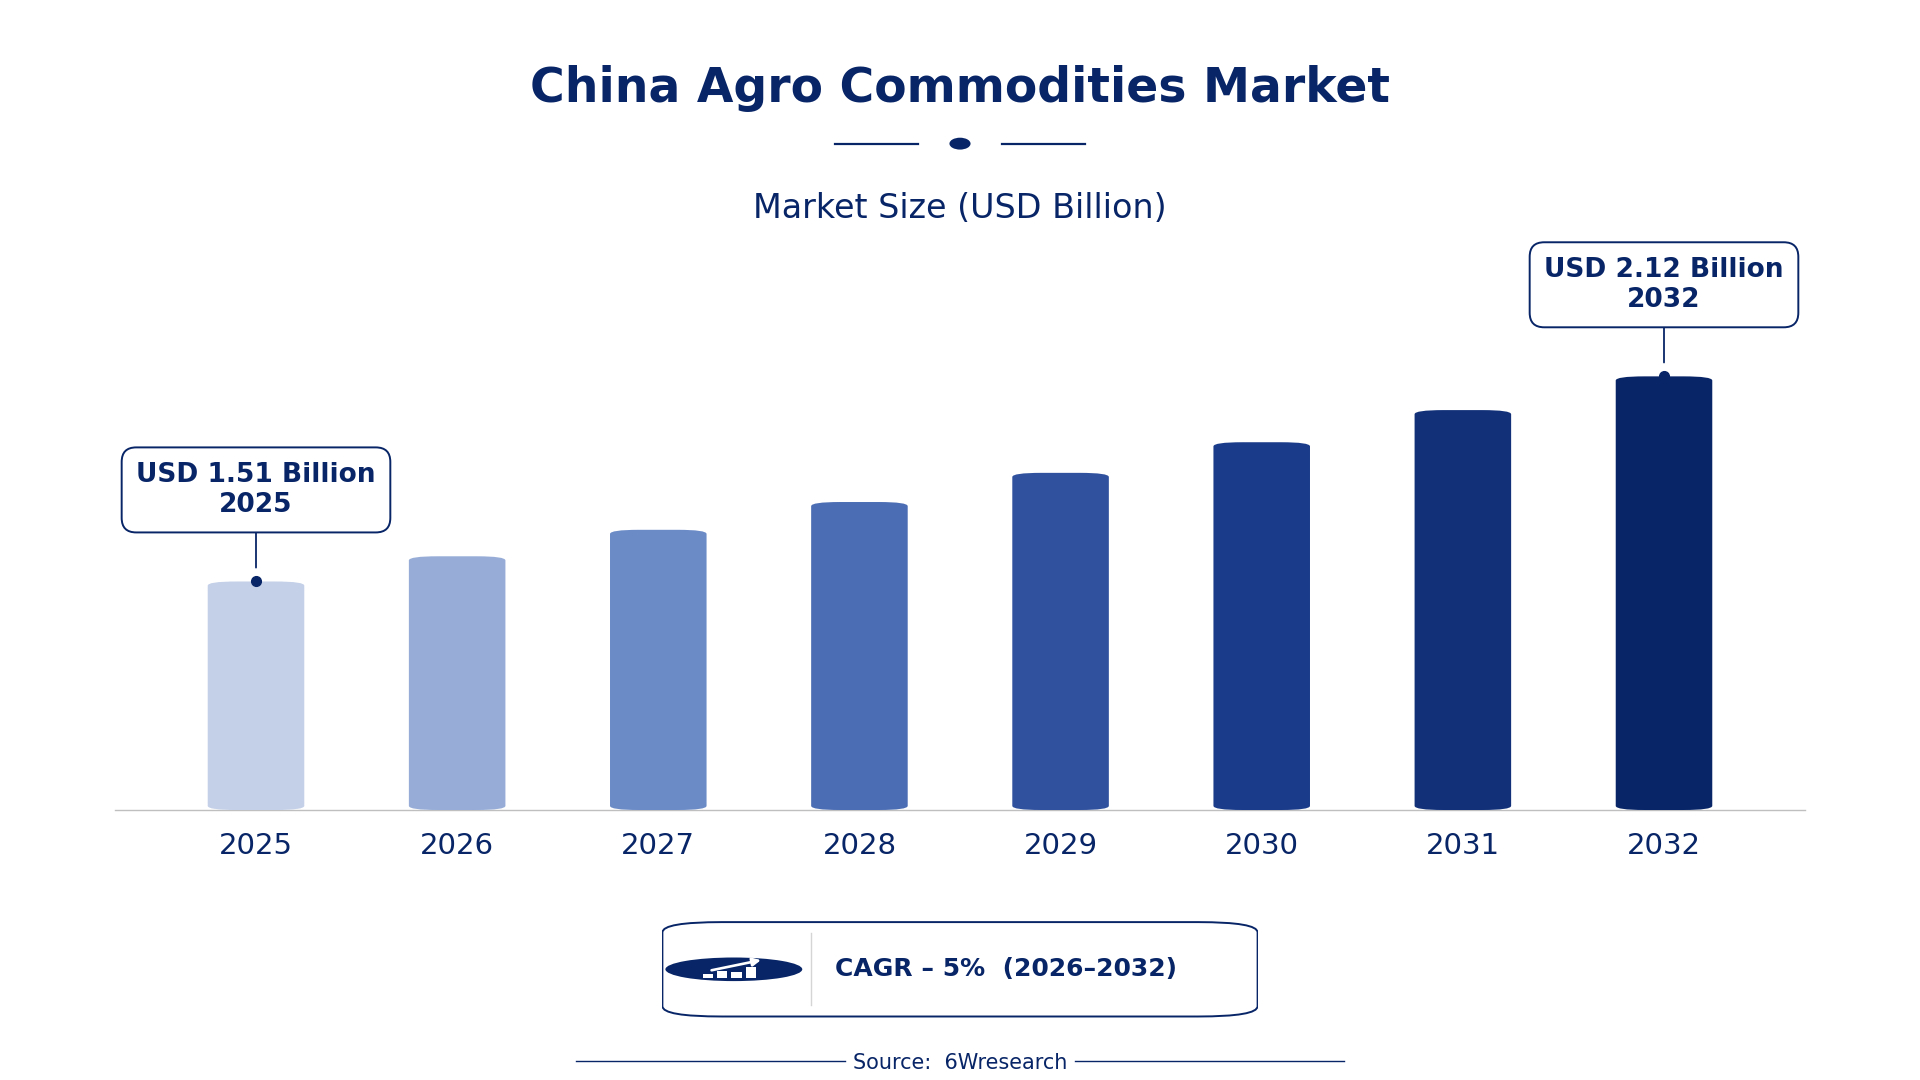
According to 6Wresearch internal database and industry insights, the China Agro Commodities Market was valued at USD 1.51 billion in 2025 and is projected to reach USD 2.12 billion by 2032, growing at a CAGR of approximately 5% during 2026–2032.
China Agro Commodities Market Highlights
| Report Metric | Details |
| Report Name | China Agro Commodities Market |
| Market Size 2025 | USD 1.51 billion |
| Market Size 2032 | USD 2.12 billion |
| Absolute Growth 2025–2032 | USD 0.61 billion |
| CAGR 2026–2032 | 5% |
| Peak Annual Growth | 6.9% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Commodity Type, 2025 | Wheat (43% share) |
| Leading Trade Form, 2025 | Raw Grains (37% share) |
| Leading Distribution Channel, 2025 | Mandis & Exchanges (48% share) |
| Leading End User, 2025 | Food Processing Companies (41% share) |
| Fastest-Growing Commodity Type | Spices (6.8% CAGR) |
| Fastest-Growing Trade Form | Whole/Dried (7.5% CAGR) |
| Fastest-Growing Distribution Channel | Export Houses (7.1% CAGR) |
| Fastest-Growing End User | International Retail Chains (6.9% CAGR) |
| Growing Sector | Food Processing |
| Key End Users | Food Processing Companies, International Retail Chains, Edible Oil Manufacturers, Retail Consumers |
China Agro Commodities Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
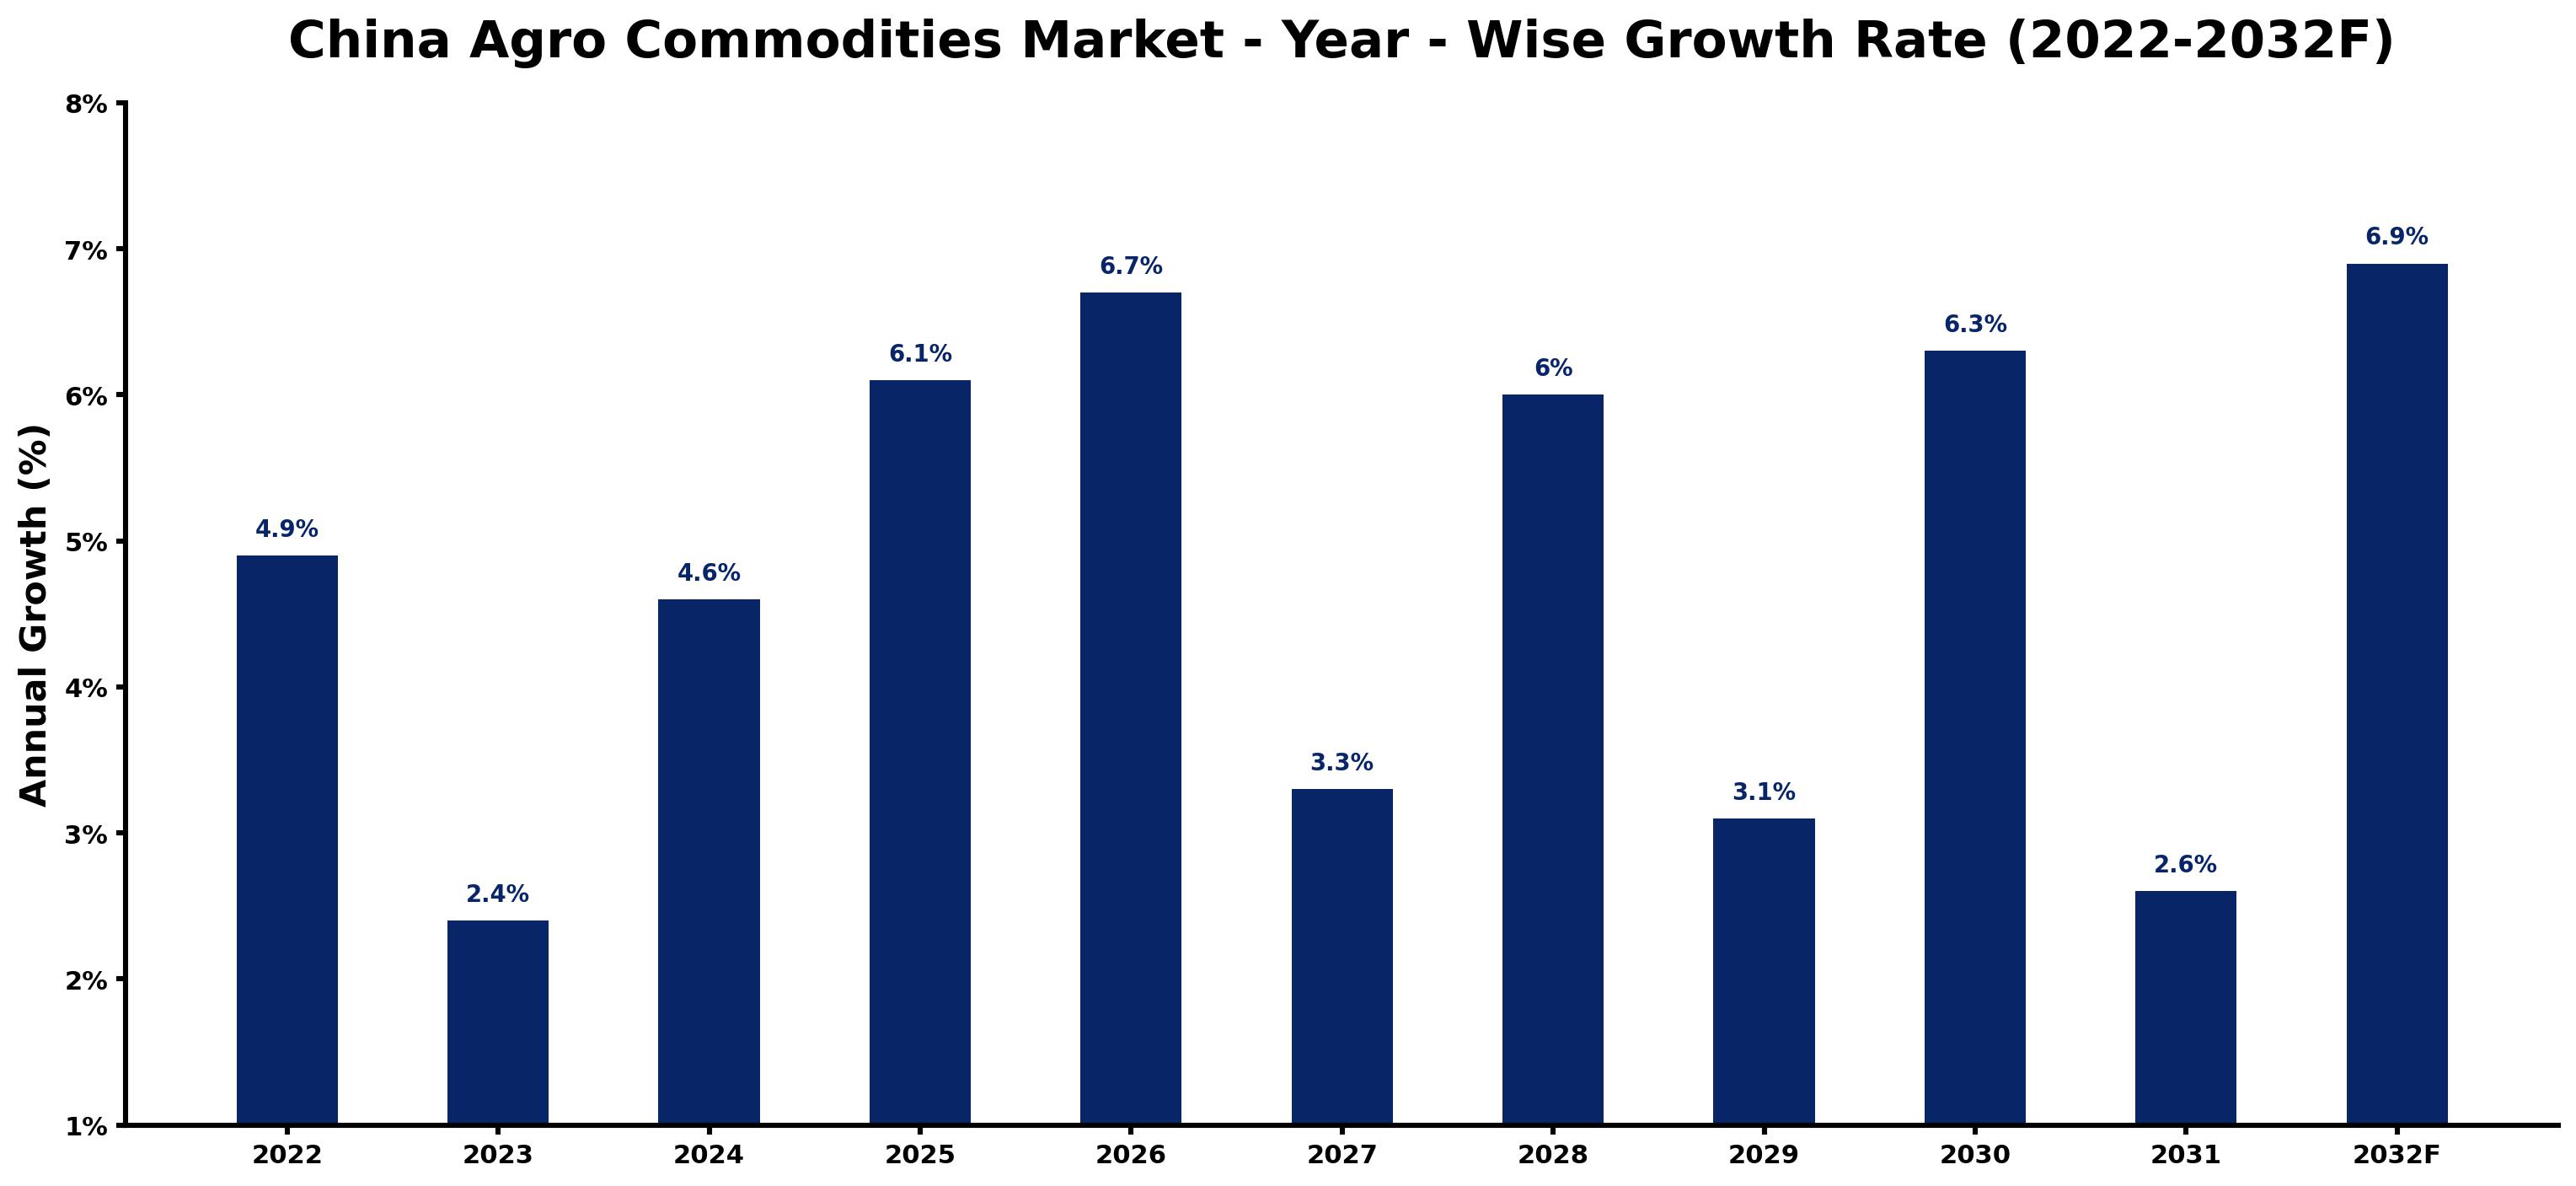
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.9 | The market experienced steady growth due to the National Food Security Strategy enhancing domestic production. |
| 2023 | 2.4 | Growth slowed as supply chain disruptions affected agro commodity distribution and logistics. |
| 2024 | 4.6 | Demand increased as food processing companies expanded production capabilities in response to consumer needs. |
| 2025 | 6.1 | A surge in wheat production drove market growth, reaching historical peaks in output. |
| 2026 | 6.7 | Investment in sustainable farming practices is expected to boost production efficiency and demand. |
| 2027 | 3.3 | Growth is projected to slow as international market fluctuations impact local pricing. |
| 2028 | 6.0 | Increased exports of pulses revitalise market dynamics and demand for local producers. |
| 2029 | 3.1 | A slowdown is expected as consumer preferences shift towards alternative protein sources. |
| 2030 | 6.3 | Demand is projected to surge again as food processing companies ramp up production capabilities. |
| 2031 | 2.6 | Growth is anticipated to slow as regulatory changes introduce new compliance costs for producers. |
| 2032 | 6.9 | The market is expected to peak as investments in technology enhance production capabilities. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Agro Commodities Market Synopsis
The China Agro Commodities Market includes raw agricultural products traded in bulk, such as grains, oilseeds, and pulses. These commodities are crucial for food production, animal feed, and export activities. The market is expanding due to rising domestic demand from the food processing sector, valued at around 14 trillion CNY, alongside increased exports, with pulses reaching 1.5 million tons in 2022. The National Food Security Plan launched in 2023 aims to boost grain production, further supporting this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| High domestic demand for food production and animal feed. | Driver | High | Wheat |
| Growing export opportunities for pulses and oilseeds. | Driver | High | Pulses |
| Increasing demand for sustainable farming practices. | Opportunity | Medium | Oilseeds |
| Expansion of e-commerce platforms for agro commodities distribution. | Opportunity | Medium | Raw Grains |
| Supply chain disruptions affecting availability and pricing. | Restraint | High | Spices |
| Regulatory compliance costs impacting producers' profitability. | Restraint | Medium | Oilseeds |
| The agro commodities market in China faces significant regulatory challenges. | Challenge | High | Pulses |
| Competition from international markets affecting local pricing. | Challenge | Medium | Wheat |
Evaluation of Drivers in China Agro Commodities Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| High domestic production of wheat supports local consumption. | Wheat | China produces over 130 million tons of wheat annually, driving demand from food processing companies. |
| Rising exports of pulses increase market demand. | Pulses | The export of pulses reached 1.5 million tons in 2022, prompting higher production levels. |
| Investment in sustainable farming practices boosts production efficiency. | Oilseeds | The Sustainable Agricultural Development Plan aims to improve production methods, increasing oilseed output. |
| Growing e-commerce channels expand market access for agro commodities. | Raw Grains | E-commerce platforms are facilitating retail distribution, improving consumer access to agro commodities. |
| Increased food processing capabilities drive higher demand for raw materials. | Spices | The food processing industry, valued at 14 trillion CNY, requires diverse agro commodities. |
Market growth for Agro Commodities in China is underpinned by high domestic production levels, rising exports, and increased investment in sustainable farming practices. The production of over 130 million tons of wheat annually supports local consumption, driving demand from food processing companies. The export of pulses reached 1.5 million tons in 2022, prompting higher production levels. Investment in sustainable farming practices is expected to boost production efficiency, benefiting suppliers. E-commerce platforms are facilitating retail distribution, improving consumer access to agro commodities, which further stimulates market growth.
Evaluation of Restraints in China Agro Commodities Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions affecting availability and pricing. | Spices | In 2022, disruptions in logistics led to increased prices and reduced availability of spices. |
| Regulatory compliance costs impacting producers' profitability. | Oilseeds | Changes in the Agricultural Product Quality and Safety Law increased compliance costs for producers. |
| Market volatility due to international pricing fluctuations. | Pulses | International market fluctuations in 2022 affected local pricing and demand for pulses. |
| Limited access to modern farming technology for small producers. | Wheat | Many small-scale farmers lack access to advanced farming techniques, limiting productivity. |
| Environmental regulations increasing production costs. | Raw Grains | New environmental regulations have raised costs for producers, impacting profit margins. |
China Agro Commodities Market Challenges
The China Agro Commodities Market faces high procurement costs for buyers, primarily due to fluctuating global prices that can increase expenses by up to 15% annually. Skills shortages among producers hinder operational efficiency, particularly in key wheat-producing regions like Shandong and Henan, resulting in delayed harvests that affect supply timelines. Compliance with standards such as GB 2716-2018 raises operational costs for suppliers, inflating production expenses by around 5%. Supply chain disruptions are exacerbated by the need for 9 million tons of imported oilseeds, complicating the timely delivery of agro commodities to domestic markets.
Trends in the China Agro Commodities Market
Four trends stand out in the China Agro Commodities Market.
- Shift towards Sustainable Farming Practices: China is increasingly adopting sustainable farming practices to improve agro commodity production efficiency. The Sustainable Agricultural Development Plan launched in 2022 aims to improve production quality and efficiency by 2030.
- Growth of E-commerce in Agro Commodities Distribution: The rise of e-commerce platforms is transforming how agro commodities are distributed in China. This shift is reflected in the growing share of online sales, projected to reach 25% by 2025.
- Increased Focus on Food Safety Standards: The National Standard for Edible Oils regulates oil quality in China, ensuring higher safety standards. Compliance with this standard is expected to improve consumer confidence and drive demand for quality products.
- Expansion of Export Markets for Pulses: China's pulse exports have been growing, reaching 1.5 million tons in 2022. This trend is likely to continue as international demand for pulses rises, opening new markets for local producers.
Investment Opportunities in the China Agro Commodities Market
Below are the investment opportunities with the strongest case in the China Agro Commodities Market.
- Growing Demand for Organic Agro Commodities: With a rising consumer preference for organic products, the market for organic agro commodities is expanding. Food processing companies are increasingly seeking organic grains, with the market projected to grow by 20% by 2025.
- Investment in Modern Farming Technology: The need for modern farming technology is vital for improving productivity. Small-scale farmers in Shandong province are seeking partnerships to access advanced techniques, which can significantly improve yields.
- Expansion of Agro Commodity Exports: The agro commodities export market presents significant opportunities, with a projected growth of 15% in the next five years. Export houses are looking to increase their offerings to international markets.
- Increased Investment in Food Processing Infrastructure: Investment in food processing infrastructure is essential for meeting rising demand. The government plans to allocate 10 billion CNY for upgrading facilities by 2025.
Government Initiatives in the China Agro Commodities Market
The National Food Security Strategy launched in 2021 focuses on improving domestic production capacity. This measure is important for buyers as it ensures a stable supply of agro commodities, reducing reliance on imports. The strategy aims to increase grain production through various initiatives, including funding for modern farming technologies and infrastructure improvements. Additionally, the Sustainable Agricultural Development Plan (2022-2030) aims to enhance production efficiency while minimising environmental impact, providing further support to producers.
The Ministry of Agriculture oversees the implementation of the Sustainable Agricultural Development Plan (2022-2030). This plan aims to improve production efficiency while minimising environmental impact. It includes funding for projects that enhance the quality of agro commodities, benefiting food processing companies and ensuring compliance with safety standards. Furthermore, the National Agro-Product Quality Improvement Program (2023) aims to raise quality standards, directly impacting producers and buyers in the agro commodities market.
Future Insight of the China Agro Commodities Market
The China Agro Commodities Market is set for notable advancements by 2032, driven by the 'National Food Security Plan' aimed at boosting grain production. The 'Green Food Development Program' will promote sustainable farming practices, ensuring more reliable supply chains. Technological innovations in agriculture will improve yield efficiency, benefiting both buyers and suppliers. The export of pulses, which reached 1.5 million tons in 2022, is expected to grow as international demand increases, creating new opportunities for producers in the agro commodities sector.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Commodity Type – Wheat Dominated, Spices Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Wheat took a 43% share of commodity type in 2025, more than any other category. Wheat holds the largest share in the China Agro Commodities Market as it is a staple for food production and animal feed, with over 130 million tons produced annually. This extensive output caters to the high domestic demand, particularly from the food processing industry. Spices are projected to grow fastest, at a CAGR of 6.8% during 2026–2032. Spices are experiencing rapid growth due to their increasing popularity for flavouring and preserving food products, driven by the expanding culinary market in China. The rising interest in diverse cuisines has led to a notable increase in both spice imports and local production. Suppliers should enhance their spice offerings to capture the growing market share driven by culinary trends.
By Trade Form – Raw Grains Dominated, Whole/Dried Expected to Grow Fastest
The largest trade form category in 2025 was Raw Grains, with a 37% share of total revenue. Raw Grains dominate the market share as they are essential for various food products and animal feed, establishing their significance in agro commodity trading. Their versatility and consistent demand from the food processing sector reinforce their leading position. Over 2026–2032, Whole/Dried is expected to post the fastest growth, at a CAGR of 7.5%. Whole/Dried products are witnessing significant growth due to their common usage in cooking and food preparation, reflecting a consumer shift towards more natural and minimally processed ingredients. This trend aligns with increasing preferences for healthier food options. Buyers should consider sourcing more whole and dried products to align with consumer trends towards natural ingredients.
By Distribution Channel – Mandis & Exchanges Dominated, Export Houses Expected to Grow Fastest
In 2025, Mandis & Exchanges led the distribution channel split with a 48% share. Mandis & Exchanges are the primary platforms for trading agro commodities, holding the largest market share due to their established networks and accessibility for farmers and traders. These traditional markets facilitate direct transactions, ensuring a reliable supply chain. The quickest growth will come from Export Houses, forecast to expand at a CAGR of 7.1% between 2026 and 2032. Export Houses are rapidly growing as they facilitate international trade of agro commodities, propelled by increasing global demand for Chinese products. The government's initiatives to boost exports further support this growth trajectory. Suppliers should strengthen partnerships with export houses to expand their reach in international markets.
By End User – Food Processing Companies Dominated, International Retail Chains Expected to Grow Fastest
With a 41% revenue share in 2025, Food Processing Companies was the largest end user category. Food Processing Companies represent the largest share as major consumers of agro commodities for production, highlighting their critical role in the supply chain. The substantial valuation of the food processing industry underscores the importance of these companies in driving demand. International Retail Chains are set to record the highest CAGR in this split, 6.9% over 2026–2032. International Retail Chains are experiencing the fastest growth as significant buyers for their stores, driven by rising consumer demand for diverse food products. Their expansion in China aligns with the increasing purchasing power of the population. Suppliers should target international retail chains to capitalise on the growing demand for agro commodities in retail.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Agro Commodities Market Outlook
- Market Size of China Agro Commodities Market, 2025
- Forecast of China Agro Commodities Market, 2032
- Historical Data and Forecast of China Agro Commodities Revenues & Volume for the Period 2022 - 2032F
- China Agro Commodities Market Trend Evolution
- China Agro Commodities Market Drivers and Challenges
- China Agro Commodities Price Trends
- China Agro Commodities Porter's Five Forces
- China Agro Commodities Industry Life Cycle
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Commodity Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Wheat for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Spices for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Oilseeds for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Pulses for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Trade Form for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Raw Grains for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Whole/Dried for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Crushed/Refined for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Packed Grains for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Mandis & Exchanges for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Export Houses for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Commodity Brokers for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By E-commerce & Warehouses for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Food Processing Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By International Retail Chains for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Edible Oil Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Agro Commodities Market Revenues & Volume By Retail Consumers for the Period 2022 - 2032F
- China Agro Commodities Import Export Trade Statistics
- Market Opportunity Assessment By Commodity Type
- Market Opportunity Assessment By Trade Form
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Agro Commodities Top Companies Market Share
- China Agro Commodities Competitive Benchmarking By Technical and Operational Parameters
- China Agro Commodities Company Profiles
- China Agro Commodities Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Commodity Type
- Wheat
- Spices
- Oilseeds
- Pulses
By Trade Form
- Raw Grains
- Whole/Dried
- Crushed/Refined
- Packed Grains
By Distribution Channel
- Mandis & Exchanges
- Export Houses
- Commodity Brokers
- E-commerce & Warehouses
By End User
- Food Processing Companies
- International Retail Chains
- Edible Oil Manufacturers
- Retail Consumers































