China AgTech Market Size & Growth Rate
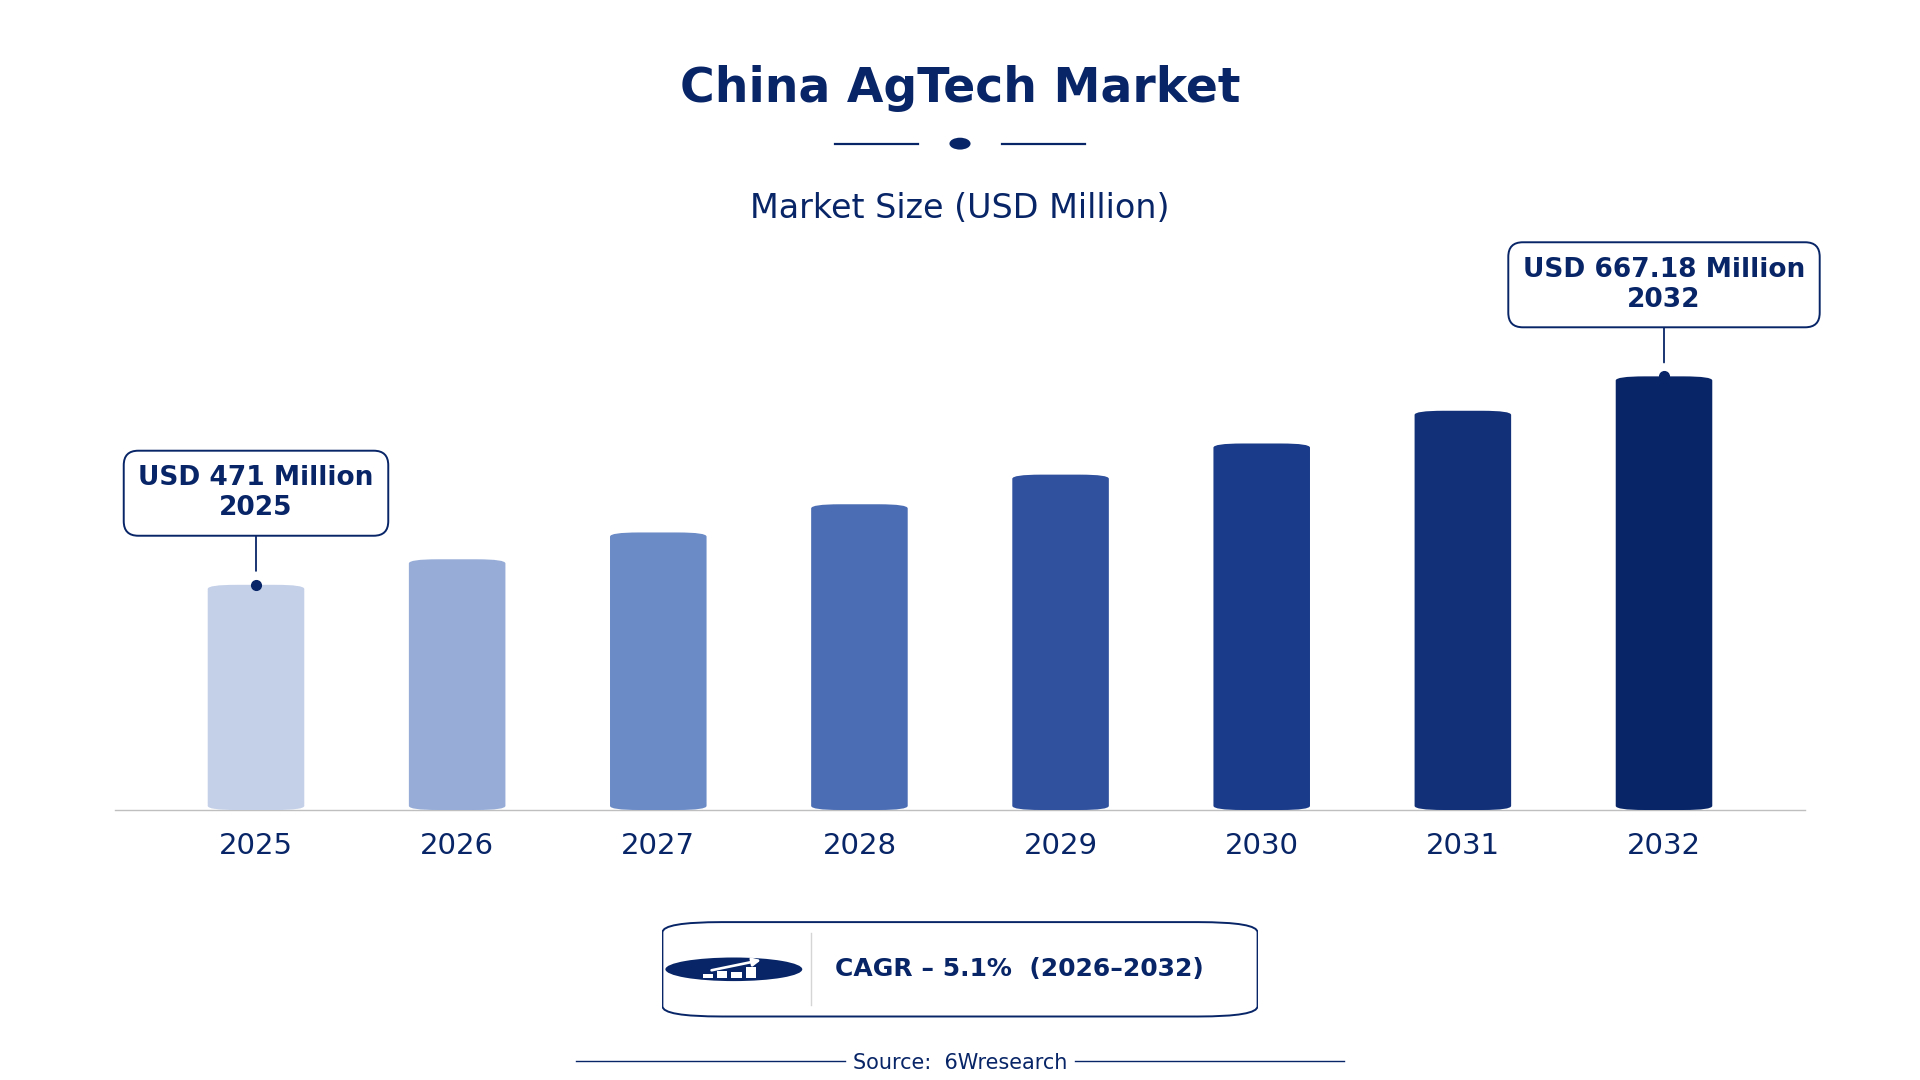
According to 6Wresearch internal database and industry insights, the China AgTech Market was valued at USD 471.0 million in 2025 and is projected to reach USD 667.18 million by 2032, growing at a CAGR of approximately 5.1% during 2026–2032.
China AgTech Market Highlights
| Report Metric | Details |
| Report Name | China AgTech Market |
| Market Size 2025 | USD 471.0 million |
| Market Size 2032 | USD 667.18 million |
| Absolute Growth 2025–2032 | USD 196.18 million |
| CAGR 2026–2032 | 5.1% |
| Peak Annual Growth | 6.7% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Farm Automation Tools (46% share) |
| Leading Technology Type, 2025 | IoT-enabled Devices (39% share) |
| Leading Distribution Channel, 2025 | Direct Sales (45% share) |
| Leading End User, 2025 | Commercial Farms (40% share) |
| Fastest-Growing Product Type | Drones & Robotics (7.6% CAGR) |
| Fastest-Growing Distribution Channel | Online Platforms (6.8% CAGR) |
| Fastest-Growing End User | Smart Farming Units (7.0% CAGR) |
| Growing Sector | Commercial Farms |
| Key End Users | Commercial Farms, Agribusiness Companies, Horticulture Enterprises |
China AgTech Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
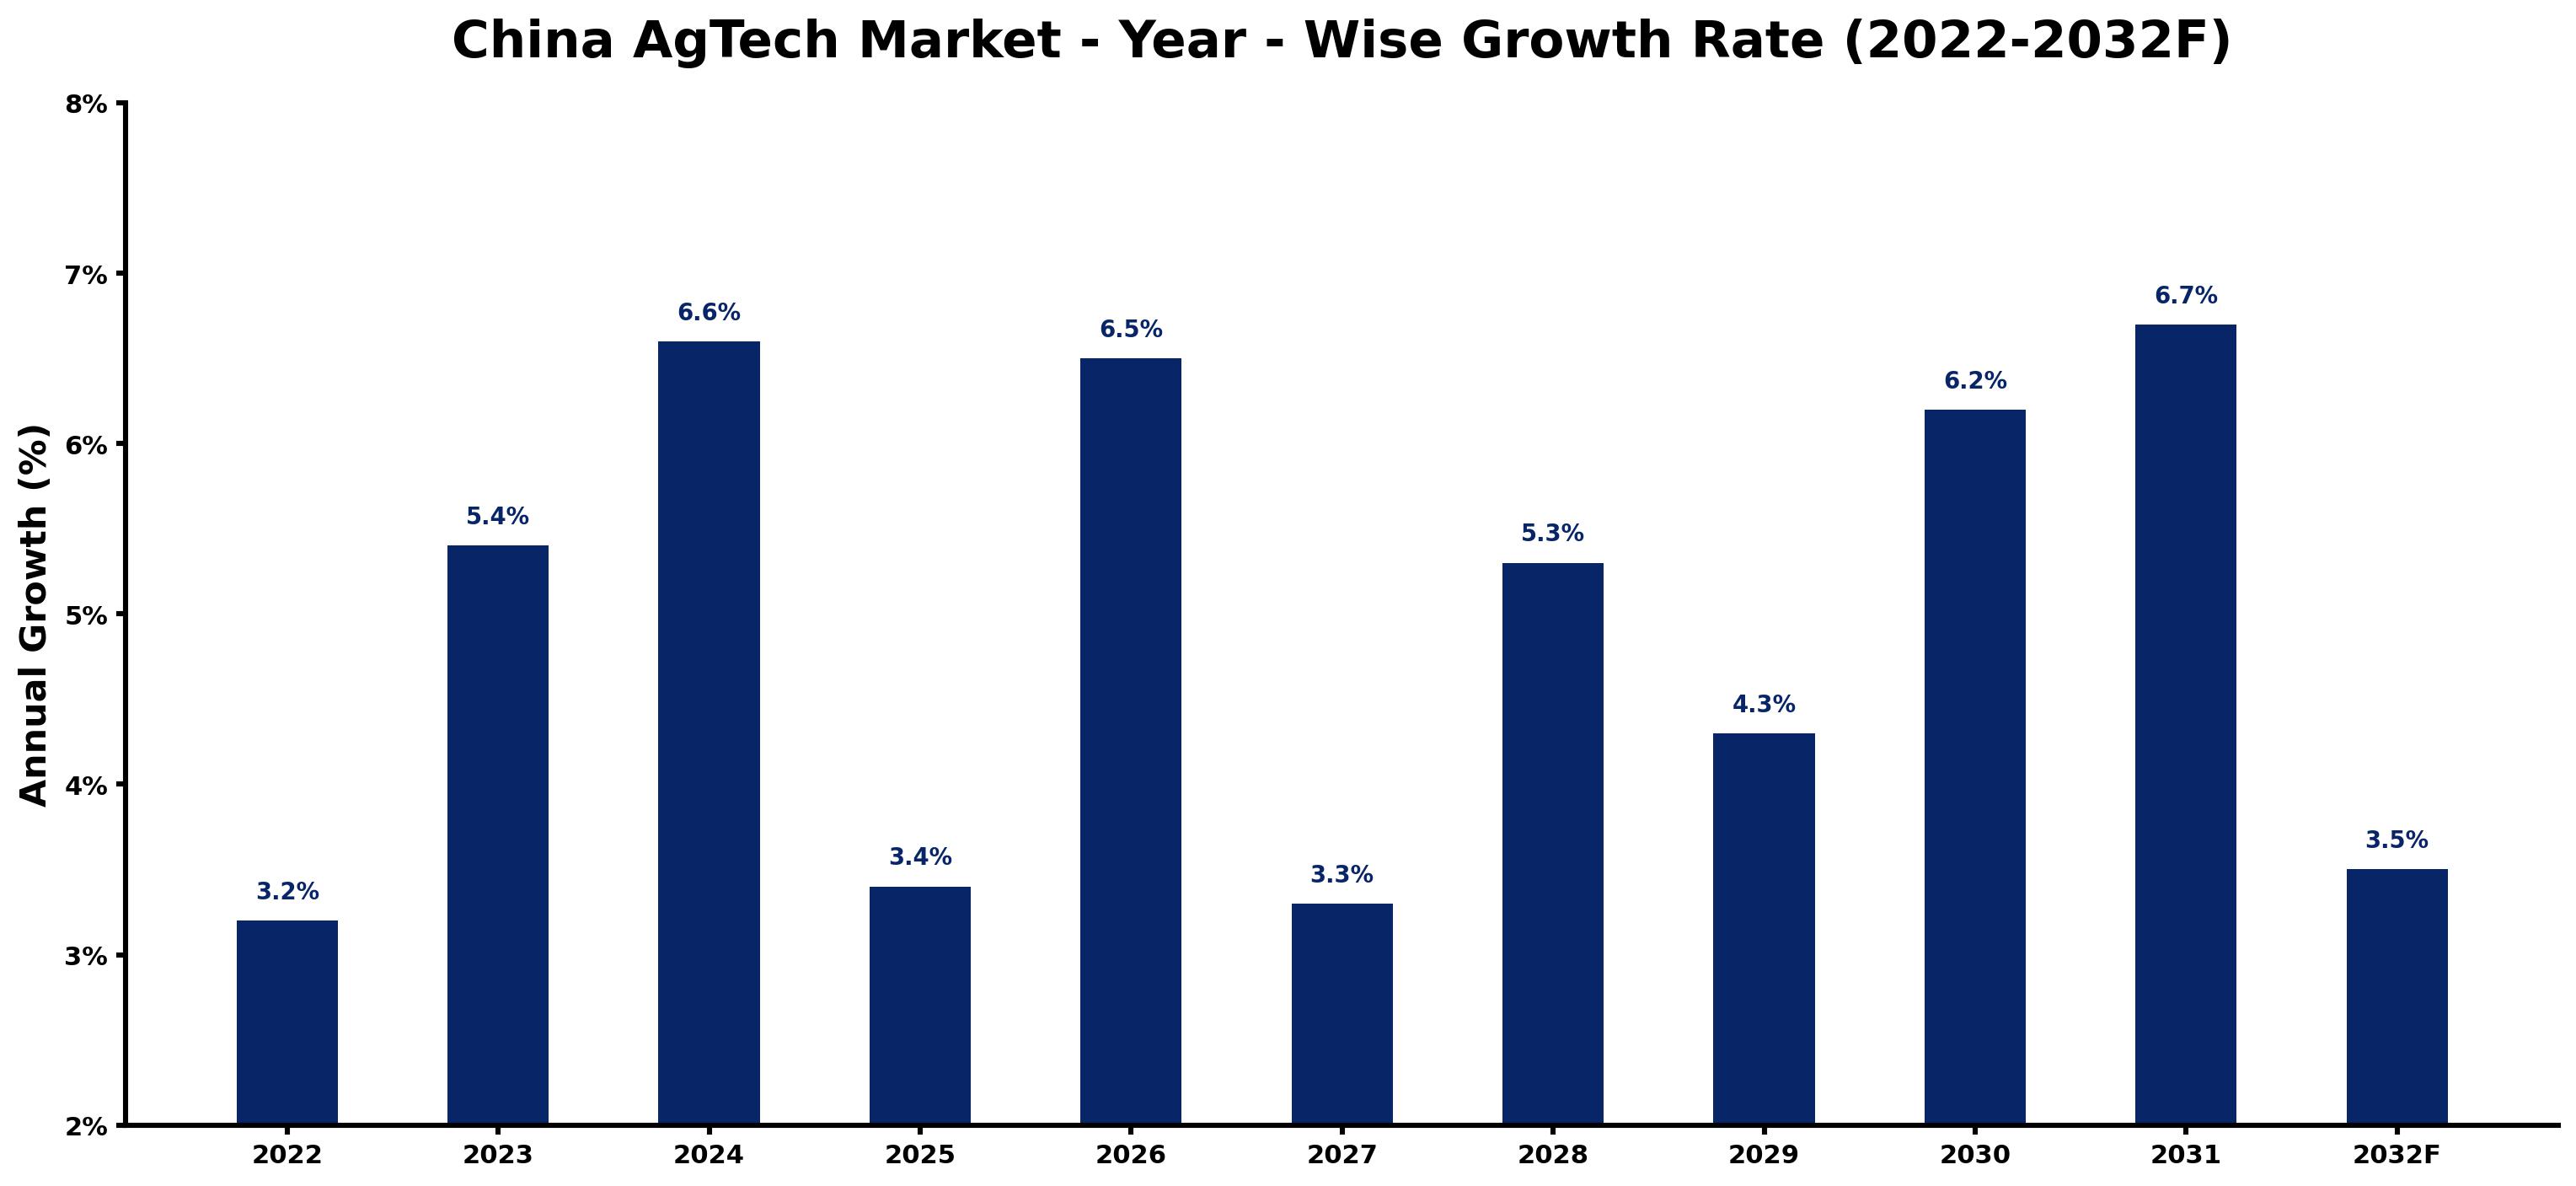
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.2 | The agricultural sector showed stable demand for technology solutions in farming practices. |
| 2023 | 5.4 | Increased adoption of precision farming technologies drove higher investment in AgTech. |
| 2024 | 6.6 | The launch of the 'National Modern Agriculture Development Plan' boosted technology integration. |
| 2025 | 3.4 | Growth slowed as market adjustments took place amid changing agricultural practices. |
| 2026 | 6.5 | Demand for IoT-enabled devices surged as farmers sought efficiency improvements. |
| 2027 | 3.3 | Adoption rates for automation tools moderated, reflecting market saturation in some areas. |
| 2028 | 5.3 | The push for sustainable practices led to renewed interest in AgTech solutions. |
| 2029 | 4.3 | Growth slowed as competition intensified among technology providers in the sector. |
| 2030 | 6.2 | Investment in agricultural technology is expected to rise due to government support. |
| 2031 | 6.7 | The market peaked as advanced technologies gained widespread acceptance among farmers. |
| 2032 | 3.5 | Growth will moderate as the market stabilises after reaching new adoption levels. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AgTech Market Synopsis
AgTech in China includes advanced agricultural technologies that improve productivity and efficiency. This encompasses tools such as drones, IoT devices, and automation systems, primarily utilised in modern farming practices. The China AgTech Market is expanding due to strong demand from commercial farms and agribusiness companies. Agricultural output reached 1.36 trillion USD in 2022, underscoring the sector's strength. Government initiatives like the 'Smart Agriculture Development Plan' further encourage technology adoption nationwide.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased adoption of precision farming technologies enhances crop yields. | Driver | High | Precision Farming Kits |
| Growing investment in IoT-enabled devices supports real-time data collection. | Driver | High | IoT-enabled Devices |
| Expansion of commercial farms creates demand for automation tools. | Opportunity | High | Farm Automation Tools |
| Emerging online platforms provide access to AgTech solutions for smaller farms. | Opportunity | Medium | Online Platforms |
| High costs of advanced technology can limit accessibility for small farmers. | Restraint | High | Drones & Robotics |
| Market saturation in certain regions may slow growth in technology adoption. | Restraint | Medium | Sensor-based Control |
| Limited access to financing options hampers investment in AgTech. | Challenge | High | Commercial Farms |
| Rapid technological advancements create a skills gap among farmers. | Challenge | Medium | Agribusiness Companies |
Evaluation of Drivers in China AgTech Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing investment in precision farming tools increases efficiency and yields. | Precision Farming Kits | Over 50% of farms in China are adopting precision farming technologies. |
| Rising demand for IoT-enabled devices enhances real-time data collection capabilities. | IoT-enabled Devices | The IoT-enabled devices market in agriculture is projected to grow significantly by 2025. |
| Commercial farms are expanding their operations, driving demand for automation. | Farm Automation Tools | China has over 300 million hectares of arable land, necessitating advanced farming technologies. |
| Government initiatives support the adoption of advanced agricultural technologies. | Drones & Robotics | The number of commercial farms using drones has increased by 30% since 2021. |
| Increased awareness of sustainable practices promotes technology integration. | Greenhouse Controllers | The 'Greenhouse Technology Promotion Program' supports sustainable farming practices. |
Market growth for AgTech in China is driven by increasing demand from commercial farms and agribusiness companies. The agricultural output reached 1.36 trillion USD in 2022, leading to greater investment in technology. More than 50% of farms are now implementing precision farming technologies, boosting productivity. In addition, the number of commercial farms using drones has risen by 30% since 2021, indicating a shift towards advanced monitoring techniques.
Evaluation of Restraints in China AgTech Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced technology limit access for smaller farms. | Drones & Robotics | The average farm size in China is about 0.6 hectares, pushing for automation. |
| Market saturation in some regions may hinder further growth. | Sensor-based Control | The adoption of sensor-based control systems has reached high levels, limiting new buyers. |
| Limited financing options restrict investment in AgTech solutions. | Commercial Farms | Many small farmers struggle to secure funding for technology upgrades. |
| Skills gap among farmers affects the adoption of new technologies. | Agribusiness Companies | Rapid advancements in technology create a need for specialised training. |
| Regulatory hurdles slow down the approval of new agricultural technologies. | IoT-enabled Devices | Compliance with ISO 9001 standards can delay product launches. |
China AgTech Market Challenges
The China AgTech market encounters several practical issues, starting with the high cost of advanced technologies. Buyers face challenges with the steep prices of precision farming technologies, which can surpass 100,000 USD per unit, limiting investment opportunities for smaller farms. Skills shortages are also common, as only 30% of farmers have received training in modern AgTech, resulting in underutilisation of available tools. The costs of agricultural inputs have surged by 15% this year, squeezing profit margins for producers. Furthermore, supply chain delays in technology delivery can extend project timelines by up to six months, negatively impacting operational efficiency for farms across the country.
Trends in the China AgTech Market
Buyers and suppliers in the China AgTech Market are adjusting to the following trends.
- Shift Towards Precision Farming Technologies: China is increasingly adopting precision farming technologies, with over 50% of farms implementing these solutions. The average yield increase from using AgTech is estimated at 15% per crop cycle, driving further investment.
- Growth of IoT in Agriculture: The IoT-enabled devices market is set to expand, focusing on real-time data collection. In 2023, the government emphasised the importance of IoT in agriculture through various initiatives.
- Expansion of Smart Farming Units: China has established over 1,000 smart farming units nationwide, promoting modern practices. This expansion is expected to enhance productivity and efficiency in the agricultural sector.
- Increased Use of Drones for Crop Monitoring: Drones are now used in over 15 provinces for crop monitoring and pest control. The number of commercial farms using drones increased by 30% since 2021, reflecting growing acceptance.
Investment Opportunities in the China AgTech Market
Several openings in the China AgTech Market merit attention from investors.
- Investment in Automation Tools: Commercial farms in China are seeking automation tools to improve productivity. Agricultural technology investment reached 10 billion USD in 2022, indicating strong market potential.
- Supply of Precision Farming Kits: With over 50% of farms adopting precision farming technologies, there is a chance to provide precision farming kits. Targeting commercial farms can yield substantial returns.
- Development of Online Platforms for AgTech: The rise of online platforms offers a chance to reach smaller farms. This segment is growing rapidly, with a projected growth rate of 6.8% by 2032.
- Expansion of Greenhouse Technologies: The 'Greenhouse Technology Promotion Program' supports sustainable practices, creating demand for greenhouse controllers. Investing in this area can cater to horticulture enterprises across multiple provinces.
Government Initiatives in the China AgTech Market
The 'Smart Agriculture Development Plan', launched in 2023, aims to improve agricultural productivity through technology with a budget of 2 billion USD. This initiative encourages the adoption of advanced agricultural technologies among producers, ensuring they meet modern farming standards. Additionally, the 'National Modern Agriculture Development Plan' updated in 2022 includes targets for technology adoption in rural areas, promoting innovation and efficiency.
The 'Agricultural Technology Innovation Program' initiated in 2020 supports research and development in AgTech, providing funding for innovative projects. The 'Greenhouse Technology Promotion Program' established in 2022 encourages sustainable practices in horticulture, helping buyers access modern technologies.
Future Insight of the China AgTech Market
The China AgTech market is set to transform by 2032, driven by several key factors. The 'Smart Agriculture Development Plan' will facilitate greater technology integration across farms, while the agricultural sensor market is expected to experience significant growth. By 2025, over 300 million hectares of arable land will increasingly adopt precision farming technologies, leading to an average yield increase of 15% per crop cycle. The government's commitment to agricultural technology innovation, with an allocation of 2 billion USD in 2023, will further accelerate advancements in automation.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Product Type – Farm Automation Tools Dominated, Drones & Robotics Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Farm Automation Tools accounted for a 46% market share by product type in 2025. Farm Automation Tools command the largest market share as they are essential for enhancing operational efficiency in diverse farming practices. Their critical role in modernising over 50% of farms in China highlights their significance in boosting agricultural productivity. Drones & Robotics are set to record the highest CAGR in this split, 7.6% over 2026–2032. Drones & Robotics are experiencing remarkable growth, primarily due to their increasing use in aerial monitoring and crop management, with a notable 30% increase in commercial farms employing drones since 2021. This trend indicates a sustained shift towards advanced agricultural techniques that will further widen the lead of Farm Automation Tools. Suppliers should focus on developing advanced farm automation solutions to meet the rising demand from commercial farms.
By Technology Type – IoT-enabled Devices Dominated and Is Expected to Record the Fastest Growth
IoT-enabled Devices held a 39% share of the China AgTech Market by technology type in 2025. IoT-enabled Devices dominate the market share as they are critical for real-time data collection and analysis, which is increasingly vital for modern farming. The government's emphasis on IoT through various initiatives further solidifies its importance in agricultural practices. Its lead should widen, with a projected CAGR of 6.8% during 2026–2032, the highest in this split. The growth of IoT-enabled Devices is propelled by their dual role in both data collection and operational efficiency, ensuring that they remain at the forefront of agricultural technology advancements. This continued focus will likely widen their market lead. Buyers should invest in IoT-enabled solutions to optimise their farming operations and stay competitive.
By Distribution Channel – Direct Sales Dominated, Online Platforms Expected to Grow Fastest
In 2025, Direct Sales led the distribution channel split with a 45% share. Direct Sales dominates the distribution channels as it effectively reaches large agricultural enterprises that require tailored solutions. This method has established strong relationships with key stakeholders, ensuring a stable market share in the AgTech sector. Over 2026–2032, Online Platforms are expected to post the fastest growth, at a CAGR of 6.8%. Online Platforms are rapidly gaining popularity, particularly among smaller farms and individual users, by offering easier access to AgTech products. This shift towards digital sales channels signifies a notable change in how agricultural products are distributed, creating opportunities for Direct Sales to expand. Suppliers must enhance their online presence to capture the growing segment of buyers who prefer digital purchasing options.
By End User – Commercial Farms Dominated, Smart Farming Units Expected to Grow Fastest
The largest end user category in 2025 was Commercial Farms, with a 40% share of total revenue. Commercial Farms represent the largest market share as they are the primary users of AgTech for large-scale production, significantly influencing China's agricultural output. Their extensive operations require the integration of advanced technologies to maintain high productivity levels. The quickest growth will come from Smart Farming Units, forecast to expand at a CAGR of 7.0% between 2026 and 2032. Smart Farming Units are the fastest-growing segment, leveraging technology for innovative farming practices that align with modern agricultural trends. Their rapid adoption reflects a broader movement towards smarter, more efficient farming solutions, which will continue to support the growth of Commercial Farms. Suppliers should tailor their offerings to meet the specific needs of smart farming units to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AgTech Market Outlook
- Market Size of China AgTech Market, 2025
- Forecast of China AgTech Market, 2032
- Historical Data and Forecast of China AgTech Revenues & Volume for the Period 2022 - 2032F
- China AgTech Market Trend Evolution
- China AgTech Market Drivers and Challenges
- China AgTech Price Trends
- China AgTech Porter's Five Forces
- China AgTech Industry Life Cycle
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Farm Automation Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Precision Farming Kits for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Drones & Robotics for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Greenhouse Controllers for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By IoT-enabled Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By GPS & GIS for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Aerial Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Sensor-based Control for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Tech Solution Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Agricultural Equipment Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Commercial Farms for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Agribusiness Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Smart Farming Units for the Period 2022 - 2032F
- Historical Data and Forecast of China AgTech Market Revenues & Volume By Horticulture Enterprises for the Period 2022 - 2032F
- China AgTech Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China AgTech Top Companies Market Share
- China AgTech Competitive Benchmarking By Technical and Operational Parameters
- China AgTech Company Profiles
- China AgTech Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Product Type
- Farm Automation Tools
- Precision Farming Kits
- Drones & Robotics
- Greenhouse Controllers
By Technology Type
- IoT-enabled Devices
- GPS & GIS
- Aerial Monitoring
- Sensor-based Control
By Distribution Channel
- Direct Sales
- Online Platforms
- Tech Solution Providers
- Agricultural Equipment Suppliers
By End User
- Commercial Farms
- Agribusiness Companies
- Smart Farming Units
- Horticulture Enterprises































