China AI Chip Packaging Market Size & Growth Rate
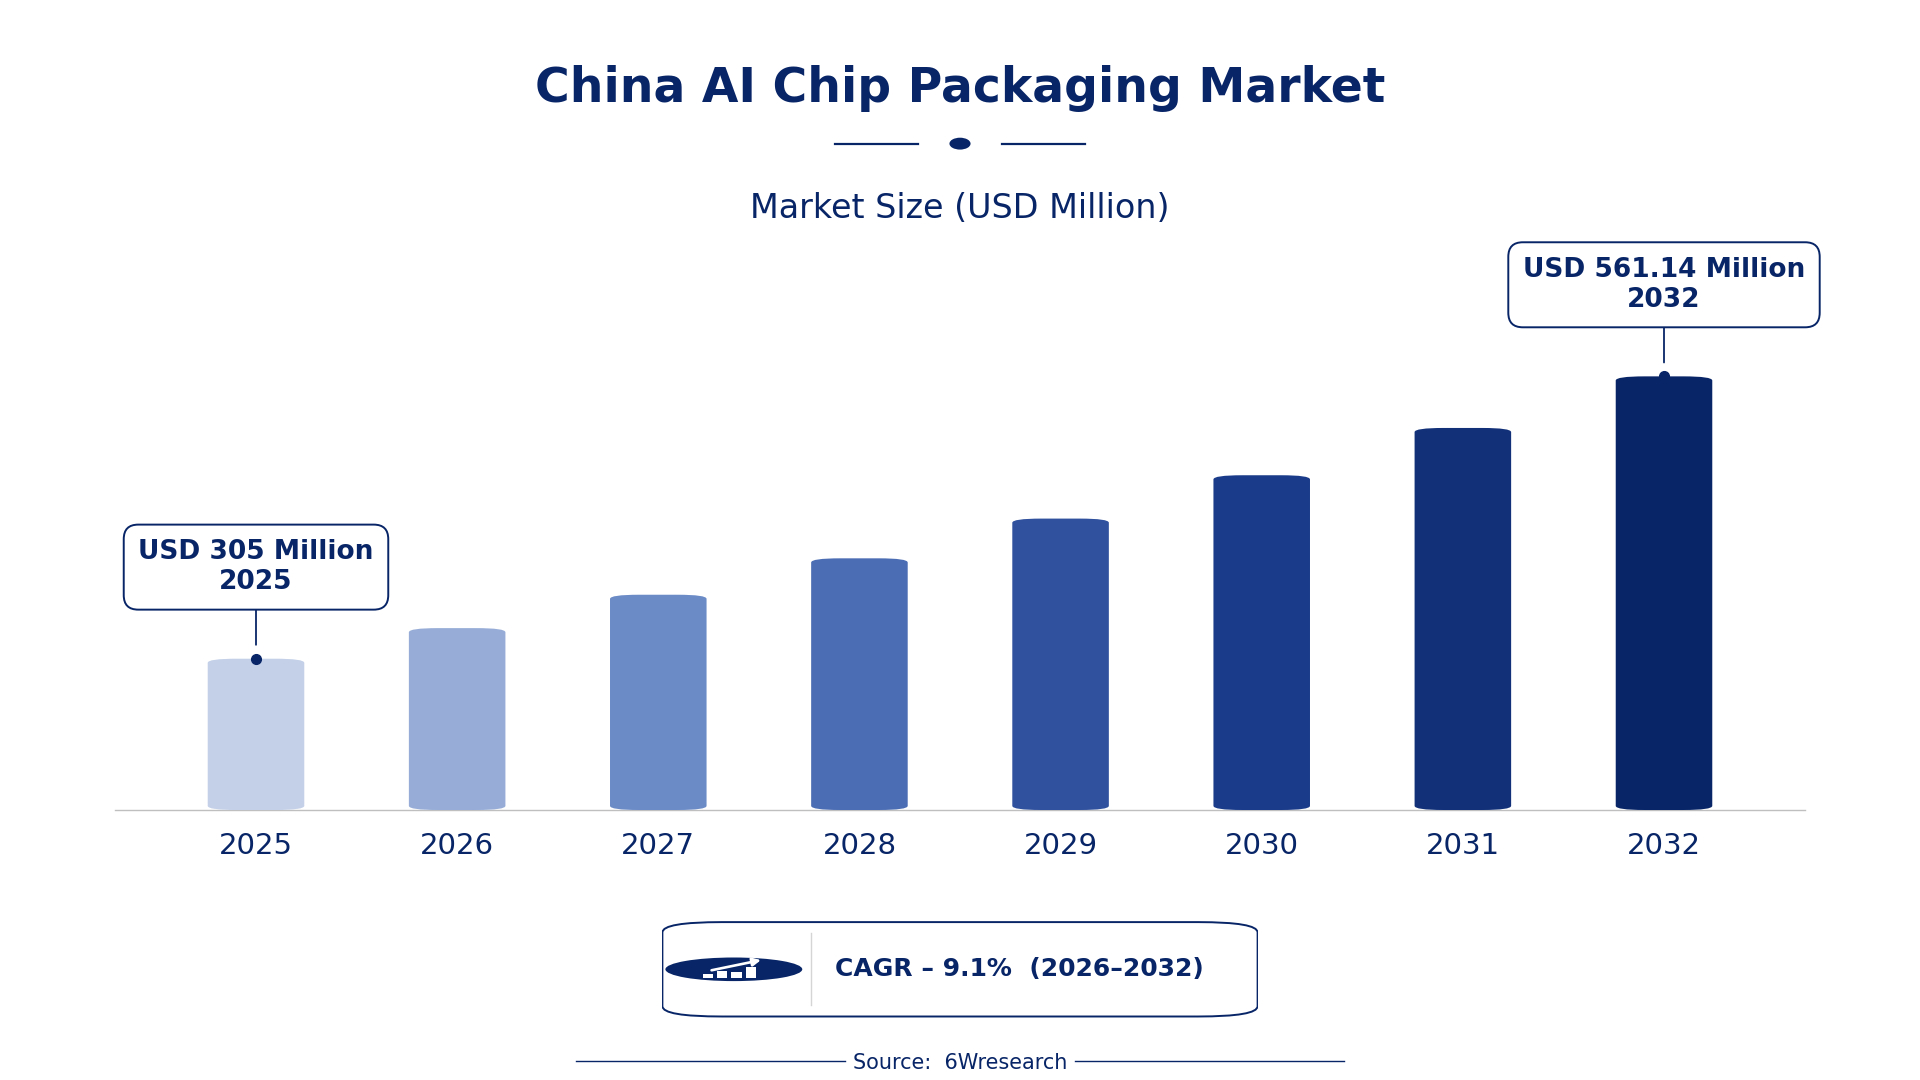
According to 6Wresearch internal database and industry insights, the China AI Chip Packaging Market was valued at USD 305.0 million in 2025 and is projected to reach USD 561.14 million by 2032, growing at a CAGR of approximately 9.1% during 2026–2032.
China AI Chip Packaging Market Highlights
| Report Metric | Details |
| Report Name | China AI Chip Packaging Market |
| Market Size 2025 | USD 305.0 million |
| Market Size 2032 | USD 561.14 million |
| Absolute Growth 2025–2032 | USD 256.14 million |
| CAGR 2026–2032 | 9.1% |
| Peak Annual Growth | 11.2% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Packaging Type, 2025 | Flip Chip Packaging (40% share) |
| Leading Material Used, 2025 | Organic Substrate (37% share) |
| Leading Distribution Channel, 2025 | Semiconductor Distributors (51% share) |
| Leading End User, 2025 | AI Chip Manufacturers (52% share) |
| Fastest-Growing Packaging Type | Fan-Out Packaging (10.5% CAGR) |
| Fastest-Growing Material Used | Epoxy Mold Compound (10.7% CAGR) |
| Fastest-Growing Distribution Channel | OEM Direct Sales (11.1% CAGR) |
| Fastest-Growing End User | High-Performance Computing (10.3% CAGR) |
| Growing Sector | High-Performance Computing |
| Key End Users | AI Chip Manufacturers, High-Performance Computing, Data Center Operators, Edge Device Producers |
China AI Chip Packaging Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
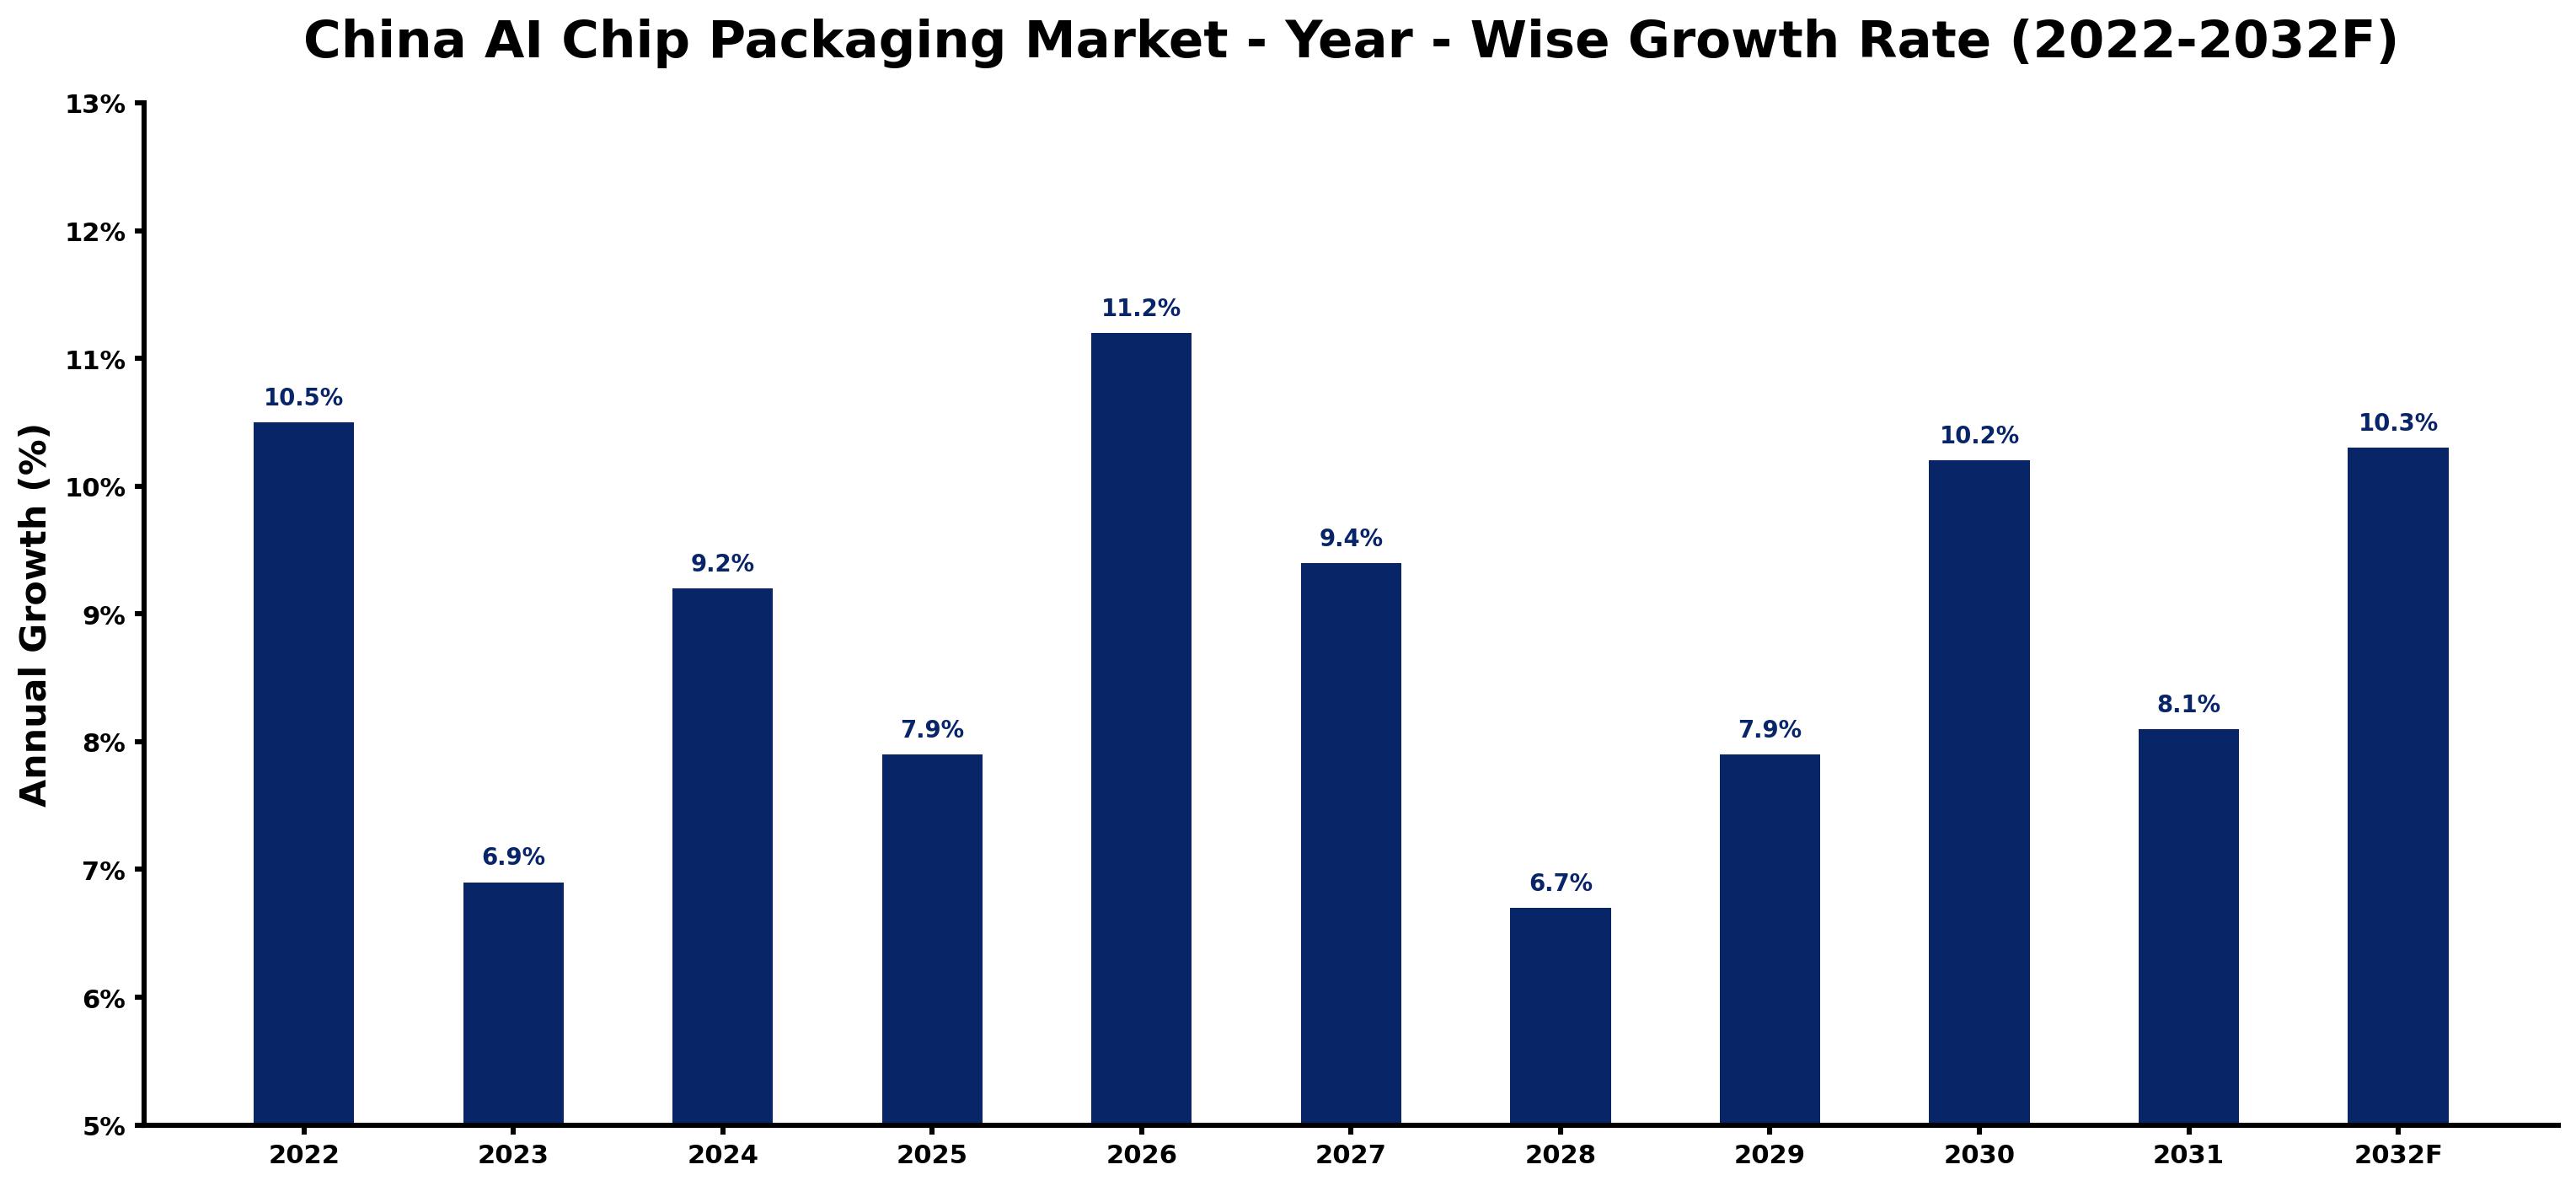
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 10.5 | The market experienced strong demand from AI chip manufacturers and data centers. |
| 2023 | 6.9 | Growth slowed due to supply chain disruptions affecting semiconductor production. |
| 2024 | 9.2 | Increased investment in high-performance computing spurred growth in packaging solutions. |
| 2025 | 7.9 | Demand from edge device producers contributed to a slower growth rate. |
| 2026 | 11.2 | The introduction of advanced packaging technologies is projected to boost market growth. |
| 2027 | 9.4 | A slowdown is anticipated as manufacturers adjust to new production standards. |
| 2028 | 6.7 | Continued demand for AI technologies is expected to lead to a further slowdown in growth. |
| 2029 | 7.9 | Growth will accelerate as requirements for high-performance computing increase. |
| 2030 | 10.2 | Demand for AI chips in data centers is projected to drive a resurgence in growth rates. |
| 2031 | 8.1 | Growth will slow as the market adapts to technological advancements. |
| 2032 | 10.3 | Rising demand for AI applications is expected to stimulate market growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AI Chip Packaging Market Synopsis
AI Chip Packaging in China covers the technology used to encase and protect AI chips, ensuring their reliability and performance. This market includes methods like flip chip and fan-out packaging, essential for high-performance computing and data centers. The China AI Chip Packaging Market is expanding due to increasing demand from domestic AI chip manufacturers and the semiconductor industry's growth. With over 1 trillion CNY in revenue generated in 2022, the market is set for further expansion, supported by advancements in packaging technologies and government initiatives for semiconductor development.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand for AI chips in data centers drives the need for advanced packaging solutions, enhancing performance and reliability. | Driver | High | Flip Chip Packaging |
| Technological advancements in packaging methods improve efficiency and reduce costs, attracting investment in the sector. | Driver | High | Fan-Out Packaging |
| The increasing number of AI chip manufacturers in the Yangtze River Delta region presents opportunities for local suppliers to meet demand. | Opportunity | High | Organic Substrate |
| The growing trend of high-performance computing creates a need for innovative packaging solutions, providing avenues for investment. | Opportunity | Medium | Epoxy Mold Compound |
| Regulatory compliance costs can exceed 200 million CNY, impacting producers' ability to launch new products. | Restraint | High | Wafer-Level Packaging |
| Supply chain disruptions can inflate material costs by 15%, affecting manufacturers' pricing strategies. | Restraint | Medium | Silicon Interposer |
| Skills shortages in advanced packaging techniques complicate production processes, delaying project timelines. | Challenge | High | Solder Bumps |
| Technological limitations in packaging methods hinder efficiency, leading to longer production cycles and delivery times. | Challenge | Medium | 2.5D/3D Packaging |
Evaluation of Drivers in China AI Chip Packaging Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing demand for AI technologies in data centers increases the need for efficient packaging solutions. | Fan-Out Packaging | The average installed base of AI chips in data centers in China is expected to exceed 10 million by 2025. |
| Investment in semiconductor manufacturing capabilities boosts production capacity. | Organic Substrate | The National Integrated Circuit Industry Investment Fund has a budget of 140 billion CNY to support development. |
| The push for high-performance computing drives the adoption of advanced packaging methods. | Flip Chip Packaging | The demand for high-performance computing is growing with a CAGR of 15% in China. |
| Technological advancements in AI chip packaging improve performance and efficiency. | 2.5D/3D Packaging | The Shanghai region is known for its advanced packaging technologies and facilities. |
| Increased collaboration between manufacturers and research institutions drives innovation. | Wafer-Level Packaging | The Ministry of Industry and Information Technology promotes the 'New Generation Artificial Intelligence Development Plan'. |
Expansion of the AI Chip Packaging market in China is backed by rising demand from AI chip manufacturers and data centers. The average installed base of AI chips in data centers is expected to exceed 10 million by 2025, driving the need for efficient packaging solutions. The National Integrated Circuit Industry Investment Fund's 140 billion CNY budget supports production capabilities, enhancing the semiconductor industry. Demand for high-performance computing is increasing, further boosting the adoption of advanced packaging methods. Technological advancements in packaging improve performance, particularly in the Shanghai region known for its facilities.
Evaluation of Restraints in China AI Chip Packaging Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Quality control issues in packaging processes can lead to production delays. | Flip Chip Packaging | In 2022, the semiconductor industry faced challenges in maintaining consistent quality standards. |
| Limited access to advanced materials restricts innovation in packaging technologies. | Epoxy Mold Compound | Supply chain disruptions have affected the availability of key materials for packaging. |
| Technological integration challenges hinder the adoption of new packaging methods. | 2.5D/3D Packaging | Manufacturers struggle to adapt to rapidly evolving technologies in the market. |
| High production costs associated with advanced packaging methods can limit profitability. | Fan-Out Packaging | The cost of implementing new technologies remains a barrier for many manufacturers. |
| Competition from international markets pressures local producers to innovate continuously. | Wafer-Level Packaging | Global competitors are advancing their packaging technologies, increasing market pressure. |
China AI Chip Packaging Market Challenges
The China AI Chip Packaging Market encounters several practical issues, starting with regulatory compliance costs that can reach up to 200 million CNY for producers, which delays product launches and raises prices for buyers. Technological constraints in packaging methods limit efficiency, resulting in longer production cycles that can extend delivery times by 30%. Supply chain disruptions, especially in sourcing materials, can inflate costs by 15% for manufacturers, ultimately pushing buyers to seek alternative suppliers. Skills shortages in advanced packaging techniques complicate matters, as producers struggle to fill roles, leading to project delays and lost revenue.
Trends in the China AI Chip Packaging Market
Below mentioned are some of the trends shaping the China AI Chip Packaging Market growth.
- Shift from Traditional to Advanced Packaging Methods: Since 2021, the industry has experienced a shift towards advanced packaging methods like fan-out packaging. This transition is driven by the need for improved thermal management and efficiency, with the Shanghai region at the forefront of technology adoption.
- Emergence of AI Chip Innovation Programs: In 2021, the Ministry of Science and Technology launched the AI Chip Innovation Program, focusing on R&D funding for domestic manufacturers. This initiative aims to boost China's competitiveness in the global market, with a budget of 50 billion CNY allocated for the program.
- Growing Importance of Environmental Sustainability in Packaging: The trend towards sustainable packaging materials has gained momentum since 2022, with many manufacturers exploring eco-friendly options. The National Standard for Semiconductor Packaging promotes sustainable practices, impacting over 100 manufacturers in the industry.
- Increased Collaboration Between Industry and Academia: Since 2023, partnerships between universities and semiconductor companies have intensified, focusing on innovative packaging solutions. This collaboration has resulted in the development of new materials, with research funding exceeding 20 billion CNY.
Investment Opportunities in the China AI Chip Packaging Market
The following opportunities in the China AI Chip Packaging Market pair current demand with a clear way in.
- Investment in Semiconductor Manufacturing Facilities: The Yangtze River Delta region is a prime location for investing in semiconductor manufacturing facilities, with 1 trillion CNY in revenue generated in 2022. Establishing local partnerships can facilitate market entry.
- Growing Demand from AI Chip Manufacturers: AI Chip Manufacturers are increasingly seeking advanced packaging solutions, with the market projected to reach 1.5 billion units by 2025. Collaborating with local distributors can improve supply chain efficiency.
- Funding for Research and Development in AI Technologies: With the National AI Development Plan prioritising AI chip research, funding opportunities are abundant, exceeding 50 billion CNY. Engaging with government agencies can provide access to these resources.
- Expansion of High-Performance Computing Facilities: The demand for high-performance computing is projected to grow significantly, with a CAGR of 15%. Investing in advanced packaging solutions tailored for data centers can capture this emerging market.
Government Initiatives in the China AI Chip Packaging Market
In 2023, the National AI Development Plan was revised to prioritise AI chip research and development, aiming for global leadership by 2030. This plan builds on the 2021 '14th Five-Year Plan for National Economic and Social Development', which emphasised semiconductor self-sufficiency. These measures support domestic manufacturers, ensuring they meet international standards and compete effectively in the global market.
The Semiconductor Industry Development Action Plan, overseen by the Ministry of Industry and Information Technology, funds local manufacturing capabilities. This plan, introduced in 2020, has approved over 50 billion CNY in subsidies for technology upgrades, benefiting numerous semiconductor companies and boosting their production capacities. Additionally, the AI Chip Innovation Program initiated in 2021 focuses on R&D funding, further supporting domestic manufacturers in their technological advancements.
Future Insight of the China AI Chip Packaging Market
The China AI Chip Packaging Market will undergo substantial changes by 2032, driven by the '14th Five-Year Plan for the Development of the Semiconductor Industry' which aims to enhance domestic production capabilities. The National Integrated Circuit Industry Investment Fund's budget of 140 billion CNY will facilitate advancements in semiconductor technologies, benefiting both producers and buyers. With the average installed base of AI chips in data centres expected to exceed 10 million by 2025, demand for efficient packaging solutions will increase. The government's backing for AI research through various funding programs will further stimulate innovation in this sector.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Packaging Type – Flip Chip Packaging Dominated, Fan-Out Packaging Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Flip Chip Packaging accounted for a 40% market share by packaging type in 2025. Flip Chip Packaging holds the largest share as it is critical for establishing high-density interconnections in AI chips. This method is predominantly used in the Yangtze River Delta region, which is a key area for semiconductor packaging. The quickest growth will come from Fan-Out Packaging, forecast to expand at a CAGR of 10.5% between 2026 and 2032. Fan-Out Packaging is experiencing rapid growth due to its efficiency in optimising space and thermal management, which are crucial for AI applications. The increasing demand for compact solutions in the semiconductor sector is driving this trend. This suggests that suppliers must focus on advancing both Flip Chip and Fan-Out Packaging technologies to meet market needs.
By Material Used – Organic Substrate Dominated, Epoxy Mold Compound Expected to Grow Fastest
In 2025, Organic Substrate led the material used split with a 37% share. Organic Substrate dominates the market share as it provides essential electrical insulation and mechanical support for AI chips. Its widespread use among AI chip manufacturers underscores its importance in the semiconductor supply chain. Epoxy Mold Compound is projected to grow fastest, at a CAGR of 10.7% during 2026–2032. Epoxy Mold Compound is growing quickly due to its effectiveness in encapsulating chips, protecting them from environmental factors. The rising focus on chip reliability in high-performance computing applications is propelling this growth. Suppliers should prioritise the development of Organic Substrate and Epoxy Mold Compound to capture the increasing demand in the AI chip packaging market.
By Distribution Channel – Semiconductor Distributors Dominated, OEM Direct Sales Expected to Grow Fastest
Semiconductor Distributors took a 51% share of distribution channel in 2025, more than any other category. Semiconductor Distributors lead the market share because they are essential to the supply chain for AI chip packaging materials. Their extensive networks facilitate efficient distribution and access to necessary components for manufacturers. Over 2026–2032, OEM Direct Sales is expected to post the fastest growth, at a CAGR of 11.1%. OEM Direct Sales is the fastest-growing channel, propelled by manufacturers seeking to provide customised solutions directly to OEMs. This trend underscores the rising demand for tailored packaging solutions in the semiconductor industry. This indicates that suppliers should enhance their direct sales strategies to effectively serve OEMs and capitalise on this growth opportunity.
By End User – AI Chip Manufacturers Dominated, High-Performance Computing Expected to Grow Fastest
With a 52% revenue share in 2025, AI Chip Manufacturers was the largest end user category. AI Chip Manufacturers represent the largest share as they are the primary end users of AI chip packaging solutions. Their continuous investment in advanced technologies drives the demand for reliable packaging methods. High-Performance Computing is set to record the highest CAGR in this split, 10.3% over 2026–2032. High-Performance Computing is the fastest-growing end user segment, requiring advanced packaging for optimal chip performance. The surge in demand for AI technologies in computing applications is a key factor in this growth. This indicates that suppliers should focus on developing packaging solutions tailored to the needs of AI Chip Manufacturers and High-Performance Computing applications.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AI Chip Packaging Market Outlook
- Market Size of China AI Chip Packaging Market, 2025
- Forecast of China AI Chip Packaging Market, 2032
- Historical Data and Forecast of China AI Chip Packaging Revenues & Volume for the Period 2022 - 2032F
- China AI Chip Packaging Market Trend Evolution
- China AI Chip Packaging Market Drivers and Challenges
- China AI Chip Packaging Price Trends
- China AI Chip Packaging Porter's Five Forces
- China AI Chip Packaging Industry Life Cycle
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Packaging Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Flip Chip Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Fan-Out Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By 2.5D/3D Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Wafer-Level Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Material Used for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Organic Substrate for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Epoxy Mold Compound for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Silicon Interposer for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Solder Bumps for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Semiconductor Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By OEM Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Online Tech Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Specialty Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By AI Chip Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By High-Performance Computing for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Data Center Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chip Packaging Market Revenues & Volume By Edge Device Producers for the Period 2022 - 2032F
- China AI Chip Packaging Import Export Trade Statistics
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China AI Chip Packaging Top Companies Market Share
- China AI Chip Packaging Competitive Benchmarking By Technical and Operational Parameters
- China AI Chip Packaging Company Profiles
- China AI Chip Packaging Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Packaging Type
- Flip Chip Packaging
- Fan-Out Packaging
- 2.5D/3D Packaging
- Wafer-Level Packaging
By Material Used
- Organic Substrate
- Epoxy Mold Compound
- Silicon Interposer
- Solder Bumps
By Distribution Channel
- Semiconductor Distributors
- OEM Direct Sales
- Online Tech Platforms
- Specialty Stores
By End User
- AI Chip Manufacturers
- High-Performance Computing
- Data Center Operators
- Edge Device Producers































