China AI Chips Market Size & Growth Rate
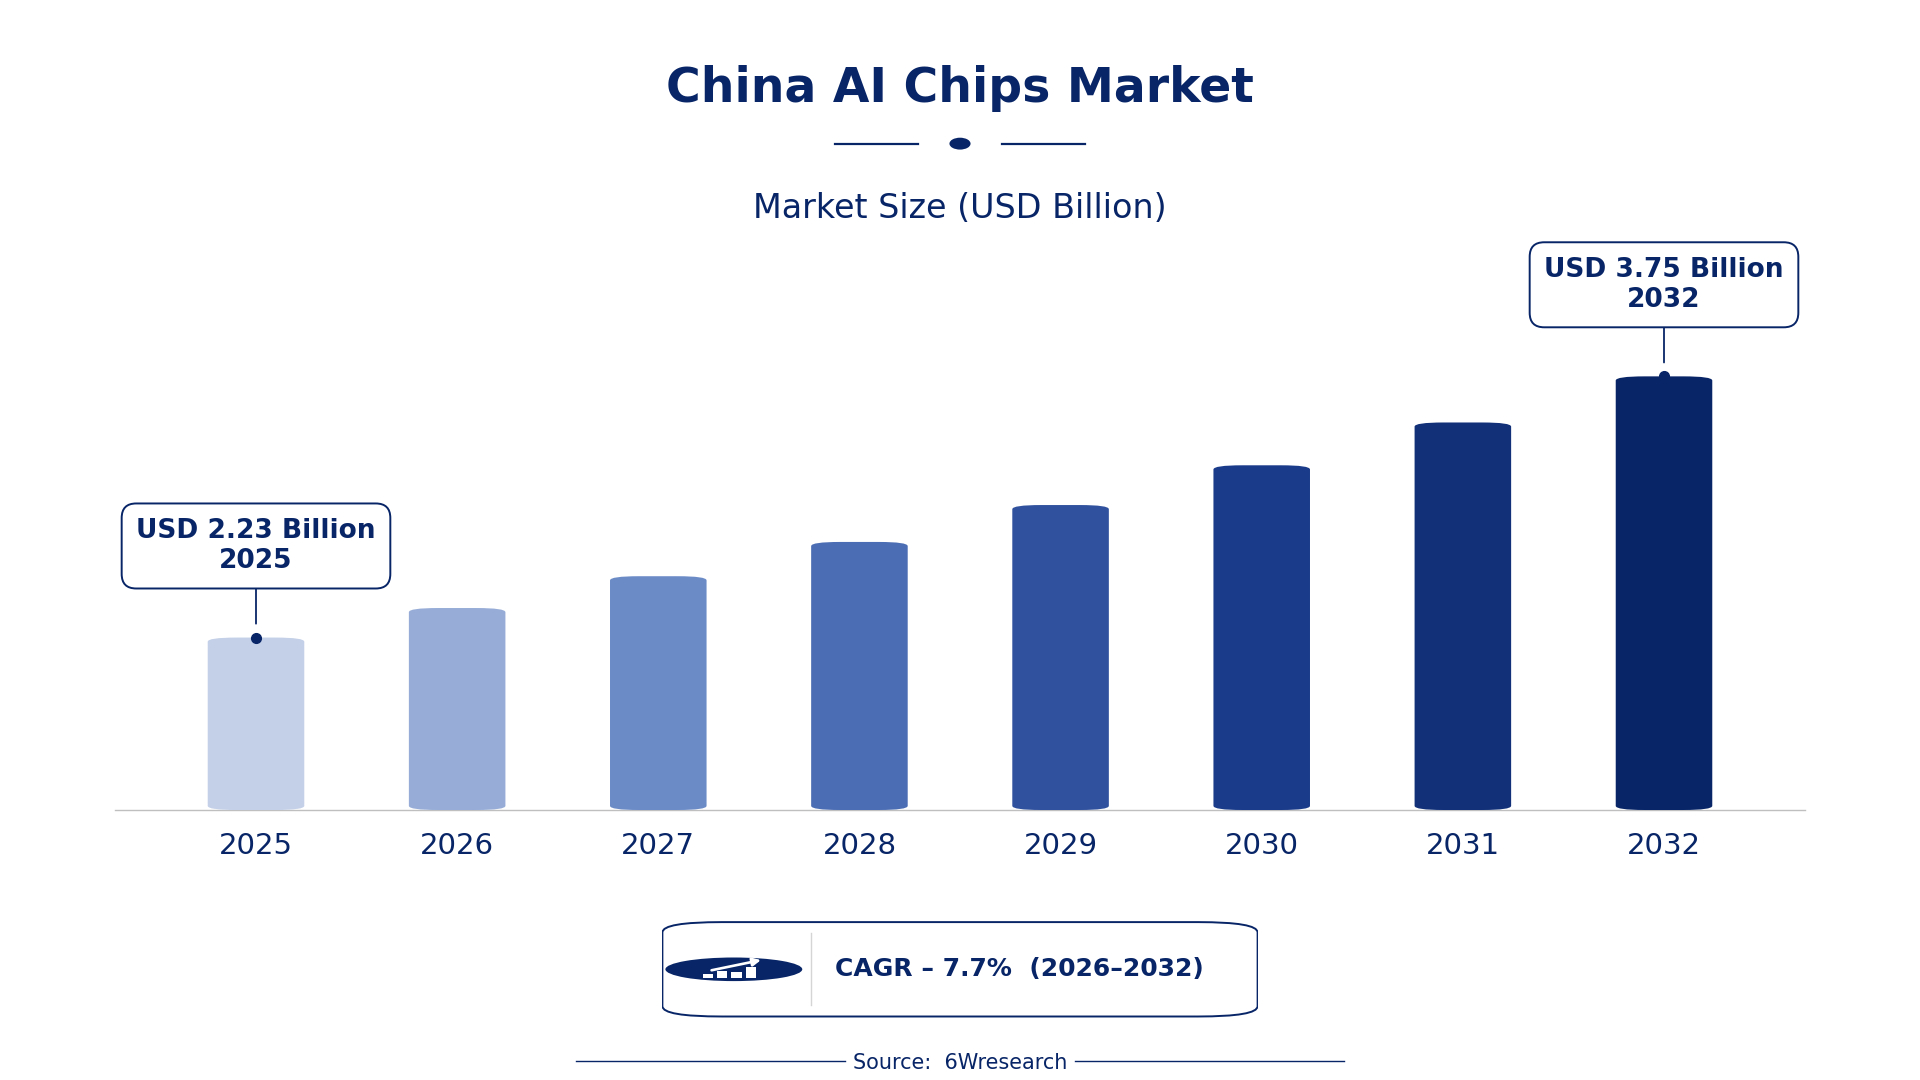
According to 6Wresearch internal database and industry insights, the China AI Chips Market was valued at USD 2.23 billion in 2025 and is projected to reach USD 3.75 billion by 2032, growing at a CAGR of approximately 7.7% during 2026–2032.
China AI Chips Market Highlights
| Report Metric | Details |
| Report Name | China AI Chips Market |
| Market Size 2025 | USD 2.23 billion |
| Market Size 2032 | USD 3.75 billion |
| Absolute Growth 2025–2032 | USD 1.52 billion |
| CAGR 2026–2032 | 7.7% |
| Peak Annual Growth | 10.2% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Chip Type, 2025 | GPUs (51% share) |
| Leading Application Area, 2025 | Model Training (38% share) |
| Leading Distribution Channel, 2025 | Tech OEMs (37% share) |
| Leading End User, 2025 | Cloud Computing Providers (35% share) |
| Fastest-Growing Chip Type | TPUs (10.4% CAGR) |
| Fastest-Growing Application Area | Edge AI (9.1% CAGR) |
| Fastest-Growing Distribution Channel | Online Platforms (10.0% CAGR) |
| Fastest-Growing End User | AI Research Labs (9.4% CAGR) |
| Growing Sector | Smart Manufacturing |
| Key End Users | AI Research Labs, Cloud Computing Providers, Smart Manufacturing Firms |
China AI Chips Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
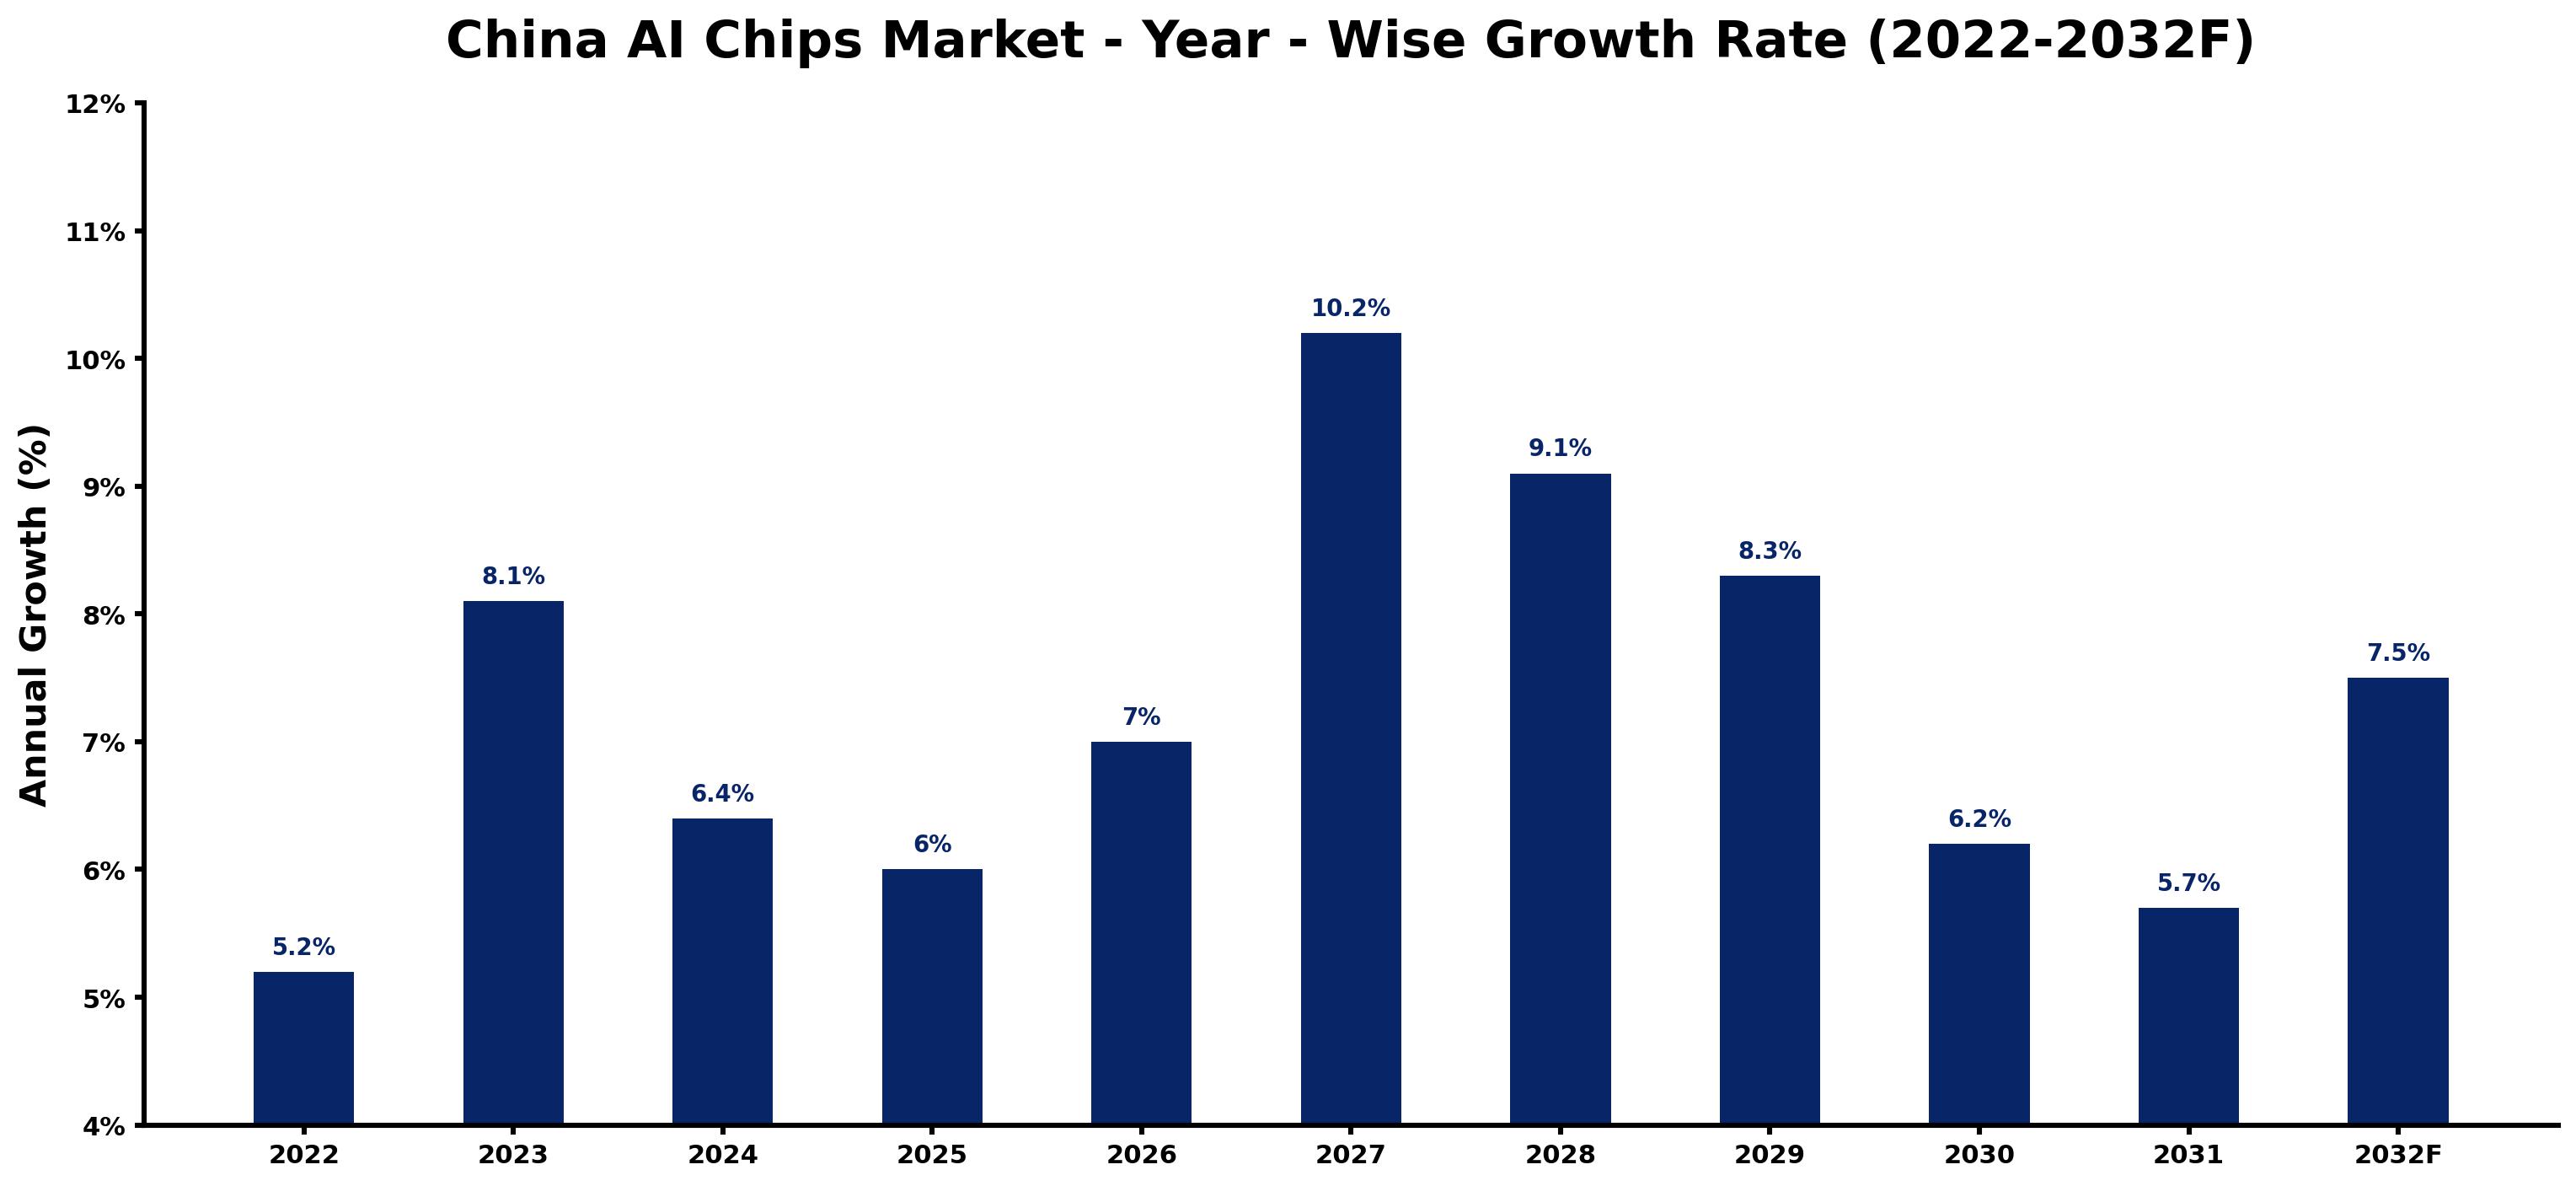
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.2 | The market experienced steady growth driven by the increasing number of AI research labs operational across major cities. |
| 2023 | 8.1 | Demand surged as the 'AI Innovation Action Plan' launched, promoting technology adoption across industries. |
| 2024 | 6.4 | Growth slowed due to a temporary reduction in investments in AI infrastructure. |
| 2025 | 6.0 | A slight slowdown in growth occurred as the market adjusted after rapid expansion. |
| 2026 | 7.0 | The market is expected to rebound with renewed investments in AI technologies. |
| 2027 | 10.2 | Peak growth is anticipated as AI applications expand in smart manufacturing and cloud services. |
| 2028 | 9.1 | Growth will decelerate as the market matures and competition intensifies. |
| 2029 | 8.3 | Demand remains strong but growth rates will continue to normalise as the market stabilises. |
| 2030 | 6.2 | A further slowdown is expected as the market approaches maturity in several segments. |
| 2031 | 5.7 | Growth will decelerate as the focus shifts towards efficiency and optimisation in production. |
| 2032 | 7.5 | The market is projected to experience a resurgence in demand due to advancements in AI applications. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AI Chips Market Synopsis
The China AI Chips Market encompasses specialized microprocessors designed to accelerate artificial intelligence tasks, essential for machine learning and data analysis. Valued at approximately 10 billion USD in 2022, the market thrives on demand from over 500 AI research labs and substantial investments in technology. The 'AI Innovation Action Plan' launched in 2023 further stimulates growth by promoting AI applications across various sectors. With a population exceeding 1.4 billion, the demand for AI applications is expected to rise, creating new opportunities for suppliers.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand from AI research labs for advanced processing capabilities. | Driver | High | AI Research Labs |
| Increasing integration of AI chips in smart manufacturing processes. | Driver | High | GPUs |
| Investment in AI technologies is projected to exceed 300 billion CNY by 2030. | Opportunity | High | GPUs |
| The rise of cloud computing providers needing efficient AI solutions. | Opportunity | High | Cloud Computing Providers |
| Limited domestic production capacity for specialized AI chips. | Restraint | High | GPUs |
| High dependency on foreign technology for advanced chip designs. | Restraint | High | GPUs |
| Challenges in scaling production to meet growing demand. | Challenge | Medium | GPUs |
| Competition from international manufacturers affecting local players. | Challenge | Medium | GPUs |
Evaluation of Drivers in China AI Chips Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in AI research and development. | AI Research Labs | Over 500 AI research labs are operational, driving demand for advanced processing solutions as they develop new applications. |
| Growing adoption of AI in smart manufacturing. | GPUs | AI chips improve automation and efficiency in production processes, leading to higher demand from manufacturers seeking competitive advantages. |
| Rising demand from cloud computing providers for AI capabilities. | Cloud Computing Providers | The installed base of AI chips in cloud computing centers reached 1 million units in 2023, indicating strong demand for enhanced AI services. |
| Expansion of the AI chip market due to government initiatives. | GPUs | The 'AI Innovation Action Plan' aims to boost AI technology development, increasing demand for chips across various sectors. |
| Increasing use of AI chips in telecommunications for 5G. | Telecom Infrastructure Firms | AI chips are integrated into 5G infrastructure to improve service delivery, driving demand from telecom companies looking to enhance network performance. |
Market growth in China for AI Chips rests on rising investments in AI research and development, with over 500 AI research labs operational. The installed base of AI chips in cloud computing centers reached 1 million units in 2023, indicating strong demand from cloud providers for enhanced services. The 'AI Innovation Action Plan' launched in 2023 aims to promote AI technology across industries, further driving demand for specialized solutions. AI chips are increasingly utilized in smart manufacturing, a key focus area for improving production efficiency.
Evaluation of Restraints in China AI Chips Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited domestic production capacity for advanced AI chips. | GPUs | Current production capabilities are insufficient to meet the growing demand for specialized chips, which hampers local manufacturers' ability to compete. |
| High dependency on foreign technology for advanced designs. | GPUs | This reliance can delay development and increase costs for local manufacturers, impacting their competitiveness in the market. |
| Challenges in scaling production to meet demand. | GPUs | Manufacturers face difficulties in ramping up production capacity quickly, which can lead to supply shortages and delayed deliveries. |
| Competition from international manufacturers affecting local market share. | GPUs | Foreign companies often have more advanced technologies and resources, making it challenging for local players to maintain market presence. |
| Regulatory hurdles in the semiconductor industry. | GPUs | Compliance with national standards can slow down production processes and increase operational costs for manufacturers. |
China AI Chips Market Challenges
The China AI Chips market still faces several challenges, starting with high costs for buyers due to reliance on imported materials, which can inflate prices by up to 30% for manufacturers. Competition remains fierce, as over 500 AI research labs drive rapid innovation, making it difficult for smaller suppliers to maintain market share and forcing them to reduce prices, which can shrink profit margins by 15%. Supply chain disruptions in Jiangsu and Guangdong provinces frequently delay deliveries, extending product wait times by several weeks for producers. Regulatory compliance poses additional challenges, as new standards from the National Standard for AI Chips require substantial investments in quality assurance, costing suppliers up to 10% of their annual revenue.
Trends in the China AI Chips Market
Below mentioned are some of the trends shaping the China AI Chips Market growth.
- Shift to AI-Driven Manufacturing: China is increasingly adopting AI chips in smart manufacturing processes, improving efficiency and productivity. In 2023, the government reported a notable rise in AI chip usage in this sector, reflecting a growing trend towards automation.
- Transition to Edge AI Processing: The demand for Edge AI chips is rising as companies seek localized processing solutions. In 2023, the market for Edge AI applications grew by 9.1%, indicating a shift towards decentralisation in AI technology.
- Integration of AI Chips in 5G Infrastructure: AI chips are being integrated into 5G telecom infrastructure to improve service delivery. In 2023, this integration was highlighted as a key development in enhancing network performance and user experience.
- Focus on AI Research and Development: The emphasis on AI research is intensifying, with over 500 labs operational across China. The government aims to increase funding for AI projects, reflecting a commitment to advancing technology and innovation.
Investment Opportunities in the China AI Chips Market
Several openings in the China AI Chips Market merit attention from investors.
- Supply AI Chips for Cloud Computing: With the installed base of AI chips in cloud centres reaching 1 million units, there is a notable supply opportunity. Cloud Computing Providers are actively seeking efficient AI solutions to enhance their services.
- Invest in AI Research and Development: Investment in AI technologies is expected to exceed 300 billion CNY by 2030, creating a gap in supply. AI Research Labs are looking for advanced chips to support their innovative projects.
- Provide AI Solutions for Smart Manufacturing: The government's focus on smart manufacturing presents a timely opportunity. With increasing automation, manufacturers are seeking AI chips to enhance production efficiency and competitiveness.
- Develop Edge AI Applications: The rising demand for localized AI processing creates opportunities for suppliers. Edge AI applications are projected to see substantial growth, requiring tailored chip solutions to meet specific needs.
Government Initiatives in the China AI Chips Market
The 'AI Innovation Action Plan' launched by the Ministry of Industry and Information Technology in 2023 aims to promote AI technology development across various sectors. This initiative encourages investment in AI research and the application of AI solutions in industries, benefiting producers and buyers alike. Additionally, the 'Made in China 2025' policy prioritises semiconductor production, aiming to reduce reliance on foreign technology and boost domestic capabilities, with a target of producing 70% of semiconductor needs domestically by 2025. The National Standard for AI Chips established in 2021 promotes quality and safety, ensuring that manufacturers meet essential benchmarks.
The Ministry of Industry and Information Technology oversees the approval and funding of projects under the 'AI Innovation Action Plan'. This includes financial support for AI startups, with funding up to 5 million CNY announced in 2023. The National Development and Reform Commission also plays a role in approving initiatives that enhance AI capabilities, ensuring that projects align with national goals and providing resources for innovation in the semiconductor sector. These measures enable producers to access funding and support for developing advanced AI technologies.
Future Insight of the China AI Chips Market
The China AI Chips market will undergo substantial change by 2032, with domestic production expected to fulfil 70% of semiconductor needs, thereby decreasing reliance on imports. The 'AI Innovation Action Plan' will channel increased funding into startups, fostering a more competitive landscape for both buyers and suppliers. An investment surpassing 300 billion CNY in AI technologies will propel advancements in chip design and manufacturing processes. The integration of AI chips into smart manufacturing systems will also create new applications, broadening their use across various industries.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Chip Type – GPUs Dominated, TPUs Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, the largest chip type category in 2025 was GPUs, with a 51% share of total revenue. GPUs command the largest share in China's AI chips market due to their widespread use in training and inference tasks across various industries. Their versatility makes them essential for sectors like cloud computing, which is experiencing a significant demand for AI capabilities. TPUs is set to record the highest CAGR in this split, 10.4% over 2026–2032. TPUs are growing rapidly as they are specifically designed for machine learning tasks, which are increasingly in demand. This targeted approach to performance in AI applications ensures that TPUs will continue to gain market share. Suppliers should focus on expanding their TPU product lines to meet the rising demand for specialised processing solutions.
By Application Area – Model Training Dominated, Edge AI Expected to Grow Fastest
Model Training took a 38% share of application area in 2025, more than any other category. Model Training commands the largest share as it is vital for developing AI models through extensive data processing, essential for numerous sectors. The increasing number of AI research labs in China further underscores the importance of this segment in the market. The quickest growth will come from Edge AI, forecast to expand at a CAGR of 9.1% between 2026 and 2032. Edge AI is the fastest-growing area, enabling localized processing at the edge of networks, which meets the rising need for real-time data analysis. The shift towards decentralised computing is a key factor propelling this segment's rapid growth. Buyers should invest in edge AI solutions to maintain competitiveness in the swiftly changing AI environment.
By Distribution Channel – Tech OEMs Dominated, Online Platforms Expected to Grow Fastest
In 2025, Tech OEMs led the distribution channel split with a 37% share. Tech OEMs lead the distribution channel as they are the primary suppliers of AI chips to various sectors, ensuring a consistent supply for manufacturers. Their established relationships with end-users solidify their dominant position in the market. Online Platforms are projected to grow fastest, at a CAGR of 10.0% during 2026–2032. Online Platforms are experiencing significant growth by offering convenient access to AI chips through e-commerce, appealing to a tech-savvy customer base. The shift towards digital purchasing is driving this segment's rapid expansion. Suppliers need to enhance their online strategies to reach a wider audience and adapt to changing consumer purchasing behaviours.
By End User – Cloud Computing Providers Dominated, AI Research Labs Expected to Grow Fastest
Cloud Computing Providers accounted for a 35% market share by end user in 2025. Cloud Computing Providers hold the largest share of the end-user segment, relying heavily on AI chips to deliver crucial services and infrastructure. The installed base of AI chips in cloud computing centres, which reached 1 million units, underscores their importance in the market. Over 2026–2032, AI Research Labs are expected to post the fastest growth, at a CAGR of 9.4%. AI Research Labs are the fastest-growing end-user group, propelled by their increasing demand for AI chips for research and development purposes. The rise in AI research initiatives across China is significantly driving this segment's growth. Suppliers should tailor their offerings to meet the specific needs of AI research labs to capitalise on the growth opportunities in this segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AI Chips Market Outlook
- Market Size of China AI Chips Market, 2025
- Forecast of China AI Chips Market, 2032
- Historical Data and Forecast of China AI Chips Revenues & Volume for the Period 2022 - 2032F
- China AI Chips Market Trend Evolution
- China AI Chips Market Drivers and Challenges
- China AI Chips Price Trends
- China AI Chips Porter's Five Forces
- China AI Chips Industry Life Cycle
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Chip Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By GPUs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By TPUs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By ASICs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By FPGAs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Model Training for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Neural Network Inference for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Edge AI for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Custom AI Acceleration for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Tech OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Semiconductor Retailers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By AI Research Labs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Cloud Computing Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Robotics & IoT Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Chips Market Revenues & Volume By Telecom Infrastructure Firms for the Period 2022 - 2032F
- China AI Chips Import Export Trade Statistics
- Market Opportunity Assessment By Chip Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China AI Chips Top Companies Market Share
- China AI Chips Competitive Benchmarking By Technical and Operational Parameters
- China AI Chips Company Profiles
- China AI Chips Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Chip Type
- GPUs
- TPUs
- ASICs
- FPGAs
By Application Area
- Model Training
- Neural Network Inference
- Edge AI
- Custom AI Acceleration
By Distribution Channel
- Tech OEMs
- Online Platforms
- Semiconductor Retailers
- Direct Sales
By End User
- AI Research Labs
- Cloud Computing Providers
- Robotics & IoT Manufacturers
- Telecom Infrastructure Firms































