China AI Cloud Services Market Size & Growth Rate
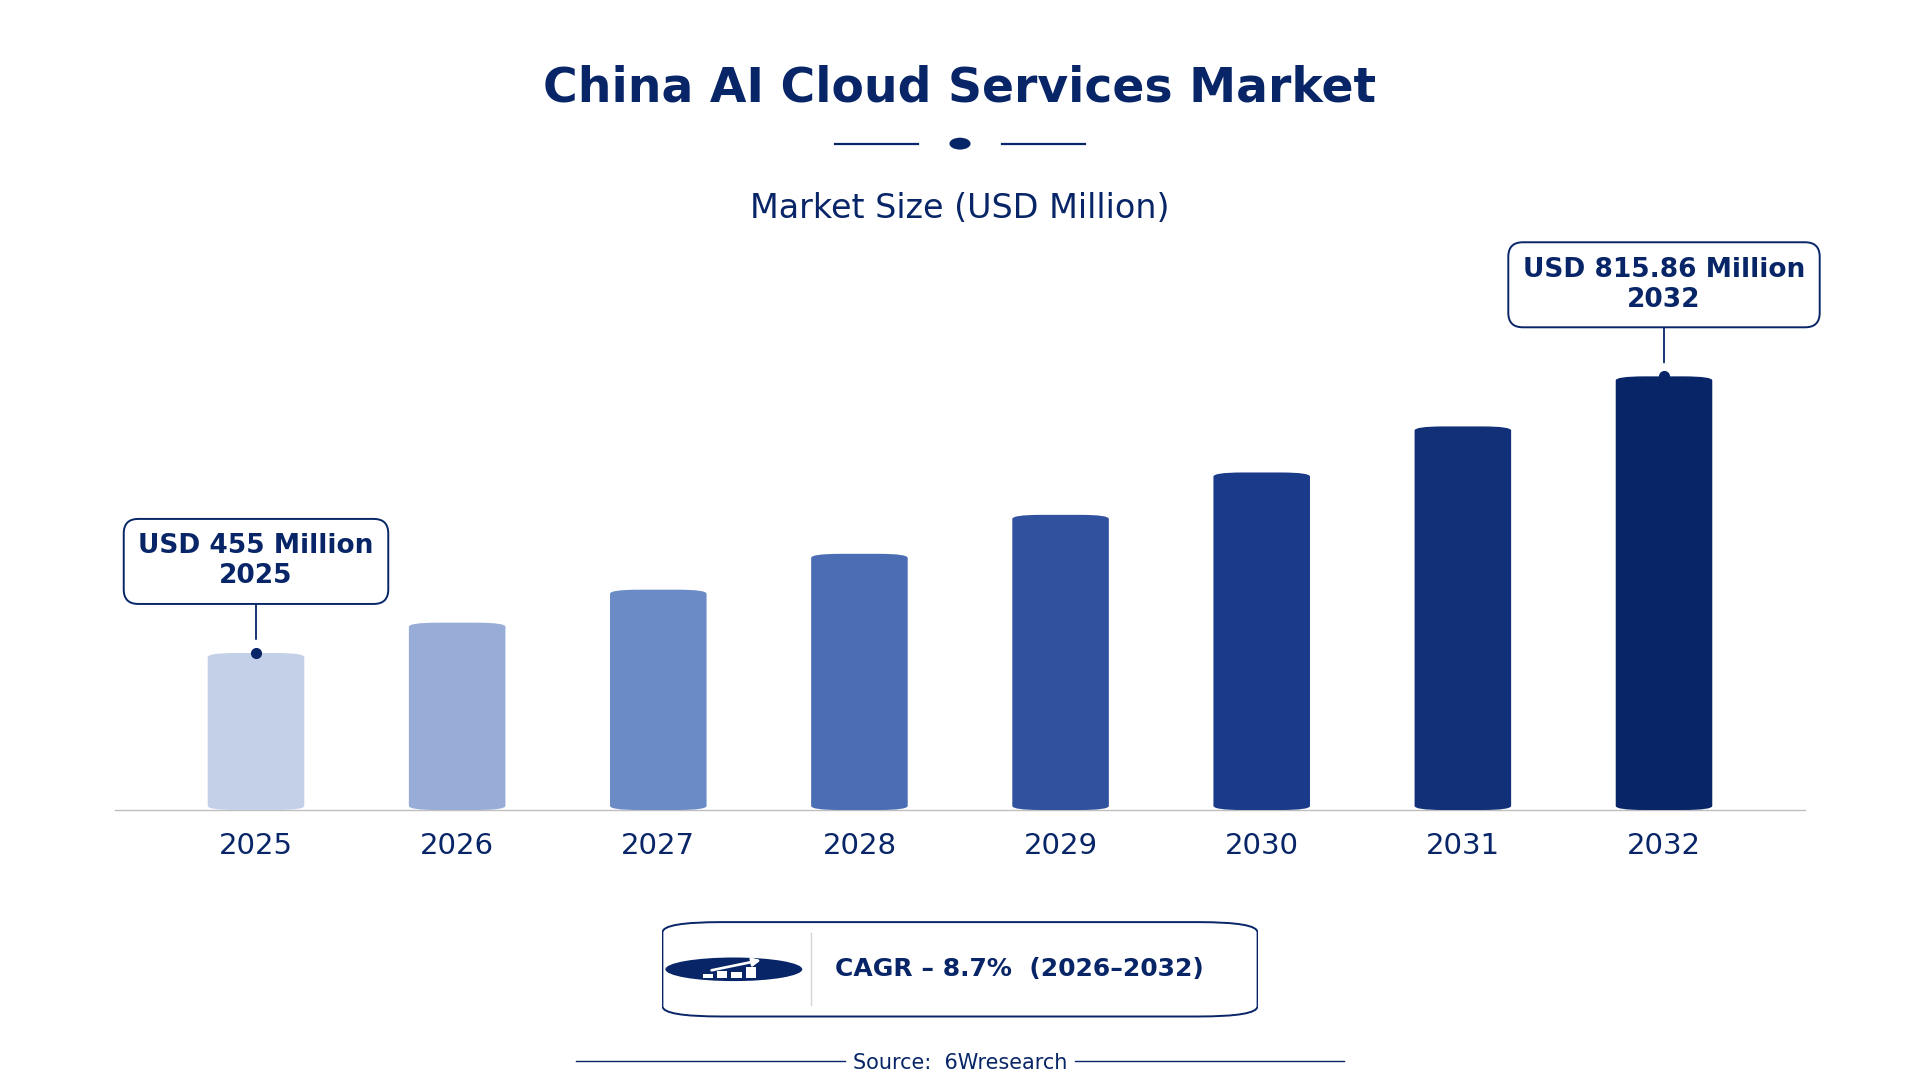
According to 6Wresearch internal database and industry insights, the China AI Cloud Services Market was valued at USD 455.0 million in 2025 and is projected to reach USD 815.86 million by 2032, growing at a CAGR of approximately 8.7% during 2026–2032.
China AI Cloud Services Market Highlights
| Report Metric | Details |
| Report Name | China AI Cloud Services Market |
| Market Size 2025 | USD 455.0 million |
| Market Size 2032 | USD 815.86 million |
| Absolute Growth 2025–2032 | USD 360.86 million |
| CAGR 2026–2032 | 8.7% |
| Peak Annual Growth | 10.4% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Service Type, 2025 | AI-as-a-Service (39% share) |
| Leading Application Focus, 2025 | ML Model Deployment (40% share) |
| Leading Distribution Channel, 2025 | Cloud Portals (46% share) |
| Leading End User, 2025 | Tech Startups (40% share) |
| Fastest-Growing Service Type | AutoML Services (11.0% CAGR) |
| Fastest-Growing Application Focus | No-code AI (10.9% CAGR) |
| Fastest-Growing Distribution Channel | Online Subscriptions (10.1% CAGR) |
| Fastest-Growing End User | AI Research Institutions (10.1% CAGR) |
| Growing Sector | No-code AI |
| Key End Users | ML Model Deployment, Big Data Analytics, Large-scale Training, No-code AI |
China AI Cloud Services Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
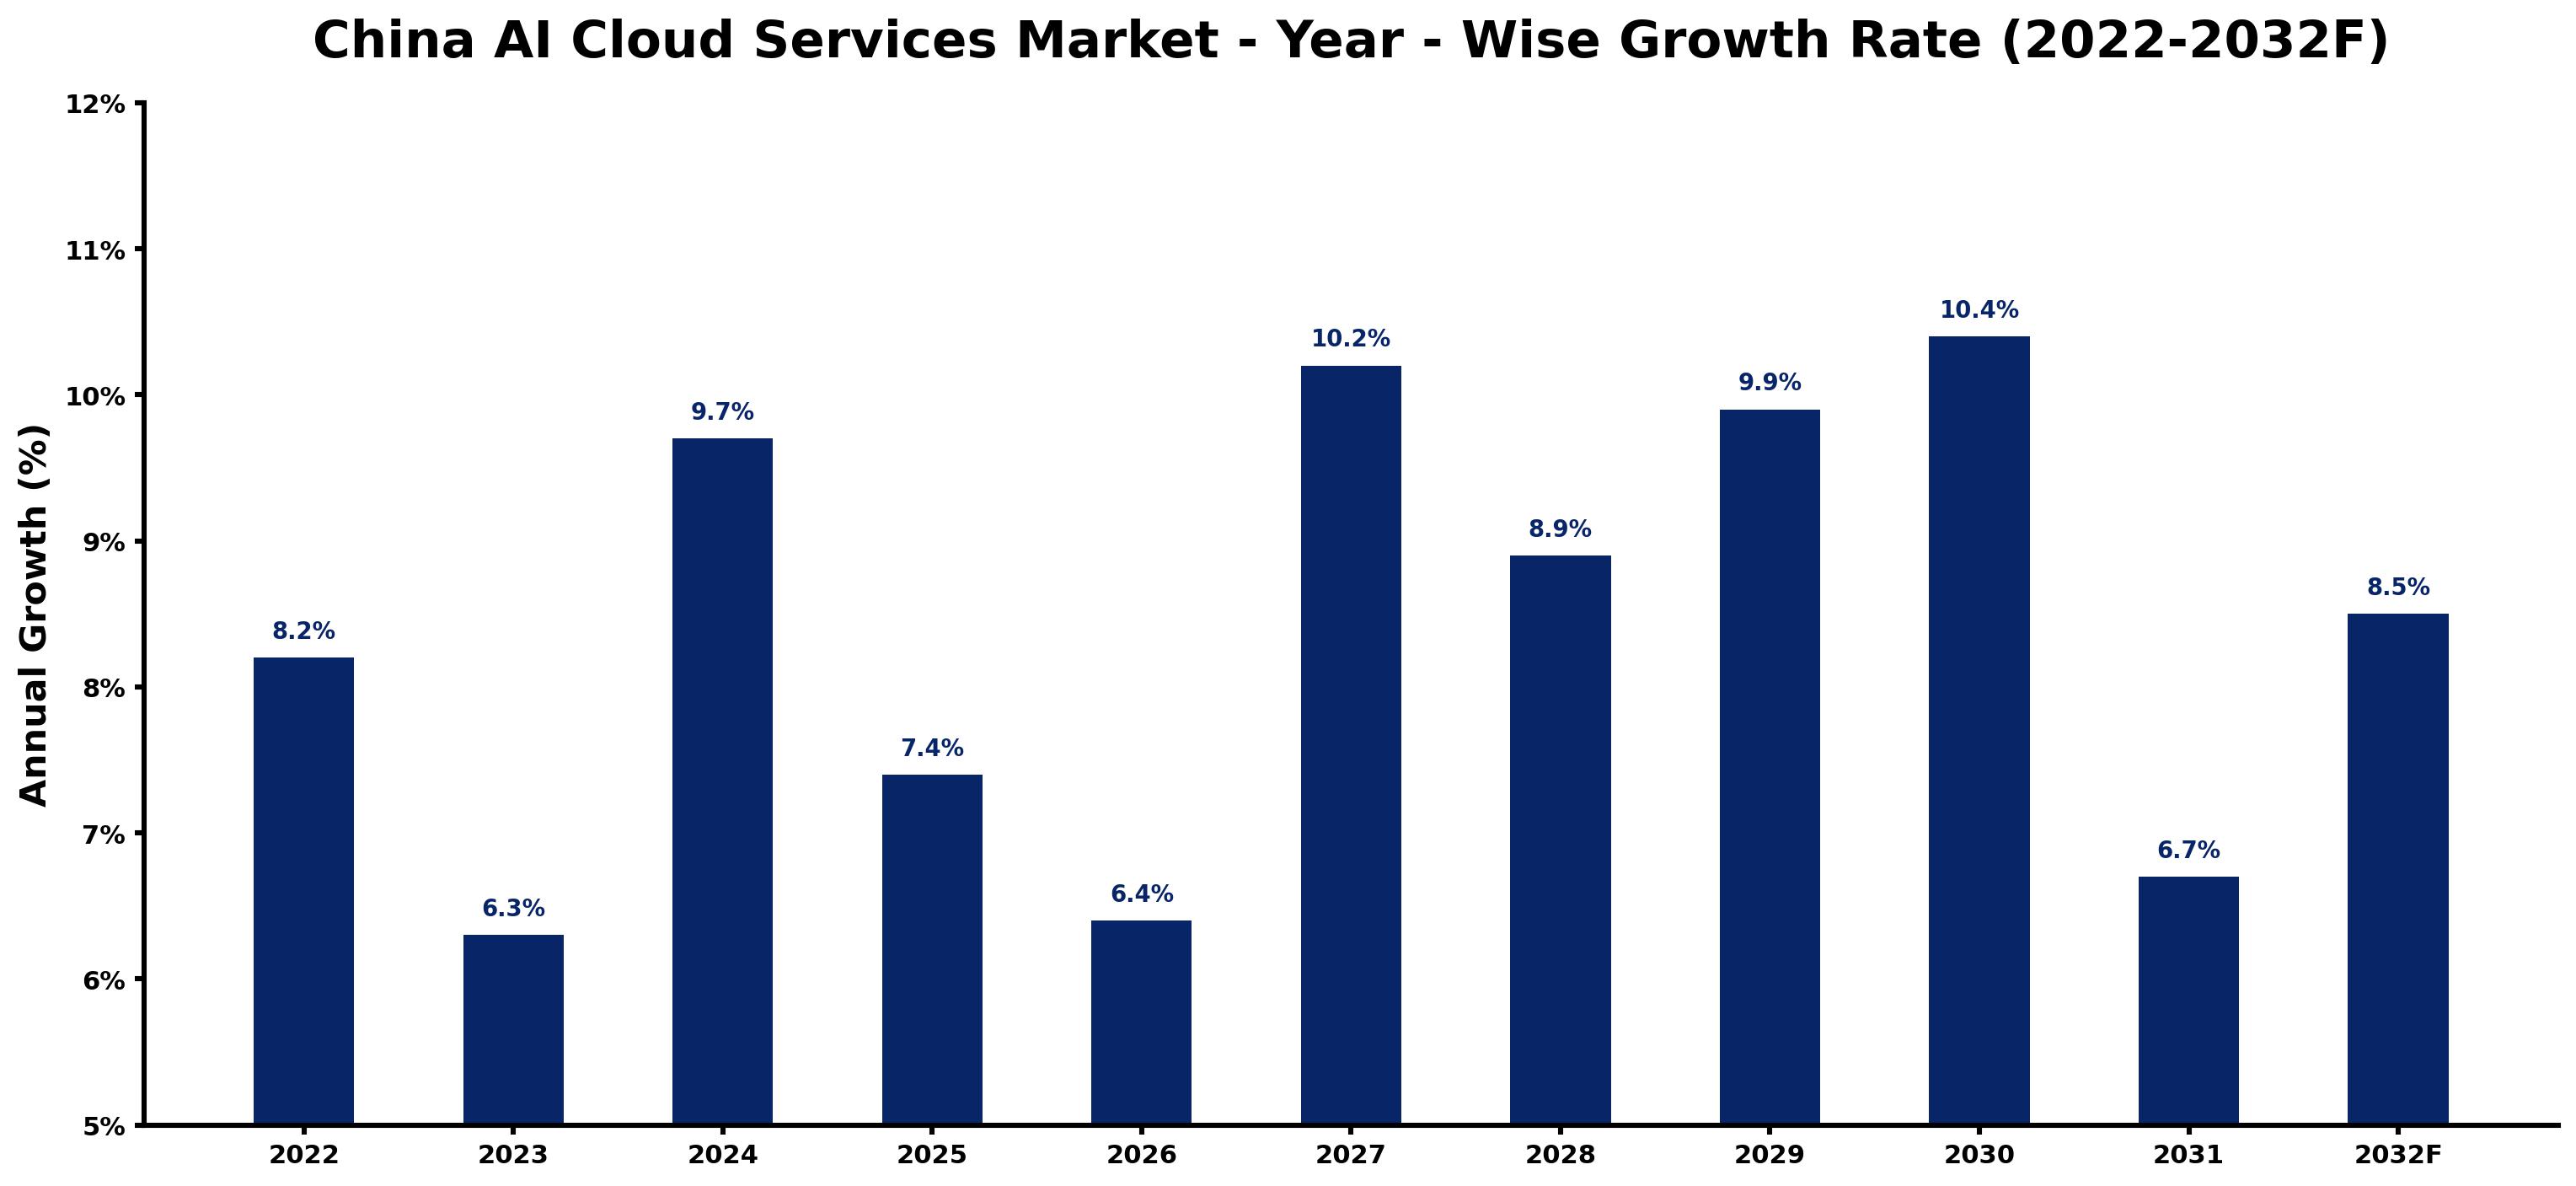
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.2 | The market experienced steady growth as tech startups increasingly adopted AI cloud services for product development. |
| 2023 | 6.3 | Growth slowed as the focus shifted to refining existing AI capabilities under the National AI Development Plan. |
| 2024 | 9.7 | Demand surged as enterprises accelerated AI model deployment to improve operational efficiency. |
| 2025 | 7.4 | A slowdown occurred as companies prioritised the integration of AI with existing systems. |
| 2026 | 6.4 | Growth decelerated as enterprises faced challenges in scaling AI solutions effectively amid rising operational costs. |
| 2027 | 10.2 | A resurgence in demand was driven by increased investments in AI infrastructure development. |
| 2028 | 8.9 | The market saw a slowdown as companies focused on optimising AI service delivery to meet user needs. |
| 2029 | 9.9 | Growth accelerated as more businesses recognised the value of AI in decision-making processes. |
| 2030 | 10.4 | The peak growth rate is expected to be achieved as AI cloud services become integral to operations across various sectors. |
| 2031 | 6.7 | A slowdown is projected as the market matures and competition intensifies among providers. |
| 2032 | 8.5 | Growth is expected to regain momentum as new AI applications emerge across various sectors, driving further adoption. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AI Cloud Services Market Synopsis
AI Cloud Services in China encompasses cloud-based platforms that provide artificial intelligence capabilities such as machine learning and data processing. These services enable businesses to utilise AI for data analytics and improve decision-making processes. The China AI Cloud Services Market is growing due to strong demand from tech startups and research institutions, with over 70% of tech startups using AI cloud services for product development. Government initiatives like the National AI Development Plan promote AI integration across various sectors, further driving growth in this market.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising adoption of AI-as-a-Service among tech startups | Driver | High | AI-as-a-Service |
| Increased demand for data storage solutions integrated with AI | Driver | High | Data Storage + AI |
| Growing need for AI capabilities in small and medium enterprises | Opportunity | Medium | AI-as-a-Service |
| Expansion of AI research institutions focusing on cloud technologies | Opportunity | High | AI Research Institutions |
| Limited awareness of AI cloud service benefits among traditional industries | Restraint | Medium | AI-as-a-Service |
| Challenges in scaling AI solutions effectively within enterprises | Restraint | High | Model Training Engines |
| The AI Cloud Services market in China faces regulatory hurdles | Challenge | High | AI-as-a-Service |
| Competition among service providers is intensifying | Challenge | Medium | Cloud Portals |
Evaluation of Drivers in China AI Cloud Services Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising adoption of AI-as-a-Service | AI-as-a-Service | This service model allows tech startups to scale AI solutions quickly, with over 70% of these startups leveraging AI cloud services for product development. |
| Growing user base of AI cloud services | Cloud Portals | The number of users exceeded 500 million in 2023, indicating a strong demand for accessible AI capabilities. |
| Government support through strategic initiatives | Model Training Engines | The National AI Development Plan promotes AI integration in sectors like healthcare, driving demand for model training capabilities. |
| Increased popularity of cloud marketplaces | Cloud Marketplaces | These platforms have seen a 30% rise in usage among businesses in 2023, facilitating easier access to AI services. |
| Focus on research and innovation | AI Research Institutions | With over 200 institutions dedicated to AI research, there is a strong push for advancements in cloud-based AI technologies. |
Market growth in China for AI Cloud Services rests on the rising adoption of AI-as-a-Service among tech startups, which has seen over 70% of these companies using AI cloud services for product development. The number of AI cloud service users in China exceeded 500 million in 2023, indicating a growing reliance on AI for data analytics. The National AI Development Plan promotes AI integration in sectors like healthcare, driving demand for model training engines. Cloud marketplaces are becoming increasingly popular, facilitating access to AI services for businesses. This trend is further supported by numerous AI research institutions focusing on cloud-based technologies for innovative solutions, with over 200 institutions actively engaged in research.
Evaluation of Restraints in China AI Cloud Services Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Technology integration challenges | AI-as-a-Service | Many producers struggle to integrate advanced AI capabilities into their existing cloud platforms, delaying service offerings for buyers. |
| Regulatory compliance issues | Model Training Engines | Compliance with standards like ISO/IEC 27001 can slow down deployment, costing producers valuable time and resources. |
| Rising operational costs | Cloud Portals | Investments in infrastructure can reach up to 10 billion CNY, forcing suppliers to pass expenses on to buyers. |
| Intense competition | Big Data Analytics | Competition among over 200 AI research institutions drives down prices, impacting profit margins for producers. |
| Market maturity | AutoML Services | As the market matures, growth rates may slow due to increased competition and market saturation. |
China AI Cloud Services Market Challenges
The China AI Cloud Services Market encounters a notable technology gap, as many providers find it challenging to incorporate essential AI capabilities into their platforms. This gap arises from the rapid pace of AI innovation, leaving some suppliers unable to adapt, which ultimately delays service offerings for buyers in sectors like healthcare and finance. Regulatory hurdles also pose challenges; compliance with standards such as ISO/IEC 27001 can impede deployment, costing producers considerable time and resources. Rising operational costs burden suppliers, with infrastructure investments reaching 10 billion CNY, compelling them to raise prices for buyers and limiting their competitiveness.
Trends in the China AI Cloud Services Market
Four trends stand out in the China AI Cloud Services Market.
- Rise of AI-as-a-Service Adoption: In 2023, over 70% of tech startups in China adopted AI-as-a-Service for product development, reflecting a shift towards cloud-based AI solutions.
- Growth of Cloud Marketplaces: Cloud marketplaces experienced a 30% increase in usage among businesses in 2023, providing easier access to AI services and driving demand for innovative solutions.
- Focus on Automation in Industries: The National AI Development Plan, initiated in 2021, has led to a growing emphasis on automation within sectors like healthcare, enhancing AI service adoption.
- Increase in AI Research Institutions: With over 200 AI research institutions in China, the focus on cloud-based AI technologies has intensified, fostering innovation and collaboration in the field.
Investment Opportunities in the China AI Cloud Services Market
Below are the investment opportunities with the strongest case in the China AI Cloud Services Market.
- Investment in AI Infrastructure: The Chinese government’s investment of 10 billion CNY in AI infrastructure development is creating opportunities for suppliers to improve their service offerings.
- Demand from Tech Startups: With over 70% of tech startups using AI cloud services, there is a significant opportunity for providers to cater to this growing market segment.
- Expansion of Cloud Marketplaces: The increasing popularity of cloud marketplaces presents an opportunity for businesses to offer AI services, facilitating easier access for users.
- Focus on Automation Tools: The rising need for automation tools, particularly in sectors like healthcare, creates opportunities for suppliers to develop tailored AI solutions.
Government Initiatives in the China AI Cloud Services Market
The 'AI Innovation Action Plan' launched by the Ministry of Industry and Information Technology in 2021 aims to enhance AI capabilities across industries by 2025, focusing on cloud technologies. This plan builds on previous initiatives to integrate AI into various sectors, ensuring that producers align with national objectives for AI development. The 'New Generation Artificial Intelligence Development Plan' outlines strategies for integrating AI into cloud services, focusing on investment and innovation, which is expected to drive further advancements in the market.
Tech startups and small enterprises benefit from the 'Digital Economy Development Strategy' initiated by the National Development and Reform Commission in 2022, which promotes AI cloud services in key sectors. This strategy funds infrastructure projects that enable these buyer groups to adopt AI solutions more effectively, with a focus on enhancing digital capabilities. The Ministry of Science and Technology's 'AI Research and Development Program' aims to allocate 5 billion CNY by 2025 to enhance AI cloud service capabilities in research institutions, further supporting innovation.
Future Insight of the China AI Cloud Services Market
Several forward-looking factors are expected to support the China AI Cloud Services Market over the coming years. The National AI Development Plan will drive widespread adoption of AI across multiple sectors, boosting demand for these services. Increased investment in AI infrastructure will enable small and medium enterprises to leverage AI cloud services more effectively. By 2025, AI model deployment services are projected to grow by 40%, indicating a shift towards more complex applications. The rise of cloud marketplaces will simplify access to AI capabilities, benefiting both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Service Type – AI-as-a-Service Dominated, AutoML Services Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, AI-as-a-Service took a 39% share of service type in 2025, more than any other category. AI-as-a-Service holds the largest market share due to its essential role in providing scalable solutions for businesses. This service is widely adopted, particularly among tech startups in China, which leverage it for product development. AutoML Services are projected to grow fastest, at a CAGR of 11.0% during 2026–2032. AutoML Services is experiencing rapid growth as it simplifies the model development process, making it accessible for users without technical expertise. The increasing number of AI cloud service users, which surpassed 500 million in 2023, underscores the demand for such user-friendly solutions. Suppliers should focus on enhancing their AI-as-a-Service offerings to meet the rising demand across various sectors.
By Application Focus – ML Model Deployment Dominated, No-code AI Expected to Grow Fastest
The largest application focus category in 2025 was ML Model Deployment, with a 40% share of total revenue. ML Model Deployment leads in market share as it enables businesses to effectively implement machine learning models in real-time applications. The National AI Development Plan promotes such initiatives, particularly in sectors like healthcare and finance, driving its widespread adoption. The quickest growth will come from No-code AI, forecast to expand at a CAGR of 10.9% between 2026 and 2032. No-code AI is the fastest-growing segment, allowing users without coding skills to easily create AI applications. The surge in interest is evident, with over 1,000 AI-related events held in China in 2023, reflecting the demand for accessible tools. Buyers are encouraged to adopt no-code AI solutions to accelerate their AI initiatives without requiring extensive technical expertise.
By Distribution Channel – Cloud Portals Dominated, Online Subscriptions Expected to Grow Fastest
In 2025, Cloud Portals led the distribution channel split with a 46% share. Cloud Portals dominate the market share as they serve as the primary access point for users to utilise AI cloud services effectively. The rise in AI cloud service users in China, which exceeded 500 million in 2023, further solidifies the importance of these platforms. Over 2026–2032, Online Subscriptions are expected to post the fastest growth, at a CAGR of 10.1%. Online Subscriptions are growing rapidly as they offer a popular model for accessing AI services on a pay-as-you-go basis. The increasing adoption of AI cloud services highlights the need for flexible payment options that cater to diverse business needs. Suppliers should optimise their online subscription models to attract a broader range of customers seeking flexible access to AI services.
By End User – Tech Startups Dominated, AI Research Institutions Expected to Grow Fastest
With a 40% revenue share in 2025, Tech Startups was the largest end user category. Tech Startups command the largest market share as they are significant adopters of AI services, facilitating rapid innovation and scaling. The vibrant tech startup ecosystem in regions like Hangzhou illustrates the substantial demand for AI cloud services among these businesses. AI Research Institutions are set to record the highest CAGR in this split, 10.1% over 2026–2032. AI Research Institutions are witnessing the fastest growth, relying heavily on AI cloud services for their research and development activities. With over 200 AI research institutions in China, the increasing need for advanced capabilities is evident. Suppliers should tailor their offerings to meet the specific needs of AI research institutions to capitalise on this expanding segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AI Cloud Services Market Outlook
- Market Size of China AI Cloud Services Market, 2025
- Forecast of China AI Cloud Services Market, 2032
- Historical Data and Forecast of China AI Cloud Services Revenues & Volume for the Period 2022 - 2032F
- China AI Cloud Services Market Trend Evolution
- China AI Cloud Services Market Drivers and Challenges
- China AI Cloud Services Price Trends
- China AI Cloud Services Porter's Five Forces
- China AI Cloud Services Industry Life Cycle
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By AI-as-a-Service for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Data Storage + AI for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Model Training Engines for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By AutoML Services for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Application Focus for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By ML Model Deployment for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Big Data Analytics for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Large-scale Training for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By No-code AI for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Cloud Portals for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Direct Enterprise Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Online Subscriptions for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Cloud Marketplaces for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Tech Startups for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By SaaS Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By AI Research Institutions for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Cloud Services Market Revenues & Volume By Citizen Developers for the Period 2022 - 2032F
- China AI Cloud Services Import Export Trade Statistics
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Application Focus
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China AI Cloud Services Top Companies Market Share
- China AI Cloud Services Competitive Benchmarking By Technical and Operational Parameters
- China AI Cloud Services Company Profiles
- China AI Cloud Services Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Service Type
- AI-as-a-Service
- Data Storage + AI
- Model Training Engines
- AutoML Services
By Application Focus
- ML Model Deployment
- Big Data Analytics
- Large-scale Training
- No-code AI
By Distribution Channel
- Cloud Portals
- Direct Enterprise Sales
- Online Subscriptions
- Cloud Marketplaces
By End User
- Tech Startups
- SaaS Companies
- AI Research Institutions
- Citizen Developers































